
 Wind Turbine Shaft Market | 2026-2036
Wind Turbine Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Shaft Market Analysis
Direct-drive permanent magnet generator technology is rewriting drivetrain architecture across the wind sector. Siemens Gamesa leverages its offshore platform scale to source ultra-large forged shafts from captive European suppliers. GE Renewable Energy anchors its onshore fleet strategy around modular drivetrain designs that accommodate multiple shaft configurations. Vestas competes through integrated nacelle assembly control, keeping shaft procurement tightly coupled to blade and hub sourcing.
A wind turbine shaft transmits rotational torque from the rotor hub to the generator or gearbox, typically forged from low-alloy steel with yield strengths exceeding 500 MPa and subjected to ultrasonic testing for subsurface defect detection. Main shafts command the largest value share as turbine ratings climb, while forging retains margin dominance over casting due to grain-flow requirements in high-cycle fatigue zones. OEMs represent the most concentrated end-user segment, though aftermarket providers are gaining structural importance as aging European and Chinese fleets approach mid-life drivetrain overhauls.
The EU's F-Gas Regulation and CE marking requirements under the Machinery Directive shape shaft seal and lubrication system specifications for European installations. China's SAMR enforces GB standards on forging quality and dimensional tolerance for domestic turbine supply chains. India's CEA mandates type certification for imported shafts under evolving wind-solar hybrid project rules. Stakeholders must monitor how offshore turbine scaling beyond 20 MW prototypes strains existing forging press capacity and reshapes supplier qualification timelines.
Market Dynamics
Offshore turbine scaling beyond 15 MW is compressing forging lead times and concentrating qualified supplier pools around coastal manufacturing clusters capable of handling 100-tonne ingots.
Growth Catalysts
- EU F-Gas Regulation:Mandatory seal and lubrication system upgrades for European offshore installations are driving replacement demand for shaft-integrated sealing assemblies in the North Sea basin.
- Direct-drive permanent magnet generators:Elimination of gearbox stages from offshore drivetrains is expanding main shaft diameter specifications and lifting per-unit material intensity.
- China's coastal provinces:Fujian and Guangdong provincial governments have anchored multi-gigawatt offshore pipelines that lock in multi-year shaft procurement contracts with domestic OEMs.
Market Restraints
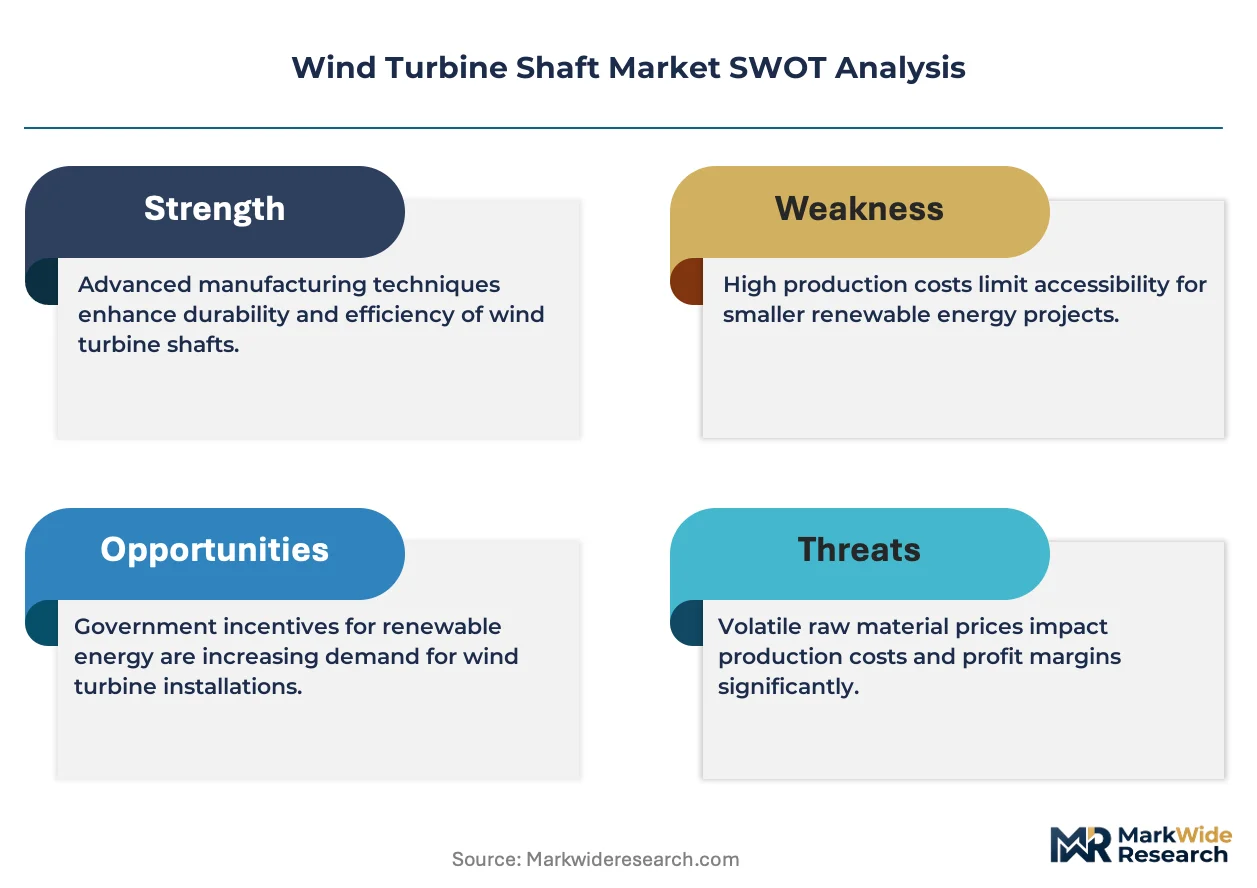
- Nickel-molybdenum alloy volatility:Low-alloy steel input costs swing with nickel futures, compressing forging margins on fixed-price turbine supply agreements.
- European forging press concentration:Only three continental facilities can handle 20 MW-class shaft dimensions, creating single-source vulnerability for North Sea developers.
- Casting substitution ceiling:Grain-flow requirements in high-cycle fatigue zones prevent casting from displacing forging in main shaft applications above 10 MW.
Strategic Opportunities
- India's wind-solar hybrid zones:CEA type certification mandates for imported shafts create first-mover advantage for forging houses that pre-qualify under evolving hybrid project rules.
- Mid-life drivetrain overhaul demand:European and Chinese fleets installed during the 2010-2015 capacity surge are approaching shaft replacement windows, expanding aftermarket service attach rates.
- GB standard harmonization:China's SAMR is aligning forging quality protocols with IEC 61400-4 gearbox standards, easing cross-border supplier qualification for dual-certified producers.
Industry Challenges
- Ultrasonic testing technician scarcity:Subsurface defect detection for 500 MPa yield-strength shafts requires certified Level III inspectors, with training pipelines lagging forging capacity expansion.
- 20 MW prototype qualification timelines:OEMs are compressing supplier validation cycles from 18 months to 12 months, straining documentation and witness-test scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Shaft Market |
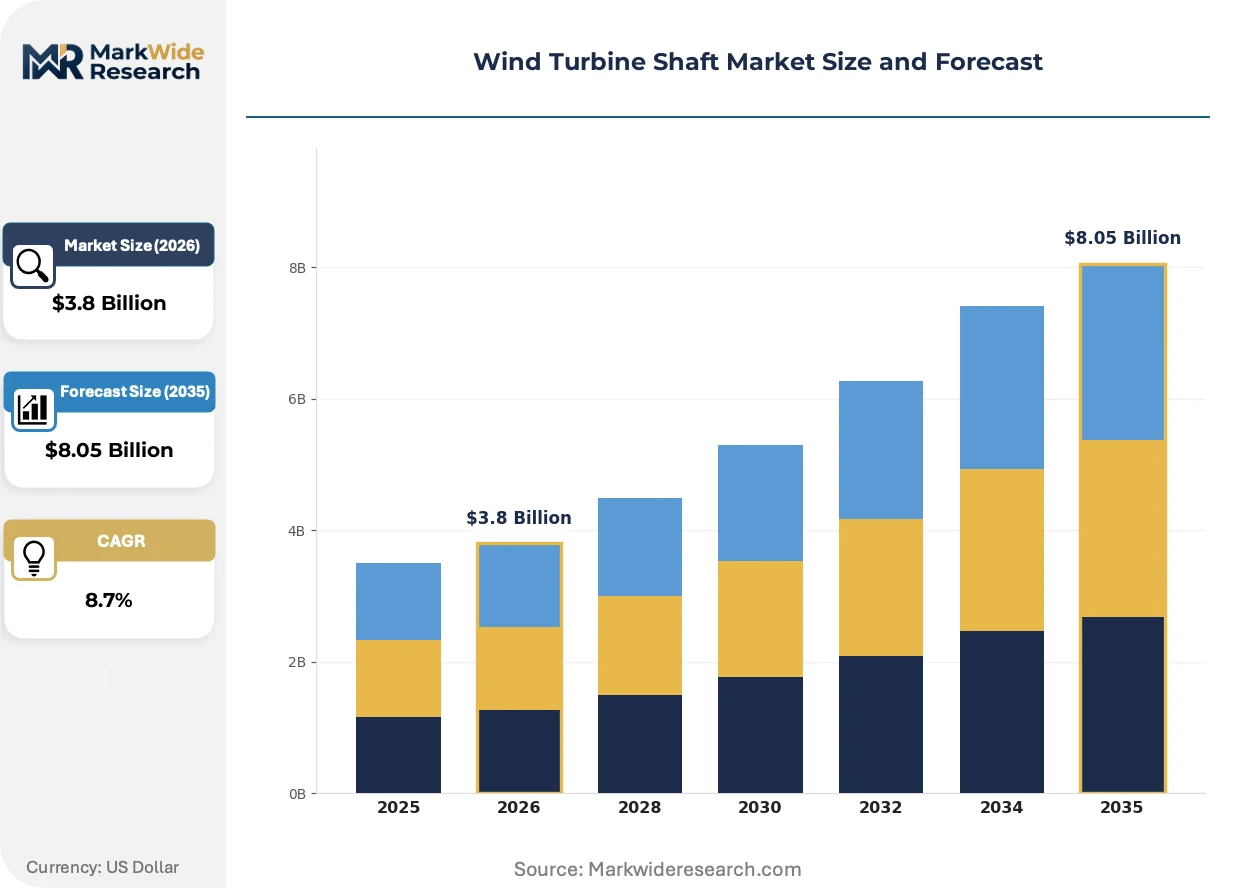
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Main Shaft, Gearbox Shaft, Generator Shaft, Brake Shaft Manufacturing Process: Casting, Forging, Machining, Welding Material: Steel, Aluminum, Composite, Alloy End User: OEMs, Aftermarket Providers, Utilities, Energy Developers |
| Companies Covered | Siemens Gamesa, GE Renewable Energy, Vestas, Nordex, Suzlon Energy, Schaeffler Technologies AG & Co. KG, Broadwind Energy, Jiangyin Zenkung Forging Co., Western Machine Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Shaft Market Emerging Trajectories
Material science and inspection protocols are converging to extend shaft fatigue life while manufacturing footprints shrink toward coastal logistics hubs.
Hybrid steel microstructures combining bainitic and martensitic phases are hybridizing traditional low-alloy forging recipes to achieve 600 MPa yield thresholds without nickel content escalation. Siemens Gamesa and Vestas procurement teams are specifying these grades for 15 MW-plus offshore platforms. The technology is hybridizing supplier metallurgy capabilities, forcing mid-size forges to license heat-treatment IP or exit the offshore tier.
REACH substance restrictions on chromium(VI) surface treatments are mandating trivalent chrome and plasma electrolytic oxidation alternatives for shaft corrosion protection. German KBA and TÜV certification bodies have accelerated approval timelines for these coatings. European OEMs are responding by consolidating plating supplier pools under single-source technical partnership agreements.
Integrated nacelle assembly contracts are compressing standalone shaft procurement into bundled blade-hub-drivetrain packages. Tier-1 suppliers are absorbing forging subcontractors into captive supply arrangements, displacing open-market spot purchasing. This concentration is most visible in Germany's North Sea clusters, where Siemens Gamesa and Vestas have locked five-year forging allocations with Schmiedag and Saarschmiede.
Wind Turbine Shaft Market Segmentation
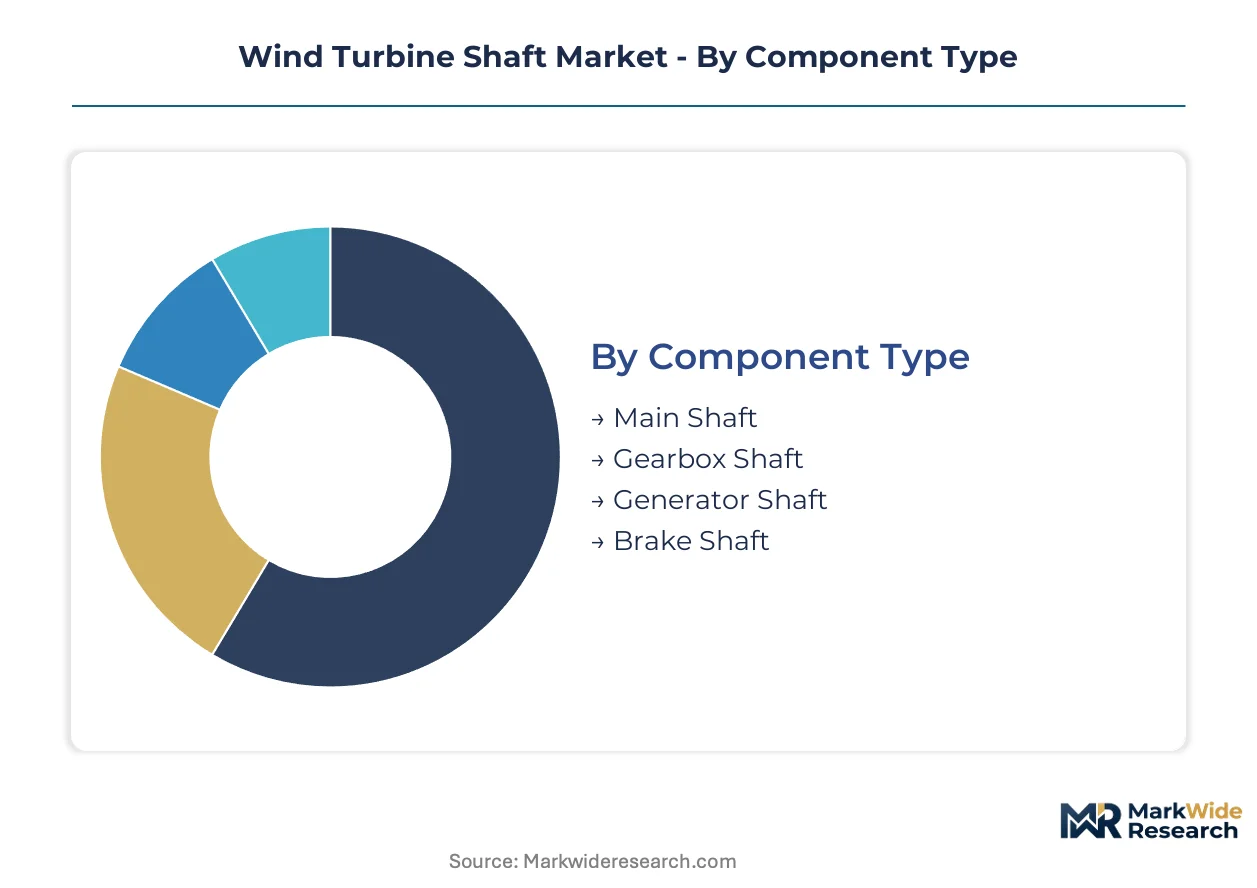
Shaft segmentation determines procurement strategy, forging capacity allocation, and aftermarket service architecture across divergent turbine drivetrain designs. Component dimensions, material specifications, and manufacturing processes map directly to OEM platform roadmaps and regional installation pipelines.
Component Type:
Use-case spectrum spans from high-torque main shafts anchoring multi-megawatt drivetrains to precision generator shafts in direct-drive architectures.
- Main Shaft:Forged low-alloy steel components exceeding 3 meters in length transmit rotor torque to gearbox or generator interfaces. China's Fujian and Guangdong offshore pipelines are locking in multi-year procurement contracts for 15 MW-class dimensions.
- Gearbox Shaft:Intermediate-speed shafts within planetary gear stages require case-hardened surfaces and precisely machined bearing journals. European OEMs are consolidating supplier pools as REACH substance restrictions mandate trivalent chrome alternatives to hexavalent coatings.
- Generator Shaft:Direct-drive permanent magnet designs eliminate gearbox stages, expanding generator shaft diameter specifications and lifting per-unit material intensity for offshore platforms.
- Brake Shaft:Compact high-torque components integrate emergency braking systems into yaw and pitch drivetrains, with demand tied to nacelle assembly bundling trends.
The dominant share belongs to Main Shaft, while Generator Shaft is closing the gap fastest.
Manufacturing Process:
Cost tiers separate premium forged shafts from cast alternatives, with process selection dictated by fatigue-life requirements and turbine rating thresholds.
- Forging:Grain-flow alignment through open-die or ring-rolling processes achieves 500-600 MPa yield strengths mandatory for high-cycle fatigue zones. Only three European facilities handle 20 MW-class shaft dimensions, creating single-source vulnerability for North Sea developers.
- Casting:Sand-cast or investment-cast shafts serve auxiliary applications below 10 MW where grain-flow requirements relax. China's SAMR enforces GB standards on dimensional tolerance that constrain casting substitution in main shaft applications.
- Machining:CNC turning and grinding operations finalize bearing journals, seal surfaces, and coupling interfaces to micrometer tolerances.
- Welding:Friction-stir and submerged-arc processes join shaft segments for transport-constrained offshore installations, with ultrasonic testing protocols mandated by IEC certification.
Forging commands the premium tier by margin, while Machining absorbs the greatest labor-hour allocation across the value chain.
Material:
Volume concentration tracks nickel-molybdenum alloy availability and hybrid microstructure development timelines.
- Steel:Low-alloy grades with controlled carbon, chromium, and molybdenum content dominate forged shaft specifications. Input cost volatility compresses forging margins on fixed-price turbine supply agreements.
- Aluminum:Lightweight extrusions and forgings serve nacelle auxiliary shafts where mass reduction outweighs strength requirements.
- Composite:Carbon-fiber reinforced polymer shafts remain experimental for small-scale demonstrators, constrained by bearing interface durability.
- Alloy:Hybrid bainitic-martensitic microstructures achieve 600 MPa yield thresholds without nickel escalation, with Siemens Gamesa and Vestas specifying these grades for 15 MW-plus offshore platforms.
Steel retains structural dominance, though Alloy formulations are expanding share fastest among next-generation offshore specifications.
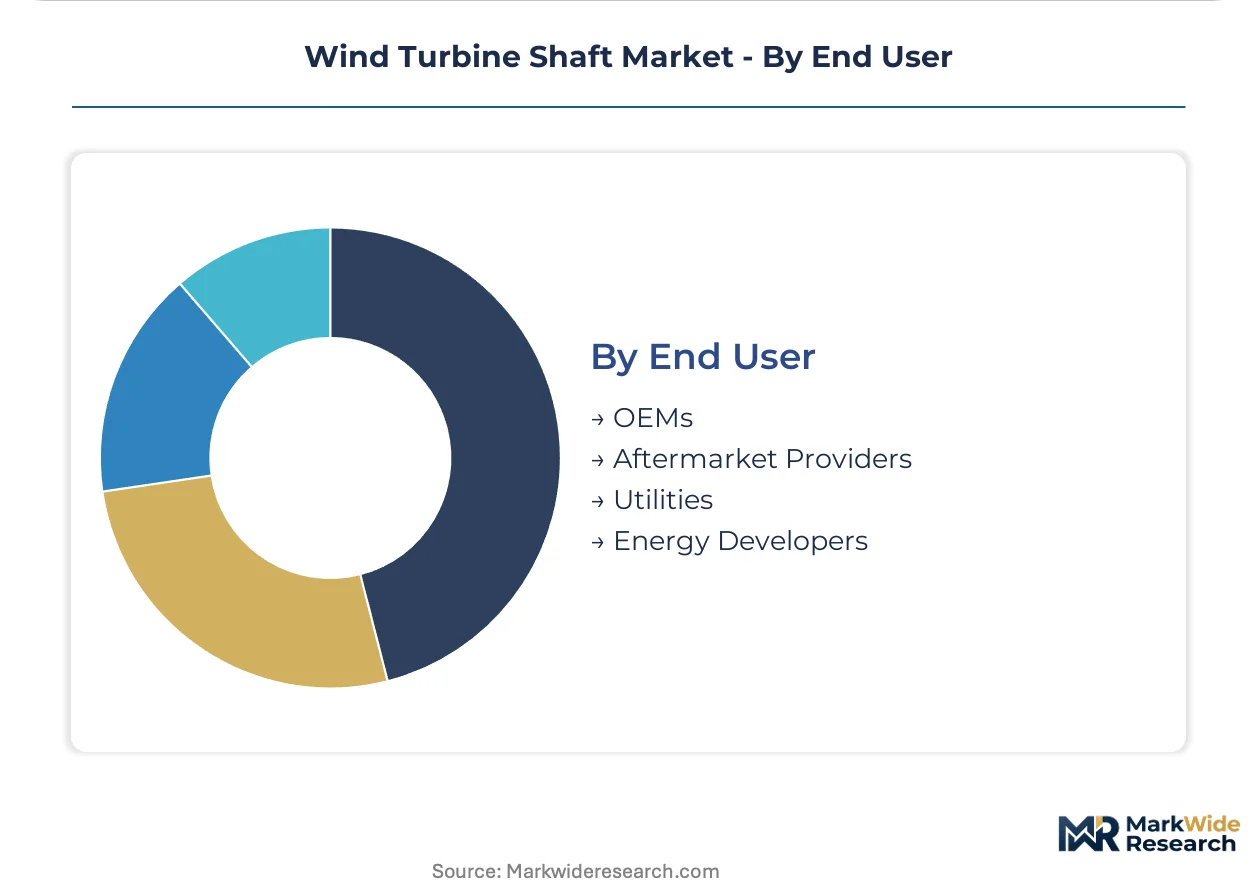
End User:
Customer type determines contract structure, from multi-year OEM framework agreements to spot aftermarket procurement.
- OEMs:Integrated nacelle assemblers including Siemens Gamesa, GE Renewable Energy, and Vestas source shafts through captive supply arrangements or five-year forging allocations. Bundled blade-hub-drivetrain packages are compressing standalone shaft procurement.
- Aftermarket Providers:Independent service contractors and OEM service arms address mid-life drivetrain overhaul demand as European and Chinese fleets from the 2010-2015 installation surge approach shaft replacement windows.
- Utilities:Vertically integrated power generators in Germany and China are securing direct forging contracts to de-risk supply chains for captive project pipelines.
- Energy Developers:Project-specific procurement teams for offshore wind farms negotiate shaft warranties within turbine supply agreements, with qualification timelines compressing from 18 months to 12 months.
OEMs anchor procurement volume, while Aftermarket Providers are steepening their expansion trajectory as fleet aging accelerates replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore developers and onshore OEMs concentrate procurement around coastal forging clusters and turbine assembly hubs. China's provincial governments, Germany's North Sea ports, and India's hybrid wind-solar zones anchor distinct demand patterns. Regulatory divergence on material certification and emissions protocols shapes supplier qualification timelines across these buyer concentrations.
China
Fujian and Guangdong provincial governments have locked multi-gigawatt offshore pipelines that secure multi-year shaft procurement contracts with domestic OEMs. SAMR enforces GB standards on forging quality and dimensional tolerance that constrain casting substitution in main shaft applications. Nantong and Yancheng clusters host integrated nacelle assembly facilities where captive forging arrangements displace open-market purchasing.
Germany
North Sea offshore developers source ultra-large forged shafts from captive European suppliers concentrated around Hamburg and Bremen port zones. The EU's F-Gas Regulation mandates seal and lubrication system upgrades that drive replacement demand for shaft-integrated sealing assemblies. Saarland forging presses at Schmiedag and Saarschmiede anchor continental capacity for 15 MW-plus turbine dimensions.
India
Gujarat and Tamil Nadu wind-solar hybrid zones generate CEA type certification mandates for imported shafts that create first-mover advantage for pre-qualified forging houses. The Ministry of New and Renewable Energy channels auction capacity toward coastal states with existing port infrastructure. Mundra and Kandla clusters are emerging as inspection and logistics hubs for Middle East and Southeast Asian re-export.
United States
Texas and Great Plains onshore developers anchor demand for modular drivetrain designs accommodating multiple shaft configurations. FERC interconnection queue reforms are compressing project development timelines and forcing faster supplier qualification cycles. Houston and Corpus Christi clusters concentrate aftermarket service providers addressing mid-life overhaul demand from 2010-2015 installation vintages.
Japan
Kyushu and Hokkaido offshore demonstration projects specify hybrid bainitic-martensitic microstructures for typhoon-resistant turbine platforms. METI feed-in tariff revisions are redirecting development toward floating foundation designs that stress shaft fatigue specifications. Nagasaki and Shimonoseki clusters host shipyard-conversion facilities adapting marine forging capacity to wind component production.
Wind Turbine Shaft Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply arrangements. Siemens Gamesa, GE Renewable Energy, and Vestas dominate through integrated nacelle assembly contracts that bundle shaft procurement into blade-hub-drivetrain packages. European forging houses anchor the premium tier through captive supply relationships with offshore developers. Mid-size Asian fabricators compete on cost for onshore replacement demand. Dominant competitive moves include capacity expansion at coastal manufacturing clusters and strategic partnerships between OEMs and metallurgy licensors.
Among European-based forging specialists, Schaeffler Technologies AG & Co. KG represents the precision-engineering archetype with integrated bearing and shaft system capabilities. Jiangyin Zenkung Forging Co. exemplifies the scale-driven Chinese fabricator segment serving domestic OEM procurement frameworks. Broadwind Energy occupies a position within the North American aftermarket and replacement shaft tier, addressing mid-life drivetrain overhaul demand from aging fleet vintages.
| Leading Market Players |
|---|
| Siemens Gamesa |
| GE Renewable Energy |
| Vestas |
| Nordex |
| Suzlon Energy |
| Schaeffler Technologies AG & Co. KG |
| Broadwind Energy |
| Jiangyin Zenkung Forging Co. |
| Western Machine Works |
| Others |
Supply Flow & Price Mechanics
Undercapacity at European 20 MW-class forging presses concentrates pricing power among three continental facilities serving North Sea offshore developers. This utilization squeeze tightens supplier margins on fixed-price turbine supply agreements while amplifying buyer dependency on coastal manufacturing clusters capable of handling 100-tonne ingots.
Pricing Analysis
Cost-plus contracts indexed to LME nickel-molybdenum futures dominate procurement frameworks for low-alloy steel shafts. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified offshore grades from onshore replacement tiers and spot-market cast alternatives. Cost compression in standard-tier forging is intensifying because Chinese OEMs are consolidating procurement under multi-year framework agreements. Aftermarket providers exhibit the highest price sensitivity due to margin pressure from independent service competition, while offshore developers accept premium pricing for qualified 15 MW-plus dimensions.
Supply Chain Analysis
Low-alloy steel feedstock draws from integrated mills in China, Germany, and Japan with specialized vacuum degassing capabilities. Nickel and molybdenum alloying elements hinge on concentrate supply from Indonesian nickel processing and Chilean molybdenum extraction. Single-source vulnerability concentrates at European forging presses handling ultra-large shaft dimensions. Distribution runs through captive nacelle assembly arrangements that bundle shaft procurement into blade-hub-drivetrain packages, displacing open-market spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated OEMs as Siemens Gamesa, Vestas, and GE Renewable Energy consolidate five-year forging allocations with European suppliers. This concentration fragments negotiating leverage among independent aftermarket providers and project-specific energy developers.
For Market Incumbents: Harden coastal forging capacity through backward integration into 100-tonne ingot handling capabilities at Nantong and Yancheng clusters. Lock in metallurgy licensing for hybrid bainitic-martensitic grades before mid-size forges exit the offshore tier. Defend against casting substitution threats by enforcing GB standard dimensional tolerances that constrain relaxation in main shaft applications.
For New Entrants and Emerging Players: Build out inspection and logistics hub capabilities at Mundra and Kandla to capture CEA type certification first-mover advantage in India's wind-solar hybrid zones. Target aftermarket service contracts for European and Chinese fleets approaching mid-life drivetrain overhaul windows. Lead with ultrasonic testing technician training partnerships to overcome Level III inspector scarcity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 20 MW prototype qualification cycles as OEMs compress supplier validation timelines. Five-to-ten year viability favors forging houses with dual GB-IEC certification and captive European OEM relationships. Watch for nickel-molybdenum alloy volatility as the inflection signal for margin compression risk in fixed-price contract portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion at Coastal Forging Clusters | Schmiedag and Saarschmiede allocations lock five-year supply for Siemens Gamesa and Vestas offshore platforms. |
| Metallurgy Licensing Partnership | Hybrid bainitic-martensitic IP access separates qualified 15 MW-plus suppliers from exiting mid-tier forges. |
| Backward Integration into Ingot Handling | Nantong and Yancheng clusters capture captive nacelle assembly demand from China's Fujian and Guangdong pipelines. |
| Aftermarket Service Network Buildout | Houston and Corpus Christi providers address mid-life overhaul demand from 2010-2015 US installation vintages. |
| Dual Certification Investment | GB standard harmonization with IEC 61400-4 eases cross-border qualification for pre-certified forging houses. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through primary interviews with wind turbine OEM procurement directors, forging plant managers, offshore project development engineers, and aftermarket service operations heads. Secondary validation drew from IEC certification databases, SAMR GB standard filings, CEA type certification registries, and customs trade records for low-alloy steel ingot movements. Bottom-up shaft procurement volume estimates were triangulated against top-down turbine installation pipeline data across the analysis window.
Calibration against historical forging capacity utilization and OEM supplier qualification timelines anchored the projection framework. Segmentation dimensions modeled encompass component type, manufacturing process, material grade, and end-user category across the projection horizon. CAGRs were derived from installed capacity growth trajectories and per-unit shaft material intensity escalations tied to turbine rating scaling.
Stress conditions across nickel-molybdenum price volatility, forging press capacity constraints, and regulatory timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM platform roadmaps and coastal cluster development pipelines. Cross-checking against IEA wind installation forecasts and OEM annual procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Wind Energy Foundation Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Europe Small Wind Turbine Market