
 Green Hydrogen Dispensing Equipment Market | 2026-2036
Green Hydrogen Dispensing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Green Hydrogen Dispensing Equipment Market Foresight
ISO 19880-1 certification for gaseous hydrogen fueling stations is redrawing competitive boundaries across the equipment supply base. Air Liquide leverages its cryogenic heritage to dominate high-capacity liquefaction-to-dispensing chains. Nel ASA anchors Nordic supply through integrated electrolyzer-to-dispenser architectures. Linde plc sustains position via control over proprietary ionic compressor designs that extend operating pressure ranges beyond conventional mechanical limits.
Green hydrogen dispensing equipment encompasses mechanical and electrochemical systems engineered to transfer hydrogen from production or storage to end-use points at pressures typically spanning 350 to 700 bar, with materials selected for hydrogen embrittlement resistance. The primary commercial purpose centers on enabling safe, rapid refueling of fuel cell electric vehicles and industrial offtake at scale. Compressor configurations within the product type segment capture the dominant margin pool due to precision metallurgy requirements and limited qualified supplier bases. Dispensing systems technology leads deployment velocity as station operators prioritize throughput optimization and protocol compatibility across vehicle OEM platforms. Permanent installation categories concentrate investment where industrial hydrogen hubs anchor offtake certainty.
The EU F-Gas Regulation and REACH compliance frameworks constrain refrigerant and sealing material selections across European supply chains, while Japan's METI hydrogen safety standards shape dispenser protocol architectures for the Asian market. Germany's KBA type-approval requirements for vehicle fueling interfaces directly influence nozzle and communication system design specifications. Stakeholders must monitor divergence between regional pressure protocols and material qualification standards as fleet operators pursue cross-border deployment flexibility.
Market Dynamics
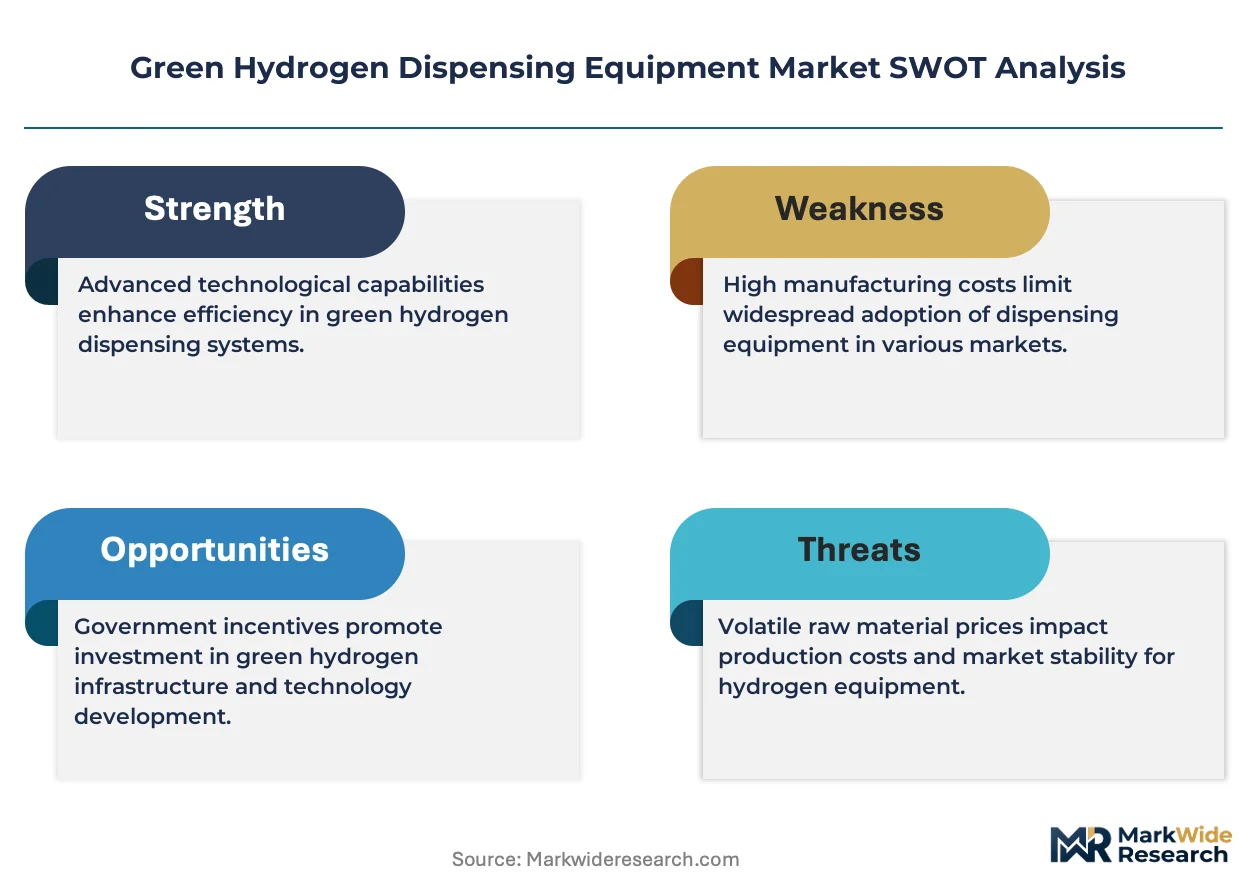
High-pressure mechanical compressor designs face structural pressure from ionic liquid and electrochemical compression alternatives that eliminate hydrogen embrittlement risks in critical metallurgical components.
Growth Catalysts
- Fuel Cell Fleet Procurement:Heavy-duty truck operators in California and Japan are mandating 700-bar dispensing compatibility for new procurement tenders, forcing station infrastructure upgrades ahead of vehicle delivery schedules.
- EU F-Gas Regulation:Refrigerant phase-down requirements are accelerating adoption of cryogenic pump systems that bypass conventional cooling circuits entirely, favoring suppliers with liquefaction heritage.
- Industrial Cluster Concentration:Rotterdam, Hamburg, and Singapore port authorities are bundling dispensing infrastructure into green ammonia export terminal developments, locking in offtake volumes before electrolyzer commissioning.
Market Restraints
- Specialized Alloy Supply Concentration:ASTM A286 and Inconel 718 forgings for high-pressure vessels concentrate among Japanese and German metallurgical suppliers, creating input bottlenecks during demand surges.
- ISO 19880-1 Certification Timeline:Station-level type-approval processes in Germany and Japan extend 18-24 months, freezing capital deployment until protocol validation completes.
- Battery Electric Substitution:Megawatt-scale charging corridors for regional trucking in China and Norway are capturing fleet investment that might otherwise flow to hydrogen infrastructure.
Strategic Opportunities
- India National Hydrogen Mission:Electrolyzer-to-dispenser integrated tenders at Mundra and Hazira industrial zones offer first-mover positioning before domestic compressor manufacturing scales.
- Maritime Bunkering Protocols:IMO 2025 alternative fuel frameworks are driving ammonia and methanol cracking-to-dispenser system development for portside hydrogen supply chains.
- Electrochemical Compression Convergence:Solid oxide electrolysis cell output integration with electrochemical hydrogen compressors eliminates intermediate storage, reducing station footprint by 40 percent in pilot Dutch deployments.
Industry Challenges
- ASME Section VIII Welder Certification Scarcity:Qualified pressure vessel fabrication labor concentrates among aging workforces in Germany and Japan, constraining manufacturing expansion.
- Legacy CNG Station Retrofit Complexity:Existing 350-bar natural gas dispensing infrastructure requires complete replacement of sealing systems and control electronics for hydrogen service, not incremental adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Hydrogen Dispensing Equipment Market |
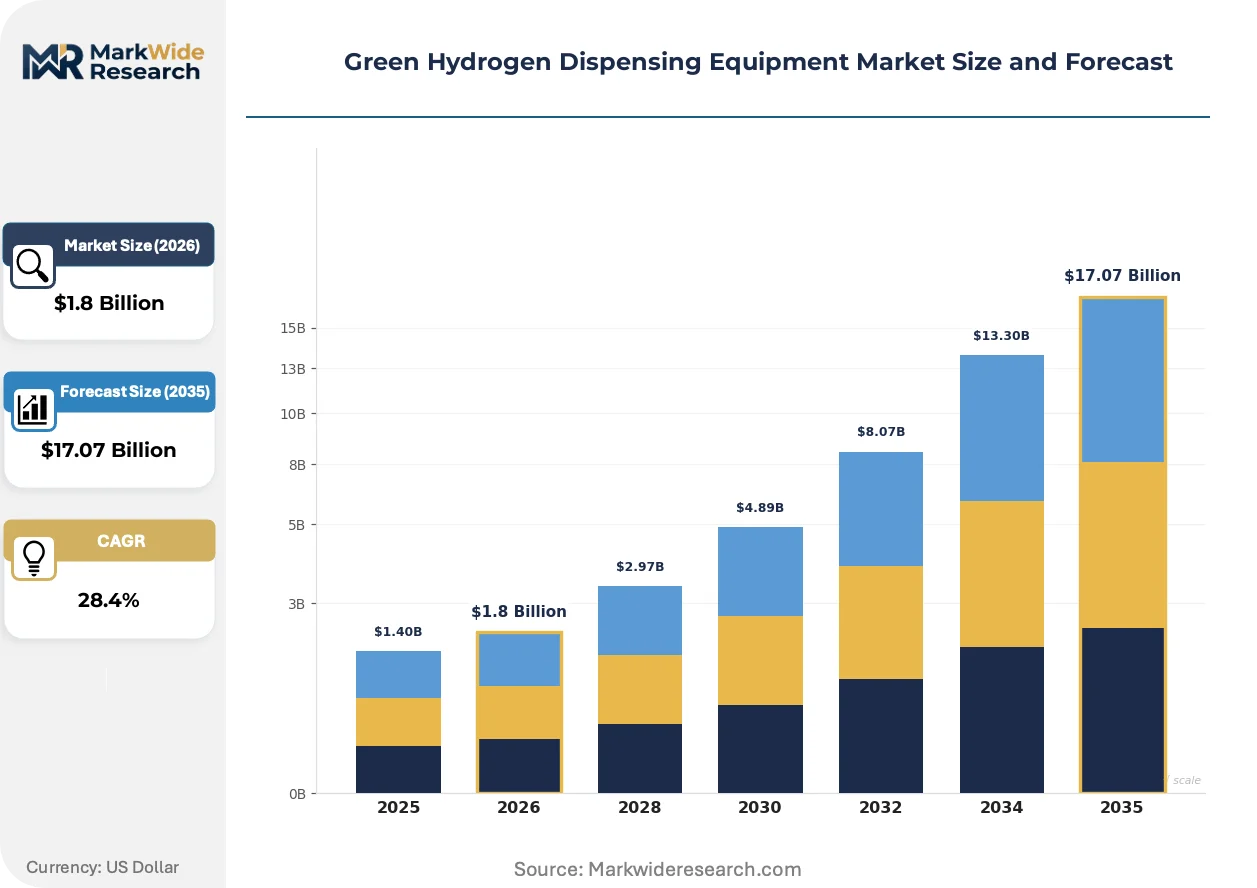
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressors, Dispensers, Valves, Storage Tanks Technology: Electrolysis, Gas Purification, Compression, Dispensing Systems End User: Fuel Cell Vehicles, Industrial Applications, Power Generation, Public Infrastructure Installation: On-site, Off-site, Temporary, Permanent |
| Companies Covered | Air Liquide, Linde plc, Nel ASA, Air Products and Chemicals, Inc., ITM Power, Chart Industries, Toyota Industries Corporation, Plug Power, Ballard Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Hydrogen Dispensing Equipment Market Shifts & Advancements
Equipment architectures are fragmenting between centralized liquefaction-to-dispenser chains favored by industrial hubs and distributed electrolyzer-integrated systems serving isolated fleet depots.
Ionic liquid piston compressors are supplanting conventional diaphragm and reciprocating mechanical designs in 700-bar dispensing applications. Station operators in Germany and Japan are specifying ionic systems for new builds to eliminate metallic friction wear and extend maintenance intervals. This shift is compressing the qualified supplier base to firms with cryogenic fluid chemistry capabilities.
Japan's METI hydrogen safety standards revision is mandating redundant pressure relief architectures and real-time embrittlement monitoring in dispenser nozzle designs. Equipment suppliers must now integrate fiber-optic sensing into high-pressure interfaces, adding 15-20 percent to bill-of-materials costs. Asian-market dispensers are diverging from European designs as KBA and METI protocols harden around incompatible technical specifications.
Fleet operators are consolidating procurement through electrolyzer-to-dispenser EPC contracts rather than sourcing compression and dispensing hardware separately. Large trucking and steel clients in South Korea and the Netherlands are awarding integrated station build-outs to single-source contractors, marginalizing standalone equipment vendors. This bundling is most pronounced where national hydrogen roadmaps guarantee offtake tariffs.
Green Hydrogen Dispensing Equipment Market Segmentation
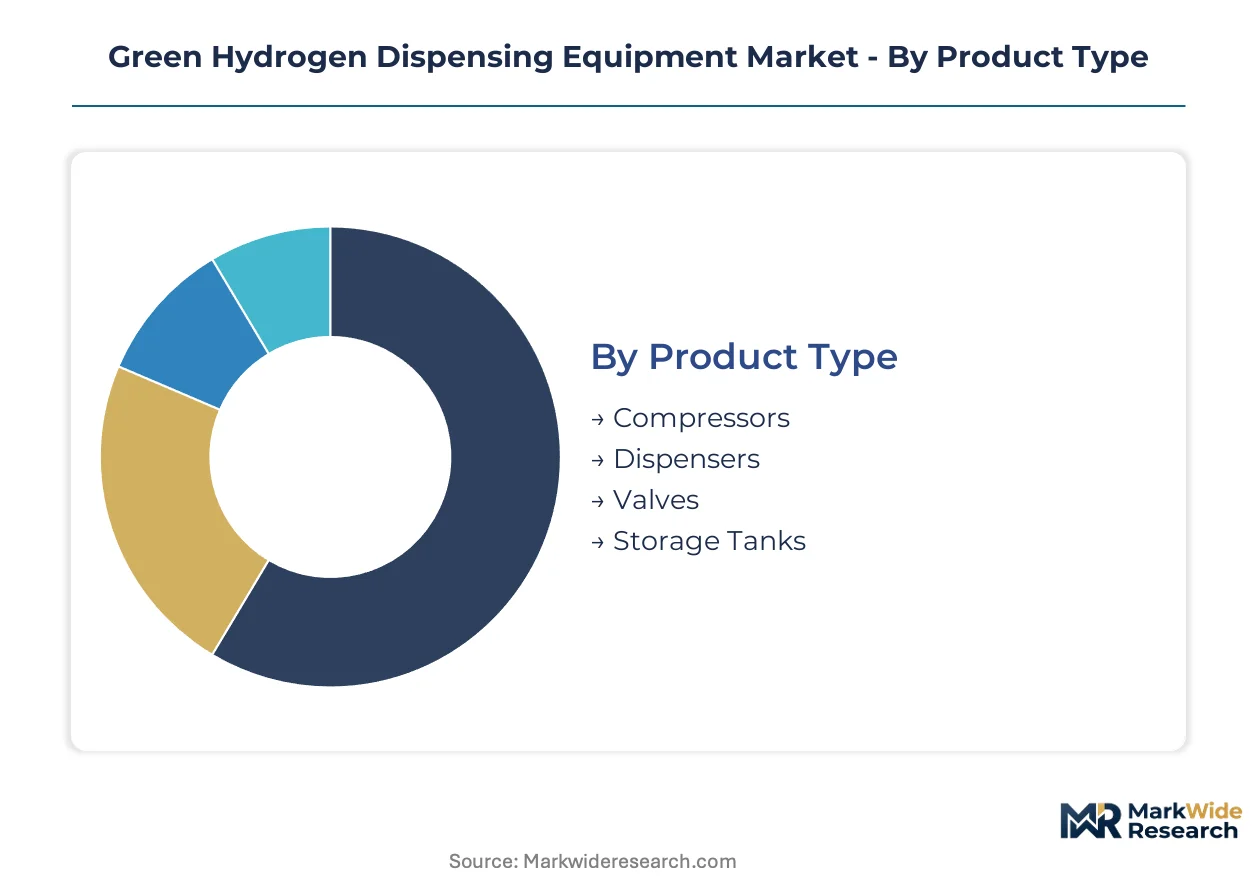
Segmentation in green hydrogen dispensing equipment reveals where capital deployment concentrates and which technical specifications command premium pricing. Procurement patterns diverge sharply between fleet operators optimizing throughput and industrial offtakers prioritizing feedstock reliability.
Product Type:
Margin pools concentrate in precision-engineered pressure systems where metallurgical qualification creates supply scarcity.
- Compressors:Mechanical and ionic liquid configurations engineered for 350-700 bar output dominate equipment spend. Demand clusters in Germany and Japan where KBA and METI type-approval requirements mandate redundant pressure architectures. Specialized alloy forgings for high-pressure vessels concentrate among Japanese and German metallurgical suppliers, creating input bottlenecks during demand surges.
- Dispensers:Nozzle and communication systems transfer hydrogen to end-use points with protocol compatibility across vehicle OEM platforms. California heavy-duty truck operators are mandating 700-bar dispensing compatibility for new procurement tenders, forcing station infrastructure upgrades ahead of vehicle delivery schedules.
- Valves:High-pressure sealing systems selected for hydrogen embrittlement resistance.
- Storage Tanks:Vessel configurations spanning cryogenic liquid and compressed gaseous states.
The dominant share belongs to Compressors, while Dispensers is closing the gap fastest.
Technology:
Cost tiers separate mature mechanical systems from emerging electrochemical alternatives eliminating metallic wear components.
- Electrolysis:Solid oxide and alkaline systems generating hydrogen at production points. Integrated electrolyzer-to-dispenser architectures in the Netherlands are eliminating intermediate storage, reducing station footprint by 40 percent in pilot deployments.
- Gas Purification:Membrane and pressure swing adsorption units removing contaminants prior to compression.
- Compression:Reciprocating, diaphragm, and ionic liquid piston designs spanning pressure ranges. Ionic liquid systems are supplanting conventional mechanical designs in 700-bar applications across Germany and Japan to eliminate metallic friction wear and extend maintenance intervals.
- Dispensing Systems:Protocol-compliant transfer interfaces with real-time monitoring capabilities. Japan's METI hydrogen safety standards revision is mandating redundant pressure relief architectures and fiber-optic sensing integration, adding 15-20 percent to bill-of-materials costs.
Compression retains the largest installed base, though Electrolysis is expanding most quickly through integrated station architectures.
End User:
Application requirements drive specification divergence between mobility and industrial offtake.
- Fuel Cell Vehicles:Light-duty and heavy-duty fleet refueling infrastructure. South Korean trucking clients are awarding integrated electrolyzer-to-dispenser EPC contracts to single-source contractors, marginalizing standalone equipment vendors.
- Industrial Applications:Steel, ammonia, and chemical feedstock supply at scale. Rotterdam, Hamburg, and Singapore port authorities are bundling dispensing infrastructure into green ammonia export terminal developments, locking in offtake volumes before electrolyzer commissioning.
- Power Generation:Grid-balancing and backup power fuel supply systems.
- Public Infrastructure:Multi-user station networks serving mixed fleets.
Industrial Applications command the dominant revenue position, while Fuel Cell Vehicles is gaining share fastest through fleet procurement mandates.
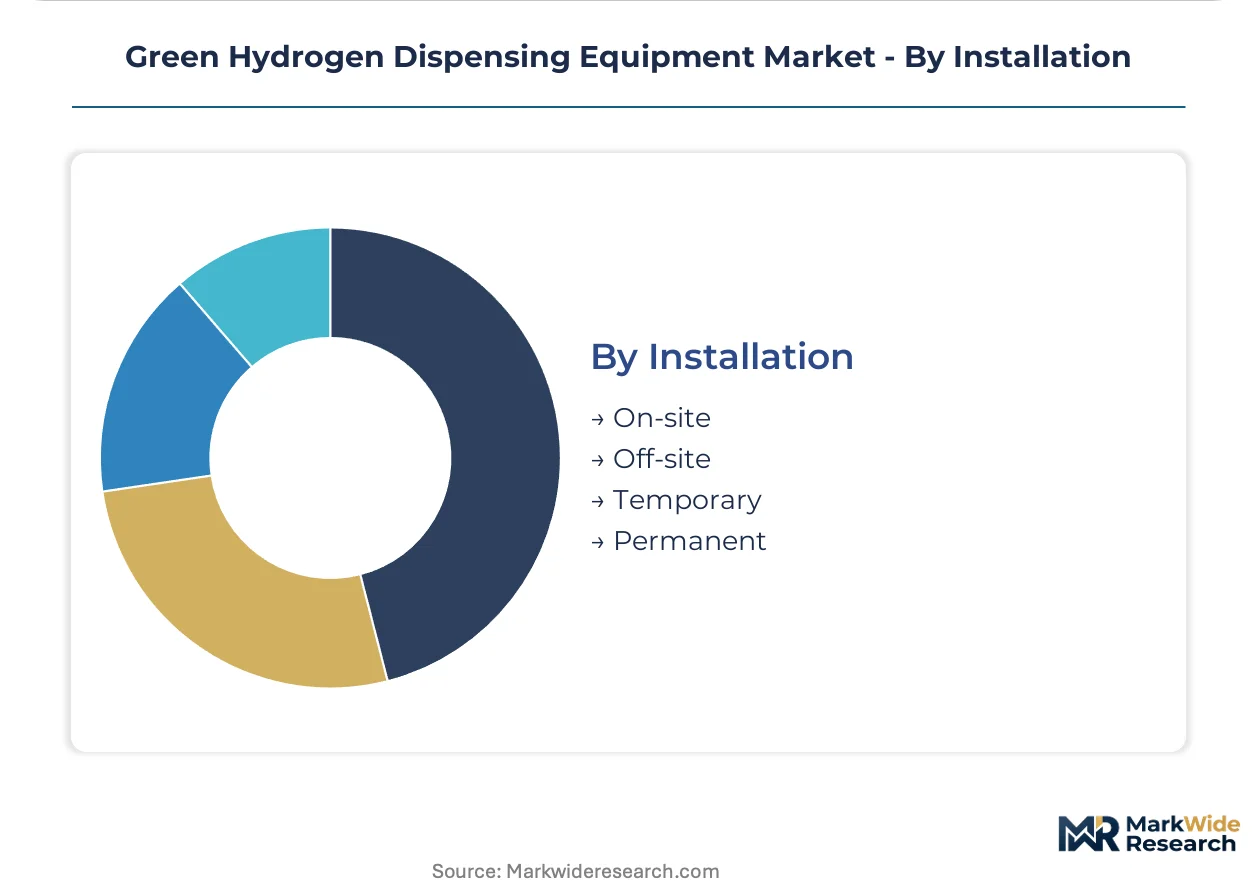
Installation:
Customer type separates capital-intensive permanent hubs from flexible deployment models.
- On-site:Integrated production and dispensing at industrial facilities or fleet depots.
- Off-site:Centralized production with pipeline or tube trailer distribution to dispensing points.
- Temporary:Modular systems for pilot programs or construction-phase supply. India's National Hydrogen Mission electrolyzer-to-dispenser integrated tenders at Mundra and Hazira industrial zones offer first-mover positioning before domestic compressor manufacturing scales.
- Permanent:Fixed station infrastructure anchoring industrial hydrogen hubs. EU F-Gas Regulation refrigerant phase-down requirements are accelerating adoption of cryogenic pump systems that bypass conventional cooling circuits entirely.
Permanent installations hold the leading position, while Temporary configurations are climbing the fastest through pilot-to-scale transition programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA type-approval requirements and Japan's METI hydrogen safety standards are accelerating station deployment timelines. National hydrogen roadmaps in South Korea and India's National Hydrogen Mission are redirecting capital toward coastal industrial clusters and fleet depots.
Germany
Heavy-duty truck operators are mandating 700-bar dispensing compatibility for new procurement tenders. KBA type-approval requirements for vehicle fueling interfaces directly influence nozzle and communication system design specifications. Hamburg port authorities are bundling dispensing infrastructure into green ammonia export terminal developments.
Japan
Fuel cell vehicle fleets are expanding procurement of high-pressure dispensing systems. METI hydrogen safety standards revision is mandating redundant pressure relief architectures and fiber-optic sensing integration. Tokyo and Nagoya industrial corridors anchor electrolyzer-to-dispenser integrated station build-outs.
South Korea
Steel and trucking clients are awarding integrated electrolyzer-to-dispenser EPC contracts to single-source contractors. National hydrogen roadmaps guarantee offtake tariffs for station operators. Busan-Ulsan port complexes concentrate dispensing infrastructure investment ahead of electrolyzer commissioning.
United States
California heavy-duty fleet operators are forcing station infrastructure upgrades ahead of vehicle delivery schedules. EPA and state-level zero-emission vehicle mandates shape procurement timelines. Los Angeles and Long Beach port authorities are piloting maritime bunkering protocols for ammonia and methanol cracking-to-dispenser systems.
India
Mundra and Hazira industrial zones offer first-mover positioning through electrolyzer-to-dispenser integrated tenders. The National Hydrogen Mission redirects capital toward domestic compressor manufacturing scale-up. Gujarat coastal clusters concentrate dispensing infrastructure for ammonia export terminal developments.
Green Hydrogen Dispensing Equipment Market Competitive Landscape
Player mix skews toward diversified industrial gas conglomerates with cryogenic heritage and specialized electrolyzer-to-dispenser integrators. Market structure concentrates margin pools among firms controlling proprietary compression architectures and qualified metallurgical supply chains. Strategic archetypes span liquefaction-to-dispensing chain operators, ionic compressor technology holders, and integrated electrolyzer station builders. Competitive moves center on backward integration into electrolyzer manufacturing and geographic expansion through port authority bundling contracts.
Among European industrial gas specialists, Air Liquide and Linde plc occupy positions defined by cryogenic fluid chemistry capabilities and proprietary ionic compressor designs. Nel ASA anchors Nordic supply through integrated electrolyzer-to-dispenser architectures. These three exemplify the divergence between centralized liquefaction chains favored by industrial hubs and distributed electrolyzer-integrated systems serving isolated fleet depots.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Nel ASA |
| Air Products and Chemicals, Inc. |
| ITM Power |
| Chart Industries |
| Toyota Industries Corporation |
| Plug Power |
| Ballard Power Systems |
| Others |
Supply & Pricing Matrix
Ionic liquid compressor adoption is displacing conventional mechanical designs across German and Japanese dispensing stations, simultaneously shifting procurement toward cryogenic fluid chemistry specialists and compressing margin pools for legacy metallurgical suppliers.
Pricing Analysis
Long-term offtake contracts with nickel-indexed pricing dominate equipment procurement between station operators and compressor manufacturers. Three-tier pricing structure across ISO 19880-1 certified premium systems, KBA/METI-compliant standard configurations, and uncertified economy alternatives separates qualified from unqualified supply. Cost compression in standard-tier mechanical compressors is intensifying because electrochemical alternatives eliminate hydrogen embrittlement risks. Industrial ammonia producers exhibit lowest price sensitivity due to feedstock cost pass-through mechanisms, while municipal bus fleet operators demonstrate highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Extended lead times for ASTM A286 and Inconel 718 forgings now stretch 18-24 months for high-pressure vessel components. Manufacturing concentrates in Germany, Japan, and South Korea where qualified welder certifications for ASME Section VIII pressure vessels remain scarce. Component sourcing draws from specialized alloy foundries, cryogenic pump fabricators, and fiber-optic sensor integrators. Single-source vulnerability concentrates in Japanese metallurgical suppliers capable of hydrogen embrittlement-resistant forgings. Distribution runs through electrolyzer-to-dispenser EPC contractors rather than standalone equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through KBA and METI type-approval timelines creates durable incumbent advantages against fast-follower competition.
For Market Incumbents: Compound certification moats by accelerating ISO 19880-1 validation pipelines ahead of competitor entry timelines. Deepen backward integration into specialized alloy forging supply through captive partnerships with German and Japanese metallurgical suppliers. Electrochemical compression substitution threatens mechanical compressor margins; defend position through ionic liquid chemistry IP licensing to emerging station developers. For New Entrants and Emerging Players: METI hydrogen safety standards revision fast-tracks market access for fiber-optic sensing-integrated dispenser architectures. White-space concentrates in India's Mundra and Hazira industrial zones before domestic compressor manufacturing scales. Target temporary modular installations for construction-phase hydrogen supply where type-approval timelines compress. Go-to-market angle: electrolyzer-to-dispenser integration for isolated fleet depots bypassing centralized liquefaction infrastructure. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors electrolyzer-to-dispenser integrators with captive offtake contracts. Five-to-ten year viability hinges on port authority bundling contract capture rates. Acquisition target archetype: cryogenic fluid chemistry specialists with ionic compressor pilot deployments. Signal to watch: IMO 2025 alternative fuel framework adoption velocity for maritime bunkering protocol standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyzer Manufacturing | Captive hydrogen supply secures margin capture across liquefaction-to-dispensing chains for industrial hub operators. |
| ISO 19880-1 Certification Acceleration | First-mover validation in Germany and Japan locks out competitors through 18-24 month regulatory timelines. |
| Port Authority Bundling Contracts | Rotterdam and Singapore terminal developments anchor offtake certainty before electrolyzer commissioning completes. |
| Ionic Liquid Compressor Scale-Up | Elimination of metallic friction wear extends maintenance intervals beyond conventional mechanical design limits. |
| Fiber-Optic Sensing Integration | METI-mandated redundant pressure relief architectures add 15-20 percent to bill-of-materials costs for Asian-market dispensers. |
Research Methodology
Operator-level perspectives from station deployment managers, electrolyzer EPC contractors, port authority infrastructure planners, and fleet procurement directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EU Hydrogen Strategy implementation trackers, KBA type-approval registries, METI safety standards documentation, and national hydrogen roadmap filings. Bottom-up equipment shipment tallies triangulated against top-down infrastructure investment commitments across Germany, Japan, South Korea, and India.
Sensitivity analysis tested forecast robustness against electrolyzer commissioning delays, alloy supply disruptions, and battery electric vehicle substitution scenarios. Segmentation modeling spanned product type, compression technology, end-use application, and installation permanence dimensions. CAGRs derived from equipment procurement timelines tied to fuel cell fleet delivery schedules and industrial cluster electrolyzer commissioning dates. Industry-specific inputs included KBA/METI certification queue lengths and port authority green ammonia terminal development pipelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU F-Gas Regulation enforcement and stable heavy-duty fleet procurement mandates; material deviation in regulatory stringency or battery electric corridor build-out would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
Green Energy Hydrogen Production System Market