
 GPU Database Market | 2026-2036
GPU Database Market Size, Share, and Industry Trends Forecast 2026-2036
GPU Database Market Intelligence
The move toward databases optimized for tensor core architectures and specialized AI accelerators is reorganizing the competitive landscape. Nvidia leverages its full-stack dominance from hardware to its CUDA software ecosystem, creating a powerful moat. Kinetica specializes in real-time analytics for geospatial and time-series data, targeting defense and logistics sectors. Brytlyt differentiates with its focus on direct PostgreSQL integration, offering a familiar interface for enterprise IT teams.
A GPU database is a database management system that utilizes the parallel processing architecture of a graphics processing unit to accelerate analytical queries. These systems employ in-memory, columnar storage formats to handle massive datasets for complex, high-throughput computations. Real-time analytics and machine learning applications represent the largest and fastest-growing demand segments. Cloud deployments are significantly outpacing on-premises installations, driven by enterprise demand for elastic scalability and managed infrastructure services.
Data governance regulations, including Europe's GDPR and the forthcoming EU AI Act, impose strict requirements on data processing, lineage, and model transparency. National data sovereignty laws in jurisdictions like China and India influence deployment choices, often favoring on-premises or sovereign cloud solutions. Vendor selection will increasingly hinge on the ability to demonstrate auditable compliance and support complex, hybrid, and multi-cloud data fabrics.
Market Dynamics
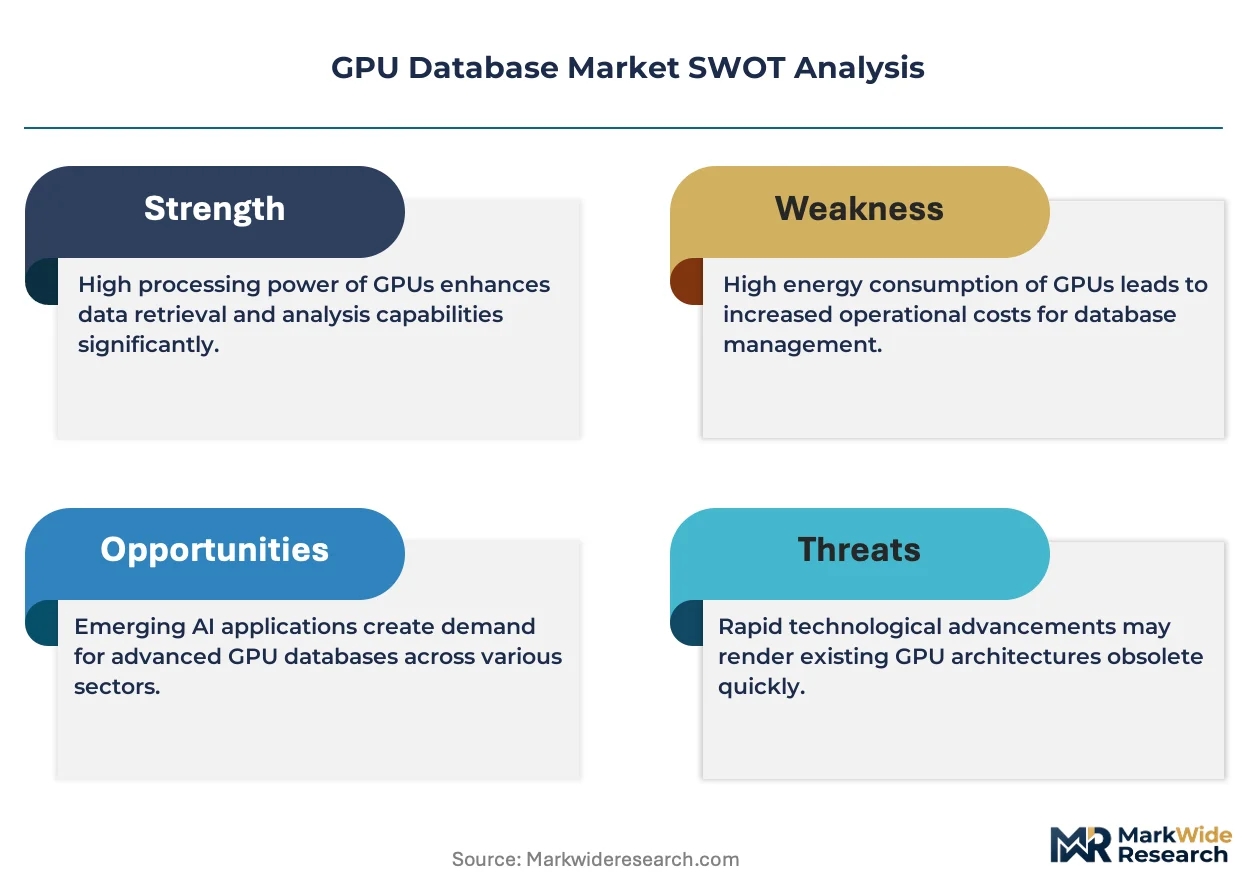
The proliferation of large language models and generative AI applications is the central force reshaping the data infrastructure landscape. This shift creates unprecedented demand for the parallel processing capabilities inherent to GPU databases, driving enterprise adoption for complex analytical workloads.
Growth Catalysts
- Generative AI Workloads:Training and inference for large language models demand massive, high-throughput data processing that GPU databases are architected to handle.
- Financial Services Adoption:High-frequency trading and risk analysis in financial centers like New York and London require real-time query performance on immense datasets.
- Scientific Research Expansion:National research programs in the United States and Germany fund supercomputing centers using GPU analytics for genomics and climate modeling.
Market Restraints
- High Total Cost of Ownership:Specialized GPU hardware and premium software licensing create a significant cost barrier for small and medium-sized enterprises.
- Data Movement Bottlenecks:Performance is often constrained by the latency of data transfer between CPU-based storage and GPU memory over the PCIe bus.
- Data Sovereignty Compliance:National data residency laws in China and India complicate cloud deployments, forcing costly on-premises or sovereign cloud architectures.
Strategic Opportunities
- Edge Computing Analytics:Deploying lightweight GPU databases on edge devices for real-time processing in autonomous vehicles and smart factories is a new frontier.
- Emerging Tech Hubs:Markets in South Korea and Israel show strong potential for adoption within their growing AI startup and cybersecurity ecosystems.
- AI Accelerator Integration:Optimizing databases for new AI accelerators beyond GPUs, such as TPUs and other ASICs, can capture emerging hardware ecosystems.
Industry Challenges
- Specialized Skill Scarcity:A shortage of data engineers and database administrators with expertise in CUDA programming and parallel computing architectures constrains enterprise deployment and management.
- Legacy System Complexity:Integrating GPU databases with existing enterprise data warehouses, ETL pipelines, and business intelligence tools presents significant technical hurdles and implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPU Database Market |
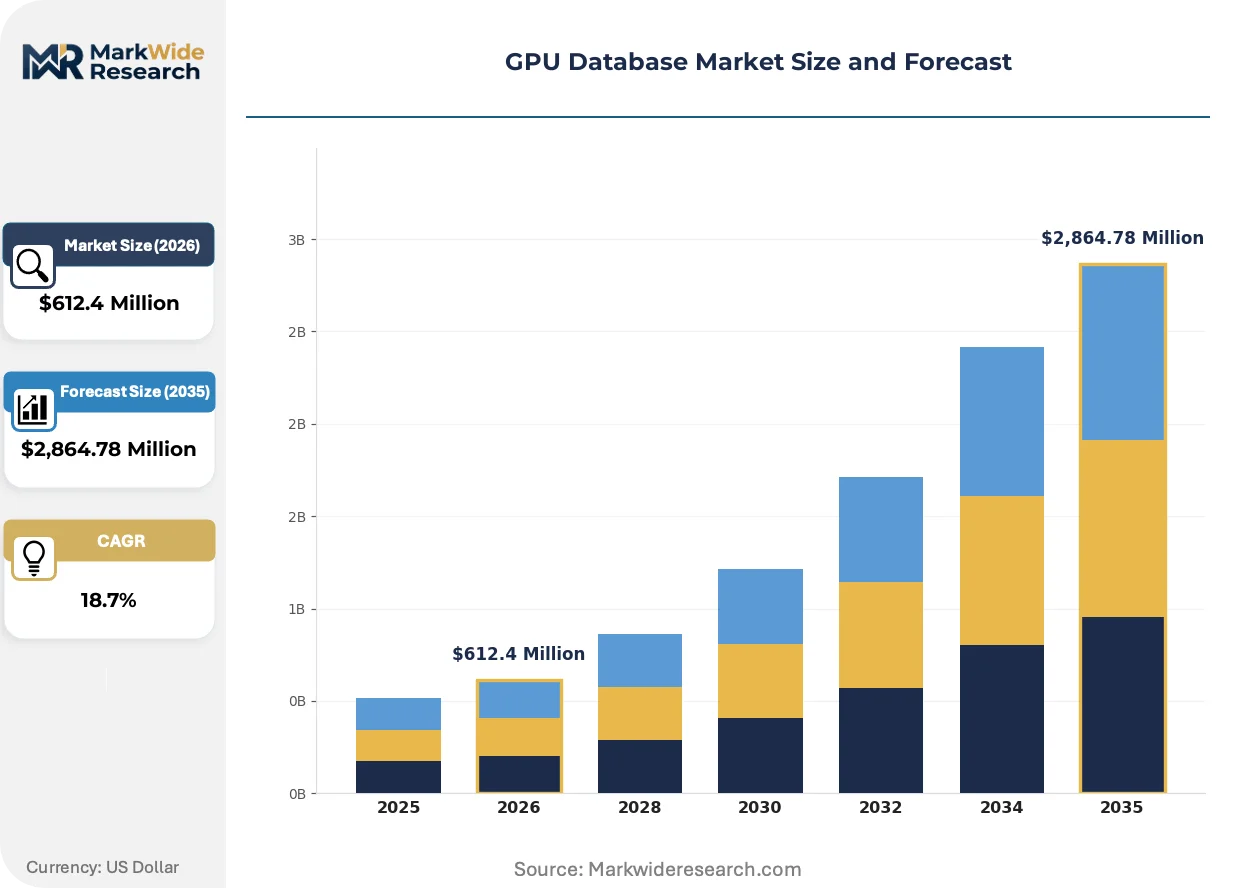
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Edge, Multi-Cloud Technology: CUDA, OpenCL, Vulkan, DirectX, Metal, ROCm Application: Real-Time Analytics, Machine Learning, Scientific Computing, Image Processing, Data Visualization End User: Financial Services, Media & Entertainment, Aerospace, Academic Research |
| Companies Covered | Brytlyt, Neo4j, Kinetica, H2O.ai, Zilliz, Omnisci, BlazingDB, Nvidia, Sqream, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPU Database Market Strategic Shifts & Innovations
The convergence of hardware and software stacks is defining the market's trajectory. Vendors are moving beyond raw query acceleration to offer integrated platforms that combine data management, machine learning libraries, and visualization tools into a unified analytical environment.
In-memory columnar storage organizes data for massively parallel processing directly on the GPU. Financial services and scientific research institutions are the primary adopters, seeking to eliminate traditional storage I/O bottlenecks. This architectural approach is displacing disk-based, row-oriented databases for analytical workloads where query latency is a critical performance metric.
Europe's AI Act introduces stringent requirements for data governance, transparency, and algorithmic model auditability. This regulation compels database vendors to embed features for tracking data lineage and logging model behavior to prove fairness. Consequently, enterprises operating within the EU prioritize solutions that can demonstrate auditable compliance, directly influencing vendor selection criteria.
A transition from perpetual software licensing toward consumption-based pricing on cloud platforms is gaining momentum. This model allows enterprises to align costs directly with usage, replacing large upfront capital expenditures with scalable operational expenses. The shift is most visible within the technology and media sectors in the United States, where workload variability favors elastic, managed infrastructure.
GPU Database Market Segmentation
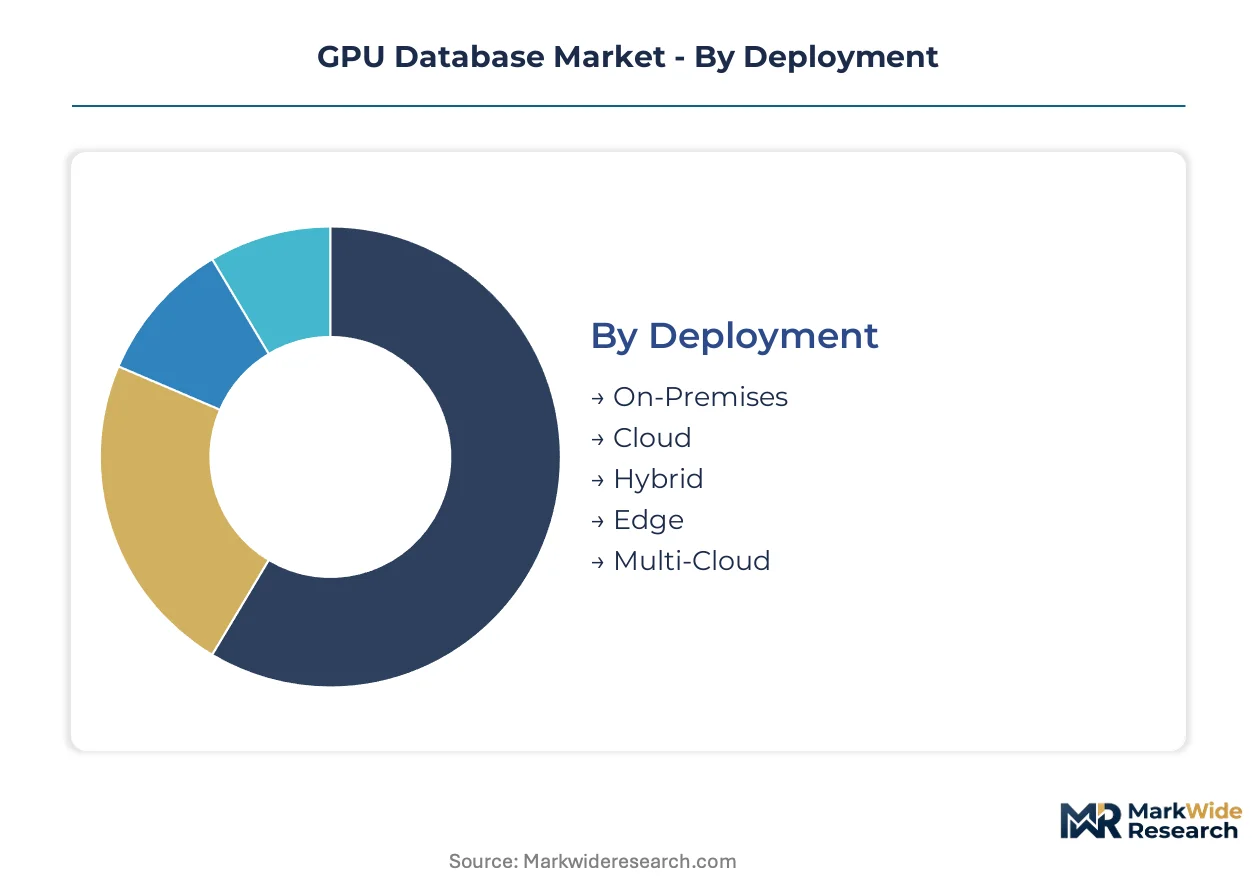
The GPU database market segmentation illustrates the diverse operational and technical requirements driving adoption across various enterprise landscapes. Understanding these distinct segments helps identify specific user needs, technological preferences, and growth trajectories within this specialized data infrastructure. These categories illuminate where specialized parallel processing capabilities deliver maximum value.
Deployment:
The substitution pressure on traditional on-premises deployments is intensifying, driven by the agility and cost-efficiency of cloud-native solutions.
- Cloud:Cloud deployments leverage managed infrastructure services for elastic scalability and reduced operational overhead. Demand concentrates in technology and media sectors in the United States, driven by variable workloads and a preference for OPEX models.
- Edge:Edge deployments integrate lightweight GPU databases directly onto devices for localized, real-time data processing. Autonomous vehicles and smart factories represent key demand areas, requiring immediate insights without cloud latency.
- On-Premises:On-Premises installations provide maximum control over data security and compliance, favored by organizations with strict data sovereignty requirements.
- Hybrid:Hybrid deployments combine on-premises infrastructure with cloud resources, offering flexibility for sensitive data and burst workloads.
- Multi-Cloud:Multi-Cloud strategies distribute GPU database workloads across multiple public cloud providers to enhance resilience and avoid vendor lock-in.
On-Premises anchors the volume base while Cloud gains share at the steepest rate.
Technology:
Supply concentration within the GPU database technology stack heavily favors proprietary ecosystems, yet open-source alternatives are steadily expanding their reach.
- CUDA:CUDA is Nvidia's proprietary parallel computing platform and programming model, widely adopted for GPU database acceleration. Its extensive library support and developer community drive demand in AI research and high-performance computing clusters.
- ROCm:ROCm (Radeon Open Compute platform) is AMD's open-source programming platform for GPU computing, offering an alternative to proprietary solutions. It is gaining traction in academic research and specific scientific computing environments seeking vendor independence.
- OpenCL:OpenCL provides an open standard for parallel programming across diverse processors, supporting cross-platform GPU database development.
- Vulkan:Vulkan is a low-overhead, cross-platform 3D graphics and compute API, finding niche applications in data visualization within GPU databases.
- DirectX:DirectX, Microsoft's collection of APIs, primarily supports gaming and graphics, with limited direct application in GPU database compute.
- Metal:Metal is Apple's low-overhead API for graphics and compute, optimized for its hardware, serving specific macOS/iOS GPU database deployments.
CUDA dominates the established market, while ROCm exhibits the steepest expansion trajectory for open-source alternatives.
Application:
Application focus for GPU databases is shifting towards complex, real-time analytical tasks that require massive parallel processing capabilities.
- Real-Time Analytics:Real-Time Analytics applications leverage GPU databases for immediate insights from streaming data, critical for fraud detection and network monitoring. Financial services in New York and London represent significant demand, requiring instant query performance.
- Machine Learning:Machine Learning applications, particularly for training large language models and generative AI, heavily rely on GPU databases for high-throughput data processing. Technology clusters in the United States and China drive this demand for advanced AI development.
- Scientific Computing:Scientific Computing utilizes GPU databases for complex simulations and data analysis in fields like genomics and climate modeling.
- Image Processing:Image Processing applications benefit from GPU databases for rapid analysis of large visual datasets in medical imaging and surveillance.
- Data Visualization:Data Visualization tools integrate with GPU databases to render complex datasets interactively, supporting exploratory analysis.
Real-Time Analytics forms the primary use case, with Machine Learning applications climbing the fastest in adoption.
End User:
The margin profile for GPU database solutions varies significantly across end-user sectors, reflecting differing data volumes, criticality, and regulatory overheads.
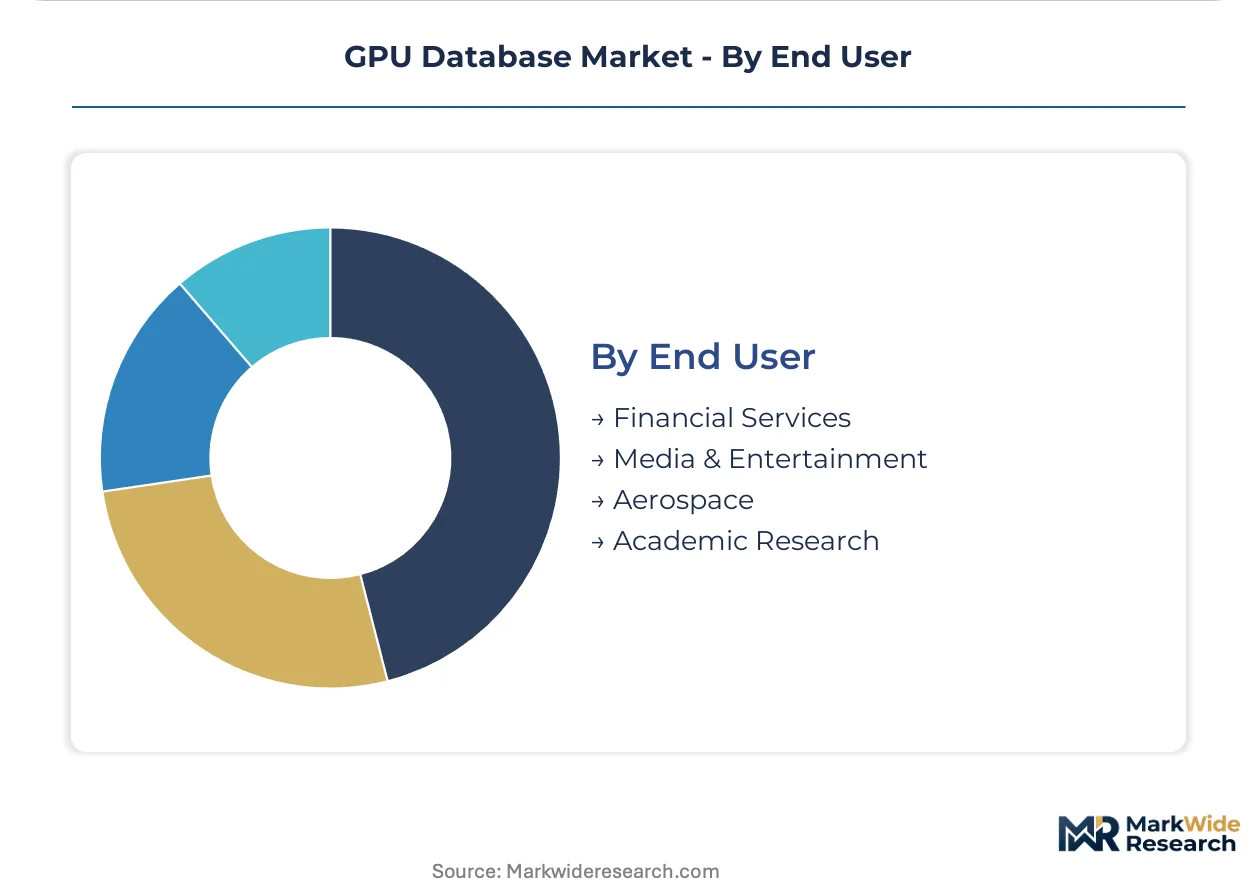
- Financial Services:Financial Services employ GPU databases for high-frequency trading, algorithmic risk analysis, and fraud detection. This sector demands ultra-low latency and processes immense datasets, justifying premium solutions.
- Academic Research:Academic Research institutions utilize GPU databases for large-scale scientific simulations, genomics, and climate modeling. National research programs in the United States and Germany fund these supercomputing centers.
- Media & Entertainment:Media & Entertainment companies use GPU databases for rendering complex graphics, video analytics, and content recommendation engines.
- Aerospace:Aerospace applications include processing sensor data from aircraft, satellite imagery analysis, and complex simulation for design and testing.
Financial Services represent the most lucrative segment, while Academic Research consistently drives innovation and foundational adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GPU database market exhibits a nuanced regional demand landscape, with technological innovation centers often importing specialized hardware while exporting advanced software solutions. This dynamic creates distinct market structures, influenced by local regulatory frameworks and industry concentrations, across major economic blocs.
United States
Demand for GPU databases in the United States stems from financial services for high-frequency trading and technology clusters developing large language models. The SEC's stringent data reporting requirements drive demand for auditable, high-performance analytical systems. Major tech hubs like Silicon Valley and New York City concentrate significant adoption for AI research and real-time financial analytics.
China
China's GPU database market is propelled by massive investments in generative AI applications and scientific computing initiatives. National data sovereignty laws, enforced by the Cyberspace Administration of China, influence deployment choices, favoring on-premises or sovereign cloud solutions. Technology parks in Beijing and Shenzhen are at the forefront of GPU database deployment for advanced AI development.
Germany
Germany's market for GPU databases is driven by scientific research in genomics and climate modeling, alongside industrial applications in advanced manufacturing. The EU AI Act imposes strict requirements for model transparency and data governance, shaping vendor selection criteria. Supercomputing centers in cities like Jülich and Dresden utilize GPU analytics for complex simulations.
United Kingdom
The United Kingdom's financial services sector, particularly in London, requires GPU databases for real-time risk analysis and fraud detection. GDPR regulations mandate robust data privacy and processing controls, influencing database architecture and compliance features. Financial technology firms in London leverage these systems for ultra-low latency query performance on immense datasets.
South Korea
South Korea exhibits a strong potential for GPU database adoption within its burgeoning AI startup ecosystem and advanced manufacturing industries. Regulations from the Ministry of Science and ICT support investments in AI infrastructure and data processing capabilities. Tech clusters in Seoul and Daejeon are increasingly deploying GPU databases for machine learning and real-time analytics.
GPU Database Market Key Industry Players
Listed leaders compete with private specialists across the GPU database market, which features a mix of established technology giants and agile startups. The market structure includes a foundational layer of hardware providers, a mid-tier of software platform developers, and specialized solution providers. Strategic partnerships and technology licensing agreements are dominant competitive moves among market participants.
Within the full-stack technology tier, Nvidia exemplifies a dominant position, leveraging its extensive hardware and CUDA software ecosystem. Specialists in real-time analytics for geospatial and time-series data, such as Kinetica, target defense and logistics sectors. Brytlyt occupies a position focused on direct PostgreSQL integration, offering a familiar interface for enterprise IT teams.
| Leading Market Players |
|---|
| Brytlyt |
| Neo4j |
| Kinetica |
| H2O.ai |
| Zilliz |
| Omnisci |
| BlazingDB |
| Nvidia |
| Sqream |
| Others |
Cost & Logistics Intelligence
GPU accelerator lead times, often extending several quarters, directly influence the supply chain shape for GPU databases and impact pricing power for specialized hardware and integrated solutions. This extended procurement cycle creates pricing stability for premium offerings but also incentivizes long-term contracts.
Pricing Analysis
Industrial OEM buyers anchor the GPU database market's pricing structure, often negotiating long-term contracts for embedded solutions. Pricing stratifies across performance tiers, reflecting query acceleration capabilities and data volume handling, with customization levels and dedicated support services driving premium differentiation. Pricing pressure stems from the high total cost of ownership for specialized hardware and increasing viability of open-source alternatives. Financial services and hyperscale cloud providers exhibit the lowest price sensitivity, prioritizing performance and reliability over cost, while small and medium-sized enterprises are most sensitive.
Supply Chain Analysis
Port congestion in key Asian manufacturing hubs can introduce volatility into the GPU database supply chain, impacting hardware availability and delivery schedules. Geographic supply concentration for core GPU components centers on Taiwan, South Korea, and the United States. The market draws from critical raw materials like silicon and relies on specialized memory technologies such as HBM. Geopolitical tensions represent a significant structural risk, particularly concerning semiconductor production, while distribution runs through direct vendor sales and cloud marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU database deployments represent a significant service-attach opportunity, with managed infrastructure services and specialized consulting expanding faster than raw hardware sales. This trend underscores the value of integrated platforms and expert support for complex AI workloads.
For Market Incumbents:
Secure full-stack integration across hardware and software ecosystems to counter emerging open-source alternatives like ROCm, which threaten market share. Invest in advanced R&D for AI accelerator optimization beyond traditional GPUs, ensuring compatibility with new ASIC architectures. Focus on strengthening enterprise-grade data governance features to meet stringent regulatory requirements like the EU AI Act, mitigating compliance risks for clients.
For New Entrants and Emerging Players:
Differentiate on ease of integration with existing enterprise data stacks and offer specialized solutions for niche applications like edge analytics. Target the mid-market segment and specific industries such as manufacturing or smart cities, where legacy system complexity offers white space. A strong go-to-market angle involves developer evangelism and providing familiar interfaces through direct PostgreSQL integration.
For Investors and Strategic Acquirers:
Long-term, this sits as a foundational infrastructure play because data-intensive AI workloads will continue to scale exponentially across industries. Acquisition targets should include specialized software vendors with strong intellectual property in GPU-native query optimization and real-time analytics capabilities. The signal to watch is increasing enterprise migration from CPU-based analytical systems to GPU databases for mission-critical applications, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies data management, ML libraries, and visualization tools for a seamless analytical experience. |
| AI Accelerator Optimization | Extends database compatibility to TPUs and other ASICs, capturing emerging hardware ecosystems. |
| Hybrid Cloud Solution Development | Addresses data sovereignty and burst workload requirements for large enterprise clients. |
| Developer Ecosystem Expansion | Fosters community contributions and broadens adoption through open-source initiatives. |
| Real-time Analytics Specialization | Enhances performance for high-frequency trading and fraud detection in financial services. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews with data engineers, database administrators, CTOs, and AI/ML researchers. This primary fieldwork was validated against a comprehensive review of secondary data sources, including SEC filings of major hardware vendors, academic research papers, industry association reports, and specialized technology publications. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and market sizing integrity.
Across the analysis window, the forecast framework integrated quantitative modeling with qualitative market insights to project future growth. Segmentation dimensions included deployment type, underlying technology, primary application, end-user industry, and regional demand patterns. Compound annual growth rates were derived from historical data trends and projected adoption rates, with GPU unit shipments and enterprise AI spending serving as key forecast inputs.
Forecasts assume regulatory continuity in the EU, China, and US; material policy shifts require re-modeling. Projections reflect current technological trajectories, but geopolitical tensions and AI regulatory shifts pose specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Data Deduplication Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Global Data Fabric Market