
 Voice Remote Control Market | 2026-2036
Voice Remote Control Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Remote Control Market Insights
Consumer electronics retail is rewriting how voice remote controls reach end users, with online retail platforms and electronics outlets now commanding the primary flow of transactions. Universal Electronics Inc. leverages its position as a white-label supplier to major cable operators, sustaining volume through long-term OEM contracts. Sony Corporation differentiates through proprietary far-field microphone arrays embedded in its Bravia-compatible remotes.
A voice remote control is a handheld wireless peripheral that captures spoken commands via integrated microphones, processes audio through on-device or cloud-based speech recognition engines, and transmits infrared or Bluetooth Low Energy signals to control consumer electronics; typical units incorporate MEMS microphones, low-power SoCs, and coin-cell batteries rated for six to twelve months of operation. Speech recognition technology leads the technology dimension due to its direct mapping to user commands, while natural language processing represents the fastest-expanding layer as conversational queries replace button-press sequences. Smart TVs anchor the product type segment through bundled inclusion with premium display purchases, whereas home assistants are maturing into a replacement-driven category with slower incremental attachment.
The FCC governs radio frequency emissions and spectrum allocation for voice remotes sold in the United States, while CE marking under the EU Radio Equipment Directive governs market access across European member states. REACH compliance additionally constrains material selection for plastics and solder compositions in remotes manufactured for European distribution. Stakeholders must monitor evolving interoperability mandates from streaming platforms that increasingly dictate which voice protocols gain device certification.
Market Dynamics
The voice remote control market is being restructured by streaming platform certification mandates that now gate device interoperability, forcing hardware manufacturers to align voice protocol stacks with proprietary requirements from content aggregators.
Growth Catalysts
- Smart TV bundle penetration:Premium display manufacturers are integrating voice-enabled remotes as standard in-box accessories, expanding installed bases across North American and European households.
- FCC Part 15 compliance clarity:Defined radio frequency emission thresholds for 2.4 GHz Bluetooth peripherals have reduced certification uncertainty for US market entrants.
- MEMS microphone cost curves:Semiconductor foundry scale economies are compressing component costs for far-field microphone arrays, enabling mid-tier remote specifications.
Market Restraints
- Lithium coin-cell supply concentration:Battery cell production clusters in East Asian manufacturing hubs create single-source vulnerability for six-to-twelve month power specifications.
- REACH substance restrictions:European chemical compliance limits solder alloy compositions and plasticizer selections, constraining material substitution flexibility.
- Smartphone voice assistant substitution:Mobile device native speech recognition reduces dedicated remote necessity for streaming control in tablet-centric households.
Strategic Opportunities
- India cable operator digitization:TRAI mandate enforcement for addressable systems is accelerating replacement cycles for IR-to-voice remote upgrades.
- Healthcare accessibility applications:Voice navigation for vision-impaired users represents an underserved specification segment with distinct certification pathways.
- CE marking harmonization:EU Radio Equipment Directive alignment across member states reduces multi-country testing burden for pan-European distribution.
Industry Challenges
- Speech recognition engine licensing complexity:Cloud API royalty structures and data governance terms fragment vendor cost models.
- Legacy IR protocol integration:Backward compatibility requirements for set-top box estates extend firmware development timelines.
- Acoustic tuning skill scarcity:Far-field audio engineering expertise concentrates among semiconductor reference design partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Remote Control Market |
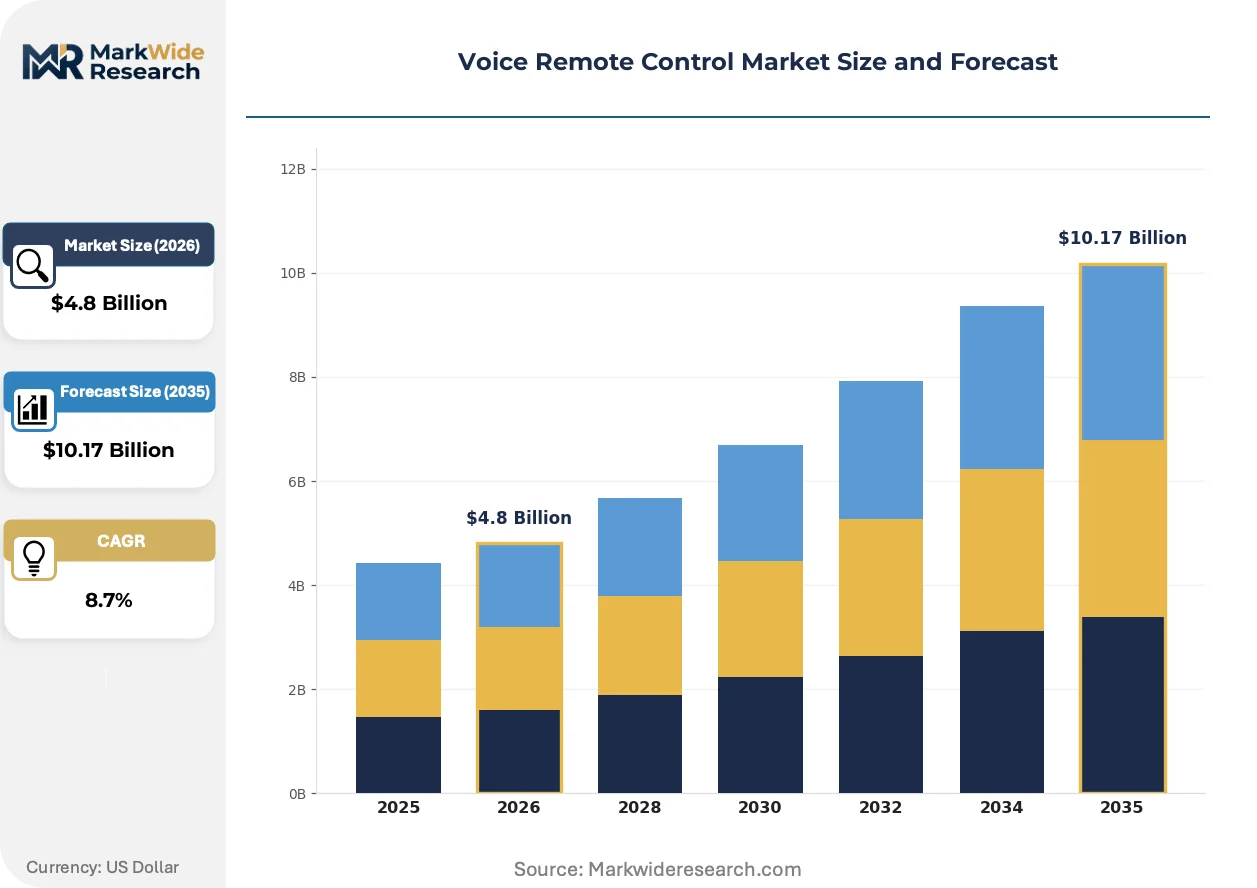
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart TVs, Streaming Devices, Sound Bars, Home Assistants Technology: Speech Recognition, Natural Language Processing, Machine Learning, Voice Activation End User: Households, Educational Institutions, Enterprises, Hospitality Distribution Channel: Online Retail, Specialty Stores, Electronics Outlets, Supermarkets |
| Companies Covered | Universal Electronics Inc., Logitech International S.A., Sony Corporation, Samsung Electronics Co. Ltd., LG Electronics Inc., Amazon.com Inc., Realtek Semiconductor Corp., Texas Instruments, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Remote Control Market Trends and Innovations
Edge AI inference is migrating voice processing from cloud dependency to on-device execution, compressing latency and addressing privacy constraints while redefing hardware specification requirements.
Ultra-low-power neural network accelerators are embedding directly into remote control SoCs, enabling wake-word detection without continuous radio transmission. Smart TV OEMs are adopting these chipsets for premium tier differentiation. This architecture is digitizing the traditional cloud-relay voice pipeline into localized command interpretation.
CE marking under the EU Radio Equipment Directive is tightening electromagnetic compatibility testing for 2.4 GHz spectrum coexistence. Manufacturers serving European distribution must now demonstrate interference resilience against Wi-Fi 6E and Bluetooth 5.3 congestion. The compliance burden falls heaviest on white-label suppliers without dedicated regulatory affairs functions.
Streaming platform certification programs are displacing generic Bluetooth HID profiles as the primary interoperability standard. Roku, Amazon Fire TV, and Google TV now mandate specific voice protocol implementations for remote control approval. This gatekeeping concentrates procurement decisions among platforms with certified peripheral ecosystems, visible most acutely in North American retail channel stocking decisions.
Voice Remote Control Market Segmentation
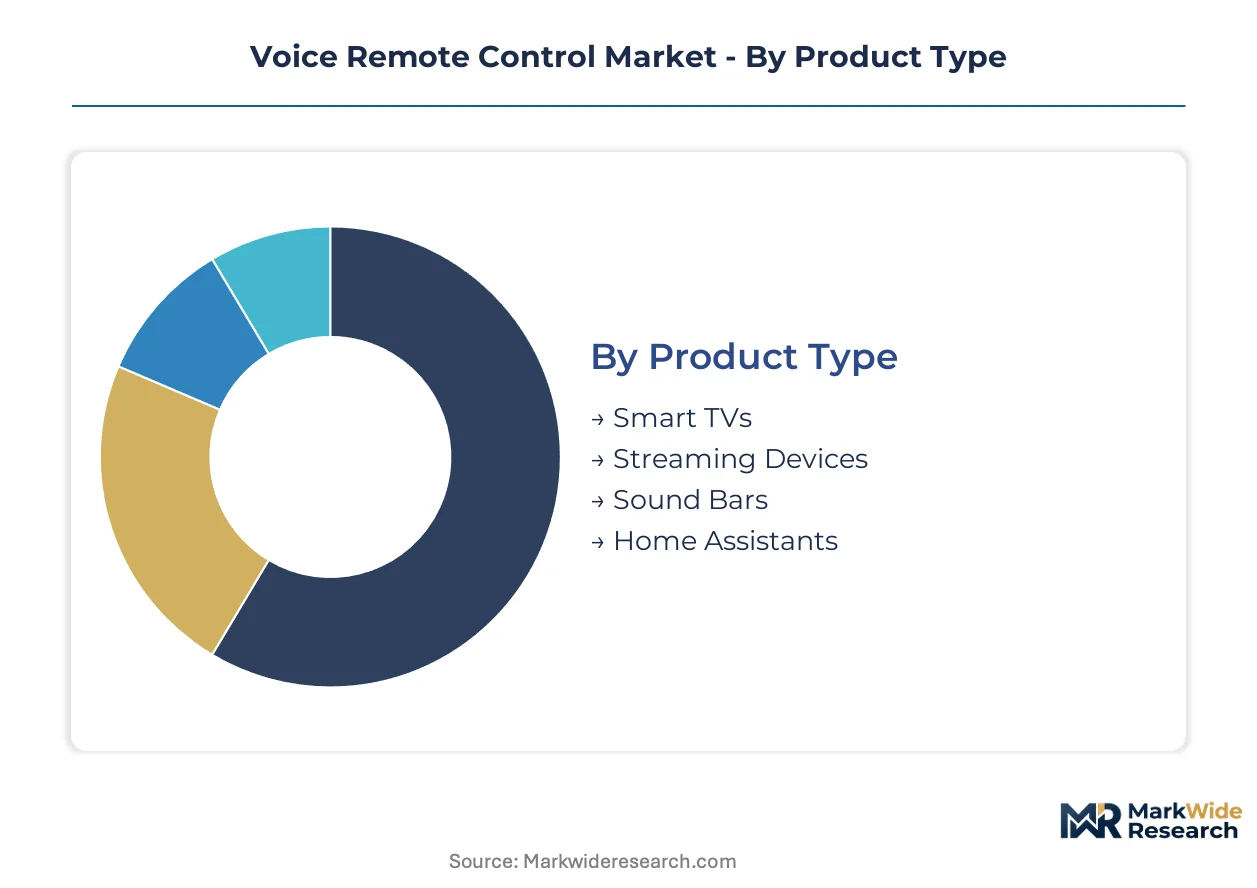
Voice remote control segmentation reveals how hardware specifications, software capabilities, and procurement pathways fragment addressable demand across consumer and commercial verticals. Understanding these divides exposes where component costs concentrate and which certification requirements gate market access.
Product Type:
Mature bundled categories dominate shipment volumes while emerging standalone formats reshape replacement dynamics.
- Smart TVs:Premium display OEMs integrate MEMS microphone arrays and Bluetooth Low Energy chipsets directly into in-box accessories. Sony Bravia bundles and Samsung Q-Series remotes anchor North American and European living room penetration through far-field voice capture specifications.
- Streaming Devices:Roku, Amazon Fire TV, and Google TV certification programs now mandate proprietary voice protocol implementations for peripheral approval. Platform gatekeeping concentrates procurement decisions among certified ecosystem partners in retail channels.
- Sound Bars:Audio-visual integration demands acoustic isolation engineering to prevent speaker feedback corrupting voice commands.
- Home Assistants:Replacement-driven category with slower incremental attachment as smart speaker penetration matures in tablet-centric households.
Smart TVs handle the majority of throughput; streaming devices are expanding most quickly on share.
Technology:
Cost tier stratification separates cloud-dependent architectures from edge-enabled local processing alternatives.
- Speech Recognition:Cloud-relayed audio processing dominates mid-tier remote specifications through API licensing arrangements with Amazon Alexa, Google Assistant, and proprietary cable operator stacks. Royalty structures fragment vendor cost models across deployment scales.
- Natural Language Processing:Conversational query interpretation is climbing the fastest as button-press sequences yield to multi-turn dialogue commands. Edge AI migration compresses latency and addresses privacy constraints in premium tier differentiation.
- Machine Learning:On-device wake-word detection without continuous radio transmission enables six-to-twelve month battery life specifications.
- Voice Activation:Low-power always-listening circuits trigger full system wake from sleep states.
Speech recognition captures the installed base; natural language processing is gaining share fastest.
End User:
Application context determines durability specifications, acoustic environment complexity, and procurement decision centralization.
- Households:Living room deployments face television audio interference and multi-speaker household noise profiles. CE marking electromagnetic compatibility requirements govern European market access for 2.4 GHz spectrum coexistence.
- Educational Institutions:Classroom and lecture hall installations demand extended-range microphone pickup and institutional fleet management capabilities.
- Enterprises:Conference room systems integrate voice remotes into unified communications platforms with IT-administered security policies.
- Hospitality:Hotel room deployments prioritize simplified pairing procedures and guest-privacy-focused local processing.
Households handle the majority of throughput; hospitality is the fastest mover on share.
Distribution Channel:
Customer type and purchase urgency separate direct-to-consumer digital platforms from assisted retail environments.
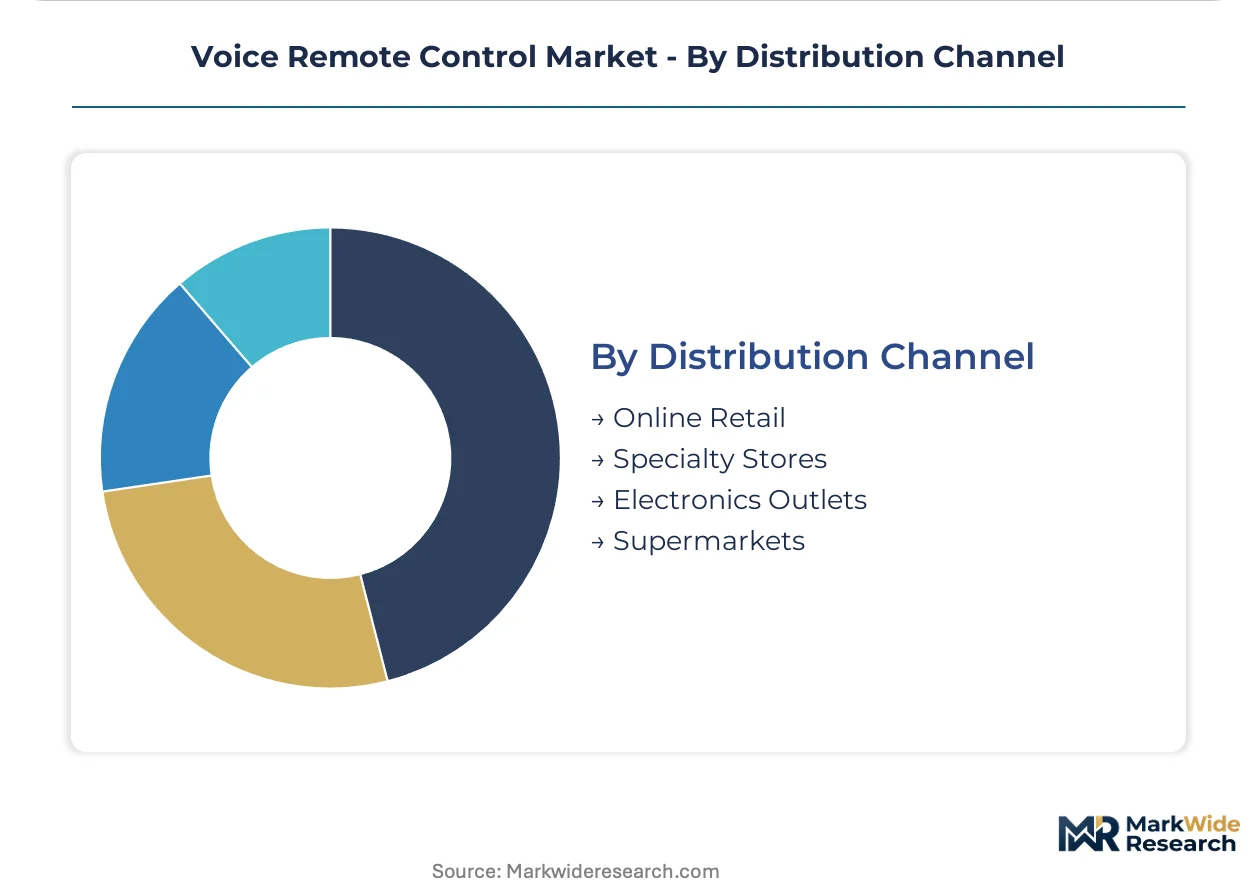
- Online Retail:Amazon, Best Buy digital storefronts, and OEM direct channels command primary transaction flow for replacement and upgrade purchases. Platform certification visibility influences stocking algorithms and search ranking.
- Specialty Stores:Custom installation professionals specify far-field microphone arrays and acoustic tuning for high-end home theater deployments.
- Electronics Outlets:Big-box retail chains bundle voice remotes with smart TV purchases through promotional pricing.
- Supermarkets:Mass-market impulse placement targets entry-level universal remote replacements.
Online retail handles the majority of throughput; specialty stores are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 compliance clarity for 2.4 GHz Bluetooth peripherals anchors the United States as the regulatory benchmark for voice remote certification, while CE marking under the EU Radio Equipment Directive governs European market access through electromagnetic compatibility mandates.
United States
Premium smart TV bundle penetration and cable operator digitization drive replacement cycles across North American households. FCC Part 15 defines radio frequency emission thresholds that reduce certification uncertainty for Bluetooth peripheral entrants. Manufacturing clusters concentrate in California's semiconductor design corridors and Texas electronics assembly hubs.
China
Domestic streaming platform partnerships with remote manufacturers accelerate hardware replacement velocity. MIIT radio transmission equipment certification governs 2.4 GHz and sub-1 GHz spectrum allocation for wireless peripherals. Yangtze River Delta foundries in Shanghai and Suzhou dominate MEMS microphone and low-power SoC fabrication.
Germany
CE marking compliance and REACH substance restrictions constrain material selection for European distribution channels. The EU Radio Equipment Directive mandates electromagnetic compatibility testing for Wi-Fi 6E and Bluetooth 5.3 spectrum coexistence. Industrial design expertise clusters in Bavaria around Munich's consumer electronics engineering centers.
India
TRAI mandate enforcement for addressable cable systems accelerates IR-to-voice remote upgrades nationwide. BIS certification requirements for electronic goods tighten quality standards for imported peripherals. Manufacturing investment concentrates in Gujarat and Tamil Nadu assembly corridors serving domestic consumer electronics demand.
South Korea
Smart TV OEM bundle strategies anchor living room voice peripheral penetration in premium display markets. MFDS and RRA radio equipment approvals govern Bluetooth Low Energy device market entry. Seoul Capital Area semiconductor design houses supply far-field microphone array reference designs to white-label manufacturers.
Voice Remote Control Market Competitive Landscape
White-label suppliers and branded OEMs split the market between volume-driven cable operator contracts and premium smart TV bundle positioning. The vendor base concentrates among semiconductor reference design partners, consumer electronics conglomerates, and streaming platform ecosystem gatekeepers. Three archetypes dominate: far-field audio engineering specialists, platform-certified ecosystem partners, and scale-driven white-label manufacturers. Competitive moves center on streaming platform certification acquisition and MEMS microphone cost curve compression through foundry partnerships.
Within the platform-certified ecosystem tier, Universal Electronics Inc. and Sony Corporation exemplify divergent positioning strategies. Universal Electronics occupies the white-label supply position through long-term OEM contracts with major cable operators, anchoring volume throughput without consumer-facing brand recognition. Sony Corporation sits within the premium-tier Bravia-compatible remote segment, representing proprietary far-field microphone array differentiation. Logitech International S.A. rounds out the named set as a Swiss-based consumer peripherals specialist with GmbH structure, exemplifying the universal remote replacement category that bridges legacy IR and voice-enabled specifications.
| Leading Market Players |
|---|
| Universal Electronics Inc. |
| Logitech International S.A. |
| Sony Corporation |
| Samsung Electronics Co. Ltd. |
| LG Electronics Inc. |
| Amazon.com Inc. |
| Realtek Semiconductor Corp. |
| Texas Instruments |
| Infineon Technologies |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Yangtze River Delta MEMS microphone foundries is compressing component pricing while simultaneously pressuring white-label manufacturers to absorb certification costs for streaming platform mandates, creating divergent margin trajectories between premium branded OEMs and volume-driven cable operator suppliers.
Pricing Analysis
North American retail channels command 15-25% premiums over equivalent specifications in Indian cable operator procurement, reflecting streaming platform certification value capture and far-field microphone array performance tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by voice protocol certification depth and acoustic isolation engineering. Pricing pressure stems from lithium coin-cell supply concentration in East Asian manufacturing hubs. Entry-level universal remote replacements exhibit highest price sensitivity; premium smart TV bundle positioning shows lowest.
Supply Chain Analysis
US export-control restrictions on advanced semiconductor manufacturing equipment constrain domestic foundry expansion for neural network accelerator SoCs, forcing voice remote designers toward Taiwanese and South Korean fabrication alternatives. Component sourcing draws from Chinese MEMS microphone suppliers, German electromagnetic compatibility testing laboratories, and Japanese battery cell manufacturers. Single-source vulnerability concentrates in Yangtze River Delta lithium coin-cell production. Distribution runs through white-label OEM contracts, streaming platform-certified ecosystem partnerships, and direct-to-consumer electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Far-field audio engineering expertise concentrates among a handful of semiconductor reference design partners, creating acquisition premiums for OEMs lacking in-house acoustic tuning capabilities and forcing strategic choices between capability building and ecosystem dependency.
For Market Incumbents: Build regulatory affairs moats by embedding dedicated CE marking and FCC Part 15 compliance teams ahead of EU Radio Equipment Directive tightening and Wi-Fi 6E coexistence mandates. Secure long-term MEMS microphone foundry partnerships to lock in cost curves against emerging fabless competitors. Streaming platform certification gatekeeping represents the primary threat; vertical integration into edge AI SoC design offers margin defense. For New Entrants and Emerging Players: India's TRAI-mandated cable digitization offers the most penetrable white-space target, with IR-to-voice upgrade cycles accelerating across addressable systems nationwide. Healthcare accessibility specifications for vision-impaired users present a second underserved segment with distinct procurement pathways and reduced platform certification barriers. Pursue white-label supply relationships with regional cable operators rather than direct consumer brand building. For Investors and Strategic Acquirers: Long-term, this sits as a component-consolidation play because streaming platform certification mandates will progressively concentrate procurement decisions among ecosystem-certified suppliers with dedicated regulatory affairs functions. Target acquisition profiles should emphasize white-label manufacturers with established cable operator relationships and pending platform certifications. Monitor FCC Part 15 rulemaking dockets for electromagnetic compatibility threshold adjustments as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Streaming Platform Certification Acquisition | Roku, Amazon Fire TV, and Google TV mandates now gate retail channel access and search algorithm visibility. |
| Edge AI SoC Integration Partnership | Ultra-low-power neural network accelerators from Realtek and Texas Instruments enable on-device wake-word detection without cloud dependency. |
| Far-Field Microphone Array Reference Design Licensing | South Korean and Taiwanese semiconductor houses concentrate acoustic tuning expertise unavailable through generic component sourcing. |
| Regulatory Affairs Function Buildout | CE marking under EU Radio Equipment Directive and REACH substance compliance require dedicated electromagnetic compatibility testing capabilities. |
| Lithium Coin-Cell Supply Agreement Diversification | East Asian manufacturing hub concentration creates single-source vulnerability for six-to-twelve month battery life specifications. |
Research Methodology
A standing panel of streaming platform hardware certification managers, cable operator procurement directors, MEMS microphone foundry sales engineers, and consumer electronics retail category buyers provided ongoing calibration throughout the research process. Primary interview insights triangulated against secondary validation from FCC equipment authorization databases, MIIT radio transmission equipment certification filings, EU Radio Equipment Directive notified body reports, and SEC 10-K disclosures from component suppliers. Bottom-up shipment modeling across product type, technology, and end-user segments converged with top-down value estimates derived from OEM contract structures and retail pricing audits.
Scenario-bracketing anchored the analytical framework, with base, upside, and downside cases reflecting streaming platform certification velocity, lithium coin-cell supply disruption probability, and smartphone voice assistant substitution rates across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user vertical, and distribution channel, with additional granularity on voice protocol certification status. CAGRs derived from logistic adoption curves fitted to smart TV bundle penetration trajectories and cable operator digitization mandates, incorporating MEMS microphone cost curve elasticity and REACH compliance cost pass-through assumptions.
Practitioners should monitor FCC Part 15 rulemaking dockets, EU Radio Equipment Directive implementing acts, and streaming platform certification program expansions for early signals of forecast revision. Forecasts reflect assumptions on platform gatekeeping persistence, foundry capacity utilization trajectories, and battery chemistry substitution timelines. Material shifts in streaming platform interoperability mandates or lithium supply chain restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Asia-Pacific Desktop Virtualization Market
Digital Solutions
Data Extraction Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
Cloud Electronic Design Automation Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Smart Connected Assets and Operations Market
Digital Solutions
Product As a Service Market
Digital Solutions
Video Management System Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Data Cleansing Tools Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
Service Mesh Market
Digital Solutions
Global Digital Art Software Market