
 Data Deduplication Market | 2026-2036
Data Deduplication Market Size, Share, and Industry Trends Forecast 2026-2036
Data Deduplication Market Outlook
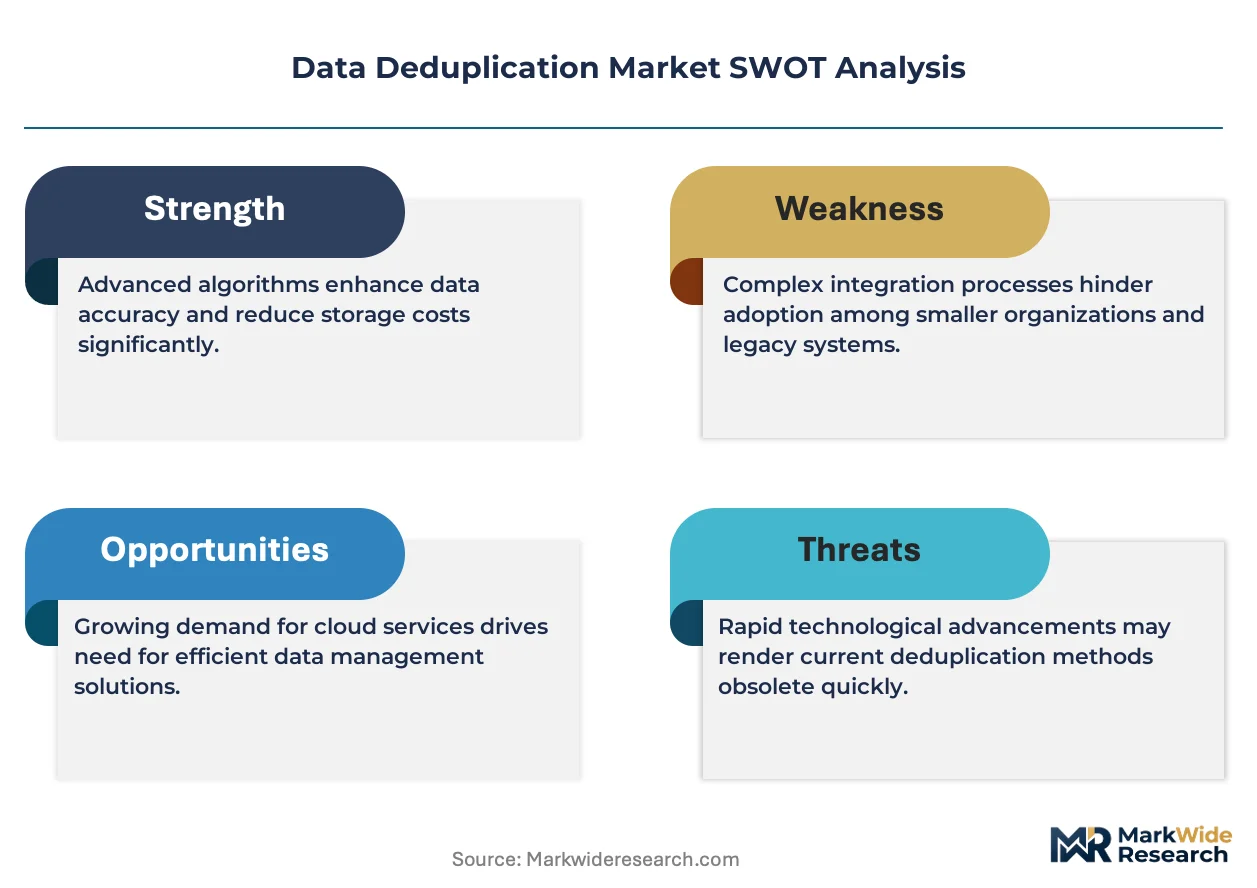
The capability gap between cloud-native and legacy on-premises data deduplication vendors is collapsing as hybrid architectures become standard. Talend leverages open-source integration frameworks to sustain development velocity across European enterprise accounts. Dun & Bradstreet anchors its competitive position through proprietary business identity graphs that reduce duplicate entity resolution cycles. Data Ladder specializes in fuzzy matching algorithms for mid-market CRM environments where data quality budgets remain constrained.
Data deduplication identifies and eliminates redundant copies of information through hash-based fingerprinting or byte-level comparison, reducing storage footprints by retaining single instances of identical data blocks while generating pointer references for subsequent occurrences. The technique serves primary industrial purposes in backup stream acceleration, disaster recovery bandwidth optimization, and long-term archival cost containment. Storage Optimization solutions dominate current revenue pools as enterprises confront exponential unstructured data growth, while Cloud Services deployment models represent the fastest-expanding segment as organizations migrate tier-2 workloads to distributed infrastructure. Hybrid deployment architectures capture disproportionate margin attention from IT Service Providers seeking to preserve governance controls while accessing elastic compute resources.
GDPR enforcement by European national data protection authorities and the EU AI Act's training data quality provisions are reshaping compliance-driven procurement specifications for deduplication accuracy thresholds. ISO 27001 certification requirements and sectoral frameworks from HIPAA in US healthcare further segment vendor eligibility across regulated industries. Stakeholders must evaluate how emerging quantum-resistant hashing standards will alter fingerprinting architectures before committing to long-term platform contracts.
Market Dynamics
Hybrid cloud architectures are collapsing the traditional boundary between on-premises and cloud-native deduplication platforms, forcing vendors to engineer unified data management stacks that span distributed environments without compromising fingerprinting integrity.
Growth Catalysts
- GDPR consolidation mandates:European data protection authorities enforce strict data minimization principles, compelling financial services firms to eliminate redundant customer records across fragmented repositories.
- Unstructured data explosion:Industrial IoT deployments in German manufacturing generate petabyte-scale sensor streams requiring real-time deduplication to control storage economics.
- Byte-level fingerprinting:Advanced hashing algorithms now process variable-block deduplication at line speed, eliminating the throughput penalties that previously constrained primary storage deployment.
Market Restraints
- Specialized engineering talent scarcity:Cryptographic hashing expertise and distributed systems architecture skills command premium compensation, inflating vendor R&D cost structures.
- Quantum vulnerability exposure:Current SHA-256 fingerprinting architectures face obsolescence risk as NIST post-quantum standards mature, creating platform refresh uncertainty.
- Legacy integration friction:Mainframe-era backup environments in US healthcare and European banking resist API-based deduplication overlays without costly middleware layers.
Strategic Opportunities
- EU AI Act training data quality:The regulation's accuracy requirements for AI systems create procurement pull for deduplication platforms that ensure clean, non-duplicative training corpora.
- Edge-to-core pipelines:Converged deduplication with 5G MEC infrastructure enables bandwidth-efficient aggregation from remote industrial sites before cloud transmission.
- Mid-market CRM penetration:Constrained data quality budgets among scaling SaaS companies create demand for lightweight, algorithm-as-a-service matching solutions.
Industry Challenges
- Cross-border data residency:Conflicting sovereignty requirements between Germany's BDSG, France's CNIL guidance, and emerging US state privacy laws fragment platform deployment architectures.
- False positive tolerance calibration:Fuzzy matching thresholds must balance aggressive redundancy elimination against accidental consolidation of distinct customer records, requiring domain-specific tuning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Deduplication Market |
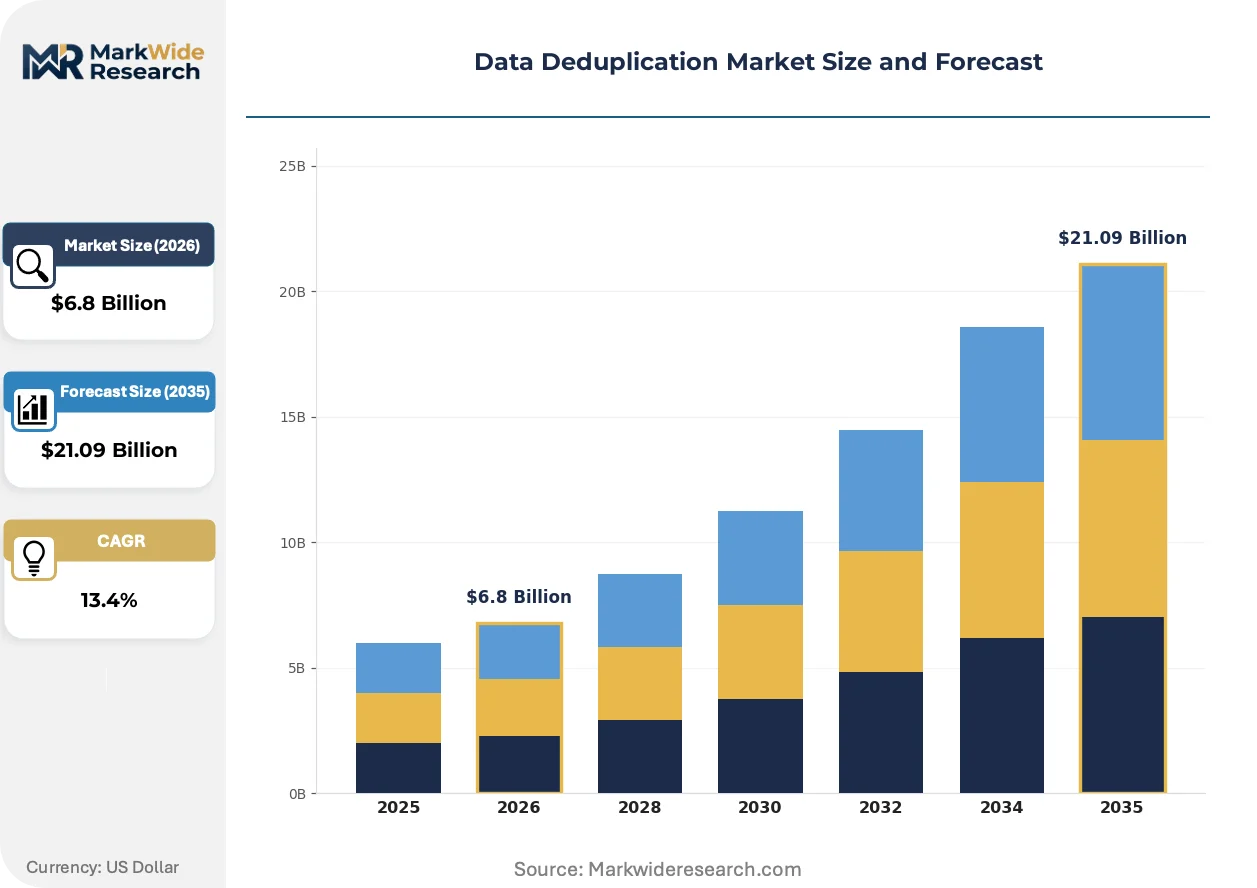
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Storage Optimization, Backup Solutions, Cloud Services, Data Management Deployment Model: On-Premises, Hybrid, Public Cloud, Private Cloud End User: Enterprises, SMBs, IT Service Providers, Government Agencies Application: Data Backup, Disaster Recovery, Archiving, Compliance |
| Companies Covered | No Duplicates, DataGroomr, Datamatics Business Solutions Inc., Dun & Bradstreet, Openprise, Melissa Clean Suite, Data Ladder, Talend, Cloudingo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Deduplication Market Strategic Shifts
Machine learning inference is embedding directly into deduplication pipelines, enabling context-aware redundancy detection that surpasses static hashing in handling semi-structured formats like JSON logs and document repositories.
Content-defined chunking algorithms are displacing fixed-block approaches in enterprise backup environments. Large-scale cloud service providers deploy these adaptive segmentation methods to achieve higher deduplication ratios against encrypted data streams. The technology is compressing storage hardware procurement cycles as customers defer capacity expansion.
EU AI Act training data quality provisions reshape vendor certification requirements. Data governance officers now mandate deduplication accuracy thresholds exceeding 99.5% for customer entity resolution before AI model ingestion. European financial services procurement teams embed these specifications into RFP evaluation matrices.
Subscription-based platform licensing supersedes perpetual software purchases among mid-market buyers. Channel partners bundle deduplication with managed backup services, displacing direct enterprise sales motions. This pattern concentrates in German industrial clusters where IT service providers maintain deep operational relationships.
Data Deduplication Market Segmentation
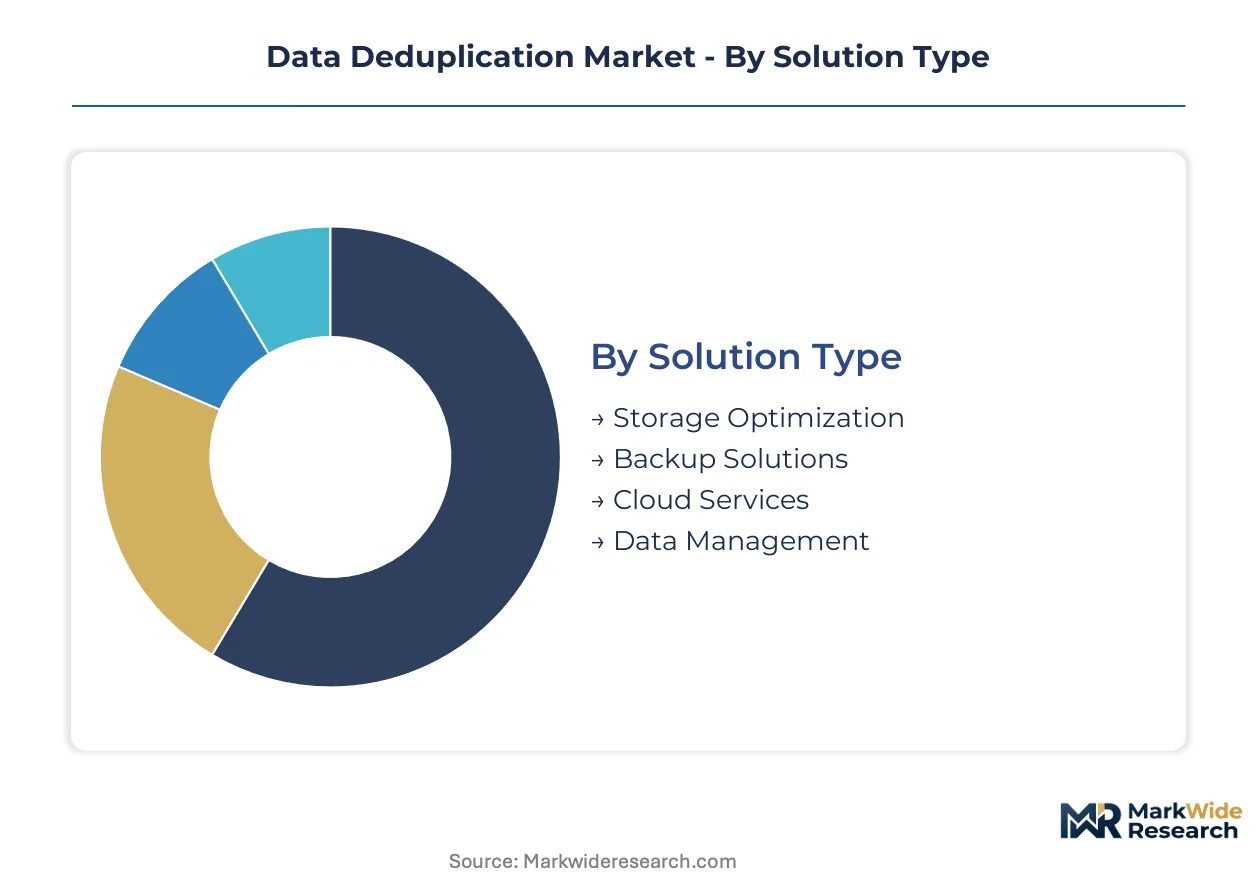
Segmentation reveals how deduplication technology adapts to divergent infrastructure constraints and compliance obligations across customer environments. Procurement patterns vary sharply between organizations prioritizing capital efficiency versus those demanding sovereign data control.
Solution Type:
Domestic procurement dominates storage-centric solutions, while cloud-native offerings increasingly serve cross-border enterprise deployments.
- Storage Optimization:Hash-based fingerprinting and byte-level comparison reduce physical storage footprints by eliminating redundant data blocks. German industrial conglomerates deploy these systems to manage petabyte-scale sensor archives from manufacturing IoT networks. Storage Optimization holds the largest share; momentum sits with Cloud Services.
- Backup Solutions:Variable-block deduplication accelerates backup stream throughput while compressing bandwidth requirements for remote replication. US healthcare systems under HIPAA mandates prioritize these platforms to secure patient record archives without capacity overruns.
- Cloud Services:Elastic deduplication-as-a-service enables tier-2 workload migration without upfront infrastructure commitment.
- Data Management:Unified governance platforms integrate deduplication with lineage tracking and quality scoring.
Cost tiering separates enterprise-grade platforms from mid-market alternatives.
Deployment Model:
Volume concentration tilts toward hybrid architectures as organizations straddle legacy systems and cloud migration timelines.
- Hybrid:Unified management stacks span on-premises and distributed cloud environments while preserving fingerprinting integrity across boundaries. European financial services firms favor this model to satisfy GDPR data residency requirements without sacrificing elastic compute access. Hybrid captures dominant volume; Public Cloud climbs the fastest.
- On-Premises:Dedicated hardware appliances deliver deterministic performance for latency-sensitive primary storage workloads. German automotive manufacturers maintain these deployments for proprietary design data under strict BDSG sovereignty rules.
- Public Cloud:Shared infrastructure reduces operational overhead for variable backup workloads.
- Private Cloud:Single-tenant environments address classified data requirements in defense and intelligence sectors.
Customer maturity determines deployment selection more than industry vertical.
End User:
Application complexity varies from standardized SMB packages to bespoke enterprise integrations.
- Enterprises:Global data estates demand petabyte-scale deduplication with sub-second query response across distributed repositories. French banking groups under CNIL guidance deploy these systems to consolidate fragmented customer databases ahead of EU AI Act compliance deadlines.
- IT Service Providers:Multi-tenant platforms enable managed backup services with tenant-isolated fingerprinting domains. German MSPs bundle deduplication into industrial maintenance contracts, embedding data quality into operational relationships.
- SMBs:Subscription licensing and simplified deployment reduce technical barriers for resource-constrained organizations.
- Government Agencies:Certified architectures meet classified processing requirements with air-gapped deployment options.
Procurement centralization distinguishes regulated industries from commercial adopters.
Application:
Margin structure favors compliance-driven deployments over cost-optimization use cases.
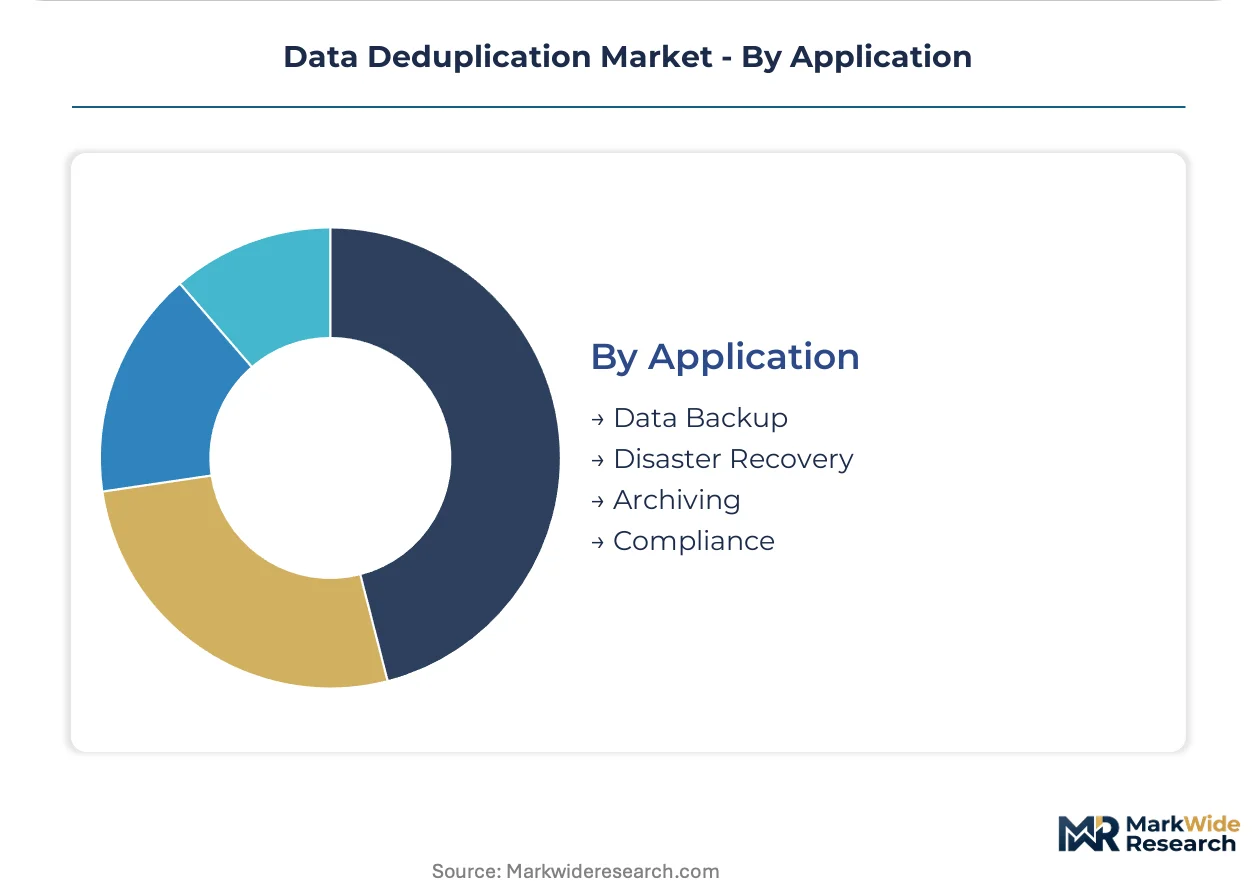
- Compliance:Entity resolution accuracy exceeding 99.5% supports AI training data quality mandates under EU AI Act provisions. European financial services procurement teams embed these thresholds into RFP evaluation matrices alongside GDPR minimization requirements.
- Disaster Recovery:Bandwidth-optimized replication enables recovery point objectives measured in minutes for critical operational systems. US healthcare networks under HIPAA business continuity rules prioritize these capabilities for patient care continuity.
- Data Backup:Routine protection of operational systems represents the most price-sensitive application segment.
- Archiving:Long-term retention with retrieval latency tolerance optimizes storage economics for historical records.
Regulatory pressure reshapes priority rankings across end-use categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial conglomerates deploy deduplication for petabyte-scale sensor archives, while US healthcare networks prioritize backup acceleration under HIPAA mandates. French banking groups consolidate fragmented customer databases ahead of EU AI Act deadlines. Japanese manufacturers and Indian IT service providers pursue divergent deployment models reflecting infrastructure maturity gaps.
United States
Healthcare systems under HIPAA business continuity rules drive bandwidth-optimized replication for patient record archives. The FDA's data integrity guidance for pharmaceutical manufacturing systems elevates deduplication accuracy requirements in life sciences. Boston's biomedical research cluster deploys entity resolution platforms to clean AI training corpora for clinical trial analytics.
Germany
Industrial IoT deployments across automotive and manufacturing sectors generate exabyte-scale data streams requiring real-time redundancy elimination. The BDSG imposes strict data residency rules that favor hybrid deployment architectures preserving sovereign control. Stuttgart's automotive engineering hub maintains on-premises deduplication appliances for proprietary design data under sector-specific confidentiality protocols.
France
Banking groups under CNIL guidance consolidate customer databases to satisfy GDPR minimization principles before EU AI Act enforcement. The country's national data protection authority mandates 99.5% accuracy thresholds for entity resolution in AI training pipelines. Paris-based asset managers deploy cloud-native deduplication to streamline cross-border fund administration data.
Japan
Precision manufacturing and robotics sectors deploy byte-level fingerprinting for deterministic primary storage performance. METI's data free flow with trust initiatives shape cross-border governance frameworks for industrial data sharing. Nagoya's automotive supplier ecosystem integrates deduplication with predictive maintenance platforms to compress sensor telemetry volumes.
India
IT service providers bundle deduplication into managed backup offerings for mid-market SaaS companies with constrained data quality budgets. The RBI's data localization directives for financial institutions accelerate domestic cloud infrastructure investment. Bangalore's technology corridor hosts delivery centers engineering fuzzy matching algorithms for global CRM environments.
Data Deduplication Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around hybrid platform capabilities that span on-premises and cloud-native deployments. Pure-play vendors concentrate on algorithmic differentiation in fuzzy matching and entity resolution, while diversified software houses embed deduplication within broader data management stacks. Strategic moves center on API ecosystem expansion and subscription licensing transitions that displace perpetual software purchases.
Within the integrated platform tier, Talend and Dun & Bradstreet occupy distinct positioning archetypes—one leveraging open-source integration frameworks, the other anchoring through proprietary business identity graphs. Data Ladder exemplifies the specialist vector, concentrating algorithm development for resource-constrained mid-market environments. These three entities collectively represent the competitive spectrum from horizontal platform breadth to vertical matching depth.
| Leading Market Players |
|---|
| No Duplicates |
| DataGroomr |
| Datamatics Business Solutions Inc. |
| Dun & Bradstreet |
| Openprise |
| Melissa Clean Suite |
| Data Ladder |
| Talend |
| Cloudingo |
| Others |
Value Chain & Pricing Dynamics
ISO 27001 certification gates vendor eligibility across European financial services procurement, simultaneously filtering supply-side participants and enabling price premiums for accredited platforms. This dual function compresses margins for uncertified entrants while rewarding incumbent investment in compliance infrastructure.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement, displacing perpetual licensing as the standard engagement structure. Three-tier pricing structure across premium, standard, and economy levels segments by deployment scale and support tier, with German industrial conglomerates showing lowest price sensitivity due to compliance-driven specification rigidity. Cost compression in mid-market SaaS tiers is intensifying because channel partners bundle deduplication into managed service margins. SMB buyers exhibit highest price sensitivity, prioritizing per-seat economics over advanced fuzzy matching capabilities.
Supply Chain Analysis
Inventory cycles for cryptographic hardware accelerators stretch lead times for high-throughput appliance vendors serving German automotive manufacturers. Supply concentrates in the United States for enterprise backup software, Germany for industrial IoT-integrated platforms, and India for IT service provider delivery centers. Component dependencies include SHA-256 hashing modules, NVMe storage controllers, and 5G edge computing chipsets. Single-source vulnerability in quantum-resistant algorithm IP creates renewal risk as NIST standards mature. Distribution runs through channel partners embedding deduplication within managed backup contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where switching costs lock enterprise customers into fingerprinting architectures, creating sustainable incumbent returns. Regulatory entrenchment through GDPR and EU AI Act certification requirements further hardens competitive positions.
For Market Incumbents: Fortify hybrid platform integration to counter cloud-native entrants exploiting API-first architectures. Invest in quantum-resistant hashing R&D before NIST standardization creates forced-migration windows. Deepen channel control through exclusive MSP partnerships in German industrial clusters, locking out specialist algorithm vendors from embedded operational relationships.
For New Entrants and Emerging Players: Lead with lightweight, algorithm-as-a-service matching solutions targeting mid-market CRM environments where Data Ladder's premium positioning leaves price-sensitive whitespace. Target Indian IT service providers bundling deduplication into RBI-mandated data localization contracts. Pursue vertical specialization in French banking entity resolution ahead of EU AI Act enforcement deadlines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment segments as subscription economics displace hardware-heavy appliance models. Favor acquisition targets possessing proprietary business identity graphs or fuzzy matching IP rather than commodity backup platforms. Monitor NIST post-quantum cryptography standardization timelines as inflection signal for platform refresh cycles and incumbent vulnerability windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Algorithm Migration | NIST standardization timelines force fingerprinting architecture refreshes across European financial services deployments. |
| Hybrid Platform Integration | Unified on-premises and cloud-native stacks capture GDPR-mandated data residency without sacrificing elastic compute access. |
| Channel Partner Embedding | MSPs in German industrial clusters lock customer relationships through operational maintenance contract bundling. |
| EU AI Act Certification Investment | 99.5% entity resolution accuracy thresholds become procurement gate for AI training data pipeline vendors. |
| Edge-to-Core Pipeline Development | 5G MEC convergence enables bandwidth-efficient aggregation from remote manufacturing sensor networks. |
Study Parameters
Desk research of vendor SEC filings, hyperscaler capex disclosures, and GDPR enforcement action databases preceded structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners. Primary fieldwork captured deployment architecture decisions across German automotive, French banking, and US healthcare environments. Secondary validation drew from ISO certification registries, NIST cryptographic standardization documents, and EU AI Act implementation guidance. Bottom-up sizing of subscription revenue pools triangulated against top-down IT services market allocation models.
Variance decomposition across deployment model, organization size, vertical, integration complexity, and regional adoption pattern anchored the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included cloud migration velocity indices, regulatory enforcement intensity scores, and sensor data volume projections from industrial IoT deployments.
Forecasts assume regulatory continuity in GDPR, EU AI Act, and HIPAA regimes; material policy shifts would require re-modeling. Quantum computing advancement timelines and NIST standardization acceleration represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Computer Servers Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Mobile Data Offload Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Network As a Service (Naas) Market
Data Center and Networking
Taiwan Data Center Networking Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Dark Fiber Network Market