
 Global Satellite Enabled IoT Software Market | 2026-2036
Global Satellite Enabled IoT Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Satellite Enabled IoT Software Market Foresight
The EU Green Deal is decoupling maritime logistics from terrestrial-only connectivity by mandating emissions transparency across international shipping corridors. Iridium Communications leverages its L-band constellation to sustain pole-to-pole coverage for vessel tracking in ice-bound routes. Orbcomm anchors its competitive position through hybrid cellular-satellite device management platforms that dominate North American freight rail. Thales differentiates via encrypted payload software serving defense and dual-use satellite IoT deployments.
Satellite enabled IoT software comprises middleware, firmware, and analytics platforms that translate narrowband satellite signals into actionable machine data, typically operating within sub-1 GHz spectrum allocations and latency tolerances of seconds to minutes for remote asset telemetry. Its primary commercial purpose is to extend IoT connectivity to geographically dispersed assets beyond cellular infrastructure, including maritime containers, agricultural sensors, and mining equipment in remote terrain. Cloud-based deployment models are capturing the fastest expansion as operators seek elastic scalability for sporadic satellite uplink patterns, while edge computing configurations are gaining traction in emergency response scenarios requiring local decision autonomy without ground station relay. Device management solutions remain the largest revenue pool given the complexity of provisioning heterogeneous satellite modems across Low Earth Orbit and geostationary networks.
FCC spectrum allocations in the United States shape market access by licensing specific satellite IoT frequency bands, while ESA coordination under EU Space Programme frameworks standardizes cross-border satellite service interoperability across member states. ISO 27001 and IEC 61508 certifications increasingly filter procurement decisions for safety-critical and data-sensitive deployments in mining and smart city infrastructure. Stakeholders must monitor evolving national spectrum auctions and orbital debris mitigation rules that will determine which software architectures secure regulatory clearance for next-generation satellite constellations.
Market Dynamics
The EU Green Deal is forcing maritime logistics operators to abandon terrestrial-only connectivity models and adopt emissions-monitoring software that functions beyond cellular range. This regulatory pressure is compressing procurement cycles for satellite-enabled telemetry platforms across international shipping corridors.
Growth Catalysts
- EU Green Deal:Mandates emissions transparency across European shipping lanes, compelling fleet operators to install satellite-connected monitoring systems for regulatory compliance.
- Brazilian offshore supply chains:ANVISA and maritime regulators now require remote monitoring for pharmaceutical and energy cargo moving through Brazilian waters.
- L-band spectrum resilience:Low Earth Orbit constellations operating in sub-1 GHz bands sustain connectivity through atmospheric interference that disrupts higher-frequency alternatives.
Market Restraints
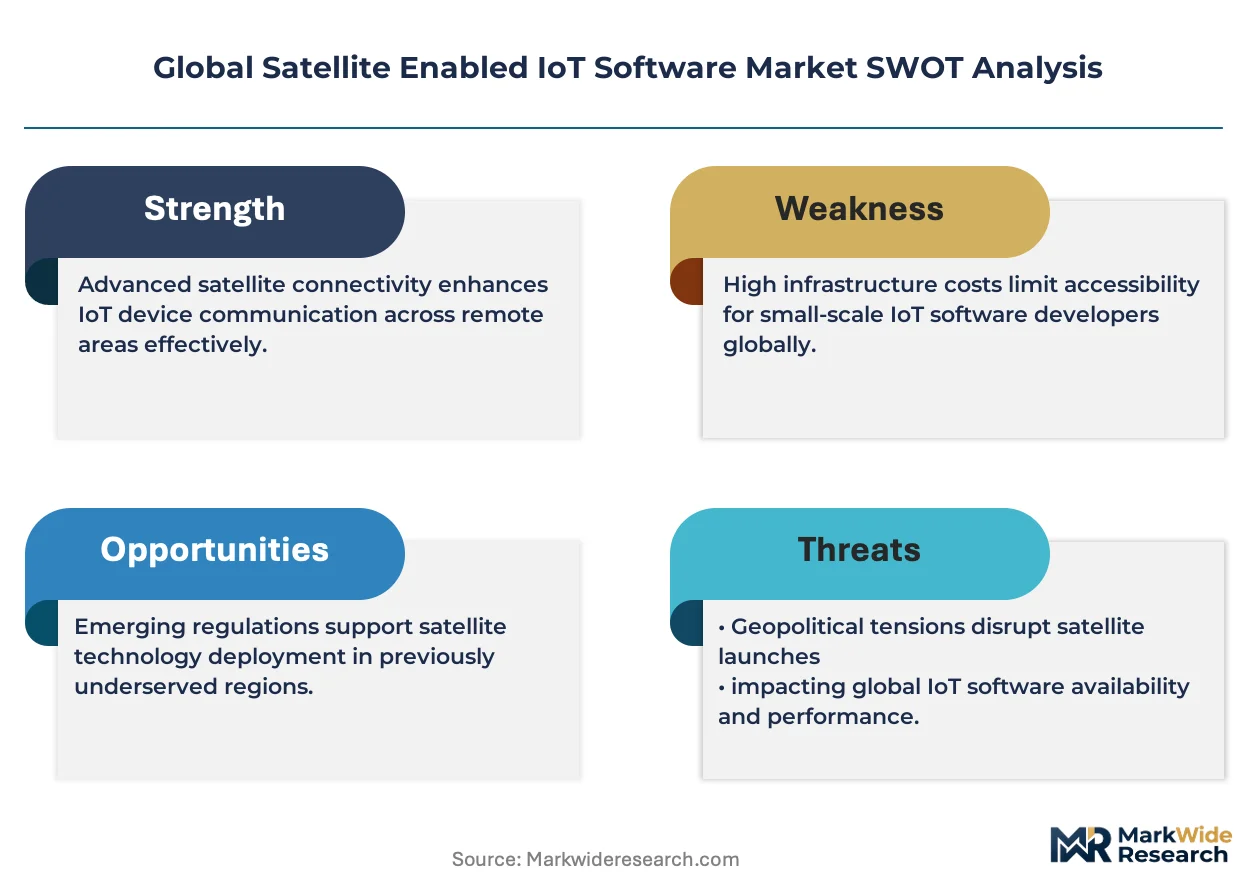
- Ground station infrastructure concentration:Polar and equatorial relay facilities remain concentrated in NATO-aligned territories, creating geopolitical access risk for certain operators.
- Latency-floor physics:Geostationary orbit positions impose minimum round-trip signal delays of 500-700 milliseconds, disqualifying real-time control applications.
- Orbital debris mitigation compliance:Emerging national rules on post-mission disposal and collision avoidance are extending certification timelines for new constellation deployments.
Strategic Opportunities
- Edge-to-cloud orchestration:Convergence of containerized edge computing with satellite backhaul enables local decision autonomy for mining equipment in terrain without fiber access.
- Indian agricultural telemetry:TRAI's satellite communication reforms are opening spectrum for remote sensor networks monitoring irrigation and soil conditions across Rajasthan and Maharashtra.
- Defense dual-use pivot:Encrypted payload software architectures developed for military applications are finding commercial traction in critical infrastructure protection contracts.
Industry Challenges
- RF engineering talent scarcity:Narrowband satellite modem optimization requires specialized expertise in link budget analysis and propagation modeling that outpaces university pipeline output.
- Heterogeneous network integration:Fleet operators struggle to unify device management across Low Earth Orbit, medium Earth orbit, and geostationary assets within single software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Satellite Enabled IoT Software Market |
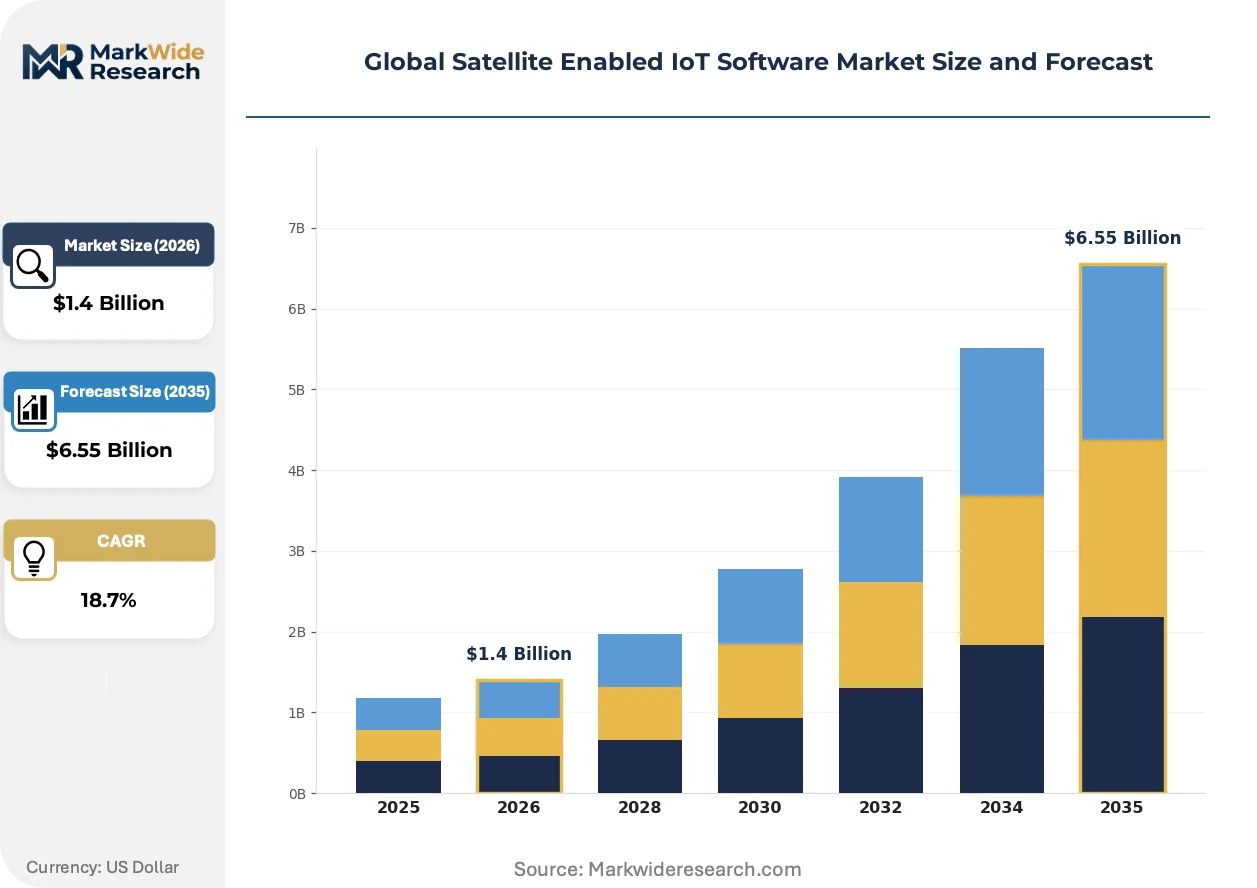
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Device Management, Data Analytics, Network Management, Security Management Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing Application Area: Asset Tracking, Environmental Monitoring, Fleet Management, Emergency Response End User Industry: Agriculture, Maritime, Mining, Smart Cities |
| Companies Covered | Orbcomm, Iridium Communications, Globalstar, Inmarsat Global, Eutelsat, Airbus, Thales, Intelsat, Astrocast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Satellite Enabled IoT Software Market Shifts & Advancements
Software-defined radio architectures are dissolving the hardware-locked boundaries between satellite network generations. Vendors now push firmware updates that retune modem parameters without physical replacement, compressing equipment refresh cycles from years to months.
Containerized edge computing is decentralizing analytics execution for maritime and mining applications. Vessel operators and extraction firms are deploying Kubernetes-orchestrated workloads directly on satellite terminals, processing telemetry locally before selective cloud uplink. This architecture reduces backhaul costs by filtering noise from sensor streams and enables autonomous emergency shutdowns during communication blackouts.
FCC Part 25 rule revisions are reshaping spectrum access economics for satellite IoT operators in the United States. The new licensing framework prioritizes non-geostationary systems with automated coordination mechanisms, accelerating deployment timelines for constellations serving agricultural and freight rail segments. Equipment manufacturers are redesigning modem firmware to exploit these streamlined authorization pathways.
Subscription-based device management is displacing perpetual license purchases among mid-sized fleet operators. Brazilian and Indian maritime buyers now favor per-asset monthly fees that bundle firmware maintenance, security patching, and constellation roaming rights. This shift compresses upfront capital requirements while locking vendors into sustained service delivery obligations.
Global Satellite Enabled IoT Software Market Segmentation
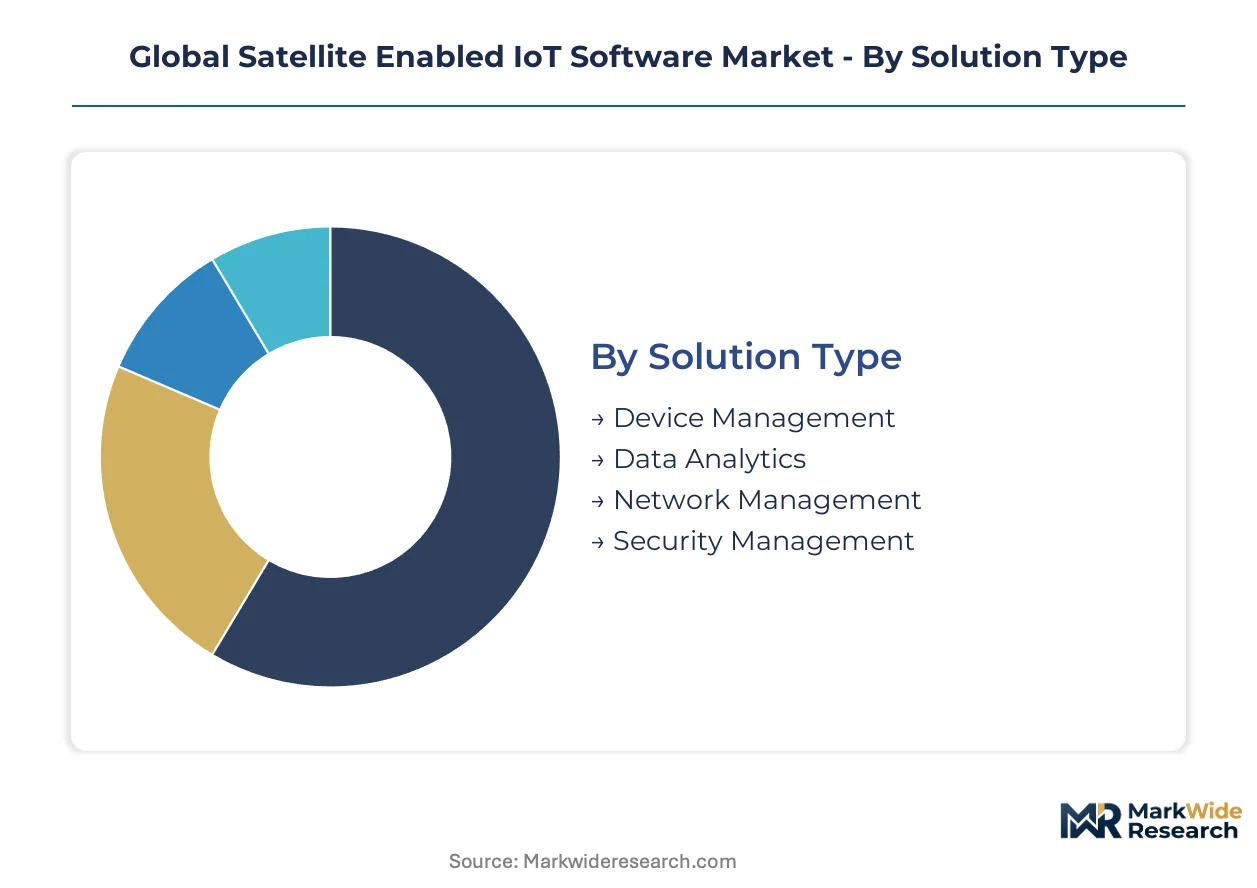
Segmentation in satellite enabled IoT software reveals how procurement concentrates around specific technical capabilities rather than generic platform features. Each dimension exposes distinct supply-side specializations that shape vendor selection criteria across maritime, agricultural, and extractive deployments.
Solution Type:
Supply concentration clusters around middleware layers that translate heterogeneous satellite signals into unified data streams, with device management commanding the deepest engineering investment from constellation operators.
- Device Management:Middleware platforms provision firmware across Low Earth Orbit and geostationary modems, handling over-the-air updates and roaming handoffs. Brazilian ANVISA-mandated offshore monitoring and EU Green Deal emissions compliance are concentrating procurement for heterogeneous fleet provisioning.
- Data Analytics:Telemetry processing engines filter noise from narrowband satellite uplinks before cloud ingestion. Indian agricultural deployments across Rajasthan and Maharashtra are driving demand for irrigation-pattern recognition algorithms that operate within sub-1 GHz bandwidth constraints.
- Network Management:Orchestration software coordinates handoffs between cellular and satellite backhaul in hybrid deployments.
- Security Management:Encrypted payload architectures protect dual-use military-civilian deployments in defense-adjacent critical infrastructure.
Device Management absorbs the bulk of installed capacity; Data Analytics is expanding most quickly.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises installations from operational expenditure models favored by mid-sized fleet operators seeking elastic scalability.
- Cloud-Based:Elastic infrastructure scales with sporadic satellite uplink patterns, eliminating stranded capacity during communication blackouts. Brazilian and Indian maritime buyers favor subscription pricing that bundles firmware maintenance with constellation roaming rights.
- Edge Computing:Containerized Kubernetes workloads process telemetry locally on satellite terminals, enabling autonomous emergency shutdowns without ground station relay. Mining operations in terrain without fiber access are driving containerized edge adoption.
- On-Premises:Dedicated infrastructure serves defense and dual-use deployments with air-gapped security requirements.
- Hybrid:Split architectures route critical alerts through edge processing while batching historical data to cloud analytics.
Cloud-Based deployments dominate new procurement cycles; Edge Computing is climbing the fastest as extraction firms seek autonomy in disconnected terrain.
Application Area:
Volume concentration tracks asset mobility patterns, with fixed infrastructure monitoring yielding to tracking applications for geographically dispersed equipment beyond cellular range.
- Asset Tracking:Location telemetry for containers, vehicles, and equipment operating across international shipping corridors and remote agricultural zones. EU Green Deal mandates are accelerating open-ocean vessel tracking installations that function beyond terrestrial connectivity.
- Fleet Management:Unified oversight of heterogeneous vehicle assets across cellular-satellite handoff zones. North American freight rail operators are consolidating procurement around hybrid connectivity platforms that bridge coverage gaps.
- Environmental Monitoring:Sensor networks tracking emissions, soil conditions, and atmospheric parameters in regulatory compliance deployments.
- Emergency Response:Rapidly deployable communication restoration for disaster zones with destroyed terrestrial infrastructure.
Asset Tracking carries the largest installed base; Fleet Management is gaining share fastest as logistics operators unify multi-modal oversight.
End User Industry:
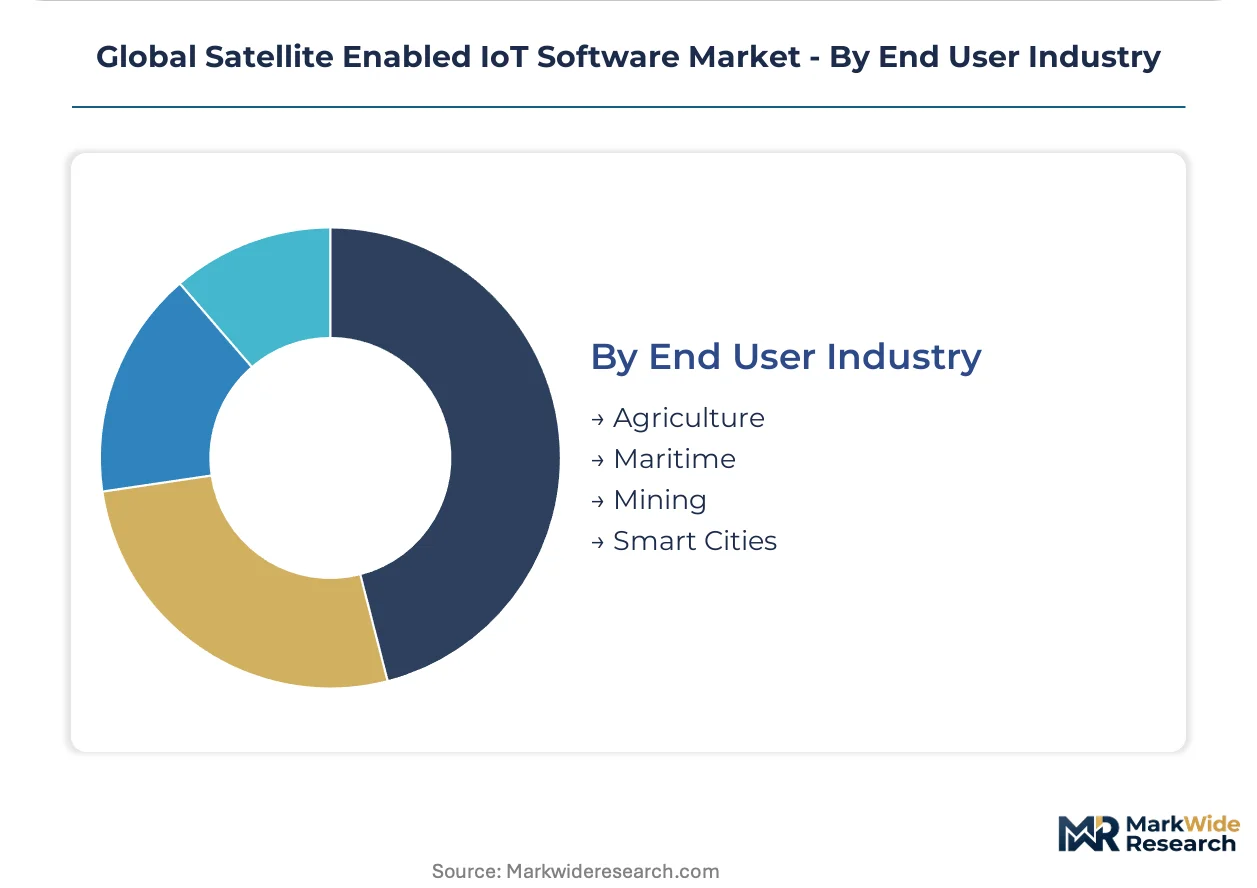
Customer type maturity varies sharply, with maritime procurement cycles compressed by regulatory mandates while agricultural adoption remains constrained by price sensitivity and technical literacy gaps.
- Maritime:Fleet operators deploy emissions-monitoring and vessel-tracking software across open-ocean routes. EU Green Deal transparency requirements and Brazilian ANVISA pharmaceutical cargo mandates are forcing rapid platform upgrades.
- Mining:Extraction firms process equipment telemetry through edge-computing satellite terminals in terrain without fiber backhaul. Containerized workloads enable autonomous shutdowns during communication blackouts.
- Agriculture:Remote sensor networks monitor irrigation and soil conditions across Indian states of Rajasthan and Maharashtra following TRAI satellite communication reforms.
- Smart Cities:Municipal infrastructure deployments concentrate in safety-critical applications requiring ISO 27001 and IEC 61508 certifications.
Maritime commands the deepest procurement commitments; Agriculture is expanding most quickly as spectrum reforms unlock rural sensor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors satellite IoT software procurement through its concentration of maritime logistics headquarters and energy sector technology buyers. The city's port operators and offshore service companies drive demand for vessel-tracking platforms that function beyond cellular range. Regulatory mandates across multiple jurisdictions are compressing deployment timelines.
United States
FCC Part 25 rule revisions prioritize non-geostationary systems with automated coordination mechanisms, accelerating constellation deployment timelines. Houston and Seattle maritime technology clusters are consolidating procurement around hybrid connectivity platforms. Freight rail operators across the Midwest are unifying device management across cellular-satellite handoff zones.
Brazil
ANVISA and maritime regulators mandate remote monitoring for pharmaceutical and energy cargo moving through Brazilian waters. The country's national pharmaceutical regulator enforces cold-chain traceability requirements for offshore supply chains. São Paulo-based fleet operators are adopting subscription-based device management to compress upfront capital requirements.
Germany
EU Green Deal transparency requirements force maritime logistics operators to install emissions-monitoring software across international shipping corridors. The country's federal maritime authority coordinates with ESA frameworks on cross-border satellite service interoperability. Hamburg port operators are upgrading open-ocean vessel tracking installations that function beyond terrestrial connectivity.
India
TRAI satellite communication reforms open spectrum for remote sensor networks monitoring irrigation and soil conditions. The country's telecommunications regulator streamlined authorization pathways for agricultural telemetry deployments. Rajasthan and Maharashtra farming cooperatives are piloting narrowband sensor networks within sub-1 GHz bandwidth constraints.
Japan
METI industrial policy supports edge-to-cloud orchestration for mining equipment in terrain without fiber access. The country's ministry of economy, trade and industry funds containerized workload development for autonomous emergency shutdowns. Kyushu-based extraction firms are deploying Kubernetes-orchestrated satellite terminals for local telemetry processing.
Global Satellite Enabled IoT Software Market Competitive Landscape
The competitive structure tilts toward constellation operators with integrated software stacks rather than pure-play middleware vendors. Tier-one players control end-to-end device-to-cloud pipelines, while specialists concentrate on encrypted payload architectures for defense-adjacent deployments. Two strategic archetypes dominate: spectrum-resilient L-band providers and hybrid cellular-satellite platform operators. Competitive moves center on firmware-defined radio updates that retune modem parameters without hardware replacement, plus subscription pricing models that bundle maintenance with constellation roaming rights.
Within the integrated constellation tier, Iridium Communications and Orbcomm exemplify divergent connectivity strategies. Iridium leverages its L-band infrastructure to sustain pole-to-pole coverage for ice-bound maritime routes. Orbcomm anchors its position through hybrid device management platforms that dominate North American freight rail. Thales occupies a specialist position via encrypted payload software serving defense and dual-use satellite IoT deployments.
| Leading Market Players |
|---|
| Orbcomm |
| Iridium Communications |
| Globalstar |
| Inmarsat Global |
| Eutelsat |
| Airbus |
| Thales |
| Intelsat |
| Astrocast |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up device management specialists have consolidated middleware provisioning capabilities across Brazilian and Indian maritime procurement, tightening pricing discipline through bundled subscription offerings that combine firmware maintenance with constellation roaming rights.
Pricing Analysis
Uptime-based pricing anchors satellite IoT software procurement, with Brazilian fleet operators paying premiums for guaranteed connectivity during ANVISA-mandated pharmaceutical cargo monitoring. Subscription SaaS-tiered models dominate mid-sized maritime buyers, compressing upfront capital requirements while locking vendors into sustained service delivery. Price differentiation separates ISO 27001-certified security management suites from standard device management tiers, with defense-adjacent deployments commanding substantial premiums. Cost compression in the standard tier intensifies as Orbcomm and Iridium Communications compete for North American freight rail accounts. Agricultural buyers across Rajasthan and Maharashtra exhibit the highest price sensitivity, favoring per-asset monthly fees over feature-rich enterprise packages.
Supply Chain Analysis
Maritime freight costs from semiconductor fabrication centers in Taiwan, South Korea, and the United States directly shape modem hardware landed costs for satellite terminal manufacturers. L-band radio frequency components, specialized antenna substrates, and radiation-hardened chipsets constitute critical input dependencies. Single-source vulnerability concentrates around polar ground station relay facilities in NATO-aligned territories, creating geopolitical access risk for certain constellation operators. Distribution runs through Houston and São Paulo maritime technology clusters, with subscription-based device management platforms increasingly displacing perpetual license channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spectrum licensing bottlenecks and orbital debris mitigation compliance timelines constrain new constellation deployment capacity, propping pricing power for incumbent software vendors with established regulatory clearances.
For Market Incumbents: To counter software-defined radio commoditization threats, Iridium Communications and Orbcomm should deepen backward integration into modem firmware development while accelerating certification investment for EU Green Deal emissions-monitoring compliance. Channel control over hybrid cellular-satellite provisioning platforms remains the critical defensive lever against emerging LEO constellation entrants. For New Entrants and Emerging Players: Capture white-space opportunity in Indian agricultural telemetry following TRAI spectrum reforms, where narrowband sensor networks across Rajasthan and Maharashtra remain underpenetrated by established maritime-focused vendors. Containerized edge computing for mining equipment in fiber-disconnected terrain offers a second penetrable segment. A direct-to-farming-cooperative go-to-market model bypasses incumbent channel structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor encrypted payload software specialists with defense-cleared architectures in Germany and Japan, where METI and ESA frameworks are accelerating dual-use commercialization. Long-term viability across the analysis window hinges on regulatory clearance moats rather than raw constellation scale. The signal to monitor is FCC Part 25 rule implementation pace, which will determine which software architectures secure streamlined authorization pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies device management across LEO, MEO, and geostationary assets for heterogeneous fleet provisioning. |
| Geographic Expansion | Targets Brazilian offshore supply chains under ANVISA pharmaceutical cargo monitoring mandates. |
| Strategic Partnership | Aligns encrypted payload architectures with ESA frameworks for EU Green Deal emissions compliance. |
| Acquisition of Specialist Firm | Consolidates Kubernetes-orchestrated edge computing capabilities for mining autonomy applications. |
| Product Launch | Deploys firmware-defined radio updates that retune modem parameters without hardware replacement. |
Research Methodology
Independent corroboration across constellation operator technical leads, maritime fleet procurement directors, and Brazilian ANVISA compliance officers underwrites the qualitative findings, validated against FCC spectrum allocation filings, ESA coordination frameworks, and TRAI satellite communication reform documentation. Bottom-up triangulation across device management platform deployments and top-down validation against subscription revenue disclosures anchor the market sizing.
Comparable-period anchoring to historical satellite IoT software adoption curves across maritime, mining, and agricultural verticals shaped the forecast window construction. The analytical framework models deployment model, solution type, application area, and end-user industry dimensions throughout the projection horizon. CAGRs derive from segmented growth trajectory analysis calibrated against constellation capacity expansion timelines and regulatory mandate implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to orbital debris mitigation rule evolution and national spectrum auction outcomes. Forecasts reflect documented assumptions about L-band constellation resilience and hybrid network integration complexity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
Iiot (Industrial Internet of Things) Technology Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
Middle East and Africa IoT Node and Gateway Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
Internet of Things (IoT) in Manufacturing Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
IoT Infrastructure Market
Internet of Things (IoT)
IoT Platform Market