
 ASEAN Geospatial Analytics Market | 2026-2036
ASEAN Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Geospatial Analytics Market Insights
Cloud-native geospatial processing is rewriting how analytics platforms deliver real-time insights across Southeast Asian infrastructure networks. Esri (Thailand) Co., Ltd. leverages localized server nodes to sustain low-latency mapping services for Bangkok municipal clients. Hexagon AB anchors its regional presence through sensor-to-software integration for precision agriculture across the Mekong Delta. MappointAsia (Thailand) PCL differentiates via proprietary terrain databases that dominate Thai cadastral surveying contracts.
Geospatial analytics encompasses the capture, storage, manipulation, analysis, and presentation of geographic data through coordinate-referenced information systems, typically processing raster and vector datasets with sub-meter accuracy for decision support. The technology stack serves urban planning, disaster management, environmental monitoring, and defense applications across ASEAN member states. Remote sensing and image processing command expanding budget allocations as defense ministries modernize satellite intelligence capabilities. Cloud-based deployment models attract fastest-growing adoption among private enterprises seeking scalable subscription access without capital-intensive infrastructure.
Indonesia's national mapping agency coordinates with BIS-aligned standards to enforce geospatial data sovereignty requirements that shape vendor qualification protocols. Thailand's Digital Economy and Society Ministry implements cybersecurity frameworks affecting cross-border data flows for foreign-hosted analytics platforms. Vietnam's Ministry of Natural Resources and Environment mandates coordinate system standardization that determines product interoperability across provincial implementations. Stakeholders must monitor evolving data localization mandates that will determine platform architecture decisions and partnership structures across the ten-member economic community.
Market Dynamics
Cloud-native deployment architectures are compressing the cost-to-insight ratio for geospatial analytics across Southeast Asian infrastructure agencies. This structural shift favors vendors with localized compute nodes over centralized hyperscaler models.
Growth Catalysts
- Smart city mandates:Bangkok and Jakarta municipal authorities embed geospatial dashboards into traffic management and flood response systems. These deployments create recurring subscription revenue streams for platform providers.
- Precision agriculture adoption:Plantation operators across Malaysia and Indonesia deploy drone-mounted multispectral sensors to optimize fertilizer application and yield forecasting. Sensor-to-software integration reduces input waste.
- BIS-aligned sovereignty standards:Indonesia's national mapping agency enforces data localization requirements that qualify domestic-hosted vendors for government contracts. Foreign platforms must establish local infrastructure partnerships.
Market Restraints
- Specialized talent scarcity:The region faces acute shortages of geospatial data scientists and remote sensing engineers. Training pipelines at Vietnamese and Thai technical universities lag industry demand curves.
- High-resolution satellite imagery costs:Commercial Earth observation data pricing remains prohibitive for provincial agriculture departments and smallholder cooperatives. Budget constraints limit adoption outside national agencies.
- Interoperability fragmentation:Vietnam's Ministry of Natural Resources and Environment mandates VN-2000 coordinate systems while neighboring states maintain WGS-84 or UTM variants. Cross-border projects require expensive reprojection workflows.
Strategic Opportunities
- Maritime boundary arbitration:Archipelagic claims in the South China Sea drive demand for bathymetric surveying and exclusive economic zone delineation. Defense and foreign ministry budgets allocate increasing resources.
- Carbon credit verification:REDD+ monitoring requirements create openings for satellite-based forest cover change detection. Indonesian and Malaysian conservation agencies seek automated alert systems.
- Edge computing convergence:Integration of on-device AI inference with low-earth orbit satellite constellations enables real-time disaster response without ground station latency. First-mover vendors capture emergency management contracts.
Industry Challenges
- Legacy cadastral system integration:Thai and Philippine land registries operate on decades-old paper-to-digital conversion projects. Modern analytics platforms must accommodate incomplete polygon geometries and disputed boundary records.
- Cross-border data flow compliance:Thailand's Digital Economy and Society Ministry implements cybersecurity frameworks that restrict foreign-hosted processing of sensitive infrastructure coordinates. Vendors architect hybrid cloud solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Geospatial Analytics Market |
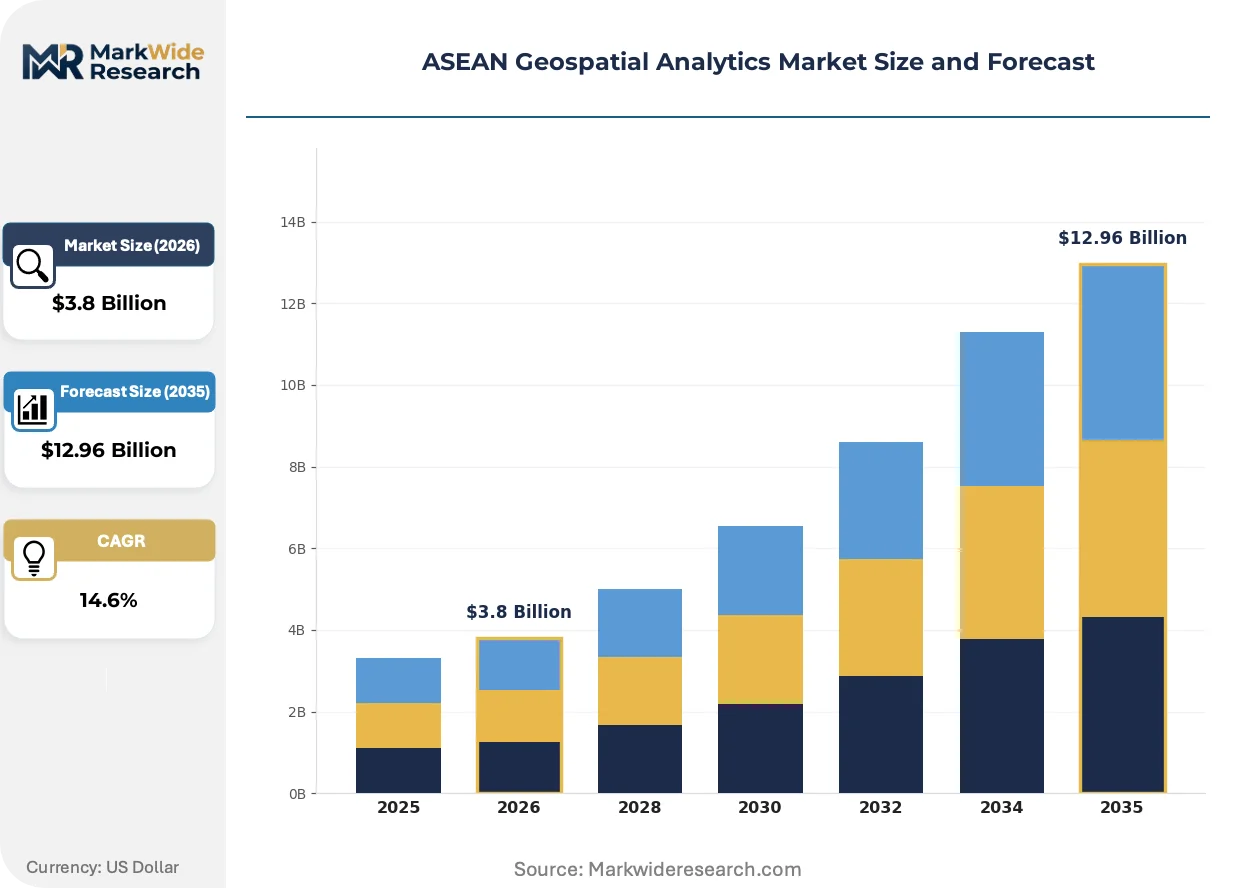
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GIS, Remote Sensing, Image Processing, Data Visualization Application: Urban Planning, Disaster Management, Environmental Monitoring, Defense End User: Government Agencies, Private Enterprises, NGOs, Research Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Hexagon AB, Esri (Thailand) Co., Ltd., MappointAsia (Thailand) PCL, PT Bhumi Varta Technology, Geospatial AI Sdn Bhd, GIS Co., Ltd., Spatialworks Sdn Bhd, Mandalay Technology Co., Ltd., Intermap Technologies, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Geospatial Analytics Market Trends and Innovations
Artificial intelligence inference is migrating toward edge-deployed sensor networks, reducing dependency on centralized cloud infrastructure for time-critical applications. This architectural pivot reshapes vendor competitive positioning across defense, disaster response, and precision agriculture segments.
Digital twin platforms for urban infrastructure is migrating from visualization tools into operational decision systems. Singapore's national research agency and Ho Chi Minh City planners deploy real-time sensor feeds into 3D city models. The technology is migrating from pilot demonstrations into procurement requirements for municipal master planning contracts.
Indonesia's geospatial data sovereignty regulations, aligned with BIS standards, now require government datasets to reside on domestically certified infrastructure. Foreign analytics providers establish local server nodes or forfeit eligibility for national mapping agency tenders. Provincial implementations in Sumatra and Kalimantan enforce these mandates most strictly, driving partnership structures with Indonesian data center operators.
Municipal procurement departments across ASEAN member states now specify subscription-based platform access rather than perpetual software licenses. Bangkok Metropolitan Administration and Jakarta Smart City office structure multi-year service agreements with usage-based pricing tiers. Vietnam's provincial natural resource departments follow this pattern, prioritizing vendors offering training and technical support bundled into annual contracts.
ASEAN Geospatial Analytics Market Segmentation
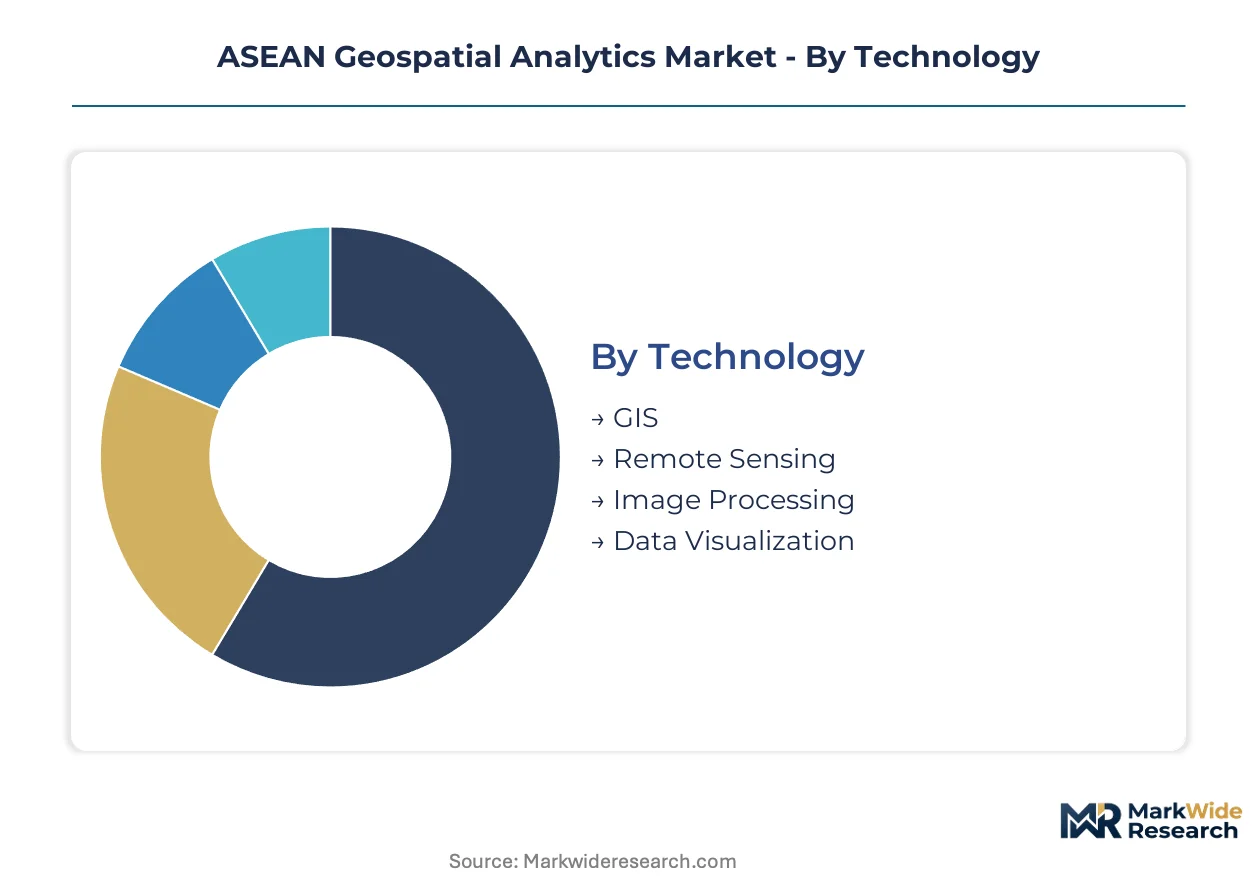
Segmentation of the ASEAN Geospatial Analytics Market reveals distinct technology stacks, deployment architectures, and end-user procurement patterns that determine vendor go-to-market strategies. Understanding these divisions enables targeted platform development and partnership prioritization across the ten-member economic community.
Technology:
After-sales service intensity varies sharply across technology segments, with GIS platforms demanding continuous technical support for coordinate system standardization while remote sensing solutions require sensor calibration maintenance and imagery processing assistance.
- GIS:Core spatial data infrastructure managing coordinate-referenced datasets with sub-meter accuracy for cadastral and infrastructure mapping. Demand concentrates among Indonesian provincial governments and Thai municipal authorities modernizing land registries under BIS-aligned sovereignty mandates.
- Remote Sensing:Satellite and aerial data acquisition systems capturing multispectral imagery for environmental and agricultural monitoring. Indonesian plantation operators and Malaysian palm oil conglomerates drive procurement for yield optimization and deforestation compliance verification.
- Image Processing:Computational pipelines for orthorectification, feature extraction, and change detection from raster datasets. Vietnamese natural resource departments utilize these tools for Mekong Delta land cover classification.
- Data Visualization:Dashboard and 3D rendering engines translating geospatial outputs into decision-support interfaces. Bangkok and Jakarta smart city offices embed these into traffic management and flood response command centers.
By volume, GIS leads. By growth pace, Remote Sensing is ahead.
Application:
Application segments diverge by procurement authority and budget cycle predictability, with defense and environmental monitoring commanding multi-year allocations while urban planning follows electoral and infrastructure investment timelines.
- Urban Planning:Zoning analysis, transportation network optimization, and 3D city modeling for master plan development. Ho Chi Minh City and Singapore national research agencies deploy real-time sensor feeds into operational digital twin platforms.
- Disaster Management:Flood prediction, seismic risk assessment, and emergency response coordination systems. Indonesia's archipelagic geography drives maritime boundary mapping integration with AI-enhanced early warning capabilities.
- Environmental Monitoring:Forest cover tracking, carbon credit verification, and pollution dispersion modeling. Malaysian and Indonesian conservation agencies seek automated REDD+ alert systems for deforestation detection.
- Defense:Satellite intelligence, exclusive economic zone delineation, and bathymetric surveying for maritime claims. South China Sea territorial arbitration requirements expand defense ministry budget allocations across coastal ASEAN states.
Urban Planning captures the largest contract value. Defense exhibits the steepest expansion trajectory.
End User:
End user categories separate by data sovereignty sensitivity and integration complexity, with government agencies imposing strict localization requirements while private enterprises prioritize scalable subscription access.
- Government Agencies:National mapping authorities, provincial natural resource departments, and municipal planning offices. Indonesia's geospatial data sovereignty regulations restrict foreign-hosted platforms from national agency tenders without domestic server node establishment.
- Private Enterprises:Plantation operators, logistics providers, and infrastructure developers seeking competitive intelligence. Cloud-based deployment models attract fastest-growing adoption among this cohort for capital expenditure avoidance.
- NGOs:Conservation organizations and humanitarian agencies conducting independent environmental monitoring. Budget constraints limit high-resolution commercial imagery procurement.
- Research Institutions:Universities and national laboratories advancing algorithm development and sensor calibration. Vietnamese and Thai technical universities supply limited talent pipelines relative to industry demand curves.
Government Agencies dominate procurement volume. Private Enterprises are gaining share fastest.
Deployment:
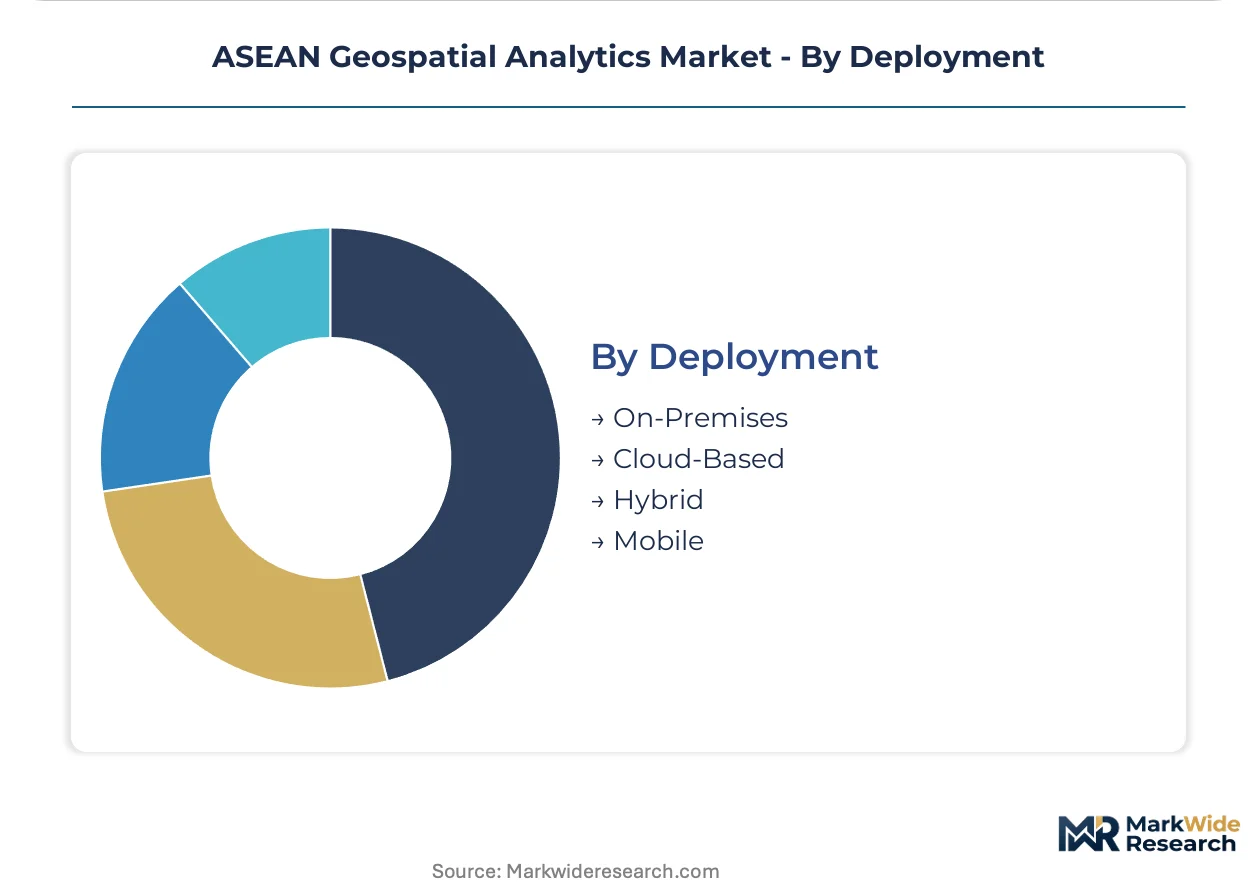
Deployment architecture selection hinges on latency requirements, data classification levels, and cross-border flow restrictions imposed by national cybersecurity frameworks.
- On-Premises:Locally installed infrastructure for classified defense coordinates and sensitive cadastral records. Thai and Philippine land registries maintain legacy systems with incomplete polygon geometries requiring specialized integration support.
- Cloud-Based:Centralized or distributed server architectures enabling subscription access and elastic compute scaling. Bangkok Metropolitan Administration structures multi-year service agreements with usage-based pricing tiers.
- Hybrid:Mixed architectures segregating sensitive processing on local nodes while leveraging cloud elasticity for non-classified analytics. Foreign vendors architect these solutions to comply with Thailand's Digital Economy and Society Ministry cross-border data flow restrictions.
- Mobile:Field-deployed applications for surveyors, emergency responders, and agricultural extension workers. Edge computing convergence with low-earth orbit satellite constellations enables real-time inference without ground station latency.
Cloud-Based deployment leads by active contract count. Hybrid architectures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore exports geospatial analytics services to Indonesian plantation operators and Vietnamese infrastructure developers. This trade corridor channels precision agriculture expertise and smart city platforms into markets with weaker domestic vendor ecosystems.
Indonesia
Archipelagic geography drives maritime boundary mapping and palm oil plantation monitoring applications. The national mapping agency enforces BIS-aligned data sovereignty standards that require domestic server hosting for government tenders. Provincial implementations in Sumatra and Kalimantan apply these mandates most strictly, forcing foreign platforms to partner with Indonesian data center operators.
Thailand
Bangkok municipal authorities embed geospatial dashboards into traffic management and flood response command centers. The Digital Economy and Society Ministry implements cybersecurity frameworks restricting cross-border data flows for sensitive infrastructure coordinates. Esri (Thailand) Co., Ltd. leverages localized server nodes to sustain low-latency mapping services for metropolitan clients.
Vietnam
Mekong Delta agricultural operators deploy drone-mounted multispectral sensors for yield optimization and fertilizer management. The Ministry of Natural Resources and Environment mandates VN-2000 coordinate system standardization that determines product interoperability across provincial implementations. Ho Chi Minh City planners integrate real-time sensor feeds into operational digital twin platforms for urban master planning.
Malaysia
Palm oil conglomerates and conservation agencies drive procurement for deforestation compliance verification and REDD+ carbon credit monitoring. Federal environmental regulations require automated forest cover change detection systems for concession licensing. Spatialworks Sdn Bhd and Geospatial AI Sdn Bhd anchor domestic service provision for plantation sector clients.
Philippines
Land registries operate decades-old paper-to-digital conversion projects with incomplete polygon geometries and disputed boundary records. The national mapping authority coordinates cadastral modernization with limited budget allocations relative to archipelagic coverage requirements. Metro Manila flood prediction systems integrate satellite imagery with artificial intelligence for disaster response coordination.
ASEAN Geospatial Analytics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment architecture and data sovereignty compliance vectors. The vendor base clusters around three strategic archetypes: multinational platform providers with localized infrastructure, domestic system integrators with regulatory relationships, and sensor-to-software specialists with precision agriculture expertise. Competitive dynamics center on M&A activity targeting regional data center assets and strategic partnerships with national mapping agencies to satisfy localization mandates.
Within the multinational platform tier, Hexagon AB exemplifies sensor-to-software integration strategies, while Esri (Thailand) Co., Ltd. occupies a position emphasizing localized service delivery. Domestic specialists PT Bhumi Varta Technology and MappointAsia (Thailand) PCL represent the regulatory-compliance archetype through proprietary terrain databases and cadastral surveying contracts. These named entities illustrate how competitive positioning fragments across technology origin and government relationship intensity.
| Leading Market Players |
|---|
| Hexagon AB |
| Esri (Thailand) Co., Ltd. |
| MappointAsia (Thailand) PCL |
| PT Bhumi Varta Technology |
| Geospatial AI Sdn Bhd |
| GIS Co., Ltd. |
| Spatialworks Sdn Bhd |
| Mandalay Technology Co., Ltd. |
| Intermap Technologies |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Indonesian domestic data center infrastructure drives foreign vendors toward partnership structures with local operators, compressing margins while elevating pricing power for certified domestic hosts serving government procurement.
Pricing Analysis
Legacy GIS software licensing commands premium positioning against cloud-native subscription tiers and emerging edge-computing service bundles. Three-tier pricing structure across enterprise, municipal, and smallholder agriculture levels segments buyers by data sovereignty requirements and integration complexity. Cost compression in municipal SaaS tiers intensifies because Bangkok and Jakarta procurement offices negotiate multi-year volume commitments. Provincial agriculture departments exhibit highest price sensitivity due to budget fragmentation across district-level implementations, while defense ministries show lowest sensitivity given classified processing mandates.
Supply Chain Analysis
Tariff exposure between United States satellite operators and ASEAN ground station networks dominates supply chain risk assessment for Earth observation data flows. Hardware concentration rests on Taiwan for edge-computing chipsets, South Korea for precision sensor components, and Japan for optical calibration systems. Raw material dependencies include rare earth elements for magnetometer arrays, high-purity silicon for photodetector fabrication, and specialized alloys for drone airframes. Single-source vulnerability concentrates in low-earth orbit satellite constellation access, where foreign-owned networks control revisit frequency pricing. Distribution runs through domestic system integrators holding regulatory relationships with national mapping agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical infrastructure investment lows, with smart city procurement cycles in Indonesia and Thailand providing the demand inflection.
For Market Incumbents: Entrench data sovereignty compliance through Indonesian data center partnerships and BIS-aligned certification investments. Vertical integration into sensor manufacturing reduces dependency on Taiwan chipset suppliers facing tariff exposure. Threat substitution emerges from Chinese platform providers offering subsidized cloud analytics to Mekong Delta agricultural cooperatives. For New Entrants and Emerging Players: Pursue carbon credit verification services for Malaysian palm oil conglomerates seeking REDD+ compliance automation, the most penetrable segment given legacy vendor gaps in automated alert systems. Philippine land registry modernization presents secondary white-space opportunity given decades of underinvestment in cadastral digitization. Go-to-market angle should emphasize edge-computing convergence with low-earth orbit constellations for real-time disaster response differentiation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform providers serving municipal subscription contracts with embedded technical support. Long-term viability over the medium-term planning horizon favors vendors with established regulatory relationships across multiple ASEAN member states. Acquisition target archetype: domestic system integrators holding exclusive terrain database rights in Thailand or Indonesia. Signal to watch as inflection indicator: defense ministry budget allocations for South China Sea bathymetric surveying capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Partnership | Indonesian BIS-aligned certification unlocks national mapping agency tender eligibility. |
| Edge-AI Sensor Integration | On-device inference with low-earth orbit constellations captures emergency management contracts. |
| REDD+ Monitoring Platform Launch | Malaysian federal concession licensing mandates drive automated forest cover detection procurement. |
| Cadastral Modernization Service | Thai and Philippine land registry digitization projects require specialized legacy system integration. |
| Maritime Boundary Analytics Suite | South China Sea territorial arbitration expands defense ministry exclusive economic zone delineation budgets. |
Research Methodology
The analysis maps cloud-native deployment architectures, sensor-to-software integration stacks, and sovereignty-compliant hosting configurations, each validated through municipal procurement officers, national mapping agency technical directors, plantation operations managers, and defense ministry intelligence coordinators. Primary interviews with these stakeholders combined with secondary validation from satellite operator service agreements, ASEAN member state cybersecurity framework filings, and BIS certification registries. Bottom-up contract aggregation and top-down macroeconomic scaling provided triangulation across the ASEAN ten-member economic community.
Assumptions held fixed include current data localization mandate enforcement intensity and existing satellite constellation access pricing structures, while variables included smart city procurement acceleration rates and edge-computing hardware cost curves. Segmentation dimensions modeled encompass deployment architecture, technology stack, application vertical, and end-user procurement authority across the projection horizon. CAGRs derived from regression analysis against infrastructure investment cycles and technology substitution elasticities. Industry-specific forecast inputs included Indonesian palm oil plantation sensor penetration rates and Thai municipal dashboard subscription renewal patterns.
Sensitivities concentrate around regulatory enforcement escalation in Vietnamese coordinate system mandates and Philippine cadastral budget allocations. Forecasts reflect documented assumptions regarding cross-border data flow restrictions and satellite imagery pricing trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe Retail Analytics Market
Analytics
Global Digital Intelligence Platform Market
Analytics
North America Mobile Analytics Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Drone Analytics Software Market
Analytics
Data Analytics in Telecom Market
Analytics
Location Analytics Market
Analytics
Global Big Data Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Analytics As a Service (Aaas) Market
Analytics
Learning Analytics Solution Market
Analytics
Middle East Geospatial Analytics Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Cyprus ICT Market
Analytics
Assortment Analytics Market