
 Global Data Management Platform Market | 2026-2036
Global Data Management Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Management Platform Market Foresight
Enterprise demand is rotating from traditional on-premises buyers toward cloud-native adopters in financial services and e-commerce. Salesforce leverages extensive CRM integration to anchor its platform position across customer analytics use cases. Oracle competes through deep database heritage and in-house hardware-software stack control. SAS Institute specializes in advanced analytics modules that differentiate its offering for risk management segments.
A data management platform is an integrated software environment that ingests, unifies, governs, and activates structured and unstructured data across enterprise systems, typically processing petabyte-scale volumes through distributed computing architectures. Its primary commercial purpose is to create unified customer profiles and operational data layers that feed real-time decision engines. Cloud deployment configurations now lead solution type adoption as enterprises seek elastic compute for data integration workloads, while data governance and security modules capture concentrated margin pools due to regulatory complexity. Master data management remains mature in manufacturing verticals, whereas marketing automation use cases in e-commerce show the fastest expansion trajectory.
The EU AI Act and GDPR frameworks in Europe, alongside HIPAA in the United States and China's PIPL standards, are mandating audit trails, consent management, and cross-border data localization that directly shape platform procurement specifications. The US SEC climate disclosure rules and CSRD reporting obligations in Europe are further tightening data provenance requirements across BFSI and manufacturing verticals. Stakeholders must monitor how divergent national data sovereignty laws reshape architectural choices for hybrid and edge deployment strategies.
Market Dynamics
Cloud-native architecture migration is compressing procurement cycles as BFSI institutions abandon on-premises data warehouses for elastic, API-first platforms that embed governance-by-design.
Growth Catalysts
- EU AI Act compliance mandates:European financial institutions are accelerating platform replacement timelines to satisfy audit trail and consent management requirements before enforcement deadlines.
- Real-time customer activation:E-commerce operators in India and Germany are demanding sub-100-millisecond profile resolution to power personalization engines at checkout.
- Edge computing proliferation:Manufacturing facilities in the United States are deploying distributed data layers to reduce latency for predictive maintenance workloads.
Market Restraints
- Specialized talent scarcity:Data governance architects and privacy engineers command premium compensation that inflates total cost of ownership for mid-market deployments.
- Cross-border data localization:China's PIPL and India's draft data protection rules fragment cloud architectures, forcing redundant infrastructure investments.
- Legacy system entrenchment:Core banking platforms at major institutions resist API-based integration, extending implementation timelines.
Strategic Opportunities
- Sovereign cloud infrastructure:Germany's Gaia-X initiative and India's MeghRaj program create procurement preference for domestically hosted platforms.
- Healthcare data monetization:HIPAA-compliant de-identification pipelines enable secondary use of clinical records for pharmaceutical research partnerships.
- Federated learning convergence:Privacy-preserving machine learning architectures allow competing banks to train models without centralizing sensitive customer records.
Industry Challenges
- Schema standardization delays:Industry consortia have failed to agree on universal customer data models, forcing expensive custom mapping for each enterprise deployment.
- Multi-cloud orchestration complexity:Platform engineering teams struggle to maintain consistent governance policies across AWS, Azure, and GCP environments simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Management Platform Market |
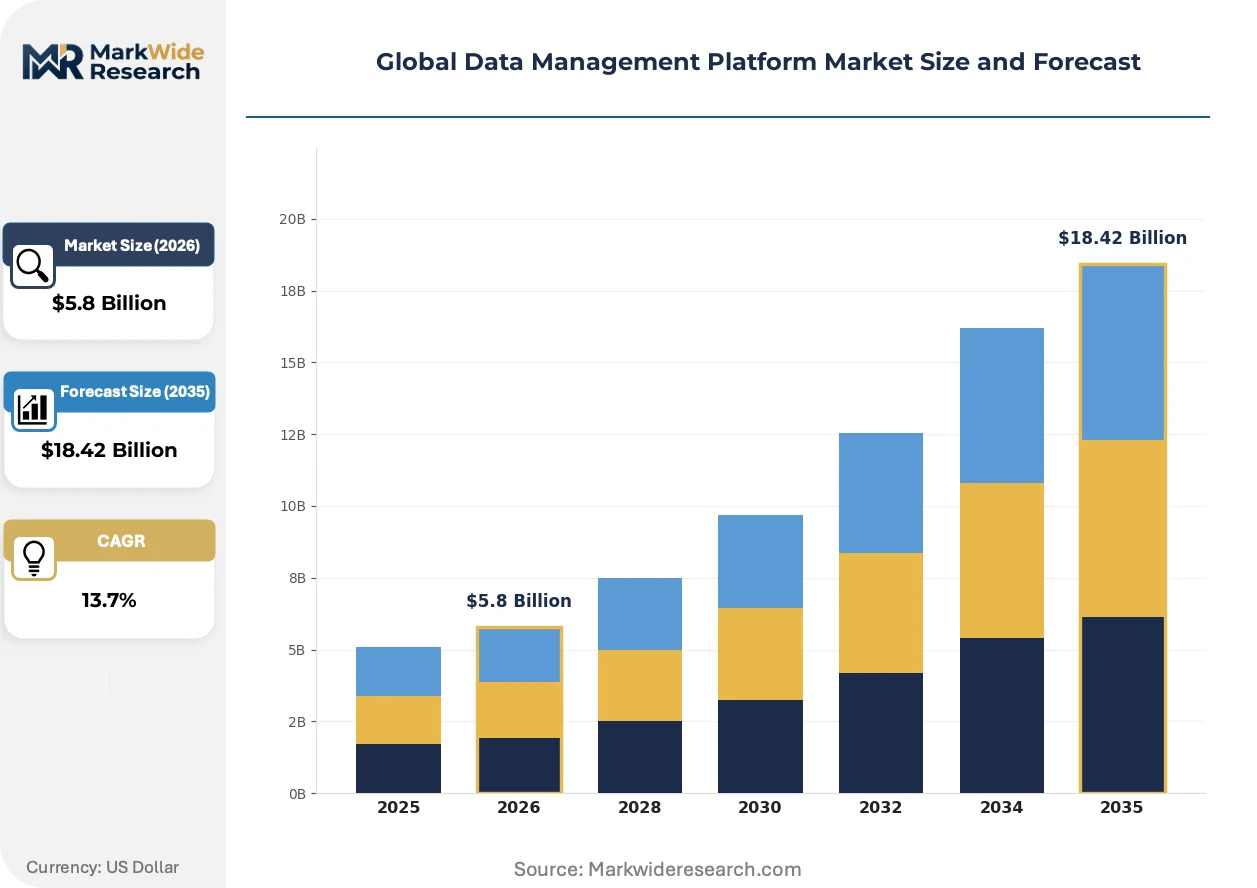
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $18.42 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Edge, Dedicated Hosting Solution Type: Data Integration, Data Governance, Master Data Management, Data Quality, Metadata Management, Data Security Use Case: Customer Analytics, Risk Management, Compliance Management, Marketing Automation, Supply Chain Optimization, Fraud Detection Industry Vertical: BFSI, Telecommunications, E-Commerce, Manufacturing, Government, Education |
| Companies Covered | Adobe, Salesforce, Oracle, SAP, IBM, Microsoft, SAS Institute, Lotame Solutions, The Trade Desk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Management Platform Market Shifts & Advancements
Data management architectures are fragmenting from monolithic suites toward composable, API-first components that enterprises assemble based on workload-specific requirements.
Embedded data observability tooling is miniaturizing quality monitoring into ingestion pipelines. Retail and logistics operators in Germany are deploying these micro-modules to catch schema drift before it corrupts downstream analytics. This compression of quality assurance into real-time streams is displacing batch-based reconciliation jobs that previously dominated enterprise workflows.
CSRD reporting obligations in Europe are mandating granular emissions traceability across supplier networks. Manufacturing conglomerates must now maintain immutable provenance records for Scope 3 calculations, forcing platform vendors to embed carbon accounting modules. German automotive suppliers and French luxury goods houses represent the most advanced adopters, with procurement specifications now requiring ISO 14064-aligned data structures.
Buyer committees are consolidating vendor relationships from point solutions to unified platforms. Procurement functions at United States-based insurers and Indian fintechs now mandate that new data tools integrate with existing customer profile stores rather than operate as standalone systems. This preference compression favors incumbents with established identity resolution capabilities while squeezing specialized challengers.
Global Data Management Platform Market Segmentation
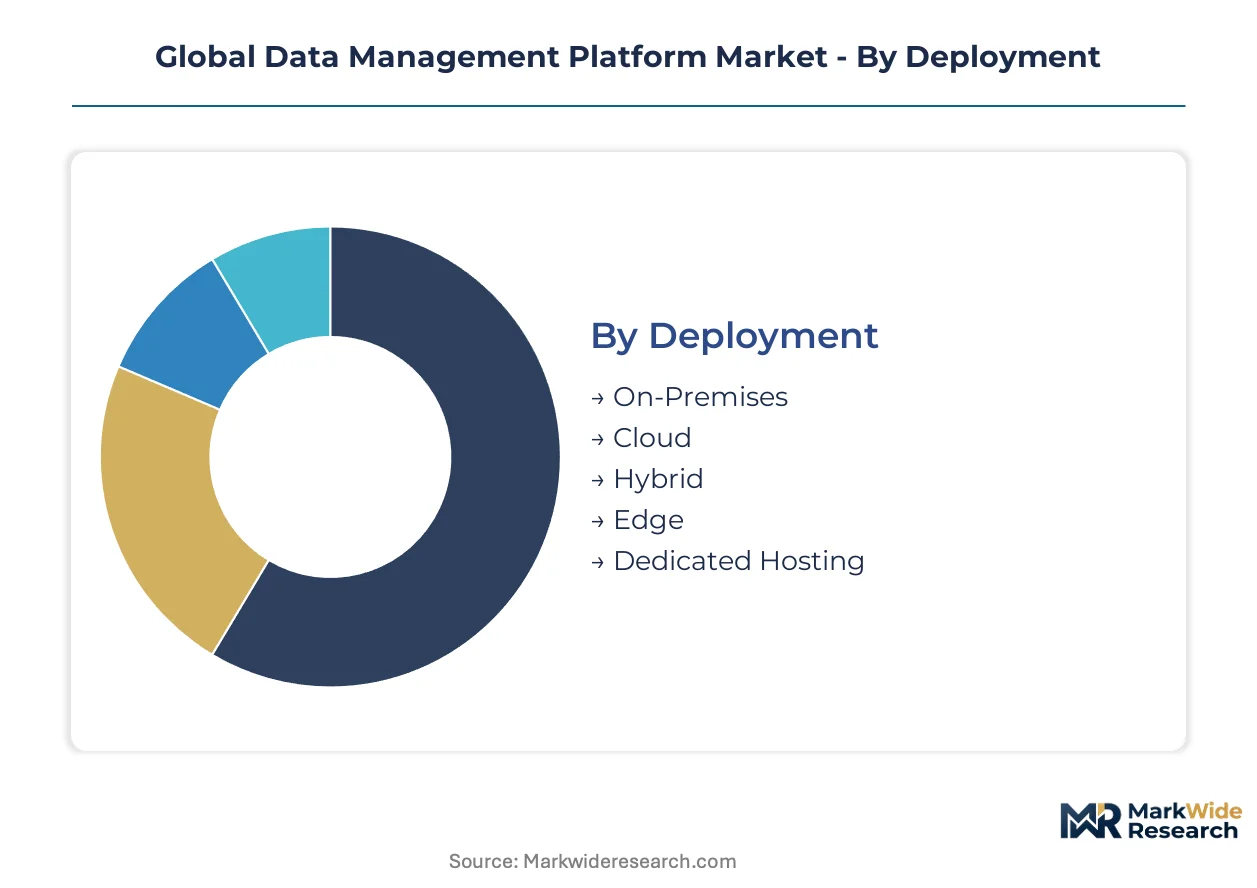
Platform procurement patterns diverge sharply across deployment models and solution types, with compliance mandates and latency requirements reshaping how enterprises allocate data infrastructure budgets. Understanding these segment boundaries reveals where vendors capture margin premiums versus where commoditization pressures dominate.
Deployment:
Margin pools concentrate in configurations that resolve sovereignty-latency tradeoffs for regulated workloads.
- Cloud:Elastic compute architectures process petabyte-scale integration workloads through API-first consumption models. Financial institutions in Germany and India are standardizing on sovereign cloud instances to satisfy data localization mandates while retaining scalability.
- Edge:Distributed data layers deploy inference-optimized nodes at manufacturing facilities and retail locations to achieve sub-100-millisecond response times. United States automotive suppliers leverage these deployments for predictive maintenance pipelines that cannot tolerate round-trip latency to centralized facilities.
- On-Premises:Legacy data warehouse estates persist in core banking systems where decades of schema entrenchment resist migration timelines.
- Hybrid:Split architectures synchronize sensitive customer records across private infrastructure and burst capacity to public cloud for batch analytics.
- Dedicated Hosting:Single-tenant bare-metal configurations serve defense contractors and classified government workloads with physical isolation requirements.
On-Premises holds installed capacity. Edge is rotating up the share rankings.
Solution Type:
Commercial differentiation tracks regulatory complexity rather than raw processing volume.
- Data Governance:Audit trail automation, consent orchestration, and lineage tracking modules embed compliance-by-design for GDPR and EU AI Act adherence. European financial institutions prioritize these capabilities above pure performance metrics.
- Data Security:Encryption-at-rest, tokenization, and zero-trust access controls protect cross-border data flows fragmented by China's PIPL and India's draft protection rules. BFSI procurement specifications now mandate security modules as non-negotiable table stakes.
- Data Integration:ETL and ELT pipelines unify structured and unstructured sources across ERP, CRM, and operational technology systems.
- Master Data Management:Golden record creation for customer, product, and supplier domains dominates manufacturing verticals with complex supplier networks.
- Data Quality:Profiling, cleansing, and matching algorithms prevent schema drift from corrupting downstream analytics.
- Metadata Management:Business glossary and data catalog functions enable self-service discovery for analytics teams.
Data Integration holds installed capacity. Data Governance is climbing the fastest.
Use Case:
Application-specific pricing power correlates with real-time decision velocity requirements.
- Customer Analytics:Unified profile resolution engines ingest behavioral signals across web, mobile, and physical touchpoints to power personalization. E-commerce operators in India demand sub-100-millisecond identity matching at checkout to prevent cart abandonment.
- Marketing Automation:Campaign orchestration and audience segmentation tools activate profiles across paid media and owned channels. German retail conglomerates are expanding fastest here as CSRD disclosure rules force granular customer journey documentation.
- Risk Management:Credit scoring and portfolio stress-testing models consume alternative data streams for BFSI model risk management.
- Compliance Management:Regulatory reporting pipelines automate SEC climate disclosures and CSRD Scope 3 calculations.
- Supply Chain Optimization:Demand sensing and inventory positioning algorithms reduce working capital for manufacturing networks.
- Fraud Detection:Real-time transaction scoring identifies anomalous patterns in payment flows.
Customer Analytics holds installed capacity. Marketing Automation is gaining share fastest.
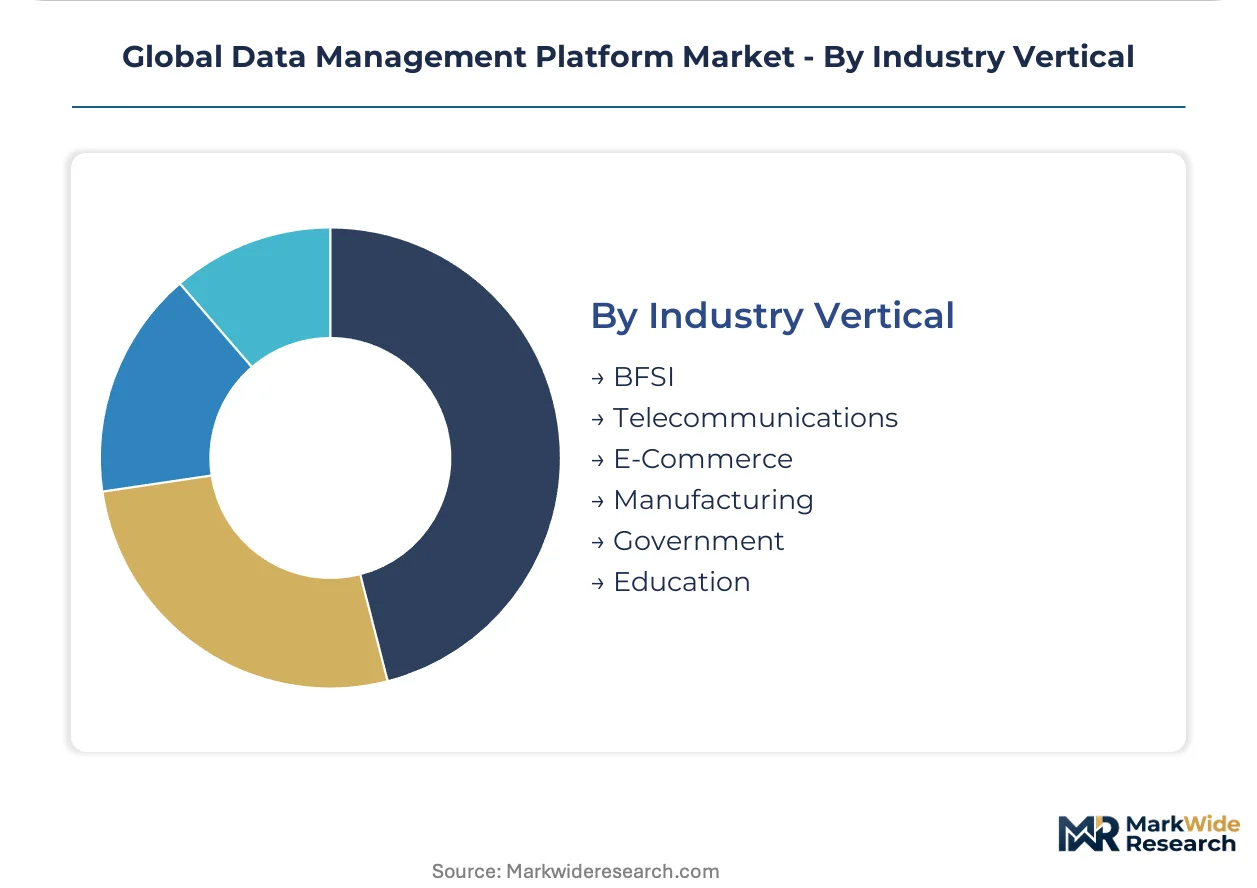
Industry Vertical:
Vertical specialization determines implementation complexity and services attach rates.
- BFSI:Core banking transformation, anti-money laundering, and open banking compliance drive the most sophisticated governance requirements. Institutions in the United States and Germany are compressing procurement cycles to meet enforcement deadlines.
- E-Commerce:Real-time personalization and inventory visibility across marketplaces demand elastic architectures that scale with promotional events. Indian platforms show the steepest expansion trajectory as digital payment penetration deepens.
- Telecommunications:Subscriber data management and network optimization workloads process call detail records at massive scale.
- Manufacturing:Product lifecycle management and supplier collaboration platforms maintain provenance records for emissions traceability.
- Government:Citizen identity systems and inter-agency data sharing require sovereign hosting certifications.
- Education:Student information systems and learning analytics platforms manage privacy-sensitive academic records.
BFSI holds installed capacity. E-Commerce is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports sovereign cloud architectures to financial institutions across the European Union, while India supplies data integration talent to North American and Middle Eastern enterprises expanding their analytics capabilities.
United States
BFSI institutions and automotive suppliers drive concentrated procurement for edge computing and predictive maintenance workloads. SEC climate disclosure rules and HIPAA mandates tighten data provenance requirements for insurers and healthcare networks. Manufacturing clusters in Michigan and Ohio deploy distributed data layers for real-time equipment monitoring.
Germany
Automotive suppliers and luxury goods houses demand granular emissions traceability for CSRD Scope 3 calculations. The Gaia-X initiative creates procurement preference for domestically hosted platforms with sovereign infrastructure certifications. Industrial data management adoption concentrates in Baden-Württemberg and Bavaria, where supplier networks require immutable provenance records.
India
E-commerce operators and fintech platforms scale elastic architectures for sub-100-millisecond personalization at checkout. The MeghRaj program and draft data protection rules steer procurement toward domestically hosted cloud infrastructure. Bengaluru and Mumbai clusters show the steepest expansion trajectory as digital payment penetration deepens across consumer markets.
China
Manufacturing conglomerates and platform operators navigate PIPL-mandated data localization requirements that fragment cloud architectures. Dual carbon goals and cross-border flow restrictions force redundant infrastructure investments for multinational enterprises. Yangtze River Delta industrial zones maintain the highest concentration of edge-deployed quality monitoring systems.
United Kingdom
Insurance underwriters and open banking providers compress procurement cycles to satisfy FCA operational resilience deadlines. GDPR alignment post-Brexit maintains stringent consent management requirements for customer analytics platforms. London financial services clusters drive demand for real-time risk scoring and alternative data integration capabilities.
Global Data Management Platform Market Competitive Landscape
Listed leaders compete with private specialists across governance-embedded and cloud-native solution categories. The vendor base organizes into three tiers: enterprise suites with database heritage, CRM-anchored customer data platforms, and analytics specialists with risk management modules. Consolidation pressure intensifies as buyer committees mandate integration with existing identity resolution infrastructure rather than standalone deployment. Dominant competitive moves include portfolio diversification into adjacent governance modules and strategic partnerships with sovereign cloud providers.
Within the enterprise suite tier, Salesforce and Oracle occupy positions that leverage extensive CRM integration and deep database heritage respectively. SAS Institute exemplifies the analytics specialist archetype with differentiated offerings for risk management segments. Adobe and SAP sit within the marketing automation and ERP-anchored data layer categories, reflecting the market's fragmentation across customer activation and operational system integration use cases.
| Leading Market Players |
|---|
| Adobe |
| Salesforce |
| Oracle |
| SAP |
| IBM |
| Microsoft |
| SAS Institute |
| Lotame Solutions |
| The Trade Desk |
| Others |
Supply & Pricing Matrix
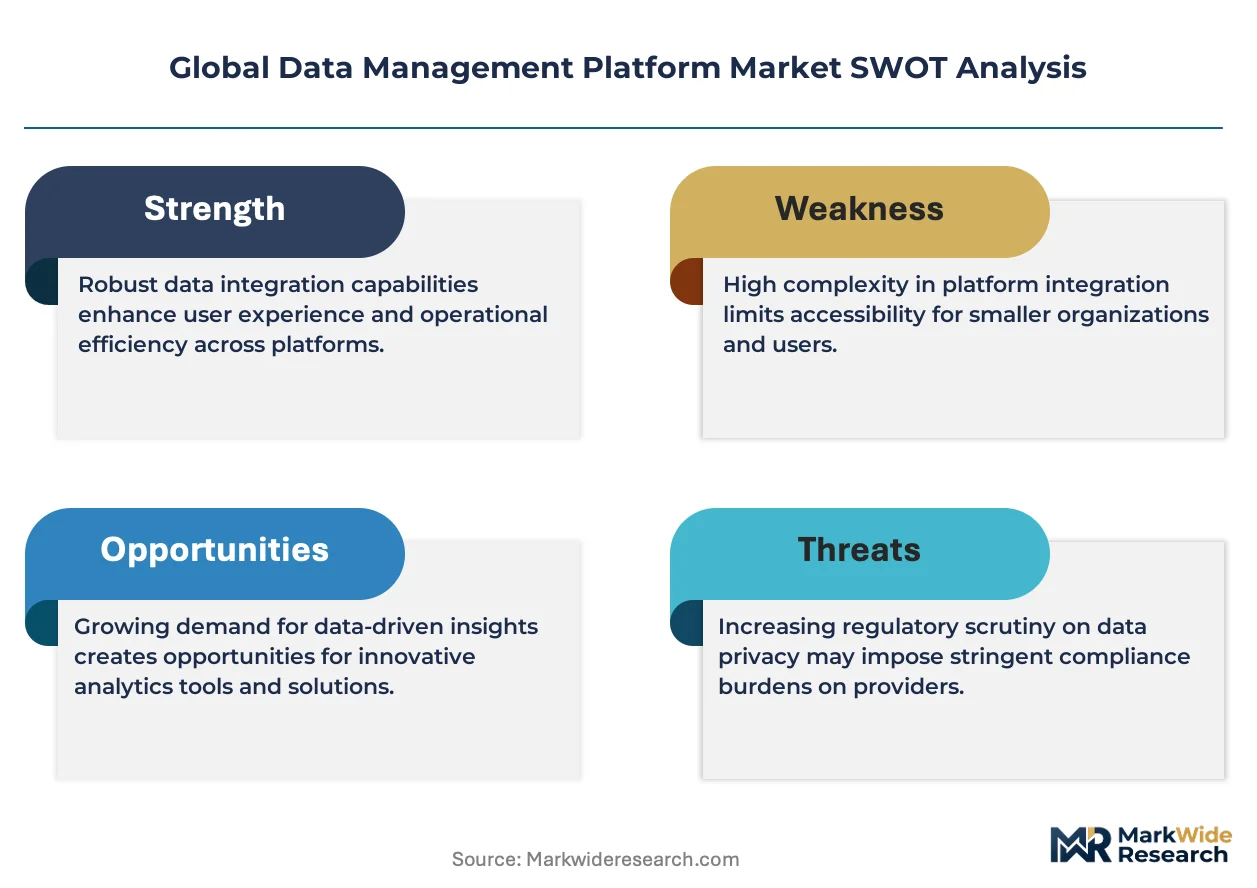
EU AI Act certification tiers gate both supplier qualification and price differentiation simultaneously, forcing platform vendors to invest in audit-trail automation before bidding on European financial services contracts while allowing certified providers to command premium positioning against uncertified rivals.
Pricing Analysis
Cloud-native architecture pricing gaps separate current-generation API-first platforms from legacy on-premises estates and emerging edge-optimized configurations. Three-tier pricing structure across premium, standard, and economy levels tracks governance module depth and data residency certification. Price differentiation hinges on ISO 27001 alignment and sovereign cloud accreditation, with German Gaia-X certification commanding substantial uplifts. Cost compression in standard tiers intensifies as hyperscaler marketplaces commoditize base integration workloads. Mid-market manufacturers show highest price sensitivity, while BFSI institutions prioritize compliance over cost.
Supply Chain Analysis
India and Germany anchor global delivery of data engineering talent and sovereign cloud infrastructure respectively. Platform development draws from Bengaluru-based integration specialists, Munich-certified compliance architects, and Seattle-area hyperscaler engineering pools. Raw material dependencies include GPU compute clusters, encryption hardware security modules, and open-source framework maintenance. Single-source vulnerability concentrates in specialized privacy engineering expertise. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform vendors face substitution pressure from composable best-of-breed challengers assembling point solutions into integrated stacks, requiring defensive architecture investments to maintain account control.
For Market Incumbents: Consolidate governance module portfolios through targeted capability acquisition, embedding EU AI Act audit automation and consent orchestration as native platform layers rather than third-party attachments. Deepen vertical integration into sovereign cloud partnerships, securing Gaia-X and MeghRaj certification pathways that challengers cannot replicate without multi-year investment cycles. Prioritize identity resolution infrastructure lock-in, as buyer committees increasingly mandate integration with existing customer profile stores. For New Entrants and Emerging Players: Embedded data observability micro-modules represent the most penetrable service-layer gap, with incumbents under-serving real-time schema drift detection for mid-market retail and logistics operators. Target German manufacturing suppliers scrambling for CSRD-compliant emissions traceability, where legacy platforms lack carbon accounting module maturity. Pursue API-first positioning with native edge deployment support, bypassing incumbent complexity in hybrid orchestration. For Investors and Strategic Acquirers: EU AI Act enforcement timeline reshapes the acquisition landscape toward governance-embedded platforms with proven European financial services deployments. Long-term viability centers on vendors demonstrating sustained R&D allocation to privacy-preserving architectures, with federated learning capabilities as the critical differentiator. Monitor sovereign cloud certification velocity as the key inflection signal, tracking which platforms secure Gaia-X and MeghRaj approvals ahead of procurement cycle peaks.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Gaia-X and MeghRaj approvals unlock European and Indian public sector procurement pipelines. |
| Governance Module Acquisition | Consent orchestration and lineage tracking capabilities compress time-to-compliance for BFSI buyers. |
| Edge Deployment Optimization | Sub-100-millisecond inference nodes capture predictive maintenance workloads in US automotive supplier networks. |
| Federated Learning Integration | Privacy-preserving architectures enable competing banks to train models without centralizing sensitive records. |
| Carbon Accounting Module Development | ISO 14064-aligned data structures satisfy CSRD Scope 3 disclosure mandates for German automotive suppliers. |
Research Methodology
A spread of perspectives from platform engineering directors, data governance officers at European financial institutions, cloud procurement leads at Indian e-commerce operators, and compliance architects converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory enforcement notices, and sovereign cloud certification registries. Bottom-up sizing of deployment configurations and top-down cross-checks against vertical IT spending benchmarks established triangulated market estimates.
Segmentation dimensions modeled span deployment architecture, solution type, use case velocity requirements, and industry vertical regulatory intensity. Value projections across the analysis window incorporate elastic compute consumption patterns, governance module attach rates, and sovereign infrastructure premium capture. CAGRs derive from regression analysis of historical procurement cycle compression and forward-looking compliance deadline impacts, with specific weighting for EU AI Act enforcement phases and CSRD disclosure rollout schedules.
Underlying assumptions cover sustained cloud migration momentum, stable regulatory enforcement timelines, and continued talent scarcity in privacy engineering, with deviation risk concentrated in data localization rule fragmentation and hyperscaler pricing volatility. Recalibration cycles align with material shifts in sovereign certification requirements and major compliance enforcement milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
South Korea Data Center Server Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Enterprise Network Infrastructure Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
DNA Digital Data Storage Market