
 Data Center Servers Market | 2026-2036
Data Center Servers Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Servers Market Outlook
AI infrastructure talent scarcity is bifurcating the Data Center Servers Market into vendors that can design liquid-cooled GPU clusters versus those locked into air-cooled legacy architectures. Dell Technologies Inc. leverages its supply chain scale to dominate enterprise rack deployments. Hewlett Packard Enterprise Company differentiates through its Cray supercomputing heritage in high-performance segments. Super Micro Computer Inc. specializes in building-block server architectures that hyperscalers customize at volume.
Data center servers are enterprise-grade computing systems engineered to process, store, and distribute data across networked environments, typically operating at power densities exceeding 15 kW per rack in modern configurations. These systems employ redundant power supplies, ECC memory, and hot-swappable components to ensure continuous uptime for mission-critical workloads. Rack servers anchor the majority of installed capacity due to their density flexibility and standardized 19-inch mounting compatibility across facilities. Blade servers capture expanding share in hyperscale deployments where shared power and cooling infrastructure trims operational overhead. Converged systems occupy premium price tiers by bundling compute, storage, and networking into pre-validated stacks that accelerate enterprise deployment timelines.
The U.S. EPA Energy Star program and EU Ecodesign regulations mandate minimum power supply efficiency and idle power thresholds, compelling OEMs to redesign motherboard voltage regulation and fan curves. California's Title 20 appliance standards extend these requirements to servers sold into the largest U.S. state economy, creating a de facto national compliance floor. China's GB standards for data center power usage effectiveness impose parallel constraints on equipment deployed domestically. Stakeholders must monitor how regional efficiency mandates reshape component sourcing and thermal design roadmaps.
Market Dynamics
Hyperscale cloud operators compress hardware refresh cycles from five years to three, forcing OEMs to accelerate thermal design roadmaps while liquid-cooled GPU clusters displace air-cooled legacy architectures across AI training workloads.
Growth Catalysts
- AI Training Clusters:Generative model deployment drives rack power densities past 100 kW, mandating direct liquid cooling adoption in hyperscale facilities.
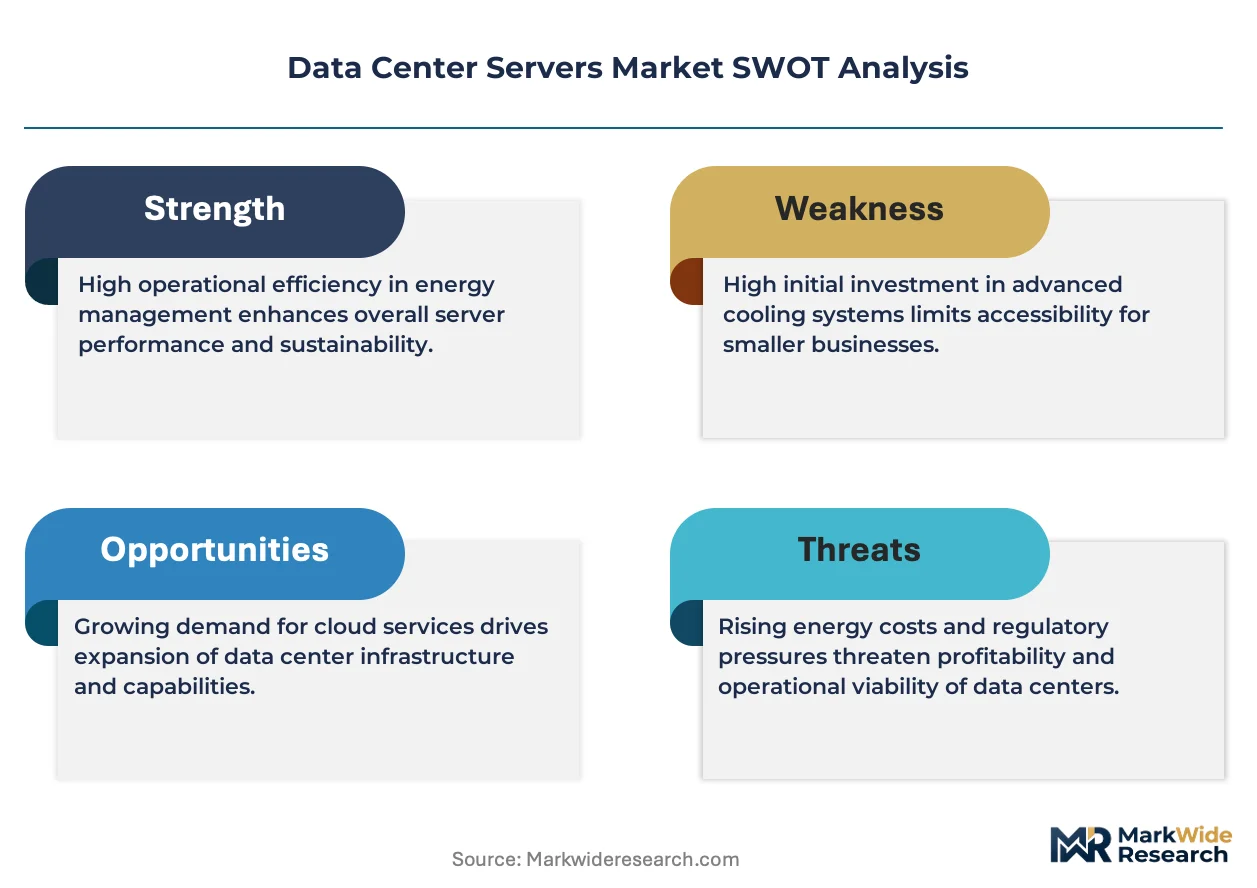
- EU Ecodesign Rules:Minimum power supply efficiency thresholds force motherboard voltage regulation redesigns, accelerating component refresh cycles.
- Northern Virginia Corridor:Concentrated cloud provider demand creates captive infrastructure zones with dedicated substations and fiber backbones.
Market Restraints
- Advanced Packaging Bottlenecks:CoWoS and HBM3 supply concentration in Taiwan constrains GPU server output regardless of downstream assembly capacity.
- Copper and Rare Earth Volatility:Power distribution busbars and permanent magnet motors face input cost swings that compress OEM margins on fixed-price enterprise contracts.
- Permitting Delays:Grid interconnection queues in Texas and Arizona extend facility commissioning timelines beyond 36 months.
Strategic Opportunities
- India Data Center Expansion:PLI scheme incentives for electronics manufacturing attract server assembly investments to Chennai and Noida.
- Edge AI Inference:Micro data centers below 500 kW deploy compact GPU servers for real-time video analytics and autonomous systems.
- Modular Liquid Cooling:Standardized cold plate and manifold designs allow hyperscalers to mix compute generations within shared infrastructure.
Industry Challenges
- Thermal Engineer Scarcity:Two-phase cooling and immersion system design expertise concentrates at a handful of specialist firms.
- Legacy DCIM Integration:Modern GPU clusters require API-native management platforms incompatible with decades-old facility monitoring software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Servers Market |
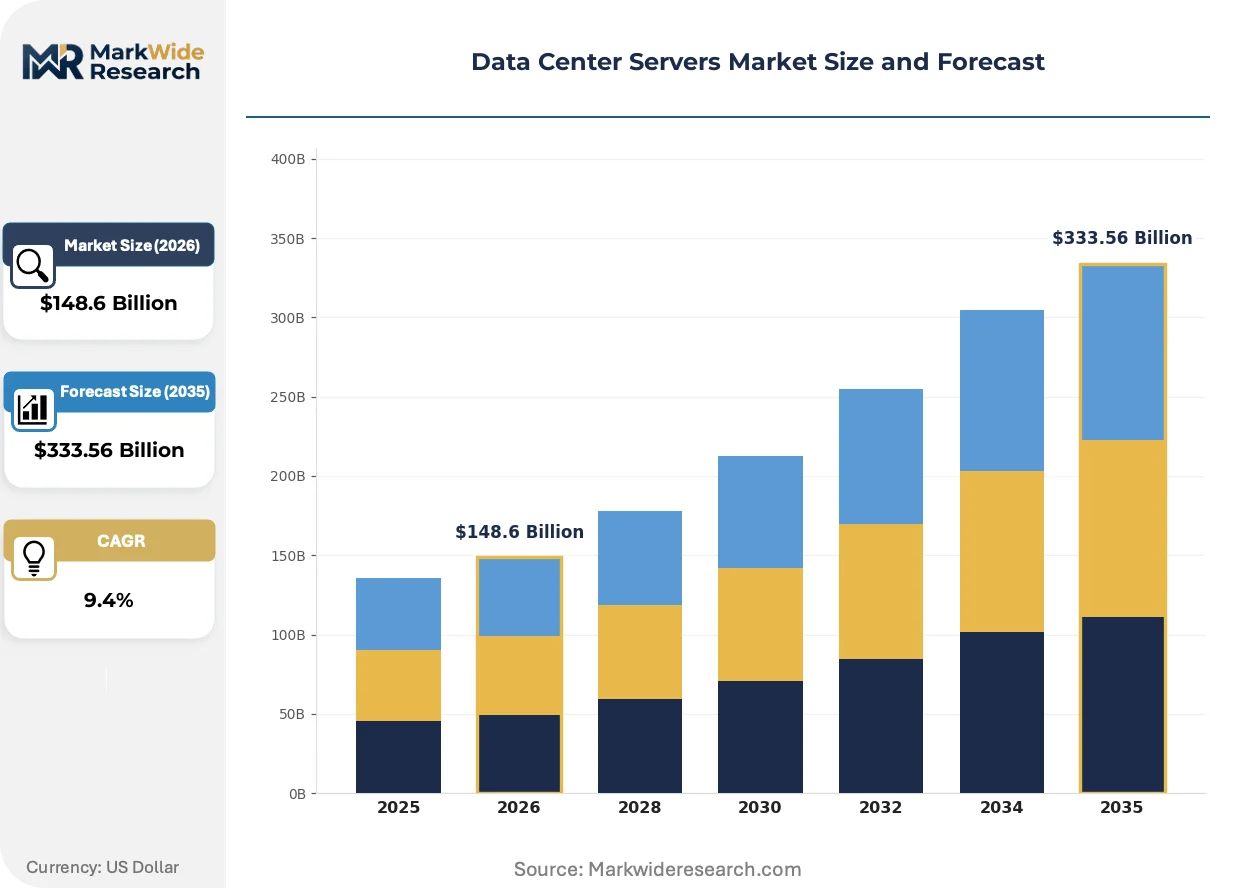
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $333.56 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Converged Systems Installation Type: On-premises, Cloud-based, Hybrid, Colocation End User: Enterprises, Government, Telecommunications, Managed Service Providers Form Factor: 1U, 2U, 3U, 4U |
| Companies Covered | Dell Technologies Inc., Hewlett Packard Enterprise Company, Lenovo Group Limited, Cisco Systems Inc., Huawei Technologies Co., Ltd., Inspur Co., Ltd., Super Micro Computer Inc., Quanta Computer Inc., Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Servers Market Strategic Shifts
Server architecture is fragmenting into disaggregated resource pools as memory, compute, and accelerators decouple from monolithic motherboard designs. This decomposition demands new interconnect standards and reshapes how OEMs configure system-level warranties.
Direct liquid cooling is decomposing traditional air-cooled rack economics. Cold plates and rear-door heat exchangers capture 80% of server thermal load, permitting 50 kW-plus rack densities. Hyperscalers in California and Singapore deploy these systems at volume, compressing facility footprint requirements and shifting CapEx toward plumbing infrastructure.
EPA Energy Star 3.0 server specifications tighten idle power thresholds and mandate power supply efficiency above 94% at 50% load. OEMs redesign voltage regulation modules and fan control curves to comply. Enterprise rack server SKUs sold into California must certify against Title 20 appliance standards, creating design constraints that propagate nationally.
Hyperscalers now procure bare-metal chassis and install own accelerators, memory, and NICs. This disintermediation compresses traditional OEM server margins and shifts value capture toward component suppliers. The practice is most visible among cloud operators in Northern Virginia and Frankfurt, where customization at volume justifies captive integration facilities.
Data Center Servers Market Segmentation
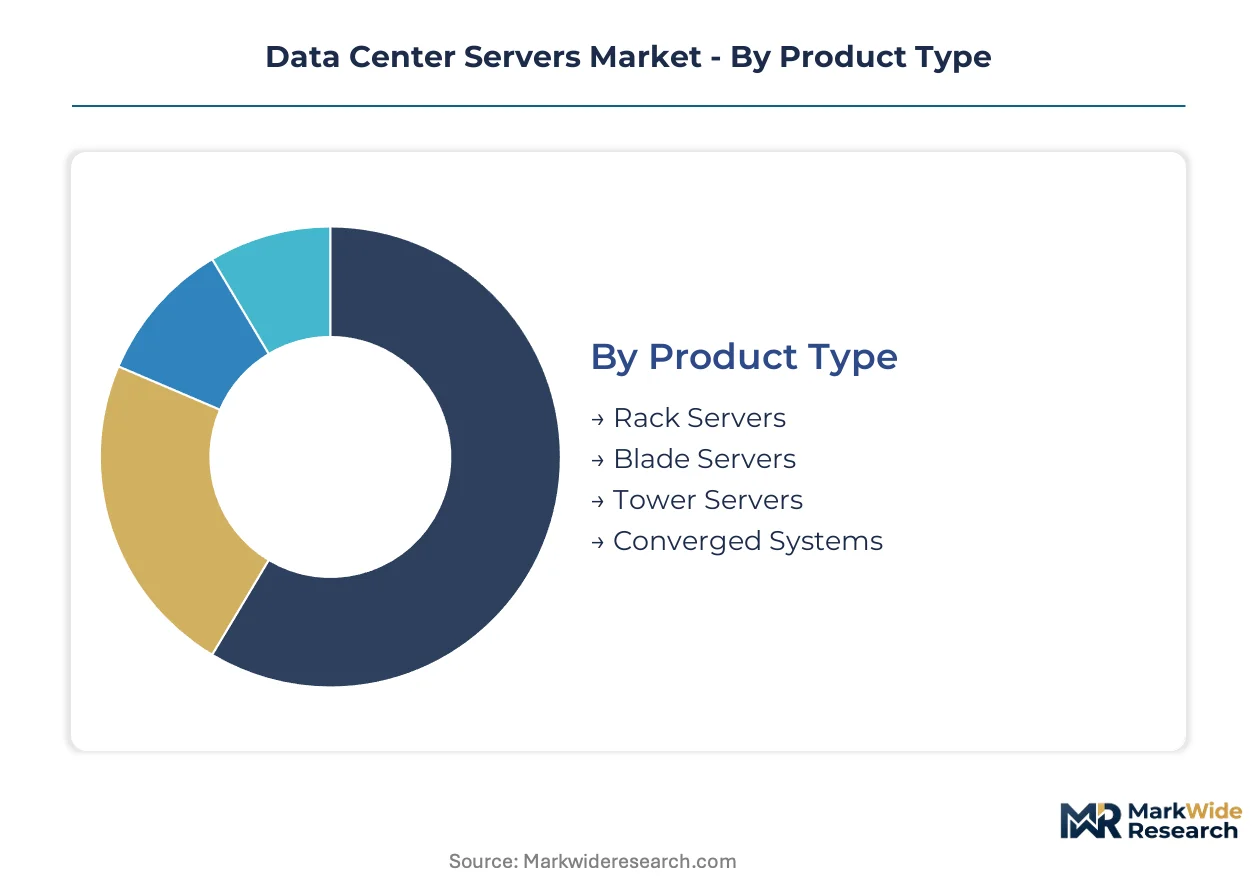
Server architecture fragmentation demands granular segmentation as liquid-cooled GPU clusters displace air-cooled legacy systems across AI workloads. Procurement patterns diverge sharply between hyperscalers customizing bare-metal chassis and enterprises purchasing pre-validated converged stacks.
Product Type:
Rack servers face intensifying substitution pressure from blade architectures in hyperscale facilities where shared infrastructure trims operational overhead per compute unit.
- Rack Servers:Standardized 19-inch mounting compatibility drives deployment across enterprise data centers and colocation facilities. Northern Virginia's cloud corridor absorbs the highest concentration of high-density rack configurations as hyperscalers refresh air-cooled infrastructure ahead of liquid-cooled transitions.
- Blade Servers:Shared power and cooling infrastructure reduces cabling complexity and facility footprint in deployments exceeding 10,000 nodes. Frankfurt and Singapore facilities deploy these systems at volume where space constraints and energy costs justify premium chassis economics.
- Tower Servers:Standalone vertical enclosures serve remote office and small business environments where rack infrastructure remains uneconomical.
- Converged Systems:Pre-validated compute-storage-network bundles accelerate enterprise deployment timelines for virtualized workloads.
Rack servers anchor the volume base while blade servers gain share at the steepest rate.
Installation Type:
Cost tier stratification separates capital-intensive on-premises deployments from operational-expense cloud models that dominate AI training workload economics.
- On-premises:Enterprise-owned facilities retain mission-critical workloads requiring sub-millisecond latency and sovereign data control. Financial services clusters in London and Tokyo maintain captive infrastructure for regulatory compliance and transaction processing.
- Cloud-based:Hyperscale operators provision bare-metal and virtualized instances with metered pricing that shifts capital burden to operational budgets. AWS, Azure, and GCP absorb the majority of generative AI training demand through reserved instance contracts spanning three-year horizons.
- Hybrid:Workload portability between private infrastructure and public cloud enables burst capacity for seasonal demand spikes.
- Colocation:Wholesale and retail leasing models provide power, cooling, and physical security without facility ownership overhead.
Cloud-based deployments command the largest revenue pool while hybrid architectures expand most quickly among regulated enterprises.
End User:
Application intensity varies dramatically as telecommunications operators deploy edge inference nodes while enterprises consolidate general-purpose compute.
- Enterprises:Fortune 500 corporations drive demand for SAP HANA-certified appliances and GPU-accelerated virtualization hosts. Manufacturing and healthcare verticals in Germany and the United States prioritize converged systems with validated disaster recovery configurations.
- Government:Defense and civilian agencies procure ruggedized servers through certified supply chains with domestic assembly requirements.
- Telecommunications:5G network densification propels micro data center deployments for low-latency edge services.
- Managed Service Providers:Multi-tenant hosting operations standardize on modular server architectures to minimize spare parts inventory across distributed facilities.
Enterprises anchor the volume base while telecommunications providers gain share at the steepest rate.
Form Factor:
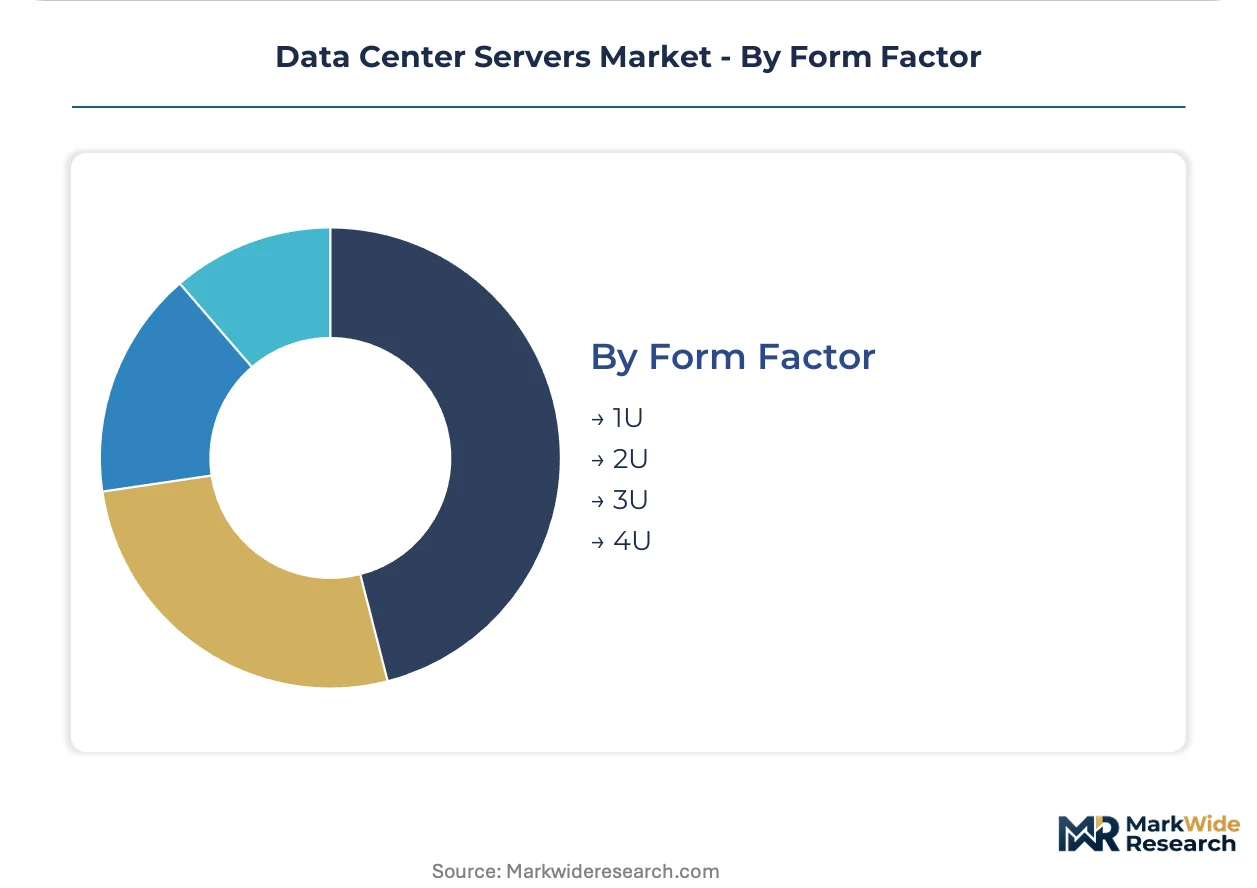
Power density constraints favor taller chassis as 100 kW-plus racks mandate liquid cooling integration that 1U enclosures cannot accommodate.
- 1U:Single-rack-unit height maximizes compute density for web serving and lightweight virtualization where thermal loads remain below 350 watts per node.
- 2U:Dual-rack-unit enclosures balance expansion slots and storage bays against vertical space consumption in standard 42U cabinets.
- 3U:Triple-rack-unit configurations accommodate multi-GPU accelerators and high-capacity storage backplanes for video rendering and analytics workloads.
- 4U:Quad-rack-unit chassis house eight-GPU training nodes with integrated liquid cooling manifolds that hyperscalers deploy for large language model development.
2U configurations anchor the volume base while 4U systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Northern Virginia's data center corridor while Indian assembly operations compete on cost. Regional regulatory fragmentation forces OEMs to maintain parallel certification tracks. Facility commissioning timelines vary dramatically based on grid interconnection queues.
United States
Hyperscale cloud operators in Northern Virginia drive rack power densities past 100 kW for AI training clusters. The EPA Energy Star program mandates power supply efficiency above 94% at 50% load. Texas and Arizona face grid interconnection queues extending facility commissioning beyond 36 months.
Germany
Frankfurt's financial services sector maintains captive infrastructure for regulatory compliance and transaction processing. EU Ecodesign rules impose minimum idle power thresholds on servers sold into member states. Bavaria's industrial clusters absorb high-density blade deployments where space constraints justify premium chassis economics.
China
Domestic cloud operators expand capacity under GB standards for data center power usage effectiveness. MIIT regulations accelerate motherboard voltage regulation redesigns for efficiency compliance. Beijing-Tianjin-Hebei corridor concentrates hyperscale facilities with dedicated substations and fiber backbones.
India
PLI scheme incentives attract server assembly investments to Chennai and Noida manufacturing zones. CEA regulations impose parallel constraints on equipment deployed domestically. Maharashtra's Mumbai-Pune corridor emerges as a captive infrastructure zone for financial services and telecommunications operators.
Singapore
Tropical climate constraints accelerate liquid cooling adoption for facilities exceeding 50 kW rack densities. The country's national efficiency mandates reshape component sourcing and thermal design roadmaps. The city-state's limited land area compresses facility footprint requirements and shifts capital expenditure toward plumbing infrastructure.
Data Center Servers Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Data Center Servers Market. The vendor base separates into three tiers: integrated OEMs with supply chain scale, specialists in high-performance computing architectures, and contract manufacturers serving hyperscaler customization demands. Strategic moves concentrate on thermal design roadmaps for liquid-cooled GPU clusters and bare-metal chassis disintermediation.
Within the integrated OEM tier, Dell Technologies Inc. and Hewlett Packard Enterprise Company exemplify divergent positioning strategies. Dell leverages supply chain scale to anchor enterprise rack deployments across standardized configurations. HPE occupies a position drawing on supercomputing heritage for high-performance segments. Super Micro Computer Inc. sits within the specialist tier, representing the building-block architecture approach that hyperscalers customize at volume.
| Leading Market Players |
|---|
| Dell Technologies Inc. |
| Hewlett Packard Enterprise Company |
| Lenovo Group Limited |
| Cisco Systems Inc. |
| Huawei Technologies Co., Ltd. |
| Inspur Co., Ltd. |
| Super Micro Computer Inc. |
| Quanta Computer Inc. |
| Fujitsu Limited |
| Others |
Value Chain & Pricing Dynamics
EPA Energy Star 3.0 certification gates both supply qualification and price differentiation simultaneously, as OEMs must redesign voltage regulation modules and fan control curves to meet idle power thresholds above 94% efficiency at 50% load. This regulatory floor compresses margins on non-compliant legacy SKUs while creating tiered pricing power for certified configurations sold into California's Title 20 jurisdiction and EU Ecodesign markets.
Pricing Analysis
Northern Virginia commands 15-20% premiums over Indian assembly pricing for identical rack configurations due to captive infrastructure zones with dedicated substations. Three-tier pricing structure across liquid-cooled GPU clusters, air-cooled enterprise racks, and bare-metal hyperscale chassis reflects thermal design complexity and certification grade. Cost compression in air-cooled legacy tiers intensifies because hyperscalers procure bare-metal chassis for captive integration. Small and medium enterprises exhibit highest price sensitivity while cloud operators prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Taiwan and South Korea anchor advanced packaging capacity for CoWoS and HBM3 components that constrain GPU server output regardless of downstream assembly scale. The supply chain draws from Malaysian PCB fabrication, Vietnamese power supply manufacturing, and Mexican final assembly for North American delivery. Single-source vulnerability concentrates in Taiwan's foundry ecosystem where geopolitical contingency risks disrupt component flows. Distribution runs through direct OEM relationships with hyperscalers and tiered channel partners serving enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center server manufacturing operates as a defensive-moat business where switching costs lock hyperscalers into validated thermal designs and captive integration facilities. Regulatory entrenchment through EPA Energy Star and EU Ecodesign compliance creates asymmetric compliance burdens that favor incumbents with dedicated certification teams.
For Market Incumbents: Shield market position by deepening backward integration into liquid cooling component production and securing captive CoWoS allocation through multi-year foundry commitments. Accelerate motherboard voltage regulation redesigns ahead of EPA Energy Star 3.0 enforcement timelines. Vertical integration into cold plate and manifold manufacturing defends margin structure against specialist component suppliers.
For New Entrants and Emerging Players: Energy Star 3.0 fast-track certification offers entry path into California and EU markets where incumbent compliance gaps persist. Target edge AI inference deployments below 500 kW where thermal engineering requirements remain accessible and hyperscaler procurement patterns have not yet standardized. Pursue modular liquid cooling partnerships with telecommunications operators densifying 5G infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid-cooled GPU cluster segments as rack power densities exceed 100 kW and plumbing infrastructure displaces traditional air-handling capital. Long-term viability favors OEMs with demonstrated hyperscaler bare-metal chassis relationships and in-house thermal engineering capabilities. Monitor CoWoS capacity expansion announcements from Taiwan foundries as inflection indicator for GPU server output constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Buildout | Direct liquid cooling adoption in Northern Virginia and Singapore facilities enables 50 kW-plus rack densities. |
| Bare-Metal Chassis Customization | Hyperscalers in Frankfurt and Northern Virginia disintermediate traditional OEM margins through captive integration. |
| Energy Efficiency Certification Investment | EPA Energy Star 3.0 and EU Ecodesign compliance gates access to California and European enterprise markets. |
| Advanced Packaging Supply Agreement | CoWoS and HBM3 allocation from Taiwan foundries determines GPU server output regardless of assembly capacity. |
| Edge AI Micro Data Center Deployment | Telecommunications operators in India and Germany deploy compact GPU servers for real-time 5G analytics workloads. |
Study Parameters
Desk research of hyperscaler capital expenditure disclosures, EPA Energy Star certification databases, and EU Ecodesign regulatory filings preceded structured interviews with data center facility engineers, server procurement officers at cloud operators, thermal design specialists, motherboard voltage regulation vendors, and liquid cooling system integrators. Primary fieldwork validated component cost structures and refresh cycle compression trends while secondary sources including SEC filings, customs trade records, and foundry capacity announcements provided supply-side calibration. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates.
Variance decomposition across product type, installation model, end-user vertical, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include rack density tier, cooling architecture, and procurement pattern divergence between hyperscale customization and enterprise converged stacks. CAGRs were derived from installed base refresh dynamics and power density inflection points. Forecast inputs incorporated GPU server output constraints from advanced packaging bottlenecks and grid interconnection queue timelines in Texas and Arizona.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscale capital deployment and stable foundry capacity allocation; material deviation in CoWoS supply or permitting timelines would warrant model refresh. Forecasts reflect base-case assumptions regarding regulatory enforcement continuity and thermal engineering talent availability. Recalibration cycles align with material shifts in EPA Energy Star specification updates and hyperscaler procurement pattern changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Italy Data Center Networking Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
Taiwan Data Center Networking Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
New Zealand Data Center Networking Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
North America Data Center Networking Market