
 Indonesia Data Center Networking Market | 2026-2036
Indonesia Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Data Center Networking Market Insights
Indonesia is reshaping Southeast Asian data center capacity as operators expand fiber and power infrastructure across the archipelago. Cisco Systems Inc leverages its established channel partnerships to dominate enterprise switching deployments in Jakarta and Surabaya. Huawei Technologies Co Ltd competes aggressively on cost-engineered optical transport for state-backed cloud projects. Juniper Networks Inc specializes in high-performance routing for financial institutions requiring sub-millisecond latency.
Indonesia data center networking encompasses the interconnected switching, routing, cabling, and software-defined systems that enable compute and storage resource communication within and between facilities, typically operating at speeds from 10 Gbps to 400 Gbps with redundancy below 50 milliseconds failover. Ethernet switching anchors the largest component spend as hyperscalers standardize on 100 Gbps and 400 Gbps leaf-spine architectures, while InfiniBand gains traction in AI training clusters where NVIDIA-backed deployments require lossless RDMA transport. Managed services command expanding margin pools as operators outsource network operations to address acute engineering talent shortages in Indonesian provinces outside Java.
BIS-equivalent national standards and Indonesia's data localization regulations enforced by the Ministry of Communication and Informatics shape equipment procurement by mandating domestic presence and certified encryption modules. The country's central bank, Bank Indonesia, imposes network resilience requirements on BFSI data centers that elevate demand for redundant routing and automated failover systems. Stakeholders must monitor how evolving spectrum allocations and submarine cable landing rights alter inter-facility bandwidth economics before committing to multi-year infrastructure contracts.
Market Dynamics
Hyperscale cloud operators are consolidating network procurement around 400 Gbps Ethernet standards, compressing vendor margins while forcing domestic system integrators to certify on foreign reference architectures.
Growth Catalysts
- Data Localization Mandates:Ministry of Communication and Informatics regulations require domestic data storage, compelling international cloud providers to build Java-based facilities and source local networking infrastructure.
- AI Training Clusters:GPU-intensive workloads in Batam and Jakarta are driving InfiniBand and high-speed Ethernet deployments for lossless RDMA transport between compute nodes.
- Submarine Cable Landings:New fiber optic systems terminating in Banten and Sulawesi are reducing inter-facility latency costs and enabling distributed disaster recovery architectures.
Market Restraints
- Optical Component Import Dependency:Indonesia lacks domestic 400 Gbps transceiver manufacturing, exposing operators to USD-denominated supply volatility and extended lead times from Chinese and Taiwanese suppliers.
- Power Infrastructure Gaps:Outside Java's PLN grid, unreliable electricity in Kalimantan and Papua forces diesel generator redundancy that elevates total cost of ownership for edge deployments.
- Spectrum Allocation Uncertainty:Pending decisions on millimeter-wave bands for wireless data center interconnects are freezing procurement cycles for campus-style facilities in Greater Jakarta.
Strategic Opportunities
- Edge Computing in Eastern Provinces:Maluku and Papua remain unserved by hyperscale presence, creating first-mover advantages for modular micro-data center networks targeting resource extraction and maritime logistics.
- Open RAN Convergence:Disaggregated radio access networks are creating demand for white-box switching fabrics that data center vendors can repurpose for telecom edge deployments.
- Green Building Certifications:Bank Indonesia's sustainable finance taxonomy is incentivizing low-PUE network designs that reduce cooling energy through liquid-cooled switch deployments.
Industry Challenges
- Network Engineering Talent Scarcity:Indonesian universities produce insufficient CCIE-equivalent certified engineers, forcing operators to import Malaysian and Singaporean contractors at premium rates.
- Legacy Protocol Integration:State-owned enterprises still operate MPLS-based wide area networks that require costly gateway equipment to interface with modern VXLAN-EVPN fabrics.
- Encryption Module Certification:BIS-equivalent testing for hardware security modules adds six to nine months to procurement timelines for financial services deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Data Center Networking Market |
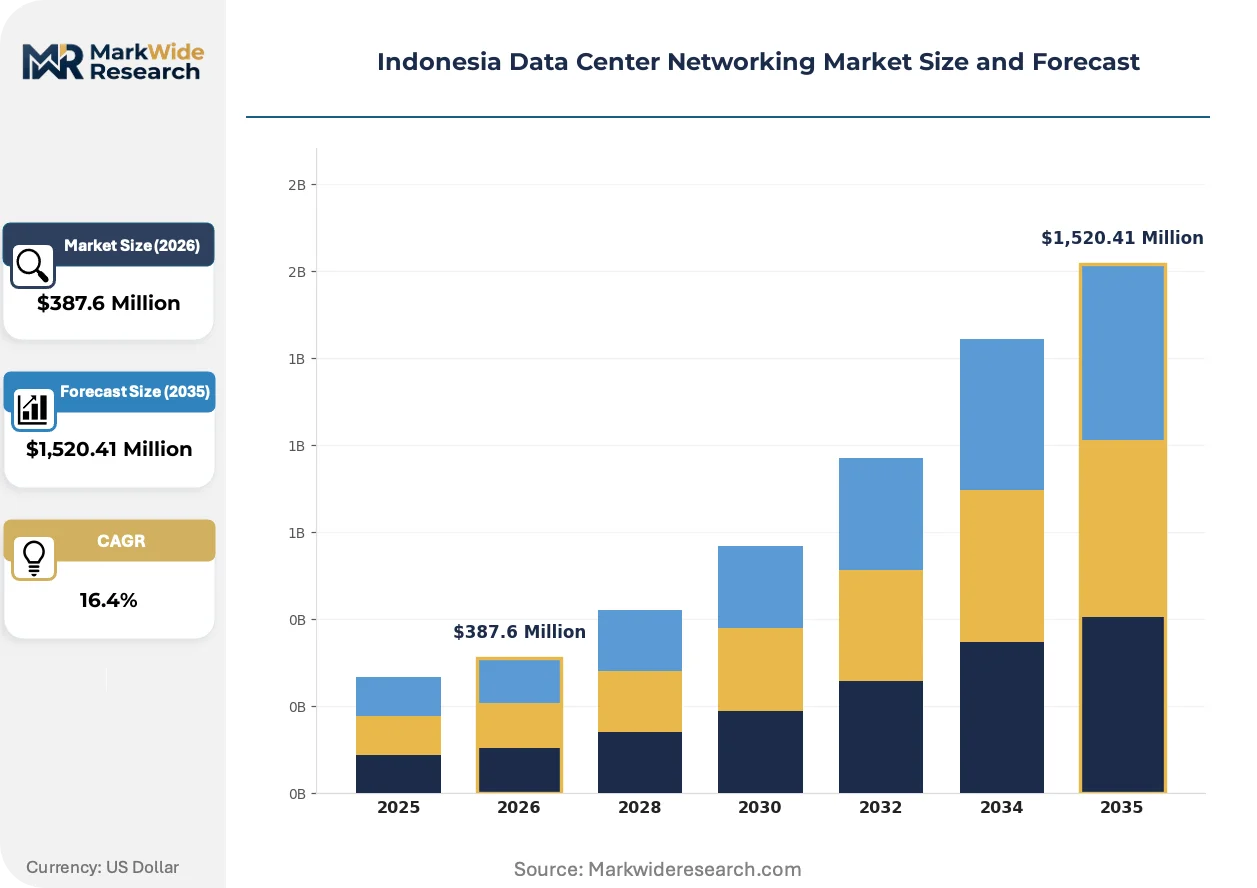
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,520.41 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ethernet, Fiber Channel, InfiniBand, SDN Component: Switches, Routers, Cables, Firewalls Service Type: Managed Services, Professional Services, Support Services, Maintenance Services End User: Telecommunications, BFSI, Healthcare, E-Commerce |
| Companies Covered | Cisco Systems Inc, Huawei Technologies Co Ltd, Juniper Networks Inc, Dell Technologies Inc, Arista Networks Inc, NEC Corporation, Hewlett Packard Enterprise, Nokia Corporation, Extreme Networks Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Data Center Networking Market Trends and Innovations
Software-defined networking is collapsing traditional hardware procurement cycles as Indonesian operators adopt programmable fabrics that reconfigure through code rather than physical replacement.
Network function virtualization is replacing dedicated hardware appliances with software instances running on commodity x86 servers. Large financial institutions in Jakarta are migrating firewall and load-balancing functions to virtualized platforms within eighteen-month refresh windows. This shift is virtualizing capital expenditure models and enabling capacity scaling without forklift upgrades to chassis-based switches.
Bank Indonesia's operational resilience guidelines now mandate automated failover testing for critical payment infrastructure, forcing tier-one banks to deploy intent-based networking with machine-verified policy compliance. The regulation elevates demand for telemetry-rich switching platforms that expose granular performance data to centralized orchestration systems. BFSI data centers in Surabaya and Medan are responding by consolidating vendor relationships around suppliers with proven API integration capabilities.
Colocation buyers are unbundling network operations from facility contracts and contracting directly with managed service providers for 24/7 monitoring. This disintermediation pressures traditional data center operators to either build captive network operations centers or surrender margin to specialized third parties. The pattern is most pronounced among e-commerce platforms in Tangerang that require sub-50 millisecond latency guarantees to CDN nodes.
Indonesia Data Center Networking Market Segmentation
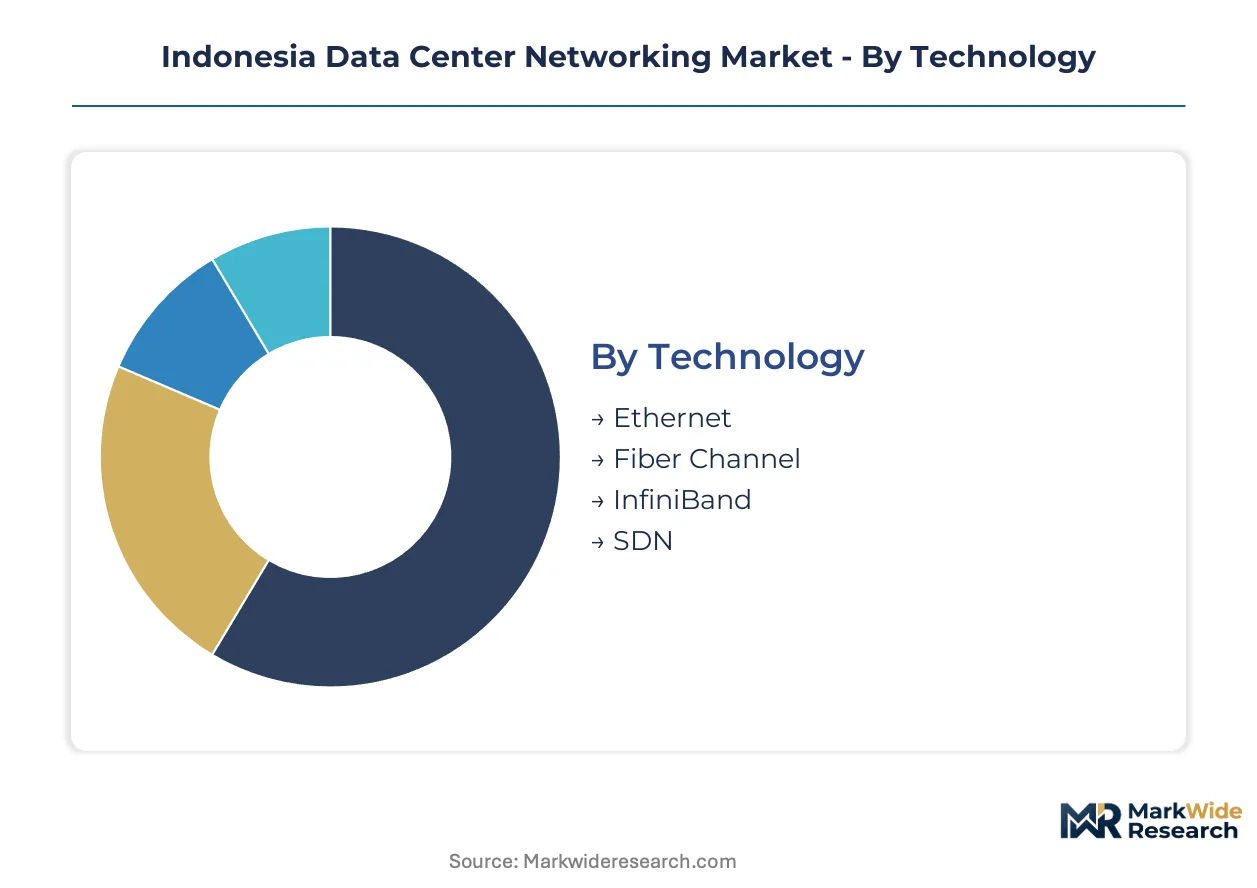
Technology selection in Indonesian data centers follows workload-specific latency and bandwidth requirements rather than vendor preference. Procurement patterns diverge sharply between Java's hyperscale clusters and provincial edge deployments where infrastructure constraints dominate decision-making.
Technology:
Mature transport protocols anchor mainstream deployments while emerging fabrics capture specialized high-performance workloads.
- Ethernet:Dominates rack-to-rack connectivity with 100 Gbps and 400 Gbps leaf-spine architectures now standard in Greater Jakarta hyperscale facilities. Bank Indonesia's payment infrastructure mandates and cloud provider procurement in Cikarang drive consistent refresh cycles.
- InfiniBand:Lossless RDMA transport enables GPU-intensive AI training clusters in Batam and Jakarta where NVIDIA-backed deployments require sub-microsecond latency between compute nodes. Ministry of Communication and Informatics data localization enforcement accelerates domestic build-outs of these specialized fabrics.
- Fiber Channel:Persists in legacy storage area networks at state-owned enterprises requiring backward compatibility with existing SAN investments.
- SDN:Programmable control planes gain traction among colocation operators seeking automated provisioning across multi-tenant environments.
Ethernet handles the majority of throughput; InfiniBand is the fastest mover on share.
Component:
Cost tier stratification separates chassis-based enterprise gear from commodity white-box deployments.
- Switches:Fixed-configuration and modular platforms form the largest procurement category, with spine-layer investments concentrated in Tangerang and Bekasi hyperscale campuses. PLN grid reliability in these zones supports power-hungry 400 Gbps chassis deployments that would fail in eastern provinces.
- Routers:Edge and core routing platforms face demand compression as SD-WAN overlays displace traditional MPLS handoffs at branch locations. Bank Indonesia operational resilience guidelines nonetheless preserve redundant routing investments at tier-one financial data centers in Surabaya and Medan.
- Cables:Fiber optic and copper interconnects represent pure commodity procurement with price sensitivity highest among second-tier colocation providers.
- Firewalls:Next-generation platforms shift toward virtualized deployments as network function virtualization collapses dedicated appliance requirements.
Switches absorb the dominant share of capital allocation; firewalls are expanding most quickly through virtualization.
Service Type:
Customer type divides between operators seeking operational control and those outsourcing complexity.
- Managed Services:Comprehensive network operations outsourcing addresses acute CCIE-equivalent talent scarcity outside Java, with Malaysian and Singaporean contractors commanding premium rates for 24/7 monitoring engagements.
- Professional Services:Design and implementation support concentrates around complex VXLAN-EVPN fabric deployments requiring specialized integration with legacy MPLS infrastructure at state-owned enterprises.
- Support Services:Vendor technical assistance contracts maintain hardware warranty compliance across distributed provincial installations.
- Maintenance Services:Preventive and corrective maintenance sustains equipment lifecycle in facilities where capital refresh cycles extend beyond typical depreciation schedules.
Managed Services commands the largest revenue pool; Professional Services shows the steepest expansion trajectory as integration complexity mounts.
End User:
Application criticality determines redundancy investment and certification requirements.
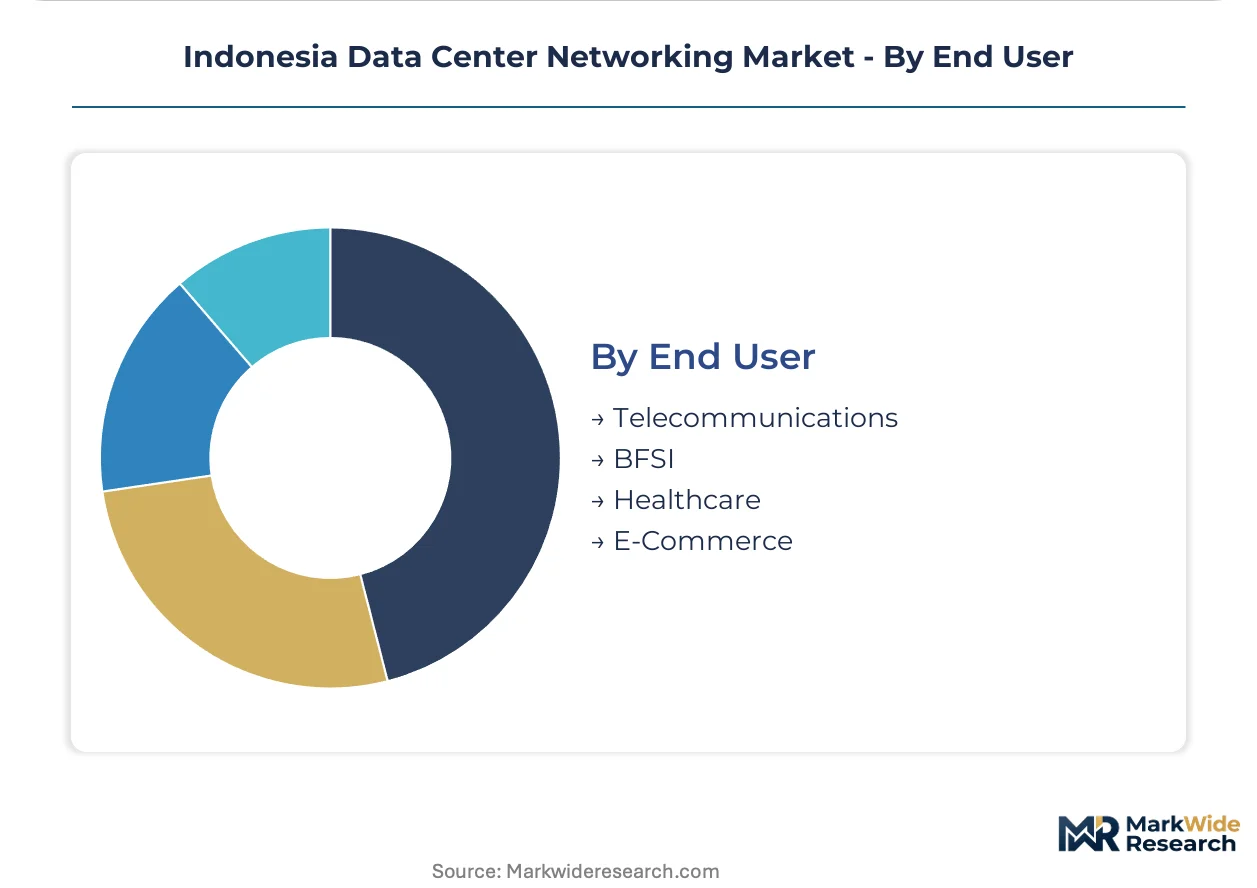
- Telecommunications:Carrier data centers and mobile network infrastructure drive massive port density requirements for 5G core and edge computing deployments across Java and Sumatra.
- BFSI:Bank Indonesia network resilience mandates enforce automated failover and encryption module certification, elevating procurement standards above other verticals. Financial institutions in Jakarta and Surabaya consolidate vendor relationships around API-integrated telemetry platforms.
- Healthcare:Hospital information systems and telemedicine infrastructure generate moderate demand concentrated in Java's major metropolitan areas.
- E-Commerce:Platform operators in Tangerang require sub-50 millisecond latency guarantees to CDN nodes, driving premium interconnect investments.
Telecommunications generates the highest absolute port volume; BFSI delivers the strongest pricing power through regulatory-mandated premium specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Java Toll Road and PLN's 500 kV backbone grid underwrite Indonesia's data center concentration, while submarine cable landings in Banten and Sulawesi anchor inter-facility connectivity across the archipelago.
Java
Greater Jakarta's hyperscale cluster absorbs the majority of 400 Gbps switching deployments, driven by cloud provider procurement in Cikarang and Tangerang. Bank Indonesia's network resilience mandates enforce redundant routing at financial data centers in Surabaya. Batam hosts GPU-intensive AI training clusters requiring InfiniBand fabrics for sub-microsecond latency between compute nodes.
Sumatra
Medan's emerging colocation market addresses northern Indonesian latency requirements for content delivery networks. The Ministry of Communication and Informatics data localization regulations compel international operators to establish Medan presence for domestic data storage compliance. State-owned enterprises in Palembang maintain legacy MPLS infrastructure requiring gateway equipment for VXLAN-EVPN integration.
Kalimantan
Resource extraction logistics in East Kalimantan generate demand for edge computing modules targeting maritime and mining operations. Unreliable PLN grid infrastructure outside major cities forces diesel generator redundancy that elevates total cost of ownership. Balikpapan's industrial zone attracts modular micro-data center networks serving oil and gas sector telemetry.
Sulawesi
New submarine cable landings in South Sulawesi reduce inter-facility latency costs for distributed disaster recovery architectures. Makassar's port infrastructure supports equipment import for eastern Indonesian network build-outs. Spectrum allocation uncertainty for millimeter-wave wireless interconnects freezes procurement cycles for campus-style facilities.
Papua and Eastern Provinces
Maluku and Papua remain unserved by hyperscale presence, creating first-mover advantages for edge computing deployments. Acute CCIE-equivalent talent scarcity forces operators to import Malaysian contractors at premium rates for network operations. Jayapura's maritime logistics hub generates nascent demand for low-latency connectivity to Jakarta-based cloud infrastructure.
Indonesia Data Center Networking Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in optical and silicon supply chains. The vendor base stratifies around three tiers: chassis-based enterprise incumbents, white-box commodity suppliers, and programmable fabric specialists. Two strategic archetypes dominate: hyperscale-optimized vendors competing on port density economics, and compliance-focused providers targeting Bank Indonesia encryption mandates. Consolidation pressure intensifies as 400 Gbps standardization compresses margins and forces domestic system integrators toward foreign reference architectures.
Among North American networking vendors, Cisco Systems Inc and Juniper Networks Inc exemplify divergent competitive positions within the Indonesian market. Cisco occupies the established channel partnership tier, leveraging Jakarta and Surabaya enterprise relationships for switching deployments. Juniper represents the high-performance routing specialization, serving financial institutions requiring sub-millisecond latency. Chinese vendor Huawei Technologies Co Ltd competes aggressively on cost-engineered optical transport for state-backed cloud projects. Arista Networks Inc sits within the hyperscale-optimized tier, capturing cloud provider procurement in Cikarang and Tangerang campus developments. These four companies anchor distinct competitive vectors rather than overlapping segment contests.
| Leading Market Players |
|---|
| Cisco Systems Inc |
| Huawei Technologies Co Ltd |
| Juniper Networks Inc |
| Dell Technologies Inc |
| Arista Networks Inc |
| NEC Corporation |
| Hewlett Packard Enterprise |
| Nokia Corporation |
| Extreme Networks Inc |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic 400 Gbps transceiver manufacturing is compressing margins for Indonesian operators while amplifying pricing power among Chinese and Taiwanese optical component suppliers. This utilization gap forces domestic system integrators to absorb USD-denominated volatility and extended procurement timelines, reshaping total cost of ownership calculations for hyperscale deployments across Java.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between hyperscale cloud operators and networking vendors, with three-tier pricing separating Bank Indonesia-mandated premium encryption tiers from standard enterprise configurations and economy-grade edge deployments. Price differentiation stems from certification grade—BIS-equivalent testing adds six to nine months to timelines—and volume scale, where cloud providers in Cikarang and Tangerang command substantial discounts. Cost compression in the economy tier is intensifying because white-box switching vendors are disaggregating hardware from software support contracts. Colocation providers in second-tier Indonesian markets exhibit the highest price sensitivity, while tier-one financial institutions in Jakarta and Surabaya prioritize compliance over cost.
Supply Chain Analysis
Tariff exposure between China and Taiwan dominates supply chain risk calculations for Indonesian data center operators sourcing 400 Gbps optical transceivers and merchant silicon. Manufacturing concentrates in China, Taiwan, and South Korea, with raw material dependencies spanning gallium arsenide substrates, precision optical lenses, and high-speed DSPs. Single-source vulnerability persists for InfiniBand switch ASICs where NVIDIA-backed deployments tether procurement to captive supply channels. Distribution runs through Singapore-based logistics hubs before final-mile delivery to Jakarta and Surabaya facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
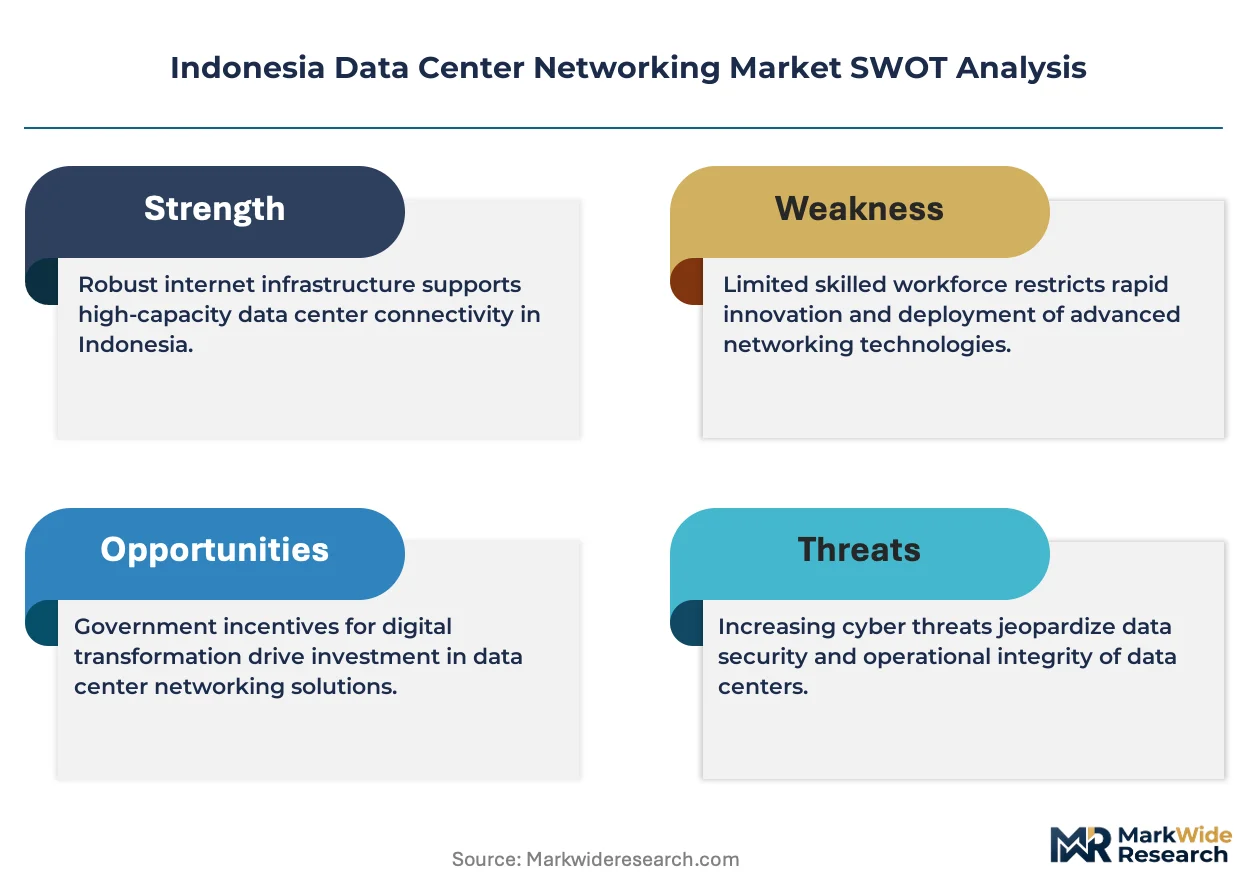
Indonesia's acute CCIE-equivalent engineering shortage outside Java creates a capability-scarcity environment where talent access, not capital, determines competitive viability. This constraint elevates the strategic value of managed service relationships and automated network operations platforms.
For Market Incumbents: Build certification moats around Bank Indonesia encryption module compliance to lock out commodity competitors. Invest in backward integration into professional services capabilities to capture VXLAN-EVPN integration complexity at state-owned enterprises. Expand captive network operations centers in Surabaya and Medan to preempt third-party managed service disintermediation threatening margin pools.
For New Entrants and Emerging Players: Eastern provinces including Maluku and Papua offer geographic underpenetration with minimal hyperscale presence and limited engineering talent competition. Target modular micro-data center networks serving oil and gas telemetry in Balikpapan and maritime logistics in Jayapura. Partner with Malaysian contractors for 24/7 network operations to circumvent local CCIE-equivalent scarcity.
For Investors and Strategic Acquirers: Capital is best deployed toward programmable fabric specialists with proven API integration capabilities serving Bank Indonesia-regulated financial institutions. Long-term viability hinges on telemetry-rich switching platforms that enable intent-based networking compliance. Monitor submarine cable landing progress in Sulawesi and spectrum allocation decisions for millimeter-wave wireless interconnects as inflection indicators for distributed disaster recovery architecture adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Professional Services Capability Buildout | Captures VXLAN-EVPN integration demand from state-owned enterprises operating legacy MPLS infrastructure. |
| Managed Network Operations Center Expansion | Prevents margin erosion from third-party disintermediation in Surabaya and Medan colocation markets. |
| Encryption Module Certification Investment | Secures Bank Indonesia-mandated procurement preference at tier-one Jakarta and Surabaya financial data centers. |
| Eastern Province Edge Computing Deployment | Establishes first-mover position in Maluku and Papua where hyperscale presence remains absent. |
| API-First Telemetry Platform Development | Enables intent-based networking compliance with Bank Indonesia automated failover testing requirements. |
Research Methodology
The analysis maps Ethernet switching, InfiniBand fabrics, SDN deployments, and managed service offerings, each validated through network engineering directors, data center procurement officers, cloud infrastructure architects, and systems integration specialists. Primary fieldwork combined structured interviews with secondary validation against Ministry of Communication and Informatics regulatory filings, Bank Indonesia operational resilience guidelines, PLN grid reliability disclosures, and hyperscaler capex announcements. Bottom-up equipment procurement modeling and top-down market sizing triangulated across vendor shipment data and facility construction permits.
Forecast assumptions held submarine cable landing schedules and spectrum allocation timelines as fixed inputs while varying AI training cluster deployment intensity and data localization enforcement stringency. Segmentation dimensions modeled include transport protocol, component category, service type, and end-user vertical across the projection horizon. CAGRs derived from equipment refresh cycle analysis and hyperscale facility build-out pipelines, with specific inputs from GPU-intensive workload growth in Batam and Jakarta.
Practitioners should monitor optical component import tariff developments and PLN grid expansion timelines in Kalimantan and Papua for early signals of cost structure revision. Forecasts reflect assumptions regarding regulatory enforcement continuity and engineering talent availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Enterprise Server Market