
 Global Recommendation Search Engine Market | 2026-2036
Global Recommendation Search Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recommendation Search Engine Market Foresight
The recommendation search engine market is pivoting on a widening gulf between premium deep-learning inference stacks and commodity collaborative filtering. Google leverages its tensor processing infrastructure to dominate latency-sensitive query ranking. Amazon anchors its recommendation layer to purchase history density across retail and streaming. Netflix differentiates through content-based encoding pipelines that reduce cold-start friction for new titles.
A recommendation search engine is an information retrieval system that ranks and surfaces items by predicting user preference through vector embedding, similarity scoring, and real-time feedback loops, typically operating at sub-100-millisecond latency to serve dynamic content feeds. Cloud-based deployment now leads in enterprise adoption because hyperscalers bundle inference APIs with storage tiers, while edge computing segments show the fastest structural expansion as retailers push personalization into physical store sensors without round-trip latency to central data centers. Deep learning models capture the dominant margin pool in solution types due to GPU training costs and proprietary data moats, though hybrid systems gain ground where explainability requirements constrain black-box architectures.
The EU AI Act and GDPR jointly constrain how recommendation systems process behavioral signals across European jurisdictions, mandating disclosure logic and consent chains that increase compliance overhead. The FCC in the United States monitors algorithmic amplification in broadcast-adjacent streaming, while China's SAMR enforces anti-monopoly provisions on dominant platforms' data usage for preference prediction. Stakeholders must weigh the cost of jurisdictional fragmentation against the revenue lift from hyper-localized recommendation precision.
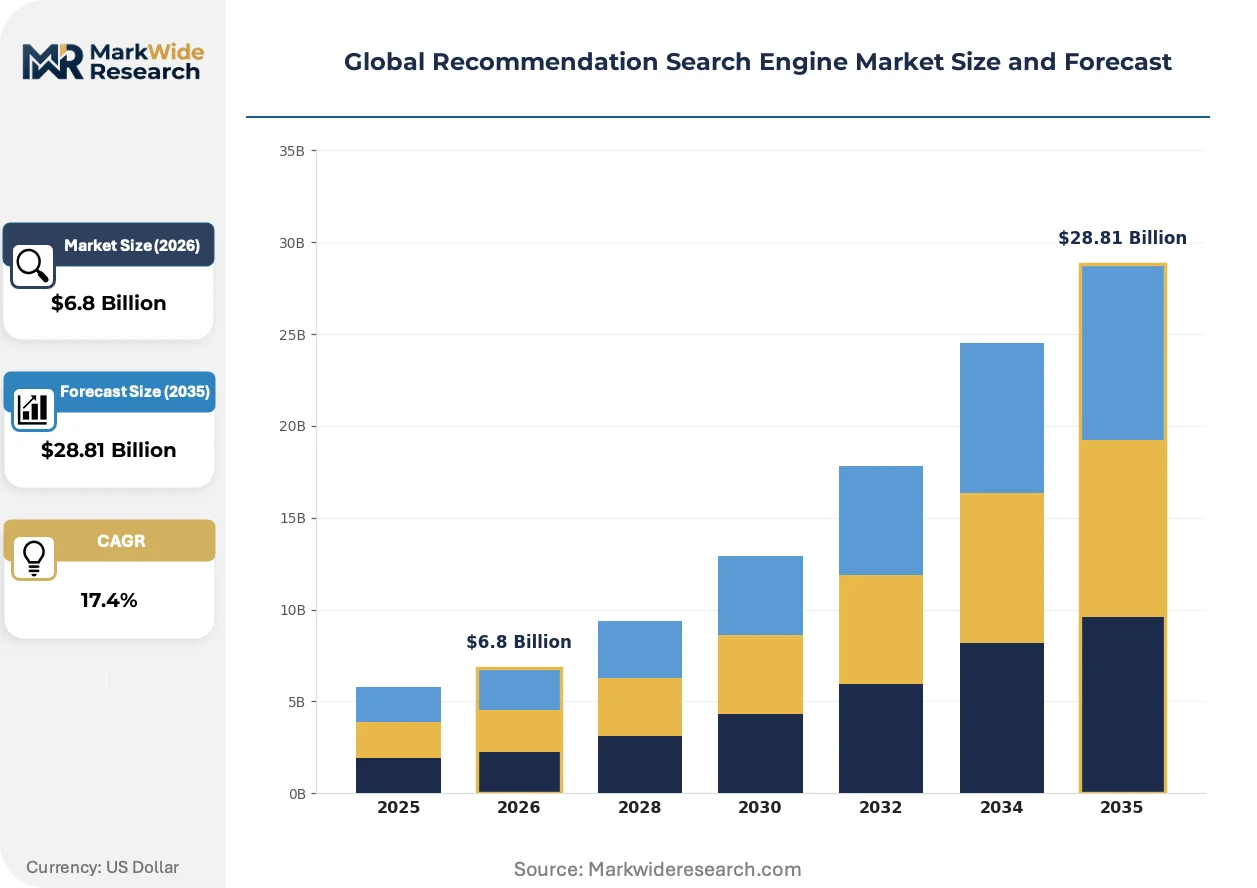
Market Dynamics
Latency compression below 50 milliseconds is fragmenting the Global Recommendation Search Engine Market into two tiers: hyperscale tensor inference stacks and lightweight edge embeddings. This bifurcation forces vendors to choose between GPU-heavy cloud architectures and quantized models for physical retail sensors.
Growth Catalysts
- Live-stream commerce infrastructure:China's super-app ecosystems demand real-time personalization engines that process billion-user behavioral signals during broadcast shopping events. Platforms embed recommendation layers directly into checkout flows to lift basket size.
- EU AI Act transparency mandates:European algorithmic ranking disclosure requirements are accelerating investment in explainable embedding architectures. Vendors redesign black-box systems to satisfy audit trails without sacrificing inference speed.
- Edge computing hardware maturation:Dedicated neural processing units in retail sensors enable on-device preference prediction without round-trip latency to central data centers. Department chains deploy these for in-aisle dynamic pricing.
Market Restraints
- GPU training cost concentration:Deep learning model development requires sustained capital access to NVIDIA H100 clusters, creating a moat that excludes mid-tier vendors from the premium margin pool.
- GDPR consent chain complexity:European behavioral signal processing requires granular user permission architectures that increase engineering overhead and degrade real-time personalization quality.
- Tensor processing unit supply bottlenecks:Google's captive TPU fabrication capacity limits external access to latency-optimized inference hardware, constraining competitive parity in query ranking.
Strategic Opportunities
- India's PLI scheme for AI infrastructure:Production-linked incentives for data center localization attract hyperscalers to build sovereign recommendation stacks serving domestic e-commerce platforms.
- Multimodal embedding convergence:Fusing visual, textual, and behavioral vectors into unified preference models opens new application surfaces in fashion and furniture verticals where image dominates intent.
- Saudi Arabia's smart city mandates:NEOM and similar projects require billion-scale personalization engines for urban service orchestration, creating greenfield procurement outside saturated Western markets.
Industry Challenges
- Vector database engineering scarcity:Specialized talent for high-dimensional similarity search at sub-100-millisecond latency commands premium compensation that strains vendor operating models.
- Legacy CRM integration friction:Enterprises with decades of purchase history in relational databases face expensive data pipeline reconstruction to feed modern embedding architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recommendation Search Engine Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Collaborative Filtering, Content-Based, Hybrid Systems, Knowledge-Based, Deep Learning Models Use Case: E-Commerce, Video Streaming, Social Networking, Online Education, Personalized Marketing End User Industry: Retail Chains, Media Providers, EdTech Firms, Telecommunications, Financial Institutions |
| Companies Covered | Yahoo, Yandex, Google, Netflix, Alibaba, Microsoft Bing, Baidu, Spotify, Amazon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recommendation Search Engine Market Shifts & Advancements
Transformer-based sequence models are compressing the cold-start problem for new inventory items. This shift is forcing collaborative filtering incumbents to rearchitect around attention mechanisms or retreat to commodity pricing tiers.
Retrieval-augmented generation is electrifying how recommendation systems blend real-time inventory availability with generative explanation layers. E-commerce platforms in South Korea deploy these hybrid stacks to produce contextual product justifications during live commerce broadcasts. The architecture compresses the gap between discovery and conversion by embedding inventory APIs directly into token generation pipelines.
The EU AI Act's algorithmic ranking disclosure requirements are mandating interpretable attention visualization for all consumer-facing preference systems. European marketplace operators must now expose which behavioral signals weighted specific recommendations, forcing engineering teams to sacrifice model complexity for auditability. Fashion and media streaming segments face the steepest compliance costs due to high-dimensional user embeddings.
Buyer procurement patterns are consolidating around bundled inference API contracts that tie vector search to cloud storage tiers. Enterprise technology teams in Germany and Japan now specify latency SLAs as primary selection criteria over model accuracy benchmarks. This shift favors hyperscale providers with proprietary fiber networks over specialized recommendation vendors dependent on third-party hosting.
Global Recommendation Search Engine Market Segmentation
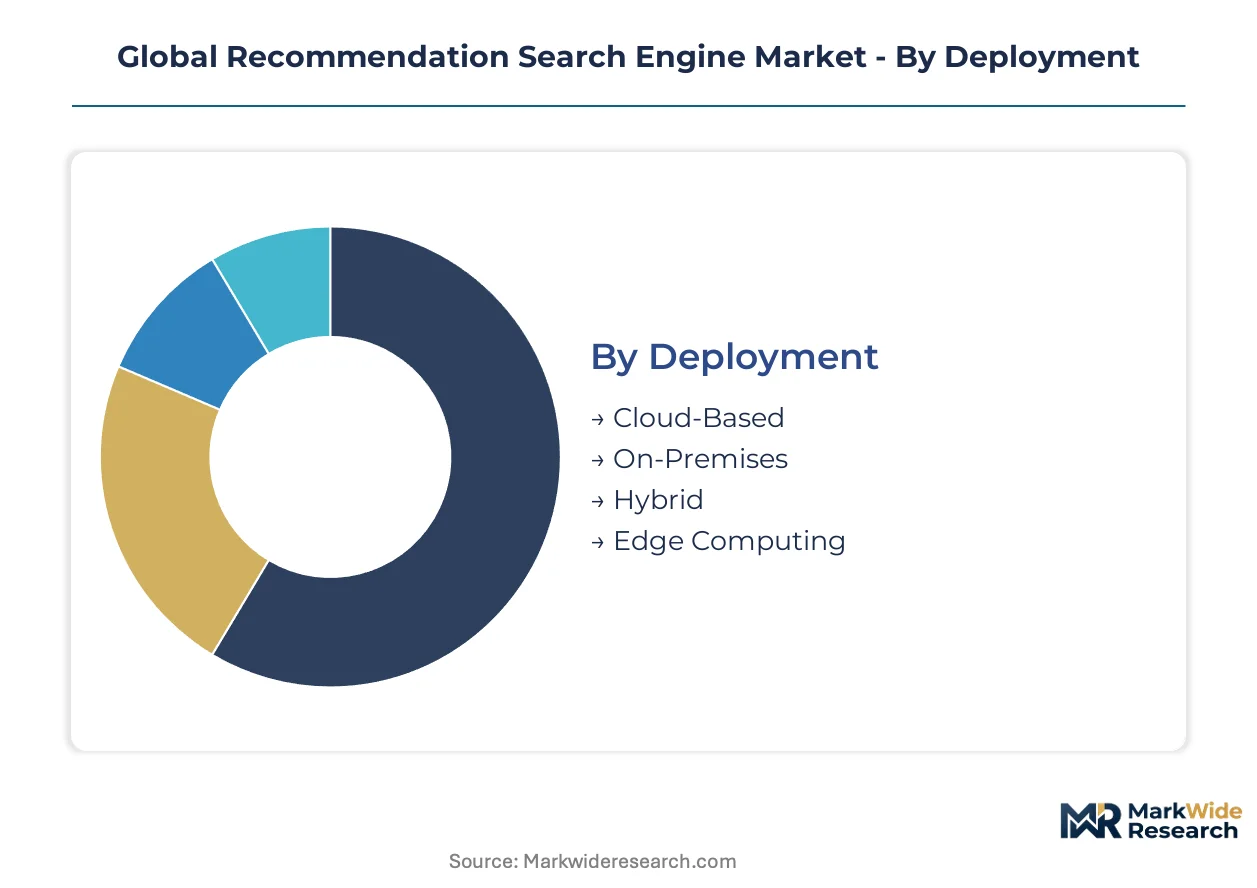
Recommendation search engine architectures fragment across deployment modes, algorithmic approaches, and vertical applications. Each segmentation axis carries distinct compliance burdens and latency requirements that reshape procurement patterns.
Deployment:
GDPR Article 32 security obligations and China's Data Security Law impose divergent certification pathways across hosting architectures. Sovereignty mandates increasingly dictate where inference occurs.
- Cloud-Based:Hyperscalers bundle vector search APIs with object storage tiers, capturing enterprise procurement through unified SLAs. German automotive platforms and South Korean live-commerce operators concentrate demand here, driven by burst scaling requirements during promotional events.
- Edge Computing:Dedicated neural processing units in retail sensors enable sub-50-millisecond preference prediction without central data center round-trips. French hypermarket chains and Japanese convenience store operators deploy these for in-aisle dynamic pricing, constrained by EU AI Act auditability requirements for on-device decision logic.
- On-Premises:Financial institutions in Switzerland and Saudi Arabia mandate air-gapped inference stacks for trading and wealth management applications.
- Hybrid:Split architectures route sensitive embeddings locally while offloading batch retraining to cloud tiers, common among Canadian healthcare networks.
Cloud-Based deployments sit at the top of the volume ranking, with Edge Computing climbing the fastest.
Solution Type:
Algorithmic complexity directly maps to GPU training cost tiers and regulatory explainability exposure.
- Deep Learning Models:Transformer-based sequence architectures compress cold-start latency for new inventory through attention mechanisms. Chinese super-app ecosystems and US streaming platforms drive demand, though EU AI Act disclosure mandates force attention visualization layers that degrade inference speed.
- Hybrid Systems:Fusing collaborative signals with content embeddings balances accuracy against auditability. German marketplace operators and Brazilian fintech firms prioritize these for GDPR-compliant recommendation trails.
- Collaborative Filtering:Legacy matrix factorization dominates price-sensitive tier, prevalent in Indian e-commerce infrastructure.
- Content-Based:Encoding pipelines for new titles reduce cold-start friction in media streaming.
- Knowledge-Based:Ontology-driven systems persist in pharmaceutical and legal research applications requiring deterministic reasoning.
Deep Learning Models command the dominant margin pool, while Hybrid Systems gain share fastest among compliance-constrained European procurement.
Use Case:
Application surface determines real-time inference requirements and integration depth with transaction systems.
- E-Commerce:Checkout-embedded recommendation layers lift basket size through real-time complementary item scoring. Chinese live-stream commerce platforms and Indonesian marketplace operators drive volume, constrained by SAMR anti-monopoly provisions on data usage.
- Video Streaming:Content-based encoding pipelines reduce subscriber churn through personalized artwork and trailer selection. Netflix and Disney+ anchor demand, with India's JioCinema expanding fastest.
- Social Networking:Feed ranking algorithms face FCC scrutiny in the US and Ofcom oversight in the UK.
- Online Education:Adaptive learning paths require low-latency skill-gap assessment, concentrated in South Korean EdTech.
- Personalized Marketing:Real-time bid optimization for programmatic advertising.
E-Commerce leads absolute deployment volume, with Video Streaming expanding most quickly as subscription saturation forces retention investment.
End User Industry:
Sector-specific data governance frameworks reshape vendor selection criteria across verticals.
- Retail Chains:Department store operators in France and Japan deploy edge-embedded sensors for in-aisle personalization, navigating GDPR and APPI consent architectures.
- Media Providers:Streaming platforms and broadcasters face divergent algorithmic amplification regulations—FCC monitoring in the US, EU Digital Services Act transparency mandates.
- Financial Institutions:Wealth management and insurance applications require explainable credit and product recommendations under SEC and FCA scrutiny.
- EdTech Firms:Adaptive learning platforms process student behavioral data under FERPA and GDPR-Edu constraints.
- Telecommunications:Content recommendation bundles for mobile subscribers.
Retail Chains anchor current procurement volume, with Financial Institutions climbing fastest as open-banking data access expands recommendation signal richness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vector database engineers cluster in Shenzhen, Seattle, and Bangalore, anchoring the geographic distribution of recommendation search engine development. These talent pools concentrate where hyperscaler headquarters intersect with top-tier computer science programs. Regulatory divergence across jurisdictions now shapes where inference stacks localize.
United States
FCC scrutiny of algorithmic amplification in streaming platforms drives transparency investments by media recommendation providers. SEC disclosure requirements for AI-driven financial product recommendations force explainability layers into wealth management stacks. Seattle and San Francisco Bay Area clusters dominate cloud-based vector search development for e-commerce and entertainment verticals.
China
SAMR anti-monopoly enforcement constrains how dominant platforms leverage purchase history density across super-app ecosystems. Live-stream commerce infrastructure demands sub-50-millisecond inference during billion-user broadcast shopping events. Hangzhou and Shenzhen anchor development of checkout-embedded recommendation layers for marketplace operators.
Germany
GDPR Article 32 security obligations and EU AI Act transparency mandates reshape procurement specifications for automotive and retail recommendation systems. German marketplace operators prioritize hybrid architectures that balance accuracy against audit trail requirements. Munich and Berlin clusters focus on explainable embedding systems for compliance-constrained European deployment.
South Korea
MFDS regulatory frameworks for AI-driven healthcare recommendations intersect with EdTech demand for adaptive learning path optimization. Retrieval-augmented generation stacks blend real-time inventory APIs with generative explanation layers for live commerce broadcasts. Seoul Capital Area vendors specialize in multimodal embedding convergence for fashion and beauty verticals.
Saudi Arabia
NEOM smart city mandates create greenfield demand for billion-scale personalization engines in urban service orchestration. SFDA requirements for pharmaceutical recommendation systems add compliance complexity to healthcare applications. Riyadh and Eastern Province development zones attract hyperscaler localization for sovereign AI infrastructure deployment.
Global Recommendation Search Engine Market Competitive Landscape
Top-tier vendors anchor hyperscale tensor inference stacks, while mid-tier specialists occupy quantized edge embedding niches. GPU training cost concentration creates a moat excluding smaller players from premium margin pools. Three archetypes dominate: cloud-native hyperscalers with captive hardware, vertical specialists in streaming or commerce, and edge-focused sensor integrators. Competitive moves center on strategic partnerships for TPU access and geographic expansion into sovereign AI jurisdictions.
Within the streaming-specialist archetype, Netflix and Spotify exemplify content-based encoding pipelines that reduce cold-start friction through attention mechanisms. Google and Amazon occupy positions spanning cloud infrastructure and direct consumer applications, representing the hyperscale integrated stack. These anchors demonstrate how proprietary data moats in purchase history or content consumption reinforce inference cost advantages.
| Leading Market Players |
|---|
| Yahoo |
| Yandex |
| Netflix |
| Alibaba |
| Microsoft Bing |
| Baidu |
| Spotify |
| Amazon |
| Others |
Supply & Pricing Matrix
EU AI Act transparency mandates gate qualified supply and premium-tier pricing access, as vendors must embed explainable attention visualization layers that degrade inference speed. Compliance-constrained European procurement commands 40-60% premiums over commodity collaborative filtering tiers, while non-compliant black-box architectures face exclusion from automotive and retail marketplace contracts in Germany and France.
Pricing Analysis
Bundled inference API contracts dominate enterprise procurement, unbundled vector search-only offerings retreat to mid-tier pricing. Three-tier pricing structure across premium deep-learning stacks, standard hybrid systems, and economy collaborative filtering separates latency-optimized GPU inference from quantized edge embeddings. Cost compression in the standard tier is intensifying because hyperscalers absorb training infrastructure into storage bundle economics. Price-sensitive Indian e-commerce infrastructure favors unbundled commodity filtering, while latency-sensitive Chinese live-stream commerce platforms absorb premium deep-learning premiums without negotiation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for cloud-based inference stacks, systems integrators manage edge sensor deployments in French and Japanese retail chains. Taiwan and South Korea anchor GPU and NPU fabrication capacity, the United States concentrates TPU design and cloud infrastructure, China dominates edge hardware assembly for retail sensor OEMs. NVIDIA H100 clusters, high-bandwidth memory modules, and proprietary fiber backhaul constitute critical input dependencies. Single-source vulnerability in Google's captive TPU fabrication capacity constrains competitive parity for external vendors seeking sub-50-millisecond latency optimization. Distribution runs through hyperscaler marketplace listings for cloud tiers and direct sensor OEM partnerships for edge computing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder justified by persistent latency compression demands that lock in recurring infrastructure refresh cycles across e-commerce and streaming verticals.
For Market Incumbents: Anchor defensive positioning through backward integration into proprietary TPU or NPU capacity, insulating inference cost structures from supply bottlenecks. Consolidate around explainable embedding architectures that preempt EU AI Act audit trail requirements before compliance deadlines harden. GPU training cost concentration itself constitutes the primary threat, as mid-tier vendors armed with quantized models erode standard-tier margins. For New Entrants and Emerging Players: Cloud hyperscaler partnership programs offer the most penetrable entry vector, bundling niche vector search capabilities into existing storage and compute marketplaces. Target India's PLI scheme for sovereign AI infrastructure localization, where domestic e-commerce platforms seek alternatives to foreign hyperscaler dependency. White-space exists in multimodal embedding convergence for fashion and furniture verticals where image-native intent signals remain underserved by text-dominant incumbents. For Investors and Strategic Acquirers: Roll-up economics work for edge-focused sensor integrators because retail chains demand turnkey in-aisle personalization without internal AI engineering capacity. Five-to-ten-year viability hinges on capturing recurring hardware refresh cycles as neural processing units commoditize. Monitor EU AI Act enforcement intensity as the inflection signal: accelerated penalty issuance would trigger distressed acquisition opportunities among non-compliant black-box vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable Embedding Architecture Investment | EU AI Act disclosure mandates force attention visualization layers that preserve audit trails without sacrificing inference speed. |
| Edge NPU Hardware Partnership | French and Japanese retail chains deploy sub-50-millisecond sensors for in-aisle dynamic pricing without cloud round-trips. |
| Multimodal Vector Fusion Development | South Korean fashion platforms blend visual, textual, and behavioral signals into unified preference models for image-dominant intent. |
| Sovereign Cloud Localization | India's PLI scheme attracts hyperscaler data center builds serving domestic e-commerce recommendation stacks. |
| Retrieval-Augmented Generation Integration | Live commerce operators embed real-time inventory APIs into token generation pipelines to compress discovery-to-conversion gaps. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with cloud infrastructure procurement officers, vector database engineering leads, streaming platform recommendation architects, and EU regulatory compliance specialists with secondary validation. SEC hyperscaler capex disclosures, EU AI Act implementation guidance documents, SAMR anti-monopoly enforcement notices, and hyperscaler marketplace pricing benchmarks anchored secondary source triangulation. Bottom-up deployment volume estimates across cloud, edge, and on-premises architectures reconciled against top-down market sizing from infrastructure spend patterns.
Segment-weighting approaches distributed value across deployment modes, algorithmic solution types, vertical use cases, and end-user industries. Deployment mode splits reflected hyperscaler revenue disclosures and edge hardware shipment data. Solution type weighting captured GPU training cost concentration effects on margin distribution. CAGRs derived from elasticity modeling of infrastructure spend against e-commerce transaction volume growth and streaming subscriber retention investment patterns. Latency requirement evolution and regulatory compliance cost trajectories informed cross-segment growth differential assumptions across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to TPU supply expansion timelines, EU AI Act enforcement intensity calibration, and live-stream commerce adoption outside China. Forecasts reflect documented assumptions around latency compression trajectories and sovereign AI infrastructure buildout schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Integrated Systems Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
Online Voting System Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Global Web Push Notification Software Market
Digital Solutions
Online Hyper-Local Services Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
United States ICT Market
Digital Solutions
Mexico Digital Twin Market
Digital Solutions
US Digital Market
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
Global Machine Translation (MT) Market
Digital Solutions
Customer-To-Customer (C2C) Community Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
Computer Aided Design (CAD) Market