
 Relational Database Management System Market | 2026-2036
Relational Database Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Relational Database Management System Market Analytics
Buyer concentration is shifting as mid-market enterprises fragment across cloud-native adopters while Fortune 500 firms consolidate procurement with fewer strategic vendors. Oracle Database leverages its installed base to sustain high switching costs in regulated industries. Amazon Web Services competes through managed service breadth, while PostgreSQL anchors open-source preference among cost-sensitive developers.
A relational database management system organizes data into structured tables with predefined schemas, enforcing ACID properties through SQL query engines and transaction logs to guarantee consistency across concurrent operations. Cloud-based deployment leads value contribution as enterprises migrate from capital-intensive on-premises estates to consumption models. Hybrid architectures represent the fastest-expanding segment as organizations balance latency-sensitive workloads against regulatory data-sovereignty constraints. Transactional solutions occupy the largest revenue pool, though analytical and data warehousing solutions command premium pricing for real-time intelligence workloads.
GDPR enforcement by European data protection authorities and the EU AI Act reshape cross-border data handling requirements, compelling vendors to certify regional residency controls. The US patchwork of state privacy laws, including CCPA and emerging frameworks, fragments compliance obligations for multi-tenant platform operators. Stakeholders must monitor divergent sovereignty mandates when architecting distribution strategies.

Market Dynamics
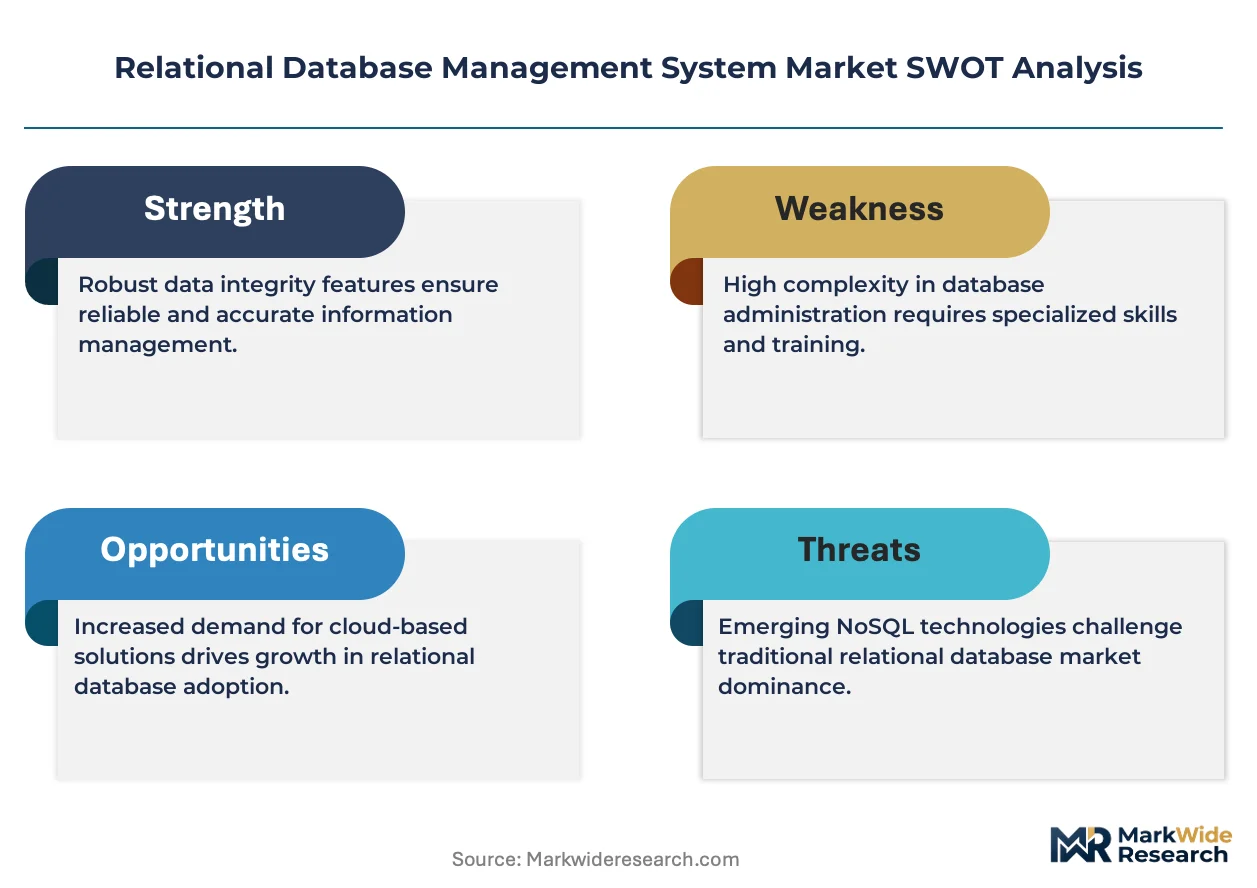
Cloud migration is fragmenting procurement authority as departmental developers bypass central IT to provision PostgreSQL and managed services directly, eroding traditional enterprise license consolidation.
Growth Catalysts
- GDPR Article 44 transfer mechanisms:European enterprises must maintain EU-resident data copies, forcing redundant database deployments across Frankfurt, Dublin, and Amsterdam regions.
- Real-time fraud detection in financial services:Transactional RDBMS with in-memory processing supports sub-100 millisecond authorization decisions for payment networks.
- India's data localization mandate:The Reserve Bank of India requires domestic storage of payment system information, compelling global cloud providers to establish Mumbai availability zones.
Market Restraints
- Skewed cloud infrastructure concentration:Three hyperscalers control over 80% of managed database capacity, creating single-provider vulnerability for multi-tenant architectures.
- Legacy schema rigidity:Predefined table structures struggle to accommodate unstructured IoT telemetry and social media feeds without expensive ETL pipelines.
- US state privacy fragmentation:CCPA, Virginia CDPA, and Colorado CPA impose conflicting technical controls on cross-state data flows, multiplying compliance engineering overhead.
Strategic Opportunities
- Germany's Gaia-X initiative:Sovereign cloud federation standards create opening for EU-controlled database services outside US jurisdictional reach.
- Edge-native SQLite deployments:Lightweight relational engines embedded in manufacturing equipment enable local analytics without round-trip latency to centralized warehouses.
- Convergence with vector databases:Hybrid architectures combining ACID transactional guarantees with AI embedding storage address retrieval-augmented generation workloads.
Industry Challenges
- Certified DBA scarcity:Oracle and Microsoft SQL Server specialists command premium compensation as universities shift curricula toward NoSQL and cloud-native stacks.
- Inter-cloud replication complexity:Maintaining transactional consistency across AWS RDS, Azure SQL, and Google Cloud SQL requires custom conflict resolution logic absent from native tooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Relational Database Management System Market |
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed End User: IT Services, BFSI, Retail, Education Technology: SQL, NoSQL, In-Memory, NewSQL Solution: Transactional, Analytical, Data Warehousing, Reporting |
| Companies Covered | MySQL, Google Cloud, PostgreSQL, SAP HANA Cloud, IBM Db2, Oracle Database, Amazon Web Services (AWS), MariaDB, Microsoft SQL Server, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Relational Database Management System Market Evolving Landscape
Serverless database architectures are dissolving the boundary between operational and analytical workloads, enabling automatic scaling without provisioned capacity planning.
Multi-model query engines are expanding into unified platforms that execute SQL, graph, and document operations against single storage backends. Fortune 500 data platform teams in the United States are piloting these systems to collapse separate Cassandra, Neo4j, and PostgreSQL estates. This consolidation is expanding into procurement rationalization as enterprises negotiate single-vendor contracts replacing three distinct support agreements.
EU AI Act risk classification rules are mandating audit trails for high-risk automated decision systems, forcing RDBMS vendors to implement immutable transaction logs with cryptographic verification. Financial services deployments across Germany and France must demonstrate query reproducibility for credit scoring algorithms. Database administrators are responding by enabling comprehensive slow-query logging and time-travel recovery features previously reserved for compliance-critical sectors.
Consumption-based pricing models are displacing perpetual licenses as the dominant procurement mechanism for mid-market enterprises. AWS Aurora and Azure SQL Database serverless tiers allow engineering teams to align database costs with actual query execution rather than peak-provisioned capacity. This shift is most visible among Series B and C software startups in India, where cash conservation priorities favor operational expenditure classification over capital-intensive on-premises deployments.
Relational Database Management System Market Segmentation
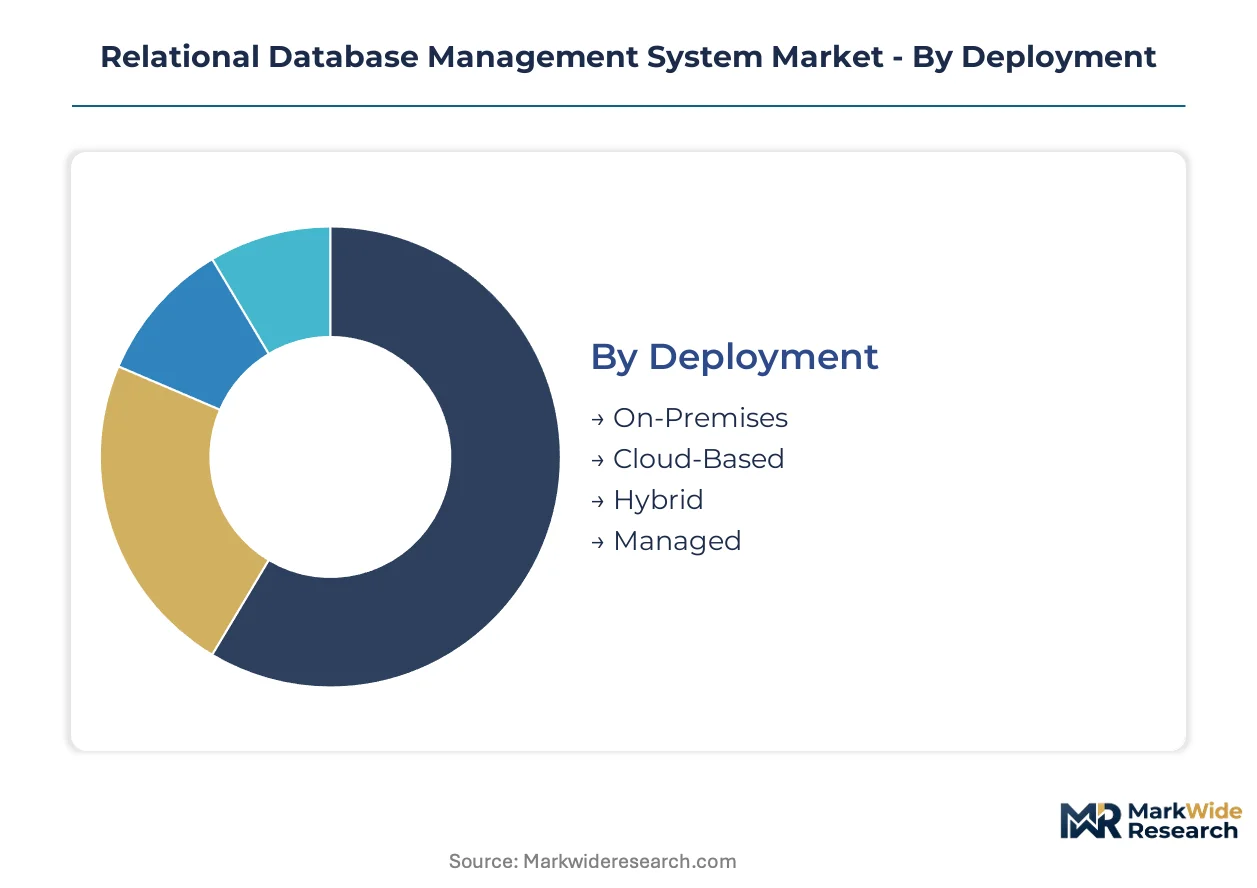
Procurement authority in the relational database management system market fragments across deployment models, end-use verticals, and solution architectures as enterprises balance sovereignty requirements against developer agility. Buyers prioritize operational expenditure classification, regulatory residency controls, and workload-specific performance guarantees when evaluating vendor proposals.
Deployment:
Capital allocation patterns determine deployment selection, with finance teams scrutinizing total cost of ownership across depreciation schedules versus metered consumption models.
- Cloud-Based:Consumption-metered infrastructure eliminates provisioned capacity planning, aligning database spend with actual query execution. Financial services firms in the United States and Germany favor this model for transactional platforms subject to elastic demand spikes.
- Hybrid:Split architectures place latency-sensitive operations on-premises while archiving compliance data to sovereign cloud regions. India's data localization mandate accelerates hybrid adoption as multinationals route payment information through Mumbai availability zones while retaining analytics workloads abroad.
- On-Premises:Capital-intensive estates persist in regulated industries requiring air-gapped environments for classified government contracts.
- Managed:Third-party operational support addresses certified DBA scarcity as enterprises outsource patch management and replication configuration.
Cloud-Based leads on scale; Hybrid leads on momentum.
End User:
Compliance engineering intensity varies sharply by vertical, with procurement teams weighting audit trail capabilities against schema flexibility requirements.
- BFSI:Sub-100 millisecond fraud authorization decisions demand in-memory transactional processing with immutable logging for EU AI Act algorithmic accountability. German and French credit scoring deployments require query reproducibility features.
- IT Services:Multi-tenant platform operators face fragmented US state privacy obligations, multiplying technical controls for cross-state data flows.
- Retail:Seasonal demand volatility favors serverless tiers that eliminate peak-provisioned capacity waste.
- Education:Cost-sensitive institutions anchor open-source preference for PostgreSQL deployments over proprietary licensing.
BFSI commands premium pricing; IT Services shows steepest expansion trajectory.
Technology:
Workload characteristics dictate query engine selection, with ACID requirements, unstructured data volumes, and latency tolerances driving divergent architectural commitments.
- SQL:Mature query optimization and declarative schema definitions sustain dominance in enterprise resource planning and financial ledger applications.
- In-Memory:Row-store architectures resident in RAM enable real-time analytics without ETL latency to disk-based warehouses.
- NewSQL:Distributed consistency models combine horizontal scalability with transactional guarantees for high-volume payment networks.
- NoSQL:Document and key-value stores accommodate IoT telemetry and social media feeds that resist rigid tabular structures.
SQL anchors installed base revenue; NewSQL gains share fastest among cloud-native adopters.
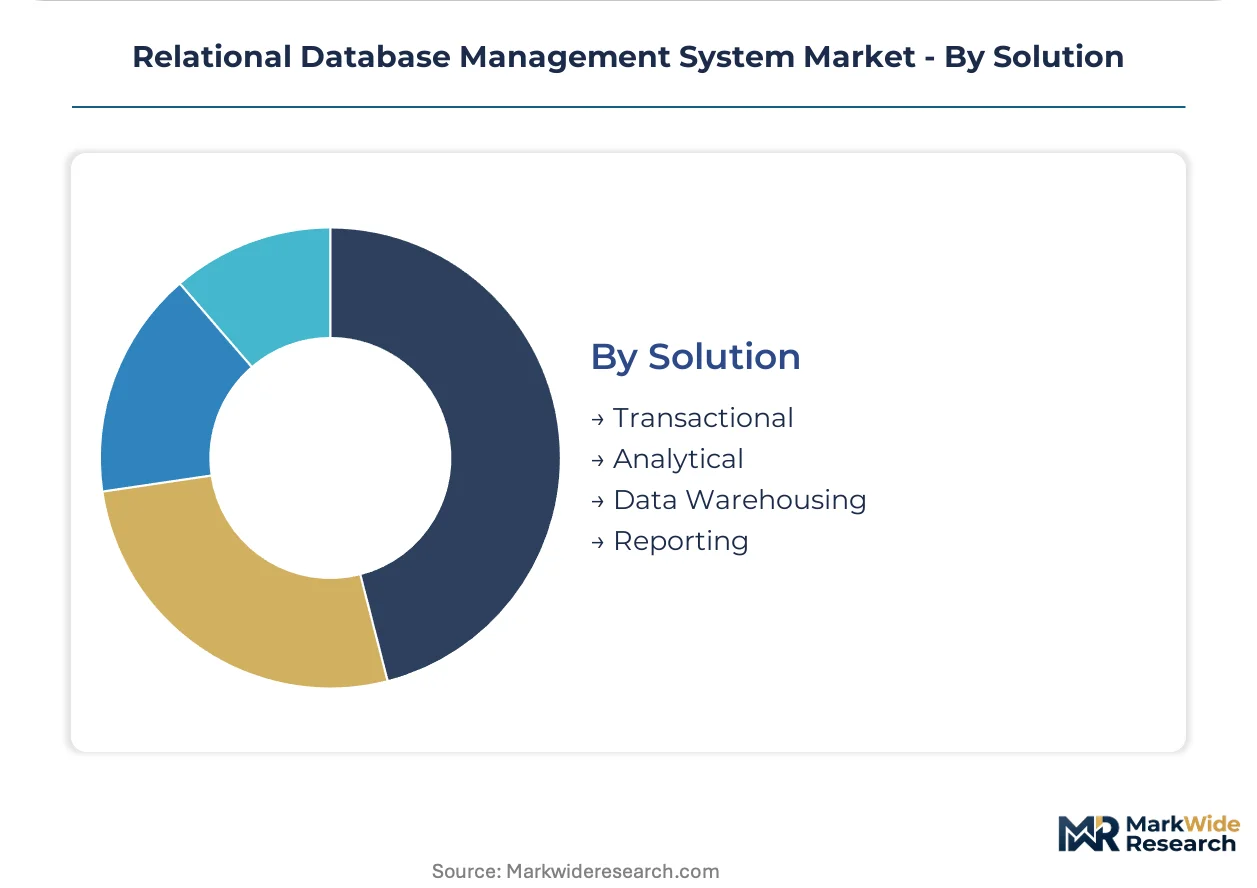
Solution:
Pricing power concentrates in analytical and data warehousing segments where real-time intelligence workloads justify premium licensing tiers.
- Transactional:OLTP engines enforcing ACID properties across concurrent operations occupy the largest revenue pool, anchoring procurement consolidation among Fortune 500 firms.
- Data Warehousing:Columnar storage and massively parallel processing command premium pricing for business intelligence workloads requiring petabyte-scale aggregation.
- Analytical:Hybrid transaction/analytical processing blurs operational and reporting boundaries through automatic scaling architectures.
- Reporting:Standardized dashboard and compliance documentation outputs represent baseline procurement with limited differentiation.
Transactional leads on scale; Data Warehousing leads on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services modernization in the United States outpaces German infrastructure spending, while India's data localization mandate forces faster cloud region buildouts than either market.
United States
Fortune 500 consolidation drives demand for managed transactional platforms with consumption-based pricing. CCPA and emerging state privacy laws fragment compliance engineering across Virginia, Colorado, and California jurisdictions. New York financial services clusters require sub-100 millisecond fraud detection capabilities for payment network authorization decisions.
Germany
EU AI Act algorithmic accountability rules mandate immutable query logging for credit scoring deployments across Frankfurt and Munich banking centers. GDPR Article 44 transfer mechanisms force redundant database deployments in Frankfurt, Dublin, and Amsterdam regions. Gaia-X sovereign cloud federation standards create procurement openings for EU-controlled database services outside US jurisdictional reach.
India
RBI data localization mandates require domestic storage of payment system information, compelling global cloud providers to establish Mumbai availability zones. Series B and C software startups favor serverless tiers for operational expenditure classification over capital-intensive on-premises estates. Bangalore and Hyderabad technology corridors anchor PostgreSQL preference among cost-sensitive developer communities.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for financial services firms maintaining both EU and UK data residency. London financial services clusters pilot hybrid transaction/analytical processing architectures for real-time intelligence workloads. Edinburgh and Manchester enterprise hubs fragment procurement authority as departmental developers provision managed services directly.
France
CNIL enforcement actions tighten technical control requirements for automated decision systems in credit and insurance underwriting. Paris banking consortia demand query reproducibility features for algorithmic accountability documentation. Lyon manufacturing clusters embed SQLite engines in production equipment for local analytics without centralized warehouse latency.
Relational Database Management System Market Competitive Landscape
United States hyperscalers anchor one tier; European and open-source specialists hold differentiated positions through sovereignty and cost positioning. Three strategic archetypes dominate: cloud-native managed service operators, legacy installed-base incumbents with high switching costs, and open-source community-backed engines. Competitive moves concentrate on hybrid architecture certifications and sovereign cloud partnerships rather than direct price confrontation.
Within the hyperscaler tier, Amazon Web Services and Google Cloud exemplify consumption-metered infrastructure plays, while Oracle Database occupies a position anchoring regulated industry consolidation through entrenched enterprise relationships. PostgreSQL and MariaDB represent the open-source archetype, sitting within developer-driven procurement patterns that bypass central IT authority. These groupings illustrate how geographic origin and licensing philosophy determine competitive positioning more than feature parity alone.
| Leading Market Players |
|---|
| MySQL |
| Google Cloud |
| PostgreSQL |
| SAP HANA Cloud |
| IBM Db2 |
| Oracle Database |
| Amazon Web Services (AWS) |
| MariaDB |
| Microsoft SQL Server |
| Others |
Value Network & Pricing Analysis
Hyperscaler-concentrated infrastructure ownership across Amazon Web Services, Microsoft Azure, and Google Cloud Platform shapes supply discipline and pricing power through consumption-metered lock-in. Sovereign cloud initiatives in Germany and India's data localization mandates are fragmenting procurement authority and forcing regional price differentiation.
Pricing Analysis
Capacity additions in Mumbai and Frankfurt availability zones are reshaping price floors for managed database services as regional competition intensifies. Three-tier pricing structure across premium enterprise, standard managed, and economy serverless tiers dominates procurement, with EU AI Act certification and sub-100 millisecond latency guarantees driving differentiation. Pricing pressure stems from open-source PostgreSQL alternatives eroding proprietary license margins. Series B software startups in India exhibit highest price sensitivity, while German financial services clusters accept premium tiers for algorithmic accountability compliance.
Supply Chain Analysis
India's RBI-mandated domestic-content requirements for payment data storage are reshaping hyperscaler sourcing patterns toward Mumbai-region infrastructure buildouts. Supply concentrates in the United States, Germany, and India as primary cloud region clusters, drawing from silicon wafer fabrication, undersea cable infrastructure, and certified database administrator labor pools. Single-source vulnerability runs through the three-hyperscaler concentration controlling managed database capacity. Distribution runs through direct enterprise sales for Fortune 500 consolidation and self-service developer portals for mid-market bypass of central IT procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The relational database management system market functions as a stable compounder anchored by irreversible enterprise data gravity and regulatory residency mandates that perpetuate recurring infrastructure spend.
For Market Incumbents: Lock in high-switching-cost accounts through EU AI Act-compliant immutable logging features and hybrid architecture certifications that entrench German financial services dependencies. Oracle Database and Microsoft SQL Server should deepen vertical integration into sovereign cloud partnerships, countering Amazon Web Services managed service breadth. Threat from PostgreSQL community editions bypassing central IT procurement demands pre-emptive enterprise license consolidation offers. For New Entrants and Emerging Players: Vector-database convergence technology offers a technology-first wedge into retrieval-augmented generation workloads underserved by legacy ACID engines. Target Gaia-X-aligned EU sovereign cloud deployments and edge-native SQLite manufacturing analytics as white-space opportunities. Go-to-market through channel partnerships with systems integrators serving GDPR-constrained European mid-market enterprises avoids direct hyperscaler confrontation. For Investors and Strategic Acquirers: Valuations sit cheapest among open-source support specialists with path to managed service revenue conversion. Long-term viability frames around 5-10 year regulatory fragmentation sustaining multi-cloud database sprawl. Acquisition target archetype: NewSQL distributed consistency engines with horizontal scalability credentials for payment network workloads. Signal to watch: sovereign cloud federation certification velocity as EU AI Act enforcement tightens.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Gaia-X certification opens German public sector procurement outside US jurisdictional reach. |
| Hybrid Architecture Certification | Split on-premises and cloud deployments satisfy India's RBI data localization mandates. |
| Vector Database Integration | ACID-guaranteed embedding storage addresses EU AI Act audit trail requirements for credit scoring. |
| Serverless Tier Expansion | Consumption-metered pricing captures Series B startup demand in Bangalore and Hyderabad corridors. |
| Immutable Logging Implementation | Cryptographic transaction verification satisfies CNIL enforcement for automated insurance underwriting. |
Research Methodology
Coverage spans the United States, Germany, India, the United Kingdom, and France, with primary inputs from each market combining interviews with database administrators, cloud platform engineers, financial services CTOs, and regulatory compliance officers alongside secondary validation. Primary research draws from hyperscaler capex disclosures, SEC filings from publicly traded software vendors, EU AI Act implementation guidance, and RBI circulars on data localization. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against aggregate enterprise IT spend estimates anchor value projections.
Rate-of-change decomposition separates cloud migration velocity from on-premises estate persistence, with segmentation dimensions spanning deployment model, end-use vertical, technology architecture, and solution type across the projection horizon. CAGRs derive from fitted adoption curves calibrated to regulatory mandate timelines and developer preference surveys. Industry-specific forecast inputs include payment network transaction volume growth for in-memory processing demand and sovereign cloud region buildout schedules for capacity planning.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hyperscaler market structure evolution and potential EU-US data transfer mechanism disruptions. Forecasts reflect assumptions around continued regulatory fragmentation sustaining multi-cloud deployments and certified DBA scarcity perpetuating managed service premiums. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Telecom IT Services Market
Software & Services
Family Law Software Market
Software & Services
Africa Sports Management Software Market
Software & Services
SMS Marketing Software Market
Software & Services
Global Knowledge Management Software Market
Software & Services
Expense Management Software Market
Software & Services
Global Voting Software Market
Software & Services
Application Server Market
Software & Services
Embroidery Design Software Market
Software & Services
Language Translation Software Market
Software & Services
Global Contract Management Software Market
Software & Services
Global Bug Tracking Software Market
Software & Services
Estate Management Software Market
Software & Services
Fire Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Application Development and Deployment Software Market