
 South America Data Center Networking Market | 2026-2036
South America Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
South America Data Center Networking Market Insights
Multi-source procurement among hyperscale operators is consolidating vendor relationships across the South American data center networking landscape. Cisco Systems leverages its extensive partner ecosystem to sustain hardware deployment pipelines across Brazilian and Chilean facilities. Arista Networks Inc competes aggressively on cloud-optimized switching architectures, while Juniper Networks Inc anchors its position through automation-driven routing platforms that reduce operational overhead for telecom operators.
South America data center networking encompasses the interconnected switching, routing, and security infrastructure that enables compute and storage resource communication within and between facilities, typically operating at speeds from 10 Gbps to 400 Gbps with sub-microsecond latency requirements for high-frequency trading and AI workloads. Ethernet switching dominates capital allocation among cloud service providers building hyperscale campuses, while InfiniBand garners traction in AI training clusters where bandwidth aggregation exceeds standard Ethernet capabilities. Firewalls and load balancers command premium pricing in financial services deployments across São Paulo and Santiago, where regulatory mandates dictate traffic inspection and application availability standards.
Brazil's LGPD framework and Argentina's data protection authority impose strict cross-border transfer rules that localize networking hardware procurement and complicate multinational supply chains. ANATEL certification requirements in Brazil and Chile's SUBTEL equipment homologation processes create compliance thresholds that filter non-specialized vendors from public-sector tenders. Stakeholders must weigh sovereign infrastructure mandates against the operational complexity of maintaining fragmented procurement policies across Mercosur jurisdictions.
Market Dynamics
Hyperscale cloud operators are consolidating vendor relationships around multi-source procurement strategies, compressing supplier margins while demanding higher performance thresholds from networking hardware deployed across São Paulo and Santiago corridors.
Growth Catalysts
- LGPD Localization Mandates:Brazil's data protection framework requires sovereign data storage, forcing cloud providers to expand domestic networking infrastructure rather than rely on cross-border connectivity.
- AI Training Clusters:Financial services and research institutions in São Paulo are deploying high-bandwidth InfiniBand fabrics to support GPU-intensive workloads with sub-microsecond latency requirements.
- Telecom Operator Automation:Brazilian and Chilean carriers are replacing legacy routing stacks with programmable platforms to reduce operational overhead in multi-tenant data center environments.
Market Restraints
- ANATEL Certification Bottlenecks:Brazil's equipment homologation timelines extend hardware deployment cycles by four to six months, delaying revenue recognition for facility operators.
- Import Duty Volatility:Networking silicon and optical transceivers face unpredictable Mercosur tariff adjustments that distort capex planning for hyperscale campus expansions.
- Concentrated Supplier Base:Advanced switching ASICs depend on a narrow set of foundry relationships concentrated in East Asian manufacturing nodes, exposing procurement to geopolitical disruption.
Strategic Opportunities
- Argentina Data Center Buildouts:Buenos Aires remains underpenetrated relative to São Paulo, creating first-mover advantages for networking vendors establishing local distribution partnerships.
- Edge Computing Convergence:5G network slicing and containerized networking functions are merging at metropolitan edge sites, opening new deployment categories beyond core hyperscale facilities.
- SUBTEL Fast-Track Pathways:Chile's streamlined equipment approval process for greenfield data centers offers regulatory arbitrage for operators seeking faster time-to-market than Brazilian alternatives.
Industry Challenges
- Specialized Network Engineering Talent:São Paulo's hyperscale corridor faces acute shortages of engineers certified in 400 Gbps fabric design and intent-based networking automation.
- Legacy Integration Complexity:Financial services deployments in Santiago must bridge decades-old mainframe connectivity protocols with modern Ethernet fabrics, multiplying integration testing cycles.
- Multi-Jurisdiction Compliance:Operators spanning Brazil, Argentina, and Chile maintain fragmented procurement policies to satisfy divergent national certification regimes, inflating administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Data Center Networking Market |
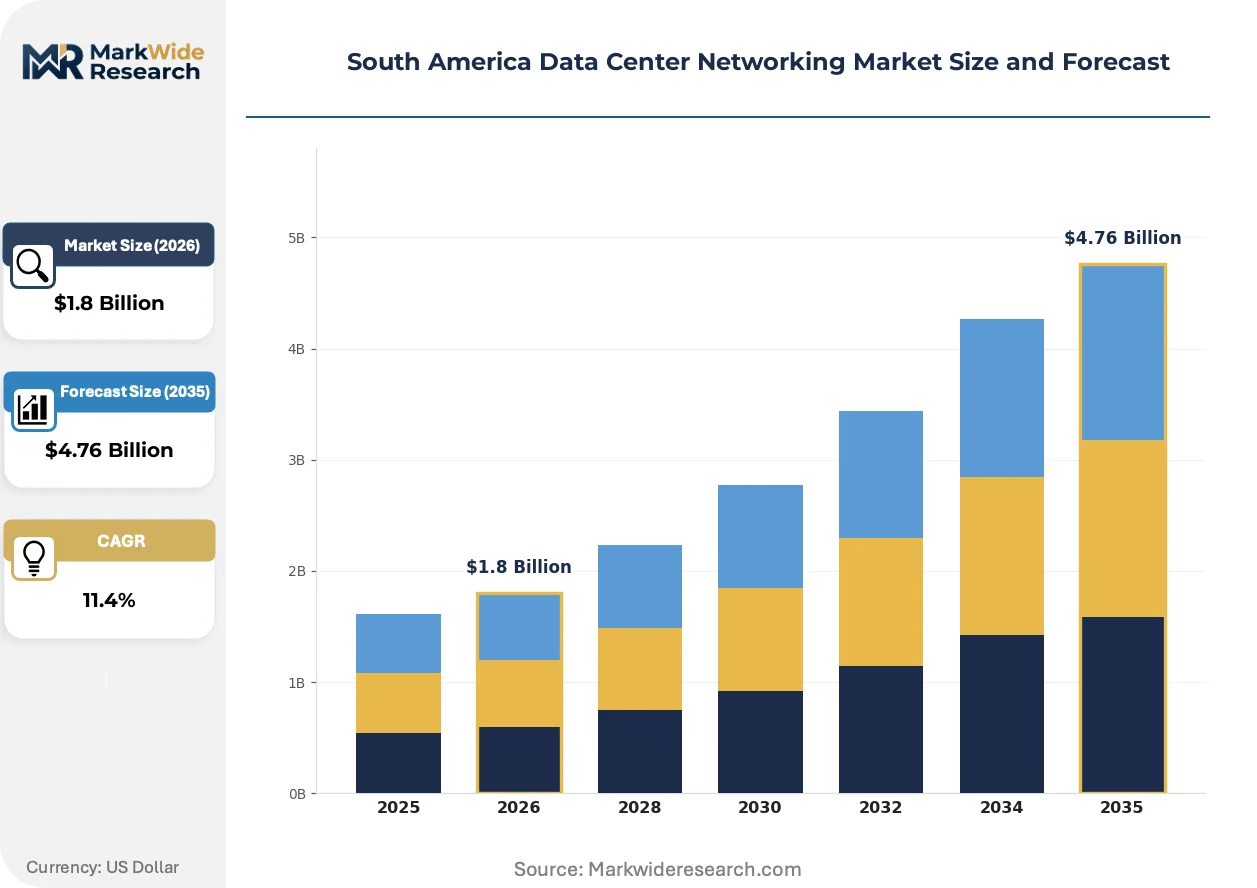
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Switches, Firewalls, Load Balancers Technology: Ethernet, InfiniBand, Fibre Channel, MPLS End User: Cloud Service Providers, Enterprises, Telecom Operators, Government Agencies Installation: On-premises, Colocation, Managed Services, Hybrid |
| Companies Covered | Cisco Systems, Juniper Networks Inc, Hewlett Packard Enterprise Development LP, Arista Networks Inc, Dell Technologies, Fortinet Inc, Radware Corporation, Extreme Networks Inc, NEC Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Data Center Networking Market Trends and Innovations
Silicon photonics and programmable switching architectures are compressing the performance-per-watt frontier, while sovereign data mandates reshape where networking capital deploys across the continent.
Co-packaged optics is absorbing the transceiver-to-switch interconnect, eliminating pluggable module overhead in high-density chassis designs. Cloud providers building São Paulo hyperscale campuses are adopting 51.2 Tbps switching platforms with embedded optical engines to reduce power consumption per gigabit by approximately one-third. This integration is absorbing traditional merchant transceiver supplier relationships into captive switch vendor ecosystems.
ANATEL's updated electromagnetic compatibility framework now mandates local testing laboratory involvement for all networking equipment deployed in Brazilian federal data centers. The regulation compresses vendor qualification timelines while elevating compliance costs for non-specialized hardware suppliers. Telecom operators and cloud providers are responding by pre-certifying platform generations through dedicated São Paulo testing facilities.
Hyperscale buyers are unbundling professional services from hardware procurement, contracting directly with systems integrators for deployment and commissioning while negotiating switch and router pricing on pure equipment terms. This disintermediation pressures traditional channel partners to reposition around managed services and operational support. The pattern is most visible in São Paulo, where cloud providers operate captive integration teams at scale.
South America Data Center Networking Market Segmentation
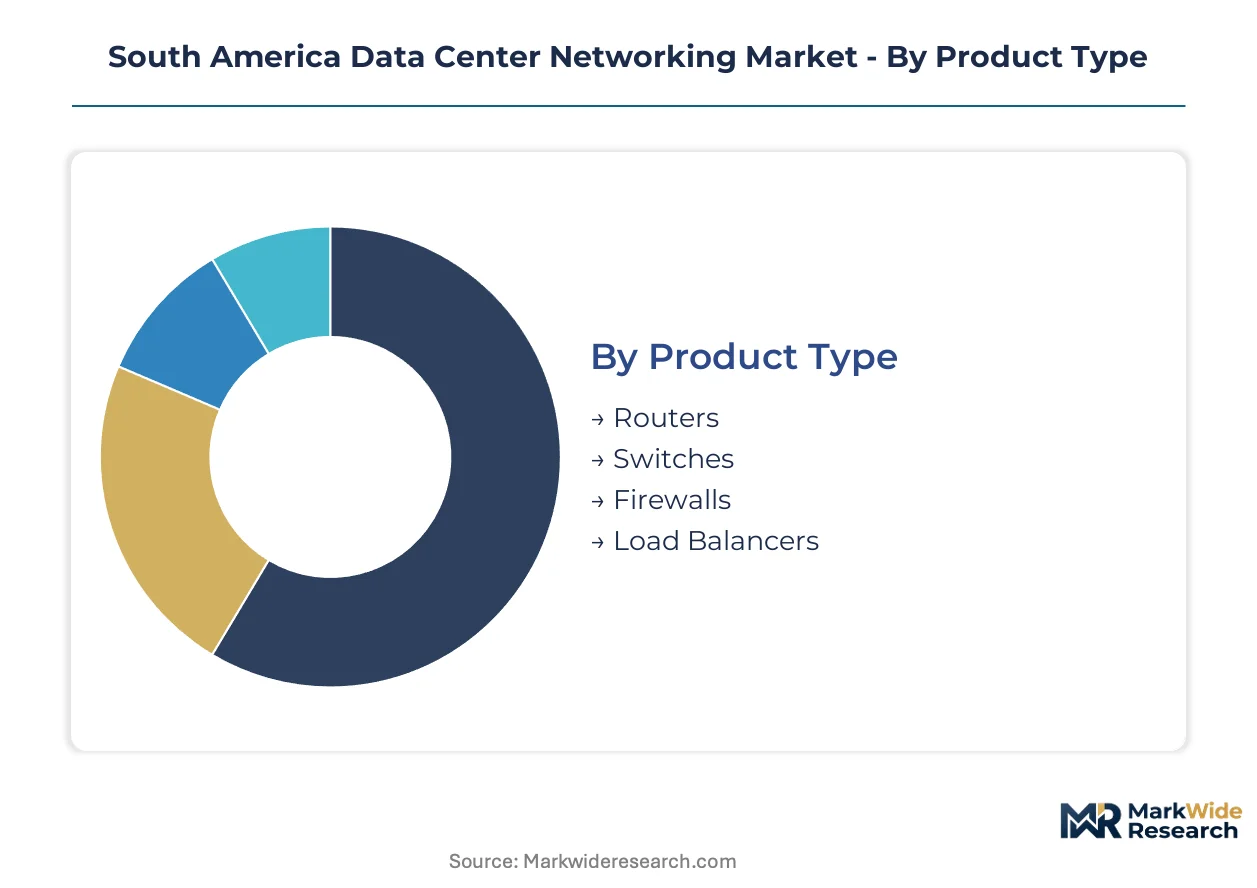
Segmentation reveals how capital flows diverge across networking hardware categories in South America. Equipment replacement cycles and technology refresh timelines vary sharply by deployment type and end-user sophistication.
Product Type:
Upgrade cycles compress fastest where bandwidth demands scale exponentially, stretching longest in legacy-anchored environments.
- Switches:Ethernet switching platforms dominate hyperscale procurement in São Paulo, with 400 Gbps spine-leaf architectures displacing 100 Gbps generations. Cloud providers in Brazil's primary corridor drive the steepest refresh cadence as GPU cluster densities climb.
- Routers:Programmable routing silicon with embedded automation engines commands premium placement among Chilean telecom operators modernizing multi-tenant facilities. ANATEL certification requirements extend deployment timelines, compressing vendor selection windows.
- Firewalls:Next-generation platforms with deep packet inspection anchor financial services deployments across Santiago and São Paulo, where regulatory mandates dictate traffic inspection standards.
- Load Balancers:Application delivery controllers support high-availability requirements in Argentine banking infrastructure, with hardware appliances preferred over virtualized alternatives for deterministic performance.
Volume placements concentrate in Switches; the faster expansion belongs to Routers as carrier automation accelerates.
Technology:
Cost tier stratification separates commodity interconnect from premium fabrics, with price-per-gigabit thresholds dictating adoption boundaries.
- Ethernet:Standard 25/100/400 Gbps switching constitutes the volume foundation across Brazilian hyperscale campuses, with merchant silicon driving cost efficiencies at scale. São Paulo's cloud corridor standardizes on this interconnect for general-purpose compute.
- InfiniBand:High-bandwidth fabrics with remote direct memory access support AI training clusters in Brazilian research institutions and financial services, where sub-microsecond latency justifies premium infrastructure spend.
- Fibre Channel:Storage-area networking persists in legacy enterprise data centers across Argentina, though Ethernet convergence pressures dedicated SAN investments.
- MPLS:Multi-protocol label switching anchors carrier backbones connecting metropolitan facilities, with segment routing displacing traditional label distribution in Chilean telecom networks.
Commercial maturity favors Ethernet deployments; InfiniBand gains share fastest where GPU-intensive workloads proliferate.
End User:
Customer type determines procurement sophistication, with captive engineering capabilities reshaping vendor engagement models.
- Cloud Service Providers:Hyperscale operators in São Paulo unbundle hardware from professional services, negotiating direct equipment pricing while retaining systems integration in-house. Multi-source procurement strategies compress supplier margins across switching categories.
- Telecom Operators:Brazilian and Chilean carriers prioritize automation-driven routing platforms to reduce operational overhead in multi-tenant colocation environments. Intent-based networking features command premium evaluation weight.
- Enterprises:Mid-market organizations across Argentina and Chile favor managed service overlays, deferring capital deployment through network-as-a-service consumption models.
- Government Agencies:Federal data center mandates in Brazil require ANATEL-certified equipment with local testing laboratory involvement, elevating compliance thresholds for public-sector tenders.
Procurement volume concentrates with Cloud Service Providers; Government Agencies expand most quickly as sovereign data mandates tighten.
Installation:
Deployment model selection tracks internal engineering depth, with hybrid architectures bridging capability gaps.
- Colocation:Multi-tenant facilities in São Paulo and Santiago absorb enterprise networking demand, with cross-connect and interconnection services bundling physical infrastructure. Brazilian operators lead regional capacity additions.
- On-premises:Captive data centers persist among financial institutions with legacy mainframe dependencies, particularly in Santiago where decades-old protocols complicate Ethernet migration.
- Managed Services:Outsourced network operations gain traction among Argentine enterprises lacking specialized engineering benches, with operational expenditure models displacing capital-intensive ownership.
- Hybrid:Split deployments spanning owned and colocated infrastructure dominate cloud provider architectures, with software-defined orchestration abstracting physical topology differences.
Facility investment concentrates in Colocation; Hybrid deployments climb the fastest as workload portability requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon photonics manufacturing concentrates in East Asian foundries, yet South American demand for data center networking hardware flows through Brazilian distribution channels that anchor regional procurement.
Brazil
LGPD localization mandates force hyperscale cloud providers to expand domestic networking infrastructure rather than rely on cross-border connectivity. ANATEL certification requirements extend hardware deployment cycles by four to six months, compressing vendor selection windows. São Paulo's hyperscale corridor clusters 400 Gbps spine-leaf deployments as GPU densities climb in cloud campuses.
Chile
Telecom operators modernize multi-tenant facilities with programmable routing platforms that reduce operational overhead. SUBTEL's streamlined equipment approval process for greenfield data centers offers regulatory arbitrage against Brazilian alternatives. Santiago anchors financial services deployments where next-generation firewalls with deep packet inspection satisfy regulatory traffic inspection mandates.
Argentina
Buenos Aires remains underpenetrated relative to São Paulo, creating first-mover advantages for networking vendors establishing local distribution partnerships. The country's data protection authority imposes strict cross-border transfer rules that complicate multinational supply chains. Argentine banking infrastructure favors hardware load balancers over virtualized alternatives for deterministic performance.
Colombia
Bogotá's emerging data center corridor attracts colocation investment as enterprises seek alternatives to saturated Brazilian markets. The national spectrum agency's equipment homologation processes create compliance thresholds that filter non-specialized vendors. Edge computing convergence at metropolitan sites opens deployment categories beyond core hyperscale facilities.
South America Data Center Networking Market Competitive Landscape
Global majors compete with regional champions across certification compliance and localization capabilities, producing a tiered structure where hardware volume concentrates with established incumbents while specialized challengers capture niche automation segments. Three archetypes dominate: full-stack infrastructure vendors with extensive partner ecosystems, cloud-optimized switching specialists, and automation-driven routing platform providers. Strategic moves center on multi-source procurement consolidation by hyperscale buyers and captive integration team buildouts that disintermediate traditional channel partners.
Among the full-stack infrastructure tier, Cisco Systems and Hewlett Packard Enterprise Development LP occupy positions defined by breadth of certification coverage across ANATEL and SUBTEL regimes. Arista Networks Inc exemplifies the cloud-optimized switching archetype, while Juniper Networks Inc anchors the automation-driven routing segment. These three companies represent the competitive anchors around which vendor selection consolidates in São Paulo and Santiago corridors.
| Leading Market Players |
|---|
| Cisco Systems |
| Juniper Networks Inc |
| Hewlett Packard Enterprise Development LP |
| Arista Networks Inc |
| Dell Technologies |
| Fortinet Inc |
| Radware Corporation |
| Extreme Networks Inc |
| NEC Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ANATEL-homologated equipment and uncertified alternatives manifests in both procurement premiums and supply chain fragmentation across Brazilian and Chilean corridors. Cloud providers absorb the compliance cost delta to secure federal data center eligibility, while non-certified vendors retreat to enterprise segments with lower regulatory thresholds.
Pricing Analysis
Warranty and professional services bundling separates incumbent full-stack vendors from cloud-optimized challengers pursuing pure equipment pricing. Hardware procurement in São Paulo operates on contract-based long-term offtake structures with volume-scale discounts and tiered service levels. Price differentiation hinges on ANATEL certification status and embedded automation capabilities, with certified platforms commanding substantial premiums. Pricing pressure stems from hyperscale buyers unbundling services and negotiating direct equipment terms, compressing margins most acutely among channel-dependent suppliers. Cloud service providers exhibit lowest price sensitivity given captive integration capabilities, while Argentine enterprises demonstrate highest sensitivity due to currency volatility and constrained capital access.
Supply Chain Analysis
ANATEL and SUBTEL qualification gating filters hardware flows through São Paulo testing facilities and Santiago distribution nodes, creating dual compliance chokepoints. Advanced switching ASICs draw from Taiwan, South Korea, and USA foundry concentrations, while optical transceivers and merchant silicon feed from Chinese and Malaysian manufacturing bases. Raw material dependencies span silicon wafers, rare-earth dopants for fiber amplification, and copper for high-speed interconnects. Single-source vulnerability concentrates in East Asian photonics manufacturing, exposing procurement to geopolitical disruption. Distribution runs through Brazilian master distributors with last-mile integration handled by systems integrators in São Paulo and Santiago corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America data center networking market functions as a cost-of-compliance arena where ANATEL certification timelines erect barrier-to-entry moats favoring pre-qualified incumbents with dedicated São Paulo testing infrastructure.
For Market Incumbents: Hedge against hyperscale service unbundling by building captive professional services capabilities around managed network operations and intent-based networking automation. Defensive consolidation should emphasize backward integration into optical component sourcing to reduce exposure to East Asian supply concentration, while channel control investments protect enterprise segment access against direct procurement trends. For New Entrants and Emerging Players: Launch via managed services partnerships targeting Argentine enterprises lacking specialized engineering benches, where network-as-a-service consumption models bypass capital-intensive hardware procurement barriers. Buenos Aires colocation facilities and Chilean edge computing sites represent the most penetrable white-space geographies, with regulatory arbitrage through SUBTEL fast-track pathways offering faster time-to-market than Brazilian alternatives. For Investors and Strategic Acquirers: Re-rating potential sits with automation-driven routing specialists given telecom operator modernization catalysts across Brazilian and Chilean carrier networks. Long-term viability favors vendors with ANATEL pre-certification infrastructure and localized testing laboratory relationships. The signal to watch as inflection indicator is hyperscale cloud provider captive integration team buildouts, which accelerate service disintermediation and compress traditional channel partner economics.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Pre-Certification Infrastructure | Dedicated São Paulo testing facilities compress vendor qualification timelines for federal data center eligibility. |
| Managed Network Services Buildout | Operational expenditure models capture Argentine enterprise demand lacking captive engineering capabilities. |
| Silicon Photonics Integration | Co-packaged optical engines reduce power consumption per gigabit in São Paulo hyperscale campuses. |
| Intent-Based Networking Platforms | Automation-driven routing reduces operational overhead for Chilean telecom operators in multi-tenant environments. |
| Edge Computing Convergence | 5G network slicing and containerized functions merge at metropolitan sites beyond core hyperscale facilities. |
Research Methodology
Document review covered ANATEL regulatory filings, SUBTEL equipment homologation records, hyperscaler capital expenditure disclosures, and telecom operator procurement databases, complemented by interviews with data center facility engineers, network architects at cloud service providers, ANATEL certification specialists, and systems integration leads. Secondary validation drew from customs trade data, SEC 10-K infrastructure spending disclosures, and carrier network modernization announcements. Bottom-up equipment shipment analysis and top-down infrastructure investment aggregation were triangulated to establish market sizing.
Segmented outputs across product type, technology, end user, and installation deployment model were generated through the projection horizon. CAGRs were derived from regression analysis against GPU cluster density trajectories and sovereign data localization enforcement patterns. Industry-specific forecast inputs included hyperscale campus construction pipelines, ANATEL certification queue depths, and 5G edge site deployment schedules.
Tariff volatility, regulatory timeline extensions, and foundry capacity allocation shifts are the dominant revision risks to modeled projections. Forecasts reflect assumptions around continued LGPD enforcement intensity and Mercosur trade policy stability. A model refresh is warranted upon material change in ANATEL electromagnetic compatibility framework updates or East Asian semiconductor export control regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Mobile Data Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Middle East Data Center Networking Market
Data Center and Networking
India Data Center Networking Market