
 Broadband Network Gateway Market | 2026-2036
Broadband Network Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Broadband Network Gateway Market Analysis
Leasing-based procurement models for carrier-grade gateway infrastructure is rewriting capital deployment patterns across the competitive landscape. Nokia Corporation leverages its end-to-end portfolio to sustain long-term contracts with tier-one operators seeking integrated optical and routing solutions. Cisco Systems anchors its position through software-defined access architectures that reduce operational complexity for service provider customers. Huawei Technologies competes aggressively on manufacturing scale, though geopolitical restrictions limit its addressable markets in North America and parts of Europe.
A broadband network gateway functions as a centralized aggregation and policy enforcement point between subscriber access networks and core IP infrastructure, typically handling throughput capacities from 10 Gbps to multi-terabit scales while executing subscriber management, QoS marking, and lawful intercept functions. The integrated gateway product type captures expanding margin pools as operators consolidate routing, switching, and security functions to reduce rack-space and power overhead. Fiber optic technology deployments outpace DSL-based gateway demand in most developed markets, though copper infrastructure persists in regions with lower fiber penetration. Service provider end users represent the dominant demand segment, with enterprise deployments gaining traction where private network slicing requirements intersect with managed service delivery models.
The FCC enforces network reliability and cybersecurity standards for broadband infrastructure receiving federal subsidy support, directly shaping gateway certification requirements for US market entry. ETSI and the Broadband Forum define interoperability frameworks that equipment vendors must satisfy for European operator qualification, while China's MIIT mandates domestic encryption and network access protocols through GB standards compliance. Stakeholders must monitor evolving spectrum of open-source disaggregation initiatives against proprietary integrated platform roadmaps when allocating R&D and partnership capital.
Market Dynamics
Carrier procurement of broadband network gateways is pivoting from perpetual license purchases toward subscription-based consumption models, compressing vendor cash conversion cycles while extending customer lifetime value horizons for equipment suppliers.
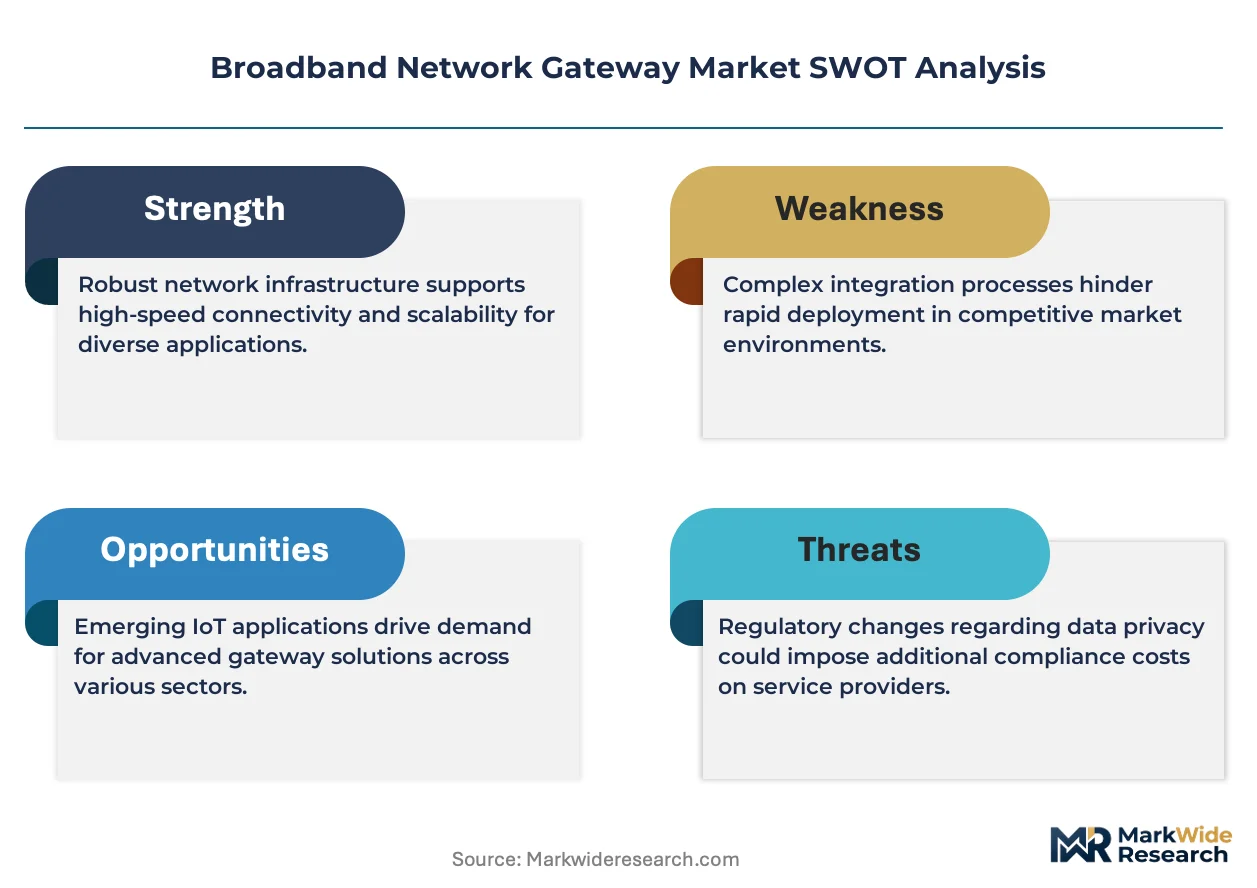
Growth Catalysts
- FTTH Infrastructure Mandates:Germany's Gigabit Strategy 2030 and the United States' Broadband Equity, Access, and Deployment Program are channeling public capital into fiber-to-the-home deployments, directly expanding addressable gateway volumes.
- Open RAN Disaggregation:O-RAN Alliance specifications are fragmenting hardware procurement across specialized vendors, enabling challenger suppliers to penetrate tier-two and tier-three operator accounts previously locked by integrated incumbents.
- Cloud-Native Orchestration:Kubernetes-based containerization of gateway control plane functions is collapsing deployment timelines for new service introductions, accelerating refresh cycles among digital-first service providers.
Market Restraints
- Semiconductor Supply Concentration:Advanced merchant silicon for terabit-scale forwarding engines concentrates at Taiwan Semiconductor Manufacturing and Samsung Foundry, exposing gateway vendors to geopolitical disruption risk in East Asian manufacturing corridors.
- Copper Infrastructure Stranding:Legacy DSL access multiplexers and associated gateway inventories face accelerated obsolescence as fiber penetration crosses 70 percent in developed metropolitan markets, compressing residual value recovery.
- Encryption Export Controls:United States Bureau of Industry and Security restrictions on cryptographic subsystem licensing create compliance friction for vendors serving multinational operator footprints spanning controlled and uncontrolled destination countries.
Strategic Opportunities
- Private 5G Convergence:Enterprise campus networks deploying standalone 5G cores are creating hybrid gateway demand that combines fixed broadband aggregation with mobile packet core interworking, opening margin pools outside traditional service provider accounts.
- India's BharatNet Expansion:The country's rural broadband infrastructure program is generating volume demand for cost-optimized gateway platforms capable of operating under constrained power and environmental conditions.
- EU Cybersecurity Certification:The European Union Agency for Cybersecurity's Common Criteria-based scheme for network equipment is creating a compliance moat that certified vendors can leverage to displace uncertified competitors in European Commission-funded procurement.
Industry Challenges
- Legacy OSS/BSS Integration:Established service providers maintain decades-old operations support systems that require costly adapter development to interface with modern REST API-driven gateway management planes, extending deployment timelines.
- Multi-Vendor Interoperability Certification:The Broadband Forum's TR-069 and USP protocol compliance testing consumes 9-14 month validation windows, delaying revenue recognition for product iterations.
- Specialized Talent Scarcity:Deep expertise in both optical transport physics and cloud-native software architecture concentrates among a limited pool of engineers, inflating compensation costs for gateway R&D teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broadband Network Gateway Market |
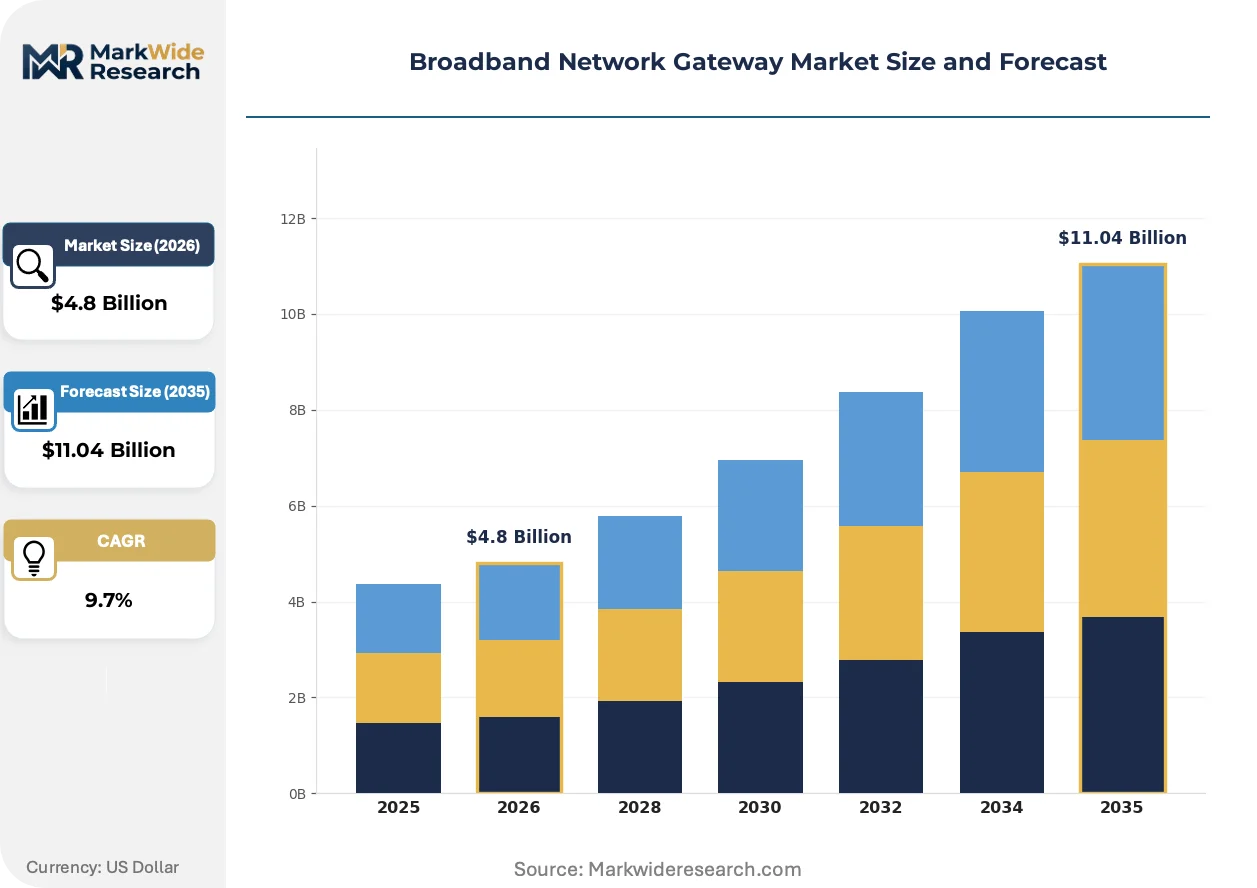
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Router, Switch, Firewall, Integrated Gateway End User: Residential, Small Business, Enterprise, Service Provider Technology: IPv4, IPv6, DSL, Fiber Optic Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service |
| Companies Covered | Ericsson, Nokia Corporation, Cisco Systems, ADTRAN, Casa Systems, Huawei Technologies, ZTE, Calix, Juniper Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broadband Network Gateway Market Emerging Trajectories
Gateway architecture is undergoing fundamental restructuring as disaggregated software stacks separate control intelligence from forwarding hardware, enabling operators to mix silicon generations and extend depreciation schedules.
Merchant silicon from Broadcom and Marvell is collapsing the performance-per-watt economics that previously justified custom ASIC development by tier-one vendors. Mid-tier operators in Spain and Italy are adopting these standardized forwarding platforms to achieve price parity with integrated incumbents. The resulting commoditization pressure is compressing gross margins on hardware while shifting value capture toward software licensing and professional services.
BEREC's 2022 guidelines on network neutrality enforcement are mandating granular traffic inspection capabilities that gateway vendors must embed at line rate. European operators in France and Germany are retrofitting existing deployments with deep packet inspection modules to avoid regulatory penalties. This compliance-driven hardware refresh is accelerating replacement cycles beyond normal technology obsolescence patterns.
Leasing arrangements for carrier-grade infrastructure are displacing traditional capital purchase models across North American cable operators. Charter Communications and Comcast are consolidating vendor relationships around multi-year service contracts that bundle hardware, software, and maintenance into per-subscriber pricing. This financial engineering is transferring balance sheet risk to equipment suppliers while locking in volume commitments through 2028-2030 contract windows.
Broadband Network Gateway Market Segmentation
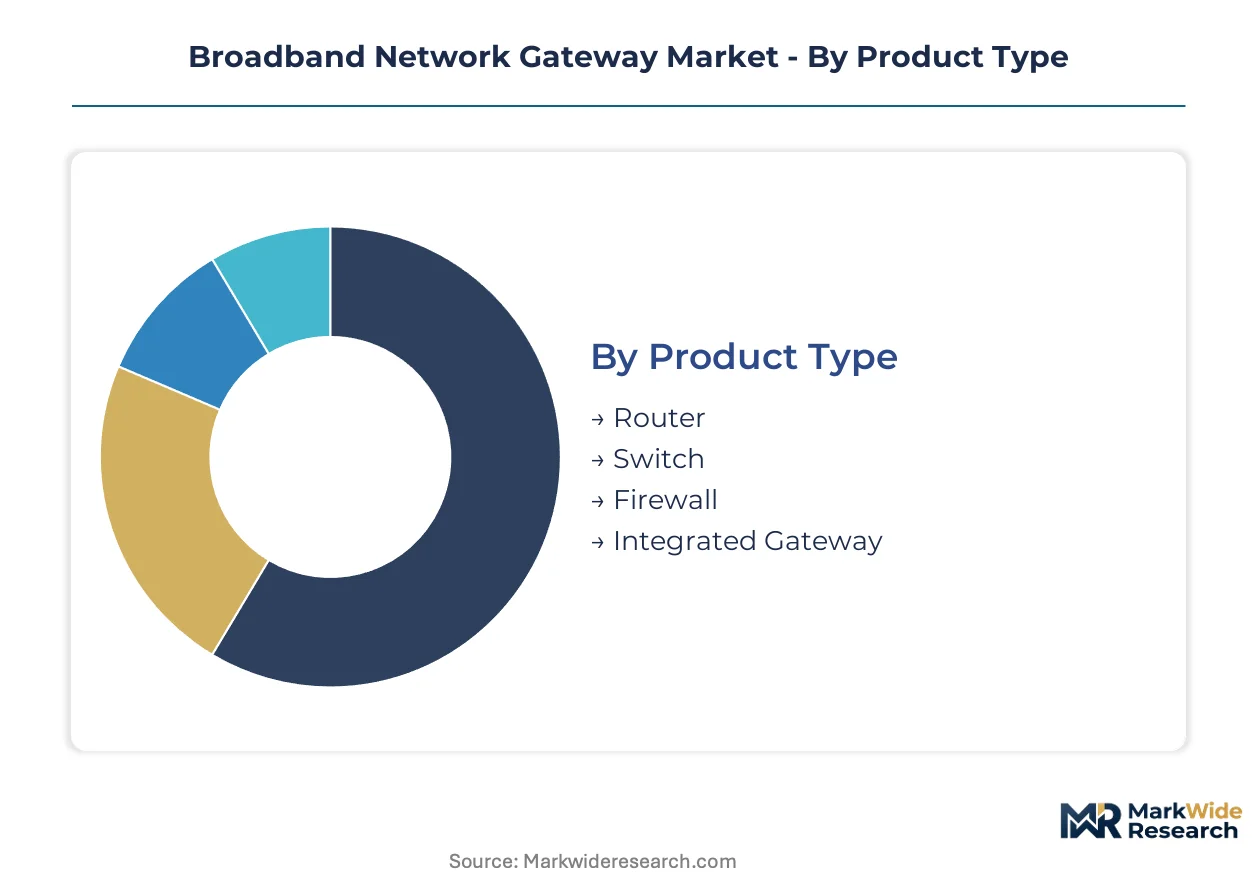
Gateway procurement patterns diverge sharply across customer scale and infrastructure vintage. Equipment refresh cycles range from 18-month cloud-native deployments to decade-long copper amortization schedules, creating heterogeneous demand profiles that vendors must segment precisely.
Product Type:
Integrated gateways turn over fastest as operators consolidate functions to reduce rack density, while standalone routers persist longest in brownfield core networks where forklift upgrades carry prohibitive service disruption risk.
- Integrated Gateway:Combines routing, switching, subscriber management, and security enforcement in single chassis designs that slash power draw and physical footprint. Demand concentrates among tier-one operators in Germany and the United States pursuing data center consolidation mandates, driven by BEREC power efficiency guidelines and FCC subsidy compliance requirements that penalize energy-inefficient infrastructure.
- Router:Purpose-built forwarding platforms handling multi-terabit scales with programmable pipeline architectures for policy enforcement. Deployment concentrates in China where MIIT-mandated domestic encryption standards require certified hardware platforms, constrained by semiconductor supply concentration at Taiwan Semiconductor Manufacturing and Samsung Foundry.
- Switch:Layer 2 aggregation platforms bridging access loops to gateway uplinks, prevalent in DSL-to-fiber transition architectures.
- Firewall:Dedicated security appliances handling stateful inspection and DDoS mitigation at network edge.
Integrated gateway dominates installed base among operators with aggressive consolidation roadmaps. Router is where expansion concentrates for standalone 5G core interworking and private network slicing applications.
End User:
Cost tier segmentation reveals stark margin differentiation: service provider volumes compress per-unit pricing while enterprise deployments sustain premium positioning through managed service bundling.
- Service Provider:Tier-one and tier-two telecommunications operators procuring carrier-grade platforms for mass-market broadband aggregation. Deployment concentrates in India under BharatNet rural infrastructure expansion and United States BEAD program subsidized rollouts, driven by government capital injection into fiber-to-the-home infrastructure.
- Enterprise:Large organizations deploying private gateway infrastructure for campus network slicing and secure WAN aggregation. Demand clusters in Germany manufacturing corridors and United States healthcare systems, constrained by HIPAA and GDPR data localization requirements that mandate on-premises policy enforcement.
- Residential:Consumer premises equipment bundled with retail broadband subscriptions.
- Small Business:Cost-optimized platforms with simplified management interfaces for sub-500 subscriber scales.
Service provider dominates installed base through volume concentration in national infrastructure programs. Enterprise is where expansion concentrates as private 5G convergence creates hybrid fixed-mobile gateway demand.
Technology:
Volume scale tilts toward fiber optic deployments as DSL infrastructure faces accelerated obsolescence, though IPv6 transition requirements sustain parallel protocol support investments.
- Fiber Optic:PON and active Ethernet termination platforms handling gigabit and multi-gigabit symmetrical throughput. Deployment concentrates in Germany Gigabit Strategy 2030 corridors and United States BEAD-funded rural builds, driven by public subsidy availability that requires BEREC and FCC certification compliance.
- IPv6:Next-generation protocol stacks enabling expanded address space and simplified header processing for IoT scale. Adoption concentrates in China where MIIT mandates domestic network access protocols through GB standards, constrained by legacy OSS/BSS integration friction in established operator environments.
- DSL:Copper-loop termination for VDSL2 and G.fast architectures in fiber-underpenetrated regions.
- IPv4:Legacy protocol support maintained through dual-stack and translation mechanisms.
Fiber optic dominates installed base through infrastructure replacement mandates. IPv6 is where expansion concentrates as address exhaustion and IoT scaling force protocol transition.
Deployment:
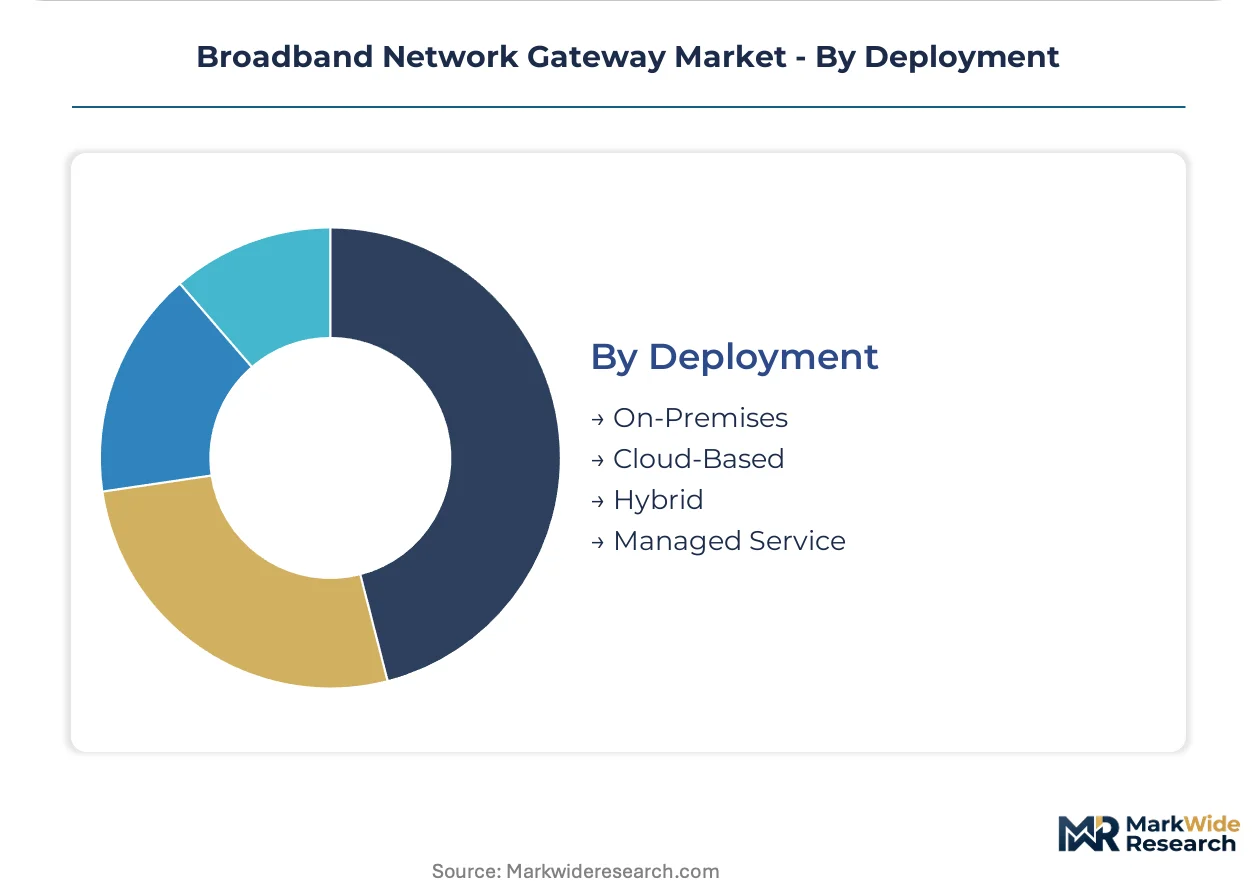
Customer type segmentation tracks operational maturity: digital-native operators adopt cloud-based orchestration while incumbent carriers retain on-premises control planes due to legacy system interdependencies.
- Cloud-Based:Kubernetes-containerized control planes with disaggregated forwarding hardware enabling elastic scaling and rapid service introduction. Adoption concentrates among United States cable operators and European altnet providers, driven by O-RAN Alliance specifications that fragment procurement across specialized vendors.
- Managed Service:Outsourced gateway operations with per-subscriber pricing transferring balance sheet risk to equipment suppliers. Deployment concentrates in North American markets where Charter Communications and Comcast have consolidated vendor relationships around multi-year service contracts.
- On-Premises:Traditional capital purchase models with customer-operated hardware and software stacks.
- Hybrid:Split architectures combining cloud-native orchestration with dedicated forwarding hardware.
Managed service dominates installed base through leasing arrangement consolidation among major operators. Cloud-based is where expansion concentrates as Kubernetes-based containerization collapses deployment timelines for new service introductions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gateway hardware trade flows tilt toward net-importing markets where fiber infrastructure subsidies exceed domestic manufacturing capacity. Export strength concentrates among integrated platform vendors serving multinational operator footprints.
United States
BEAD program disbursements are channeling federal capital into rural fiber builds across Appalachia and the Mountain West. FCC network reliability mandates require cybersecurity certification for subsidy-eligible equipment. Texas and California data center corridors are absorbing high-throughput gateway deployments for cable operator consolidation.
Germany
Gigabit Strategy 2030 targets drive municipal fiber partnerships in Bavaria and North Rhine-Westphalia. BEREC network neutrality guidelines mandate granular traffic inspection capabilities at line rate. Stuttgart manufacturing clusters are retrofitting private 5G campus networks with hybrid gateway infrastructure.
China
MIIT domestic encryption standards and GB protocol compliance shape procurement for state-owned operator tenders. Dual carbon goals accelerate power-efficient chassis replacements in Yangtze River Delta hubs. Shenzhen and Beijing house the primary design centers for merchant silicon integration.
India
BharatNet Phase III expansion generates volume demand for cost-optimized platforms in rural Maharashtra and Gujarat. TRAI infrastructure sharing rules enable multi-operator gateway colocation at tower sites. Bangalore software corridors are developing Kubernetes-native control plane adaptations for tropical operating conditions.
Japan
METI regional revitalization subsidies support fiber-to-the-home in aging prefectural populations. JIS interoperability standards govern equipment qualification for NTT East and West procurement. Osaka-Kobe industrial zones are deploying edge gateway clusters for manufacturing IoT aggregation.
Broadband Network Gateway Market Vendor Landscape
On the supply side, the industry is consolidating around three structural tiers: integrated platform vendors with end-to-end portfolios, disaggregated specialists leveraging merchant silicon, and geographically constrained challengers serving protected domestic markets. Strategic archetypes include the full-stack systems integrator, the cloud-native software pure-play, and the state-affiliated national champion. Dominant competitive moves encompass multi-year managed service contracting that transfers balance sheet risk to vendors, and open-source disaggregation initiatives that fragment procurement across specialized suppliers.
Within the integrated platform tier, Nokia Corporation and Cisco Systems exemplify divergent architectural bets—one anchoring long-term operator relationships through optical-routing convergence, the other reducing operational complexity via software-defined abstraction layers. Huawei Technologies occupies a position shaped by manufacturing scale advantages and geopolitically constrained market access. ADTRAN and Calix represent the mid-market specialist archetype focused on cost-optimized rural and small-market deployments.
| Leading Market Players |
|---|
| Ericsson |
| Nokia Corporation |
| Cisco Systems |
| ADTRAN |
| Casa Systems |
| Huawei Technologies |
| ZTE |
| Calix |
| Juniper Networks |
| Others |
Supply Flow & Price Mechanics
Overcapacity at Taiwan Semiconductor Manufacturing and Samsung Foundry is compressing merchant silicon pricing while concentrating supplier leverage, forcing gateway vendors to absorb margin erosion or cede volume to integrated platform rivals.
Pricing Analysis
Industrial OEM buyers anchor a subscription-dominant pricing structure where multi-year managed service contracts bundle hardware, software, and maintenance into per-subscriber rates. Three-tier pricing stratifies across premium certified platforms, standard interoperable systems, and economy rural deployments differentiated by throughput scale and BEREC compliance level. Cost compression in the economy tier is intensifying because BharatNet and BEAD program procurement mandates prioritize lowest-compliant-bid award criteria. Tier-one operators exhibit lowest price sensitivity due to switching costs embedded in legacy OSS/BSS integration, while rural infrastructure programs demonstrate highest sensitivity to upfront capital outlay.
Supply Chain Analysis
United States Bureau of Industry and Security encryption export controls limit cryptographic subsystem flows to controlled destination countries, fragmenting vendor manufacturing footprints. Merchant silicon supply concentrates in Taiwan, South Korea, and mainland China, drawing from advanced node dependencies at TSMC and Samsung Foundry. Optical transceivers, power management ICs, and specialized memory modules constitute critical input vulnerabilities. Single-source concentration at East Asian foundries exposes gateway vendors to geopolitical disruption risk. Distribution runs through tier-one operator direct procurement channels and systems integrator partnerships serving altnet and enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment moat where FCC cybersecurity certification and BEREC interoperability mandates create compliance barriers that compound over multi-year refresh cycles.
For Market Incumbents: Pre-empt disaggregated challenger penetration by accelerating cloud-native control plane roadmaps before O-RAN specifications fragment tier-two procurement. Secure long-term managed service contracts with North American cable operators to lock in volume commitments through 2028-2030 windows. Counter merchant silicon commoditization through vertical integration into optical transport physics expertise that concentrates among limited engineering pools. For New Entrants and Emerging Players: Establish a beachhead in India's BharatNet Phase III rural expansion where cost-optimized platforms under constrained power conditions favor specialized suppliers over integrated incumbents. Target European altnet providers in Spain and Italy adopting standardized forwarding platforms to achieve price parity. Pursue Kubernetes-native certification pathways that collapse deployment timelines for digital-first service providers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier specialists with proven MIIT or FCC certification portfolios that can be leveraged across multiple national infrastructure programs. Long-term viability hinges on recurring revenue exposure through subscription-based consumption models rather than transactional hardware sales. Monitor O-RAN Alliance specification maturity as inflection signal for disaggregation-driven vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Control Plane Migration | Kubernetes containerization collapses deployment timelines for Charter Communications and Comcast service introductions. |
| BEREC Compliance Certification Investment | Deep packet inspection module integration avoids regulatory penalties in France and Germany enforcement corridors. |
| Merchant Silicon Platform Adoption | Broadcom and Marvell standardization enables Spanish and Italian altnets to achieve incumbent price parity. |
| Managed Service Contract Consolidation | Per-subscriber pricing transfers balance sheet risk while locking volume through 2028-2030 procurement windows. |
| Rural Cost Optimization Engineering | Constrained power and tropical condition adaptations capture BharatNet Phase III volume in Maharashtra and Gujarat. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, ETSI interoperability certification registries, and operator procurement disclosure filings. Primary interviews engaged network engineering executives at tier-one operators, procurement leads at European altnet providers, regulatory affairs specialists navigating BIS encryption controls, and gateway product management directors at integrated platform vendors. Secondary validation drew from SEC 10-K infrastructure segment disclosures, TRAI infrastructure sharing rulemakings, and Broadband Forum protocol compliance testing records. Bottom-up demand modeling triangulated against top-down subsidy program allocation forecasts.
Forecast inputs encompass product type segmentation across integrated gateway, router, switch, and firewall categories; end-user splits between service provider, enterprise, residential, and small business; technology dimensions spanning fiber optic, IPv6, DSL, and IPv4; and deployment models including cloud-based, managed service, on-premises, and hybrid architectures. CAGRs derive from elasticity-calibrated infrastructure investment trajectories across the projection horizon. Industry-specific forecast inputs incorporate BEAD program disbursement schedules, Gigabit Strategy 2030 milestone tracking, and BharatNet Phase III rural coverage targets.
Sensitivities concentrate around semiconductor supply disruption at East Asian manufacturing corridors, O-RAN Alliance specification acceleration timelines, and encryption export control regime expansion. Forecasts reflect documented assumptions regarding subsidy program continuity and regulatory certification pathway stability. Material shifts in FCC network reliability mandate stringency or BEREC network neutrality enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Data Center Services Market
Data Center and Networking
Data Center Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Dark Fiber Network Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Enterprise Network Infrastructure Market
Data Center and Networking
Germany Data Center Networking Market