
 Global Virtual Private Network Market | 2026-2036
Global Virtual Private Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Private Network Market Foresight
The capital-intensity divergence between bare-metal server operators and cloud-reseller VPN providers is unwinding competitive stability. Cisco Systems, Inc. leverages its enterprise hardware installed base to bundle security appliances with VPN licensing. NordVPN anchors consumer subscription revenue through proprietary server infrastructure across privacy-focused jurisdictions. ProtonVPN differentiates via Swiss jurisdiction advantages and open-source protocol transparency.
A Virtual Private Network creates an encrypted tunnel over public internet infrastructure using protocols such as IPsec or SSL/TLS with AES-256 encryption standards to authenticate endpoints and encapsulate data packets. Its primary commercial purpose is to extend private network security boundaries to remote users, branch offices, and cloud resources without dedicated leased lines. Remote Access VPN captures the dominant share of enterprise deployments as permanent hybrid work policies institutionalize distributed workforce security requirements. Cloud-Based deployment is expanding fastest among mid-market adopters seeking to avoid capital expenditure on gateway hardware. MPLS VPN retains margin concentration in legacy financial and manufacturing networks where deterministic latency remains non-negotiable.
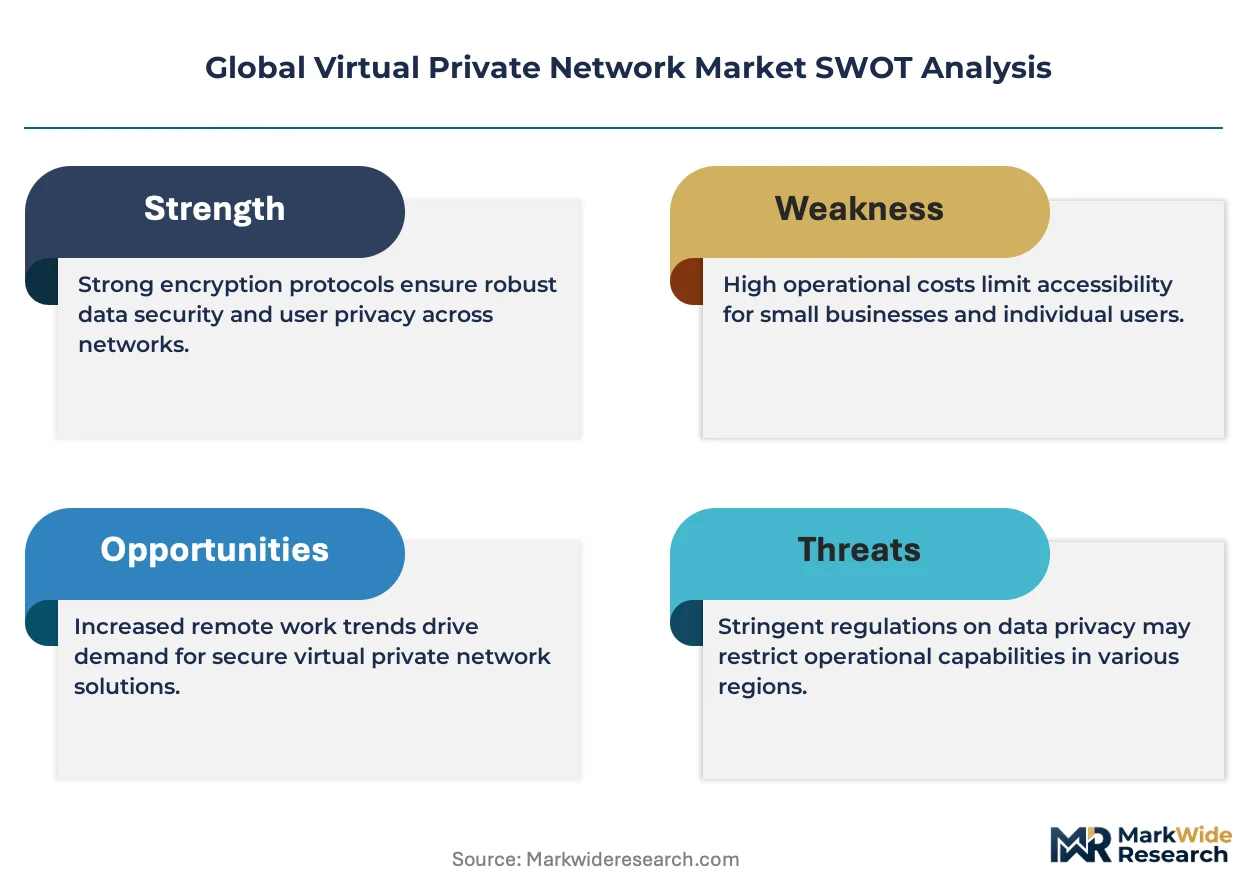
FCC broadband privacy rulings in the United States, GDPR cross-border transfer mechanisms in Europe, and China's GB/T cybersecurity standards collectively shape protocol choices, logging policies, and server location strategies for VPN providers. The EU AI Act's risk-classification framework is extending data governance obligations that reinforce enterprise demand for zero-trust network access overlays. Stakeholders must monitor regulatory fragmentation between data localization mandates and encryption backdoor proposals to determine architectural bets on centralized versus distributed infrastructure models.
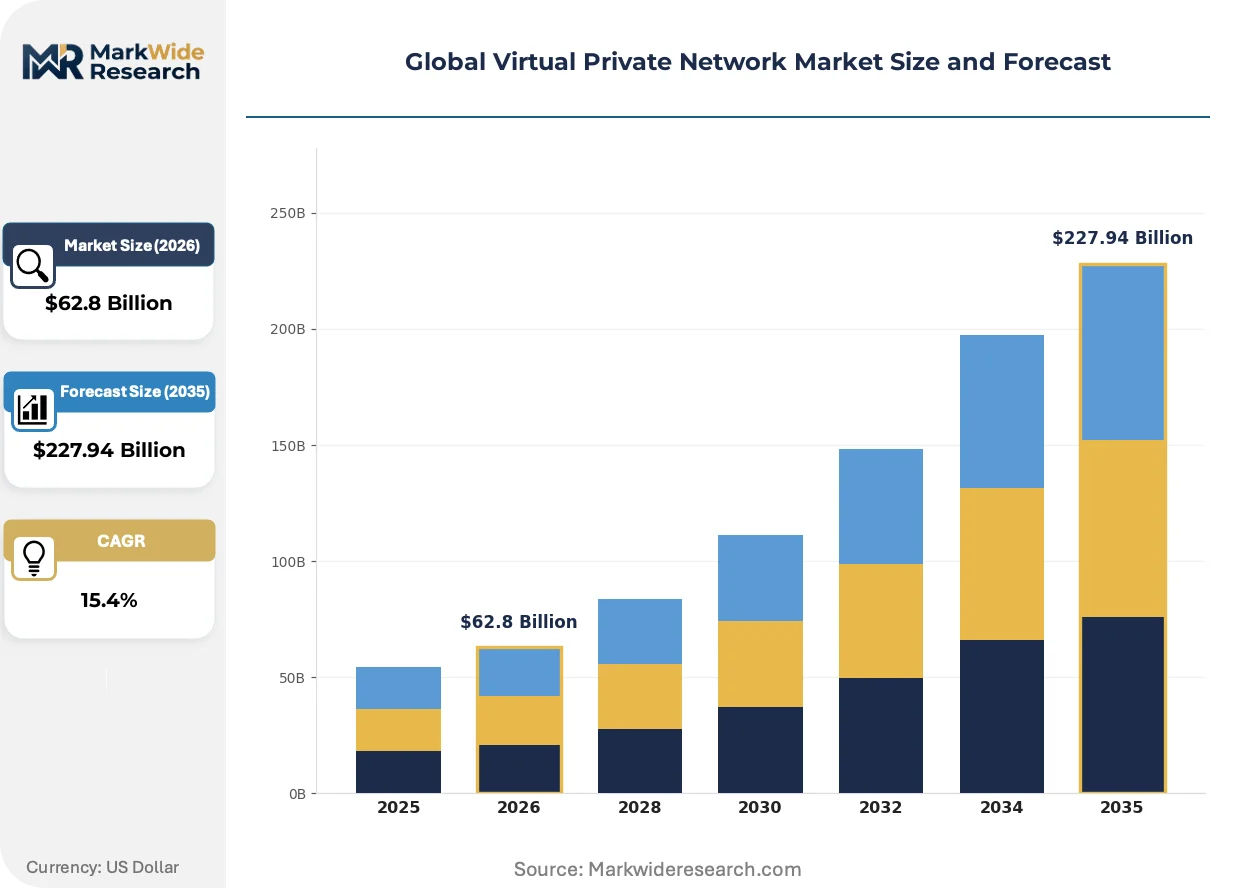
Market Dynamics
Zero-trust network architecture mandates from enterprise security teams are compressing traditional perimeter-based VPN deployments into identity-verified microsegmentation models.
Growth Catalysts
- GDPR cross-border transfer mechanisms:European enterprises face escalating pressure to encrypt data flows between member states and third countries, expanding managed VPN service contracts.
- Financial services hybrid workforce institutionalization:Banks and insurers maintain permanent remote-work policies requiring always-on encrypted access to core trading and claims systems.
- Cloud gateway hardware avoidance:Mid-market enterprises across the United States are abandoning capex-heavy MPLS termination equipment for subscription-based cloud VPN orchestration.
Market Restraints
- Encryption backdoor legislative proposals:Australia's Assistance and Access Act and similar frameworks in the United Kingdom create jurisdictional compliance conflicts for providers maintaining no-log policies.
- Server infrastructure concentration:Bare-metal hosting in privacy-focused jurisdictions—Switzerland, Iceland, Panama—limits geographic diversity and raises single-point-of-failure risk.
- Latency-performance tradeoffs in TLS 1.3:Handshake overhead degrades real-time application performance for manufacturing and energy sector remote monitoring use cases.
Strategic Opportunities
- India's Data Protection Board enforcement:Pending localization requirements for critical personal data create first-mover advantage for providers establishing Mumbai and Hyderabad points of presence.
- Post-quantum cryptography migration:NIST-standardized algorithms enable differentiation for providers offering hybrid classical-quantum key exchange before regulatory mandates crystallize.
- IoT device identity federation:Convergence of VPN tunnels with hardware security modules allows automotive and healthcare OEMs to secure over-the-air update channels.
Industry Challenges
- Zero-trust architecture skill scarcity:Enterprise IT departments lack personnel capable of integrating SDP overlays with legacy Active Directory certificate infrastructure.
- Cross-border data localization audits:Providers face escalating operational burden from Russia's data sovereignty law and Vietnam's cybersecurity decree requiring in-country logging capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Private Network Market |
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $227.94 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Remote Access VPN, Site-to-Site VPN, Intranet VPN, Extranet VPN Deployment: Cloud-Based, On-Premises, Hybrid, Hosted End User Industry: BFSI, IT & Telecom, Government, Manufacturing, Energy & Utilities Solution Type: Software-Defined Perimeter, IPsec, SSL, Clientless VPN, MPLS VPN |
| Companies Covered | NordVPN, ExpressVPN, Surfshark, CyberGhost, Private Internet Access, IPVanish, TunnelBear, ProtonVPN, Cisco Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Private Network Market Shifts & Advancements
Software-defined perimeter technology is bifurcating the enterprise VPN market between legacy tunnel-based vendors and identity-native challengers. This structural shift reconfigures procurement criteria, architectural roadmaps, and partnership ecosystems simultaneously.
WireGuard protocol adoption is fragmenting the IPsec/SSL duopoly that dominated enterprise VPN stacks for two decades. The lightweight codebase reduces attack surface and improves battery efficiency for mobile endpoints. Financial services firms in Singapore and Germany are piloting WireGuard for trader mobility, compressing incumbent vendor maintenance revenue as open-source implementations proliferate.
The EU AI Act's high-risk system classification is extending data governance obligations beyond traditional privacy frameworks. Article 10 requirements for training data integrity force enterprises to document data lineage across cloud boundaries. German automotive manufacturers and French healthcare AI developers are accelerating zero-trust overlay deployments to satisfy audit trail requirements for cross-border model training datasets.
Consumption-based licensing is displacing per-seat VPN subscriptions in mid-market procurement. Channel partners in the United States now bundle VPN capacity with Microsoft Azure and AWS marketplace commitments. This shift compresses direct vendor relationships and transfers pricing leverage to hyperscaler field sales organizations managing consolidated cloud security budgets.
Global Virtual Private Network Market Segmentation
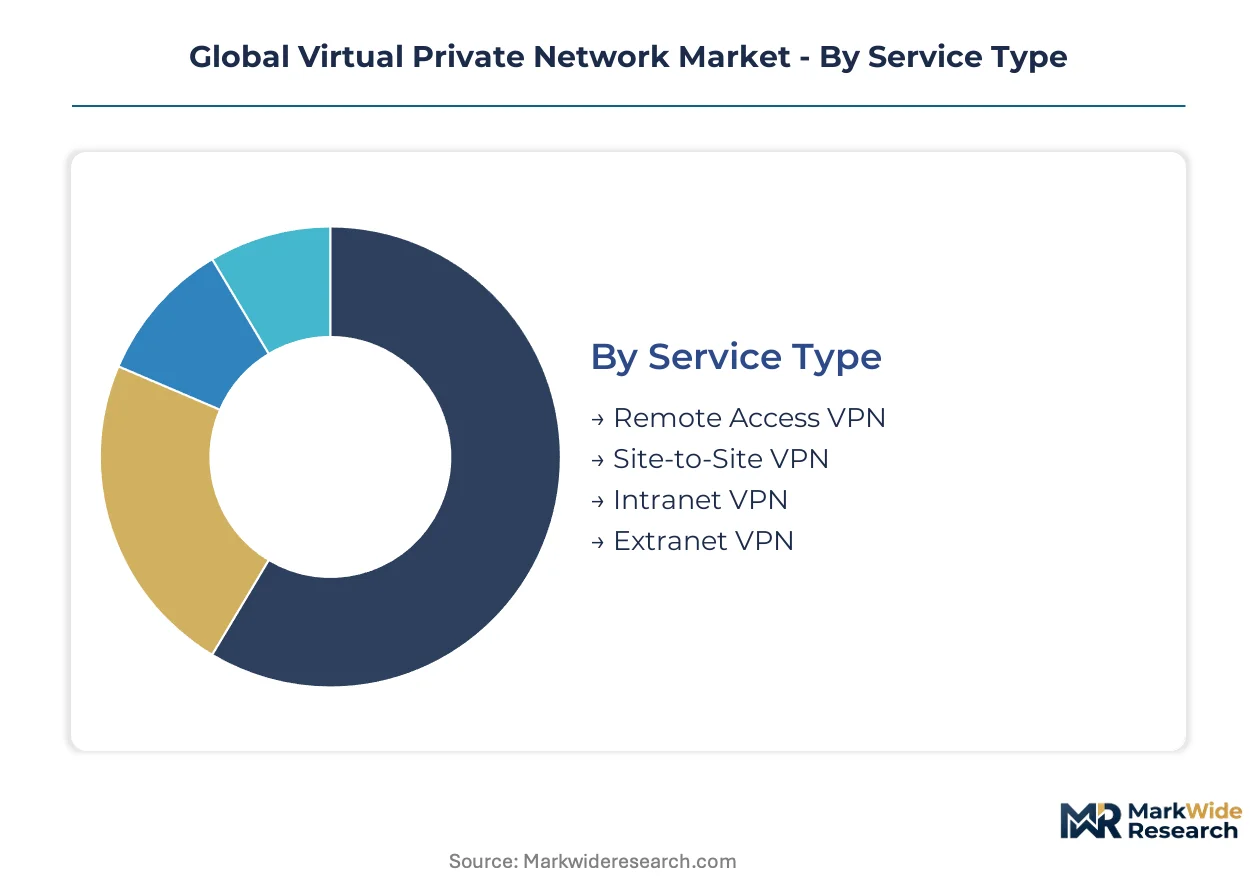
VPN market segmentation reveals divergent substitution pressures across deployment models and protocol architectures. Enterprise procurement teams increasingly trade dedicated hardware stacks for consumption-based alternatives, reshaping vendor revenue concentration and margin structures.
Service Type:
Zero-trust network access and software-defined perimeter technologies are exerting substitution pressure on traditional tunnel-based VPN services, forcing incumbents to defend installed bases against identity-native challengers.
- Remote Access VPN:This architecture establishes encrypted tunnels between individual endpoints and corporate gateways using IPsec or SSL/TLS protocols. Financial services firms in the United States and Germany maintain permanent deployments for hybrid trading floors and distributed claims processing operations. Always-on requirements from institutionalized remote-work policies sustain contract renewal rates despite zero-trust migration rhetoric.
- Site-to-Site VPN:Permanent encrypted connections between fixed network locations replace leased-line dependencies for inter-branch data synchronization. Manufacturing conglomerates across Japan and South Korea rely on these tunnels for real-time production line coordination between facilities. Deterministic latency requirements in automotive and semiconductor fabrication limit cloud-based substitution in this segment.
- Intranet VPN:Internal network segmentation using VPN protocols isolates departmental traffic within single-organization boundaries.
- Extranet VPN:Controlled tunnel access extends to external partners, suppliers, and joint-venture entities with credential-limited permissions.
Remote Access VPN anchors the volume base while Site-to-Site VPN gains share at the steepest rate as manufacturing reshoring accelerates inter-facility connectivity requirements.
Deployment:
Capital expenditure avoidance among mid-market enterprises is compressing on-premises deployment share, with procurement criteria prioritizing operational flexibility over infrastructure ownership.
- Cloud-Based:Subscription orchestration of VPN gateways through hyperscaler marketplaces eliminates hardware procurement cycles and data center footprint. United States mid-market enterprises migrating productivity workloads to Microsoft Azure and AWS drive capacity expansion. Consumption-based licensing aligns cost structures with actual tunnel utilization rather than peak-provisioned capacity.
- On-Premises:Dedicated gateway appliances within corporate data centers maintain full administrative control over encryption key lifecycle and logging policies. Defense contractors and classified government facilities across the United Kingdom and Australia mandate air-gapped deployments for compliance with national security frameworks. Hardware refresh cycles extend as software-defined alternatives capture new procurement decisions.
- Hybrid:Split tunnel configurations route sensitive traffic through on-premises gateways while general internet-bound flows traverse cloud proxies.
- Hosted:Third-party data center colocation of customer-owned VPN equipment blends control with outsourced facility management.
On-Premises deployment retains the highest revenue per customer while Cloud-Based alternatives expand most quickly among net-new enterprise accounts.
End User Industry:
Regulatory enforcement intensity varies sharply across verticals, with financial and government sectors facing mandatory encryption mandates that insulate against pure price competition.
- BFSI:Banking, insurance, and capital markets operations require always-on encrypted access to core systems for traders, underwriters, and wealth advisors. European institutions navigate GDPR cross-border transfer mechanisms and EU AI Act data lineage requirements simultaneously. Singapore and Hong Kong monetary authorities mandate specific protocol configurations for systemically important institutions.
- Government:Federal, state, and municipal agencies deploy classified and unclassified VPN infrastructures with divergent certification requirements. United States Department of Defense Impact Level 4+ deployments demand hardware security module integration. India's Data Protection Board localization mandates are accelerating domestic point-of-presence establishment.
- IT & Telecom:Technology service providers and network operators use VPNs for internal infrastructure access and customer-managed security offerings.
- Manufacturing:Industrial remote monitoring and supply chain integration drive deployment, though latency constraints limit TLS 1.3 adoption.
- Energy & Utilities:Critical infrastructure protection frameworks in the United States and European Union mandate encrypted operational technology access.
BFSI contributes the largest absolute revenue while Government verticals demonstrate the most inelastic demand characteristics under regulatory compulsion.
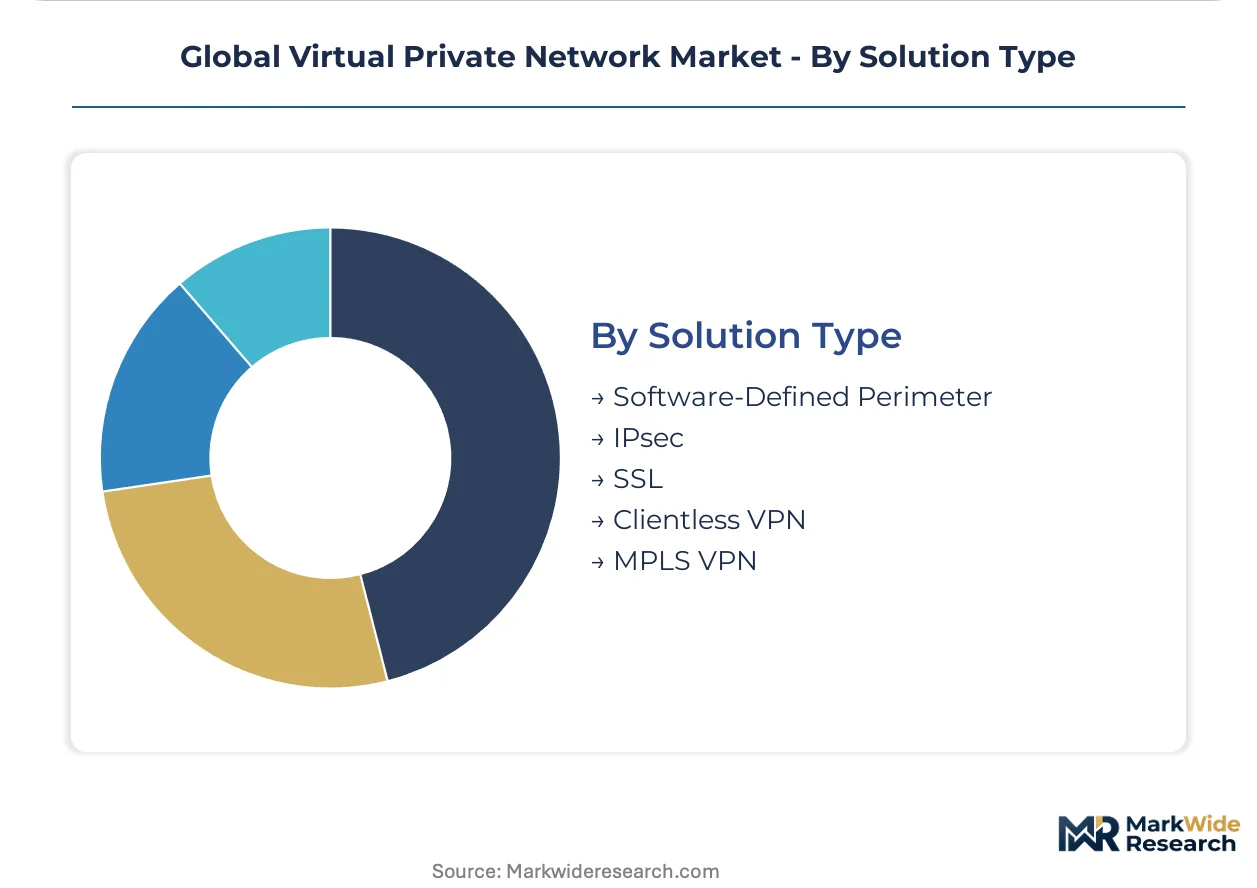
Solution Type:
Protocol standardization battles between incumbent IPsec/SSL duopoly and WireGuard challengers are fragmenting procurement specifications across enterprise segments.
- Software-Defined Perimeter:Identity-verified microsegmentation replaces network-location-based access decisions with continuous device and user attestation. German automotive manufacturers deploy these overlays to satisfy EU AI Act training data audit trail requirements for cross-border model development. Financial services pilots in Singapore validate trader mobility use cases with reduced battery consumption versus traditional tunnels.
- MPLS VPN:Carrier-managed private networking delivers deterministic latency and service-level agreements for legacy financial trading and manufacturing control systems. Premium pricing persists where milliseconds determine arbitrage profitability or production line synchronization. Migration pressure mounts as SD-WAN overlays replicate performance characteristics at lower cost.
- IPsec:Standards-based tunneling protocol dominates enterprise interoperability requirements and legacy system integration.
- SSL:Browser-native encryption simplifies remote access deployment without client software installation overhead.
- Clientless VPN:Portal-based access through standard web browsers serves occasional-use scenarios and contractor populations.
IPsec retains the broadest installed base while Software-Defined Perimeter climbs the fastest as zero-trust mandates penetrate Fortune 500 security roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where mid-market cloud migration accelerates subscription uptake, while European providers absorb compliance cost premiums from GDPR and EU AI Act mandates without equivalent margin recovery.
United States
Financial services hybrid workforces and defense contractor classified networks sustain demand bifurcation between cloud-based and air-gapped deployments. FCC broadband privacy rulings shape logging policy architectures for domestic providers. Northern Virginia's data center corridor hosts concentrated cloud VPN gateway infrastructure serving federal and enterprise accounts.
Germany
Automotive manufacturers and healthcare AI developers drive zero-trust overlay procurement for EU AI Act training data audit compliance. BSI federal cybersecurity guidelines mandate specific protocol configurations for critical infrastructure operators. Munich and Stuttgart industrial clusters pilot WireGuard implementations for reduced battery consumption in mobile engineering workflows.
United Kingdom
Financial services trading floors and government classified facilities sustain MPLS VPN premium pricing despite SD-WAN substitution pressure. The Investigatory Powers Act and proposed encryption backdoor frameworks create jurisdictional tension with no-log policy providers. London's fintech corridor concentrates managed VPN service contracts for cross-border payment system access.
Singapore
Wealth management and trading mobility use cases validate lightweight protocol adoption for battery-sensitive endpoints. Monetary Authority of Singapore mandates specific encryption standards for systemically important financial institutions. The Marina Bay financial district anchors regional VPN point-of-presence expansion serving ASEAN cross-border data flows.
India
IT services export growth and domestic data localization mandates create dual-track demand for offshore delivery center access and in-country infrastructure. The Data Protection Board's pending enforcement of critical personal data localization requirements accelerates Mumbai and Hyderabad point-of-presence establishment. Bangalore's technology corridor concentrates enterprise procurement decision-making for regional managed security services.
Global Virtual Private Network Market Competitive Landscape
Concentration sits with enterprise hardware incumbents leveraging installed base relationships against specialized privacy-focused challengers. The vendor base stratifies across three tiers: infrastructure conglomerates bundling security appliances, consumer subscription specialists operating proprietary server networks, and open-source transparency advocates exploiting jurisdictional advantages. Dominant competitive moves include hyperscaler marketplace partnership expansion and post-quantum cryptography capability differentiation.
Within the infrastructure-anchored tier, Cisco Systems, Inc. exemplifies enterprise hardware bundling strategies, while NordVPN and ProtonVPN occupy distinct positions in the consumer-privacy specialist segment. These three anchors represent divergent architectural bets: appliance-centric perimeter defense, proprietary server network scale, and jurisdictional transparency positioning respectively.
| Leading Market Players |
|---|
| NordVPN |
| ExpressVPN |
| Surfshark |
| CyberGhost |
| Private Internet Access |
| IPVanish |
| TunnelBear |
| ProtonVPN |
| Cisco Systems, Inc. |
| Others |
Supply & Pricing Matrix
FCC broadband privacy rulings and GDPR cross-border transfer mechanisms gate both server infrastructure qualification and subscription tier differentiation simultaneously. Providers must architect logging policies and jurisdiction placement to satisfy divergent compliance regimes, with certification investments translating directly into pricing power over uncertified competitors.
Pricing Analysis
Configured-to-order enterprise deployments command substantial premiums over standard consumer subscription tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation anchored in server jurisdiction certification, dedicated IP allocation, and managed security service bundling. Pricing pressure stems from hyperscaler marketplace consolidation transferring leverage to AWS and Azure field sales organizations. Mid-market enterprises exhibit highest price sensitivity, while defense contractors and financial institutions demonstrate inelastic demand under regulatory compulsion.
Supply Chain Analysis
Just-in-time server provisioning prevails among cloud-reseller VPN providers, while bare-metal operators in Switzerland, Iceland, and Panama maintain strategic hardware reserves to ensure jurisdictional continuity. Bare-metal hosting draws from privacy-focused data center clusters, submarine cable landing stations, and hardware security module manufacturers. Single-source vulnerability concentrates in specialized encryption chip foundries. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and managed security service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed security service attach rates are expanding faster than standalone VPN licensing, as enterprise procurement teams consolidate security budgets under unified zero-trust architectures.
For Market Incumbents: Consolidate installed base relationships through hardware-software bundling and post-quantum cryptography certification investments. Defend against WireGuard-native challengers by embedding proprietary protocol extensions within existing appliance footprints. Prioritize vertical integration into bare-metal server networks across privacy-focused jurisdictions to reduce third-party hosting dependency. For New Entrants and Emerging Players: Zero-trust architecture skill scarcity among enterprise IT departments creates immediate service-layer opportunity. Target mid-market cloud migration projects in the United States where incumbent vendor relationships remain underdeveloped. Penetrate through consumption-based licensing aligned with Microsoft Azure and AWS marketplace procurement workflows. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape by mandating data lineage documentation capabilities across cross-border model training workflows. Long-term viability centers on providers with established zero-trust overlay integration and jurisdictional diversification beyond concentrated privacy havens. Watch India's Data Protection Board localization mandates as signal for first-mover infrastructure valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Migration | NIST-standardized algorithms differentiate providers before regulatory mandates crystallize across federal and financial verticals. |
| Hyperscaler Marketplace Integration | AWS and Azure field sales organizations capture pricing leverage through consolidated cloud security budget management. |
| Zero-Trust Architecture Overlay Development | Software-defined perimeter integration satisfies EU AI Act training data audit trail requirements for automotive and healthcare developers. |
| Jurisdictional Point-of-Presence Expansion | Mumbai and Hyderabad infrastructure establishes first-mover positioning under India's pending data localization enforcement. |
| WireGuard Protocol Certification | Lightweight codebase adoption reduces battery consumption for trader mobility use cases in Singapore and German financial centers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and regulatory enforcement databases covering FCC, GDPR, and EU AI Act implementation. Interviews with CISOs, network operations directors, channel partners, and managed security service providers inform demand-side validation. Bottom-up tunnel utilization estimates triangulate against top-down enterprise IT security spending allocations.
Segmentation dimensions modeled include deployment architecture, protocol standard, end-user industry vertical, and organization size tier across the analysis window. CAGRs derive from regression analysis of historical subscription growth rates and projected cloud migration penetration curves. Industry-specific inputs incorporate zero-trust mandate adoption timelines and cross-border data transfer mechanism enforcement intensity.
Material uncertainties — encryption backdoor legislative progression, quantum computing advancement timelines, and data localization mandate implementation delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained hybrid work policy institutionalization and hyperscaler marketplace channel consolidation. Revision becomes warranted when post-quantum cryptography standardization or major jurisdiction blocking orders cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Managed Network Services Market
Data Center and Networking
Data Deduplication Market
Data Center and Networking
Italy Data Center Networking Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Infrastructure As a Service Market
Data Center and Networking
France Data Center Networking Market
Data Center and Networking
Netherlands Data Center Networking Market
Data Center and Networking
Saudi Arabia Data Center Networking Market
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Mobile Data Offload Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Spain Data Center Networking Market