
 Operational Predictive Maintenance Market | 2026-2036
Operational Predictive Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Operational Predictive Maintenance Market Outlook
Premium predictive maintenance suites is decoupling from commodity sensor-alert packages in both capability and buyer economics. Siemens leverages deep domain expertise in industrial automation to anchor high-margin consulting engagements for European heavy industry. IBM Corporation competes through AI-driven analytics platforms that integrate with existing enterprise asset management systems. General Electric sustains technology leadership in edge-computing deployments for power generation and aviation turbine fleets.
Operational predictive maintenance encompasses the continuous monitoring of industrial equipment health through sensor data, algorithmic analysis, and failure forecasting to schedule interventions before functional degradation causes downtime. Systems typically process vibration spectra in the 0.5–20 kHz range, oil particulate counts, and thermal signatures against baseline operational envelopes to generate remaining-useful-life estimates. Cloud-based deployment models are capturing the fastest expansion as manufacturers abandon capital-intensive on-premises data centers for scalable SaaS architectures. Machine learning technology dominates R&D investment flows, though IoT Devices generate the underlying data streams that determine model accuracy and prediction horizons.
The US Occupational Safety and Health Administration and the EPA enforce equipment integrity standards that indirectly mandate predictive monitoring for hazardous process industries. The EU Machinery Directive and CE marking requirements pressure European manufacturers to document proactive safety systems, expanding addressable demand for integrated predictive platforms. Stakeholders must weigh vendor lock-in risks against the interoperability benefits of open architecture standards as procurement teams consolidate maintenance technology stacks.
Market Dynamics
Cloud migration is compressing deployment timelines as manufacturers abandon on-premises SCADA infrastructure for subscription-based analytics platforms, forcing vendors to restructure pricing and service delivery models around recurring revenue rather than perpetual licenses.
Growth Catalysts
- OSHA Process Safety Management:US hazardous process industries face mandated equipment integrity documentation, expanding demand for continuous vibration monitoring and thermal imaging systems that generate auditable failure-prediction records.
- Automotive OEM mandates:German vehicle manufacturers and tier suppliers now require condition-based monitoring protocols from component vendors, pulling predictive maintenance adoption through multi-tier supply chains.
- Edge computing architectures:Real-time inference at the device level enables sub-millisecond anomaly detection for rotating machinery, eliminating latency bottlenecks that previously constrained cloud-only deployments.
Market Restraints
- Sensor hardware concentration:MEMS accelerometer and infrared detector supply chains cluster in East Asian manufacturing zones, creating single-source vulnerability for vibration and thermal monitoring hardware.
- Data interoperability friction:Proprietary protocols from incumbent automation vendors fragment sensor data formats, forcing buyers into expensive middleware development or vendor lock-in.
- Skilled analyst scarcity:Interpretation of vibration spectra and oil debris analysis requires specialized tribology and signal-processing expertise that outpaces current vocational training pipeline output.
Strategic Opportunities
- EU AI Act compliance services:European manufacturers deploying machine-learning-based failure prediction must document algorithmic transparency and bias testing, creating adjacent consulting revenue for vendors with validation expertise.
- Small and mid-sized manufacturer penetration:US metal fabrication and food processing facilities below 500 employees remain underserved by enterprise-focused predictive maintenance suites, presenting white-space for tiered SaaS offerings.
- Digital twin convergence:Integration of physics-based equipment simulation with live sensor streams enables scenario modeling for maintenance timing, opening premium pricing tiers for integrated platform vendors.
Industry Challenges
- Legacy SCADA integration complexity:Brownfield facilities operate decades-old control systems with incompatible data architectures, requiring costly gateway hardware and protocol translation layers that erode project ROI.
- Calibration and certification timelines:Thermal imaging systems for electrical inspection require annual traceable calibration to IEC standards, creating operational overhead and downtime that discourages adoption.
- Cross-functional alignment gaps:Maintenance, operations, and IT departments maintain conflicting KPIs and budget ownership, delaying procurement decisions and complicating post-deployment accountability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Operational Predictive Maintenance Market |
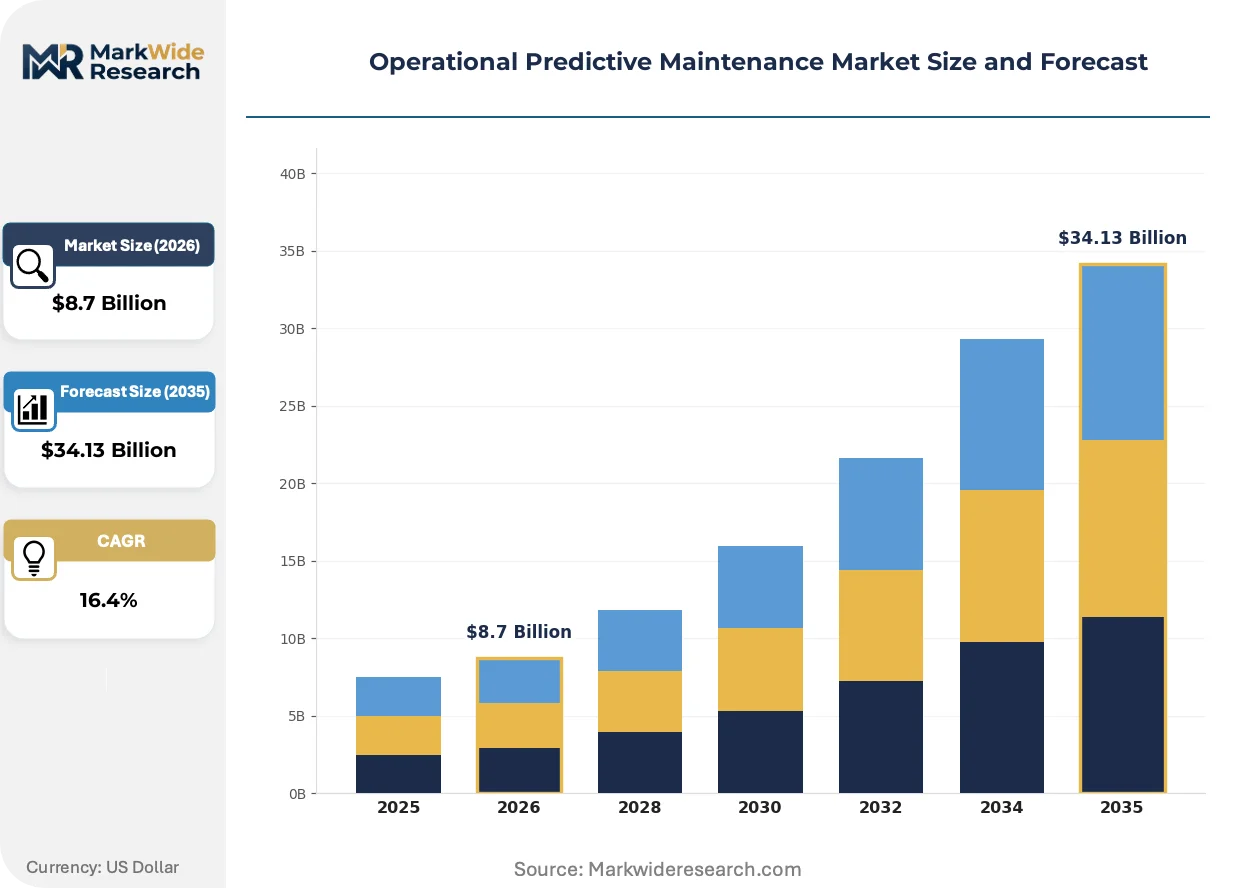
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Integration, Support, Training Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Manufacturing, Transportation, Energy, Utilities Technology: Machine Learning, IoT Devices, Predictive Analytics, Big Data |
| Companies Covered | IBM Corporation, Siemens, General Electric, Schneider Electric, SAP SE, Rockwell Automation, ABB, Honeywell International, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Operational Predictive Maintenance Market Strategic Shifts
Machine learning inference is migrating toward sensor endpoints, compressing the architecture from cloud-centric batch processing to distributed real-time decisioning that reduces bandwidth costs and prediction latency.
Digital twin technology is absorbing capital allocation from standalone monitoring software as aerospace and power generation operators demand integrated simulation-to-physical feedback loops. Siemens and GE Aviation deploy these fused systems for turbine fleet management. The convergence is absorbing budget share previously directed at discrete condition-monitoring platforms, forcing pure-play vendors to embed physics modeling or exit high-value segments.
REACH substance restrictions and the EU F-Gas Regulation are phasing out conventional refrigerants and lubricant additives used in thermal imaging cooling systems and bearing oils. Equipment manufacturers reformulate thermal camera cooling circuits and develop synthetic lubricant compatibility databases. German chemical processors face the steepest compliance timeline, accelerating supplier qualification cycles for replacement chemistries.
Buyer contracting preferences are pivoting from capital equipment purchases to performance-guaranteed service agreements where vendors assume uptime risk. Power utilities and municipal water authorities in the US Southeast lead this shift, signing multi-year contracts tying vendor compensation to measurable downtime reduction rather than sensor installation counts.
Operational Predictive Maintenance Market Segmentation
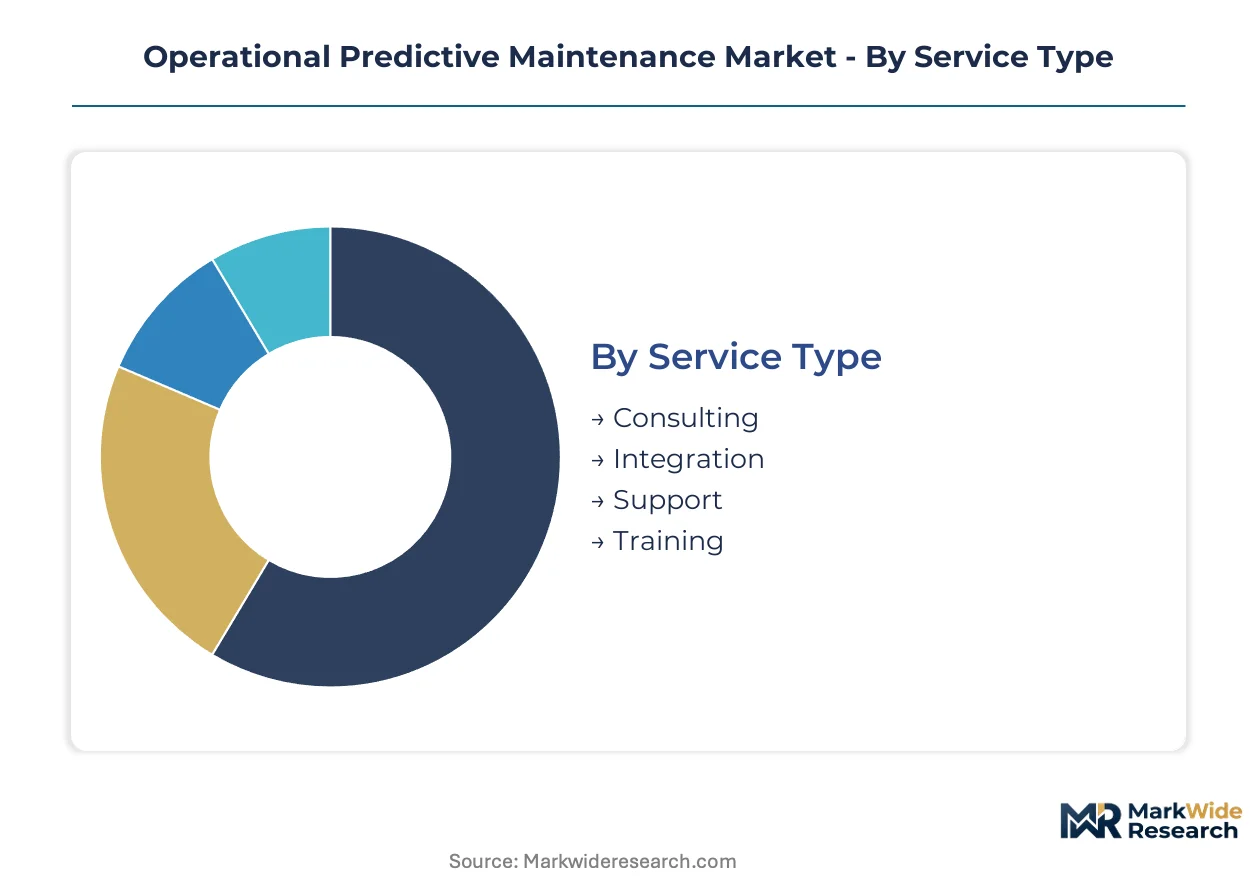
Segmentation in operational predictive maintenance reveals how procurement decisions split between capital-intensive on-premises installations and subscription-driven cloud architectures. Buyers weigh data sovereignty requirements against scalability needs, while technology choices determine prediction accuracy and integration complexity.
Service Type:
Procurement teams prioritize service bundles that minimize internal capability gaps and accelerate time-to-value.
- Consulting:Domain specialists assess equipment criticality, sensor placement strategy, and baseline failure-mode libraries. German automotive OEMs mandate consulting engagements for supplier qualification, pulling demand through tier-1 and tier-2 supply chains.
- Integration:Engineering teams bridge legacy SCADA protocols with modern analytics platforms, deploying gateway hardware and API middleware. Brownfield manufacturing facilities in the US Midwest concentrate demand as decades-old control systems resist native interoperability.
- Support:Vendors provide 24/7 anomaly alert validation and model retraining services.
- Training:Workforce development programs address the scarcity of vibration spectra interpreters and tribology analysts.
Consulting leads on scale; integration leads on momentum.
Deployment Model:
Total cost of ownership calculations increasingly favor recurring payment structures over upfront capital deployment.
- Cloud-Based:Scalable SaaS architectures eliminate data center capital expenditure and enable remote fleet visibility. US metal fabrication and food processing facilities below 500 employees drive adoption as tiered pricing opens access previously reserved for enterprise buyers.
- On-Premises:Air-gapped installations satisfy data residency mandates in defense and nuclear sectors. European chemical processors facing EU AI Act documentation requirements favor on-premises control for algorithmic audit trails.
- Hybrid:Edge inference handles latency-critical rotating machinery while cloud aggregation supports fleet-level pattern recognition.
- SaaS:Pure subscription models bundle hardware, software, and predictive accuracy guarantees into single contracts.
Cloud-based deployments are expanding most quickly; on-premises retains the largest installed base.
End User:
Equipment criticality and downtime cost magnitude determine willingness to invest in predictive infrastructure.
- Manufacturing:Discrete and process manufacturers deploy vibration analysis and thermal imaging to compress unplanned outage windows. Automotive stamping plants and semiconductor fabs anchor demand in Germany, Japan, and the US.
- Energy:Power generation operators leverage edge computing for turbine fleet management, with GE Aviation and Siemens deploying fused digital twin systems for combustion anomaly detection.
- Transportation:Rail operators and commercial aviation maintenance teams prioritize remaining-useful-life estimates for wheel bearings and engine components.
- Utilities:Municipal water authorities in the US Southeast pioneer performance-guaranteed contracts tying vendor compensation to measurable uptime improvement.
Manufacturing dominates current spend; utilities show the steepest expansion trajectory.
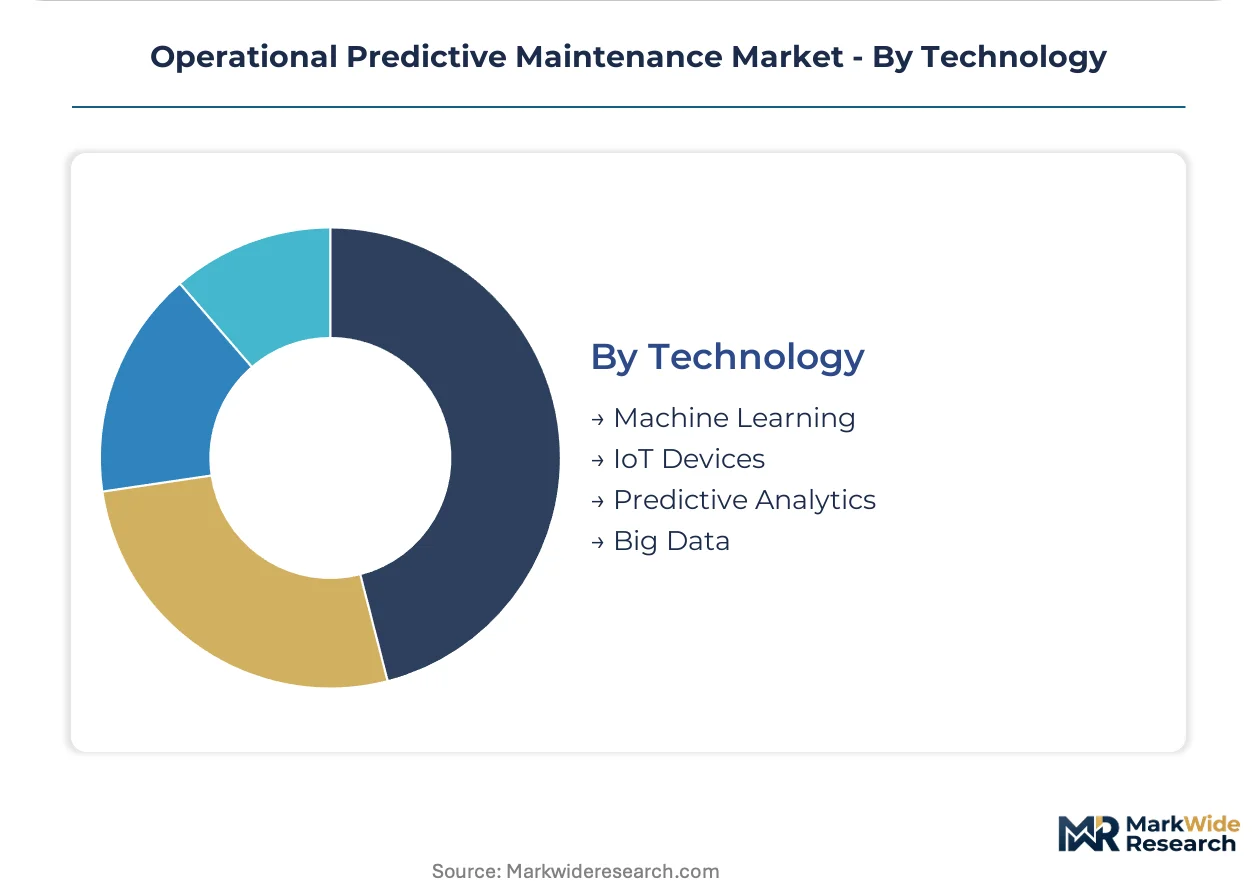
Technology:
Underlying data infrastructure and algorithmic sophistication separate commodity alert systems from premium predictive platforms.
- Machine Learning:Supervised and unsupervised models process multi-sensor streams to generate failure probability distributions. IBM Corporation competes through AI-driven analytics platforms that integrate with existing enterprise asset management systems.
- IoT Devices:MEMS accelerometers, infrared detectors, and oil particulate sensors generate the raw data streams that determine model accuracy. Supply chains for these components cluster in East Asian manufacturing zones, creating single-source vulnerability.
- Predictive Analytics:Statistical process control and time-series forecasting provide deterministic failure windows for mature equipment classes.
- Big Data:Historian architectures aggregate years of operational envelopes across dispersed industrial fleets.
Machine learning commands the highest R&D allocation; IoT devices constitute the foundational layer without which advanced analytics cannot function.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany mandates condition-based monitoring protocols across automotive supply chains, while the United States concentrates demand in hazardous process industries facing OSHA enforcement. Japan and China advance edge-computing architectures for manufacturing automation, and the United Kingdom navigates post-Brexit regulatory alignment for industrial safety systems.
United States
Power utilities and municipal water authorities in the Southeast pioneer performance-guaranteed contracts tying vendor compensation to measurable uptime improvement. OSHA Process Safety Management mandates equipment integrity documentation for chemical processors and refineries. The Gulf Coast petrochemical corridor and Midwest manufacturing belt drive vibration analysis adoption for rotating machinery.
Germany
Automotive OEMs and tier suppliers mandate condition-based monitoring protocols from component vendors, pulling predictive maintenance through multi-tier supply chains. The EU Machinery Directive and CE marking requirements pressure manufacturers to document proactive safety systems. Industrial clusters in Bavaria and Baden-Württemberg deploy integrated predictive platforms for automotive stamping and precision engineering.
China
State-owned power generation operators leverage edge computing for turbine fleet management amid grid modernization campaigns. MIIT industrial internet initiatives accelerate sensor deployment in Yangtze River Delta manufacturing zones. Shanghai and Shenzhen anchor cloud-based predictive maintenance adoption for electronics and semiconductor fabrication facilities.
Japan
METI smart factory initiatives drive digital twin convergence for automotive and precision machinery producers. JIS standards for equipment reliability create certification pull for integrated monitoring systems. The Chubu region around Nagoya and Kansai industrial belt surrounding Osaka concentrate thermal imaging and vibration analysis deployment.
United Kingdom
North Sea oil and gas operators face HSE equipment integrity standards that expand demand for continuous monitoring systems. Post-Brexit regulatory divergence creates uncertainty for EU-harmonized safety certifications. Aberdeen's energy technology cluster and Midlands automotive manufacturing regions adopt hybrid cloud-edge architectures for legacy asset management.
Operational Predictive Maintenance Market Competitive Environment
Top-tier vendors anchor high-margin consulting engagements, while mid-tier specialists compete on SaaS pricing and rapid deployment timelines. The market structures around three tiers: industrial automation conglomerates with deep domain expertise, cloud-native analytics platforms with AI-driven capabilities, and pure-play sensor hardware manufacturers facing commoditization pressure. Strategic moves concentrate on digital twin integration partnerships and outcome-based contracting models that shift revenue from equipment sales to uptime guarantees.
Within the industrial automation tier, Siemens and General Electric exemplify archetypes combining hardware manufacturing with predictive software ecosystems. IBM Corporation occupies a distinct position bridging enterprise IT infrastructure with machine-learning analytics. These three anchors represent contrasting strategic postures: European heavy-industry integration, power-generation edge-computing specialization, and cross-vertical AI platform deployment.
| Leading Market Players |
|---|
| IBM Corporation |
| Siemens |
| General Electric |
| Schneider Electric |
| SAP SE |
| Rockwell Automation |
| ABB |
| Honeywell International |
| Microsoft Corporation |
| Others |
Value Chain & Pricing Dynamics
A sharp bifurcation between premium predictive maintenance suites and commodity sensor-alert packages manifests in divergent pricing architectures and supply chain sourcing strategies, with German automotive OEMs and US hazardous process industries anchoring opposite ends of the value spectrum while East Asian component manufacturing concentrates cost leverage.
Pricing Analysis
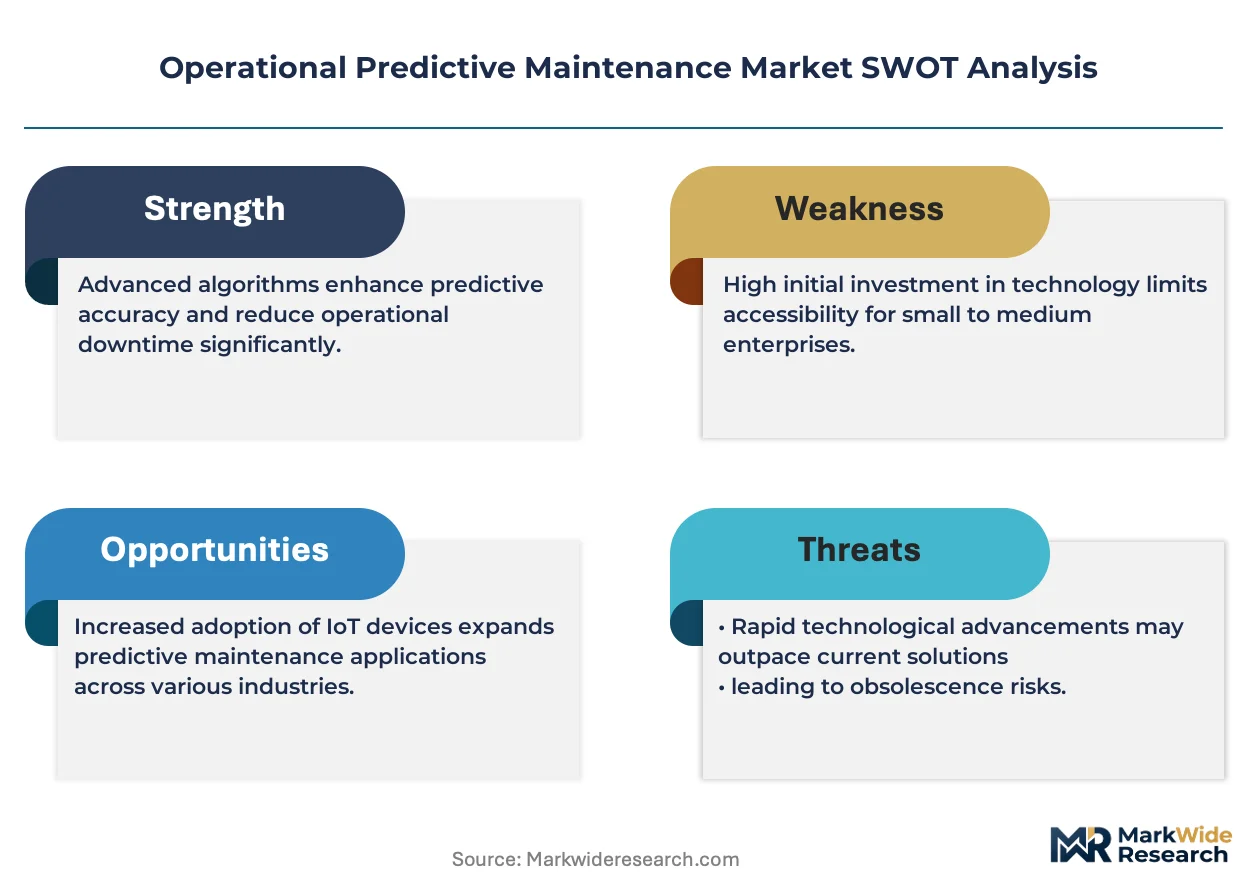
Capacity additions in cloud infrastructure are reshaping price floors for SaaS-tiered subscription models across the predictive maintenance landscape. Three-tier pricing structure across premium, standard, and economy levels separates Siemens and IBM's high-margin consulting-anchored engagements from mid-tier pure-play analytics vendors and entry-level sensor hardware bundles. Price differentiation hinges on algorithmic sophistication depth and ISO 50001 energy management certification tier. Cost compression in commodity MEMS accelerometer tiers is intensifying because Taiwanese and Chinese manufacturers expanded fab capacity. Small and mid-sized US metal fabricators below 500 employees exhibit highest price sensitivity; German chemical processors facing EU AI Act mandates show lowest.
Supply Chain Analysis
Domestic-content mandates in China's MIIT industrial internet initiatives and India's PLI scheme for electronics manufacturing are reshaping sourcing patterns for sensor hardware and edge-computing modules. MEMS accelerometer and infrared detector production clusters in Taiwan, China, and South Korea anchor upstream supply. Raw material dependencies span rare-earth elements for thermal imaging cooling systems, silicon wafers for sensor fabrication, and synthetic lubricant base stocks reformulated under REACH F-Gas restrictions. Single-source vulnerability concentrates in East Asian MEMS foundry capacity. Distribution runs through tier-1 industrial automation distributors and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where US OSHA enforcement timelines compress faster than EU AI Act compliance documentation requirements, creating differential cost-to-serve structures across Atlantic deployment footprints.
For Market Incumbents: Deploy outcome-based contracting mechanisms to lock in multi-year performance-guaranteed relationships with power utilities and municipal water authorities. Siemens and GE Aviation's digital twin convergence threatens pure-play vibration analytics vendors with margin compression; backward integration into edge-computing hardware manufacturing secures supply chain control against MEMS foundry concentration risk. For New Entrants and Emerging Players: Enter via white-space targeting of US metal fabrication and food processing facilities below 500 employees currently underserved by enterprise-focused predictive maintenance suites. Tiered SaaS pricing with remote fleet visibility capabilities penetrates this segment faster than on-premises installations. Channel partnerships with regional industrial distributors accelerate time-to-revenue versus direct enterprise sales cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier SaaS analytics platforms lack embedded physics-based digital twin capabilities and face displacement by Siemens and GE's integrated offerings. Long-term viability favors vendors with algorithmic transparency documentation expertise for EU AI Act compliance services. Acquisition target archetype: cloud-native predictive analytics firms with established API middleware for legacy SCADA integration. Watch for inflection where automotive OEM mandates extend from Germany into tier-2 and tier-3 supplier networks.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Siemens and GE Aviation deploy fused simulation-to-physical systems for turbine fleet management. |
| Outcome-Based Contracting | US Southeast utilities tie vendor compensation to measurable uptime improvement rather than sensor counts. |
| Edge Computing Architecture | Real-time inference at device level eliminates latency bottlenecks for rotating machinery monitoring. |
| EU AI Act Compliance Services | European manufacturers require algorithmic transparency documentation creating adjacent consulting revenue. |
| Legacy SCADA Integration | Gateway hardware and API middleware bridge decades-old control systems with modern analytics platforms. |
Study Parameters
Bottom-up manufacturing plant modeling reconciled against top-down sensor hardware production tracking forms the analytical core of this study. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combined with secondary validation from customs trade data, SEC 10-K filings, and MIIT industrial internet deployment statistics. Triangulation across bottom-up equipment installation counts and top-down vendor revenue reporting ensures dimensional consistency.
Historical trendline analysis of vibration analysis and thermal imaging system deployments informs projection modeling across the analysis window. Segmentation dimensions span deployment model, end-user industry, technology tier, and service type. CAGRs derive from curve-fitting observed adoption velocity against equipment replacement cycles and regulatory mandate enforcement timelines. Forecast inputs incorporate OSHA Process Safety Management compliance deadlines and EU Machinery Directive CE marking requirement phase-ins.
Inputs from plant-level maintenance directors and industrial automation vendor sales operations were available through the study window; gaps in small-facility adoption rates below 500 employees introduce uncertainty bands around SaaS penetration trajectories. Forecasts reflect documented assumptions regarding cloud migration velocity and edge-computing hardware cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Agricultural Automation Market
Industrial Automation
Smart Factory Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Intralogistics Market
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Automatic Screw Feeding System Market