
 Europe Data Center Robotics Market | 2026-2036
Europe Data Center Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Robotics Market Analytics
Software-defined fleet orchestration is decoupling hardware procurement from long-term service contracts across European data center operations. ABB Group leverages its automation heritage to dominate robotic arm deployments in Nordic facilities. Siemens AG anchors its position through deep integration with building management systems and power infrastructure. Huawei Technologies Co., Ltd. competes aggressively on price-performance ratios for AI-enabled mobile robots despite geopolitical headwinds.
Data center robotics encompasses autonomous machines engineered for environmental monitoring, equipment handling, and predictive maintenance within server facilities, typically operating across temperature ranges from 18°C to 27°C with IP54 minimum ingress protection for dust and moisture resistance. Robotic arms currently occupy the largest product type segment due to established precision handling requirements for rack-mounted servers, while mobile robots represent the fastest-expanding category as edge computing nodes multiply across secondary European markets. By end user, colocation providers sustain the dominant revenue share through centralized procurement at scale, whereas cloud service providers are concentrating investment in computer vision-enabled drones for thermal inspection of hyperscale campuses.
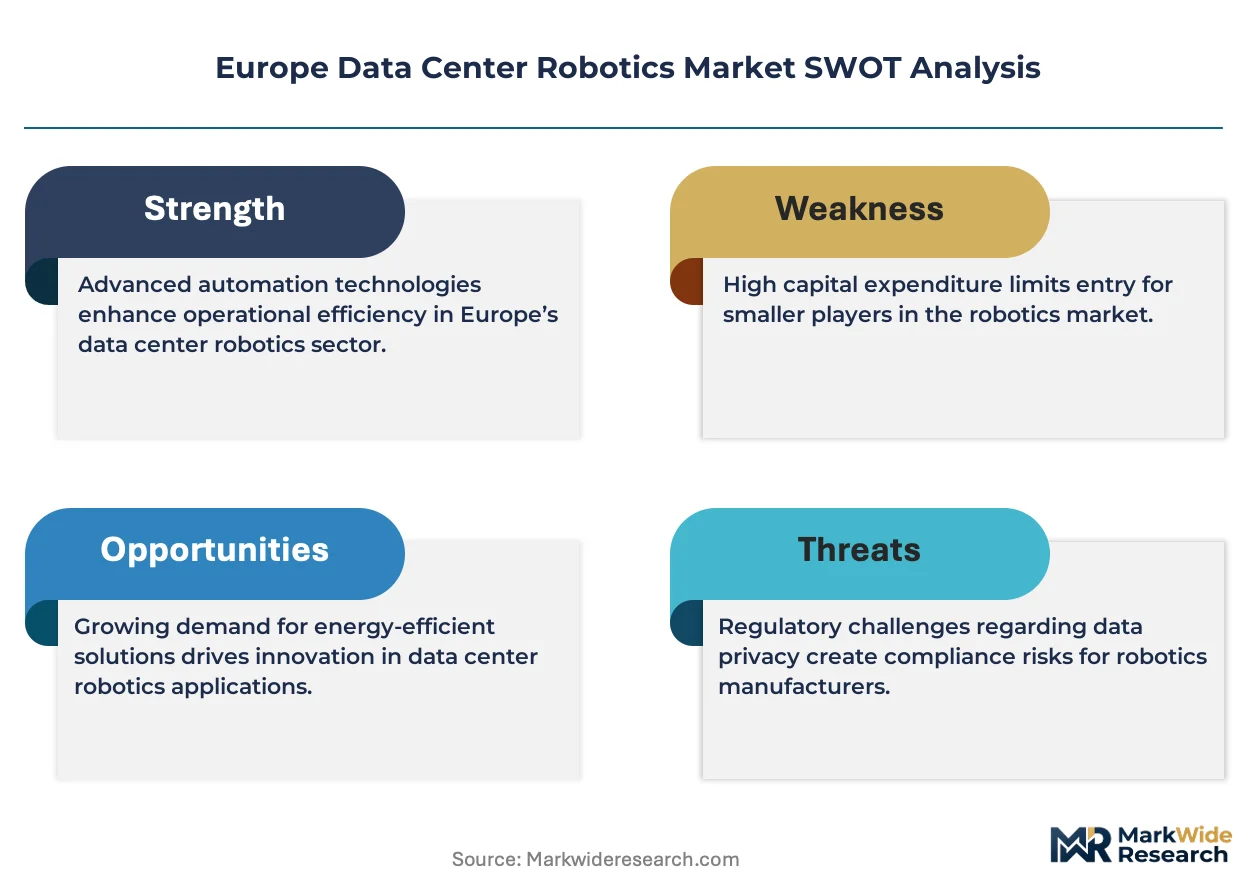
The EU AI Act imposes strict conformity assessments on autonomous decision-making systems deployed in critical digital infrastructure, directly influencing product certification timelines and liability frameworks for robotics vendors. REACH and RoHS regulations constrain material selection for battery-powered mobile units and servo motors, elevating compliance costs for non-European manufacturers. EMA cybersecurity guidelines for critical infrastructure further shape procurement specifications, particularly for telco-operated edge data centers. Stakeholders must weigh regulatory compliance investments against the operational savings from fully autonomous maintenance workflows as deployment scales accelerate.
Market Dynamics
The EU AI Act's conformity assessment requirements are compressing vendor certification timelines while simultaneously elevating liability exposure for autonomous systems deployed in Frankfurt and Amsterdam hyperscale clusters.
Growth Catalysts
- Edge Computing Proliferation:Mobile robot demand is accelerating across secondary European markets as distributed compute nodes multiply beyond core Frankfurt-London-Amsterdam hubs.
- EU AI Act Compliance Infrastructure:Mandatory conformity assessments for autonomous decision-making systems are creating standardized procurement specifications that favor robotics vendors with established certification pathways.
- Thermal Inspection Automation:Computer vision-enabled drones are displacing manual thermal audits across Nordic colocation campuses operating sub-1.1 PUE targets.
Market Restraints
- REACH-Compliant Material Costs:Battery chemistries and servo motor components face restricted substance lists that elevate unit economics for non-European manufacturers.
- Geographic Supply Concentration:Precision gearbox and harmonic drive production clusters in East Asia create lead time vulnerability for European system integrators.
- IP54 Ingress Protection Floor:Ambient temperature robotics operating below server-grade environmental thresholds face substitution pressure from hardened industrial automation platforms.
Strategic Opportunities
- Poland and Czech Republic Edge Expansion:Underpenetrated Central European data center construction is generating first-mover advantage for mobile robot fleet deployments.
- EMA Cybersecurity Guideline Alignment:Telco-operated edge facilities require robotics platforms certified to critical infrastructure standards, creating vendor lock-in potential.
- Digital Twin Convergence:Integration of real-time robotic telemetry with building management systems enables predictive maintenance contracts that displace break-fix service models.
Industry Challenges
- Mechatronics Talent Scarcity:Cross-functional robotics deployment teams require simultaneous expertise in HVAC, electrical infrastructure, and autonomous navigation software.
- CE Marking Timeline Compression:Machinery Directive compliance for collaborative robotic arms now overlaps with EU AI Act conformity assessments, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Robotics Market |
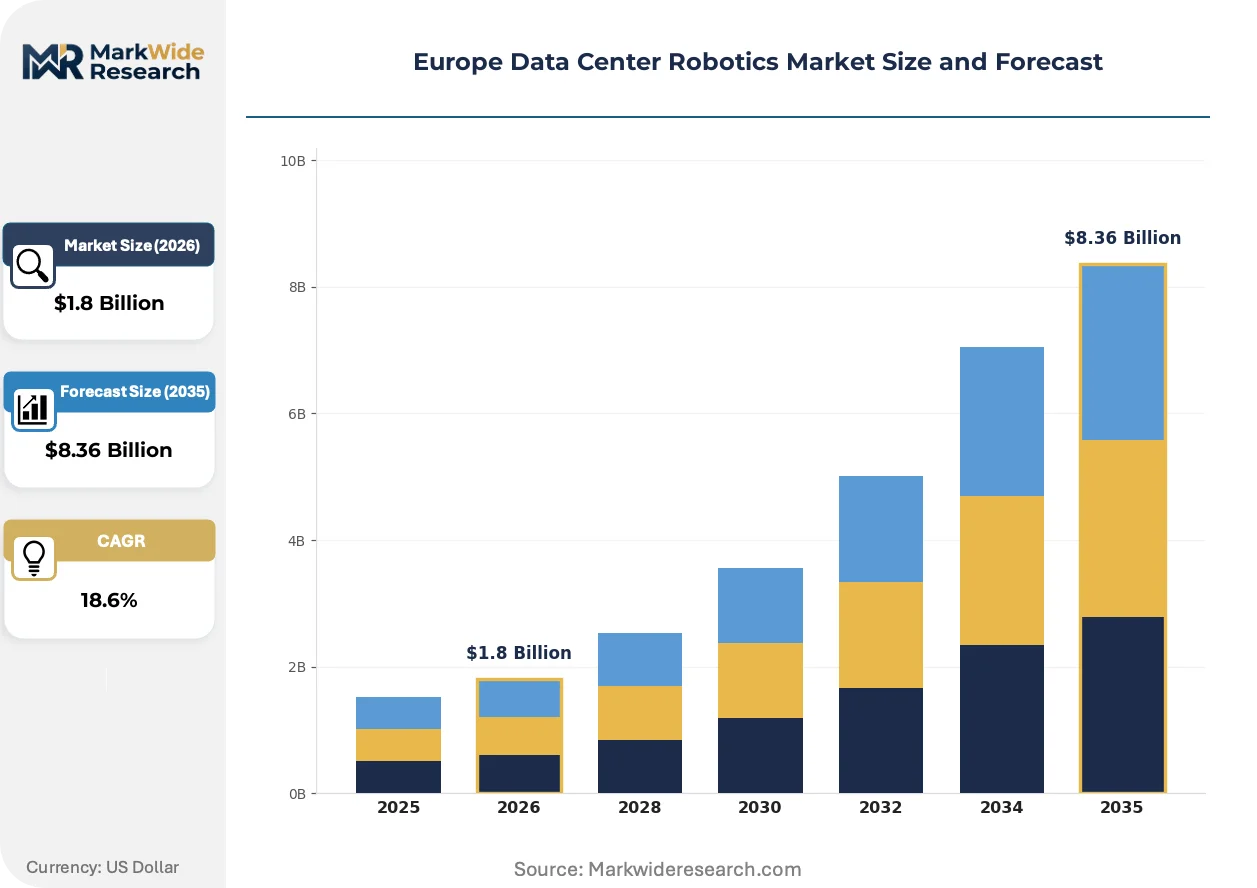
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Robotic Arms, Drones, Mobile Robots End User: Colocation Providers, Cloud Service Providers, Enterprises, Telcos Technology: Artificial Intelligence, Machine Learning, Computer Vision, IoT Installation: Indoor, Outdoor, Modular, Retrofits |
| Companies Covered | ABB Group, Amazon Web Services, Inc, Microsoft Corporation, Equinix, Inc., Cisco Systems, Inc., Siemens AG, Huawei Technologies Co., Ltd., Hewlett Packard Enterprise Company, Rockwell Automation, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Robotics Market Evolving Landscape
Software-defined orchestration layers are separating hardware procurement from long-term service commitments, while regulatory frameworks accelerate the standardization of autonomous system architectures.
Edge-native mobile robotics platforms equipped with SLAM navigation and thermal imaging payloads are decentralizing inspection workflows across distributed server facilities. Colocation providers in secondary Nordic and Benelux markets are deploying these units at accelerating cadence. The technology is decentralizing maintenance labor pools away from centralized hyperscale campuses toward regional edge nodes.
The EU AI Act's risk-based classification system for autonomous systems is mandating documented conformity assessments before commercial deployment in critical digital infrastructure. Robotics vendors must now maintain technical documentation and quality management systems that satisfy notified body scrutiny. Mobile robot categories operating in Tier III+ facilities face the most intensive compliance burden, with German and Dutch operators leading implementation.
After-sales service unbundling is fragmenting traditional robotics procurement into discrete hardware, software license, and maintenance subscription components. Colocation providers in Germany and the Netherlands are negotiating direct sensor and actuator sourcing while contracting software orchestration separately. This pattern is most visible among hyperscale-adjacent operators seeking to optimize total cost of ownership across 10-year facility lifecycles.
Europe Data Center Robotics Market Segmentation
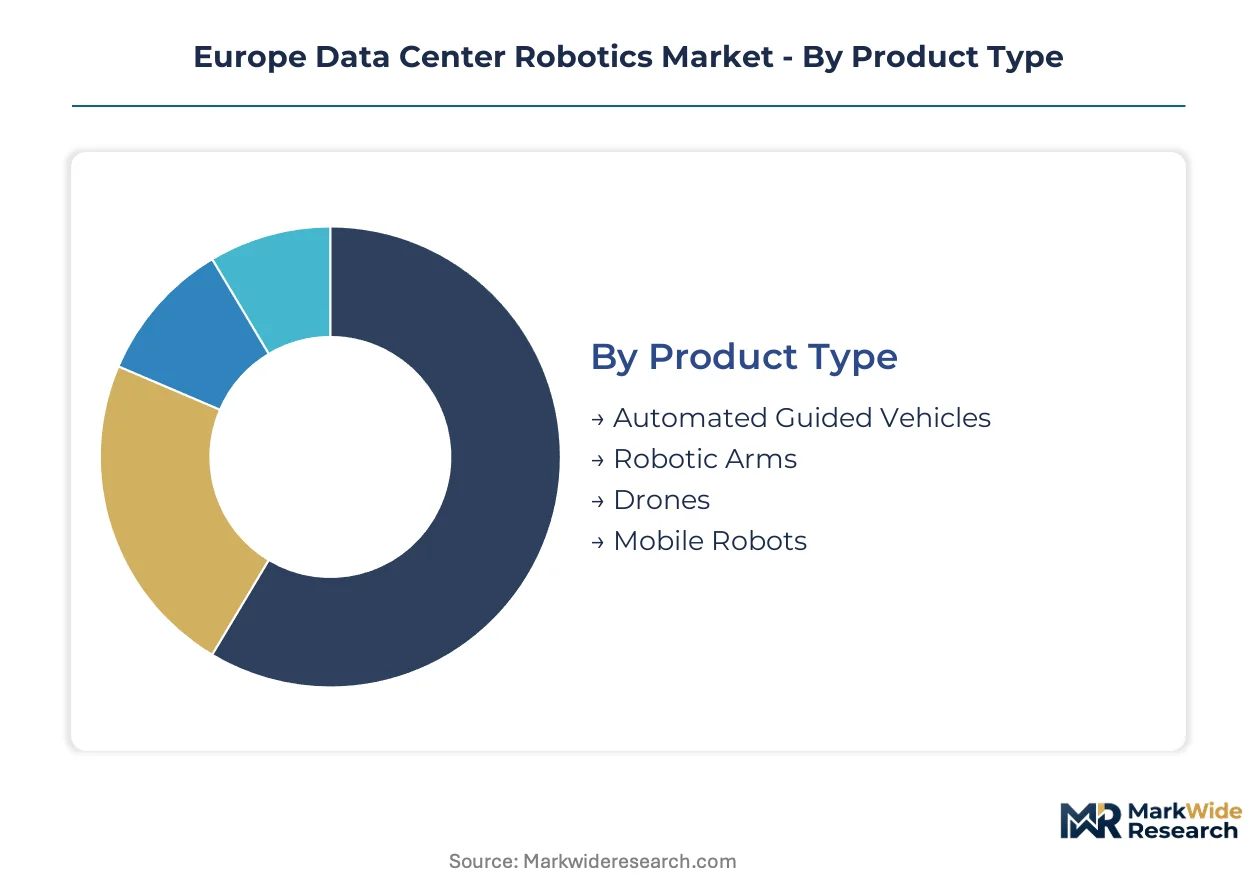
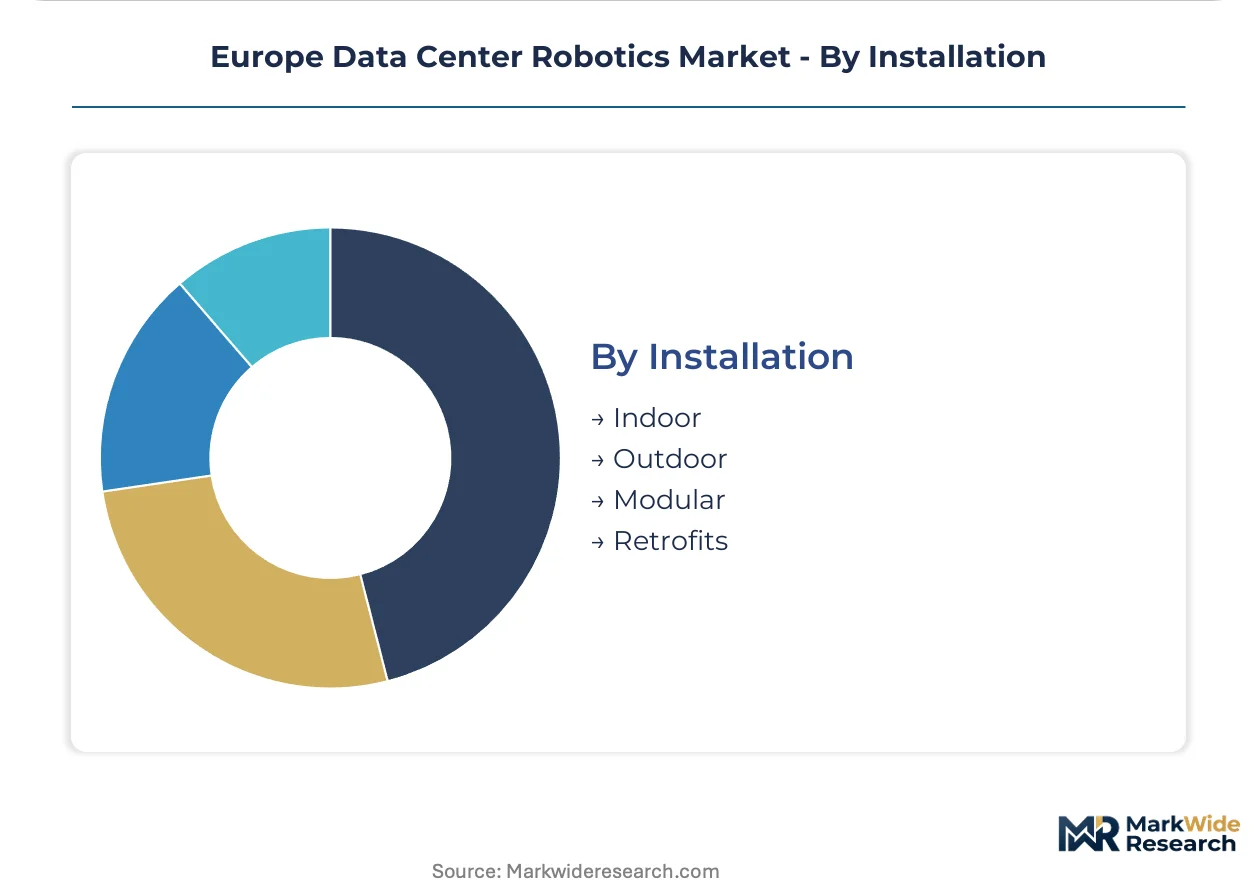
Segmentation reveals distinct procurement patterns across European data center robotics. Product architecture, end-user scale, and deployment environment each shape vendor selection criteria and compliance pathways differently.
Product Type:
Volume concentration favors established handling equipment, while premium expansion clusters around autonomous mobility platforms.
- Robotic Arms:Articulated manipulators with six-axis precision control dominate rack-mounted server installation and component replacement workflows. Frankfurt and Amsterdam hyperscale campuses sustain concentrated procurement for these units, driven by standardized server form factors and repetitive handling demands.
- Mobile Robots:Autonomous ground vehicles equipped with SLAM navigation and thermal payloads are expanding most quickly across Nordic and Benelux edge facilities. Poland and Czech Republic construction pipelines are generating first-mover fleet deployments as distributed compute nodes multiply.
- Automated Guided Vehicles:Magnetic tape or QR-guided transport units handle palletized equipment movement along fixed facility corridors. German colocation providers favor these for predictable inventory transfer between receiving docks and server halls.
- Drones:Aerial platforms with computer vision-enabled thermal imaging conduct ceiling infrastructure and cooling system inspection. Nordic operators pursuing sub-1.1 PUE targets are displacing manual audit workflows with these systems.
Mature deployment sits with Robotic Arms. Newer deployment is concentrated in Mobile Robots.
End User:
Procurement scale separates centralized operators from distributed infrastructure owners.
- Colocation Providers:Multi-tenant facility operators leverage centralized procurement power to negotiate hardware-software unbundling. German and Dutch hyperscale-adjacent operators are separating sensor sourcing from orchestration subscriptions to optimize ten-year facility economics.
- Cloud Service Providers:Hyperscale operators concentrate investment in computer vision-enabled drones for thermal inspection across expansive campuses. These buyers specify EU AI Act conformity documentation as mandatory procurement criteria.
- Enterprises:Captive data center operators deploy robotics selectively for compliance-sensitive maintenance in financial services and healthcare verticals. EMA cybersecurity guidelines shape their vendor selection for critical infrastructure certification.
- Telcos:Edge facility operators require robotics platforms aligned with critical infrastructure cybersecurity standards. This specification creates vendor lock-in potential for certified system integrators.
Procurement volume concentrates with Colocation Providers. Specification complexity is highest among Telcos.
Technology:
Functional capability layers determine integration depth with facility management systems.
- Computer Vision:Optical sensing systems enable defect detection, thermal anomaly identification, and navigation landmark recognition. REACH-compliant camera component sourcing elevates unit economics for non-European vendors.
- Artificial Intelligence:Autonomous decision-making systems face EU AI Act conformity assessment requirements before commercial deployment in Tier III+ facilities. German operators lead implementation of documented quality management systems for these platforms.
- Machine Learning:Predictive models trained on equipment telemetry enable failure anticipation and maintenance scheduling optimization. Integration with Siemens AG building management systems anchors deployment in Nordic facilities.
- IoT:Sensor networks feed real-time environmental and equipment status data to centralized orchestration layers. Digital twin convergence with robotic telemetry is displacing break-fix service contracts.
Integration maturity sits with IoT. Regulatory scrutiny is intensifying around Artificial Intelligence.
Installation:
Environmental exposure dictates ingress protection specifications and deployment economics.
- Indoor:Climate-controlled server hall deployment dominates current installed base, operating within 18°C to 27°C ranges with IP54 minimum protection. These conditions favor hardened automation platforms over purpose-built data center robotics.
- Modular:Prefabricated facility units require robotics compatibility with standardized container dimensions and rapid deployment protocols. Edge computing proliferation is accelerating specification development for these configurations.
- Retrofits:Existing facility automation upgrades face spatial constraints from legacy aisle configurations and overhead infrastructure. CE Marking timeline compression under overlapping Machinery Directive and EU AI Act assessments extends project cycles.
- Outdoor:External cooling equipment and power infrastructure inspection demands IP65+ protection and extended temperature tolerance. These specifications constrain vendor participation to industrial automation specialists.
Deployment density sits with Indoor. Specification evolution is fastest around Modular installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's hyperscale cluster density concentrates procurement volume for mobile robots and robotic arms across the European data center robotics landscape. The region's regulatory fragmentation under EU AI Act, REACH, and national cybersecurity frameworks shapes vendor certification pathways differently across member states. Market activity clusters around established digital infrastructure corridors with mature colocation ecosystems.
Germany
Frankfurt's hyperscale density drives concentrated procurement of six-axis robotic arms for rack-mounted server handling. The EU AI Act's conformity assessment requirements extend product launch cycles for autonomous systems deployed in Tier III+ facilities. Bavaria's edge computing construction pipeline generates first-mover mobile robot fleet deployments as distributed compute nodes multiply beyond core hubs.
Netherlands
Amsterdam's colocation campus expansion sustains demand for automated guided vehicles along standardized facility corridors. REACH-compliant material sourcing for battery chemistries elevates unit economics for non-European manufacturers serving Dutch operators. The Randstad region's hyperscale-adjacent providers are unbundling hardware procurement from software orchestration subscriptions to optimize ten-year facility economics.
United Kingdom
London's financial services captive data centers deploy robotics selectively for compliance-sensitive maintenance workflows. EMA cybersecurity guidelines shape vendor selection criteria for critical infrastructure certification in telco-operated edge facilities. The Southeast's modular data center construction accelerates specification development for container-compatible robotics platforms.
Sweden
Nordic sub-1.1 PUE targets drive computer vision-enabled drone deployment for thermal inspection of ceiling infrastructure and cooling systems. RoHS regulations constrain servo motor component selection for mobile units operating across Stockholm's colocation campuses. The country's building management system integration with Siemens AG anchors predictive maintenance contract structures.
Poland
Warsaw's underpenetrated data center construction generates first-mover advantage for mobile robot fleet deployments at distributed edge nodes. CE Marking timeline compression under overlapping Machinery Directive and EU AI Act assessments extends integration project cycles. The country's secondary market position attracts price-performance focused procurement of AI-enabled autonomous ground vehicles.
Europe Data Center Robotics Market Competitive Landscape
Capital-heavy automation conglomerates compete with asset-light robotics specialists across European data center deployments. The vendor base organizes around three strategic archetypes: industrial automation heritage players with deep building management integration, hyperscale cloud operators with captive robotics development, and emerging Chinese manufacturers competing on price-performance ratios. Consolidation pressure concentrates among mid-scale system integrators facing certification cost escalation. Dominant competitive moves include strategic partnerships with facility management platforms and geographic expansion into underpenetrated Central European edge markets.
Within the industrial automation tier, ABB Group and Siemens AG exemplify heritage players leveraging established certification pathways and facility system integration. Huawei Technologies Co., Ltd. occupies a position among price-focused competitors navigating geopolitical headwinds through aggressive performance positioning. These three anchors represent distinct competitive vectors: European regulatory alignment, building infrastructure convergence, and cost-engineered mobility platforms.
| Leading Market Players |
|---|
| ABB Group |
| Amazon Web Services, Inc |
| Microsoft Corporation |
| Equinix, Inc. |
| Cisco Systems, Inc. |
| Siemens AG |
| Huawei Technologies Co., Ltd. |
| Hewlett Packard Enterprise Company |
| Rockwell Automation, Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up colocation specialists across Germany and the Netherlands are consolidating procurement leverage to unbundle hardware sourcing from software subscriptions, compressing vendor margins while extending payment terms that strain smaller system integrators.
Pricing Analysis
Outcome-based pricing anchored to uptime guarantees and thermal audit throughput is displacing traditional capital expenditure models across Tier III+ facilities. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified autonomous platforms from CE Marking-only units and uncertified industrial automation substitutes. Pricing pressure stems from REACH-compliant material cost elevation for battery chemistries and servo motors. Colocation providers exhibit highest price sensitivity through centralized volume negotiations, whereas cloud service providers prioritize conformity documentation over unit economics.
Supply Chain Analysis
Precision gearbox and harmonic drive supply rests on concentrated production clusters in Japan, Germany, and China, creating lead time vulnerability for European system integrators. Lithium-ion battery cells, rare-earth servo magnets, and REACH-compliant cable assemblies constitute critical input dependencies. Single-source vulnerability intensifies around harmonic drive suppliers serving six-axis robotic arm manufacturers. Distribution runs through certified system integrators with Machinery Directive compliance expertise, bypassing direct OEM relationships for mid-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe data center robotics market operates as a cost-of-compliance story where EU AI Act conformity assessment investments erect barrier-to-entry moats favoring established vendors with documented quality management systems.
For Market Incumbents: Acquire specialized certification consultancies and notified body relationships to compress CE Marking timelines under overlapping Machinery Directive and EU AI Act assessments. Consolidate backward integration into REACH-compliant servo motor sourcing to defend against Chinese price-performance competitors. Threat substitution from industrial automation platforms operating below IP54 thresholds demands hardened environmental protection R&D investment. For New Entrants and Emerging Players: Edge-native SLAM navigation platforms with thermal imaging payloads offer technology-first entry into Poland and Czech Republic construction pipelines where first-mover fleet deployments remain uncommitted. White-space concentration sits with telco-operated edge facilities requiring EMA cybersecurity guideline alignment. Go-to-market execution should anchor on critical infrastructure certification partnerships rather than hardware price competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale system integrators facing certification cost escalation across underpenetrated Central European markets. Long-term viability hinges on software-defined orchestration recurring revenue attachment rates exceeding hardware depreciation cycles. Watch mobile robot fleet deployment velocity at Nordic sub-1.1 PUE campuses as inflection signal for thermal inspection automation adoption.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Accelerates certification pathways for autonomous systems deployed in Frankfurt hyperscale clusters. |
| Software-Defined Orchestration Development | Enables hardware-software unbundling that optimizes ten-year facility economics for Dutch colocation providers. |
| Central European Edge Expansion | Captures first-mover mobile robot deployments across Poland and Czech Republic construction pipelines. |
| REACH-Compliant Material Sourcing | Secures battery chemistry and servo motor supply chains against regulatory restriction elevation. |
| Digital Twin Integration Partnership | Converges robotic telemetry with Siemens AG building management systems for predictive maintenance contracts. |
Research Methodology
Multi-period observation of vendor certification timelines, fleet deployment announcements, and colocation construction pipelines anchored the trend analysis, supplemented by interviews with data center operations directors, robotics procurement managers, system integration specialists, and EMA cybersecurity compliance officers. Secondary validation drew from EU AI Act implementation guidance, ECHA REACH substance restriction updates, hyperscaler capital expenditure disclosures, and Nordic colocation operator sustainability reports. Bottom-up unit economics modeling triangulated against top-down market sizing across product type and end-user segments.
Segment-weighting approaches distributed volume projections across robotic arms, mobile robots, automated guided vehicles, and drone platforms, with end-user stratification between colocation providers, cloud service providers, enterprises, and telcos. CAGRs derived from facility construction pipeline analysis, robotic fleet replacement cycles, and regulatory compliance investment trajectories. Industry-specific forecast inputs included PUE target evolution across Nordic markets and EU AI Act conformity assessment completion rates.
Several conditions sit outside the modeled scope, including geopolitical disruption to East Asian component supply, unilateral national cybersecurity regulations superseding EMA guidelines, and breakthrough autonomous navigation technologies eliminating SLAM hardware requirements. Forecasts reflect documented assumptions regarding regulatory implementation timelines and facility construction completion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Europe AUV Market
Robotics and Automation
Cognitive Robotic Process Automation Market
Robotics and Automation
Household Cleaning Robotics Market
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Latin America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Smart Machines Market
Robotics and Automation
Cleanroom Robots in Healthcare Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Harvesting Robot Market
Robotics and Automation
Asia Pacific Automated Guided Vehicle (AGV) Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
Robotics Actuators Market