
 Asia Pacific Manufacturing Execution Systems (MES) Market | 2026-2036
Asia Pacific Manufacturing Execution Systems (MES) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Manufacturing Execution Systems (MES) Market Outlook
Cloud-native specification tiers is reorganizing competitive dynamics across the Asia Pacific MES landscape. Siemens leverages deep domain expertise in process manufacturing to anchor premium deployments across chemical and pharmaceutical facilities. Yokogawa Electric Corporation specializes in hybrid architectures that bridge legacy on-premise systems with edge-native data pipelines. Schneider Electric extends its energy management heritage into manufacturing execution, competing on sustainability-integrated shop floor control.
Manufacturing Execution Systems comprise software layers that mediate between enterprise resource planning and physical production equipment, typically enforcing work-in-process tracking, quality event management, and equipment performance monitoring through ISA-95 functional hierarchies. Their primary industrial purpose centers on reducing work-order cycle times while enforcing genealogical traceability for regulated output. Cloud-based deployments capture expanding margin pools as pharmaceutical end users in India and Australia prioritize elastic capacity scaling over capital-intensive on-premise installations. Discrete manufacturing segments sustain higher customization intensity, with automotive original equipment manufacturers demanding AI Analytics integration for predictive defect interdiction at weld and paint stations.
China's MIIT, Japan's METI, and Australia's TGA collectively shape MES demand through divergent compliance architectures spanning cybersecurity classification, energy efficiency benchmarking, and pharmaceutical batch record integrity. Japan's JIS standards for manufacturing data interoperability create incremental specification burdens that favor vendors with proven multi-protocol integration stacks. Stakeholders must weigh sovereign data localization mandates against the operational agility of multi-tenant cloud architectures when configuring regional deployment strategies.
Market Dynamics
China's MIIT cybersecurity standards for industrial software are forcing vendors to harden cloud-native architectures and restructure deployment models across the Asia Pacific MES landscape. This regulatory pressure compounds with wafer-to-wafer traceability mandates in South Korean semiconductor clusters to reshape competitive positioning.
Growth Catalysts
- Automotive Quality Protocols:Japanese and South Korean OEMs are accelerating MES adoption to synchronize assembly lines with real-time defect interdiction at weld and paint stations.
- MIIT Cybersecurity Classification:China's mandatory industrial software security tiers compel vendors to invest in hardened cloud architectures, expanding addressable market for compliant solutions.
- Semiconductor Traceability Mandates:Wafer-to-wafer genealogy requirements in South Korean fabrication clusters drive advanced MES deployments with sub-second data granularity.
Market Restraints
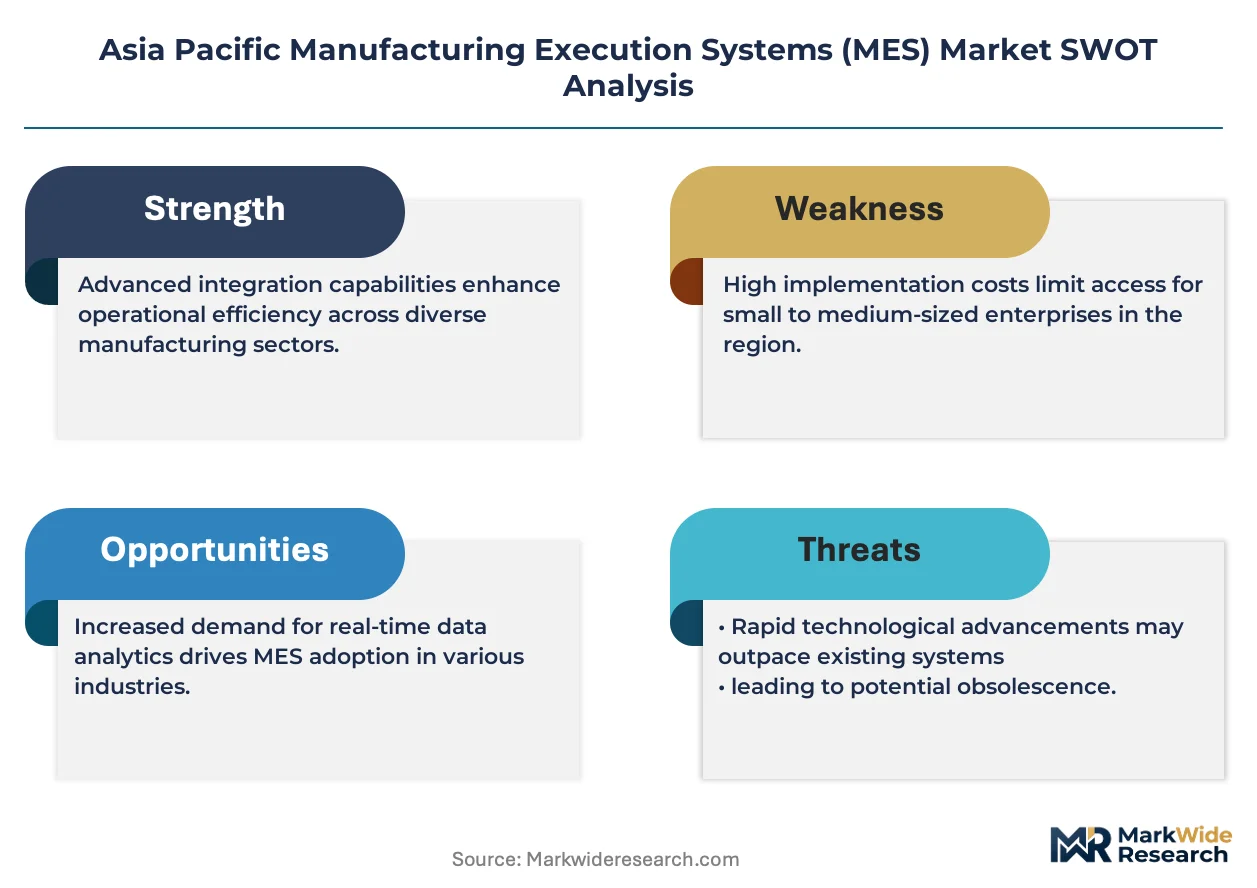
- Legacy Integration Costs:Brownfield facilities in Japan and Australia face prohibitive capital requirements to bridge ISA-95 hierarchies with cloud-native data pipelines.
- Skill Concentration:MES implementation expertise concentrates in Shanghai, Seoul, and Tokyo, creating 40-60% labor cost premiums for projects in secondary manufacturing hubs.
- Data Localization Friction:Australia's TGA batch record integrity requirements and China's MIIT cross-border data rules fragment multi-tenant cloud architectures into jurisdiction-specific instances.
Strategic Opportunities
- Indian Pharmaceutical Elasticity:CDSCO-regulated facilities in Hyderabad and Ahmedabad prioritize subscription-based MES over capital-intensive on-premise installations, opening SaaS margin pools.
- AI Analytics Convergence:Predictive quality algorithms fused with edge-native data pipelines enable real-time defect interdiction for automotive OEMs without cloud latency penalties.
- Australian Sustainability Integration:TGA and energy efficiency benchmarking create demand for MES modules that correlate batch records with carbon intensity per unit output.
Industry Challenges
- Multi-Protocol Integration Complexity:Japan's JIS standards for manufacturing data interoperability impose specification burdens that strain vendor engineering capacity and extend deployment timelines.
- Cybersecurity Certification Timelines:MIIT security classification reviews for industrial software extend sales cycles by 6-12 months for foreign vendors seeking Chinese market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Manufacturing Execution Systems (MES) Market |
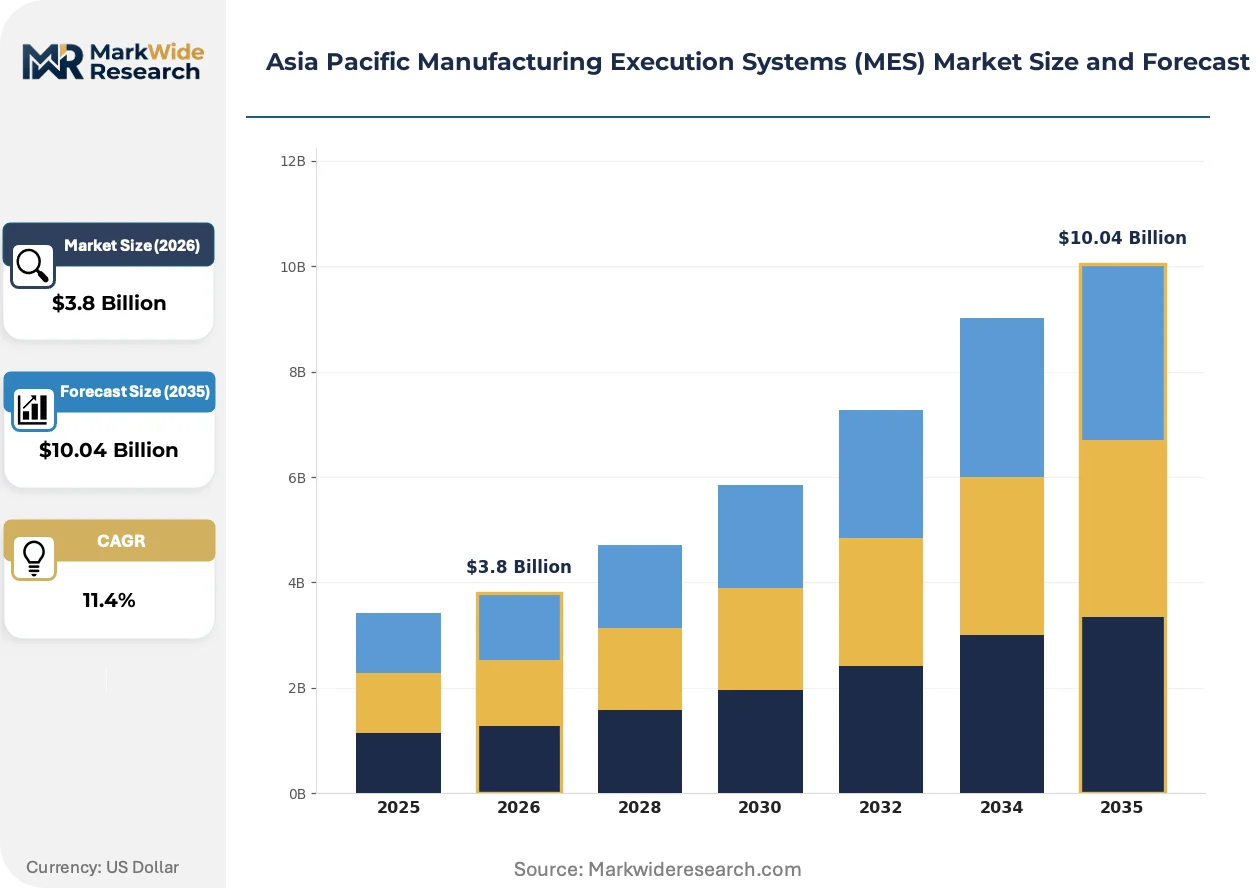
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Managed End User: Discrete Manufacturing, Process Manufacturing, Automotive Industry, Pharmaceutical Deployment: Public Cloud, Private Cloud, On-Premises, Multi-Tenant Technology: IoT Integration, AI Analytics, Big Data, Edge Computing |
| Companies Covered | Schneider Electric, Rockwell Automation, Yokogawa Electric Corporation, ABB, Honeywell International Inc., Siemens, SAP SE, Cerexio, Dassault Systèmes, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Manufacturing Execution Systems (MES) Market Strategic Shifts
Cloud-native specification tiers are bifurcating competitive dynamics as pharmaceutical and automotive end-users diverge in their architectural preferences. Three distinct vectors are reshaping how MES capabilities are packaged, deployed, and monetized across the region.
Edge-native data pipelines are bifurcating the MES architecture market. These distributed processing layers execute quality algorithms and equipment control within 10-millisecond latency envelopes. Semiconductor fabricators in South Korea and Taiwan are adopting them at accelerated pace to bypass cloud round-trip delays for wafer handling robotics. The technology is bifurcating vendor revenue models away from perpetual licenses toward capacity-based consumption metering tied to edge node activation.
METI's 2023 amendments to Japan's Industrial Cybersecurity Framework impose mandatory security-by-design certification for manufacturing software handling critical infrastructure data. The regulation mandates third-party penetration testing and source code audit trails for vendors serving automotive and chemical sectors. Pharmaceutical exporters to Japan are responding by embedding JIS-compliant data interoperability modules into their MES configurations to preempt customs documentation friction.
Automotive OEM procurement patterns are compressing MES vendor selection cycles from 18-month RFP processes to 6-month pilot-to-production mandates. Tier-1 suppliers in Thailand and Indonesia are displacing traditional systems integrator channels with direct vendor relationships to accelerate AI analytics integration. This behavioral shift is most visible in Bangkok and Jakarta manufacturing corridors, where Chinese MES vendors are capturing share through rapid deployment guarantees and Mandarin-speaking implementation teams.
Asia Pacific Manufacturing Execution Systems (MES) Market Segmentation
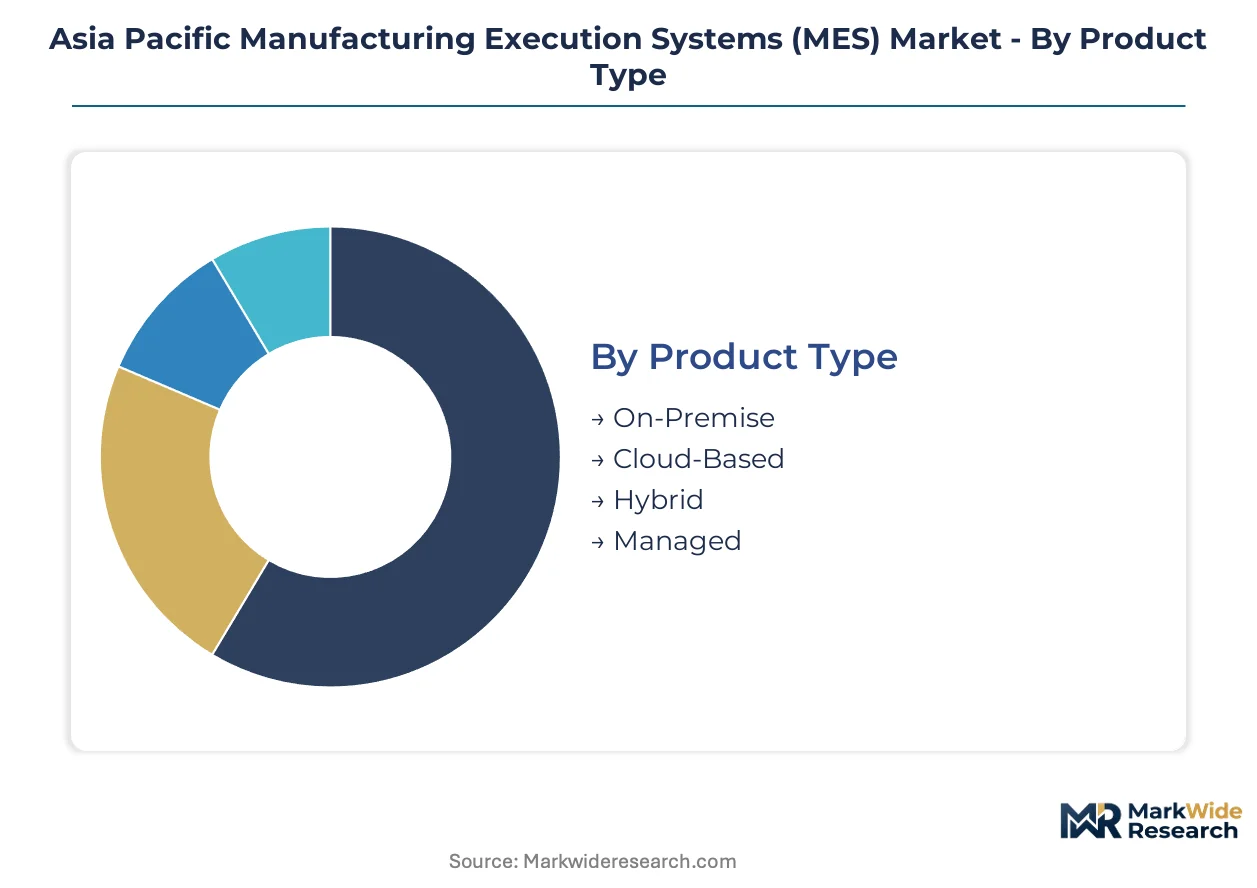
MES procurement patterns across Asia Pacific diverge sharply by deployment architecture and regulatory exposure. Pharmaceutical facilities in India and Australia prioritize elastic capacity models, while South Korean semiconductor clusters demand sub-millisecond latency envelopes that reshape technology selection.
Product Type:
Channel flows bifurcate between capital-intensive perpetual licenses and subscription-based consumption models, with systems integrators dominating on-premise deployments while direct vendor relationships capture cloud-native expansion.
- On-Premise:Perpetual license architectures with dedicated hardware stacks enforce ISA-95 hierarchies in brownfield Japanese automotive plants. MIIT cybersecurity classification timelines extend sales cycles for foreign vendors serving Chinese state-owned chemical facilities, entrenching incumbent domestic suppliers.
- Cloud-Based:Multi-tenant SaaS architectures enable elastic capacity scaling for CDSCO-regulated pharmaceutical manufacturers in Hyderabad and Ahmedabad. Australia's TGA batch record integrity requirements fragment multi-tenant instances into jurisdiction-specific deployments, eroding margin efficiency.
- Hybrid:Bridged architectures partition quality-critical workloads on-premise while offloading analytics to cloud tiers.
- Managed:Outsourced operational responsibility models concentrate in Thailand and Indonesia where MES implementation expertise scarcity drives 40-60% labor cost premiums.
On-Premise dominates installed base. Cloud-Based is where expansion concentrates.
End User:
Cost tier stratification separates premium AI-integrated deployments from standardized work-in-process tracking configurations.
- Discrete Manufacturing:Automotive OEMs in Japan and South Korea demand AI Analytics integration for predictive defect interdiction at weld and paint stations. JIS standards for manufacturing data interoperability impose specification burdens that extend deployment timelines for foreign vendors.
- Process Manufacturing:Chemical and pharmaceutical facilities prioritize genealogical traceability modules with ISA-95 Level 3 enforcement. China's MIIT cybersecurity standards compel hardened cloud-native architectures, expanding addressable market for compliant solutions.
- Automotive Industry:Tier-1 suppliers in Bangkok and Jakarta manufacturing corridors compress vendor selection cycles from 18-month RFP processes to 6-month pilot-to-production mandates.
- Pharmaceutical:TGA-regulated Australian exporters embed JIS-compliant data interoperability modules to preempt customs documentation friction.
Process Manufacturing anchors revenue concentration. Discrete Manufacturing is climbing the fastest.
Deployment:
Volume distribution skews toward private infrastructure where data localization mandates fragment multi-tenant architectures.
- Public Cloud:Shared infrastructure models face structural headwinds from Australia's TGA cross-border data restrictions and China's MIIT cybersecurity classification tiers.
- Private Cloud:Dedicated single-tenant instances capture pharmaceutical demand in India and Australia where elastic capacity scaling outweighs capital efficiency tradeoffs.
- On-Premises:Captive infrastructure sustains dominance in South Korean semiconductor fabrication clusters where wafer-to-wafer traceability mandates require sub-second data granularity.
- Multi-Tenant:Shared logical partitions concentrate in secondary manufacturing hubs where cost sensitivity overrides sovereignty concerns.
On-Premises sustains majority share. Private Cloud is gaining share fastest.
Technology:
Margin concentration follows edge-native processing layers that bypass cloud round-trip delays for latency-critical applications.
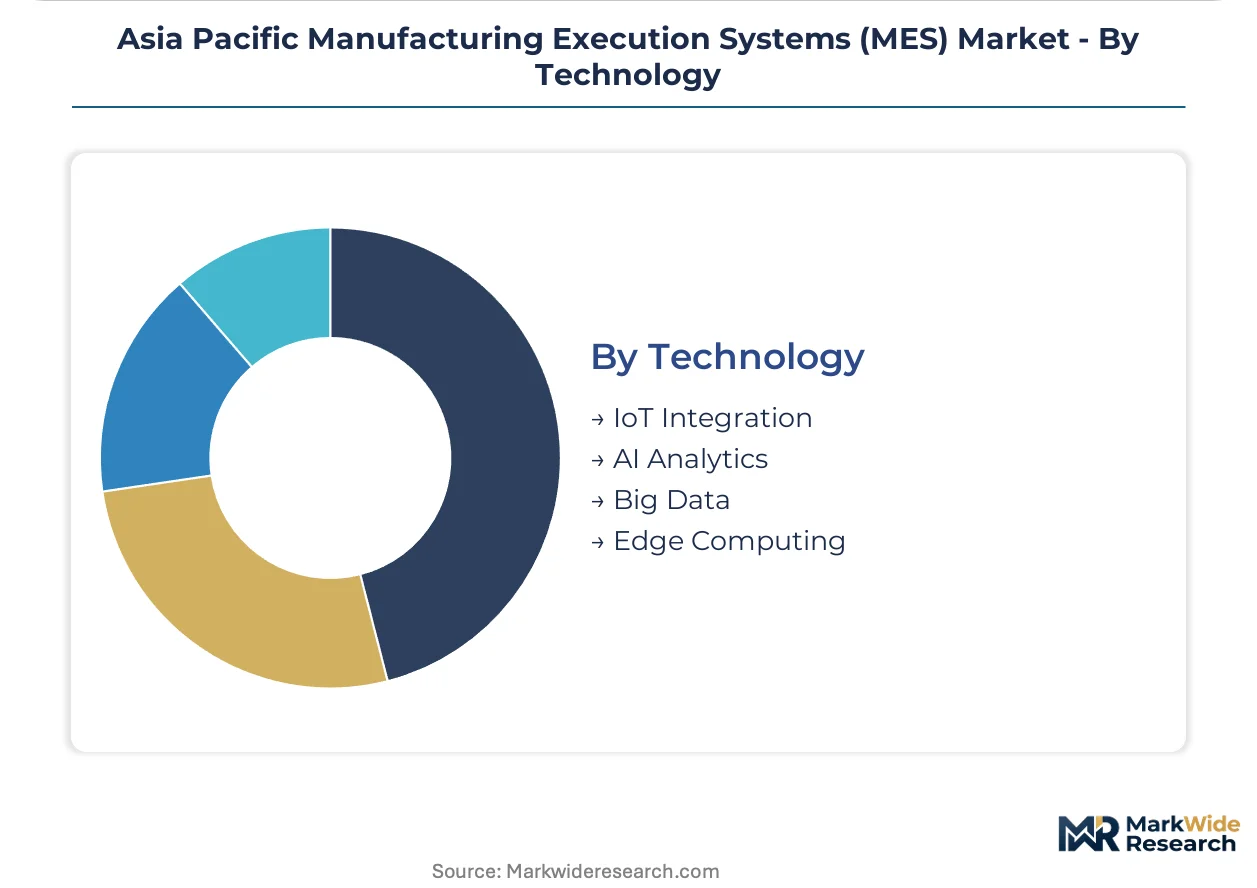
- IoT Integration:Sensor-to-system data pipelines enable equipment performance monitoring across ISA-95 functional hierarchies.
- AI Analytics:Predictive quality algorithms fused with edge-native data pipelines execute real-time defect interdiction without cloud latency penalties. Automotive OEM procurement patterns favor vendors with rapid deployment guarantees and Mandarin-speaking implementation teams.
- Big Data:Historical batch record warehousing correlates carbon intensity per unit output for Australian sustainability-integrated MES modules.
- Edge Computing:Distributed processing layers execute quality algorithms within 10-millisecond latency envelopes. South Korean and Taiwanese semiconductor fabricators adopt these at accelerated pace to bypass cloud delays for wafer handling robotics.
IoT Integration anchors installed base. Edge Computing is where vendor R&D concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing hubs across Asia Pacific drive MES adoption to maintain quality certifications for international markets. Import-dependent economies prioritize traceability modules that satisfy foreign regulatory scrutiny. Regional deployment patterns diverge sharply between sovereign data mandates and operational agility requirements.
China
State-owned chemical facilities and automotive joint ventures anchor domestic demand. MIIT cybersecurity classification tiers compel hardened cloud-native architectures from foreign vendors. Shanghai and Yangtze River Delta manufacturing clusters concentrate implementation expertise and sustain premium labor cost structures.
Japan
Automotive OEMs and precision machinery producers enforce JIS-compliant data interoperability standards. METI's 2023 Industrial Cybersecurity Framework amendments mandate third-party penetration testing for manufacturing software. Kanto and Chubu industrial corridors concentrate brownfield facilities facing legacy integration cost pressures.
South Korea
Semiconductor fabricators in Busan-Ulsan and Seoul Capital Area drive sub-millisecond latency requirements. Wafer-to-wafer genealogy mandates from the national semiconductor regulator shape vendor selection criteria. Samsung and SK Hynix supplier ecosystems propagate advanced MES specifications across the fabrication cluster.
India
CDSCO-regulated pharmaceutical manufacturers in Hyderabad and Ahmedabad prioritize subscription-based deployments over capital-intensive installations. Active pharmaceutical ingredient exporters embed traceability modules to satisfy US FDA and EMA inspection protocols. Implementation expertise scarcity in secondary hubs creates 40-60% labor cost premiums.
Australia
TGA batch record integrity requirements fragment multi-tenant cloud architectures into jurisdiction-specific instances. Energy efficiency benchmarking correlates carbon intensity per unit output with sustainability-integrated MES modules. Victorian and New South Wales pharmaceutical exporters preempt customs documentation friction through JIS-compliant data interoperability configurations.
Asia Pacific Manufacturing Execution Systems (MES) Market Competitive Environment
Listed leaders compete with private specialists across cloud-native specification tiers and legacy integration capabilities. The vendor base segments into three strategic archetypes: diversified industrial conglomerates with energy management heritage, pure-play automation specialists with deep domain expertise, and emerging SaaS-native challengers with rapid deployment guarantees. Competitive positioning hardens around MIIT cybersecurity certification timelines and JIS standards compliance rather than raw feature differentiation.
Within the diversified industrial tier, Schneider Electric and Siemens occupy positions that exemplify sustainability-integrated shop floor control and premium process manufacturing deployments respectively. Yokogawa Electric Corporation represents the hybrid architecture specialist archetype, bridging legacy on-premise systems with edge-native data pipelines for latency-critical applications.
| Leading Market Players |
|---|
| Schneider Electric |
| Rockwell Automation |
| Yokogawa Electric Corporation |
| ABB |
| Honeywell International Inc. |
| Siemens |
| SAP SE |
| Cerexio |
| Dassault Systèmes |
| Others |
Value Chain & Pricing Dynamics
Edge-native data pipelines substituting for centralized cloud architectures are redrawing procurement geography across the Asia Pacific MES landscape. This substitution simultaneously compresses latency-sensitive deployments into Seoul-Busan and Taipei semiconductor corridors while fragmenting pricing power away from perpetual-license incumbents toward consumption-metering specialists.
Pricing Analysis
Industrial OEM buyers anchor a bifurcated pricing structure where automotive manufacturers absorb premium tiers for AI-integrated defect interdiction while pharmaceutical facilities in secondary hubs gravitate toward subscription elasticity. Three-tier pricing stratifies across MIIT-certified premium deployments, JIS-compliant standard configurations, and economy SaaS tiers for Indian CDSCO-regulated sites. Cost compression in the economy tier intensifies as Chinese vendors with Mandarin-speaking implementation teams undercut foreign incumbents on deployment velocity. Tier-1 automotive suppliers exhibit lowest price sensitivity; secondary manufacturing hubs in Thailand and Indonesia demonstrate highest elasticity.
Supply Chain Analysis
Inventory lead times for edge computing hardware stretch 12-16 weeks, tethering deployment schedules to Taiwanese semiconductor foundry output cycles. MES software supply concentrates in Germany, Japan, and the United States, with implementation services drawing from Shanghai, Seoul, and Tokyo talent pools. Single-source vulnerability permeates the edge node component layer where South Korean memory suppliers dominate. Distribution runs through direct vendor relationships displacing traditional systems integrator channels in Southeast Asian manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific MES market rewards vendors who command scarce implementation expertise in MIIT cybersecurity certification and JIS data interoperability protocols. This capability scarcity penalizes foreign entrants facing 6-12 month extended sales cycles in China and specification-burdened deployment timelines in Japan.
For Market Incumbents: Fortify certification moats by accelerating MIIT security classification reviews and embedding JIS-compliant interoperability modules as standard configurations. Siemens and Yokogawa Electric Corporation should deepen captive supply of Mandarin-speaking implementation teams to defend against Chinese SaaS-native challengers capturing share through rapid deployment guarantees in Bangkok and Jakarta corridors. For New Entrants and Emerging Players: Post-implementation support gaps in brownfield Japanese automotive plants present white-space targets where legacy integration expertise commands 40-60% labor cost premiums. CDSCO-regulated pharmaceutical facilities in Ahmedabad and Hyderabad offer the most penetrable segment given their prioritization of subscription elasticity over capital-intensive installations. A channel partnership strategy with regional systems integrators accelerates market access without bearing full implementation burden. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors acquisition targets with pre-certified cybersecurity architectures and established edge-native data pipeline deployments. Long-term viability over a multi-year horizon hinges on cloud-native specification tier dominance. The signal to watch is MIIT cybersecurity classification timeline compression for foreign vendors, which would erode incumbent certification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Cybersecurity Certification Acceleration | Preemptive certification investment unlocks Chinese state-owned chemical facility procurement pipelines before competitors complete review cycles. |
| Edge-Native Data Pipeline Development | Sub-10 millisecond latency execution captures South Korean semiconductor fabricator demand bypassing cloud round-trip delays. |
| JIS-Compliant Interoperability Module Embedding | Standardized data format compatibility preempts customs documentation friction for Australian pharmaceutical exporters serving Japanese markets. |
| Mandarin-Speaking Implementation Team Expansion | Localized deployment expertise neutralizes Chinese vendor advantages in Southeast Asian manufacturing corridor capture. |
| Subscription-Based SaaS Tier Introduction | Elastic capacity models align with CDSCO-regulated Indian pharmaceutical facility procurement preferences over perpetual licenses. |
Study Parameters
Desk research of regulatory filings from MIIT, METI, CDSCO and TGA preceded structured interviews with MES platform engineers, automotive Tier-1 procurement directors, pharmaceutical manufacturing IT leads, and semiconductor fabrication operations managers. Secondary validation drew from ISA-95 technical documentation, industrial cybersecurity framework amendments, and customs trade data for manufacturing software imports. Bottom-up segmentation modeling triangulated against top-down market sizing across deployment architecture, end-use vertical, and regional regulatory cluster dimensions.
Analytical variance decomposes across cloud-native versus on-premise deployment splits, AI analytics integration intensity, and edge computing penetration rates by semiconductor fabrication cluster. Modeled segmentation spans product type, end user industry, deployment infrastructure, and technology layer including IoT integration and predictive quality algorithms. CAGRs derive from regression against industrial software investment cycles and regulatory compliance timeline acceleration. Forecast inputs incorporate MIIT cybersecurity classification backlog estimates and JIS standards amendment implementation schedules.
Material uncertainties — MIIT regulatory timeline volatility, JIS interoperability specification revisions, and edge hardware supply disruption — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification completion rates and talent pool expansion in secondary manufacturing hubs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Operational Technology Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Utility Automation Market
Industrial Automation
Industrial Fieldbus Solution Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
Digital Rotator Market
Industrial Automation
Multi-Axis Motion Controller Market
Industrial Automation
Connected Worker Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Distribution Feeder Automation Market