
 Tilt Tray Sorter Market | 2026-2036
Tilt Tray Sorter Market Size, Share, and Industry Trends Forecast 2026-2036
Tilt Tray Sorter Market Analytics
European conveyor systems manufacturing is hardening as logistics automation investments accelerate across the continent. Vanderlande leverages its airport baggage and parcel handling heritage to sustain technology leadership in high-throughput tilt tray configurations. Daifuku anchors its position through deep integration with parent-company steel fabrication and control systems capabilities. Eurosort specializes in compact, modular designs that compete effectively in space-constrained European distribution centers.
A tilt tray sorter is a loop-based conveyor system employing individual pivoting trays that deposit items into designated chutes or destinations, typically operating at speeds exceeding 2.5 meters per second and handling items ranging from envelopes to parcels up to 50 kilograms. The equipment serves primary commercial purposes in parcel distribution hubs, e-commerce fulfillment centers, and airport baggage handling operations where high-volume sortation accuracy exceeds 99.5%. Automated tilt tray systems dominate capacity installations across the logistics end user segment, while AI-Based technology integration represents the fastest-growing configuration as machine vision and predictive routing algorithms reduce mis-sort rates and enable dynamic destination assignment. Small Scale and Medium Scale capacity categories occupy the broadest addressable market, though Enterprise-scale deployments command concentrated margin pools due to complex system integration requirements and long-term service contracts.
The EU Machinery Directive and CE marking framework mandate functional safety standards and electromagnetic compatibility for automated sortation equipment entering European markets, effectively raising engineering barriers for non-compliant suppliers. Germany's KBA and national workplace safety regulators enforce supplementary operational certifications for systems deployed in automotive and pharmaceutical logistics environments. Stakeholders must monitor evolving EU AI Act provisions governing automated decision systems, as future sortation algorithms incorporating machine learning may face conformity assessment requirements that reshape product development roadmaps and vendor qualification criteria.
Market Dynamics
E-commerce fulfillment centers are compressing sortation windows as parcel volumes surge beyond legacy capacity, forcing infrastructure decisions toward high-throughput automation. The EU Machinery Directive and CE marking requirements are tightening safety and interoperability standards, raising engineering barriers for equipment suppliers seeking European market entry.
Growth Catalysts
- CE Marking Mandate:The EU Machinery Directive's functional safety requirements are accelerating replacement cycles for non-compliant legacy systems across German logistics hubs and automotive parts distribution networks.
- Machine Vision Integration:AI-based sortation configurations incorporating predictive routing algorithms are reducing mis-sort rates below 0.5% in high-volume parcel distribution environments.
- Netherlands Parcel Hub Concentration:Rotterdam and Amsterdam distribution corridors are driving enterprise-scale tilt tray installations as European e-commerce fulfillment gravity shifts toward Benelux logistics infrastructure.
Market Restraints
- Steel Input Volatility:Sortation system fabricators face margin compression from fluctuating hot-rolled steel prices, with Daifuku's captive steel production providing insulation unavailable to modular specialists.
- Control Systems Supplier Concentration:Proprietary PLC and servo drive architectures from a limited German and Japanese vendor base create integration bottlenecks for non-vertically integrated installers.
- Electromagnetic Compatibility Certification:CE marking's EMC testing requirements add 4-6 month pre-market timelines, disadvantaging smaller European manufacturers against established airport baggage handling heritage players.
Strategic Opportunities
- Polish E-commerce Fulfillment:Underpenetrated Central European distribution center construction is creating greenfield demand for compact modular tilt tray configurations optimized for space-constrained Warsaw and Krakow facilities.
- EU AI Act Conformity Pathway:Early alignment with automated decision system assessment frameworks positions vendors to capture premium pricing for machine learning-enabled sortation algorithms as regulatory clarity emerges.
- Pharmaceutical Cold Chain Convergence:Integration of temperature-controlled tray designs with track-and-trace serialization requirements opens specialized installations in Belgian and Dutch pharmaceutical logistics corridors.
Industry Challenges
- Mechatronics Talent Scarcity:German KBA certification requirements for system commissioning engineers exceed available qualified personnel, extending deployment timelines for complex automotive sector installations.
- Legacy Warehouse Management System Integration:Proprietary communication protocols in existing European distribution centers force costly middleware development for tilt tray control system interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tilt Tray Sorter Market |
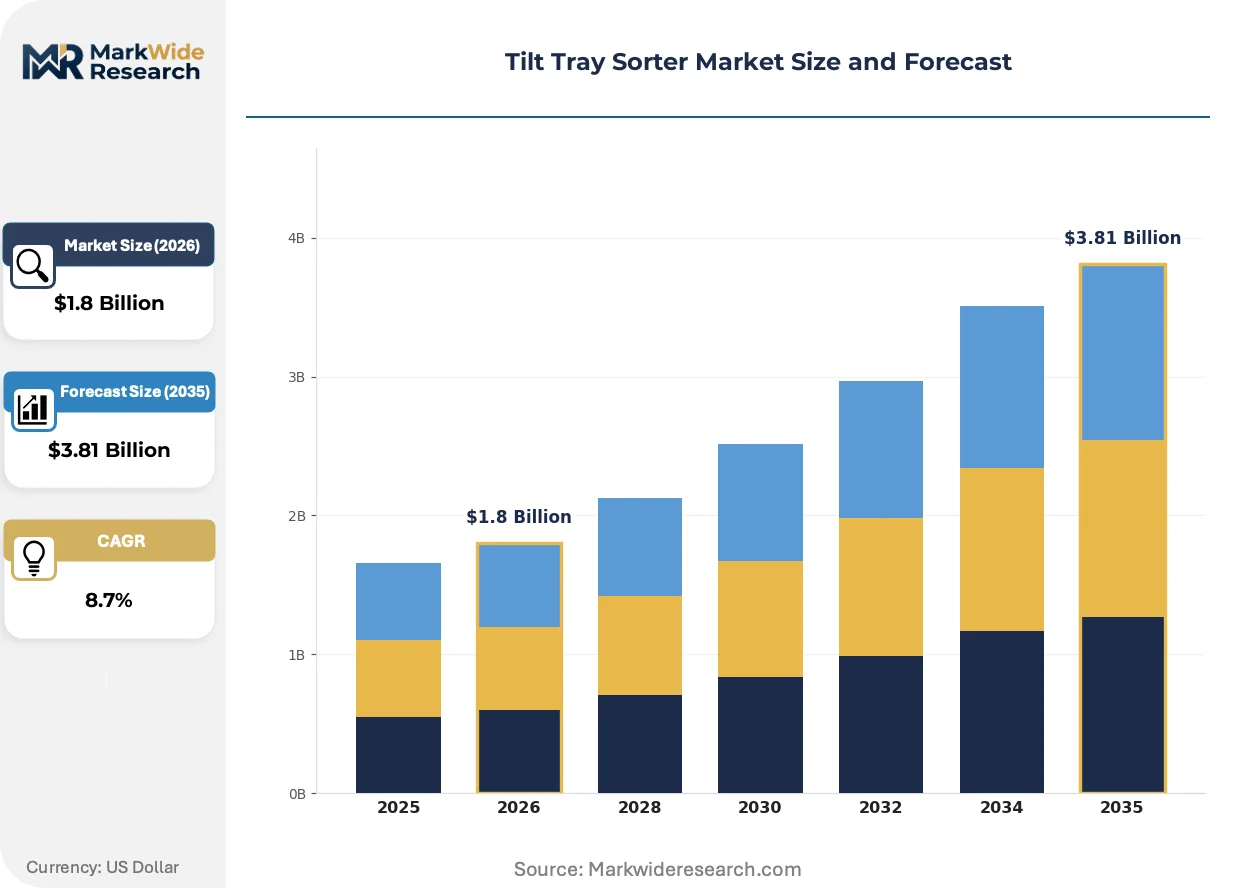
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Automated, Semi-Automated, Manual, Hybrid End User: E-Commerce, Logistics, Retail, Manufacturing Technology: Optical Scanning, RFID, Barcode, AI-Based Capacity: Small Scale, Medium Scale, Large Scale, Enterprise |
| Companies Covered | Inther Group, Eurosort, Vanderlande, Dematic, Beumer Group, Daifuku, TOYO KANETSU, TGW Logistics Group, GBI Intralogistics Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tilt Tray Sorter Market Evolving Landscape
Machine learning is penetrating sortation control architectures, compressing decision latency from centralized PLC hierarchies toward edge-computing node distributions. Three distinct vectors are restructuring competitive positioning.
Edge-based inference engines are decentralizing routing authority from master controllers to individual tray-mounted processing units. E-commerce fulfillment centers with volatile SKU mixes are adopting these architectures fastest. This topology is decentralizing system design away from monolithic control cabinets toward distributed intelligence networks that reduce single-point failure exposure.
REACH substance restrictions and RoHS recast directives are eliminating specific flame retardants and heavy metals from printed circuit board assemblies used in tray electronics. Industrial consequence includes accelerated qualification cycles for alternative solder alloys and conformal coatings. Airport baggage handling OEMs with established aerospace supply chain relationships are adapting existing material libraries faster than parcel-focused competitors.
Performance-based maintenance contracting is displacing traditional time-and-materials service agreements in German automotive parts distribution networks. Tier-1 logistics providers are unbundling equipment ownership from operational responsibility, transferring uptime risk to OEM service organizations. This restructuring is most visible in Bavarian and Baden-Württemberg automotive supplier clusters where just-in-sequence delivery penalties exceed equipment capital costs.
Tilt Tray Sorter Market Segmentation
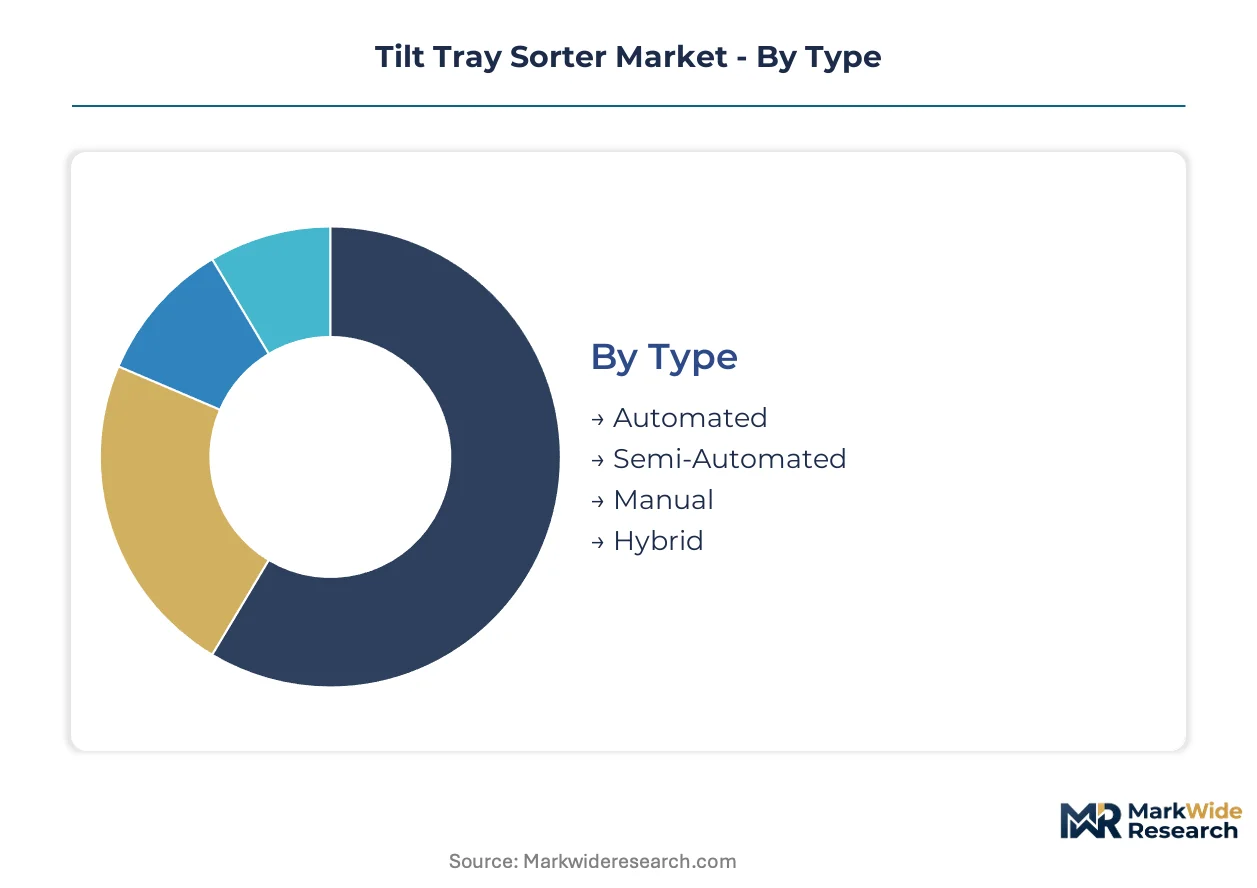
Tilt tray sorter procurement decisions hinge on integration depth with existing warehouse management architectures. System configurations range from standalone modular units to fully embedded enterprise networks, with each tier demanding distinct engineering specifications and commissioning protocols.
Type:
Standalone installations dominate greenfield e-commerce fulfillment centers, while embedded configurations prevail in automotive parts distribution networks requiring seamless ERP integration.
- Automated:Loop-based conveyor architectures with individual pivoting trays operate at speeds exceeding 2.5 meters per second, handling parcels up to 50 kilograms. German logistics hubs and airport baggage operations in Amsterdam and Frankfurt drive concentrated demand as labor costs and throughput requirements escalate simultaneously.
- Hybrid:Configurations blending automated tray mechanisms with manual induction stations reduce capital intensity for mid-volume operations. Polish and Czech distribution centers favor this architecture where parcel volumes fluctuate seasonally and full automation cannot be justified.
- Semi-Automated:Systems requiring operator intervention for exception handling occupy retrofit installations where legacy infrastructure constrains full automation.
- Manual:Basic tilt tray configurations with human-powered sorting functions persist in small-scale retail backrooms and micro-fulfillment centers.
Volume placements concentrate in Automated; the faster expansion belongs to Hybrid.
End User:
Cost tier stratification separates high-throughput parcel hubs from precision manufacturing applications, with pricing scaling nonlinearly against system complexity and integration requirements.
- Logistics:Parcel distribution hubs and third-party logistics providers deploy enterprise-scale installations exceeding 10,000 trays per system. Rotterdam and Amsterdam corridor investments are accelerating as European e-commerce gravity shifts toward Benelux infrastructure.
- E-Commerce:Fulfillment centers with volatile SKU mixes and compressed delivery windows demand AI-enabled configurations with predictive routing algorithms. Belgian pharmaceutical e-commerce operations are emerging as a specialized sub-segment requiring temperature-controlled tray designs.
- Retail:Store replenishment and omnichannel fulfillment operations favor compact modular systems for space-constrained urban distribution centers.
- Manufacturing:Automotive parts distribution in Bavaria and Baden-Württemberg requires just-in-sequence precision, with KBA certification mandates extending deployment timelines.
Margin pools concentrate in Logistics; E-Commerce climbs the fastest.
Technology:
Application maturity varies sharply across identification methods, with optical and barcode systems representing installed base dominance while AI architectures capture greenfield specification share.
- AI-Based:Machine vision and predictive routing algorithms reduce mis-sort rates below 0.5% through dynamic destination assignment. E-commerce fulfillment centers with volatile SKU mixes are adopting these configurations fastest as the EU AI Act conformity pathway clarifies.
- Optical Scanning:Camera-based parcel dimensioning and label recognition systems provide proven reliability in high-speed airport baggage handling operations. Established aerospace supply chain relationships accelerate material qualification cycles under REACH and RoHS recast directives.
- Barcode:Laser scanning systems remain cost-effective for standardized parcel formats in legacy logistics infrastructure.
- RFID:Radio-frequency identification enables non-line-of-sight tracking for pharmaceutical serialization and high-value goods authentication.
Technology transitions favor AI-Based for new specifications; Optical Scanning defends replacement demand.
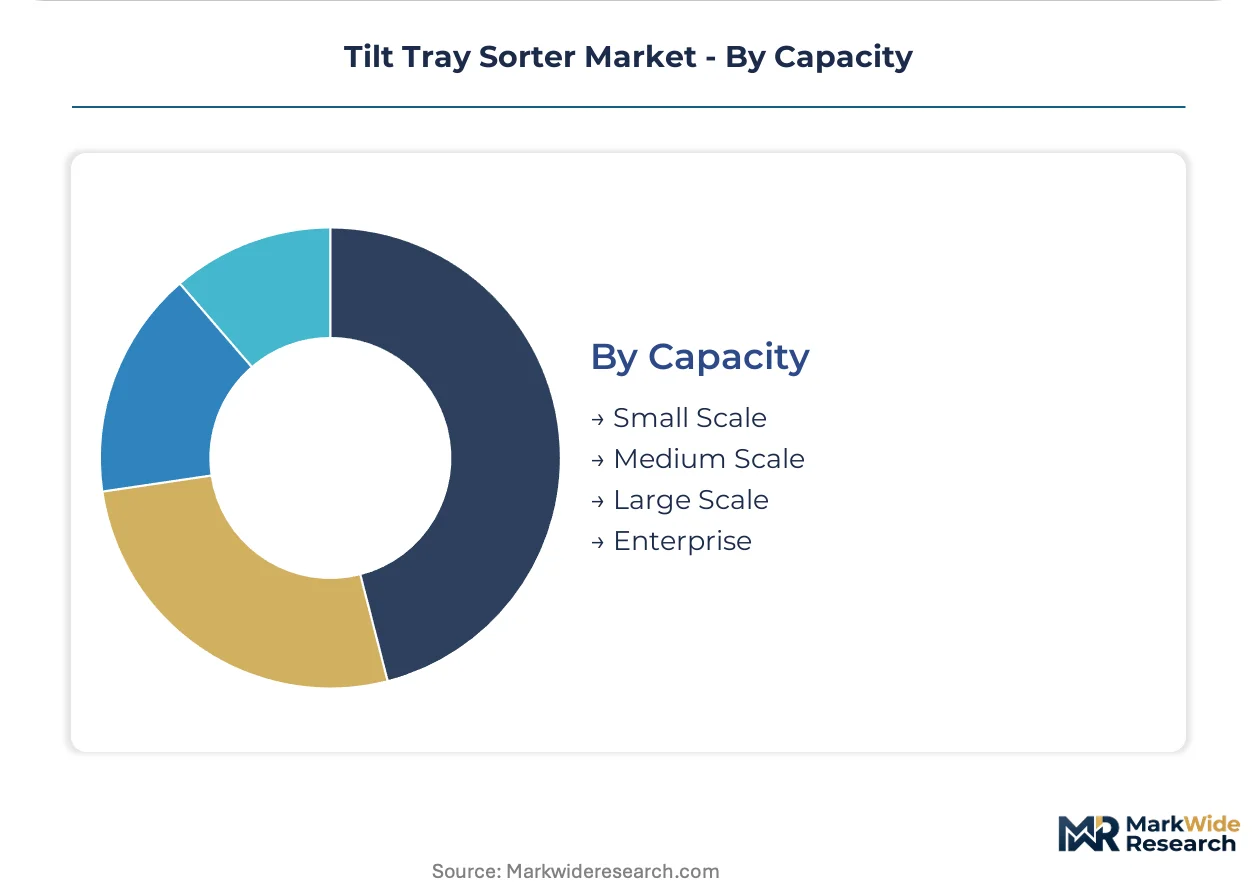
Capacity:
Customer type segmentation separates asset-light operators from capital-intensive owners, with service contracting models diverging sharply across scale tiers.
- Enterprise:Systems exceeding 15,000 trays with redundant control architectures command concentrated margin pools through complex integration requirements and long-term service contracts. German automotive parts distribution networks are unbundling equipment ownership from operational responsibility, transferring uptime risk to OEM service organizations.
- Medium Scale:Configurations between 5,000 and 15,000 trays occupy the broadest addressable market, serving regional parcel hubs and large retail distribution centers. Eurosort specializes in compact designs that compete effectively in space-constrained European facilities.
- Small Scale:Modular systems under 5,000 trays target micro-fulfillment centers and pharmaceutical cold chain operations in Belgian and Dutch corridors.
- Large Scale:Mid-tier installations bridge enterprise and medium configurations, often serving as expansion modules for growing logistics networks.
Service revenue concentrates in Enterprise; Medium Scale captures the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hot-rolled steel from German mills anchors European tilt tray fabrication, with Ruhr Valley foundries supplying structural components to logistics automation clusters across the continent.
Germany
Automotive parts distribution networks in Bavaria and Baden-Württemberg drive enterprise-scale installations exceeding 15,000 trays. KBA certification mandates extend deployment timelines for just-in-sequence delivery systems. Frankfurt and Hamburg logistics corridors concentrate maintenance contracting activity as tier-1 providers unbundle equipment ownership from operational responsibility.
Netherlands
Rotterdam and Amsterdam distribution corridors accelerate Benelux infrastructure investment as European e-commerce gravity shifts toward these ports. REACH substance restrictions eliminate specific flame retardants from tray electronics, forcing accelerated qualification cycles for alternative solder alloys. Eindhoven Region hosts compact modular system deployments optimized for space-constrained pharmaceutical cold chain operations.
Poland
Underpenetrated Central European distribution center construction creates greenfield demand for mid-scale configurations in Warsaw and Krakow facilities. EU Machinery Directive CE marking requirements raise engineering barriers for non-compliant equipment entering these markets. Silesian logistics parks attract hybrid system architectures where seasonal parcel volume fluctuations justify blended automation approaches.
Belgium
Pharmaceutical serialization requirements converge with temperature-controlled tray designs in Belgian logistics corridors. RoHS recast directives eliminate heavy metals from printed circuit board assemblies used in sortation controls. Antwerp and Brussels distribution hubs specialize in small-scale modular installations serving micro-fulfillment networks.
United Kingdom
Post-Brexit customs processing complexity drives sortation automation at Dover and Felixstowe port facilities. The country's national workplace safety regulators enforce supplementary operational certifications for systems deployed in pharmaceutical logistics environments. Midlands distribution clusters favor retrofit installations where legacy warehouse management system integration constrains full automation.
Tilt Tray Sorter Market Competitive Landscape
Global majors compete with regional champions across control system architectures and service contracting models. The vendor base separates into three tiers: integrated steel-and-systems conglomerates, modular fabrication specialists, and airport heritage baggage handling players. Two strategic archetypes dominate competitive positioning: vertically integrated fabricators leveraging captive material supply, and compact-system specialists exploiting space-constrained facility demand. Capacity expansion and performance-based maintenance contracting represent the dominant competitive moves reshaping vendor relationships.
Within the airport heritage tier, Vanderlande occupies a position exemplifying high-throughput baggage and parcel handling expertise. Eurosort represents the compact modular specialist archetype competing effectively in space-constrained European distribution centers. Daifuku anchors the integrated conglomerate segment through backward integration into steel fabrication and control systems capabilities.
| Leading Market Players |
|---|
| Inther Group |
| Eurosort |
| Vanderlande |
| Dematic |
| Beumer Group |
| Daifuku |
| TOYO KANETSU |
| TGW Logistics Group |
| GBI Intralogistics Solutions |
| Others |
Value Network & Pricing Analysis
Hot-rolled steel price indices from German Ruhr Valley mills cascade through tilt tray sorter fabrication into three-tier pricing structures across premium, standard, and economy levels. CE marking compliance costs and captive steel supply capabilities separate vendor pricing power across European logistics automation procurement.
Pricing Analysis
Warranty and performance-based maintenance bundling distinguishes enterprise-tier vendor pricing from unbundled equipment-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects KBA certification depth, control system redundancy, and steel fabrication sourcing. Cost compression in mid-scale configurations is intensifying because Eurosort and compact modular specialists exploit space-constrained facility demand. Third-party logistics providers show highest price sensitivity; German automotive networks demonstrate lowest due to just-in-sequence delivery penalty exposure.
Supply Chain Analysis
CE marking and KBA certification requirements gate component qualification, extending procurement cycles for non-heritage suppliers. Manufacturing concentrates in Germany, Netherlands, and Japan, with Ruhr Valley steel mills anchoring structural fabrication. Control systems draw from German and Japanese PLC architectures; tray electronics hinge on REACH-compliant solder alloys and conformal coatings. Single-source vulnerability concentrates in servo drive architectures. Distribution runs through OEM-direct and systems integrator channels serving logistics hub construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Machinery Directive creates a cost-of-compliance moat where CE marking investment barriers protect established European vendors against low-cost import competition. This regulatory architecture rewards early conformity alignment.
For Market Incumbents: To counter margin pressure from modular specialists, Daifuku and integrated conglomerates should exploit captive steel supply and control systems capabilities to compress delivery timelines. Capacity addition in Polish logistics corridors captures greenfield Central European demand. Certification investment in EU AI Act conformity pathways preserves premium positioning for machine learning-enabled configurations.
For New Entrants and Emerging Players: Capture underpenetrated pharmaceutical cold chain convergence in Belgian and Dutch corridors where temperature-controlled tray designs and serialization requirements favor specialized entrants. Compact modular configurations for Warsaw and Krakow distribution centers represent the most penetrable geography. Partner with local systems integrators possessing KBA-certified commissioning engineers to bypass talent scarcity bottlenecks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor airport heritage baggage handling players with established aerospace supply chain relationships and REACH-compliant material libraries. Long-term viability centers on service revenue unbundling from equipment ownership in German automotive networks. Watch EU AI Act implementing acts as the inflection signal for machine learning-enabled sortation algorithm premium pricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Maintenance Contracting | Transfers uptime risk to OEMs in Bavarian automotive supplier clusters. |
| EU AI Act Conformity Pathway Investment | Positions vendors for premium machine learning-enabled sortation pricing. |
| Compact Modular System Development | Exploits space-constrained demand in Warsaw and Krakow facilities. |
| Temperature-Controlled Tray Integration | Opens Belgian pharmaceutical serialization and cold chain installations. |
| Captive Steel Supply Expansion | Insulates Daifuku against hot-rolled steel price volatility hurting competitors. |
Research Methodology
Independent corroboration across OEM product managers, logistics automation procurement leads, systems integrator engineers, and aftermarket service heads underwrites the qualitative findings. Secondary validation draws from EU Machinery Directive implementation guidance, CE marking conformity assessment databases, German KBA certification registries, and SEC filings of publicly traded material handling equipment suppliers. Bottom-up installation data triangulates against top-down European logistics automation capex estimates.
Comparable-period anchoring to historical CE marking adoption cycles and e-commerce fulfillment construction waves shapes the projection horizon. The analytical framework models capacity scale tiers, technology configurations, end-user segments, and geographic regulatory clusters across the analysis window. CAGRs derive from segment-level shipment trajectories and average selling price evolution. Forecast inputs incorporate steel price index correlation and EU AI Act implementation timeline uncertainty.
The model holds under stable EU regulatory enforcement and continued e-commerce fulfillment gravity shift toward Benelux infrastructure; deviation in REACH substance restriction expansion or German KBA certification requirement tightening would shift vendor cost structures and deployment timelines. Forecasts reflect these base-condition assumptions with acknowledged sensitivity to steel input volatility and mechatronics talent availability. A model refresh is warranted upon material change in EU AI Act automated decision system assessment criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
South Korea Automation and Industrial Control Market
Industrial Automation
Automatic Screw Feeding System Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Motion Control Centers Market
Industrial Automation
Middle East and Africa Process Automation Market
Industrial Automation
Smart Elevator Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Conveyor-Free Sortation Modules Market
Industrial Automation
HMI Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Utility Automation Market