
 Electric Linear Actuator Market | 2026-2036
Electric Linear Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Linear Actuator Market Analysis
Market Context
Brushless DC motor integration with integrated drive electronics is tilting the technology stack toward compact, self-contained motion modules that reduce cabinet space and wiring complexity. LINAK A/S dominates the healthcare furniture segment with dedicated actuator lines for patient handling equipment. Festo Inc. leverages its pneumatic heritage to bridge fluid power and electromechanical platforms in process automation. Parker Hannifin Corporation anchors the heavy-industrial tier with high-force electromechanical cylinders rated beyond 50 kN for metal forming and press applications.
Technical Definition and Segment Structure
An electric linear actuator converts rotational energy from an electric motor into precise linear displacement through ball screw, roller screw, or belt-and-pulley mechanisms, typically delivering stroke lengths from 50 mm to over 2,000 mm with positioning repeatability of ±0.05 mm for industrial-grade units. The screw type segment commands the highest force-density applications in metalworking and injection molding, while belt type units capture the fastest growth in packaging and electronics assembly where speed exceeds load requirements. Rod type actuators retain mature volume in hydraulic replacement projects across agriculture and construction equipment, though margin pools are migrating toward closed-loop control variants with integrated encoder feedback.
Regulatory Environment
The EU Machinery Directive and ISO 13849-1 safety standards mandate redundant position monitoring and force limiting for actuators deployed in collaborative robot cells and patient-contact medical devices. In the United States, OSHA lockout/tagout rules and FCC electromagnetic compatibility requirements shape product design for factory floor and wireless-enabled actuator networks. Stakeholders must monitor evolving IEC 61800-5-2 safe motion profiles and regional cybersecurity frameworks as connected actuators become default in Industry 4.0 architectures.
Market Dynamics
Brushless DC motor integration with embedded drive electronics is compressing actuator footprints while eliminating separate control cabinets, forcing incumbent suppliers to redesign around thermal management in confined spaces.
Growth Catalysts
- EU Machinery Directive:Redundant position monitoring mandates for collaborative robot cells are pulling demand toward closed-loop electromechanical systems with integrated safety-rated encoders.
- Automotive assembly:Factory automation lines in Germany and the United States are replacing pneumatic cylinders with electric actuators for programmable force control during battery module assembly.
- Ball screw mechanisms:Force-density improvements in roller screw designs are capturing hydraulic replacement projects in metal forming presses rated above 50 kN.
Market Restraints
- Rare earth magnet volatility:Neodymium price swings from Chinese export quotas are compressing margins on high-torque brushless DC motor configurations.
- ISO 13849-1 compliance costs:Third-party safety certification for medical patient-handling actuators adds twelve to eighteen months to product launch timelines.
- Pneumatic legacy infrastructure:Installed base of compressed air systems in Japanese automotive plants creates switching friction for electromechanical alternatives.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced manufacturing equipment are attracting actuator assembly investments serving domestic pharmaceutical packaging lines.
- Wireless-enabled maintenance:Bluetooth Low Energy diagnostic modules are opening predictive service revenue streams independent of traditional distributor channels.
- GB standard harmonization:China's convergence with IEC 61800-5-2 safe motion profiles is reducing re-engineering costs for multinational suppliers entering NEV battery plants.
Industry Challenges
- Mechatronics talent scarcity:Shortage of engineers fluent in both electromagnetic design and real-time control firmware is throttling R&D velocity at mid-tier suppliers.
- Legacy PLC integration:Proprietary fieldbus protocols in decade-old automotive stamping lines require custom gateway development for smart actuator retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Linear Actuator Market |
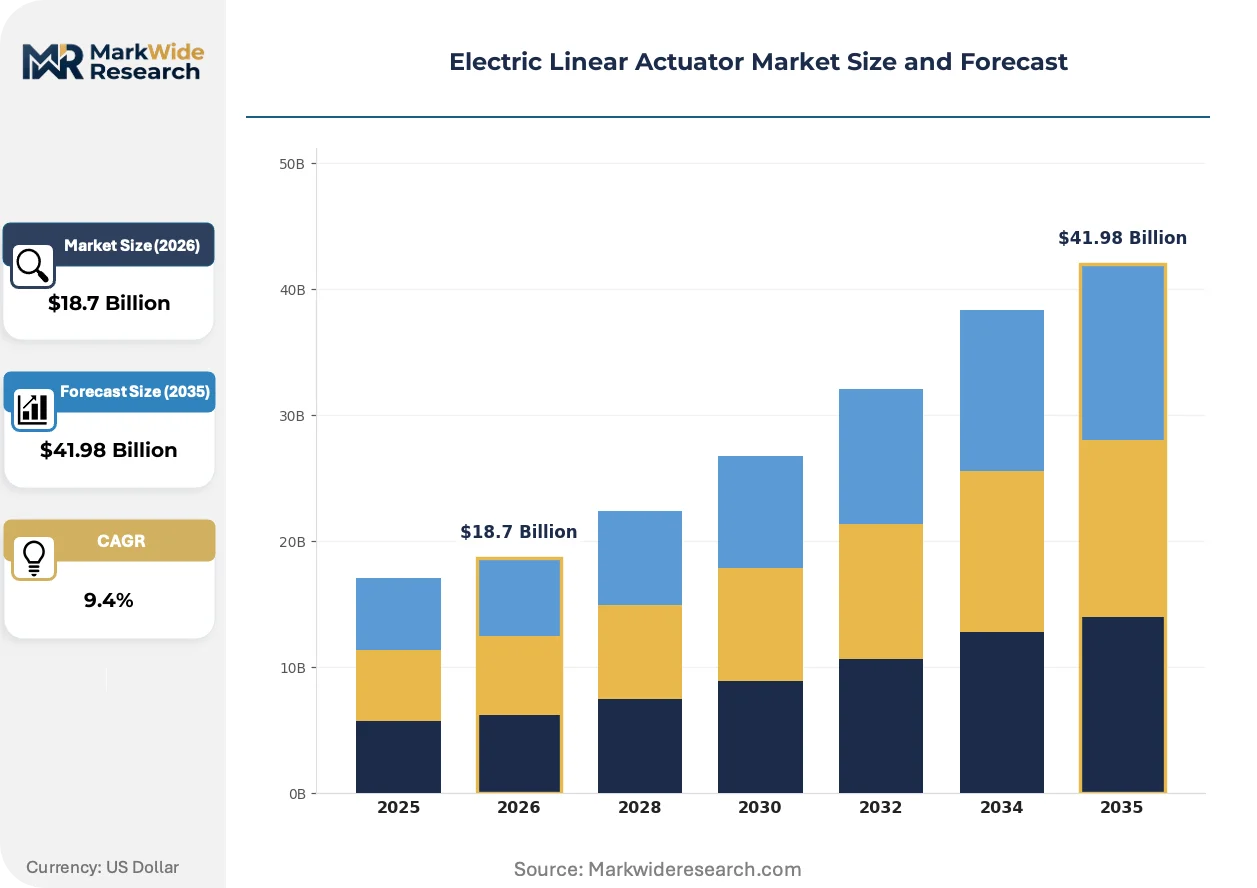
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rod Type, Block Type, Belt Type, Screw Type Application: Aerospace, Automotive, Robotics, Manufacturing End User: Industrial Equipment, Healthcare, Home Automation, Agriculture Control Type: Closed Loop, Open Loop, Proportional, Digital |
| Companies Covered | TiMOTION, Festo Inc., LINAK A/S, Rockwell Automation Inc., ABB Ltd, Parker Hannifin Corporation, Emerson Electric Co., SKF AB, Thomson Linear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Linear Actuator Market Emerging Trajectories
Digital thread integration is collapsing the boundary between actuator hardware and factory software layers, enabling real-time force profiling and remote parameter adjustment without physical access.
Integrated servo motors with absolute multi-turn encoders are digitizing motion control architectures by embedding position loops directly at the actuator housing. Automotive battery assembly lines in Germany are adopting these units to eliminate external drive cabinets. This compression of control topology is digitizing how machine builders specify electromechanical subsystems.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing lubricant reformulation for ball screw assemblies deployed in European medical devices. Suppliers must qualify new greases without compromising lifetime ratings under ISO 3408 load tests. The medical furniture segment is responding by consolidating supplier audits around pre-certified material declarations.
Buyers in the United States are unbundling actuator procurement from full-machine contracts, sourcing electromechanical axes directly through industrial distributors rather than OEM captive supply agreements. This disintermediation is compressing distributor margins while expanding SKU proliferation for standardized stroke lengths. The shift is most visible in packaging machinery rebuilds across the Midwest manufacturing belt.
Electric Linear Actuator Market Segmentation
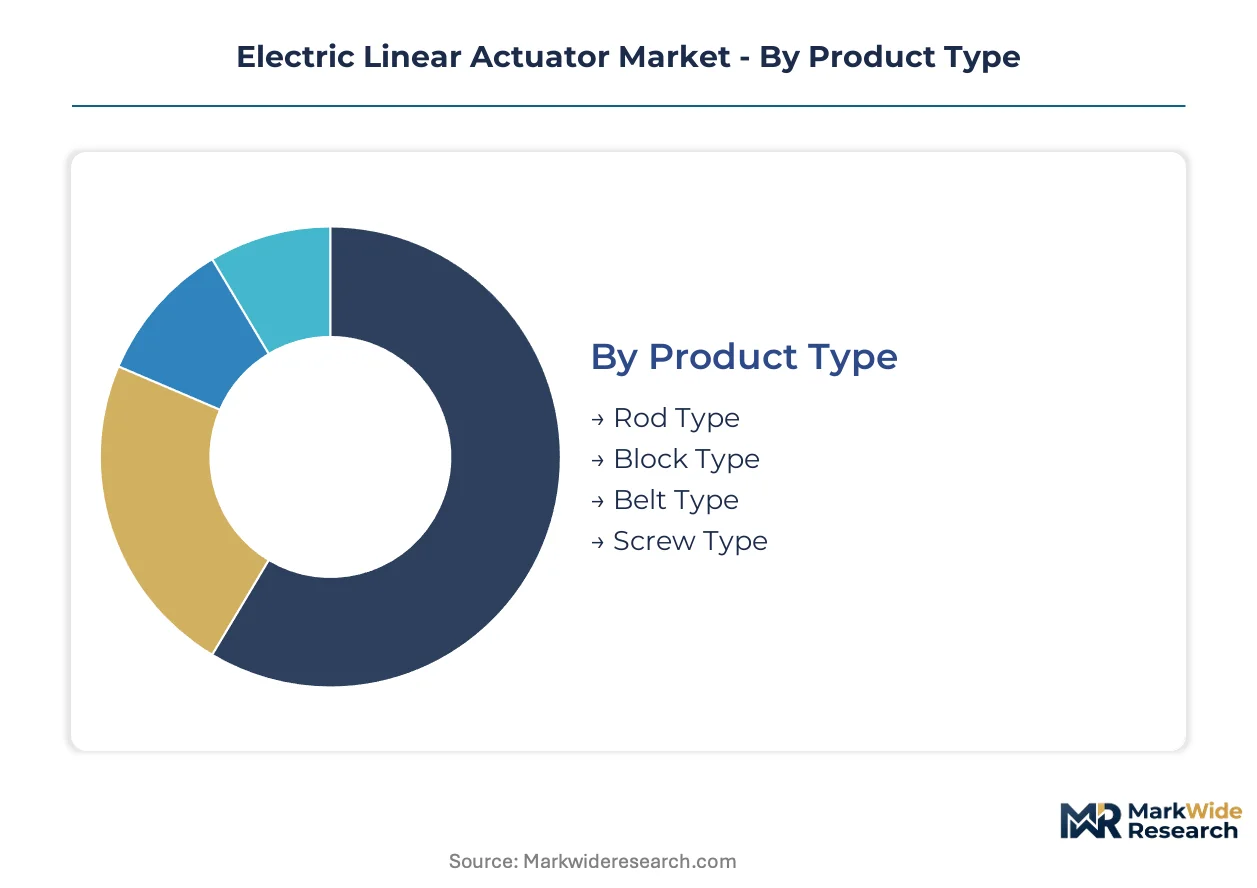
Segmentation in the electric linear actuator market reveals how force density, precision requirements, and environmental exposure dictate technology selection across divergent deployment contexts. Understanding these partitions exposes where margin pools concentrate versus where commodification pressures dominate procurement decisions.
Product Type:
Cost tier stratification separates hydraulic replacement projects from precision motion systems, with force density and speed requirements driving the technology stack selection.
- Screw Type:Roller screw and ball screw mechanisms deliver force densities exceeding 50 kN for metal forming presses and injection molding equipment. Demand concentrates in Germany and the United States where automotive battery module assembly requires programmable force control with ±0.05 mm repeatability.
- Belt Type:Belt-and-pulley configurations achieve linear velocities beyond screw alternatives for packaging lines and electronics assembly. China captures the steepest expansion trajectory as NEV battery plants prioritize speed over load capacity in pick-and-place operations.
- Rod Type:Telescoping rod actuators retain mature volumes in agricultural and construction equipment hydraulic replacement projects.
- Block Type:Compact block form factors integrate into space-constrained medical furniture and collaborative robot joints.
Screw type holds installed capacity across heavy industrial tiers. Belt type is rotating up the share rankings in electronics and packaging automation.
Application:
Application segmentation maps directly to duty cycle intensity and safety certification requirements, with collaborative environments imposing redundant position monitoring mandates.
- Manufacturing:Factory automation lines deploy closed-loop electromechanical systems for programmable motion profiles in stamping, welding, and assembly sequences. ISO 13849-1 compliance costs add twelve to eighteen months to product launches for patient-contact variants, concentrating procurement among pre-certified supplier pools.
- Automotive:Battery module assembly lines in Germany and the United States are replacing pneumatic cylinders with electric actuators for force-controlled joining operations. EU Machinery Directive mandates for collaborative robot cells are pulling demand toward integrated safety-rated encoders.
- Robotics:Collaborative robot cells require force limiting and redundant position monitoring under ISO 13849-1 and IEC 61800-5-2 safe motion profiles.
- Aerospace:Flight control surface actuation demands MIL-STD qualification for shock, vibration, and temperature extremes.
Manufacturing holds installed capacity across process automation. Automotive is rotating up the share rankings as electrification reshapes assembly line architectures.
End User:
Customer type segmentation separates specification-driven procurement in regulated medical environments from price-sensitive agricultural equipment retrofits.
- Industrial Equipment:Metal forming, packaging machinery, and press applications specify roller screw actuators rated above 50 kN. FCC electromagnetic compatibility requirements shape design for wireless-enabled actuator networks in United States factory floors.
- Healthcare:Patient handling equipment and medical furniture demand dedicated actuator lines with REACH-compliant lubricants and redundant safety systems. LINAK A/S dominates this segment with pre-certified material declarations streamlining supplier audits.
- Agriculture:Tractor and harvester hydraulic replacement projects prioritize rod type actuators with IP6K9K sealing for environmental exposure.
- Home Automation:Adjustable beds and standing desks drive volume for low-force, quiet-operation belt type units.
Industrial equipment holds installed capacity across heavy manufacturing tiers. Healthcare is rotating up the share rankings as aging demographics expand patient handling infrastructure.
Control Type:
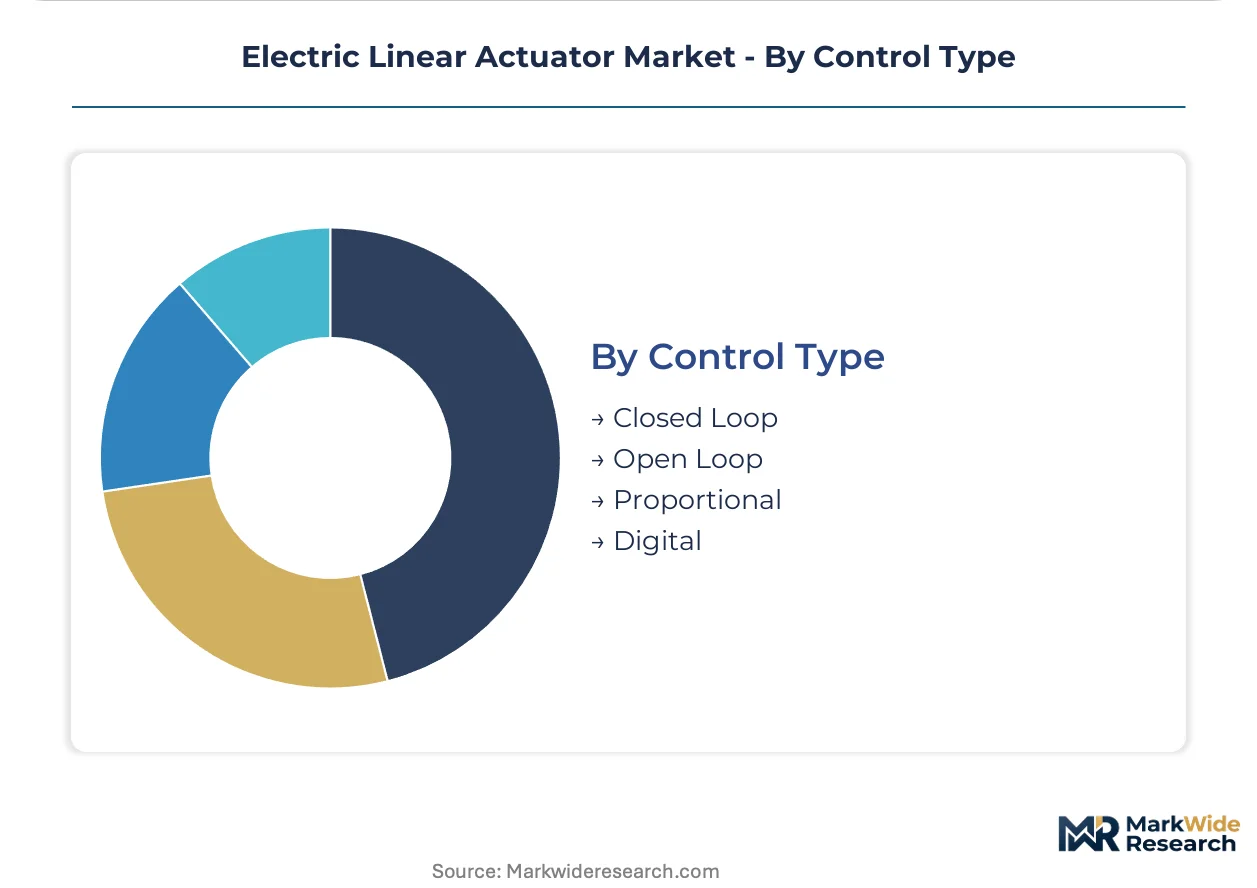
Control architecture segmentation tracks the migration from external drive cabinets toward embedded electronics, with thermal management becoming the constraining design variable.
- Closed Loop:Integrated encoder feedback enables force profiling and position verification for collaborative robot and medical device applications. Automotive battery assembly lines in Germany adopt these units to eliminate external drive cabinets and compress control topology.
- Digital:Fieldbus-connected actuators with Bluetooth Low Energy diagnostics enable predictive maintenance revenue streams independent of traditional distributor channels.
- Open Loop:Stepper-based systems without feedback retain cost-sensitive applications in packaging and material handling where absolute precision is secondary.
- Proportional:Analog velocity and force control bridges legacy PLC integration in decade-old automotive stamping lines.
Closed loop holds installed capacity across safety-critical applications. Digital is rotating up the share rankings as Industry 4.0 architectures mandate connected device defaults.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement for electric linear actuators concentrates among automotive battery assembly lines in Germany, medical furniture manufacturers in Denmark, and factory automation integrators across the United States. Each geography imposes distinct certification requirements and duty-cycle specifications that shape supplier qualification processes.
Germany
Automotive battery module assembly lines in Stuttgart and Munich are replacing pneumatic cylinders with electric actuators for programmable force control. The EU Machinery Directive mandates redundant position monitoring for collaborative robot cells, pulling demand toward closed-loop systems with integrated safety-rated encoders. Bavarian machine builders source roller screw actuators rated above 50 kN for metal forming press retrofits.
United States
Factory automation lines in Michigan and Ohio specify electromechanical axes for stamping and welding sequences. OSHA lockout/tagout rules and FCC electromagnetic compatibility requirements shape product design for wireless-enabled actuator networks. Midwest packaging machinery rebuilds are unbundling actuator procurement from full-machine contracts, expanding distributor SKU proliferation for standardized stroke lengths.
China
NEV battery plants in Shenzhen and Shanghai prioritize belt type actuators for pick-and-place speed over load capacity. GB standard harmonization with IEC 61800-5-2 safe motion profiles is reducing re-engineering costs for multinational suppliers. Yangtze River Delta manufacturing clusters are absorbing capacity from reshoring automotive supply chains.
Denmark
Healthcare furniture manufacturers in Copenhagen and Odense demand dedicated actuator lines with REACH-compliant lubricants for patient handling equipment. The country's national pharmaceutical regulator enforces ISO 13849-1 compliance timelines that add twelve to eighteen months to product launches. LINAK A/S anchors this segment with pre-certified material declarations streamlining supplier audits.
India
Pharmaceutical packaging lines in Maharashtra and Gujarat are attracting actuator assembly investments under the PLI scheme for advanced manufacturing equipment. The Central Electricity Authority shapes electrical safety requirements for industrial motion systems. Mumbai-Pune industrial corridor integrators specify compact block form factors for space-constrained medical device production.
Electric Linear Actuator Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered price-performance bands. The vendor base organizes around three strategic archetypes: healthcare-dedicated specialists, industrial automation generalists, and motion-component pure-plays. Consolidation pressure is accelerating as integrated servo motors compress the boundary between hardware and control electronics. Dominant competitive moves include portfolio diversification into predictive maintenance services and backward integration into motor manufacturing.
Within the healthcare-specialist tier, LINAK A/S and TiMOTION exemplify archetype concentration around patient-handling applications. Among industrial automation generalists, Festo Inc. and Parker Hannifin Corporation occupy positions bridging fluid power heritage with electromechanical platforms. Rockwell Automation Inc. represents the factory-floor control integration archetype, embedding motion systems within broader automation architectures. These named entities serve as anchors for understanding how competitive positioning fragments across end-use specialization rather than geographic coverage alone.
| Leading Market Players |
|---|
| TiMOTION |
| Festo Inc. |
| LINAK A/S |
| Rockwell Automation Inc. |
| ABB Ltd |
| Parker Hannifin Corporation |
| Emerson Electric Co. |
| SKF AB |
| Thomson Linear |
| Others |
Supply Flow & Price Mechanics
Neodymium magnet processing in China feeds directly into brushless DC motor cost structures, concentrating margin capture among suppliers with captive rare earth sourcing or long-term offtake arrangements with Jiangxi and Inner Mongolia processors.
Pricing Analysis
Cost-plus contracts with neodymium price indexation dominate procurement for high-torque brushless DC configurations, insulating suppliers from rare earth volatility while passing through base material swings. Price differentiation rests on ISO 13849-1 safety certification tier and integrated encoder sophistication, with medical-grade units commanding substantial premia over industrial open-loop alternatives. Cost compression in standard-duty belt type actuators is intensifying as Chinese NEV battery plants scale domestic sourcing. Agricultural equipment retrofits exhibit highest price sensitivity, while collaborative robot integrators prioritize force-control precision over unit economics.
Supply Chain Analysis
Export controls on high-performance permanent magnet technology limit technology transfer from Japanese and German motor specialists to emerging Asian manufacturers, constraining supply expansion for safety-rated integrated servo modules. Component sourcing draws from China for rare earth processing, Germany for precision ball screw grinding equipment, and Japan for absolute encoder ASICs. Single-source vulnerability concentrates in sintered neodymium magnet supply, where Chinese export quota policies create intermittent availability constraints. Distribution runs through industrial automation distributors in the United States and Europe, with direct OEM supply agreements dominating high-volume automotive battery assembly contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory automation retrofits and collaborative robot deployments are accelerating actuator replacement cycles, positioning the market for sustained expansion as pneumatic-to-electric conversion penetrates Japanese automotive plants and Midwest packaging rebuilds.
For Market Incumbents: Pre-empt margin erosion in standard-duty screw type actuators by securing captive neodymium magnet supply through backward integration into rare earth processing partnerships or long-term offtake with Chinese refiners. Accelerate certification investment for IEC 61800-5-2 safe motion profiles to defend positioning against emerging motion-component pure-plays targeting collaborative robot integrators. For New Entrants and Emerging Players: India's pharmaceutical packaging corridor offers the most penetrable white space, with PLI scheme incentives reducing capital barriers for assembly investments serving domestic adjustable bed and medical device production. Target wireless-enabled predictive maintenance modules as a service wedge, bypassing entrenched distributor relationships through Bluetooth Low Energy diagnostic subscriptions sold direct to plant maintenance departments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across integrated servo motor architectures as embedded drive electronics eliminate external control cabinets, compressing working capital requirements for scaled production. Acquire motion-component pure-plays with certified ISO 13849-1 product lines and established automotive battery assembly customer relationships. Monitor neodymium export quota announcements from Chinese regulators as the critical inflection signal for margin trajectory across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing from Jiangxi processors insulates margins from Chinese export quota volatility. |
| IEC 61800-5-2 Safe Motion Certification Investment | Pre-certified architectures reduce twelve-to-eighteen-month compliance timelines for collaborative robot deployments. |
| Wireless Predictive Maintenance Module Launch | Bluetooth Low Energy diagnostics open recurring revenue streams independent of traditional distributor channels. |
| India PLI Scheme Manufacturing Footprint | Domestic assembly capacity captures pharmaceutical packaging demand in Maharashtra and Gujarat clusters. |
| Roller Screw Force Density Advancement | Ratings beyond 50 kN capture hydraulic replacement projects in German metal forming press retrofits. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs trade data, and IEC standard certification databases, combining structured interviews with plant engineers, OEM procurement teams, and aftermarket service heads with bottom-up validation of installed base estimates and top-down triangulation against automotive production and medical furniture shipment data.
Forecast inputs include screw type versus belt type technology mix, closed-loop control adoption rates across safety-critical applications, and regional manufacturing reshoring intensity. Modeled segmentation spans product type, application, end user, and control architecture dimensions across the projection horizon. CAGRs derive from elasticity-adjusted demand curves for pneumatic replacement and collaborative robot deployment, with neodymium price trajectory and EU Machinery Directive enforcement timelines as key sensitivity variables.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese integrated servo motor specialists or accelerated rare earth recycling commercialization would shift outcomes beyond modeled ranges. Cross-checking against IHS Markit automotive production forecasts and hospital capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
North America Automated Storage and Retrieval System Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Global Industrial Wireless Automation Market
Industrial Automation
Smart Manufacturing Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Europe Retail Automation Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
Drilling Automation Market
Industrial Automation
Europe Smart Manufacturing Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market