
 Smart Sorting Line Market | 2026-2036
Smart Sorting Line Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sorting Line Market Insights
A capital-intensity divergence between sensor-integrated platform builders and conveyor-only assemblers is reorganizing competitive tiers in the smart sorting line landscape. TOMRA Systems ASA leverages deep optical-sensor expertise to dominate high-value recycling and food-grade applications. Bühler AG anchors grain and food-processing sortation through proprietary imaging technology and integrated process control.
Smart sorting lines integrate conveyors, optical sensors, AI-driven classification software, and actuated diverter mechanisms to autonomously separate items by material, size, shape, or destination at throughput rates exceeding human capability. Automated sorting systems command the largest installed base, while AI algorithm deployments represent the fastest-expanding technology layer as logistics operators pursue sub-second decision latency. E-commerce companies and recycling facilities constitute the most active end-user pools, with parcel sortation applications generating concentrated margin pools due to volume scale and uptime sensitivity.
FDA food-contact material rules, EU machinery directives under CE marking, and China's GB standards for industrial automation equipment collectively shape product certification requirements and cross-border market access. The EU AI Act introduces new conformity obligations for autonomous decision systems in material handling, compelling vendors to embed explainability and safety-by-design protocols. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance costs and certification timelines that could alter competitive positioning in contract bids.
Market Dynamics
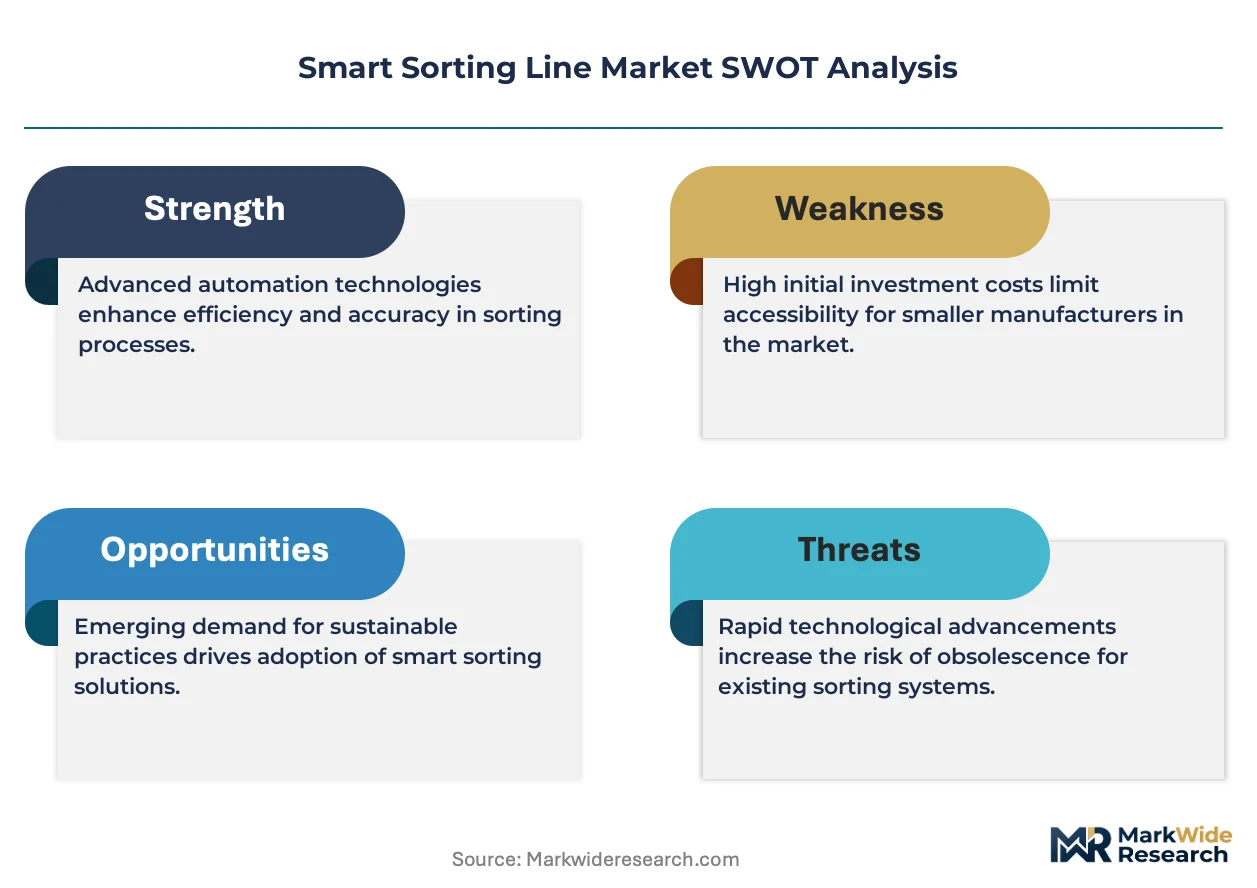
Capital intensity divergence between sensor-integrated platform builders and conveyor-only assemblers is reorganizing competitive tiers in the smart sorting line landscape.
Growth Catalysts
- E-commerce parcel volume surge:Logistics operators in Germany, China, and the United States are accelerating deployment of automated parcel handling infrastructure to manage throughput exceeding human capability.
- EU AI Act compliance mandates:The regulation introduces new conformity obligations for autonomous decision systems in material handling, compelling vendors to embed explainability and safety-by-design protocols.
- Optical-sensor fusion:Deep learning integration with hyperspectral imaging is enabling sub-second classification of mixed-material streams in recycling and food-processing applications.
Market Restraints
- Specialized component supply concentration:High-precision optical sensors and AI accelerators depend on concentrated Asian manufacturing clusters, creating vulnerability to geopolitical friction.
- CE marking complexity:EU machinery directives require extensive third-party assessment for autonomous sorting equipment, extending certification timelines and pre-deployment capital lockup.
- Human sorter substitution economics:Low-wage labor markets in Southeast Asia and parts of Eastern Europe dampen automation ROI calculations for mid-scale operators.
Strategic Opportunities
- India logistics hub buildout:The country's PLI scheme for industrial automation and expanding e-commerce fulfillment networks create first-mover positioning for integrated system vendors.
- Pharmaceutical serialization mandates:Track-and-trace regulations in the United States and EU are driving demand for vision-based sorting lines capable of verifying individual package identifiers.
- Edge-AI and 5G convergence:Real-time inference at the sorting point combined with low-latency wireless control enables decentralized line architectures without centralized server dependency.
Industry Challenges
- Multidisciplinary talent scarcity:System integrators struggle to recruit engineers fluent in both mechanical conveyor design and machine learning pipeline deployment.
- Legacy WMS integration friction:Brownfield logistics facilities face extended downtime and custom middleware development when connecting AI-driven sorters to existing warehouse management infrastructure.
- Explainability audit requirements:EU AI Act documentation demands for autonomous decision systems impose ongoing compliance engineering overhead that pure hardware vendors lack organizational capacity to deliver.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sorting Line Market |
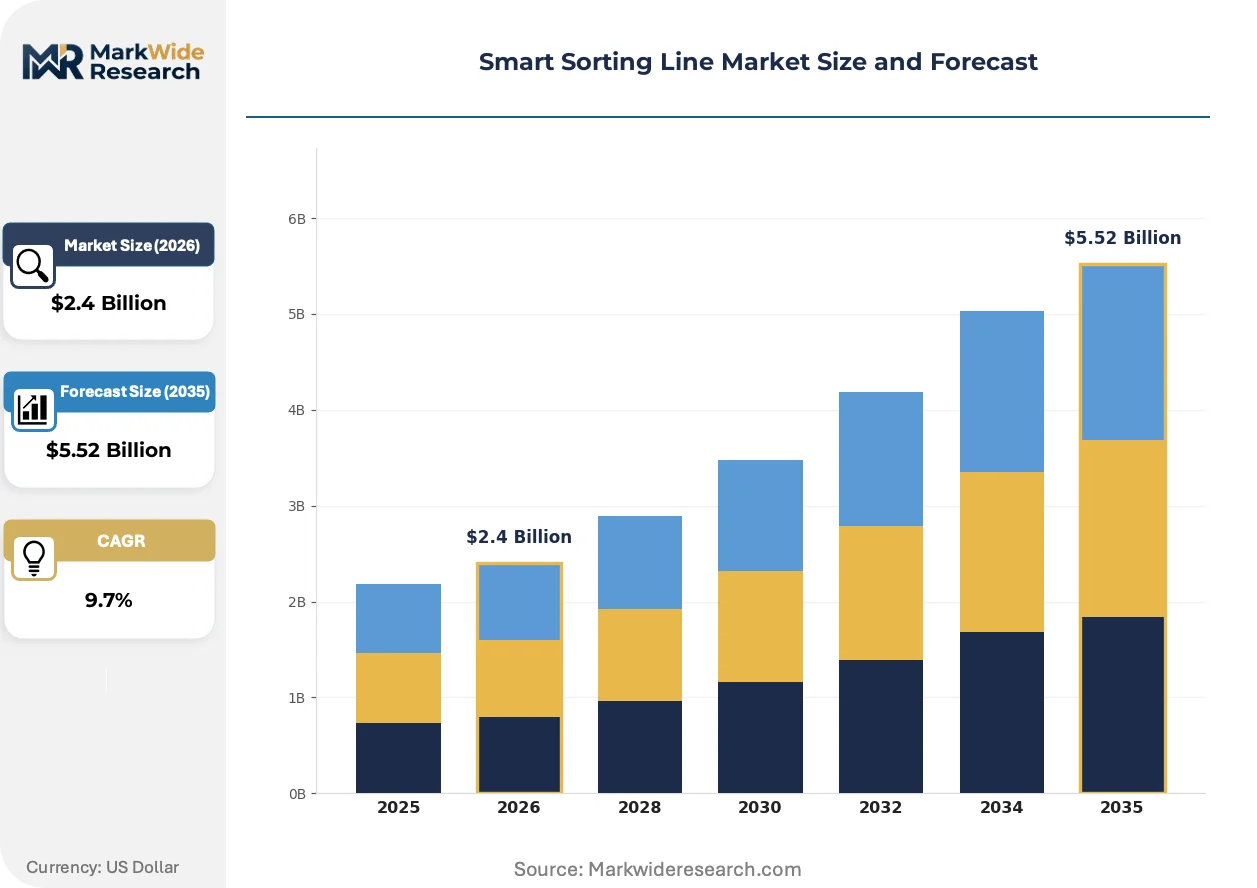
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Sorting Systems, Manual Sorting Solutions, Hybrid Sorting Machines, Conveyor-Based Systems Technology: AI Algorithms, Machine Learning, RFID Integration, Optical Sensors End User: Logistics Providers, E-Commerce Companies, Manufacturing Plants, Recycling Facilities Application: Parcel Sorting, Waste Management, Inventory Control, Food Processing |
| Companies Covered | TOMRA Systems ASA, Bühler AG, Siemens AG, Vanderlande, BEUMER Group, Honeywell International, Daifuku, Key Technology, Sesotec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sorting Line Market Trends and Innovations
Three interconnected developments are compressing decision latency and expanding sortable material categories across logistics, recycling, and food-processing installations.
Hyperspectral imaging arrays are miniaturizing from laboratory-scale units to conveyor-integrated modules capable of real-time polymer identification in mixed-plastic streams. Recycling facilities in the Netherlands and California are retrofitting existing lines with these sensors to capture higher-value resin grades. The technology is miniaturizing capital barriers for mid-scale operators previously excluded from automated optical sorting.
The EU AI Act's risk-based classification framework now explicitly covers autonomous material-handling systems executing high-speed divert decisions without human intervention. Vendors must demonstrate conformity with safety-by-design protocols and maintain technical documentation for post-market surveillance. German and French logistics operators are prioritizing suppliers with established EU notified body relationships to preempt certification delays.
Third-party sorting-as-a-service contracts are displacing traditional equipment purchase models among mid-tier e-commerce fulfillment providers. Under these arrangements, vendors retain asset ownership and charge per-parcel throughput fees, transferring uptime risk from operator to supplier. This model is gaining traction in the United States and United Kingdom where capital constraints and demand volatility make fixed-asset ownership less attractive.
Smart Sorting Line Market Segmentation
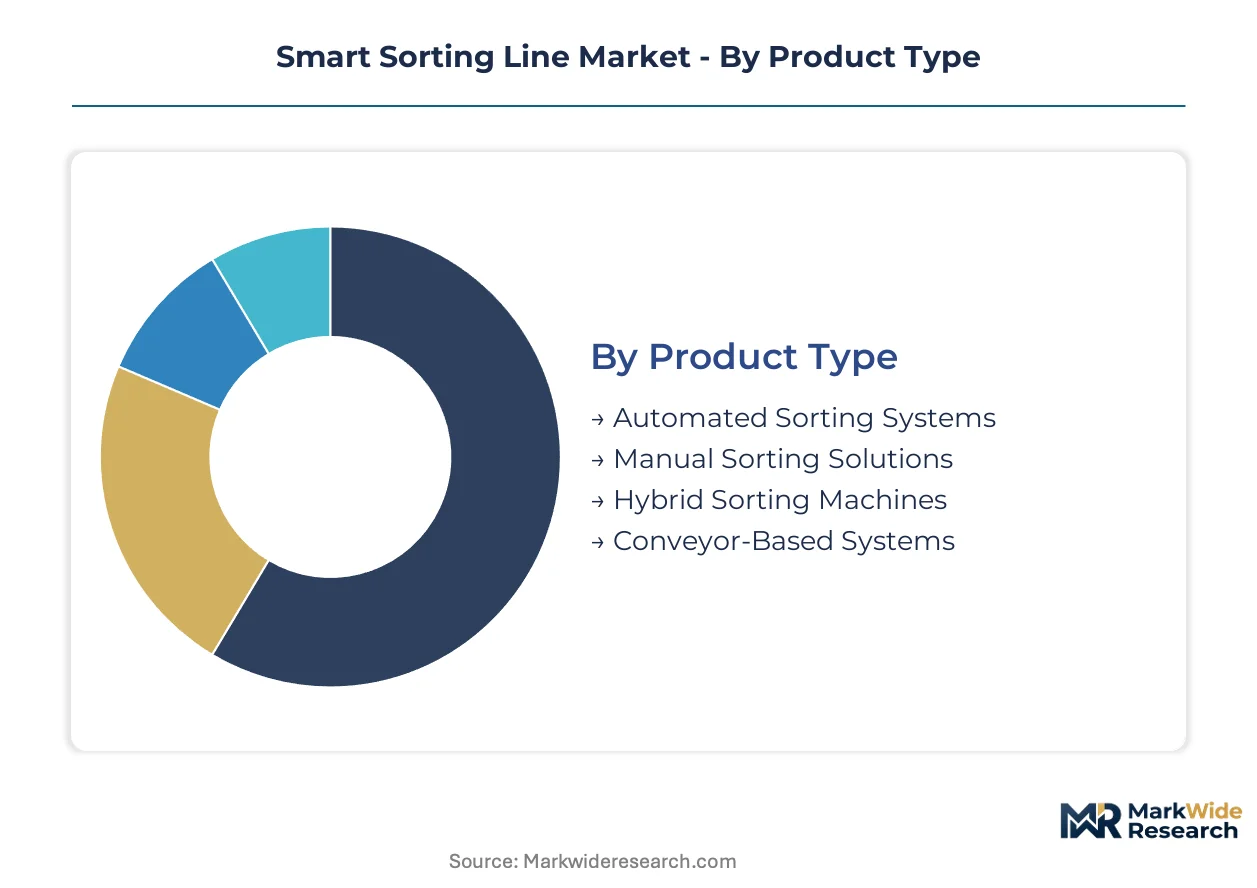
Smart sorting line segmentation reveals how technology layering and end-use intensity create divergent margin profiles. Product architecture choices determine capital recovery timelines, while application specificity dictates sensor integration depth and software licensing value.
Product Type:
Margin pools concentrate in systems combining proprietary vision hardware with integrated process control, leaving pure mechanical conveyors in commoditized pricing bands.
- Automated Sorting Systems:Fully integrated platforms fuse conveyor mechanics with AI-driven divert actuation and real-time classification engines. E-commerce fulfillment centers in Germany and China deploy these systems to achieve throughput rates exceeding 35,000 parcels per hour with sub-second decision latency.
- Hybrid Sorting Machines:Configurations blend automated optical identification with human-assisted exception handling for irregular parcel geometries. These systems dominate mid-scale recycling facilities in California and the Netherlands where material stream variability exceeds pure automation tolerance.
- Manual Sorting Solutions:Basic conveyor configurations with operator stations persist in low-wage manufacturing clusters.
- Conveyor-Based Systems:Mechanical transport infrastructure without integrated sensing commands pricing at the commodity tier.
The dominant share belongs to Automated Sorting Systems, while Hybrid Sorting Machines is closing the gap fastest.
Technology:
Software and sensor layers capture expanding value share as hardware commoditization accelerates across conveyor mechanics.
- Optical Sensors:Hyperspectral imaging arrays and laser triangulation modules enable real-time material composition analysis. Recycling operators in the Netherlands retrofit existing lines with polymer-specific sensors to capture higher-value resin grades from mixed-plastic streams.
- AI Algorithms:Deep learning classification models process sensor outputs to generate divert commands without rule-based programming. Logistics operators in France prioritize vendors with EU AI Act conformity documentation to preempt certification delays for autonomous decision systems.
- Machine Learning:Supervised training pipelines adapt sort criteria based on operational feedback loops.
- RFID Integration:Radio-frequency identification enables item-level tracking through warehouse management system coupling.
Optical Sensors holds the revenue base, with AI Algorithms expanding most quickly as explainability requirements reshape procurement criteria.
End User:
Volume concentration and uptime sensitivity determine willingness to pay for predictive maintenance and throughput guarantees.
- E-Commerce Companies:Parcel volume volatility and delivery speed mandates drive demand for modular, rapidly deployable sortation infrastructure. Fulfillment networks in the United States and United Kingdom increasingly favor sorting-as-a-service contracts transferring uptime risk to vendors.
- Logistics Providers:Third-party operators require multi-tenant flexibility and rapid reconfiguration for seasonal demand spikes. Hub operators in China integrate 5G-enabled edge AI to enable decentralized line architectures without centralized server dependency.
- Recycling Facilities:Material recovery facilities seek polymer-grade purity for resale value maximization.
- Manufacturing Plants:Inbound component sortation and finished goods routing drive deployment in automotive and electronics assembly.
E-Commerce Companies commands the installed value, while Logistics Providers is gaining share fastest through throughput-based contracting models.
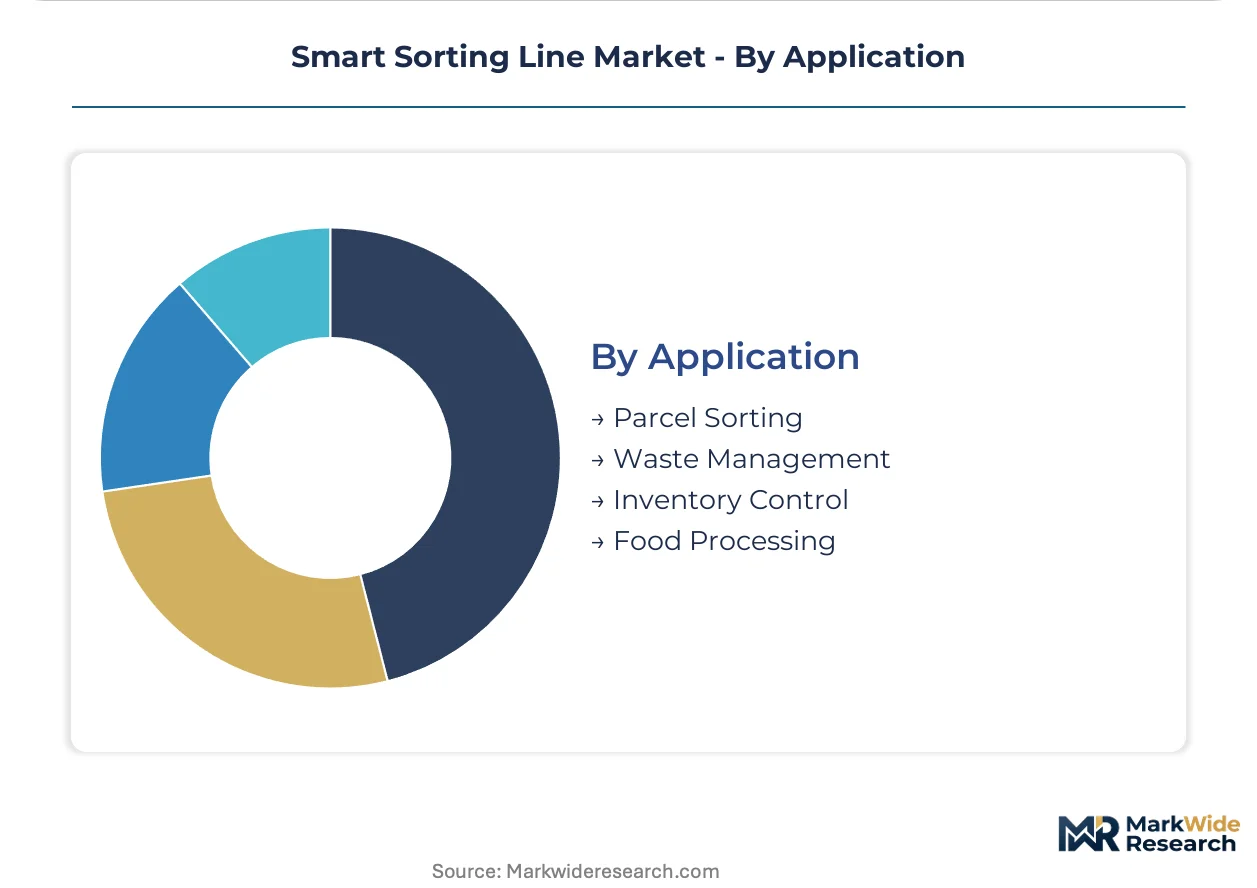
Application:
Parcel sortation generates concentrated margin pools due to volume scale and uptime sensitivity, while waste management applications prioritize capital efficiency.
- Parcel Sorting:High-speed divert decisions for destination routing dominate e-commerce logistics. German operators deploy these lines with EU machinery directive CE marking to access cross-border fulfillment networks.
- Food Processing:FDA food-contact material compliance and contamination detection requirements drive premium sensor integration. Grain processors leverage hyperspectral imaging for mycotoxin screening and foreign material removal.
- Waste Management:Municipal and commercial recycling operations focus on resin-grade recovery economics.
- Inventory Control:Warehouse put-away and picking optimization applications serve manufacturing and retail distribution.
Parcel Sorting anchors revenue concentration, with Food Processing climbing the fastest as safety regulations tighten detection sensitivity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys smart sorting lines for high-throughput parcel automation, while China prioritizes recycling-grade optical sorting and India concentrates on cost-constrained logistics hub buildouts. This consumption-mix differential reflects divergent labor costs, regulatory timelines, and infrastructure maturity across major demand centers.
Germany
E-commerce fulfillment networks drive demand for CE-marked autonomous sorting systems with sub-second divert latency. The EU AI Act mandates explainability documentation for high-risk autonomous decision systems, compelling vendors to embed safety-by-design protocols. The Rhine-Ruhr logistics corridor hosts dense clusters of parcel hubs retrofitting legacy lines with AI-integrated optical sensors.
China
Recycling facilities and municipal waste operations deploy hyperspectral imaging modules for polymer-grade recovery from mixed-plastic streams. GB standards for industrial automation equipment govern product certification and cross-border market access. The Yangtze River Delta concentration of material recovery facilities leads adoption of edge-AI sorting architectures.
United States
Third-party logistics operators favor sorting-as-a-service contracts transferring uptime risk from operator to vendor. FDA food-contact material rules shape sensor integration requirements for food-processing applications. The Chicago-Detroit industrial corridor anchors deployment of vision-based pharmaceutical serialization lines.
India
E-commerce fulfillment networks and third-party logistics providers accelerate automation adoption amid labor cost pressures and volume volatility. The PLI scheme for industrial automation subsidizes capital equipment procurement for domestic manufacturing. The Mumbai-Pune logistics belt concentrates first-mover deployments of modular, rapidly deployable sortation infrastructure.
Netherlands
Recycling operators retrofit existing lines with miniaturized hyperspectral sensors to capture higher-value resin grades from complex mixed-waste streams. EU machinery directives under CE marking require extensive third-party assessment for autonomous equipment. The Port of Rotterdam logistics cluster integrates optical sorting with circular economy waste-to-resource pipelines.
Smart Sorting Line Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital intensity divergence between sensor-integrated platform builders and conveyor-only assemblers reorganizing competitive tiers. The landscape stratifies into three archetypes: optical-sensor specialists leveraging deep imaging expertise, integrated process-control vendors bundling hardware with proprietary software, and mechanical-conveyor fabricators competing on throughput scale. M&A activity concentrates on AI algorithm acquisitions and optical-sensor technology licensing, while geographic expansion into India and Southeast Asia represents the dominant capacity buildout vector.
Within the integrated platform tier, TOMRA Systems ASA and Bühler AG exemplify sensor-anchored competitive positioning. TOMRA represents the optical-sensor specialist archetype with Norwegian-originated deep imaging expertise. Bühler AG occupies a position within the integrated process-control segment through Swiss-originated proprietary technology bundling. Siemens AG anchors the industrial automation conglomerate archetype, leveraging German-originated scale across electromechanical and digital control layers.
| Leading Market Players |
|---|
| TOMRA Systems ASA |
| Bühler AG |
| Siemens AG |
| Vanderlande |
| BEUMER Group |
| Honeywell International |
| Daifuku |
| Key Technology |
| Sesotec GmbH |
| Others |
Pricing and Supply Chain Analysis
Scale economies in AI accelerator and hyperspectral sensor production concentrate bargaining power among Asian manufacturing clusters, compressing price floors for mid-tier operators while elevating lifetime value capture for integrated platform vendors. This concentration amplifies procurement leverage for high-volume buyers in Germany and China, forcing conveyor-only assemblers toward commoditized margin bands.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions generate the dominant lifetime value streams, shifting vendor economics from equipment margin to recurring revenue. Three-tier pricing structure across premium sensor-integrated platforms, standard hybrid configurations, and economy mechanical conveyors stratifies buyer segments. Pricing pressure stems from sorting-as-a-service contracts transferring uptime risk to vendors, compressing upfront equipment premiums. Mid-scale recycling facilities in Southeast Asia exhibit highest price sensitivity due to capital constraints, while German parcel hubs prioritize throughput guarantees over unit cost.
Supply Chain Analysis
Taiwan Strait transit vulnerability and concentrated Japanese optical-component fabrication create chokepoint exposure for hyperspectral imaging modules and AI inference accelerators. High-precision sensors draw from Taiwan, South Korea, and Japan, while conveyor mechanics source from China and Germany. Single-source dependency on Taiwanese semiconductor foundries for edge-AI chips amplifies geopolitical risk. Distribution runs through direct vendor-operator relationships for large deployments, with regional system integrators serving mid-tier installations in India and Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of engineers fluent in both mechanical conveyor design and machine learning pipeline deployment constrains system integrator capacity, creating asymmetric returns for organizations that resolve this interdisciplinary gap. Vendors securing this talent compound advantage in EU AI Act compliance documentation and brownfield WMS integration.
For Market Incumbents: Shield installed base relationships by embedding explainability documentation teams to preempt EU AI Act certification delays for German and French logistics operators. Acquire optical-sensor technology licenses to close capability gaps against TOMRA Systems ASA and Bühler AG. Prioritize backward integration into AI accelerator supply to reduce Taiwan Strait exposure. For New Entrants and Emerging Players: Sorting-as-a-service contract gaps among mid-tier e-commerce fulfillment providers in the United States and United Kingdom represent the most penetrable white-space target. Target India logistics hub buildout under PLI scheme subsidies for first-mover positioning in modular, rapidly deployable infrastructure. Lead with throughput-based pricing to transfer capital constraints from operator to vendor balance sheet. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform vendors bundling proprietary vision hardware with process control software, indicating superior long-term viability. Prioritize acquisition targets with established EU notified body relationships and edge-AI architectural patents. Monitor India PLI scheme utilization rates as inflection signal for regional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Establishes market access for autonomous decision systems in German and French logistics corridors. |
| Optical-Sensor Technology Licensing | Closes capability gaps against TOMRA and Bühler in polymer-grade recycling applications. |
| Sorting-as-a-Service Model Launch | Transfers uptime risk to vendors and unlocks mid-tier e-commerce fulfillment contracts. |
| Edge-AI Architecture Development | Enables decentralized line control without centralized server dependency in China hubs. |
| India Manufacturing Footprint Expansion | Captures PLI scheme subsidies and serves Mumbai-Pune logistics belt automation demand. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with logistics automation directors, recycling facility operations managers, OEM procurement leads, and aftermarket service heads; and secondary validation through customs trade records, EU machinery directive CE marking databases, SEC equipment vendor filings, and industrial automation capex disclosures. Bottom-up installation tracking across Germany, China, United States, India, and Netherlands converged with top-down market sizing.
Across the projection horizon, the analytical framework modeled technology layering, end-use intensity, and application specificity as core segmentation dimensions. CAGRs derived from vendor shipment disclosures and operator capital expenditure patterns, with optical-sensor fusion adoption curves and EU AI Act implementation timelines as key forecast inputs.
Forecasts assume regulatory continuity in EU machinery directives, FDA food-contact material rules, and China's GB standards; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as geopolitical friction in Taiwan Strait supply corridors and India PLI scheme modifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Global Intelligent Completion Market
Industrial Automation
North America Automated Storage and Retrieval System Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Utility Automation Market
Industrial Automation
North America Smart Factory Market
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
Programmable Automation Controller (PAC) Market