
 Europe Business Process Outsourcing (BPO) Market | 2026-2036
Europe Business Process Outsourcing (BPO) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Business Process Outsourcing (BPO) Market Foresight
Capital-intensity divergence between technology-forward platforms and labor-dependent operators is rotating competitive dynamics across the European BPO landscape. Telus International leverages proprietary AI-enabled contact center infrastructure to sustain premium pricing in multilingual customer service engagements. Comdata Group anchors its position through deep vertical specialization in finance and accounting workflows for Italian and French banking clients.
Business Process Outsourcing encompasses the contractual delegation of non-core operational functions—such as customer interaction management, payroll administration, and IT helpdesk operations—to third-party providers employing workflow automation, cloud-based service delivery, and standardized SLA frameworks. Its primary purpose is cost reduction combined with operational scalability for client organizations. Customer Service and IT Services represent the most mature segments with established margin pools, while Cloud-based deployment models are capturing accelerated adoption as enterprises migrate from legacy on-premise installations. Finance & Accounting outsourcing retains strong growth velocity among Large Enterprises seeking regulatory compliance support.
The EU AI Act and GDPR impose stringent requirements on automated decision-making and cross-border data flows, compelling BPO providers to restructure processing architectures and client contracting frameworks. EMA guidelines and national financial regulators in Germany and France further shape healthcare and banking outsourcing standards through audit trail mandates and data localization expectations. Stakeholders must evaluate provider certification depth against evolving regulatory thresholds before committing to long-term outsourcing partnerships.
Market Dynamics
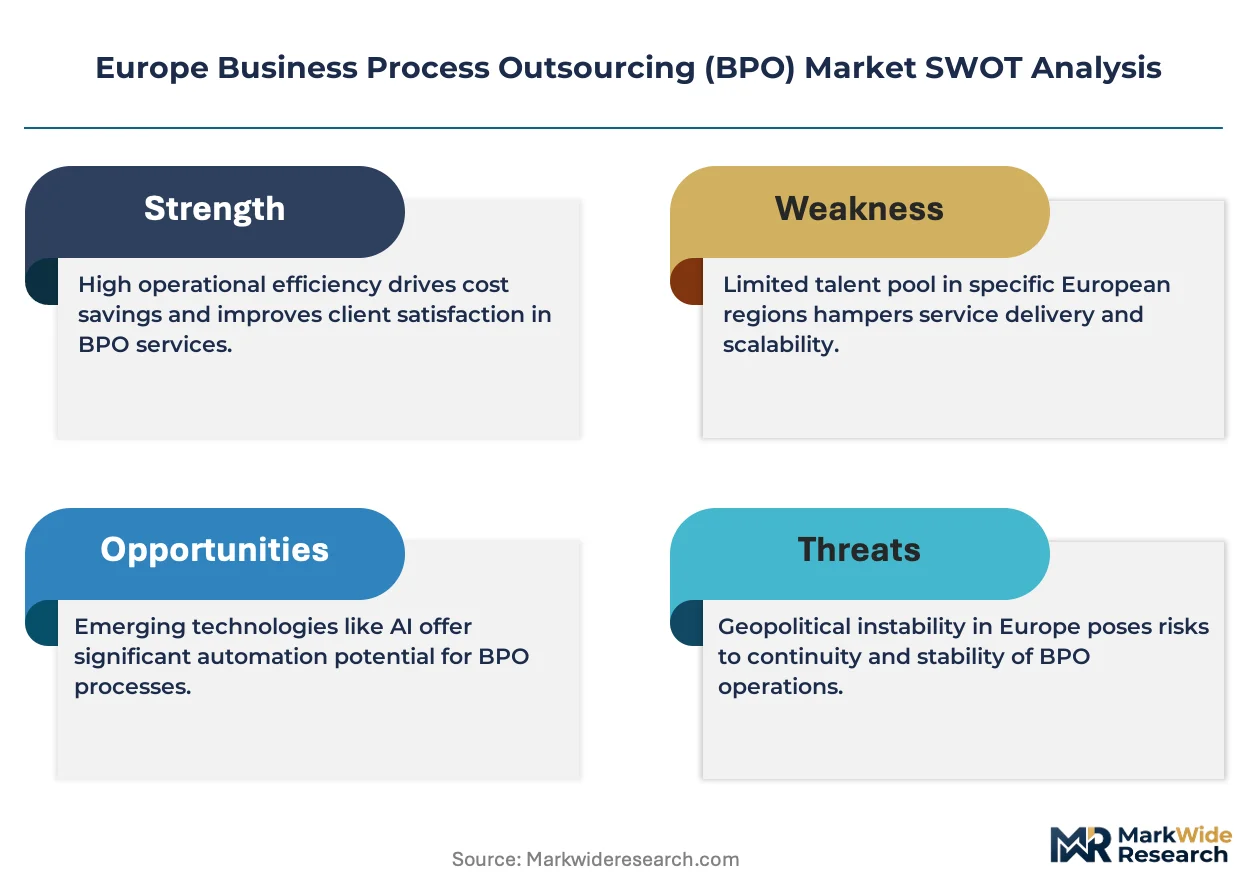
The EU AI Act is forcing European BPO providers to restructure automated decision-making architectures and client contracting frameworks around explainability mandates and human oversight requirements.
Growth Catalysts
- Healthcare outsourcing expansion:German and French hospital networks are delegating patient administration and claims processing to specialized BPO operators seeking operational scale.
- GDPR-compliant automation:Cloud-based service delivery models with embedded data localization capabilities are attracting finance sector clients facing cross-border transfer restrictions.
- Industrial enterprise demand:Manufacturing headquarters in Stuttgart and Munich are driving finance and accounting outsourcing at scale for regulatory compliance support.
Market Restraints
- Labor cost volatility:Wage inflation in Polish and Romanian delivery centers is compressing margins for voice-dependent contact center operators.
- Regulatory fragmentation:Divergent national implementations of the EU AI Act across member states create compliance complexity for multi-country service contracts.
- Technical debt burden:Legacy on-premise installations in Italian and Spanish banking clients slow cloud migration timelines and extend payback periods.
Strategic Opportunities
- Underpenetrated Nordic markets:Swedish and Danish enterprises show low BPO adoption relative to continental peers, presenting first-mover expansion potential for compliant operators.
- CSRD reporting services:The Corporate Sustainability Reporting Directive creates new demand for ESG data collection and verification outsourcing from EU-listed companies.
- AI-human hybrid models:Convergence of generative AI with retained human oversight layers enables premium service tiers for high-stakes healthcare and financial interactions.
Industry Challenges
- Multilingual talent scarcity:Contact center operators face acute shortages of agents fluent in Dutch, Nordic languages, and Eastern European combinations.
- EMA audit trail mandates:Healthcare BPO providers must rebuild processing systems to capture decision lineage for pharmaceutical client inspections.
- Integration complexity:SAP and Oracle ERP environments in German industrial clients resist standardized API connections, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Business Process Outsourcing (BPO) Market |
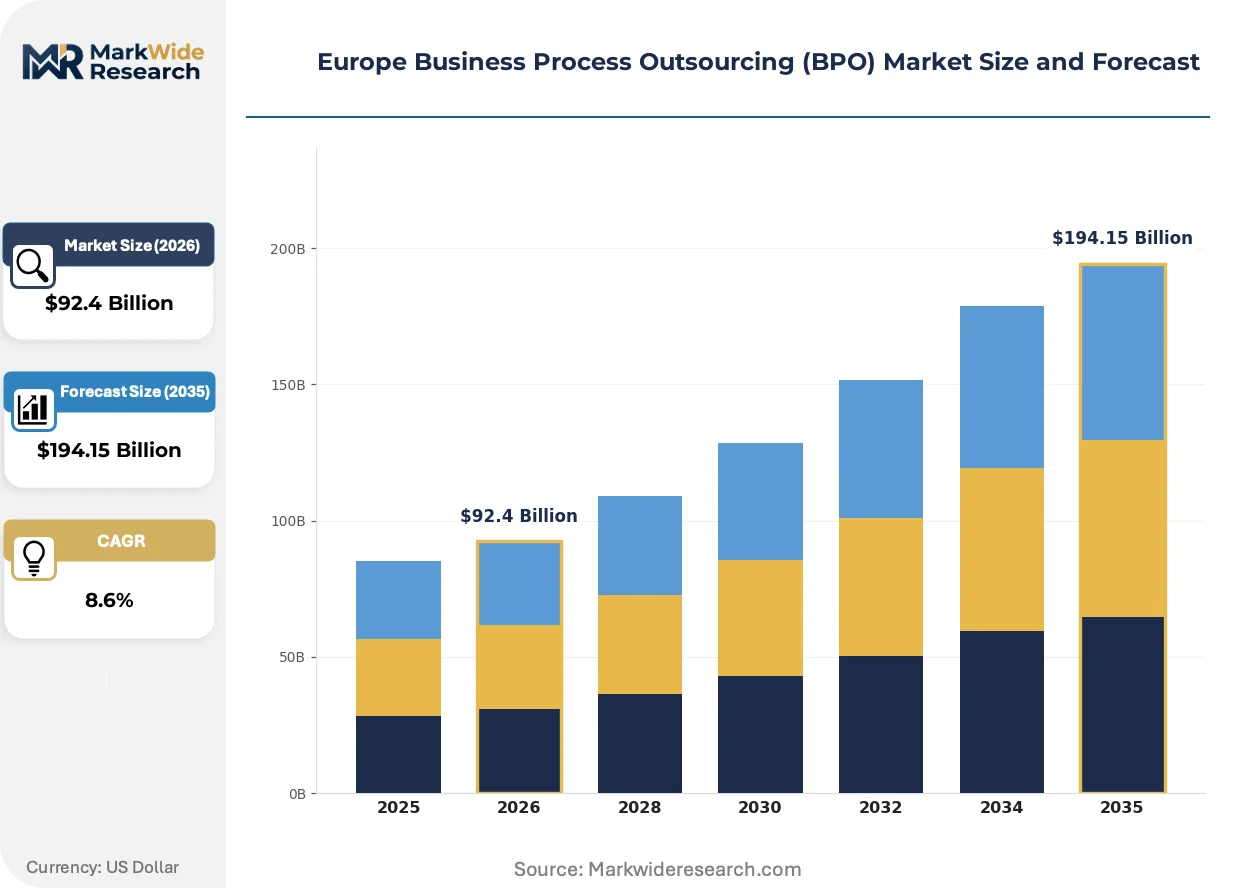
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $194.15 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Human Resources, Customer Service, Finance & Accounting, IT Services End User: Small Enterprises, Medium Enterprises, Large Enterprises, Government Agencies Industry Vertical: Healthcare, Retail, Telecom, Manufacturing Deployment Model: On-premise, Cloud-based, Hybrid, Offshore |
| Companies Covered | Corpshore Solutions, TDCX, Telus International, Cyclad International, Baltic Assist, Abtran, Pontica Solutions, IntelligentBee, Comdata Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Business Process Outsourcing (BPO) Market Shifts & Advancements
Automation architectures across European BPO are pivoting from labor arbitrage toward intelligence-augmented service delivery, with regulatory compliance emerging as a primary design constraint rather than afterthought.
Generative AI copilots for agent assistance are supplanting scripted response trees in multilingual customer service engagements. Dutch and Belgian banking clients are deploying these tools for complex query resolution. The technology is compressing average handle times while elevating first-contact resolution rates beyond traditional offshore benchmarks.
The EU AI Act's risk classification framework is restructuring vendor selection criteria for automated customer interactions. High-risk use cases in credit decisions and healthcare triage now require conformity assessments and human-in-the-loop architectures. German automotive finance units and French insurance claims processors are front-loading compliance investments ahead of enforcement deadlines.
Enterprise buyers are unbundling monolithic outsourcing contracts into modular, outcome-measured service components. Procurement teams in Swiss pharmaceutical headquarters and Austrian industrial conglomerates are replacing fixed-fee arrangements with transaction-based pricing tied to measurable quality thresholds. This shift is most visible in finance and accounting outsourcing, where accuracy SLAs now dominate contractual negotiations over headcount commitments.
Europe Business Process Outsourcing (BPO) Market Segmentation
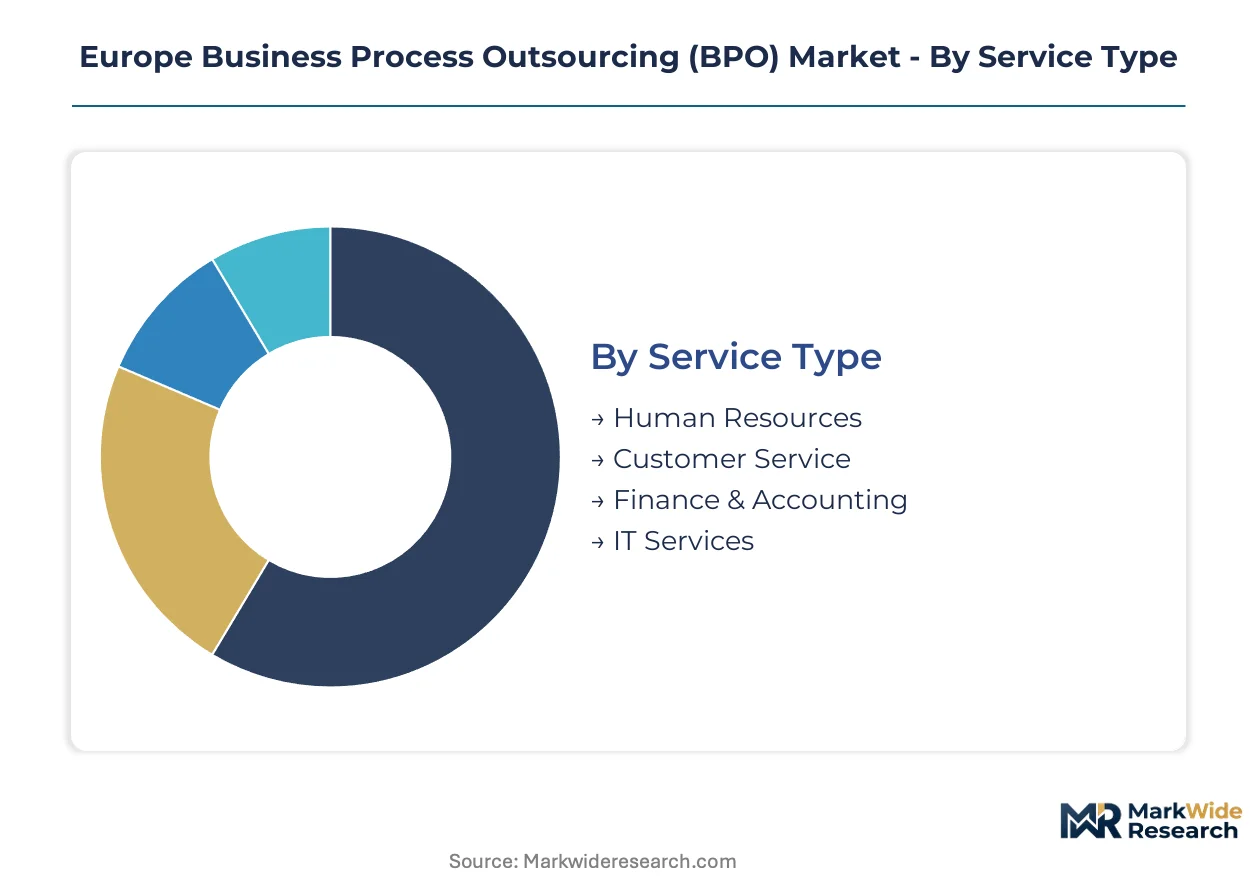
European BPO procurement patterns diverge sharply across service maturity and regulatory exposure. Margin capture concentrates in segments where compliance architecture and automation density create defendable pricing power.
Service Type:
Customer Service and IT Services anchor established margin pools through scale economies, while Finance & Accounting commands premium pricing from regulatory complexity.
- Customer Service:Multilingual contact center operations with embedded quality assurance frameworks dominate contract value. German automotive OEMs and French retail chains are consolidating vendor relationships around AI-augmented agent assistance models that compress handle times while satisfying GDPR consent requirements.
- IT Services:Service desk operations, infrastructure monitoring, and application maintenance delivered through standardized ITIL frameworks. Cloud migration support for SAP and Oracle environments in Stuttgart and Munich manufacturing headquarters is rotating demand toward providers with certified middleware capabilities.
- Human Resources:Payroll administration, benefits management, and talent acquisition process outsourcing.
- Finance & Accounting:Accounts payable, receivable, and regulatory reporting workflows.
IT Services holds installed capacity. Finance & Accounting is rotating up the share rankings.
End User:
Volume concentration sits with Large Enterprises, though Medium Enterprises present the steepest expansion trajectory as compliance burdens professionalize internal functions.
- Large Enterprises:Complex multi-country contracts requiring harmonized SLAs across German, French, and Italian operating subsidiaries. Industrial conglomerates headquartered in Munich and pharmaceutical clusters around Basel are unbundling monolithic arrangements into modular, outcome-measured components.
- Medium Enterprises:Organizations with 250-999 employees seeking regulatory compliance support without captive infrastructure. Danish and Swedish manufacturing mid-caps are adopting cloud-based finance and accounting outsourcing to meet CSRD reporting deadlines without internal ESG data capabilities.
- Small Enterprises:Limited outsourcing penetration concentrated in payroll and basic customer interaction management.
- Government Agencies:Public sector procurement with stringent audit trail and data localization mandates.
Large Enterprises dominate contract value. Medium Enterprises are climbing the fastest.
Industry Vertical:
Healthcare and Manufacturing concentrate premium pricing through specialized compliance requirements that resist commoditization.
- Healthcare:Patient administration, claims processing, and clinical data management subject to EMA audit trail mandates. German hospital networks in North Rhine-Westphalia and French regional health authorities are delegating back-office functions to operators with pharmaceutical inspection readiness.
- Manufacturing:Finance and accounting outsourcing for regulatory compliance support in industrial enterprise headquarters. Stuttgart and Munich-based automotive and machinery producers are driving scale demand for standardized ERP-integrated workflows.
- Retail:Seasonal customer service scaling and omnichannel order management.
- Telecom:Subscriber lifecycle management and technical support operations.
Manufacturing holds installed capacity. Healthcare is rotating up the share rankings.
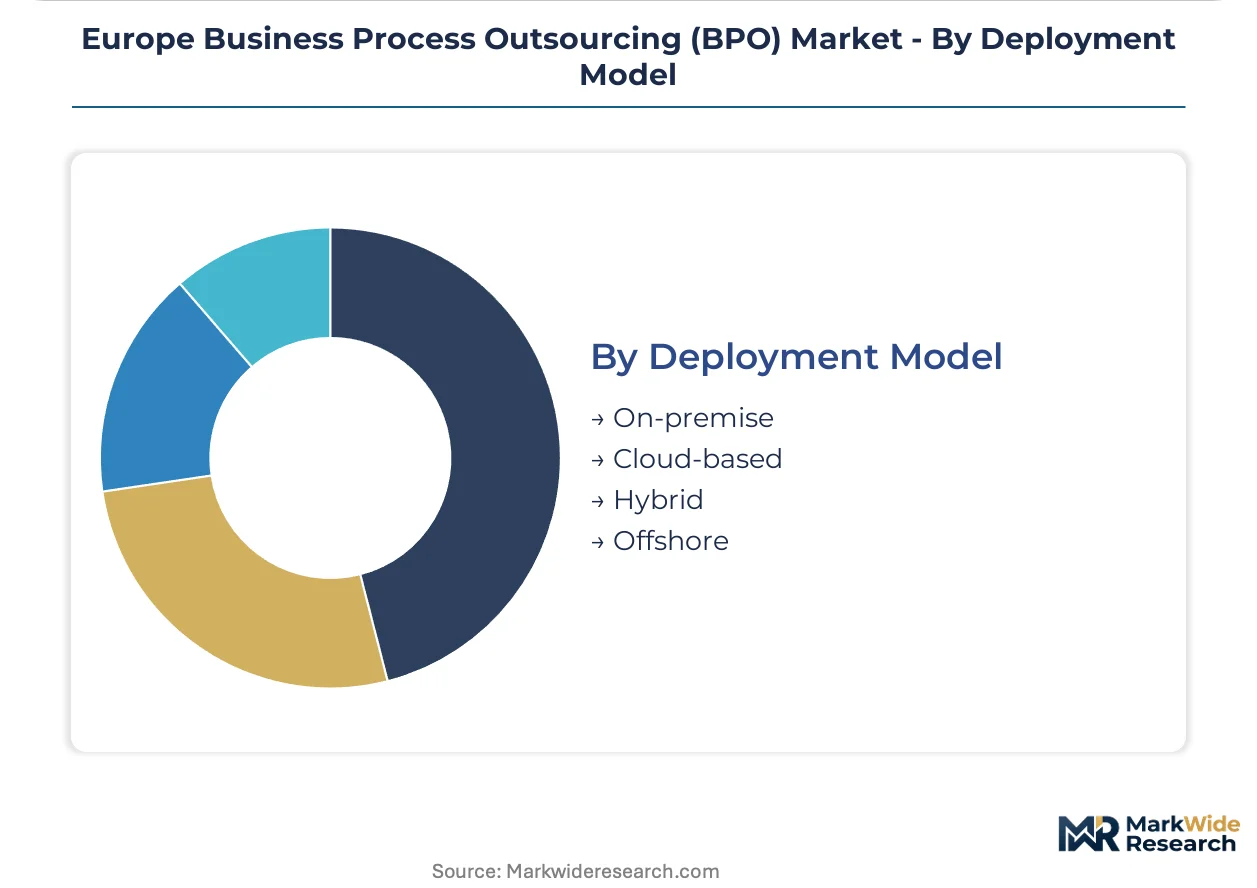
Deployment Model:
Cloud-based architectures are capturing accelerated adoption as data localization capabilities resolve cross-border transfer restrictions.
- Cloud-based:Fully managed service delivery with embedded GDPR compliance and EU data residency guarantees. Dutch and Belgian banking clients are migrating from legacy installations to capture generative AI copilot capabilities without on-premise infrastructure burdens.
- Hybrid:Sensitive data retained on-premise with processing workloads shifted to cloud. German automotive finance units are front-loading hybrid architectures to satisfy EU AI Act human-in-the-loop requirements for credit decision automation.
- On-premise:Legacy installations in Italian and Spanish banking clients resisting migration timelines.
- Offshore:Delivery from Polish and Romanian centers facing wage inflation pressure.
On-premise holds installed capacity. Cloud-based is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial corridors while Polish delivery centers face margin compression from wage inflation. This asymmetry is rotating contract flows toward compliant automation providers in Western Europe.
Germany
Automotive OEMs in Stuttgart and Munich are consolidating finance and accounting outsourcing around ERP-integrated workflows. The EU AI Act's human-in-the-loop requirements are front-loading compliance investments in credit decision automation. Industrial conglomerate headquarters in Bavaria and Baden-Württemberg are unbundling monolithic contracts into modular, outcome-measured components.
France
Regional health authorities are delegating patient administration and claims processing to operators with pharmaceutical inspection readiness. EMA audit trail mandates are forcing healthcare BPO providers to rebuild processing systems for decision lineage capture. Insurance claims processors in Paris and Lyon are deploying AI-human hybrid architectures ahead of enforcement deadlines.
Netherlands
Dutch banking clients are migrating from legacy installations to cloud-based service delivery with embedded GDPR compliance. Generative AI copilots for complex query resolution are compressing average handle times in Amsterdam and Rotterdam contact centers. Belgian financial institutions are following similar migration patterns.
Poland
Wage inflation in Kraków and Warsaw delivery centers is compressing margins for voice-dependent contact center operators. GDPR-compliant automation is attracting finance sector clients seeking cross-border transfer solutions. Technical talent scarcity in multilingual combinations is rotating demand toward automation-heavy service models.
Sweden
Manufacturing mid-caps are adopting cloud-based finance and accounting outsourcing to meet CSRD reporting deadlines. Low BPO adoption relative to continental peers presents first-mover expansion potential for compliant operators. Stockholm and Copenhagen enterprise clusters are professionalizing internal functions without captive infrastructure.
Europe Business Process Outsourcing (BPO) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European BPO landscape. The market structure fragments across three tiers: multinational platforms with proprietary AI infrastructure, regional specialists with deep vertical expertise, and labor-dependent operators competing on scale. Strategic differentiation concentrates in compliance architecture density and automation deployment velocity. Consolidation pressure is intensifying through vertical specialization acquisitions and cloud migration partnership formations.
Within the technology-forward tier, Telus International and Comdata Group exemplify divergent positioning strategies. Telus International anchors premium multilingual customer service engagements through AI-enabled contact center infrastructure. Comdata Group occupies a position within finance and accounting specialization for Italian and French banking clients. Cyclad International and Baltic Assist represent the regional delivery center archetype with cost-optimized operations in Eastern European markets.
| Leading Market Players |
|---|
| Corpshore Solutions |
| TDCX |
| Telus International |
| Cyclad International |
| Baltic Assist |
| Abtran |
| Pontica Solutions |
| IntelligentBee |
| Comdata Group |
| Others |
Supply & Pricing Matrix
Cloud-based service delivery is displacing legacy on-premise installations across European BPO, simultaneously redrawing delivery geography toward Western European compliance hubs and compressing price premiums for standardized voice services. This substitution dynamic elevates automation-heavy providers while eroding margin pools for labor-dependent operators in Eastern European delivery centers.
Pricing Analysis
The customization-premium spread in European BPO separates ERP-integrated finance and accounting workflows from standardized contact center engagements. Three-tier pricing structure across premium, standard, and economy levels captures differentiation by compliance certification depth and automation density. Price differentiation rests on GDPR certification tier and vertical specialization in healthcare or banking workflows. Cost compression in voice-dependent services is intensifying because wage inflation in Polish and Romanian centers erodes labor arbitrage. Small enterprises show highest price sensitivity, while German automotive OEMs prioritize compliance architecture over unit cost.
Supply Chain Analysis
Inventory and lead-time compression distinguishes cloud-native BPO provisioning from legacy system migrations requiring 12-18 month implementation cycles. Delivery capacity concentrates in Germany, Poland, and Romania, with emerging nodes in Portugal and Greece for multilingual talent. Raw material dependencies center on proprietary AI training data, SAP-certified middleware, and GDPR-compliant cloud infrastructure. Single-source vulnerability sits with concentrated generative AI model providers supplying copilot capabilities. Distribution runs through direct enterprise sales teams for large contracts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework constitutes a regulatory inflection accelerating market disruption, forcing compliance investments that favor capitalized platforms over fragmented regional operators.
For Market Incumbents: Shield market position by deepening vertical integration into healthcare and banking compliance workflows before EMA audit trail mandates take full effect. Prioritize certification investment in ISO 27001 and GDPR-adjacent frameworks to sustain premium pricing against automation-native challengers. Consolidate around ERP-integrated service delivery for German industrial clients resisting standardized API connections.
For New Entrants and Emerging Players: CSRD reporting fast-track certification opens white-space in Swedish and Danish manufacturing mid-caps seeking ESG data outsourcing without captive infrastructure. Nordic markets present lowest competitive density relative to continental peers. Target cloud-native finance and accounting deployment for industrial enterprises facing regulatory compliance deadlines. Go-to-market angle emphasizes transaction-based pricing tied to accuracy SLAs rather than headcount commitments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists in Italian and French banking BPO lacking AI infrastructure scale. Five-to-ten year viability favors providers with embedded compliance architecture density over labor-arbitrage operators. Acquisition target archetype: vertical specialists with pharmaceutical inspection readiness in healthcare administration. Signal to watch: unbundling of monolithic contracts into modular components indicating procurement sophistication shift.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Architecture | Human-in-the-loop redesign for German automotive finance credit decisions satisfies enforcement deadlines. |
| Cloud Migration Partnership | SAP-certified middleware capabilities capture Stuttgart and Munich manufacturing headquarters demand. |
| Vertical Specialization Acquisition | Healthcare BPO with EMA audit trail readiness commands premium pricing from French regional authorities. |
| CSRD Reporting Service Launch | ESG data collection outsourcing meets Danish and Swedish manufacturing mid-cap regulatory deadlines. |
| Generative AI Copilot Deployment | Agent assistance tools in Dutch banking contact centers compress handle times below offshore benchmarks. |
Research Methodology
Desk research of EU regulatory filings, EMA guidance documents, and national banking supervisor reports preceded structured interviews with BPO procurement officers, compliance directors at German industrial enterprises, healthcare administration executives, and cloud infrastructure vendors. Primary fieldwork captured contract structuring practices and vendor selection criteria across France, Germany, Netherlands, and Poland. Secondary validation drew from GDPR enforcement case databases, CSRD implementation timelines, and ERP vendor partnership disclosures. Bottom-up service line sizing and top-down macroeconomic triangulation anchored value estimates.
Variance decomposition across service type, end-user scale, industry vertical, and deployment model shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include customer service modality, finance and accounting workflow complexity, healthcare versus manufacturing vertical exposure, and cloud-native versus hybrid infrastructure. CAGRs were derived from elasticity-adjusted demand curves and regulatory implementation schedules. Industry-specific inputs encompassed EU AI Act enforcement phasing and EMA inspection readiness requirements.
Underlying assumptions cover regulatory implementation timelines and enterprise cloud migration velocity, with deviation risk concentrated in divergent national AI Act interpretations and wage inflation persistence in Eastern European delivery centers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
North America Business Process-As-A-Service (Bpaas) Market
Business Process Outsourcing (BPO)
US Managed Print Services Market
Business Process Outsourcing (BPO)
BPO Business Analytics Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
Public Cloud Business Process Services Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
Customer Relationship Management (CRM) Outsourcing Market
Business Process Outsourcing (BPO)
Desktop Outsourcing Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
Cloud Based BPO Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market