
 Europe Data Center Networking Market | 2026-2036
Europe Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Networking Market Insights
Hyperscale operators are redrawing procurement priorities across Europe, shifting capital toward 400G and 800G Ethernet fabrics that support AI training clusters. Cisco Systems, Inc. leverages its installed base of enterprise and service provider relationships to defend switching revenue across Western European hubs. Arista Networks, Inc. specializes in low-latency, high-density platforms that dominate new AI datacenter builds. Nokia Corp. extends its position through optical interconnect and routing portfolios that anchor Nordic and Central European expansion projects.
Europe data center networking encompasses the switching, routing, cabling, and interconnect infrastructure that enables compute-to-compute and compute-to-storage communication within and between facilities, with modern deployments requiring port densities exceeding 51.2 Tbps per switch ASIC and latency budgets below 600 nanoseconds for AI workloads. Ethernet switching leads product type demand as hyperscalers standardize on this protocol for both front-end and back-end networks, while InfiniBand technology captures premium positioning in GPU cluster fabrics where bandwidth and congestion control parameters determine training throughput. Among end users, colocation providers occupy the fastest-growing demand segment as enterprises defer owned-facility capex in favor of multi-tenant environments with pre-provisioned cross-connect and cloud on-ramp services.
EU CSRD disclosure rules and the EU AI Act are mandating traceability, energy efficiency reporting, and risk classification for AI infrastructure, which shapes vendor qualification criteria and procurement specifications across member states. ETSI standards and national regulators in Germany, France, and the Netherlands enforce electromagnetic compatibility and cybersecurity certification that gate market access for non-compliant equipment. Stakeholders must monitor how the EU Green Deal's embodied carbon requirements for ICT equipment reshape total-cost-of-ownership calculations and supplier selection frameworks.
Market Dynamics
Hyperscale cloud operators are compressing refresh cycles from 36 to 18 months as AI training clusters demand 800G Ethernet fabrics with sub-microsecond latency guarantees. This procurement acceleration is reshaping vendor qualification timelines and capital allocation across Western European facilities.
Growth Catalysts
- EU AI Act compliance mandates:Risk classification requirements for high-impact AI systems are forcing enterprises to deploy sovereign infrastructure within member state borders.
- GPU cluster density requirements:Training workloads exceeding 10,000 accelerators per pod are necessitating new spine-leaf architectures with 51.2 Tbps switching capacity.
- Frankfurt-London-Amsterdam fiber corridors:Subsea and terrestrial route diversity investments are multiplying interconnection options for financial services latency arbitrage.
Market Restraints
- Optical component supply concentration:Coherent DSP and laser sources from a narrow East Asian supplier base create 26-week lead time volatility for 800G transceivers.
- CE marking electromagnetic compatibility testing:ETSI EN 300 386 certification delays for new switch silicon generations extend time-to-revenue by 4-8 months.
- Copper-cable distance limitations:Passive direct attach copper reaches 3 meters at 800G, forcing costly active optical cable migration for rack-scale deployments.
Strategic Opportunities
- Nordic renewable energy arbitrage:Norway and Sweden's hydroelectric surplus enables sub-1.10 PUE operations that attract AI training facility investment.
- Quantum-safe encryption hardware:Post-quantum cryptographic offload engines represent a nascent attach-rate opportunity for high-security government and finance verticals.
- CSRD Scope 3 reporting requirements:Embodied carbon disclosure mandates are creating preference for vendors with verified supply chain transparency and circular take-back programs.
Industry Challenges
- Terabit-scale network engineering talent scarcity:Design and operations expertise for 800G PAM4 signal integrity and liquid cooling integration remains concentrated among a limited workforce pool.
- Multi-vendor interoperability certification:Open Compute Project and SONiC compatibility testing consumes 6-12 months of pre-deployment validation for heterogeneous fabric builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Networking Market |
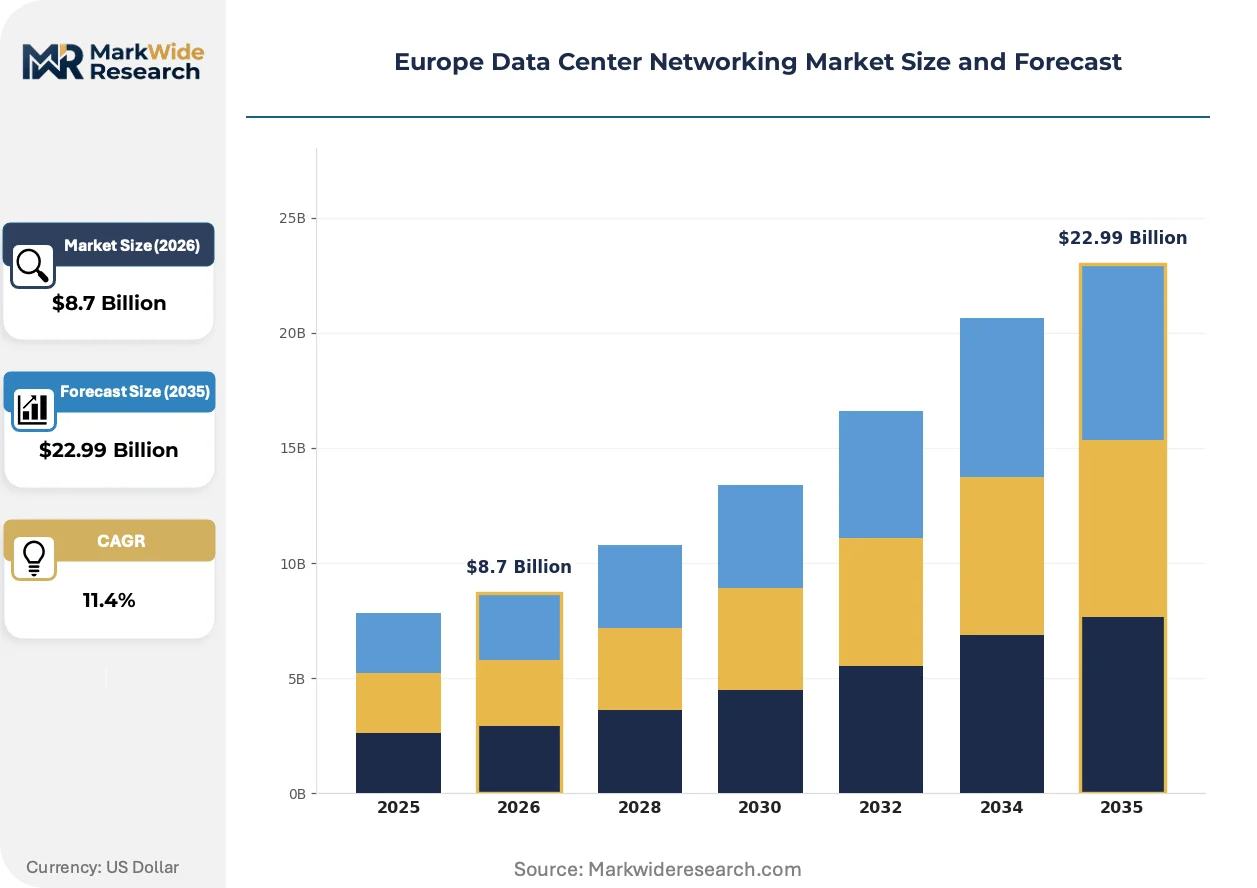
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Cables, Adapters Technology: Ethernet, InfiniBand, Fiber Channel, Wireless End User: Hyperscale Operators, Colocation Providers, Enterprises, Government Application: Cloud Computing, Virtualization, Data Storage, Disaster Recovery |
| Companies Covered | Cisco Systems, Inc., Arista Networks, Inc., Juniper Networks, Inc., Huawei Technologies Co., Ltd., Dell Technologies Inc., Extreme Networks Inc., Broadcom Inc., Hewlett Packard Enterprise Co., Nokia Corp., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Networking Market Trends and Innovations
Silicon photonics co-packaging is disrupting traditional pluggable transceiver economics while liquid cooling integration is becoming a mandatory design parameter rather than an efficiency option. These shifts are compressing hardware refresh timelines and redefining facility power density specifications.
Co-packaged optics technology is fragmenting the established pluggable transceiver supply chain by integrating optical engines directly onto switch ASIC substrates. Hyperscale operators in the Netherlands and Germany are piloting 51.2 Tbps platforms with co-packaged silicon photonics to reduce power per bit by 30 percent. This architecture is fragmenting procurement relationships as switch vendors assume direct responsibility for optical component qualification.
The EU Green Deal's embodied carbon requirements for ICT equipment are mandating lifecycle assessment documentation for all network hardware deployed in member states. Manufacturers must now disclose Scope 3 emissions from silicon wafer fabrication through end-of-life recycling. Colocation providers in France and Germany are incorporating these carbon intensity metrics into vendor scorecards alongside traditional TCO calculations.
Enterprise buyers are consolidating network procurement under sovereign cloud frameworks that mandate EU-based data residency and operational control. Financial services and defense contractors in Frankfurt and Paris are rejecting standard hyperscale contracts in favor of multi-tenant facilities with certified EU staff and audit rights. This behavioral pivot is fragmenting the colocation market into sovereign-certified and standard-tier supply pools with diverging pricing structures.
Europe Data Center Networking Market Segmentation
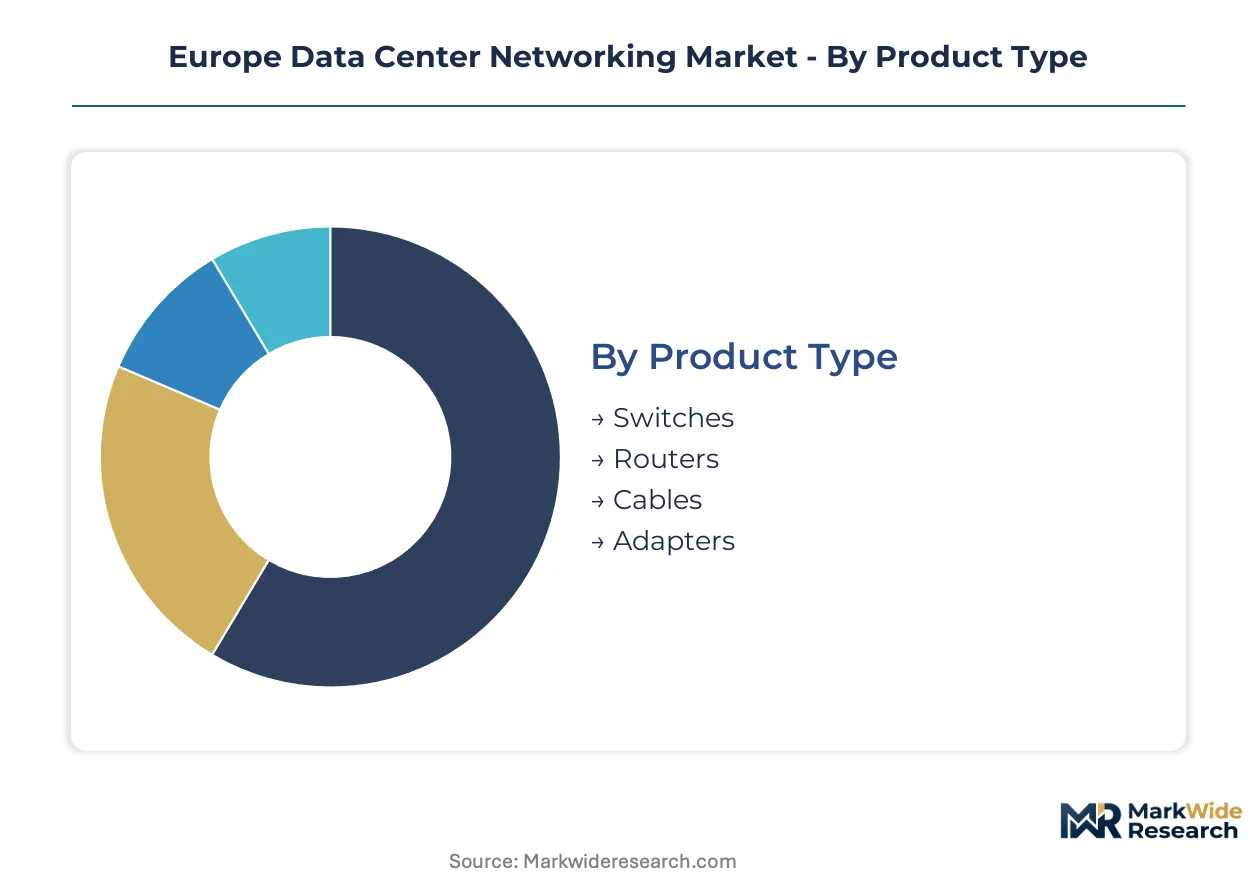
Segmentation in Europe data center networking reveals how procurement patterns diverge between sovereign infrastructure mandates and hyperscale efficiency targets. Each dimension—product, technology, end user, and application—carries distinct geographic and regulatory footprints that reshape vendor priorities across member states.
Product Type:
Switches dominate procurement volumes in Germany and France where hyperscale buildouts concentrate, while cables and adapters follow divergent trade flows shaped by CE marking requirements and optical component sourcing.
- Switches:High-density Ethernet platforms with 51.2 Tbps ASIC capacity anchor AI cluster fabrics. Demand concentrates in Frankfurt and Amsterdam for financial services latency arbitrage and cloud region expansion, with ETSI EN 300 386 certification gating market entry for new silicon generations.
- Routers:Backbone-class systems handle inter-facility traffic across the FLAP corridor. Procurement tilts toward Nokia and Cisco installations in Nordic markets where submarine cable landing stations require redundant path diversity.
- Cables:Active optical cables at 800G displace passive copper beyond 3-meter reaches. Dutch and German facilities drive volume as rack-scale AI deployments multiply.
- Adapters:SmartNICs and DPUs offload network processing from host CPUs. French defense contractors and German automotive enterprises specify these for zero-trust segmentation compliance.
Switches hold the largest share; momentum sits with cables as 800G migration accelerates.
Technology:
Protocol selection splits between hyperscale standardization pressures and specialized workload requirements, with cost tiers separating commodity Ethernet from premium InfiniBand deployments.
- Ethernet:400G and 800G standards dominate front-end and back-end networks. Hyperscalers in the Netherlands and Ireland standardize on this protocol for cost-efficient scale, with OCP and SONiC compatibility testing consuming 6-12 months pre-deployment.
- InfiniBand:RDMA-enabled fabrics deliver sub-microsecond latency for GPU clusters. Training workloads exceeding 10,000 accelerators per pod in Frankfurt and Paris mandate this technology despite premium pricing.
- Fiber Channel:Legacy storage area networks persist in German manufacturing and French healthcare where FC-NVMe transition timelines extend refresh decisions.
- Wireless:60 GHz and Wi-Fi 6E support edge compute and maintenance access. Nordic facilities deploy these for flexible rack repositioning without structured cabling disruption.
Ethernet commands volume leadership; InfiniBand is climbing the fastest as AI training clusters multiply.
End User:
Customer type determines facility ownership models, with government and enterprise buyers prioritizing sovereign certification while hyperscalers optimize for energy arbitrage.
- Hyperscale Operators:Cloud providers compress refresh cycles from 36 to 18 months for AI infrastructure. Norway and Sweden attract these operators with sub-1.10 PUE hydroelectric power.
- Colocation Providers:Multi-tenant facilities capture deferred enterprise capex with pre-provisioned cross-connects. Interxion and Equinix expansions in Frankfurt, Amsterdam, and Paris lead regional supply growth.
- Enterprises:Automotive, pharmaceutical, and financial services firms in Stuttgart, Basel, and London maintain owned facilities for regulatory control.
- Government:Defense and intelligence agencies in France, Germany, and the UK mandate EU staff certification and audit rights, fragmenting procurement into sovereign-tier pools.
Hyperscale operators anchor revenue concentration; colocation providers are gaining share fastest as enterprise outsourcing accelerates.
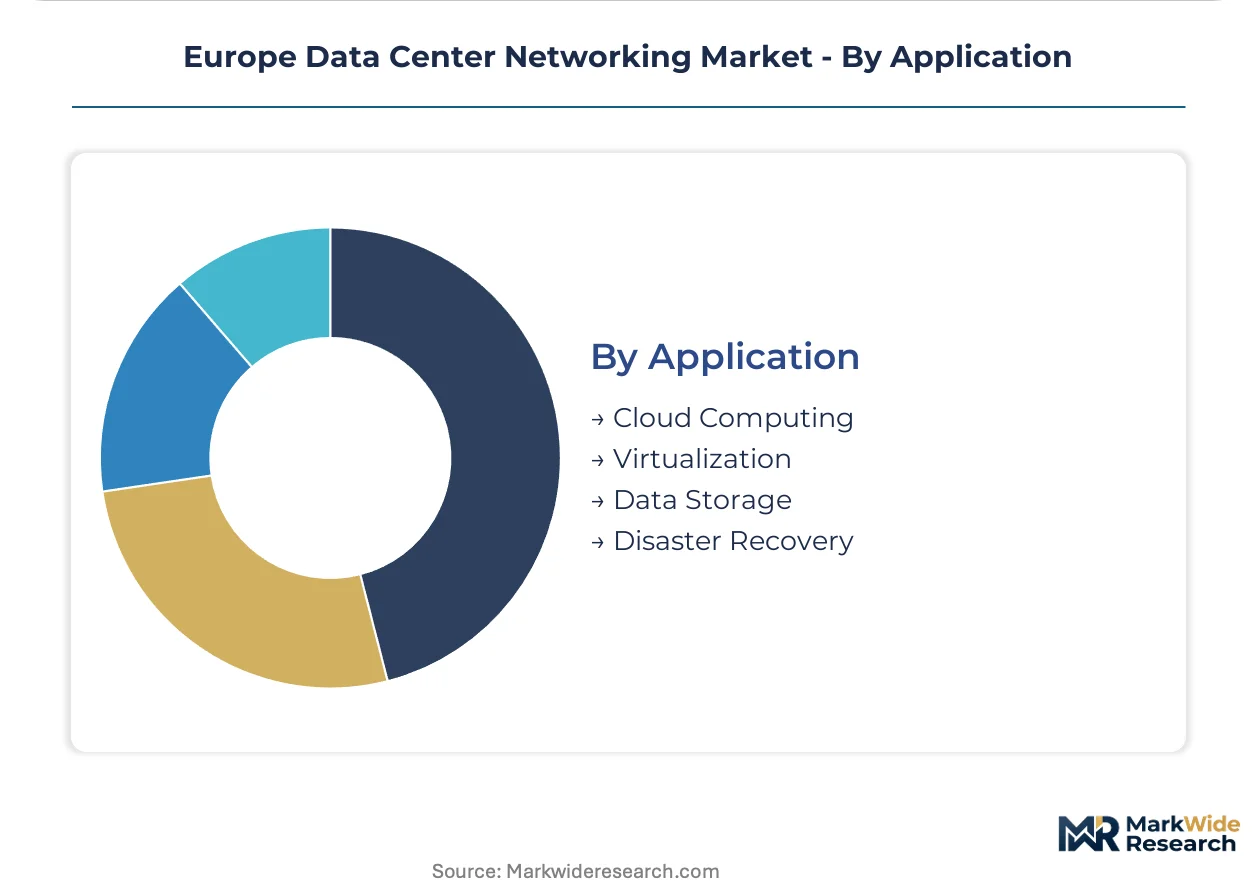
Application:
Workload purpose shapes network architecture, with cloud and virtualization demanding horizontal scale while storage and recovery prioritize deterministic performance.
- Cloud Computing:Public and private cloud aggregation requires spine-leaf topologies with east-west bandwidth dominance. French and German sovereign cloud frameworks redirect procurement toward EU-controlled facilities.
- Virtualization:SDN overlays and container networking demand programmable data planes. Kubernetes cluster networking in Amsterdam and Dublin drives SmartNIC attachment rates.
- Data Storage:NVMe-oF and distributed object storage need lossless Ethernet or converged fabrics. Italian and Spanish enterprises lag northern adoption curves due to infrastructure investment gaps.
- Disaster Recovery:Synchronous replication within 100km radii mandates dedicated dark fiber or wavelength services. London-Frankfurt and Frankfurt-Milan corridors carry critical financial services traffic.
Cloud computing holds the largest share; disaster recovery shows steepest expansion trajectory as regulatory resilience mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
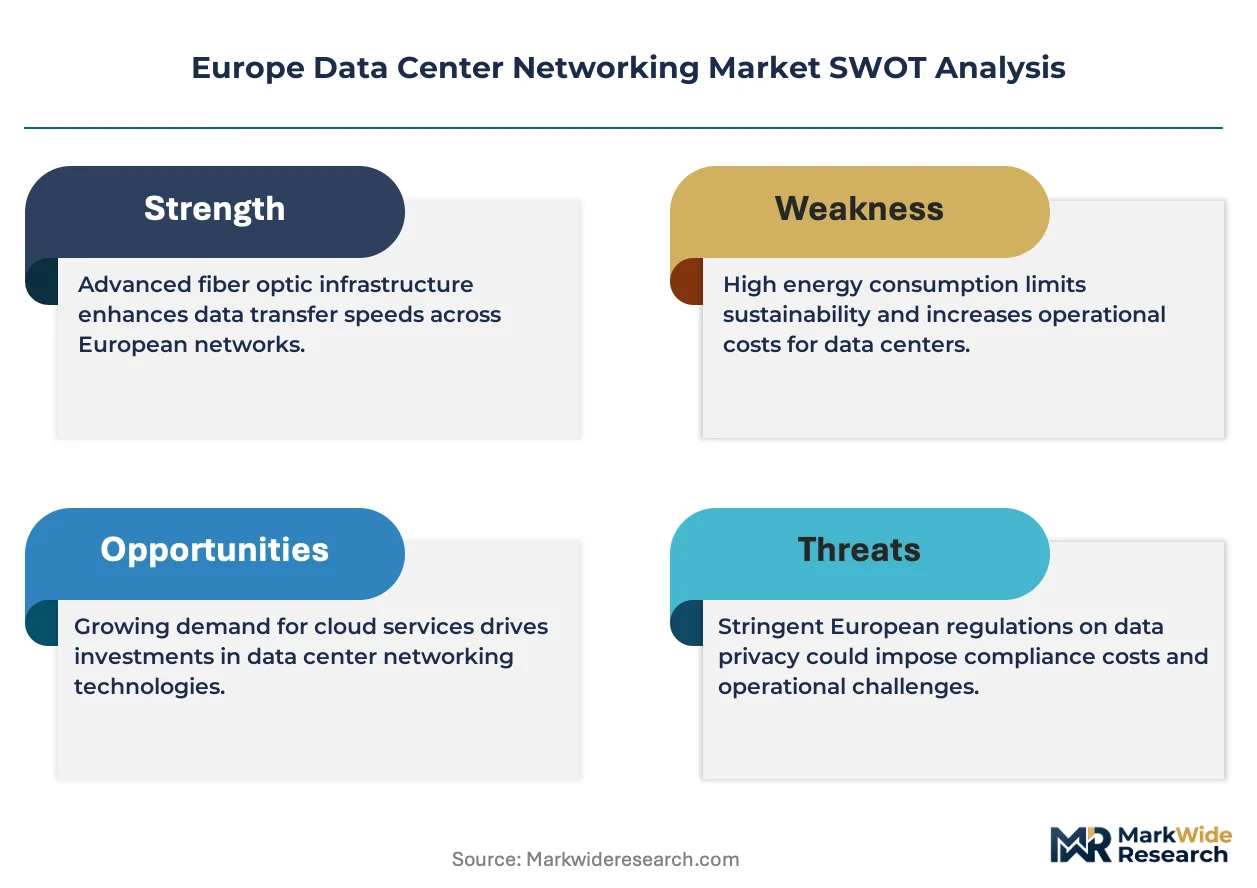
The FLAP fiber corridor—Frankfurt-London-Amsterdam-Paris—underwrites Europe's data center networking gravity, with subsea cable landings and terrestrial cross-border routes multiplying interconnection capacity across Western European hubs.
Germany
Hyperscale AI training clusters and automotive cloud workloads drive 800G switching demand. The EU AI Act's risk classification rules force sovereign infrastructure deployment within national borders. Frankfurt anchors the largest concentration, where Equinix and CyrusOne expand campus-scale facilities with direct cloud on-ramps.
Netherlands
Amsterdam's AMS-IX peering density and North Sea cable landings attract latency-sensitive financial services networks. The Dutch Authority for Digital Infrastructure enforces NIS2 cybersecurity standards for critical facility operators. Eindhoven and Rotterdam host emerging edge compute zones with 400G metro interconnects.
France
Sovereign cloud frameworks redirect procurement toward EU-controlled data residency solutions. ANSSI certification requirements gate market access for government and defense network equipment. Paris and Marseille benefit from trans-Mediterranean cable investments linking African and Middle Eastern traffic.
United Kingdom
Post-Brexit data adequacy arrangements sustain London's role as a financial services networking hub. Ofcom regulates wholesale fiber access and interconnection pricing for multi-tenant facilities. Slough and London Docklands concentrate colocation supply with direct access to transatlantic cable systems.
Sweden
Hydroelectric surplus enables sub-1.10 PUE operations that attract AI training facility investment from international operators. The Swedish Energy Agency's efficiency incentives accelerate liquid cooling adoption. Luleå and Stockholm host major cloud regions with direct renewable power purchase agreements.
Europe Data Center Networking Market Competitive Landscape
Concentration sits with diversified networking incumbents and specialized low-latency fabric providers. The vendor landscape splits between three strategic archetypes: established enterprise networking conglomerates defending installed bases, cloud-native specialists capturing hyperscale buildouts, and optical interconnect providers anchoring long-haul and metro deployments. Competitive moves center on silicon photonics co-packaging partnerships and sovereign cloud certification programs that gate public sector procurement.
Within the diversified incumbent tier, Cisco Systems, Inc. and Dell Technologies Inc. represent entrenched positions across enterprise and service provider channels. Arista Networks, Inc. exemplifies the hyperscale-specialist archetype with density-optimized platforms. Nokia Corp. anchors optical and routing portfolios across Nordic and Central European infrastructure projects. These three patterns—incumbent breadth, hyperscale focus, and optical specialization—capture the competitive structure visible in procurement data.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Arista Networks, Inc. |
| Juniper Networks, Inc. |
| Huawei Technologies Co., Ltd. |
| Dell Technologies Inc. |
| Extreme Networks Inc. |
| Broadcom Inc. |
| Hewlett Packard Enterprise Co. |
| Nokia Corp. |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with East Asian optical component suppliers lock in 800G transceiver availability while capping price volatility for Dutch and German hyperscale operators. These arrangements tie switch vendors to 18-24 month procurement horizons that compress margin flexibility when silicon photonics co-packaging disrupts legacy pluggable economics.
Pricing Analysis
Volume-discount tiering structures separate hyperscale direct procurement from colocation provider aggregator pricing and enterprise spot purchases. Certification grade—specifically ETSI EN 300 386 electromagnetic compatibility and ANSSI cybersecurity tiers—drives price differentiation alongside port density specifications. Pricing pressure stems from coherent DSP supply concentration forcing switch vendors to absorb optical component cost spikes. Hyperscale operators exhibit lowest price sensitivity due to TCO-optimized refresh cycles, while mid-market enterprises face procurement delays from budget fragmentation.
Supply Chain Analysis
Inventory buffers at 26-week lead times for 800G transceivers expose European switch vendors to allocation volatility from Taiwan and South Korean coherent DSP foundries. Silicon wafers, laser sources, and passive optical components feed from this East Asian manufacturing base. Single-source vulnerability concentrates in indium phosphide laser suppliers, with tariff exposure rising on US-China technology restrictions. Distribution runs through direct OEM relationships for hyperscalers and channel partners for enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale operators and sovereign-certified colocation providers, fragmenting procurement into volume-tiered and compliance-tiered pools that reshape vendor margin structures.
For Market Incumbents: Compound defensive positions through silicon photonics co-packaging partnerships that internalize optical component qualification and compress supplier count. Deepen certification investment in EU AI Act and NIS2 compliance frameworks to gate public sector procurement against emerging cloud-native competitors. Prioritize liquid cooling integration capabilities as Nordic energy arbitrage attracts AI training facility investment. For New Entrants and Emerging Players: Sovereign cloud managed service gaps in French and German defense verticals offer white-space entry where ANSSI certification requirements delay incumbent response times. Target mid-market automotive enterprises in Stuttgart and Wolfsburg with pre-certified, pre-integrated edge networking bundles. Pursue co-development partnerships with Nordic renewable-powered facility operators seeking sub-1.10 PUE network architectures. For Investors and Strategic Acquirers: Capital is best deployed toward optical interconnect specialists with coherent DSP design capabilities and established CE marking pathways. Long-term viability rests on positioning for post-quantum cryptographic offload engine attach rates in high-security government and finance verticals. Monitor EU Green Deal embodied carbon disclosure enforcement as the inflection signal for circular take-back program valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Co-Packaging Partnership | Integrates optical engines onto switch ASIC substrates, reducing power per bit by 30 percent for Dutch hyperscale pilots. |
| Sovereign Cloud Certification Program | ANSSI and BSI cybersecurity tiers gate French and German public sector procurement against non-compliant vendors. |
| Liquid Cooling Integration Investment | Sub-1.10 PUE operations in Sweden and Norway attract AI training facility operators with direct renewable PPAs. |
| Post-Quantum Cryptographic Hardware Development | Offload engines address EU AI Act risk classification requirements for high-impact government systems. |
| Scope 3 Supply Chain Transparency Program | Embodied carbon disclosure mandates from the EU Green Deal reshape vendor scorecards at Equinix and Interxion. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hyperscale network architects, colocation procurement directors, and ETSI certification engineers; and secondary validation through hyperscaler capex disclosures, SEC filings, EU regulatory filings, and customs trade data. Bottom-up demand modeling across switching, routing, and interconnect product categories triangulated against top-down market sizing from facility buildout pipelines.
Across the analysis window, forecasts incorporate segmentation by product type, protocol technology, end-user archetype, and application workload, with regional regulatory clusters treated as distinct adoption environments. CAGRs derive from facility deployment velocity, refresh cycle compression, and sovereign infrastructure mandate timelines. AI training cluster density requirements and NIS2 cybersecurity enforcement serve as primary demand elasticity inputs.
Forecasts assume regulatory continuity in EU AI Act implementation, CSRD disclosure rules, and NIS2 critical infrastructure standards; material policy shifts or trade restriction escalations would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Global Data Lakes Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Dark Fiber Network Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Singapore Data Center Networking Market
Data Center and Networking
Global Data Fabric Market