
 Europe Warranty Management System Market | 2026-2036
Europe Warranty Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Warranty Management System Market Foresight
Subscription-based maintenance overlays for industrial equipment is realigning how European manufacturers monetize post-sale relationships. SAP SE leverages deep ERP integration to anchor enterprise warranty workflows across German automotive clusters. Syncron AB specializes in aftermarket service lifecycle management, sustaining competitive position through predictive parts planning. Oracle Corporation extends cloud infrastructure dominance into warranty analytics, competing on scalability for multi-national manufacturer networks.
A warranty management system constitutes an integrated software platform that automates claim validation, tracks product failure patterns, and manages service entitlements across distributed supply chains, typically processing structured data from IoT sensors, ERP modules, and field service records to reduce fraudulent claims and accelerate resolution cycles. Cloud Deployment and SaaS models are capturing fastest expansion as manufacturers abandon capital-intensive on-premises installations for elastic subscription economics. Software Solutions anchored by machine learning modules command the deepest margin pools, while Blockchain-enabled verification remains nascent but attracts pilot investment from premium automotive brands seeking tamper-proof service histories.
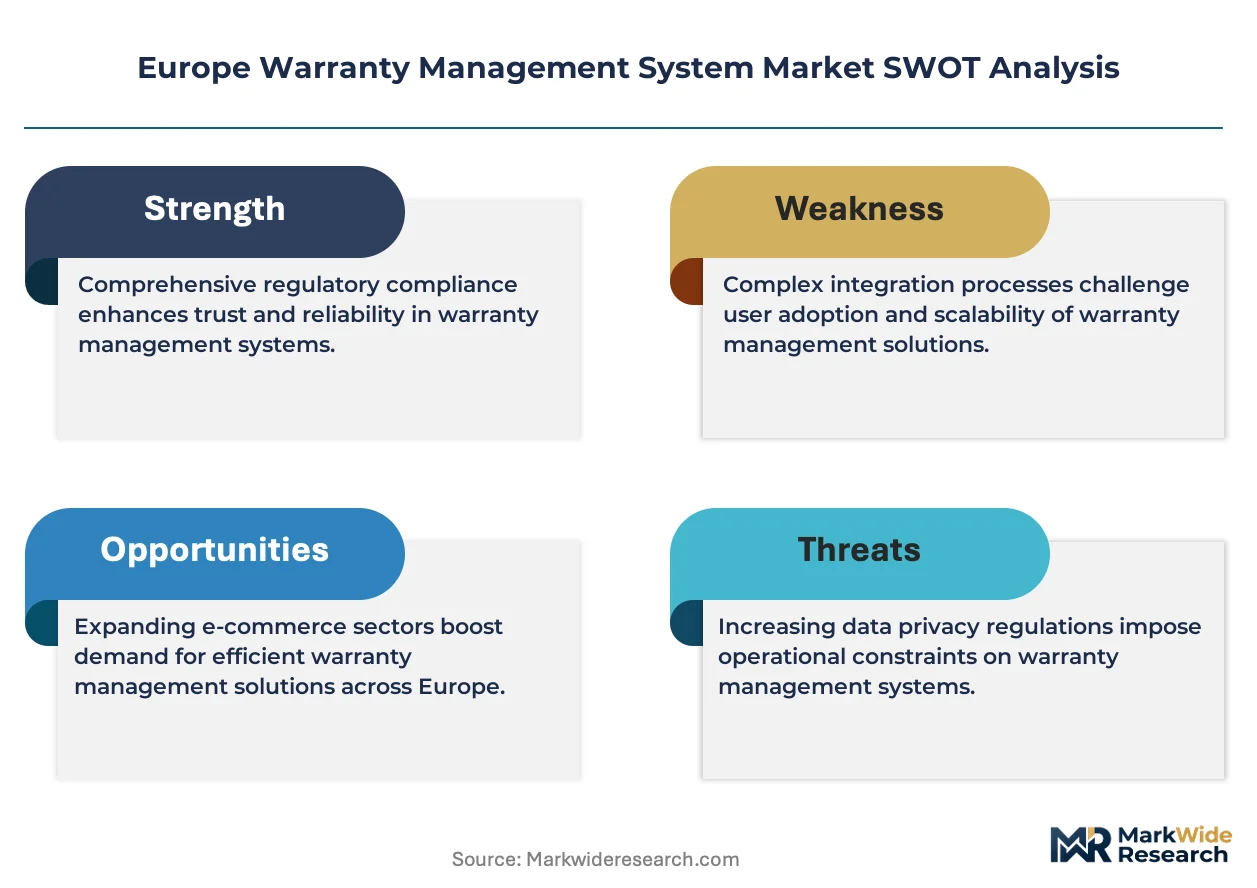
The EU AI Act and GDPR impose strict algorithmic transparency and data residency requirements on automated warranty decision systems, compelling vendors to architect explainable claim-scoring models and EU-localized data processing. The EU Green Deal's right-to-repair mandates force manufacturers to maintain extended warranty documentation for reconditioned components, expanding addressable system scope. Stakeholders must monitor how CSRD sustainability reporting rules will integrate warranty return rates into mandatory corporate disclosures, reshaping platform requirements.
Market Dynamics
Cloud-native warranty platforms are compressing deployment timelines across European manufacturing clusters, displacing decade-old on-premises installations that required multi-year capital commitments and specialized infrastructure teams.
Growth Catalysts
- EU Digital Operational Resilience Act (DORA):Financial and manufacturing enterprises must maintain auditable warranty records, accelerating compliance-oriented software procurement across German automotive and industrial equipment sectors.
- Automotive electrification:Battery-electric vehicle platforms generate complex thermal and electronic failure modes that legacy warranty systems cannot track, forcing OEMs toward predictive analytics modules.
- Right-to-repair mandates:The EU Green Deal compels manufacturers to maintain extended documentation for reconditioned components, expanding system scope beyond original equipment to cover refurbished supply chains.
Market Restraints
- GDPR data residency requirements:Algorithmic transparency mandates under the EU AI Act force vendors to localize processing infrastructure, raising operational costs for cloud-native providers serving multi-jurisdictional clients.
- Legacy ERP entrenchment:German automotive clusters run heavily customized SAP environments that resist modular warranty platform integration without expensive middleware development.
- Skills concentration:Machine learning engineers with domain expertise in industrial failure prediction cluster in Munich, Stuttgart, and Paris, creating talent scarcity for vendors expanding into secondary markets.
Strategic Opportunities
- France's aerospace aftermarket:Toulouse and Bordeaux maintenance hubs lack integrated warranty-to-MRO data pipelines, creating whitespace for platforms bridging OEM warranties with airline operator records.
- Blockchain verification pilots:Premium automotive brands in Italy and Germany are testing tamper-proof service histories, opening early-adopter revenue streams before standardization.
- CSRD sustainability integration:The Corporate Sustainability Reporting Directive will mandate warranty return rate disclosures, positioning analytics vendors to embed carbon-footprint modules alongside traditional claim management.
Industry Challenges
- Interoperability friction:Field service management platforms from different vendors use incompatible data schemas, forcing warranty providers to maintain expensive custom connectors for each client installation.
- Explainable AI compliance:The EU AI Act requires automated claim-scoring models to produce auditable decision trails, extending development cycles for vendors relying on black-box neural networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Warranty Management System Market |
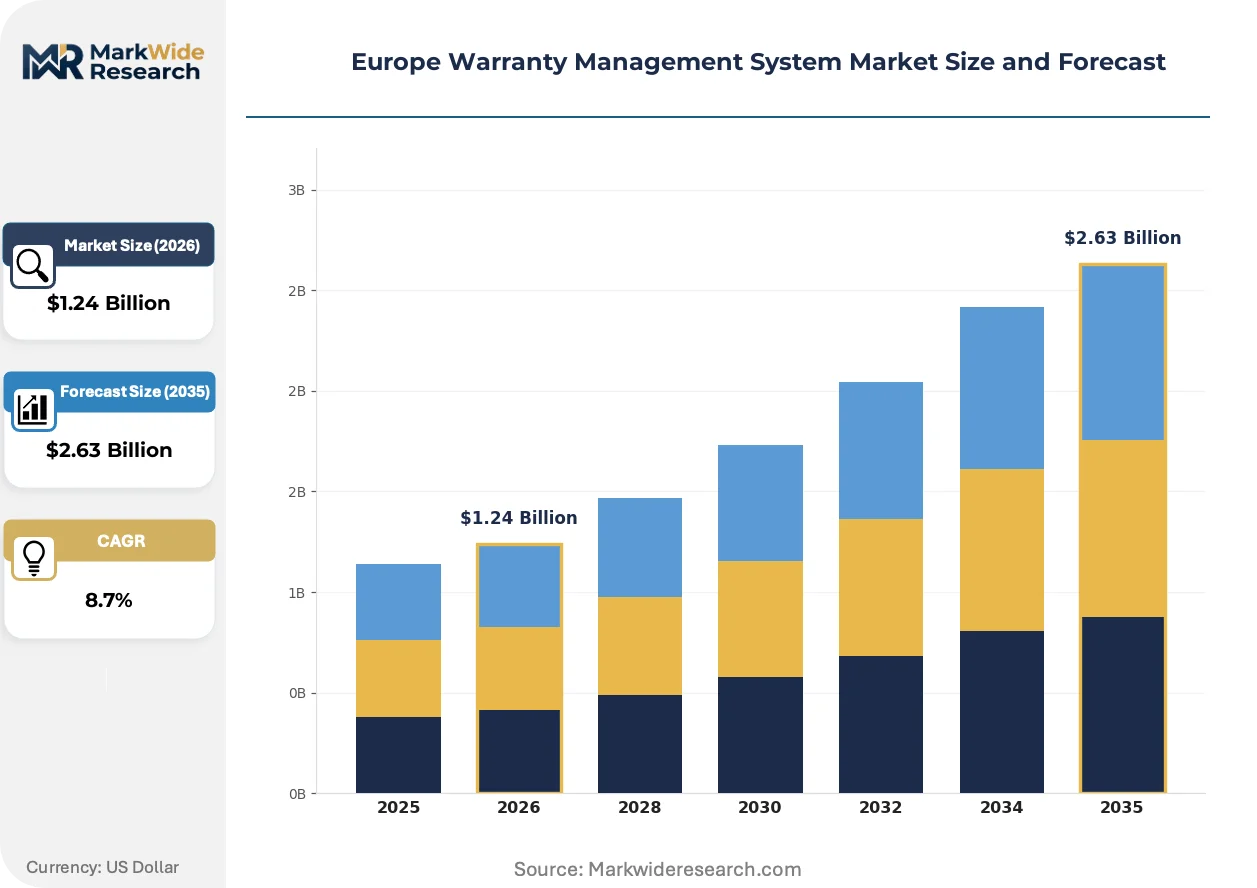
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.63 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Cloud-Based Management, Integration Services, Analytics Tools End User: Manufacturers, Retail Chains, Service Providers, Distributors Deployment: On-Premises, Cloud Deployment, Hybrid Models, SaaS Technology: Machine Learning, Predictive Analytics, Blockchain, IoT Solutions |
| Companies Covered | Syncron AB, IFS AB, SAP SE, ServiceMax Inc., Tavant Technologies Inc., Oracle Corporation, PTC Inc., Infor, Sage, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Warranty Management System Market Shifts & Advancements
Warranty management is pivoting from reactive claim processing toward predictive service orchestration, embedding machine learning directly at the edge of industrial equipment networks.
Machine learning modules for failure prediction are consolidating vendor competitive positions across the European automotive aftermarket. Tier-1 suppliers in Germany and France are deploying these tools at pilot scale, compressing the window between anomaly detection and service dispatch from days to hours. Early movers are capturing multi-year contracts by embedding predictive capabilities into existing maintenance agreements.
The EU AI Act's algorithmic transparency requirements are forcing architectural redesigns across automated warranty decision systems. Vendors must now produce explainable claim-scoring models that regulators and customer ombudsmen can audit, raising development costs but creating compliance moats against non-European competitors. Financial services and automotive verticals face the steepest compliance burdens given their high claim volumes.
After-sales service unbundling is disrupting traditional warranty bundling practices among industrial equipment buyers. German machine-tool operators now procure predictive maintenance subscriptions separately from base warranty coverage, fragmenting vendor revenue streams. This pattern is most visible in Bavaria's automotive supplier ecosystem, where procurement teams negotiate service tiers independently of capital equipment purchases.
Europe Warranty Management System Market Segmentation
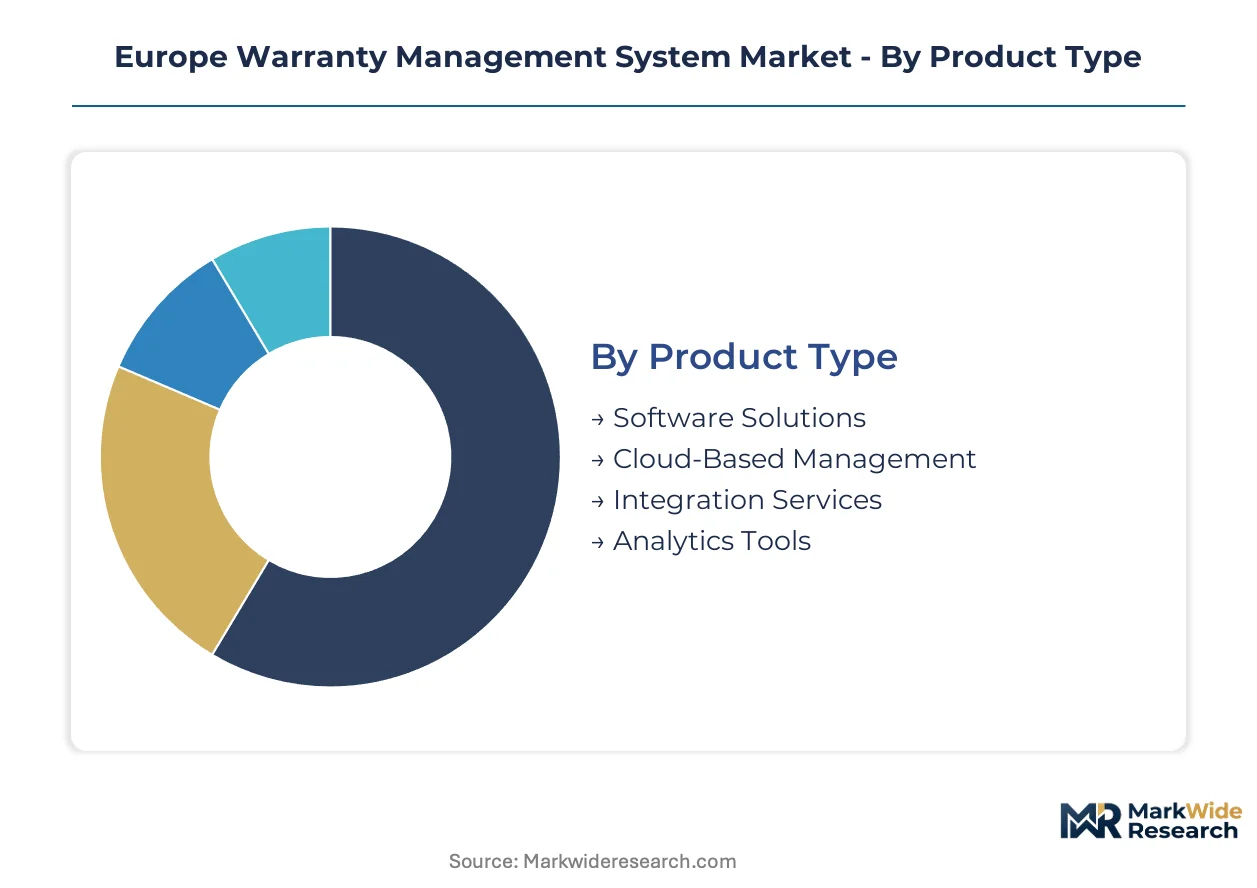
Warranty management system segmentation reveals how European manufacturers balance specialized functionality against integration complexity. Each category reflects distinct procurement priorities across German automotive clusters, French aerospace hubs, and industrial equipment networks spanning the continent.
Product Type:
Standardized modules dominate low-complexity deployments, while customized configurations command premium pricing in multi-site manufacturing environments.
- Software Solutions:Core platforms automate claim validation, entitlements tracking, and supplier recovery workflows. German automotive OEMs in Stuttgart and Munich anchor regional demand, driven by EU Digital Operational Resilience Act audit requirements for structured warranty record-keeping.
- Cloud-Based Management:Elastic infrastructure eliminates capital-intensive server procurement, compressing deployment timelines from years to months. French industrial equipment makers in Lyon and Grenoble favor these offerings for distributed service networks, though GDPR data residency rules force EU-localized processing investments.
- Integration Services:Middleware development connects warranty platforms to legacy ERP environments.
- Analytics Tools:Visualization and reporting modules extract actionable intelligence from claim patterns.
Leading the category by volume: Software Solutions. Growing fastest: Cloud-Based Management.
End User:
Procurement authority varies sharply across this spectrum, with capital equipment buyers demanding predictive capabilities and retail operators prioritizing cost containment.
- Manufacturers:Industrial equipment and automotive producers generate the deepest warranty data volumes. Bavarian machine-tool operators now unbundle predictive maintenance subscriptions from base coverage, fragmenting vendor revenue streams while expanding addressable system scope.
- Service Providers:Independent repair networks and authorized dealers require claim submission portals and parts entitlement verification. Italian premium automotive brands in Modena and Maranello pilot blockchain-enabled service history verification through these channels.
- Retail Chains:Consumer electronics and appliance sellers manage extended warranty programs.
- Distributors:Wholesale intermediaries track batch-level defect rates and coordinate returns.
Manufacturers capture the largest revenue share. Service Providers are climbing the fastest as aftermarket unbundling accelerates.
Deployment:
Capital intensity and data sovereignty concerns create divergent adoption patterns across regulated industries and mid-market players.
- Cloud Deployment:Subscription economics displace multi-year capital commitments, with elastic scaling matching warranty claim volatility. Multi-national manufacturers spanning Germany, France, and Poland favor this model for centralized visibility across dispersed production sites.
- SaaS:Pre-configured tenant environments accelerate time-to-value for mid-market industrial equipment makers. GDPR and EU AI Act compliance burdens concentrate development resources among established vendors, creating compliance moats.
- On-Premises:Heavily customized installations persist in German automotive clusters with entrenched SAP environments.
- Hybrid Models:Split architectures isolate sensitive claim data locally while leveraging cloud analytics.
Cloud Deployment holds the dominant position. SaaS is gaining share fastest among mid-market entrants.
Technology:
Maturity gradients separate proven automation from experimental verification methods, with regulatory pressure accelerating explainable AI development.
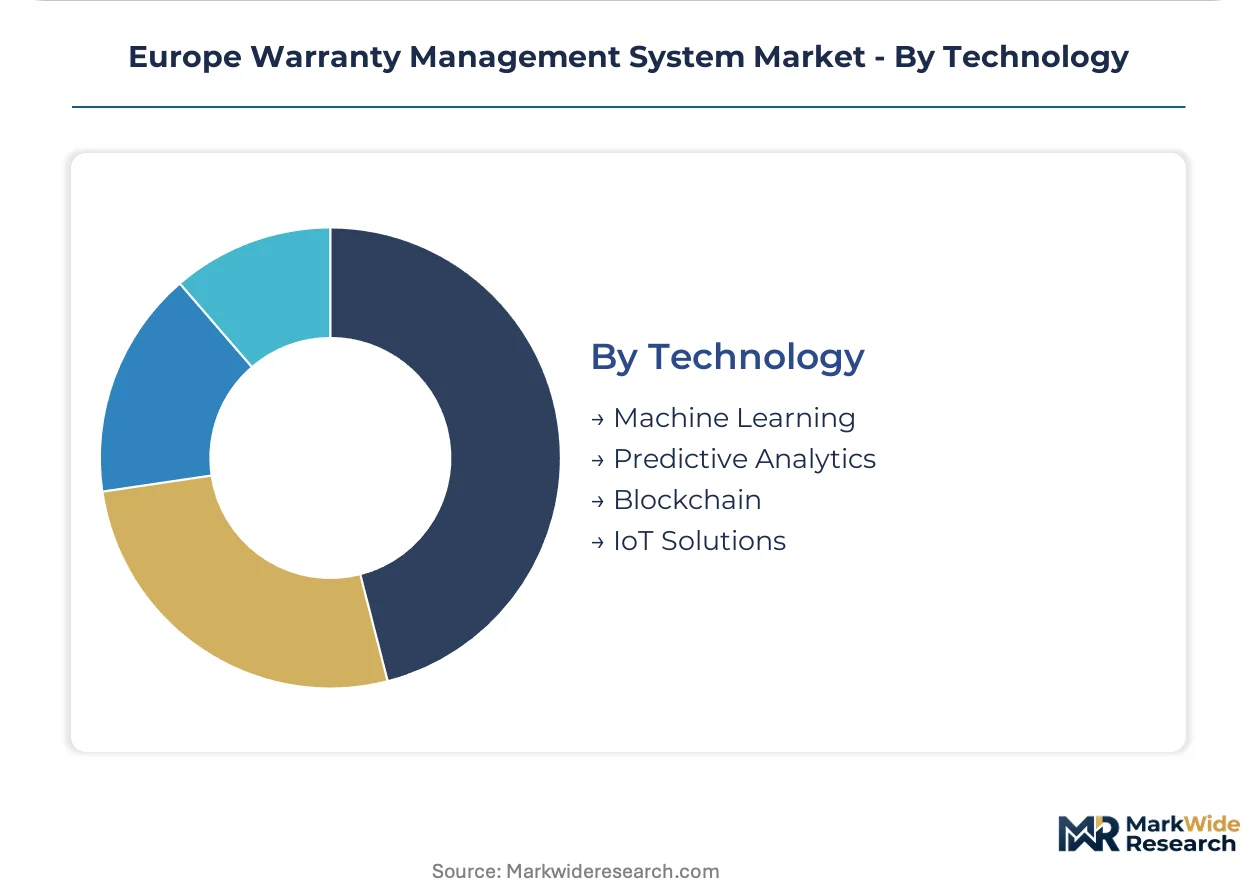
- Machine Learning:Failure prediction algorithms compress anomaly-to-dispatch windows from days to hours. Tier-1 automotive suppliers in Germany deploy these modules at pilot scale, embedding predictive capabilities into multi-year maintenance agreements.
- Predictive Analytics:Statistical models forecast component degradation and optimize spare parts positioning. French aerospace maintenance hubs in Toulouse lack integrated warranty-to-MRO data pipelines, creating whitespace for platforms bridging OEM coverage with airline operator records.
- IoT Solutions:Edge-connected sensors stream operational telemetry directly into entitlement systems.
- Blockchain:Tamper-proof service histories attract pilot investment from premium automotive brands seeking fraud-resistant documentation.
Machine Learning leads technology investment. Predictive Analytics shows the steepest expansion trajectory as CSRD sustainability reporting mandates warranty return rate disclosures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European warranty management system deployment, with automotive OEMs and Tier-1 suppliers driving enterprise software procurement across German industrial corridors.
Germany
Bavarian machine-tool operators and Stuttgart automotive clusters generate the deepest warranty data volumes in Europe. The EU Digital Operational Resilience Act compels financial and manufacturing enterprises to maintain auditable warranty records, accelerating compliance-oriented software procurement. Munich and Stuttgart host concentrated vendor development operations serving multi-national manufacturer networks.
France
Toulouse and Bordeaux aerospace maintenance hubs lack integrated warranty-to-MRO data pipelines, creating whitespace for platforms bridging OEM coverage with airline operator records. The EU AI Act imposes algorithmic transparency requirements on automated claim-scoring systems used by financial services and automotive verticals. Paris-based software vendors are localizing processing infrastructure to satisfy GDPR data residency mandates.
United Kingdom
London financial services firms deploy warranty management platforms to satisfy CSRD sustainability reporting requirements for embedded product guarantees. The UK Information Commissioner's Office enforces data protection standards parallel to GDPR, shaping cloud deployment architectures. Midlands manufacturing clusters are piloting predictive analytics modules for industrial equipment failure forecasting.
Italy
Modena and Maranello premium automotive brands pilot blockchain-enabled service history verification, opening early-adopter revenue streams before standardization. The EU Green Deal's right-to-repair mandates compel manufacturers to maintain extended documentation for reconditioned components. Northern Italian industrial districts are unbundling predictive maintenance subscriptions from base warranty coverage.
Poland
Multi-national manufacturers favor cloud deployment models for centralized visibility across dispersed production sites spanning Germany, France, and Polish manufacturing zones. GDPR compliance burdens concentrate development resources among established vendors, creating compliance moats against non-European competitors. Warsaw and Krakow are emerging as delivery centers for warranty platform implementation services.
Europe Warranty Management System Market Competitive Landscape
Capital-heavy ERP integrators compete with asset-light SaaS specialists across European warranty management, creating a tiered vendor structure. The market consolidates around three strategic archetypes: enterprise resource planning anchors with deep manufacturing connectivity, aftermarket service lifecycle specialists with predictive capabilities, and cloud infrastructure providers extending analytics dominance. Dominant competitive moves include strategic partnerships with automotive OEMs and vertical integration into predictive maintenance modules.
Among Nordic-based specialists, Syncron AB and IFS AB exemplify the aftermarket service lifecycle archetype, embedding predictive parts planning into multi-year maintenance agreements. SAP SE anchors the enterprise integration tier, leveraging deep ERP connectivity across German automotive clusters. These three occupy positions reflecting distinct strategic bets: SaaS elasticity versus embedded manufacturing workflows versus comprehensive enterprise suites.
| Leading Market Players |
|---|
| Syncron AB |
| IFS AB |
| SAP SE |
| ServiceMax Inc. |
| Tavant Technologies Inc. |
| Oracle Corporation |
| PTC Inc. |
| Infor |
| Sage |
| Others |
Supply & Pricing Matrix
Machine learning engineers with warranty analytics expertise cluster in Munich, Stuttgart, and Paris, creating labor-cost differentials that widen pricing-tier spreads between premium predictive modules and standardized claim-processing platforms. German automotive OEMs absorb these premiums for embedded ERP-integrated solutions, while mid-market French industrial equipment makers gravitate toward SaaS alternatives that compress implementation labor.
Pricing Analysis
Value-based pricing anchored to warranty claim reduction outcomes dominates enterprise procurement conversations, with manufacturers paying against realized fraud detection rates and accelerated resolution cycles. Three-tier pricing structure across premium, standard, and economy levels separates deep ERP-integrated suites from modular cloud offerings and entry-level claim portals. Cost compression in the mid-market tier is intensifying because GDPR-compliant EU-localized infrastructure raises operational overhead for SaaS providers. Retail chains and independent service providers exhibit the sharpest price sensitivity, while German automotive clusters prioritize functionality over procurement cost.
Supply Chain Analysis
The EU AI Act's algorithmic transparency mandates and GDPR data residency rules are reshaping sourcing toward EU-based cloud infrastructure and localized development talent. Software development concentrates in Germany, France, and Poland, with Warsaw and Krakow emerging as delivery centers for implementation services. Platform architecture rests on proprietary machine learning frameworks, open-source analytics libraries, and ERP connector middleware. Single-source vulnerability concentrates in specialized ML engineering talent pools. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with vendors pursuing backward integration into predictive maintenance hardware and forward integration into field service dispatch networks to capture full after-sale value chains.
For Market Incumbents: Deploy explainable AI development resources to satisfy EU AI Act audit requirements before non-European competitors can adapt their black-box architectures. Deepen ERP connector libraries to defend against modular SaaS challengers targeting SAP-entrenched German automotive clusters. The regulatory shift toward algorithmic transparency threatens vendors relying on opaque neural networks for claim scoring.
For New Entrants and Emerging Players: Capture the whitespace in France's aerospace aftermarket by building warranty-to-MRO data pipelines that bridge OEM coverage with airline operator records. Target blockchain-enabled service history verification for Italian premium automotive brands seeking fraud-resistant documentation before standardization freezes competitive entry. A specialist partnership strategy with regional systems integrators accelerates credibility in legacy-ERP environments.
For Investors and Strategic Acquirers: Re-rating potential sits with aftermarket service lifecycle specialists given CSRD sustainability reporting mandates expanding warranty analytics scope into carbon-footprint modules. Long-term viability favors platforms with predictive capabilities embedded in multi-year maintenance agreements rather than transactional claim-processing tools. Watch for inflection when CSRD disclosure deadlines force industrial manufacturers to procure integrated warranty-sustainability reporting suites.
| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Architecture Investment | EU AI Act compliance creates defensible moats against non-European competitors lacking auditable decision trails. |
| ERP Connector Ecosystem Expansion | Deep SAP integration defends market position in German automotive clusters resisting modular platform adoption. |
| Predictive Maintenance Hardware Integration | Backward integration into IoT sensor networks captures edge-data streams before third-party intermediation. |
| Blockchain Service History Pilots | Early partnerships with Italian premium brands establish standards influence before industry-wide protocol adoption. |
| CSRD Sustainability Module Development | Warranty return rate disclosure requirements position analytics vendors for mandatory corporate reporting procurement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with warranty platform product managers, automotive aftermarket directors, industrial equipment maintenance heads, and ERP integration specialists. Secondary validation drew from EU Digital Operational Resilience Act implementation guidance, GDPR enforcement precedent, CSRD technical standards drafts, and cloud infrastructure expenditure disclosures. Bottom-up deployment estimates across German, French, and Polish manufacturing clusters were reconciled with top-down software market sizing from technology trade associations.
Data-stream reconciliation across vendor revenue disclosures, enterprise procurement patterns, and regulatory compliance timelines informed the analytical framework. Segmentation dimensions modeled include deployment architecture, end-user procurement authority, integration complexity tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and compliance-mandated replacement cycles. Forecast inputs incorporated EU AI Act implementation phasing and CSRD disclosure deadline clustering.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory enforcement variance and machine learning talent mobility across European technology hubs. Forecasts reflect documented assumptions regarding DORA audit timeline adherence and right-to-repair mandate expansion scope. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Parking Management Systems Market
Digital Solutions
Business As a Service Market
Digital Solutions
Web Based E-Detailing Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Docketing Solution Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Global Automatic Content Recognition (ACR) Market
Digital Solutions
Community Forum Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Legal Technology Market
Digital Solutions
Customer-To-Customer (C2C) Community Market
Digital Solutions
Global Network Engineering Service Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
North America Everything As a Service (Xaas) Market