
 Global Mining Automation Consumption Market | 2026-2036
Global Mining Automation Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mining Automation Consumption Market Outlook
Autonomous haulage systems is reshaping how surface mining operations orchestrate fleet logistics and material flow. Sandvik AB leverages deep expertise in underground drilling automation to sustain technology leadership in hard-rock environments. Caterpillar Inc. anchors its competitive position through integrated command-and-control platforms that span autonomous trucks to remote dozing. Komatsu Ltd. differentiates through FrontRunner autonomous haulage systems that operate across multiple continents.
Mining automation consumption encompasses the procurement and deployment of sensor-driven, software-orchestrated equipment that executes extraction, transport, and processing functions with minimal human intervention, typically integrating LiDAR, radar, and GPS-RTK positioning achieving sub-10 centimeter accuracy. Its primary purpose is to displace manual operator exposure to hazardous conditions while optimizing cycle times and fuel efficiency in 24/7 operations. Autonomous Vehicles commands the largest installed base among technology categories, though Remote Monitoring generates disproportionate recurring revenue through software subscriptions and predictive maintenance contracts. Surface Mining dominates application-level spending due to favorable economics of fleet-scale autonomy, while Underground Mining represents the fastest expansion vector as confined-space hazards amplify the value proposition of removing personnel from active headings.
Australia's national mining regulator, WorkSafe Western Australia, enforces autonomous equipment isolation protocols that directly shape system architecture requirements for vendors seeking site access. The ISO 17757 earth-moving machinery safety standard and MSHA proximity detection mandates in the United States collectively elevate compliance costs while creating technical barriers for non-certified suppliers. Stakeholders must monitor how Canada's provincial mining codes evolve to accommodate remote-operation centers that manage multiple underground sites from centralized urban locations.
Market Dynamics
Autonomous haulage systems are collapsing the traditional operator-to-equipment ratio in surface mining, while ISO 17757 certification requirements and MSHA proximity detection mandates in the United States reshape vendor qualification barriers.
Growth Catalysts
- Worker Safety Mandates:Australia's WorkSafe Western Australia enforces autonomous equipment isolation protocols that accelerate replacement of manned vehicles in hazardous headings.
- Underground Metal Mining:Hard-rock operators in Chile and Canada deploy remote-operated drilling systems to remove personnel from confined-space exposure.
- ISO 17757 Adoption:Functional safety standardization across earth-moving machinery creates procurement preference for certified autonomous platforms.
Market Restraints
- Sensor Hardware Concentration:LiDAR and radar component supply concentrates among specialized photonics manufacturers, creating single-source vulnerability for tier-two automation vendors.
- Certification Timeline Friction:MSHA proximity detection mandates impose multi-year validation cycles that delay fleet deployment in United States underground coal operations.
- Legacy System Interoperability:Existing fleet management software architectures lack API standardization, forcing costly middleware development for brownfield automation retrofits.
Strategic Opportunities
- Canadian Remote Operations Centers:Provincial mining code evolution in Ontario and British Columbia enables centralized urban control of multiple underground sites, reducing fly-in-fly-out labor costs.
- Predictive Maintenance Subscriptions:Remote Monitoring software contracts generate recurring revenue streams that decouple vendor economics from equipment sales cycles.
- AI-Enhanced Ore Sorting:Machine vision convergence with X-ray transmission technology creates autonomous processing circuits that upgrade run-of-mine material before haulage.
Industry Challenges
- Autonomous Systems Integration:Mining engineers with combined expertise in rock mechanics and robotics command scarcity premiums that inflate project staffing costs.
- Interoperability Certification:Vendor-proprietary command protocols complicate multi-fleet site management, forcing operators to standardize on single-platform architectures.
- 24/7 Reliability Engineering:Autonomous vehicle uptime requirements exceed conventional maintenance crew scheduling, demanding predictive analytics capabilities most sites lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mining Automation Consumption Market |
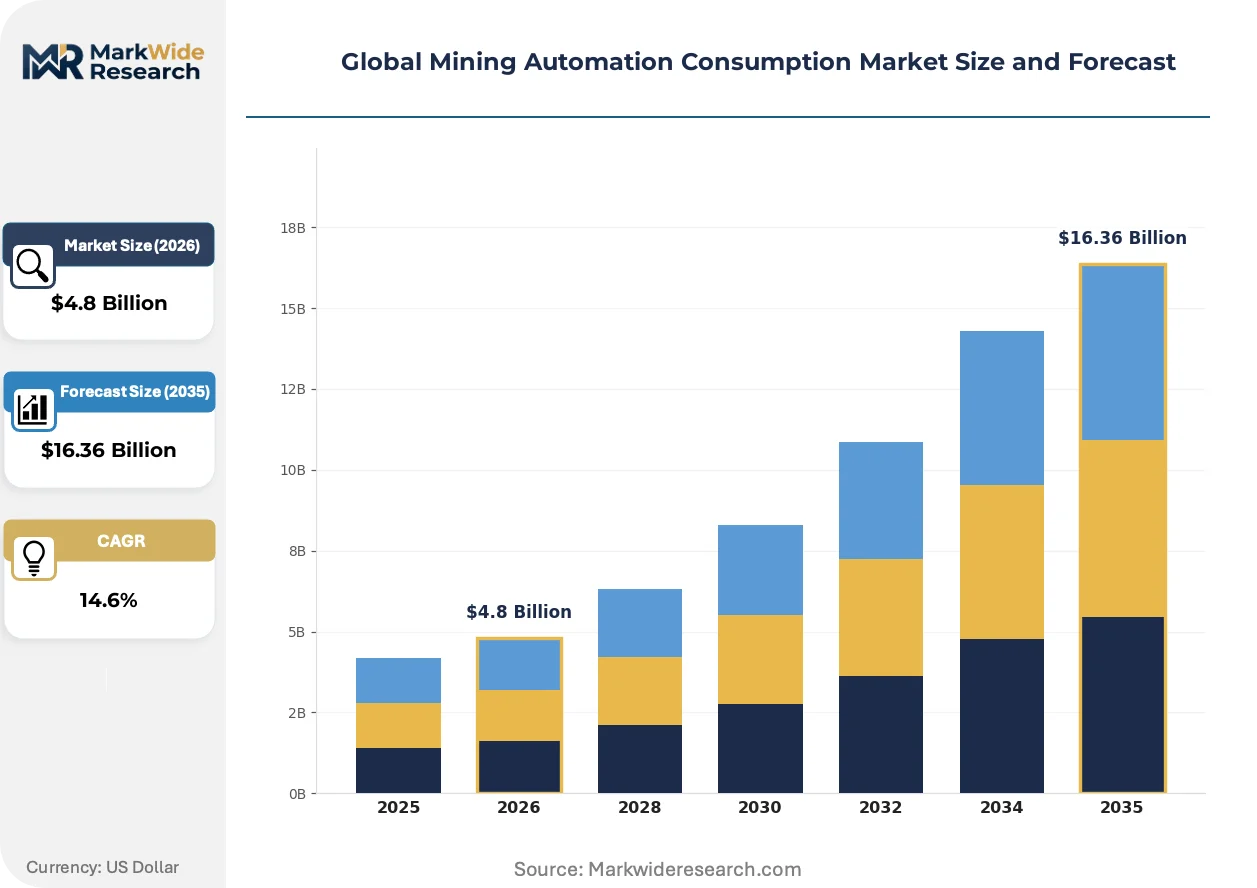
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Autonomous Vehicles, Robotics, Remote Monitoring, Drones Product Type: Drilling Equipment, Excavators, Haul Trucks, Loaders End User: Metal Mining, Coal Mining, Mineral Extraction, Quarrying Application: Surface Mining, Underground Mining, Processing, Waste Management |
| Companies Covered | Sandvik AB, ABB Ltd., Hexagon AB, Rio Tinto Group, Epiroc AB, Rockwell Automation Inc., Caterpillar Inc., Autonomous Solutions Inc., Komatsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mining Automation Consumption Market Strategic Shifts
Digital twin technology and edge computing architectures are compressing decision latency in autonomous mining operations, while regulatory frameworks in multiple jurisdictions accelerate equipment certification requirements.
Teleoperation-over-5G is collapsing the geographic distance between remote operation centers and active mine sites, enabling centralized control of dispersed fleets. Underground hard-rock operators in Canada and Australia adopt this architecture fastest, compressing the historical requirement for on-site operator shelters and reducing surface infrastructure capital intensity.
REACH substance restrictions in Europe and emerging carbon border adjustments are tightening supply chain scrutiny on battery and sensor materials used in autonomous vehicle production. Mining OEMs with European manufacturing footprints respond by qualifying alternative cell chemistries and solid-state LiDAR packages that eliminate restricted rare earth dependencies.
After-sales service unbundling is fragmenting traditional equipment procurement, with Pilbara iron ore operators now purchasing autonomous haulage capability as throughput-guaranteed service contracts rather than capital assets. This consumption model concentrates in Western Australia's mature automation installations, where Rio Tinto and peer operators negotiate availability-based payments that transfer mechanical risk to vendors.
Global Mining Automation Consumption Market Segmentation
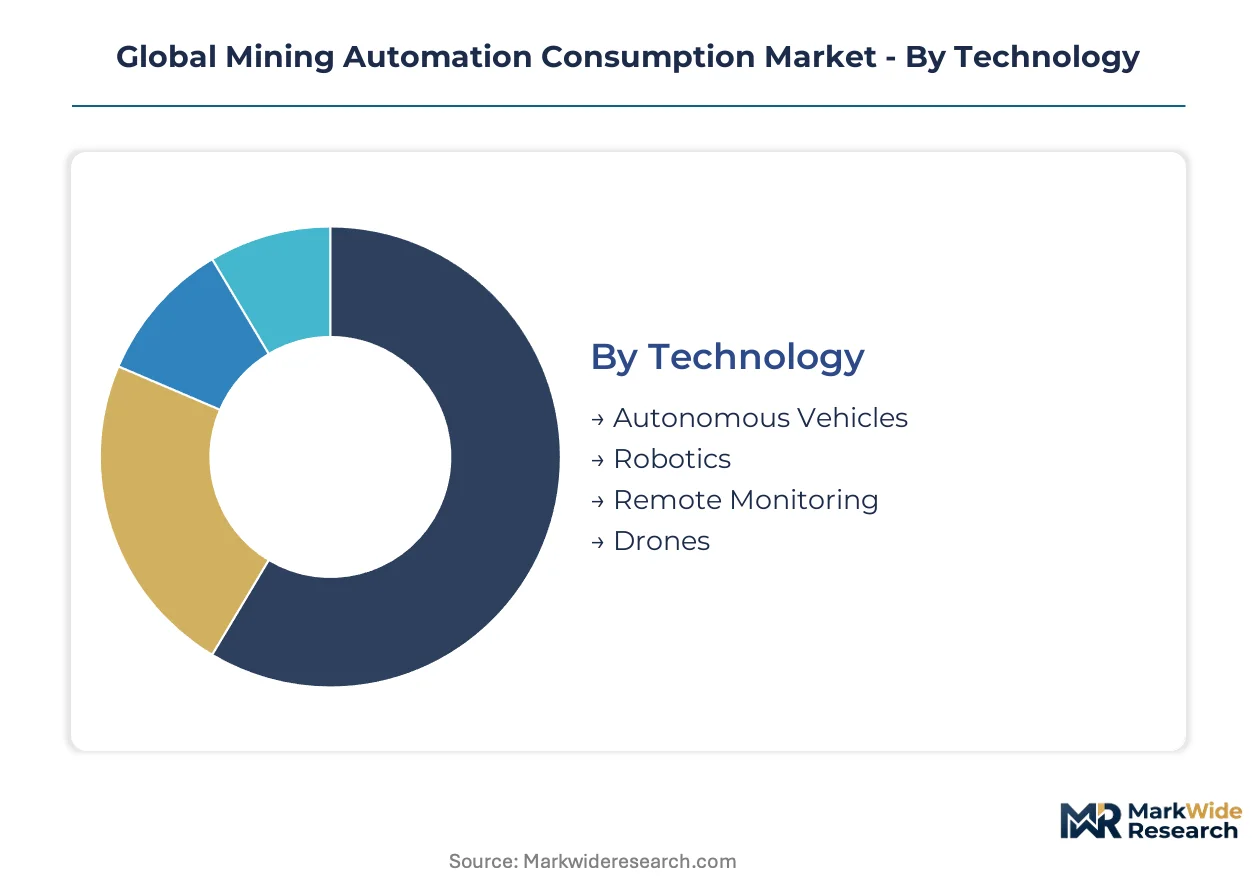
Mining automation procurement patterns diverge sharply by technology lifecycle and operational exposure. Capital-intensive segments with extended depreciation cycles concentrate in surface operations, while safety-critical categories turn over faster in underground deployments.
Technology:
Cycle times compress from multi-year fleet deployments to quarterly software renewals across this category. Autonomous Vehicles and Remote Monitoring anchor capital budgets with contrasting refresh economics.
- Autonomous Vehicles:Self-driving haul trucks and drilling rigs integrate LiDAR, radar, and GPS-RTK positioning for sub-10 centimeter navigation accuracy in 24/7 operations. Western Australia's Pilbara iron ore basin concentrates the largest installed base as Rio Tinto and peer operators pursue productivity gains through fleet-scale autonomy.
- Remote Monitoring:Cloud-orchestrated sensor networks transmit equipment health data to centralized diagnostics platforms, enabling predictive maintenance interventions before mechanical failure. This segment generates disproportionate recurring revenue through software subscriptions that decouple vendor economics from equipment sales cycles.
- Robotics:Articulated manipulators execute repetitive material handling and inspection tasks in hazardous zones.
- Drones:Aerial platforms conduct volumetric surveying and blast pattern verification across open-pit operations.
Autonomous Vehicles dominates installed base. Remote Monitoring is where expansion concentrates.
Product Type:
Unit economics stratify by payload capacity and automation complexity, with ultra-class haulers commanding premium pricing against standardized drilling platforms.
- Haul Trucks:Ultra-class autonomous trucks exceeding 400-ton payload capacity form the backbone of surface fleet automation, with integrated command-and-control platforms enabling single-operator supervision of multiple units. Australia's Pilbara operations anchor global demand as mature installations validate throughput-guaranteed service contract models.
- Drilling Equipment:Automated blasthole and exploration rigs execute precise pattern drilling without operator exposure to noise, dust, or ground instability. Underground hard-rock environments in Chile and Canada drive fastest adoption as confined-space hazards amplify the value proposition of removing personnel from active headings.
- Excavators:Hydraulic mining shovels with autonomous dig capability optimize bucket fill factors in overburden removal.
- Loaders:Underground and surface loading units with remote or autonomous tramming reduce operator fatigue in repetitive cycle operations.
Haul Trucks command the largest capital allocation. Drilling Equipment is climbing the fastest as underground safety mandates tighten.
End User:
Commodity price volatility and labor cost structures create divergent automation urgency across extraction sectors.
- Metal Mining:Copper, gold, and iron ore operators deploy autonomous fleets at scale to offset declining ore grades with productivity gains. Western Australia's iron ore basin and Chile's copper belt concentrate visible demand as majors pursue 24/7 operational continuity.
- Coal Mining:Surface thermal coal operations in Australia and North America adopt haul truck autonomy fastest, while underground coal faces extended certification timelines from MSHA proximity detection mandates.
- Mineral Extraction:Lithium, rare earth, and industrial mineral producers automate to secure supply chain positioning for battery and electronics feedstocks.
- Quarrying:Aggregate and dimension stone operations deploy entry-level automation for loader and hauler fleets in fragmented ownership structures.
Metal Mining anchors technology development investment. Coal Mining is gaining share fastest as labor availability constraints intensify.
Application:
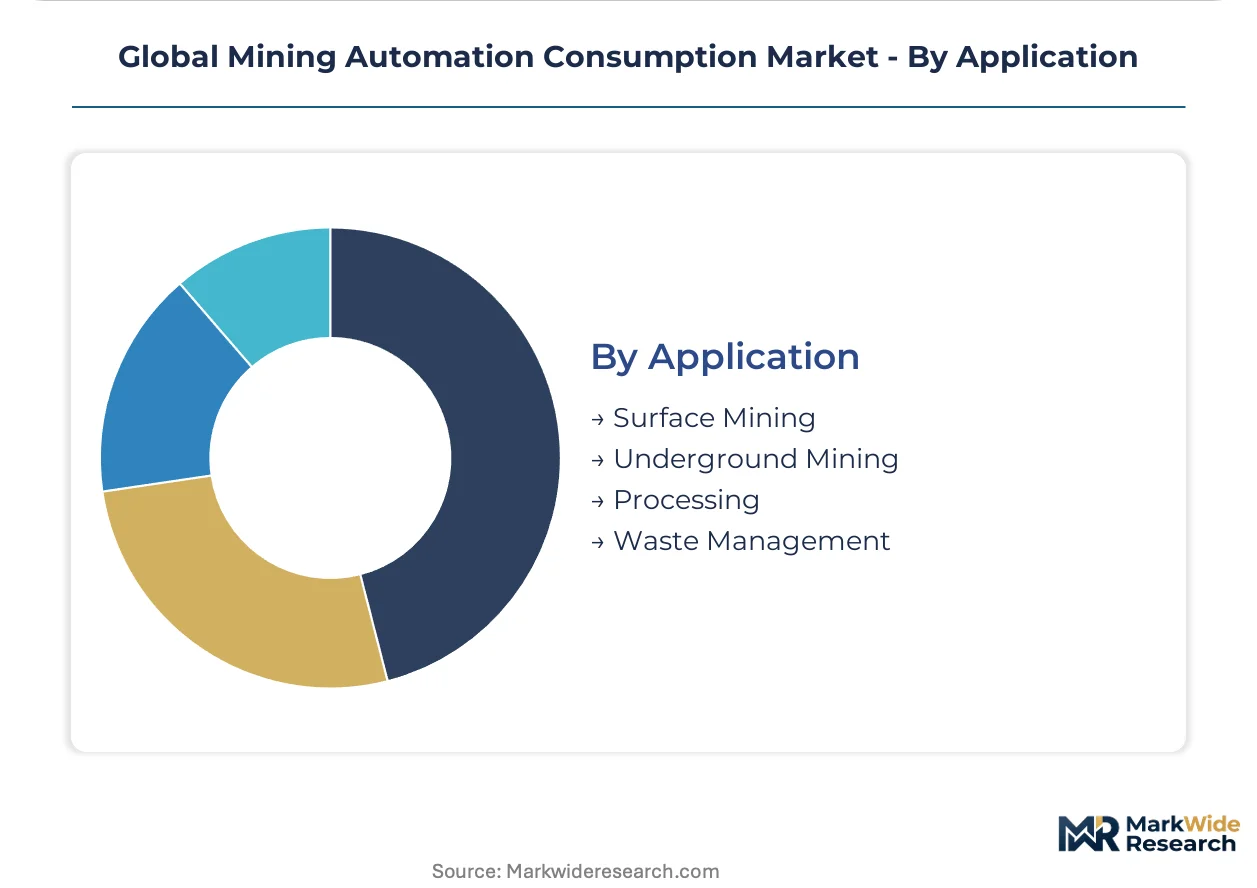
Surface infrastructure density enables faster autonomous deployment than confined underground environments with limited communications backhaul.
- Surface Mining:Open-pit operations leverage favorable economics of fleet-scale autonomy with established GPS coverage and wide haul road corridors. Australia's mature automation installations demonstrate availability-based contracting that transfers mechanical risk to equipment vendors.
- Underground Mining:Confined headings and ventilation constraints demand specialized positioning systems and teleoperation-over-5G architectures. Canada's Ontario and British Columbia mining codes now accommodate centralized urban control centers that manage multiple sites remotely.
- Processing:Crushing, grinding, and flotation circuits integrate machine vision and sensor fusion for autonomous ore sorting and grade control.
- Waste Management:Tailings dam monitoring and waste dump operations deploy drone and robotic inspection to reduce personnel exposure to geotechnical hazards.
Surface Mining holds the dominant revenue position. Underground Mining represents the steepest expansion trajectory as teleoperation architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia exports autonomous haulage expertise to Chile's copper belt and Canada's hard-rock districts, establishing a knowledge corridor that shapes procurement standards across three continents.
Australia
Western Australia's Pilbara iron ore basin hosts the world's largest autonomous truck fleet as Rio Tinto and BHP deploy fully driverless haulage at scale. WorkSafe Western Australia enforces strict autonomous equipment isolation protocols that vendors must satisfy for site access. Perth serves as the engineering hub where remote operations centers manage dispersed mine sites with 5G backhaul.
Chile
Copper operators in the Atacama Desert deploy remote drilling systems to extract ore from geotechnically unstable headings without personnel exposure. The National Geology and Mining Service regulates autonomous equipment certification alongside environmental impact assessments. The Antofagasta mining cluster concentrates demand for teleoperation-over-5G architectures that link urban control centers to remote pit operations.
Canada
Ontario and British Columbia hard-rock mines adopt centralized urban control centers that manage multiple underground sites simultaneously, eliminating fly-in-fly-out labor costs. Provincial mining codes now accommodate remote-operation architectures that were previously prohibited by ventilation and communications mandates. Sudbury and Vancouver anchor the technical workforce that programs autonomous drilling and loading sequences.
United States
Surface coal and copper operations in Arizona and Wyoming pursue haul truck autonomy to offset tightening labor availability in rural extraction zones. MSHA proximity detection mandates impose multi-year validation cycles that delay underground coal deployments relative to surface applications. The Powder River Basin demonstrates fleet-scale retrofit economics that transfer mechanical risk to equipment vendors through availability contracts.
China
Domestic iron ore and coal producers accelerate autonomous shovel and truck deployments to maintain production continuity amid workforce aging in remote northern provinces. MIIT standards for autonomous mining equipment create procurement preference for certified domestic platforms. The Shanxi coal basin and Anshan iron ore district concentrate pilot programs that integrate 5G private networks with fleet management systems.
Global Mining Automation Consumption Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that concentrates in integrated command-and-control platforms while fragmenting in sensor hardware and niche robotics. Tier-one automation vendors anchor procurement decisions through multi-decade service relationships and captive financing arms. Three archetypes dominate: diversified industrial conglomerates with mining divisions, pure-play automation technology vendors, and mining operators that internalize technology development. Competitive moves center on strategic partnerships for 5G infrastructure integration and backward integration into LiDAR and radar component supply.
Among diversified industrial players, Caterpillar Inc., Komatsu Ltd., and Sandvik AB exemplify the integrated-platform archetype that spans autonomous trucks to remote underground drilling. Caterpillar anchors North American surface mining procurement through command-and-control architectures that standardize fleet interoperability. Komatsu occupies a parallel position across Australian and Chilean iron ore basins with autonomous haulage systems that operate at continental scale. Sandvik represents the underground-specialist counterweight, with hard-rock automation expertise concentrated in European and Canadian metal mining districts. These three entities structure competitive dynamics by defining the interface standards that constrain second-tier vendors to middleware or component supply roles.
| Leading Market Players |
|---|
| Sandvik AB |
| ABB Ltd. |
| Hexagon AB |
| Rio Tinto Group |
| Epiroc AB |
| Rockwell Automation Inc. |
| Caterpillar Inc. |
| Autonomous Solutions Inc. |
| Komatsu Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in LiDAR sensor fabrication across China and South Korea is compressing component costs while concentrating bargaining power among tier-one automation vendors who can absorb volume commitments. This utilization dynamic forces tier-two suppliers into unfavorable payment terms and accelerates consolidation around integrated platform providers who bundle hardware with software subscriptions.
Pricing Analysis
Cost-plus contracts with steel and rare earth indexation dominate autonomous vehicle procurement in Australia's Pilbara operations. Three-tier pricing structure across premium-certified, standard-compliant, and economy retrofit levels separates Rio Tinto-scale deployments from mid-tier coal operators. Pricing pressure stems from REACH substance restrictions forcing qualification of alternative cell chemistries. Junior miners exhibit highest price sensitivity, while iron ore majors prioritize availability guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for automation vendors with North American manufacturing footprints. Component supply concentrates in China, Germany, and Japan for LiDAR modules, radar systems, and precision hydraulics. Raw material dependencies span neodymium magnets, lithium-ion cells, and high-grade steel alloys. Distribution runs through OEM captive financing arms and regional equipment dealers with service integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Teleoperation-over-5G architectures are collapsing geographic constraints on labor deployment, creating a regulatory-inflected disruption window as Canadian and Australian mining codes accommodate centralized urban control centers.
For Market Incumbents: Build switching-cost moats through captive financing arms that bundle autonomous haulage hardware with predictive maintenance subscriptions. Deepen backward integration into solid-state LiDAR supply to eliminate rare earth dependencies threatened by REACH restrictions. Anchor fleet interoperability standards that force second-tier vendors into middleware roles. For New Entrants and Emerging Players: Establish a beachhead in underground drilling automation where Sandvik and Epiroc concentration leaves midsize hard-rock operators underserved. Target Chilean copper belt expansions where National Geology and Mining Service certification requirements favor nimble compliance specialists over legacy platform complexity. Lead with 5G-native teleoperation architectures that eliminate surface infrastructure capital intensity. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play automation software vendors with recurring revenue models that decouple from equipment sales cyclicality. Long-term viability hinges on predictive maintenance platform penetration rates across brownfield mining installations. Watch for provincial mining code amendments enabling multi-site remote operation centers as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Infrastructure Partnership | Teleoperation-over-5G collapses latency between urban control centers and remote pit operations in Western Australia. |
| Backward Integration into LiDAR | Captive solid-state sensor production eliminates rare earth dependencies threatened by European REACH substance restrictions. |
| Availability-Based Service Contract | Throughput-guaranteed agreements transfer mechanical risk from Pilbara iron ore operators to equipment vendors. |
| Remote Operations Center Buildout | Centralized urban control of multiple underground sites reduces fly-in-fly-out labor costs across Ontario and British Columbia. |
| ISO 17757 Certification Investment | Functional safety standardization creates procurement preference barriers against uncertified autonomous platform competitors. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with mining automation stakeholders and secondary validation across regulatory and trade databases. Interview programs captured perspectives from mine operations directors, OEM procurement leads, remote operations center engineers, and aftermarket service heads. Secondary sources included MSHA enforcement data, ISO certification registries, WorkSafe Western Australia incident reports, and customs records for autonomous vehicle component trade. Bottom-up equipment deployment tallies were triangulated against top-down commodity production forecasts.
Forecast inputs spanned technology adoption curves across autonomous vehicles, remote monitoring, and robotics segments, with additional modeling for surface versus underground application penetration. End-user segmentation incorporated metal mining, coal mining, and mineral extraction verticals alongside haul truck, drilling equipment, and loader product categories. CAGRs were derived from logistic diffusion curves fitted to historical automation deployment patterns, cross-referenced against labor cost inflation and safety regulation enforcement intensity.
Stress conditions across copper price volatility, 5G infrastructure rollout delays, and MSHA certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization and component cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Europe Retail Automation Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Switzerland Industrial Automation Market