
 Global Motion Controller Market | 2026-2036
Global Motion Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Global Motion Controller Market Intelligence
The integration of motion control software directly into embedded systems is reconfiguring product architectures for industrial automation, enabling more compact and decentralized control. Siemens leverages its extensive portfolio in digital twins to simulate performance for complex systems. Rockwell Automation competes through its integrated architecture platforms, while FANUC Corporation sustains a dominant position in the CNC machine tool segment with highly specialized controllers.
A motion controller is a device that generates control signals for motors to execute precise movements, processing setpoints and feedback using algorithms like PID loops. Its primary purpose is to manage the velocity, position, and torque of automated mechanical actions. Among product types, digital motion controllers hold the largest market share due to their flexibility. Within technology, Ethernet-based control systems represent the fastest-growing segment, meeting the need for high data throughput in applications like semiconductor fabrication.
Compliance with safety directives, including Europe's CE marking and specific machinery regulations in Germany, dictates market access. In parallel, adherence to global functional safety standards like ISO 13849 shapes product design and validation protocols required by industrial automation firms. The critical decision for equipment manufacturers is how to balance open architecture systems against proprietary, high-performance solutions for specific end-uses.
Market Dynamics
The central force shaping the motion controller market is the escalating precision requirement from advanced manufacturing sectors. This demand, particularly from semiconductor and electronics fabrication, necessitates higher data throughput and real-time processing, favoring networked control architectures.
Growth Catalysts
- Robotics in Electronics:High-speed assembly demand in South Korea's electronics hubs requires multi-axis controllers for component placement and wafer handling.
- Ethernet-Based Control:The shift to industrial Ethernet enables deterministic communication for synchronized motion in machinery like semiconductor fabrication tools.
- Functional Safety Standards:Adherence to ISO 13849 compels adoption of controllers with integrated safety, creating a premium for certified industrial automation systems.
Market Restraints
- High Integration Cost:The expense of integrating advanced motion control systems with legacy factory equipment is a significant barrier for smaller enterprises.
- Proprietary Architectures:Vendor lock-in from proprietary software and communication protocols limits interoperability and increases total cost of ownership.
- Component Supply Concentration:The supply of critical components like high-resolution optical encoders is concentrated in Japan and Germany, creating supply chain risk.
Strategic Opportunities
- AI and Machine Learning:Integrating AI algorithms for predictive maintenance and self-tuning of PID loops offers a new frontier for performance optimization.
- Logistics Automation:E-commerce warehouse expansion creates demand for decentralized controllers in autonomous mobile robots and high-speed sortation systems.
- Medical Device Robotics:An emerging need exists for high-precision, safety-certified controllers in surgical robots and laboratory automation, a high-value segment.
Industry Challenges
- Skills Gap:A shortage of engineers with expertise in mechatronics, control theory, and network programming hinders the implementation of complex, multi-axis automation projects.
- Integration Complexity:Ensuring seamless interoperability between motion controllers, drives, and motors from different vendors remains a persistent operational hurdle for system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Motion Controller Market |
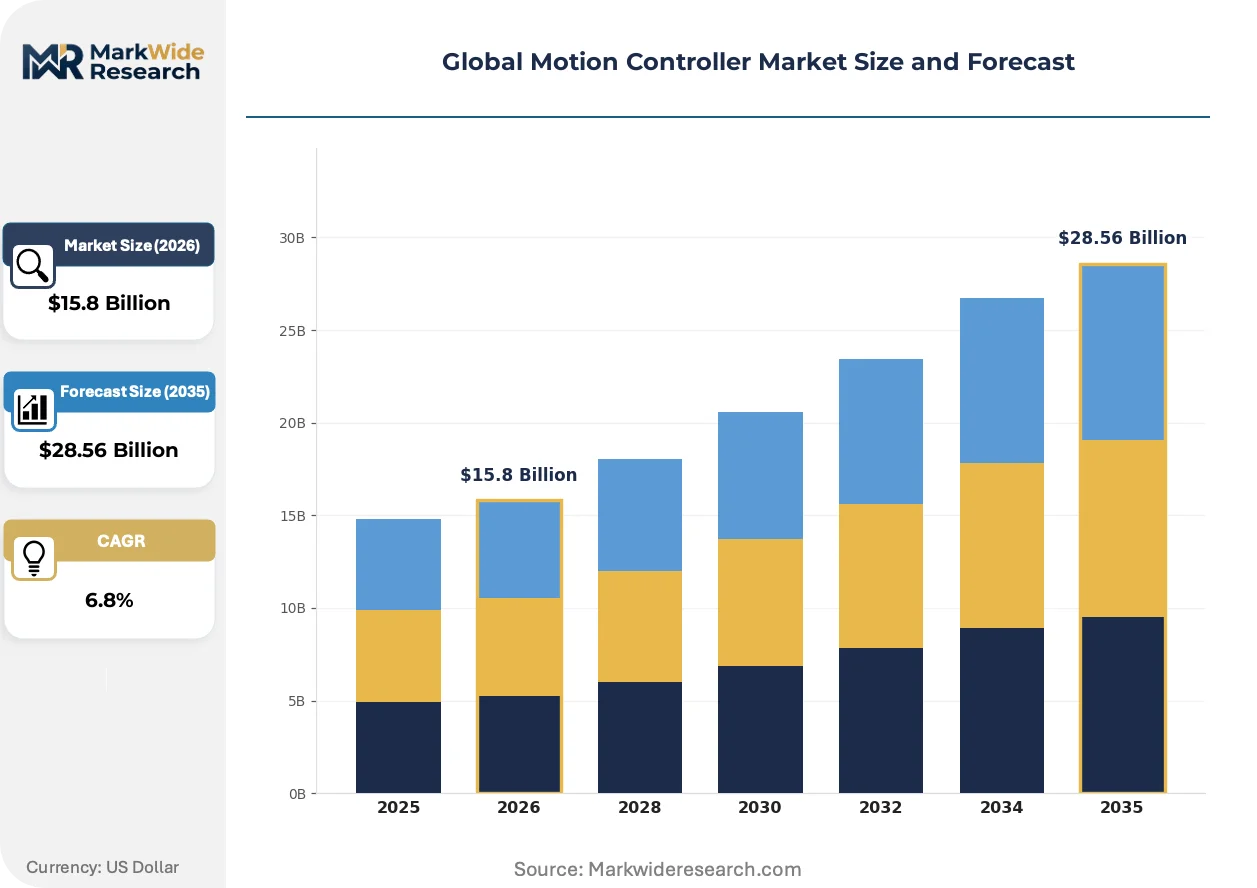
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $28.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Motion Controllers, Digital Motion Controllers, Programmable Logic Controllers, Embedded Motion Controllers Technology: Stepper Motor Control, Servo Motor Control, Fieldbus Systems, Ethernet-based Control, Motion Control Software Application: Robotics Automation, Semiconductor Fabrication, Packaging Machinery, CNC Machines, Printing Equipment End User: Manufacturing Plants, Research Laboratories, Aerospace Manufacturers, Industrial Automation Firms |
| Companies Covered | ABB, FANUC Corporation, Siemens, Mitsubishi Electric Corporation, Rockwell Automation, Yaskawa Electric Corporation, Schneider Electric, Omron Corporation, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Motion Controller Market Strategic Shifts & Innovations
Software-defined functionality is reconfiguring the physical architecture of industrial automation. The decoupling of control logic from dedicated hardware enables more flexible and decentralized system designs, shifting value from the controller box to the underlying software ecosystem and network.
Embedded motion control integrates the controller's logic directly onto the motor drive or into a PLC. Machine builders in the packaging and material handling industries are adopting this approach to reduce cabinet size and wiring complexity. This trend is collapsing the traditional, separate hardware tiers of controller, drive, and motor into a single, networked mechatronic unit.
The European Union's updated Machinery Regulation introduces stringent cybersecurity requirements for safety-related control systems. This compels manufacturers to validate software integrity and network security as part of the machine's overall CE marking compliance. The CNC machine tool segment is most affected, now requiring threat modeling to meet market access rules.
Equipment manufacturers are increasingly selecting vendors based on the quality of their software development kits and simulation tools. This procurement pattern moves the decision away from pure hardware specifications toward the ease of custom application development and virtual commissioning. This shift is most visible in Germany's special-purpose machine building sector, where digital twin integration is key.
Global Motion Controller Market Segmentation
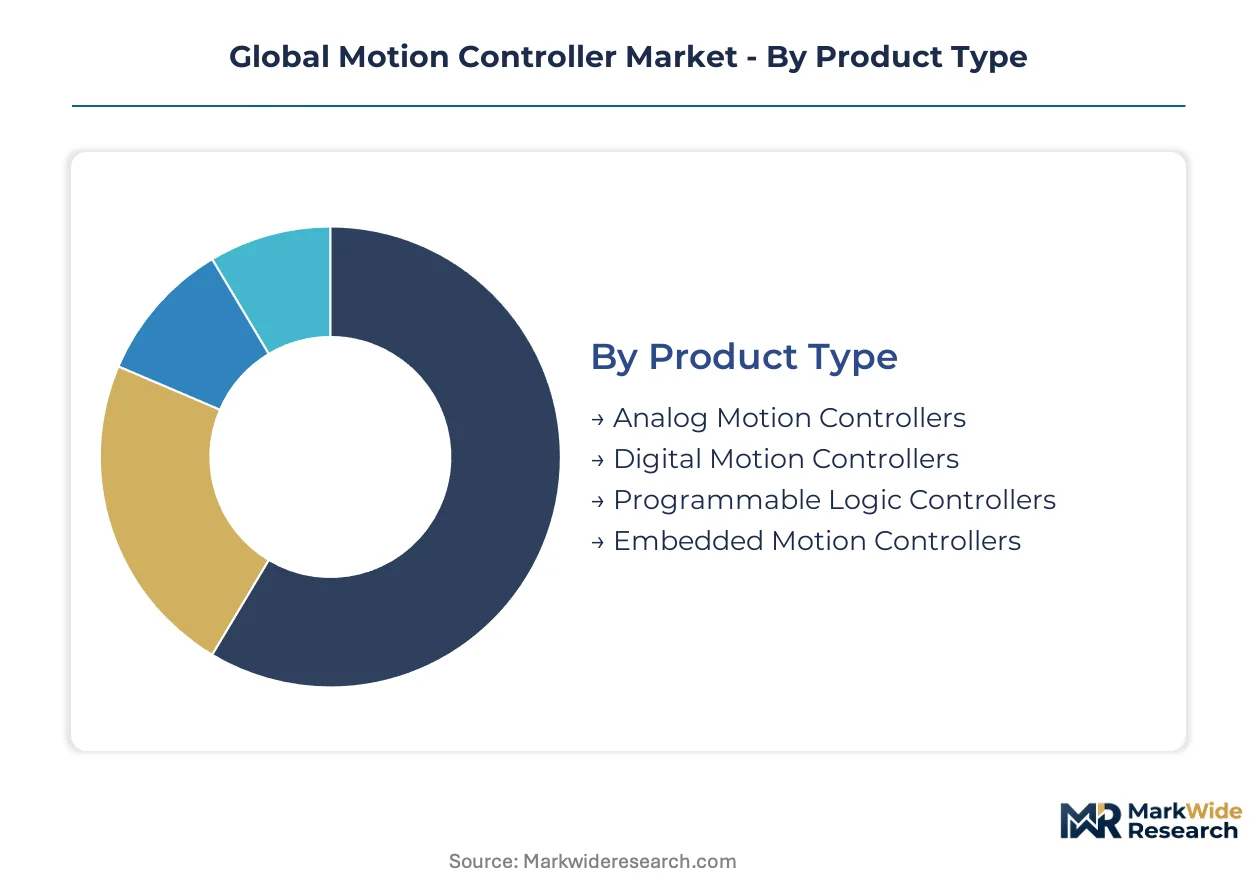
Segmentation provides a granular view of the Global Motion Controller Market, highlighting distinct product capabilities and application specificities. Understanding these segments helps manufacturers tailor offerings to precise industrial demands. This analysis identifies where innovation is concentrated and where established technologies maintain their market presence.
Product Type:
The product type segment illustrates the maturity spectrum of motion control solutions, ranging from foundational analog systems to highly integrated embedded units.
- Analog Motion Controllers:These systems utilize continuous electrical signals for motor control, providing a cost-effective solution for less demanding applications.
- Digital Motion Controllers:These devices process control signals using digital data, offering high precision and flexibility through software algorithms. Demand concentrates in semiconductor fabrication in South Korea, driven by the need for exact component placement.
- Programmable Logic Controllers:PLCs integrate motion control functions alongside broader automation logic, serving diverse manufacturing plant operations.
- Embedded Motion Controllers:These controllers integrate logic directly onto motor drives or within PLCs, reducing physical footprint and wiring complexity. Packaging and material handling industries in Germany adopt this approach for decentralized control.
Digital Motion Controllers retain volume leadership; Embedded Motion Controllers hold the steepest expansion curve.
Technology:
The technology segment differentiates solutions based on communication protocols and motor drive methods, influencing system performance across diverse applications.
- Stepper Motor Control:This technology provides open-loop control for precise positioning through incremental steps, suitable for cost-sensitive applications.
- Servo Motor Control:These systems offer closed-loop feedback for highly dynamic and accurate position, velocity, and torque control in robotics.
- Fieldbus Systems:These digital communication networks connect industrial devices, providing robust data exchange in factory automation environments.
- Ethernet-based Control:This technology uses industrial Ethernet protocols for deterministic communication, enabling high data throughput and synchronized motion. Semiconductor fabrication tools require this for real-time processing and precision.
- Motion Control Software:This software defines control logic, decoupling it from dedicated hardware for flexible and decentralized system designs. German special-purpose machine builders value simulation tools and application development ease.
Cost and performance trade-offs define adoption patterns across these technologies.
Application:
The application segment highlights the primary industrial sectors driving demand for motion control systems, reflecting specific operational requirements.
- Robotics Automation:This application integrates motion controllers into robotic systems for tasks like assembly, material handling, and logistics. E-commerce warehouse expansion creates demand for decentralized controllers in autonomous mobile robots.
- Semiconductor Fabrication:This sector demands ultra-high precision motion for wafer handling, lithography, and inspection processes. High-speed assembly in South Korea's electronics hubs relies on multi-axis controllers.
- Packaging Machinery:This application uses motion controllers for high-speed, synchronized movements in processes like filling, sealing, and labeling.
- CNC Machines:These machine tools rely on specialized motion controllers for precise multi-axis cutting and shaping operations, particularly in manufacturing.
- Printing Equipment:This application utilizes motion control for accurate paper feeding, registration, and print head positioning in industrial printing presses.
Precision and throughput requirements dictate the specific motion control solutions deployed across these diverse applications.
End User:
The end-user segment delineates the diverse organizational types that procure motion control technology, each with unique operational priorities.
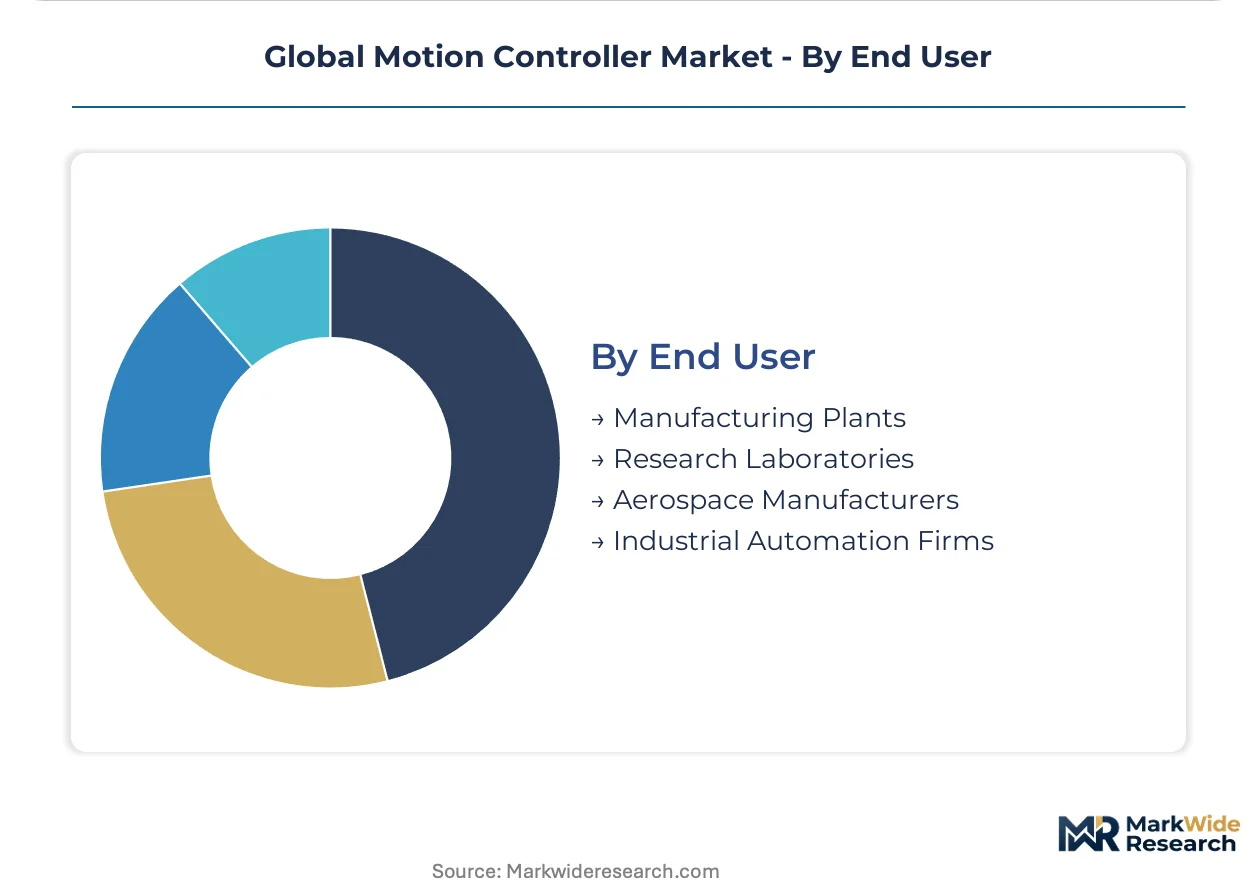
- Manufacturing Plants:These facilities utilize motion controllers across various production lines for assembly, processing, and quality control. German automotive sector demand drives adoption of advanced control systems.
- Research Laboratories:These institutions employ motion controllers for experimental setups requiring precise movement and data acquisition in scientific studies.
- Aerospace Manufacturers:This sector demands highly reliable and accurate motion control for specialized manufacturing processes and testing of aircraft components.
- Industrial Automation Firms:These companies integrate motion control systems into broader automation solutions for clients, requiring interoperability and robust validation protocols. Compliance with functional safety standards like ISO 13849 is critical.
Operational scale and precision needs significantly influence the motion control system choices for these end-user groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation firms and equipment manufacturers represent the primary buyer archetypes across key geographies. These entities prioritize motion control systems that offer precision, reliability, and compliance with local safety standards. Demand is particularly strong in regions with advanced manufacturing capabilities and robust industrial infrastructure.
Germany
Germany's automotive sector drives significant demand for advanced control systems, particularly for precision manufacturing. Compliance with Europe's CE marking and specific machinery regulations in Germany dictates market access for new products. Bavaria's industrial clusters, including those around Stuttgart and Munich, integrate digital twin technology for virtual commissioning in special-purpose machine building.
South Korea
South Korea's electronics manufacturing hubs, especially in semiconductor fabrication, demand ultra-high precision motion control for wafer handling and component placement. Adherence to global functional safety standards like ISO 13849 shapes product design for these critical applications. Gyeonggi Province, a major electronics cluster, relies on multi-axis controllers for high-speed assembly lines.
United States
The United States market sees robust demand from robotics automation, particularly in logistics automation for expanding e-commerce warehouses. OSHA regulations influence the design of integrated safety features in industrial motion control systems. Silicon Valley's technology firms and the Midwest's manufacturing belt drive innovation in decentralized controllers for autonomous mobile robots.
Japan
Japan's precision manufacturing sector, including the CNC machine tool segment, requires highly specialized motion controllers for intricate operations. METI guidelines encourage technological advancements and quality control in industrial machinery. Aichi Prefecture, a manufacturing powerhouse, concentrates demand for high-performance controllers in automotive and robotics applications.
Global Motion Controller Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure. The market sees consolidation among large integrated automation providers, while numerous smaller firms specialize in niche applications or component supply. Strategic archetypes include full-suite industrial automation giants, dedicated motion controller manufacturers, and software-focused solution providers. Dominant competitive moves involve portfolio diversification into adjacent technologies and strategic partnerships for system integration.
Within the integrated automation ecosystem, Siemens, a German multinational conglomerate, exemplifies a broad portfolio approach, leveraging its extensive digital twin capabilities. The US-based Rockwell Automation occupies a similar position, anchoring its competitive positioning through integrated architecture platforms. Conversely, FANUC Corporation, a Japanese company, represents a specialized archetype, sustaining a dominant position in the CNC machine tool segment with highly specialized controllers.
| Leading Market Players |
|---|
| ABB |
| FANUC Corporation |
| Siemens |
| Mitsubishi Electric Corporation |
| Rockwell Automation |
| Yaskawa Electric Corporation |
| Schneider Electric |
| Omron Corporation |
| Delta Electronics |
| Others |
Cost & Logistics Intelligence
The cost dynamics of specialized components transported through global freight corridors directly influence supply concentration and downstream price differentiation within the motion controller market. This interaction shapes how manufacturers procure and price their advanced automation solutions.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material and component costs, dominate pricing for custom motion control systems. Price differentiation stems from the level of software customization for specific applications and adherence to functional safety certifications like ISO 13849. Pricing pressure arises from the high integration costs faced by smaller enterprises, compelling vendors to offer more standardized solutions. End-users in semiconductor fabrication exhibit lower price sensitivity due to precision requirements, while packaging machinery manufacturers are more cost-conscious.
Supply Chain Analysis
Supplier-financing arrangements, including extended payment terms and supply-chain finance facilities, are critical for managing inventory and cash flow in the motion controller supply chain. Geographic supply concentration for high-resolution optical encoders and specialized microcontrollers centers on Japan and Germany. Key dependencies include power semiconductors and advanced integrated circuits. A structural risk is the single-source vulnerability for these critical components. Distribution runs through a dual model, with direct sales to large industrial automation firms and specialized distributors serving smaller equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Motion Controller Market presents a fragmentation opportunity, driven by the specialized demands of logistics automation creating distinct niches for decentralized control solutions.
For Market Incumbents:
Harden core intellectual property around digital twin integration to simulate complex system performance for German automotive clients. Expand integrated architecture platforms to counter interoperability challenges for system integrators. Invest in R&D for AI algorithms that enable predictive maintenance and self-tuning of PID loops. This defends against emerging software-focused solution providers and addresses the industry's skills gap for advanced mechatronics.
For New Entrants and Emerging Players:
Decentralized controllers for autonomous mobile robots in e-commerce warehouses represent a highly penetrable entry point. Target logistics automation in expanding distribution centers by offering open architecture systems with robust software development kits. Focus on providing flexible, embedded motion control solutions that reduce cabinet size and wiring complexity for material handling applications. This strategy leverages the shift towards software-defined functionality and addresses integration complexity.
For Investors and Strategic Acquirers:
Carve-out targets emerge from large industrial conglomerates seeking to divest non-core motion control software divisions. Long-term viability rests on sustained demand for precision automation across high-growth sectors like medical device robotics. Acquisition targets should include specialized component manufacturers for high-resolution encoders or firms with advanced AI/ML capabilities for motion optimization. The adoption rates of Ethernet-based control systems in new industrial builds serve as a critical inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating motion control software with broader automation platforms enhances system interoperability for industrial automation firms. |
| Acquisition of Specialist Firm | Acquiring specialized component manufacturers secures critical supply for high-resolution optical encoders. |
| Strategic Partnership | Partnering with AI/ML developers optimizes predictive maintenance and self-tuning capabilities for advanced controllers. |
| Product Launch | Launching safety-certified controllers for medical device robotics addresses a high-value, precision-driven segment. |
| Geographic Expansion | Expanding into South Korea's electronics hubs captures demand for multi-axis controllers in high-speed assembly. |
Research Approach
Operator-level perspectives from plant managers, automation engineers, procurement leads, and R&D directors anchored the qualitative base of this analysis. This primary research was rigorously validated against secondary data sources, including industry association reports, patent databases, company financial filings, and government industrial statistics. The study employed both bottom-up and top-down triangulation to ensure comprehensive data coverage and accuracy.
Scenario-bracketing framed the analytical framework across the analysis window, modeling market dynamics under various conditions. The study segmented the market by product type, technology, application, end-user, and regional manufacturing clusters. Compound Annual Growth Rates were derived from historical trends, expert consensus, and projected technological shifts in robotics automation adoption rates and semiconductor fabrication expansion plans.
Stress conditions across supply chain disruptions for critical components and rapid shifts in industrial safety regulations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
India Industrial Automation Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
Linear Motion System Market
Industrial Automation
SCADA Alarm Management Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
Latin America Laboratory Automation Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Modular Automation and Services Market