
 Global Intelligent Completion Market | 2026-2036
Global Intelligent Completion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intelligent Completion Market Foresight
Carbon steel is decoupling from premium alloy mandrels in lower-pressure intelligent completion assemblies, reshaping product economics across the supply chain. Schlumberger Ltd. leverages its integrated subsurface-to-surface portfolio to anchor deepwater contracts in West Africa and the Gulf of Mexico. Halliburton Co. differentiates through real-time diagnostics software bundled with its electro-hydraulic intelligent well systems. Baker Hughes Co. competes on manufacturing scale, sustaining one of the broadest catalogs of multi-zone completion tools globally.
Intelligent completion denotes a well architecture integrating remotely actuated downhole valves, inflow control devices, and permanent monitoring sensors to optimize production from multiple zones without mechanical intervention. These systems typically operate at pressures exceeding 10,000 psi and temperatures above 150°C, enabling real-time reservoir management through surface-controlled downhole adjustments. Multi-zone completions occupy the dominant share of deployed systems, as operators prioritize capital efficiency across stacked pay intervals. Autonomous systems represent the fastest-growing technology segment, displacing electro-hydraulic architectures where subsea infrastructure complexity drives demand for self-powered, decision-capable downhole tools.
API RP 19G2 wellhead equipment standards, NORSOK D-010 drilling and well operations requirements, and Brazil's ANP regulatory framework collectively shape product certification demands and market access thresholds for intelligent completion suppliers. The US BSEE well control rules and Norway's PSA facility regulations further mandate redundant barrier systems that directly expand addressable demand for zonal isolation technologies. Stakeholders must monitor the pace at which autonomous downhole algorithms gain regulatory acceptance as primary control mechanisms, as this shift will redefine competitive positioning between electromechanical incumbents and software-centric entrants.
Market Dynamics
Autonomous downhole algorithms are displacing electro-hydraulic architectures as the primary control paradigm, compressing intervention cycles and rewiring supplier value capture from hardware toward embedded software and predictive analytics.
Growth Catalysts
- Pre-salt carbonate developments:Brazil's ANP regulatory framework mandates advanced zonal isolation for high-pressure formations, pulling multi-zone intelligent completion systems into deepwater contracts.
- Fiber-optic sensing maturation:Permanent distributed temperature and pressure monitoring reduces well intervention frequency by half, cutting operational expenditure for Gulf of Mexico operators.
- NORSOK D-010 barrier redundancy:Norway's PSA facility regulations require redundant zonal isolation, directly expanding addressable demand for intelligent completion hardware across North Sea assets.
Market Restraints
- Nickel alloy cost volatility:Premium Inconel and Hastelloy mandrel prices swing with mining output, squeezing margins on high-temperature completion assemblies rated above 150°C.
- Subsea infrastructure lock-in:Existing electro-hydraulic control umbilical networks in mature West African fields create switching friction against autonomous system retrofits.
- Regulatory algorithm acceptance lag:Brazil's ANP and the US BSEE have yet to certify autonomous downhole decision loops as primary control mechanisms, delaying full deployment.
Strategic Opportunities
- Middle East carbonate underpenetration:Saudi Arabia's offshore and onshore sour gas reservoirs remain sparsely equipped with intelligent completion, presenting greenfield deployment potential for multi-zone systems.
- Wireless telemetry convergence:Integration of acoustic and electromagnetic signal transmission eliminates hydraulic control lines, enabling completions in slim-hole and extended-reach laterals previously inaccessible to conventional architectures.
- EU Green Deal methane intensity targets:The bloc's CSRD disclosure requirements pressure operators to install real-time inflow control for fugitive emissions reduction, creating regulatory-pull demand for monitoring-intensive completions.
Industry Challenges
- Downhole data science talent scarcity:Reservoir engineers with hybrid expertise in petroleum systems and machine learning model deployment command premium compensation, constraining autonomous system rollout velocity.
- Multi-vendor integration complexity:Bundling electro-hydraulic valves from one supplier with fiber-optic sensors from another creates interoperability failures during commissioning, extending project timelines.
- API RP 19G2 certification bottlenecks:Wellhead equipment qualification timelines stretch eighteen to twenty-four months for new intelligent completion designs, delaying revenue recognition for product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent Completion Market |
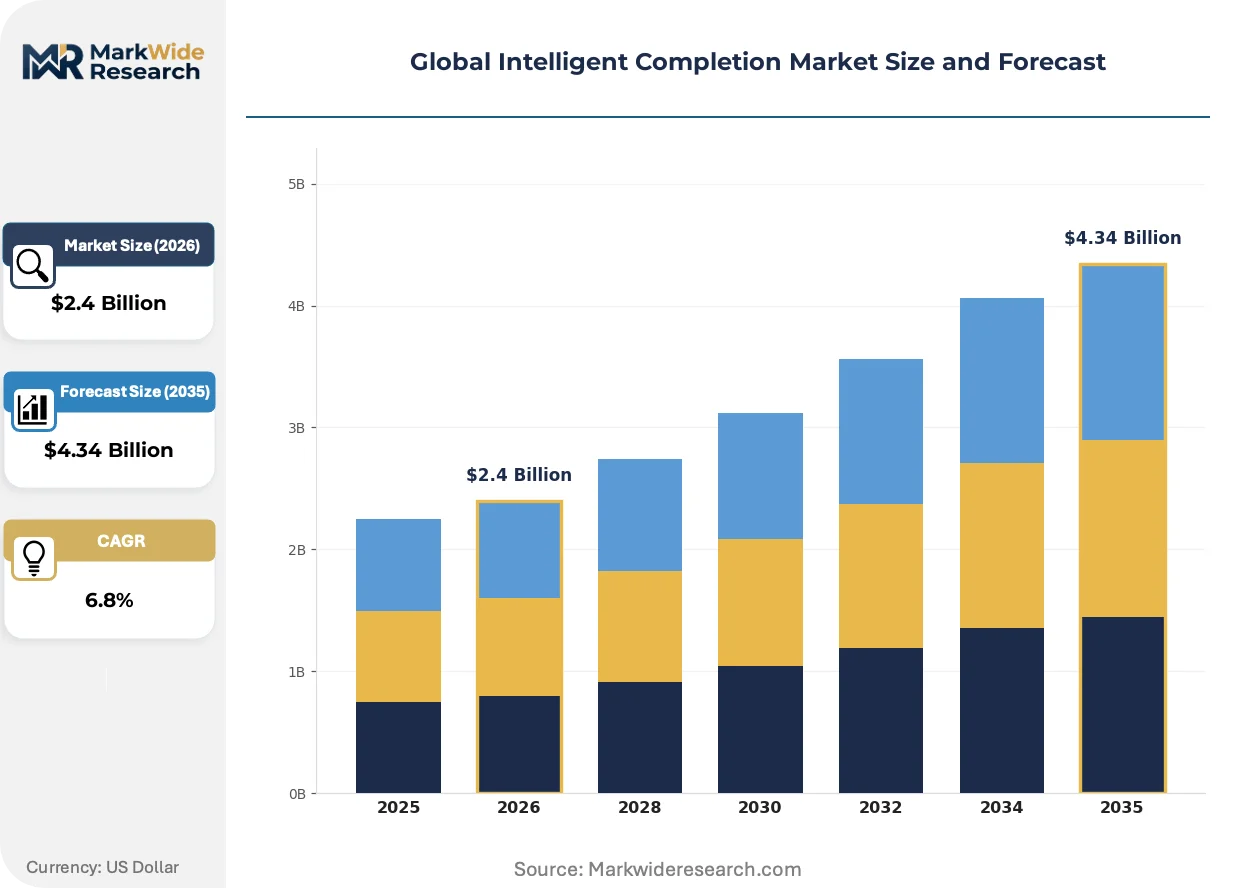
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual Sleeve, Intelligent Sleeve, Multi-Zone, Single Zone Technology: Electromechanical, Hydraulic, Electro-Hydraulic, Autonomous Systems Application: Conventional Wells, Unconventional Wells, Deepwater Extraction, Enhanced Recovery End User: Exploration Companies, Drilling Contractors, Oilfield Services, Reservoir Engineers |
| Companies Covered | Schlumberger Ltd., Halliburton Co., Baker Hughes Co., Weatherford International Plc, TechnipFMC plc, NOV Inc., Expro Group Holdings NV, Tendeka, Packers Plus Energy Services Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent Completion Market Shifts & Advancements
Software-defined downhole control is fragmenting the historical hardware-centric value chain, pulling margin toward analytics platforms while commoditizing valve actuators and sensors.
Self-powered autonomous inflow control devices are decentralizing reservoir management authority from surface facilities to downhole tools. Majors operating Brazil's pre-salt clusters are piloting these systems at scale. The shift compresses response latency from hours to seconds, eliminating hydraulic umbilical dependency and reducing subsea infrastructure weight.
REACH substance restrictions on perfluorinated compounds are forcing seal material substitutions in high-pressure packer elements. European operators face accelerated elastomer replacement cycles as fluorocarbon alternatives mature. Completion suppliers with in-house polymer chemistry capabilities are capturing specification authority from component vendors.
Integrated service contracting is consolidating vendor relationships around bundled subsurface-to-surface portfolios. Deepwater operators in the Gulf of Mexico now favor single-source accountability over discrete equipment procurement. This procurement compression disadvantages pure-play hardware manufacturers without diagnostic software or reservoir engineering service arms.
Global Intelligent Completion Market Segmentation
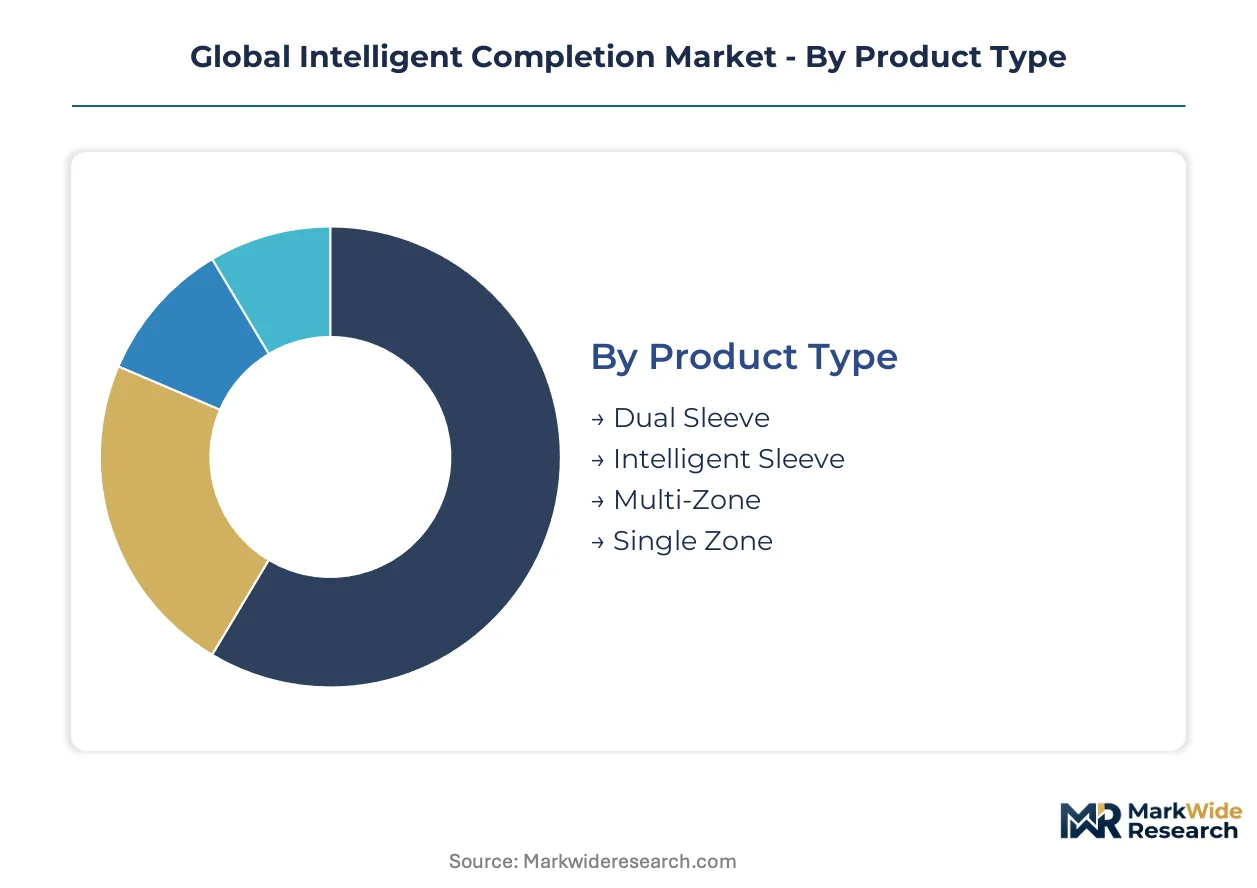
Intelligent completion architectures vary dramatically in complexity and cost depending on reservoir characteristics and operator capabilities. Understanding how demand fragments across product configurations, control technologies, well types, and buyer categories reveals where suppliers must concentrate engineering resources and field service capacity.
Product Type:
Supply concentrates around systems capable of isolating multiple pay zones from a single wellbore, with manufacturing scale favoring standardized sleeve geometries over bespoke single-zone designs.
- Multi-Zone:These assemblies integrate multiple remotely actuated sleeves and inflow control devices within a single completion string, enabling simultaneous production from stacked reservoirs. Demand clusters in Brazil's pre-salt developments and Gulf of Mexico deepwater assets where capital efficiency across thin pay intervals drives specification. Schlumberger and Baker Hughes anchor their manufacturing scale around these complex configurations.
- Dual Sleeve:Simpler two-zone architectures serve mature field redevelopment and secondary recovery projects where reservoir complexity is moderate. North Sea operators favor these systems for zonal isolation compliance under Norway's PSA facility regulations, balancing functionality against intervention simplicity.
- Intelligent Sleeve:Modular sleeve designs with integrated sensors and actuation mechanisms support retrofit applications in existing well stock.
- Single Zone:Basic intelligent completions for homogeneous reservoirs or pilot testing of new technologies.
Multi-zone systems absorb the bulk of installed capacity; dual sleeve configurations are expanding most quickly in mature basin redevelopment.
Technology:
Cost tiers separate legacy electro-hydraulic architectures from emerging autonomous platforms, with margin migrating toward embedded software as hardware commoditizes.
- Autonomous Systems:Self-powered downhole tools with onboard decision algorithms eliminate surface umbilical dependency and compress response latency from hours to seconds. Brazil's ANP regulatory framework has yet to certify these as primary control mechanisms, delaying full deployment despite pilot success in pre-salt clusters. Halliburton and specialized entrants are capturing specification authority through predictive analytics platforms.
- Electro-Hydraulic:Hybrid architectures combining electrical signal transmission with hydraulic actuation power dominate current deepwater installations. West African fields exhibit substantial lock-in to existing umbilical infrastructure, creating switching friction against autonomous retrofits.
- Electromechanical:All-electric actuation systems for platforms with limited hydraulic infrastructure or extreme temperature requirements.
- Hydraulic:Conventional pressure-actuated systems retaining relevance in cost-sensitive conventional applications.
Electro-hydraulic systems retain the dominant installed base; autonomous platforms command the steepest expansion trajectory as regulatory acceptance matures.
Application:
Volume concentrates in deepwater extraction where subsea infrastructure complexity justifies premium intelligent completion economics over conventional interventions.
- Deepwater Extraction:Subsea completions at depths exceeding 1,000 meters require permanent monitoring and remote actuation to avoid prohibitively expensive intervention vessels. Brazil's pre-salt carbonate formations and Gulf of Mexico Lower Tertiary trends anchor demand, with fiber-optic sensing maturation reducing operational expenditure by half for distributed temperature monitoring.
- Enhanced Recovery:Intelligent completions enable real-time inflow control for waterflood and gas injection optimization, critical for maximizing recovery factors in mature fields. EU Green Deal methane intensity targets under CSRD disclosure requirements are pulling monitoring-intensive completions into North Sea and Middle East assets.
- Unconventional Wells:Shale and tight formation applications where multi-stage fracturing complicates zonal management.
- Conventional Wells:Standard reservoir applications with lower complexity and intervention frequency.
Deepwater extraction commands the dominant revenue share; enhanced recovery applications are climbing the fastest as mature basin operators prioritize recovery factor optimization.
End User:
Customer type determines procurement complexity, with integrated service contracting consolidating vendor relationships around bundled subsurface-to-surface accountability.
- Oilfield Services:Schlumberger, Halliburton, and Baker Hughes deploy intelligent completions as components of integrated drilling and completion contracts, capturing margin through diagnostic software and reservoir engineering services. Gulf of Mexico operators increasingly favor this single-source accountability over discrete equipment procurement.
- Exploration Companies:International oil companies and national oil companies with in-house reservoir engineering capabilities specify intelligent completions directly, particularly for strategic pre-salt and deepwater developments where technology differentiation matters.
- Drilling Contractors:Rig owners expanding into integrated well construction services.
- Reservoir Engineers:Technical specialists influencing specification through reservoir simulation and production optimization studies.
Oilfield services providers capture the dominant procurement volume; exploration companies are gaining share fastest as operators bring completion engineering in-house for strategic developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in deepwater provinces where subsea infrastructure complexity justifies premium intelligent completion economics. Brazil's pre-salt clusters, the US Gulf of Mexico, and Norway's North Sea shelf anchor procurement volume. Operators in these jurisdictions prioritize multi-zone systems to maximize recovery from stacked carbonate and sandstone reservoirs.
United States
Gulf of Mexico Lower Tertiary developments drive specification for high-pressure intelligent completions rated above 10,000 psi. The US BSEE well control rules mandate redundant barrier systems that expand addressable demand for zonal isolation technologies. Houston-headquartered oilfield services providers anchor deepwater contracting relationships through bundled subsurface-to-surface portfolios.
Brazil
Pre-salt carbonate formations in the Santos Basin require advanced inflow control devices for high-pressure reservoir management. Brazil's ANP regulatory framework shapes certification demands for intelligent completion suppliers accessing deepwater contracts. Operators pilot autonomous downhole systems at scale despite pending regulatory acceptance of algorithmic primary control mechanisms.
Norway
North Sea mature field redevelopment prioritizes capital efficiency through multi-zone intelligent completions. Norway's PSA facility regulations and NORSOK D-010 drilling standards require redundant zonal isolation, directly expanding hardware demand. Stavanger and Bergen clusters concentrate engineering procurement for subsea production systems.
United Kingdom
UK Continental Shelf decommissioning timelines accelerate enhanced recovery investments requiring real-time reservoir monitoring. The North Sea Transition Authority's emissions reduction targets pressure operators toward monitoring-intensive completions for methane intensity compliance. Aberdeen remains the dominant procurement hub for North Sea intelligent completion services.
Saudi Arabia
Offshore and onshore sour gas reservoirs in the Arabian Gulf remain underpenetrated by intelligent completion technology. The country's national oil company specifications increasingly emphasize permanent downhole monitoring for carbonate reservoir optimization. Dhahran-based engineering centers coordinate procurement for high-temperature completion assemblies.
Global Intelligent Completion Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated service providers capturing deepwater procurement through bundled accountability. The vendor base concentrates around three strategic archetypes: full-service oilfield conglomerates with diagnostic software arms, pure-play completion hardware specialists, and emerging autonomous system entrants with predictive analytics platforms. Competitive dynamics center on manufacturing scale for multi-zone tool catalogs and technology licensing for wireless telemetry architectures.
Within the integrated services tier, Schlumberger Ltd. and Halliburton Co. occupy positions exemplifying bundled subsurface-to-surface portfolio strategies. Baker Hughes Co. anchors the manufacturing-scale archetype through broad multi-zone completion tool offerings. These three entities represent the dominant competitive anchors against which specialized autonomous system entrants and regional fabricators position differentiation.
| Leading Market Players |
|---|
| Schlumberger Ltd. |
| Halliburton Co. |
| Baker Hughes Co. |
| Weatherford International Plc |
| TechnipFMC plc |
| NOV Inc. |
| Expro Group Holdings NV |
| Tendeka |
| Packers Plus Energy Services Inc |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between API RP 19G2-qualified assemblies and uncertified alternatives manifests in pricing spreads exceeding three-to-one, while supply chain configurations cluster around Houston, Stavanger, and Singapore to service deepwater contracting hubs. Premium alloy mandrel sourcing from specialty steel mills in Germany and Japan anchors the high-pressure tier, with carbon steel alternatives for lower-pressure Brazilian pre-salt applications compressing margins across standardized sleeve geometries.
Pricing Analysis
Volume concentrates in project-based contracting for multi-zone completions where margin capture shifts toward bundled diagnostics software, while transactional component sales of individual sleeves and sensors face relentless cost compression. Price differentiation rests on NORSOK D-010 certification grade and after-sales reservoir engineering support, with Gulf of Mexico operators least sensitive to premium positioning and Middle East national oil companies driving hardest on standard-tier procurement. Pricing pressure stems from nickel alloy cost volatility squeezing high-temperature assembly margins, forcing suppliers to absorb input swings or lose Brazilian deepwater contracts.
Supply Chain Analysis
Dual-sourcing requirements from Brazil's ANP and Norway's PSA mandate qualified supplier rosters for critical zonal isolation components, fragmenting procurement across Schlumberger, Halliburton, and Baker Hughes manufacturing networks in the United States, Norway, and Singapore. Raw material dependencies center on Inconel and Hastelloy mandrels from German and Japanese specialty mills, fiber-optic sensing cables from Scandinavian suppliers, and high-pressure elastomer seals subject to REACH substance restrictions. Supply chain risk concentrates in single-source vulnerability for premium alloy forging capacity, with distribution running through oilfield services providers' integrated project logistics rather than independent channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as autonomous algorithm acceptance by Brazil's ANP and US BSEE threatens to obsolete electro-hydraulic incumbents without predictive analytics capabilities, forcing subscale hardware specialists toward distressed exits or strategic absorption.
For Market Incumbents: Lock in Brazilian pre-salt contracting relationships through integrated subsurface-to-surface portfolios before autonomous system entrants gain regulatory certification, while accelerating backward integration into fiber-optic sensing manufacturing to capture specification authority from Scandinavian component vendors. The priority lever centers on software-defined downhole control platforms that commoditize valve hardware while embedding recurring analytics revenue.
For New Entrants and Emerging Players: The premium-to-economy price gap in Saudi Arabian sour gas reservoirs—where intelligent completion penetration lags Brazilian benchmarks by half—offers white-space entry through wireless telemetry architectures that eliminate hydraulic control line infrastructure. Target Middle East carbonate redevelopment with acoustic signal transmission systems for slim-hole applications inaccessible to conventional electro-hydraulic completions, positioning on EU Green Deal methane intensity compliance as the regulatory-pull demand catalyst.
For Investors and Strategic Acquirers: Re-rating potential sits with autonomous system specialists possessing predictive analytics platforms given pending ANP algorithm certification as primary control mechanisms, which would displace electromechanical incumbents' hardware-centric valuations. Acquisition focus should center on software-centric entrants with pilot deployment records in Brazil's pre-salt clusters, with the signal to watch being BSEE publication of autonomous downhole decision loop safety guidelines that would unlock Gulf of Mexico contracting.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Algorithm Certification Pursuit | ANP and BSEE acceptance of self-powered downhole control as primary barrier mechanisms would restructure competitive tiers entirely. |
| Wireless Telemetry Integration | Acoustic and electromagnetic signal transmission eliminates hydraulic umbilical dependency for extended-reach laterals. |
| Predictive Analytics Platform Development | Software-defined reservoir management pulls margin from commoditized valve actuators toward recurring diagnostics revenue. |
| REACH-Compliant Seal Material Substitution | Fluorocarbon alternatives for high-pressure packer elements capture specification authority from polymer chemistry vendors. |
| Integrated Service Contracting Consolidation | Single-source subsurface-to-surface accountability displaces discrete equipment procurement in Gulf of Mexico deepwater. |
Research Methodology
Document review covered regulatory filings with Brazil's ANP, Norway's PSA, and the US BSEE, complemented by interviews with reservoir engineering directors at international oil companies, intelligent completion product managers at oilfield services providers, and procurement leads for national oil companies in the Middle East. Secondary validation drew from API equipment certification databases, NORSOK standard documentation, and SEC filings of publicly traded oilfield services conglomerates, with bottom-up installation data triangulated against top-down deepwater capital expenditure forecasts across the analysis window.
Segmentation outputs reflect modeling across product type, control technology architecture, well application category, and end-user procurement structure, with growth trajectories derived from basin-specific development timelines and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated pre-salt carbonate reservoir complexity indices and fiber-optic sensing adoption curves in mature North Sea assets.
Inputs from ANP certification timelines and BSEE well control rulemaking were available through the study window; gaps in autonomous system pilot performance data introduce uncertainty bands around algorithm acceptance assumptions. Deviation in Brazil's regulatory certification pace or nickel alloy supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Factory Automation Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Smart Industries Market
Industrial Automation
Smart Handwriting Machine Market
Industrial Automation
Global Mining Automation Consumption Market
Industrial Automation
UV Curing System Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
Industrial Multiprotocol Gateways Market