
 Latin America HMI Market | 2026-2036
Latin America HMI Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America HMI Market Foresight
Brazil's INMETRO certification requirements for industrial electronics is realigning the cost-of-entry calculus for HMI vendors seeking market access. Siemens AG leverages its established automation portfolio to sustain channel dominance across Brazilian heavy industry. Rockwell Automation anchors its position through specialized manufacturing execution system integration. Schneider Electric SE differentiates via energy-efficient panel designs suited to Latin American utility constraints.
Human Machine Interface technology encompasses hardware and software systems enabling operator interaction with industrial equipment, typically featuring resistive or capacitive touchscreens with IP65-rated enclosures and real-time data visualization capabilities. These systems serve primarily to reduce operator error and accelerate response times in automated production environments. Touch technology leads volume deployment across Latin American factory floors, while embedded systems represent the fastest-expanding segment as OEMs integrate control functions directly into machinery. Software offerings command the strongest margin pools due to recurring licensing and remote update architectures.
INMETRO in Brazil, NOM standards in Mexico, and Argentina's IRAM certification collectively shape product design requirements and compliance timelines for HMI equipment deployed across the region. ANATEL telecommunications regulations in Brazil further constrain wireless-enabled interface deployments requiring pre-market approval. Stakeholders must monitor evolving local content rules and energy efficiency mandates as governments tighten industrial equipment standards without harmonizing across borders.
Market Dynamics
Brazilian automotive assembly lines are driving touchscreen standardization across Latin American manufacturing floors, forcing HMI vendors to recalibrate hardware durability specifications and software localization investments.
Growth Catalysts
- INMETRO Certification Thresholds:Brazil's tightening industrial electronics standards are filtering out low-tier imports and elevating procurement criteria for factory automation buyers.
- Automotive Touchscreen Deployment:Brazilian vehicle manufacturers are embedding HMI panels directly into welding and paint shop control stations, creating sustained hardware refresh cycles.
- Northern Mexico Manufacturing Corridor:Export-oriented maquiladoras near the US border are consolidating HMI procurement through centralized engineering hubs.
Market Restraints
- Semiconductor Input Volatility:Display driver IC shortages continue disrupting panel production schedules for Mexican and Brazilian system integrators.
- ANATEL Wireless Approval Friction:Brazil's telecommunications regulator imposes 6-12 month pre-market timelines on cellular-enabled HMI devices.
- Resistive Touch Substitution Pressure:Capacitive alternatives are eroding demand for legacy resistive interfaces in premium industrial segments.
Strategic Opportunities
- Argentine Industrial Rehabilitation:IRAM certification pathways for imported HMI equipment remain underutilized by foreign vendors despite recovering manufacturing investment.
- Energy Efficiency Mandates:Mexico's CONUEE standards for industrial electrical equipment are creating specification advantages for low-power panel designs.
- Cloud-Edge Convergence:Hybrid architectures combining local SCADA processing with remote diagnostics are opening software subscription revenue streams.
Industry Challenges
- Portuguese-Spanish Localization Gap:HMI software vendors struggle to maintain parallel technical documentation and training ecosystems across Brazil and Spanish-speaking markets.
- Legacy PLC Integration Complexity:Brownfield facilities in São Paulo and Monterrey require costly protocol bridging to connect modern touch interfaces with 1990s-era control hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America HMI Market |
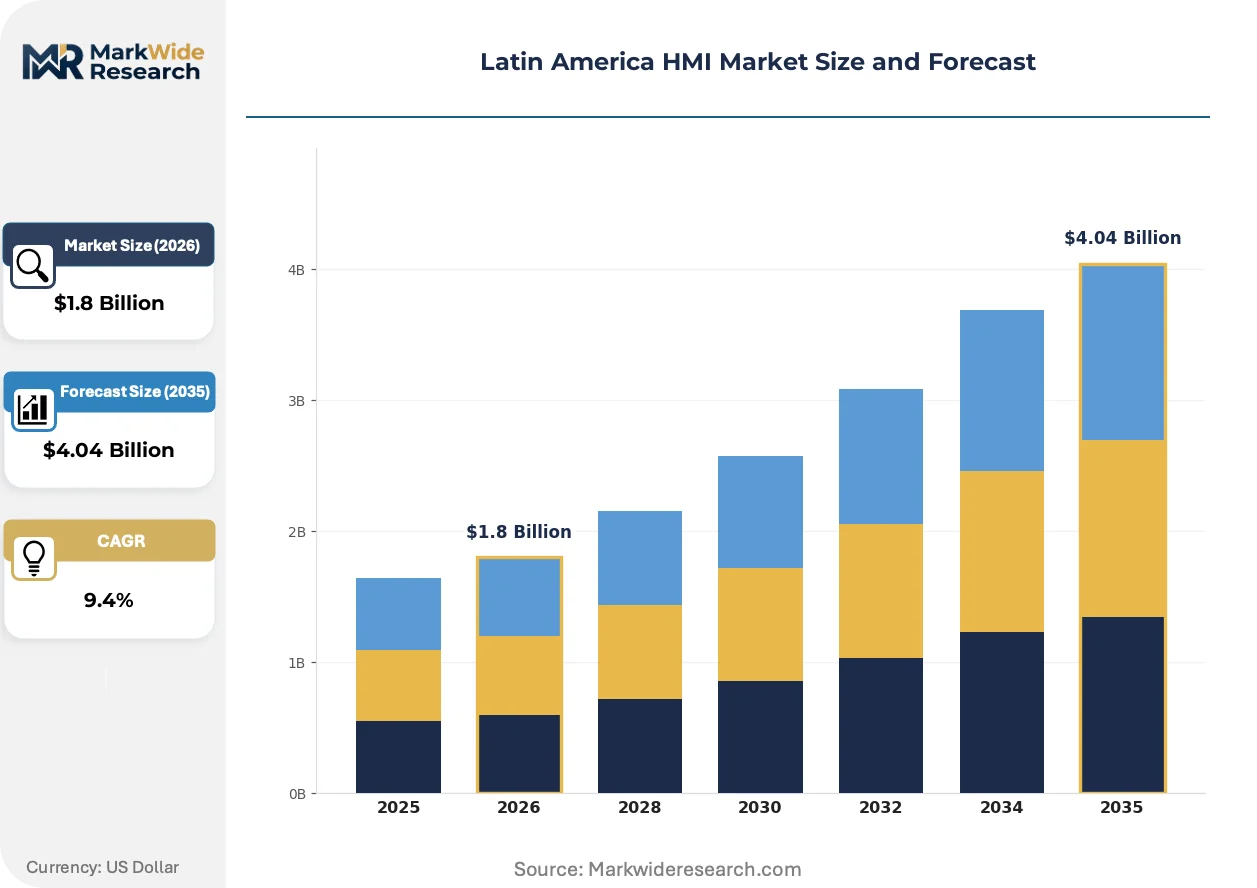
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Touch, Voice, Gesture, Visualization Application: Industrial Automation, Transportation, Healthcare, Entertainment End User: Manufacturers, Service Providers, Automotive, Defense Product Type: PCRT, Software, Panels, Embedded Systems |
| Companies Covered | ABB Ltd, Siemens AG, Schneider Electric SE, Rockwell Automation, Honeywell International Inc, Advantech Inc, Mitsubishi Electric Corporation, Panasonic Corporation, GE Ltd, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America HMI Market Shifts & Advancements
Edge-native HMI architectures are displacing centralized control room models across Latin American factory networks, redistributing computational load and reshaping vendor service relationships.
Embedded HMI systems with integrated PLCs are expanding into packaging machinery and material handling equipment across Mexican food processing plants. OEMs in Guadalajara and Querétaro are specifying these consolidated control units to reduce panel footprint and wiring complexity. This convergence is compressing the traditional separation between hardware suppliers and automation software vendors.
INMETRO's updated electromagnetic compatibility requirements for industrial electronics are forcing redesigns of HMI enclosure shielding and grounding architectures. Brazilian certification labs report extended testing queues as manufacturers adapt legacy product lines. Heavy industry segments in Minas Gerais and Rio de Janeiro are experiencing the longest compliance verification delays.
Buyer procurement committees are consolidating HMI vendor relationships from an average of four suppliers per plant to single-source framework agreements. Automotive assemblers in São Bernardo do Campo are leading this concentration, trading price competition for integrated lifecycle support. This pattern is most pronounced in Brazil's southern manufacturing belt where engineering staff shortages favor simplified supplier management.
Latin America HMI Market Segmentation
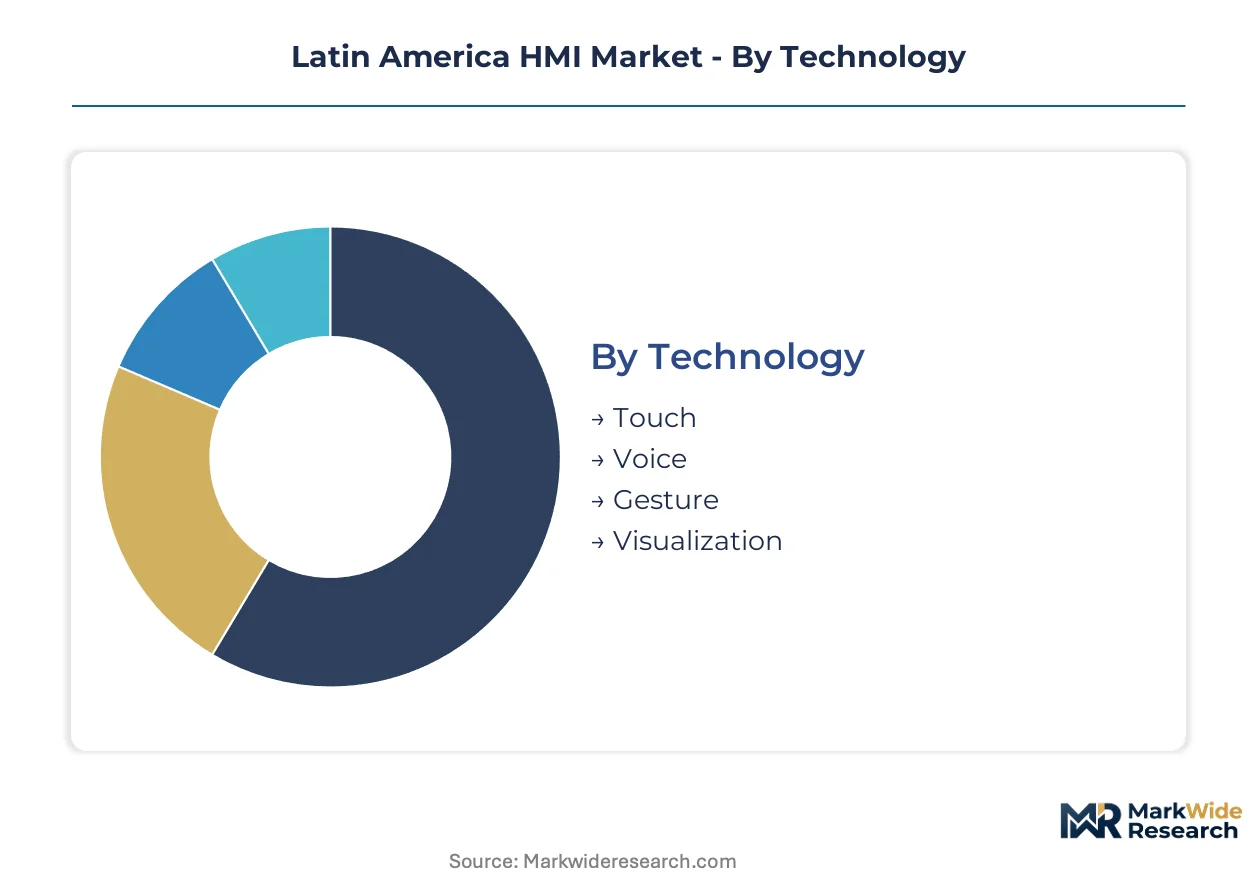
HMI procurement patterns across Latin America diverge sharply by deployment context. Technology choice, application environment, and end-user sophistication each reshape vendor engagement models and service requirements.
Technology:
Upgrade cycles in Brazilian automotive plants and Mexican maquiladoras are accelerating replacement of legacy interface technologies.
- Touch:Resistive and capacitive touchscreen systems dominate factory floor deployments, with IP65-rated enclosures standard for welding and paint shop environments in São Bernardo do Campo. Brazilian assembly lines are consolidating procurement around multi-touch capacitive panels to reduce operator error rates in high-vibration settings.
- Voice:Speech-activated interfaces are penetrating cleanroom and food processing applications where hands-free operation reduces contamination risk. Mexican pharmaceutical manufacturers in Guadalajara are piloting voice commands for sterile filling line adjustments.
- Gesture:Motion-sensing HMI remains nascent, with limited deployment in Colombian mining visualization centers where dust-resistant non-contact operation offers safety advantages.
- Visualization:Advanced graphics rendering supports complex SCADA integration for Chilean copper concentrator remote monitoring stations.
Volume placements concentrate in Touch; the faster expansion belongs to Voice.
Application:
Cost tier differentiation separates specification-intensive heavy industry from price-sensitive commercial implementations.
- Industrial Automation:Factory control systems command the largest hardware budgets, with INMETRO-certified panels mandatory for Brazilian steel and petrochemical complexes. Monterrey system integrators bundle HMI with PLC programming services to capture lifecycle value.
- Transportation:Railway signaling and port logistics interfaces in Santos and Valparaíso prioritize ruggedized displays with extended temperature ranges. Chilean mining rail operators are refreshing cab control systems with sunlight-readable panels.
- Healthcare:Medical device interfaces in São Paulo and Mexico City require IEC 60601 compliance for electromagnetic compatibility, constraining supplier pools.
- Entertainment:Casino and stadium control systems in Buenos Aires and Rio de Janeiro favor large-format touch displays with consumer-grade aesthetics.
Industrial Automation captures the dominant share of hardware expenditure; Healthcare applications are climbing the fastest as hospital infrastructure investment recovers.
End User:
Customer type determines service intensity, with multinational manufacturers demanding centralized procurement frameworks that reshape vendor economics.
- Manufacturers:Discrete and process industry producers in Minas Gerais and Querétaro drive standardization through corporate engineering specifications. Volkswagen and Nissan plants in Resende and Aguascalientes enforce common HMI platforms across multiple supplier tiers.
- Service Providers:System integration firms in São Paulo and Mexico City aggregate demand from mid-sized factories, favoring configurable software licenses over hardware margins.
- Automotive:OEM assembly plants specify embedded HMI for welding robots and conveyor controls, with direct vendor relationships bypassing distribution channels.
- Defense:Brazilian Armed Forces procurement through the Ministry of Defense imposes stringent security and local content requirements on command interface suppliers.
Manufacturers account for the greatest installed base; Service Providers are expanding most quickly as outsourcing of automation engineering accelerates.
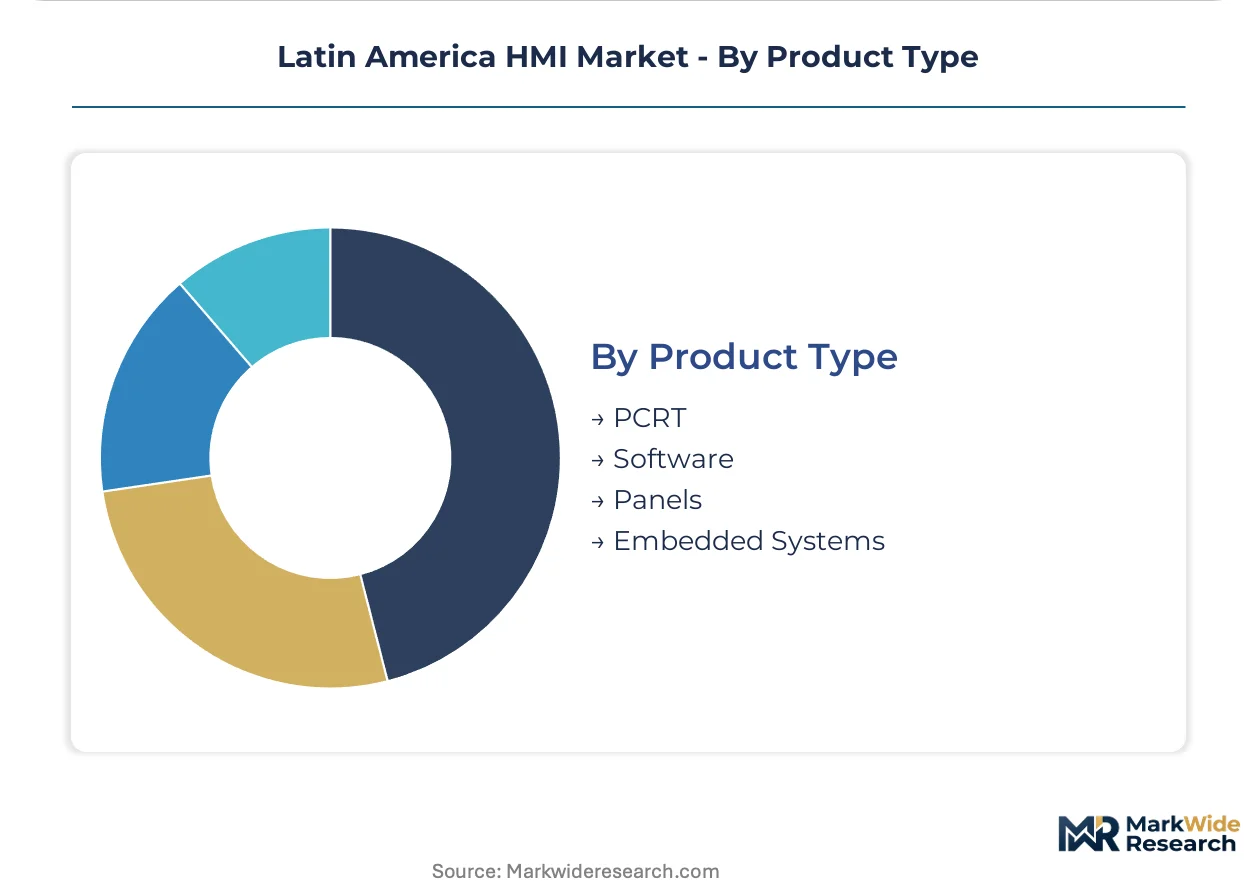
Product Type:
Margin structure varies dramatically across physical hardware, software licensing, and integrated embedded solutions.
- PCRT:Panel-mounted computers with resistive touchscreens retain footholds in legacy brownfield facilities across São Paulo state, though capacitive alternatives are displacing them in new greenfield investments.
- Software:Runtime licenses and development environments generate recurring revenue streams, with remote update architectures enabling subscription pricing for SCADA and manufacturing execution system integration.
- Panels:Standalone display units with integrated I/O constitute the volume hardware category, with Mexican maquiladoras consolidating procurement through framework agreements.
- Embedded Systems:PLC-integrated control units are gaining share in packaging machinery OEM specifications from Guadalajara and Querétaro, compressing panel footprint and wiring complexity.
Panels dominate unit shipments; Embedded Systems are gaining share fastest as machinery OEMs consolidate control architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for HMI equipment concentrates in Brazil's southern manufacturing belt and Mexico's northern border corridor, with procurement committees consolidating supplier relationships to streamline engineering management. Argentine and Chilean markets remain secondary but present certification pathway opportunities for prepared vendors. Regulatory fragmentation across Portuguese and Spanish-speaking jurisdictions complicates technical documentation and training ecosystem maintenance.
Brazil
Automotive assemblers in São Bernardo do Campo drive touchscreen standardization for welding and paint shop control stations. INMETRO certification requirements for industrial electronics are tightening electromagnetic compatibility thresholds and extending testing queues at Brazilian labs. Heavy industry complexes in Minas Gerais and Rio de Janeiro experience the longest compliance verification delays as manufacturers adapt legacy product lines.
Mexico
Export-oriented maquiladoras near the US border are consolidating HMI procurement through centralized engineering hubs in Monterrey. NOM standards for industrial electrical equipment shape product design requirements and compliance timelines for equipment deployed across the region. OEMs in Guadalajara and Querétaro are specifying embedded control units to reduce panel footprint and wiring complexity in packaging machinery.
Argentina
IRAM certification pathways for imported HMI equipment remain underutilized by foreign vendors despite recovering manufacturing investment in Buenos Aires. The country's national standards body maintains distinct electromagnetic compatibility requirements that diverge from Brazilian and Mexican frameworks. Industrial rehabilitation in the Greater Buenos Aires area is creating specification opportunities for low-power panel designs.
Chile
Copper concentrator remote monitoring stations require advanced graphics rendering for complex SCADA integration in the Atacama Desert mining belt. Railway signaling operators are refreshing cab control systems with sunlight-readable panels for port logistics interfaces in Valparaíso. The national mining regulator imposes equipment durability specifications that exceed standard industrial ratings for high-altitude deployments.
Colombia
Motion-sensing HMI deployment remains nascent in Colombian mining visualization centers where dust-resistant non-contact operation offers safety advantages. The country's industrial equipment import regulations lack harmonization with Andean Community neighbors, creating documentation friction for cross-border suppliers. Bogotá-based system integrators aggregate demand from mid-sized factories favoring configurable software licenses over hardware margins.
Latin America HMI Market Competitive Landscape
European producers anchor the premium-tier certification-compliant segment; East Asian specialists hold the embedded systems and component supply tier. The vendor base stratifies across three layers: multinational automation conglomerates with established certification expertise, regional system integrators with localized service capabilities, and machinery OEMs integrating control functions in-house. Dominant competitive moves include vertical integration into software subscription architectures and strategic partnerships to bypass ANATEL wireless approval timelines.
Within the multinational conglomerate tier, Siemens AG and Schneider Electric SE exemplify archetypes leveraging established automation portfolios to sustain channel dominance across Brazilian heavy industry. Rockwell Automation occupies a position representing specialized manufacturing execution system integration capabilities. These three anchors illustrate how certification navigation and energy-efficient design differentiation separate premium positioning from commodity panel competition.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| Rockwell Automation |
| Honeywell International Inc |
| Advantech Inc |
| Mitsubishi Electric Corporation |
| Panasonic Corporation |
| GE Ltd |
| Others |
Supply & Pricing Matrix
Display driver IC spot price volatility cascades through Latin American HMI supply chains, compressing margins for Mexican system integrators while elevating procurement premiums for INMETRO-certified panels in Brazilian heavy industry.
Pricing Analysis
Volume shipments concentrate in standalone panel hardware with thin margins, while software runtime licenses capture superior returns through recurring subscription architectures. Three-tier pricing structure across premium certified, standard industrial, and economy non-certified levels separates Siemens and Schneider Electric from regional assemblers. Cost compression in economy tiers intensifies because East Asian panel suppliers are flooding Brazilian distribution channels with uncertified alternatives. Automotive OEMs in São Bernardo do Campo exhibit lowest price sensitivity due to lifecycle support requirements, whereas mid-sized food processors in Guadalajara drive hardest bargain on unit economics.
Supply Chain Analysis
Refurbishment flows for legacy resistive touch panels are extending equipment lifecycles in São Paulo brownfield facilities, creating secondary market price anchors that constrain new equipment premiums. Manufacturing concentration rests on Taiwan and South Korea for display driver ICs, China for capacitive touch sensor modules, and Germany for precision enclosure shielding. Semiconductor input volatility represents the dominant structural risk, with 6-12 month ANATEL approval timelines for wireless-enabled devices adding regulatory friction. Distribution runs through Monterrey and São Paulo-based system integrators who bundle hardware with PLC programming services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's HMI market functions as a cost-of-compliance story where Brazil's INMETRO certification requirements erect formidable barrier-to-entry moats that reward prepared incumbents and filter out speculative entrants.
For Market Incumbents: Anticipate capacitive touch substitution pressure by accelerating embedded system development for Guadalajara packaging machinery OEMs. Secure backward integration into display driver IC sourcing to buffer semiconductor volatility. Deepen certification expertise at Brazilian INMETRO labs to extend compliance verification timelines that disadvantage import-dependent competitors. For New Entrants and Emerging Players: Argentine industrial rehabilitation programs represent the most penetrable geography, with IRAM certification pathways remaining underutilized despite recovering Buenos Aires manufacturing investment. Target voice-activated HMI pilots in Guadalajara pharmaceutical cleanrooms where hands-free operation commands specification premiums. Pursue partnership routes with Bogotá system integrators to bypass direct ANATEL wireless approval friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-centric HMI specialists with established remote update architectures in Mexico's northern manufacturing corridor. Long-term viability hinges on subscription revenue conversion rates rather than hardware shipment volumes. Monitor CONUEE energy efficiency mandate enforcement timelines as inflection indicator for low-power panel design premiums.| Strategic Initiative | Industry Significance |
|---|---|
| INMETRO Certification Pre-Investment | Early certification queue positioning at Brazilian labs secures 6-12 month lead time advantage over import-dependent rivals. |
| Embedded PLC Integration Development | Consolidated control units specified by Querétaro packaging OEMs compress panel footprint and wiring complexity. |
| Portuguese-Spanish Localization Buildout | Parallel technical documentation ecosystems address the persistent software vendor gap across Brazil and Spanish-speaking markets. |
| Cloud-Edge Hybrid Architecture Launch | Local SCADA processing combined with remote diagnostics opens software subscription revenue streams in Monterrey maquiladoras. |
| Argentine IRAM Certification Partnership | Joint pathway development with Buenos Aires standards body captures recovering industrial rehabilitation specification opportunities. |
Research Methodology
Document review covered SEC filings from automation conglomerates, ANATEL and INMETRO regulatory databases, and OEM procurement specifications, complemented by interviews with plant engineers at São Bernardo do Campo automotive facilities, Monterrey system integrators, and aftermarket service heads at Brazilian heavy industry complexes. Secondary validation drew from customs trade records, NOM standards documentation, and SCADA platform deployment disclosures. Bottom-up equipment shipment tallies were cross-referenced against top-down manufacturing automation capex estimates.
Historical volume trajectories were cross-referenced against panel input from automation procurement committees to anchor projection parameters across the analysis window. Segmentation dimensions modeled include technology type, application environment, end-user sophistication, and product architecture. CAGRs were derived through iterative reconciliation of hardware refresh cycle data with software subscription conversion rates. Industry-specific forecast inputs encompassed INMETRO certification queue lengths and Mexican maquiladora framework agreement renewal patterns.
Revisions become necessary when semiconductor input availability shifts, ANATEL regulatory timelines extend, or Argentine industrial rehabilitation investment accelerates beyond baseline assumptions. Forecasts reflect documented parameters and stakeholder input consensus. Practitioners should monitor display driver IC spot price movements and CONUEE energy efficiency mandate enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Grippers Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Warehouse Automation Systems Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Drilling Automation Market
Industrial Automation
United States Human Machine Interface Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Europe Sortation Systems Market