
 Survey and Feedback Management Software Market | 2026-2036
Survey and Feedback Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Survey and Feedback Management Software Market Analytics
North American software engineering capacity is decoupling from traditional on-premises deployment cycles as cloud-native architectures dominate new builds. Qualtrics International Inc. leverages its vertical integration across experience management to sustain enterprise retention. SurveyMonkey anchors the self-serve segment with freemium-to-paid conversion mechanics. Medallia competes through AI-powered text analytics specialization for Fortune 500 accounts.
Survey and feedback management software constitutes a category of enterprise applications that collect, aggregate, and analyze structured and unstructured sentiment data through channels including web forms, mobile interfaces, and embedded APIs, with core functional parameters encompassing real-time dashboarding, natural language processing for open-text analysis, and closed-loop action management. Its primary commercial purpose centers on enabling organizations to measure stakeholder satisfaction, identify operational friction points, and trigger corrective workflows across customer experience and employee engagement domains. Cloud-based deployment leads current revenue generation due to lower total cost of ownership and faster implementation cycles, while open-source alternatives occupy a niche among academic researchers and privacy-sensitive European institutions. Enterprise user types command the deepest per-seat pricing, though SMBs represent the fastest-growing subscription base as no-code configuration reduces implementation barriers.
GDPR and the EU AI Act impose strict constraints on automated sentiment scoring and cross-border data transfers, compelling vendors to architect region-specific data residency options. The US lacks comprehensive federal privacy legislation, though sectoral HIPAA and state-level frameworks create compliance complexity for healthcare and multi-state operators. Stakeholders must monitor whether emerging algorithmic accountability rules in the European Union and analogous proposals in the US Congress reshape competitive moats around proprietary AI models versus transparent, auditable scoring methodologies.
Market Dynamics
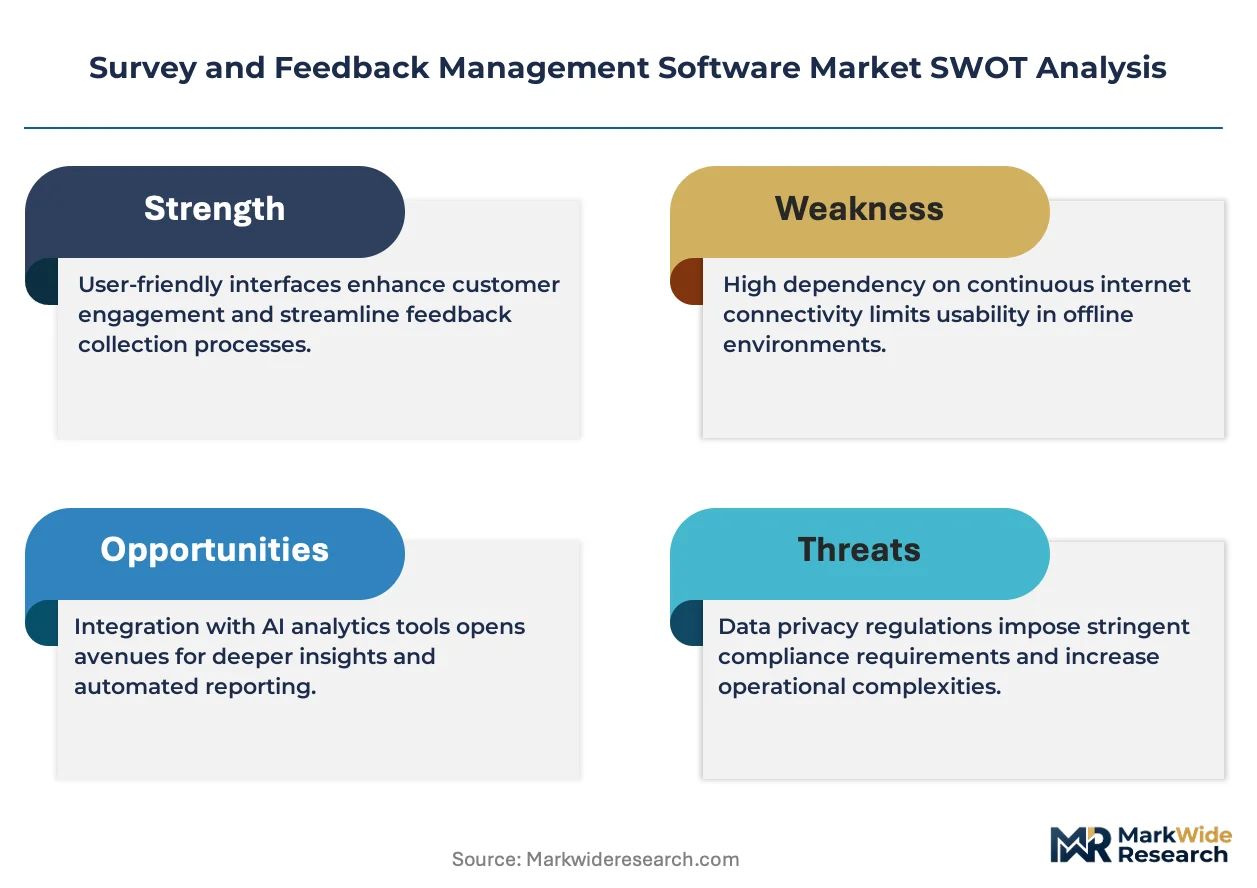
The EU AI Act and GDPR compliance requirements are forcing vendors to rearchitect data residency and algorithmic transparency features, compressing product development cycles while elevating procurement scrutiny around automated sentiment scoring capabilities.
Growth Catalysts
- Real-time pulse survey adoption:Enterprise HR departments in the United States are replacing annual engagement surveys with continuous feedback loops, driving subscription expansion for cloud-native platforms.
- GDPR Article 22 enforcement:European regulators are mandating human oversight for automated decision-making, creating demand for explainable AI modules that audit sentiment classification outputs.
- No-code configuration:SMB adoption is accelerating as visual workflow builders eliminate dependency on IT departments for survey deployment and dashboard customization.
Market Restraints
- Cross-border data transfer friction:Schrems II rulings invalidate Privacy Shield mechanisms, forcing vendors to maintain separate infrastructure instances for EU and US data processing.
- Open-source substitution threat:Academic institutions and privacy-sensitive organizations in Germany are deploying LimeSurvey and self-hosted alternatives to SaaS platforms.
- Technical limitation in low-resource languages:NLP models for open-text analysis exhibit reduced accuracy for Indic languages, constraining penetration in Indian regional markets.
Strategic Opportunities
- Embedded API distribution:Survey widgets are integrating directly into Salesforce and ServiceNow workflows, capturing feedback at transaction touchpoints without platform switching.
- CSRD mandate tailwind:The EU Corporate Sustainability Reporting Directive requires stakeholder sentiment disclosure, expanding addressable market for ESG-focused feedback modules.
- Voice-to-text convergence:Contact center speech analytics are merging with traditional survey data, enabling unified customer experience scoring across channels.
Industry Challenges
- Prompt engineering talent scarcity:Vendors struggle to hire specialists capable of tuning large language models for domain-specific sentiment classification without hallucination risks.
- Legacy system integration complexity:On-premises HRIS and CRM databases in Fortune 500 accounts require custom ETL pipelines, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Survey and Feedback Management Software Market |
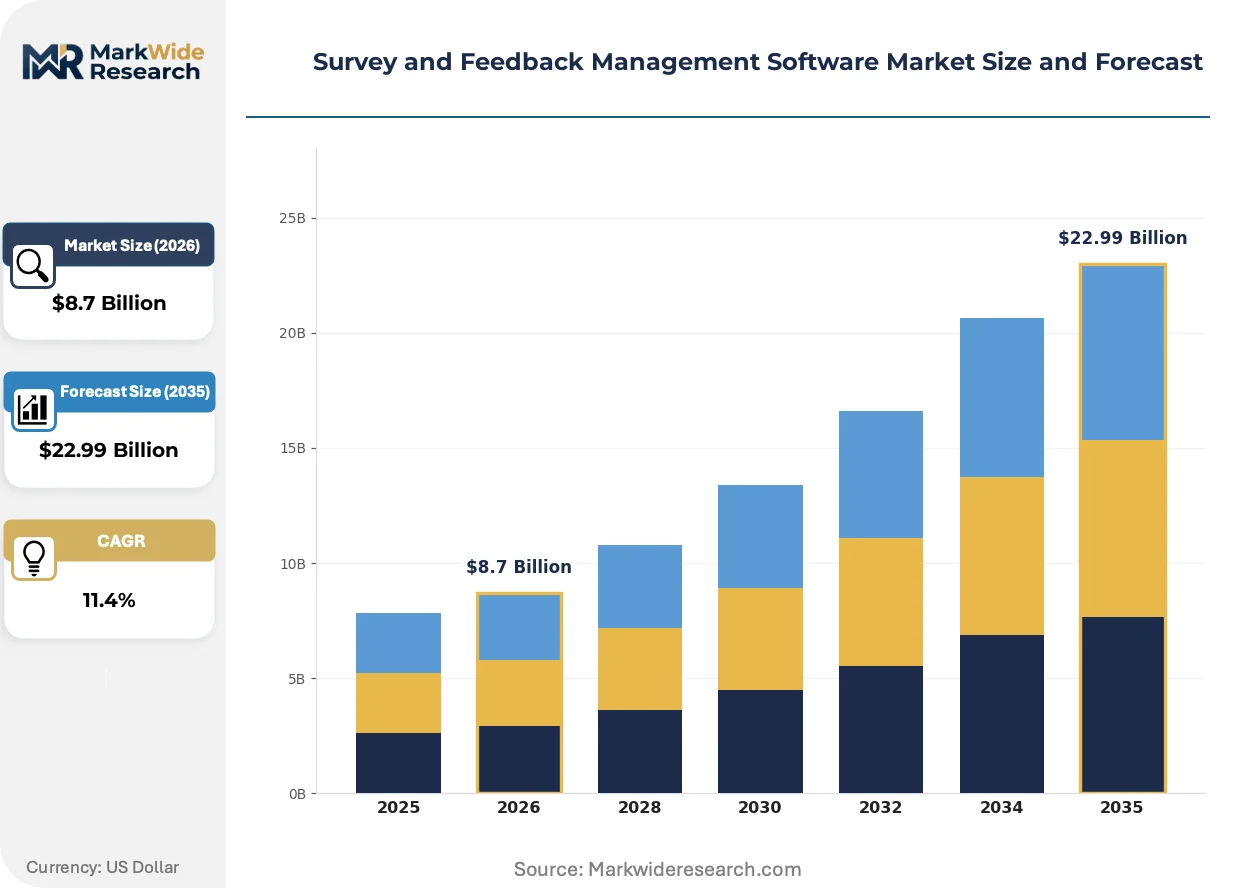
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Cloud-Based, On-Premises, Open Source, Enterprise User Type: Enterprises, SMBs, Educational Institutions, Nonprofits End User: Marketing Teams, HR Departments, Customer Service, Researchers Distribution Channel: Direct Sales, Online Platforms, Resellers, Affiliates |
| Companies Covered | Qualtrics International Inc., SurveyMonkey, Alchemer LLC, Typeform S.L., SurveySparrow, Zoho Corporation, Zonka Feedback, Survicate, Medallia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Survey and Feedback Management Software Market Evolving Landscape
Generative AI is compressing the traditional survey design cycle from days to minutes, while regulatory pressure on algorithmic accountability is reshaping vendor competitive positioning around transparency features rather than raw accuracy metrics.
Multimodal feedback collection is unifying structured survey responses, unstructured social media sentiment, and behavioral telemetry into single-pane analytics. Large enterprises in financial services are piloting these integrated streams for real-time churn prediction. The technology is unifying previously siloed customer experience and employee engagement data architectures, forcing vendors to reposition from point solutions to platform plays.
The EU AI Act's risk-based classification system places automated employee sentiment scoring in the "high-risk" category, triggering conformity assessment requirements before market deployment. Vendors must now document training data provenance and maintain human-in-the-loop override capabilities. German works councils are leveraging these provisions to demand pre-approval rights for pulse survey deployments, slowing enterprise rollout velocity.
Subscription bundling is displacing standalone survey tool procurement as enterprises consolidate vendor relationships. CIOs in the United States are prioritizing experience management suites that embed feedback capabilities within broader SaaS ecosystems. This preference shift favors platforms with pre-built connectors to Workday, SAP SuccessFactors, and ServiceNow over best-of-breed specialists.
Survey and Feedback Management Software Market Segmentation
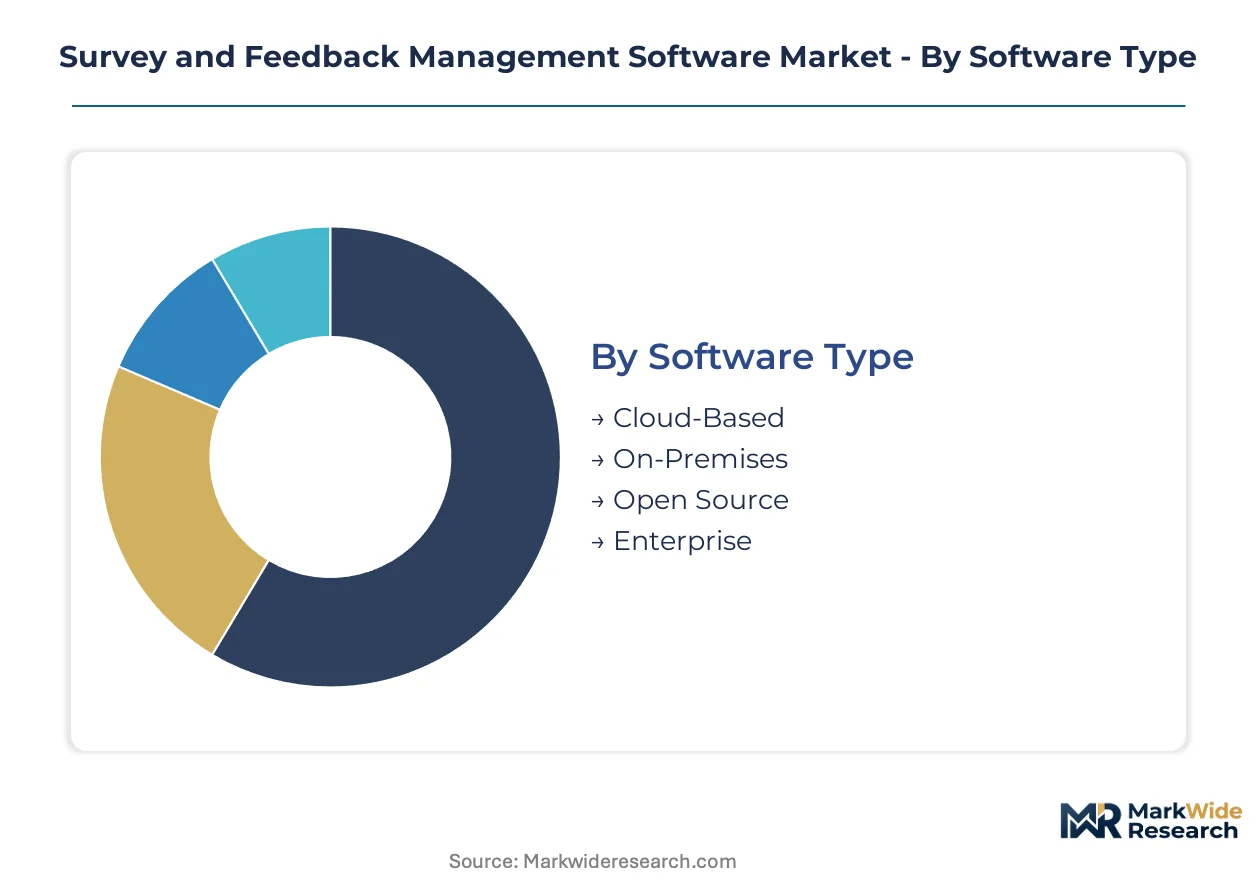
Segmentation in survey and feedback management software reveals how procurement priorities diverge across technical infrastructure preferences, organizational scale, functional use cases, and channel economics. Buyers optimize for fundamentally different value equations—IT control versus deployment velocity, enterprise integration versus departmental autonomy.
Software Type:
Cloud-based platforms command attention from buyers prioritizing subscription flexibility and rapid implementation over capital expenditure cycles.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic feature updates and elastic scaling without infrastructure ownership. Demand concentrates among United States mid-market firms replacing legacy on-premises installations to reduce IT maintenance burdens.
- On-Premises:Single-tenant deployments behind corporate firewalls satisfy data residency mandates in regulated industries. German financial institutions and healthcare operators specify these configurations to satisfy GDPR Article 44 cross-border transfer restrictions.
- Open Source:Self-hosted alternatives like LimeSurvey grant complete code auditability and zero licensing fees. Academic researchers in European universities and privacy-advocacy organizations deploy these tools to eliminate vendor data access.
- Enterprise:Dedicated instance deployments with custom SLAs and premium support tiers serve Fortune 500 procurement requirements. These contracts bundle advanced analytics modules and dedicated customer success management.
Cloud-Based leads volumes today; Open Source is gaining share fastest among privacy-sensitive institutional buyers.
User Type:
Organizational scale determines pricing tolerance, implementation complexity, and feature depth requirements across the buyer base.
- Enterprises:Global deployments spanning tens of thousands of employees demand SSO integration, advanced permission hierarchies, and API ecosystem connectivity. These buyers negotiate multi-year contracts with platform consolidation clauses.
- SMBs:Departments under 500 seats prioritize no-code configuration and immediate deployment without IT dependency. Visual workflow builders and template libraries accelerate adoption among marketing agencies and professional services firms.
- Educational Institutions:Universities and K-12 districts require FERPA-compliant data handling and semester-based pricing flexibility. Research grants often fund specialized academic survey tools with citation management integration.
- Nonprofits:Budget-constrained organizations leverage donor-funded subscriptions and pro bono platform partnerships. These users maximize free-tier allowances and volunteer-administered deployment models.
Enterprises dominate current revenue; SMBs represent the steepest expansion trajectory as self-service tooling matures.
End User:
Functional department objectives shape feature prioritization, from real-time operational response to longitudinal academic rigor.
- Marketing Teams:Campaign attribution and brand tracking modules integrate with CRM workflows to close feedback-to-action loops. These users demand social media listening convergence and influencer sentiment correlation.
- HR Departments:Pulse survey cadences and anonymous whistleblower channels support continuous engagement monitoring. European works councils increasingly mandate pre-approval rights for automated sentiment scoring deployments.
- Customer Service:Post-interaction CSAT triggers and contact center speech analytics unify qualitative and quantitative experience data. Voice-to-text transcription accuracy drives vendor selection in multilingual support environments.
- Researchers:Methodological rigor requirements include quota management, randomization algorithms, and statistical export compatibility. Academic IRB compliance documentation and data retention protocols differentiate procurement criteria.
Customer Service leads deployment volumes today; HR Departments are climbing the fastest as pulse survey adoption displaces annual engagement studies.
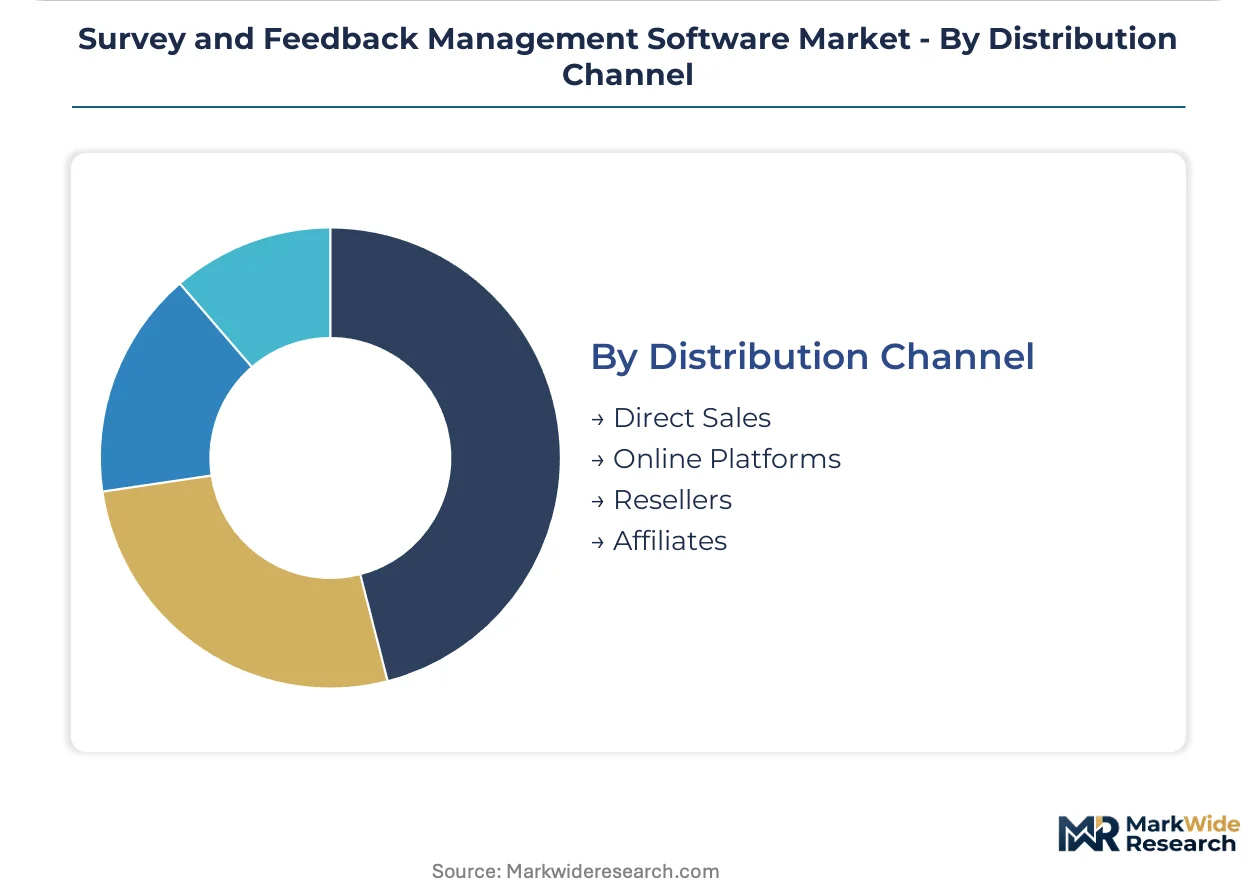
Distribution Channel:
Route-to-market economics determine customer acquisition costs and implementation support depth across the revenue stack.
- Direct Sales:Field teams and inside sales representatives manage complex enterprise procurement cycles with custom security reviews and legal negotiation. These relationships sustain the highest lifetime value through expansion revenue.
- Online Platforms:Self-service marketplaces and vendor websites enable immediate credit-card subscription without sales intervention. Freemium-to-paid conversion mechanics dominate customer acquisition in the sub-50-seat segment.
- Resellers:Systems integrators and regional IT consultants bundle survey tools with broader digital transformation engagements. These partners provide localized implementation support and ongoing administrative services.
- Affiliates:Content publishers and industry influencers earn commission on referred subscriptions through tracked referral codes. Review site placements and comparison engine visibility drive low-touch acquisition for price-sensitive evaluators.
Direct Sales commands revenue concentration today; Online Platforms are expanding most quickly as product-led growth strategies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing vendor development capacity as GDPR Article 44 cross-border transfer restrictions and the EU AI Act's high-risk system classification elevate compliance costs in Europe relative to the United States and India.
United States
Enterprise HR departments in the United States are replacing annual engagement surveys with continuous pulse feedback loops, driving subscription expansion for cloud-native platforms. HIPAA and sectoral state privacy frameworks create compliance complexity for healthcare and multi-state operators. Silicon Valley and Seattle host the densest concentration of AI-native sentiment analytics startups.
Germany
German financial institutions and healthcare operators specify on-premises deployments to satisfy GDPR Article 44 cross-border transfer restrictions. Works councils leverage EU AI Act provisions to demand pre-approval rights for automated sentiment scoring, slowing enterprise rollout velocity. Berlin and Munich anchor the largest self-hosted open-source adoption clusters among privacy-advocacy organizations.
India
Indian enterprises prioritize real-time employee and customer sentiment analytics as digital transformation accelerates across IT services and banking sectors. The RBI and SEBI impose data localization requirements on financial institutions processing stakeholder feedback. Bengaluru and Hyderabad concentrate vendor delivery centers and NLP engineering talent for Indic language model development.
United Kingdom
Post-Brexit divergence from EU GDPR enforcement patterns creates regulatory uncertainty for vendors maintaining unified European data architectures. The Financial Conduct Authority scrutinizes automated decision-making in customer experience applications. London's fintech corridor drives demand for embedded API survey widgets integrated into Salesforce and ServiceNow workflows.
Japan
Japanese enterprises adopt multimodal feedback collection unifying structured surveys with contact center speech analytics for real-time churn prediction. METI guidelines on AI governance emphasize explainable sentiment classification outputs. Tokyo and Osaka host the regional headquarters of global experience management platforms serving Fortune 500 manufacturing accounts.
Survey and Feedback Management Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded API distribution and no-code configuration interfaces. The vendor base stratifies across three maturity tiers: cloud-native platforms with vertical integration across experience management, self-serve specialists with freemium-to-paid conversion mechanics, and AI-powered text analytics specialists for Fortune 500 accounts. Consolidation pressure intensifies as subscription bundling displaces standalone survey tool procurement and CIOs prioritize experience management suites with pre-built connectors to Workday, SAP SuccessFactors, and ServiceNow.
Within the vertical integration tier, Qualtrics International Inc. exemplifies platform consolidation strategies spanning customer and employee experience domains. SurveyMonkey anchors the self-serve segment with conversion-optimized onboarding flows. Medallia occupies a position among AI-native specialists targeting enterprise accounts with unified behavioral telemetry and survey response analytics.
| Leading Market Players |
|---|
| Qualtrics International Inc. |
| SurveyMonkey |
| Alchemer LLC |
| Typeform S.L. |
| SurveySparrow |
| Zoho Corporation |
| Zonka Feedback |
| Survicate |
| Medallia |
| Others |
Value Network & Pricing Analysis
Enterprise-to-SMB tier divergence in deployment complexity manifests in both subscription pricing and cloud infrastructure sourcing strategies. Premium dedicated instances command custom SLAs and regional data residency, while multi-tenant SaaS tiers leverage pooled infrastructure to compress per-seat costs.
Pricing Analysis
Direct-to-enterprise field sales teams capture 40-60 point gross margins through multi-year platform consolidation contracts. Three-tier pricing structure across premium, standard, and economy levels differentiates by SSO integration depth, API call volume, and human-in-the-loop audit capabilities. Cost compression in the self-serve tier intensifies as freemium conversion mechanics drive customer acquisition economics. SMB marketing agencies exhibit highest price sensitivity; Fortune 500 CHROs demonstrate lowest sensitivity due to bundled experience management procurement.
Supply Chain Analysis
India's data localization mandates under RBI and SEBI guidelines are reshaping vendor cloud region provisioning and engineering center placement. Software development capacity concentrates in India, the United States, and Germany for NLP model training and compliance engineering. Proprietary large language model development rests on GPU compute clusters, open-source framework dependencies, and specialized prompt engineering talent pools. Single-source vulnerability runs through hyperscaler cloud infrastructure concentration. Distribution runs through embedded API partnerships with Salesforce and ServiceNow ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications around explainable AI and GDPR Article 22 compliance are displacing raw accuracy metrics as procurement criteria, favoring vendors with documented training provenance and human oversight architectures.
For Market Incumbents: Hedge against open-source substitution in European privacy-sensitive institutions by accelerating region-specific data residency deployments and pre-built connector ecosystems to Workday and SAP SuccessFactors. Certification investment in EU AI Act conformity assessment procedures protects enterprise renewal rates against emerging AI-native challengers. For New Entrants and Emerging Players: Mid-market HR departments in India represent the most penetrable buyer archetype, underserved by legacy annual survey tools and hungry for real-time pulse capabilities. Voice-to-text convergence for Indic languages offers technical differentiation in a market where NLP accuracy gaps constrain incumbent penetration. Channel partnership with regional systems integrators accelerates localized implementation support without direct sales overhead. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-powered text analytics specialists possessing unified behavioral telemetry and survey response architectures. Long-term viability in this market hinges on platform consolidation momentum rather than point solution retention. Watch for EU AI Act enforcement velocity in Germany as the signal indicating whether explainable AI capabilities become table stakes or sustainable competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Human-in-the-loop audit capabilities satisfy GDPR Article 22 mandates in German enterprise accounts. |
| Embedded API Distribution Partnership | Native Salesforce and ServiceNow integration captures feedback at transaction touchpoints without platform switching. |
| Indic Language NLP Development | Bengaluru and Hyderabad engineering centers address accuracy gaps constraining penetration in Indian regional markets. |
| Regional Data Residency Expansion | Separate EU and US infrastructure instances respond to Schrems II invalidation of Privacy Shield mechanisms. |
| Experience Management Suite Consolidation | Pre-built connectors to Workday and SAP SuccessFactors align with CIO preference for bundled vendor relationships. |
Research Methodology
Direct dialogue with CTOs, HR technology procurement officers, platform integration specialists, and European works council representatives grounded qualitative findings in operational reality. Secondary validation drew from SEC SaaS company filings, hyperscaler regional capex disclosures, EU regulatory implementation guidance, and App Annie mobile deployment analytics. Bottom-up subscription data triangulated against top-down enterprise IT spend surveys to anchor market sizing.
Segment-level revenue projections across cloud-based, on-premises, open-source, and enterprise deployment models informed the analytical framework over the projection horizon. Organization size, functional use case, and regional adoption pattern dimensions shaped demand elasticity assumptions. CAGRs derived from historical subscription growth trajectories, net revenue retention benchmarks, and replacement cycle acceleration in HR technology stacks.
Underlying measurement precision varies by segment; cloud-based SaaS volumes carry tighter precision than self-hosted open-source deployments where usage telemetry remains opaque. Forecasts reflect assumptions around regulatory enforcement velocity, AI Act implementation timelines, and enterprise consolidation preferences that could shift materially. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Invoice Processing Software Market
Software & Services
Ad Creation Software Market
Software & Services
Petcare Software Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Customer Self-Service Software Market
Software & Services
Global Voting Software Market
Software & Services
France HR Payroll Software Market
Software & Services
Train Reservation Software Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
Automation Test Software Market
Software & Services
Product Analytics Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Global Award Management Software Market
Software & Services
Lab Automation Software Market
Software & Services
Laboratory Management Software Market
Software & Services
Architectural Rendering Software Market