
 Global Waterproofing Chemicals Market | 2026-2036
Global Waterproofing Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waterproofing Chemicals Market Intelligence
Distribution through large-scale building material suppliers is tilting toward more specialized, project-specific channels managed by contractors. Sika AG leverages its strong relationships with major global construction firms and project specifiers. BASF SE competes on the basis of its broad chemical portfolio and deep R&D in liquid applied coatings. Meanwhile, MAPEI S.p.A. sustains a strong market position in cementitious and specialized repair-focused product lines.
Waterproofing chemicals are specialized formulations designed to create an impermeable barrier against water ingress in building structures. These materials, often based on polymers like polyurethane or acrylics, or bituminous compounds, prevent moisture damage and enhance structural longevity. Bituminous membranes remain a mature and high-volume product type, particularly in roofing applications. Liquid applied coatings, however, are seeing rapid adoption for their flexibility in complex geometries for foundation protection and renovation projects.
Regulatory frameworks significantly influence product formulation and market access. The EU's REACH regulation governs chemical substance use, while EPA standards in the United States limit volatile organic compound (VOC) content in coatings. In China, national GB standards dictate performance requirements for construction materials. Suppliers must now navigate a complex decision matrix balancing raw material costs, long-term durability performance, and evolving sustainability mandates.
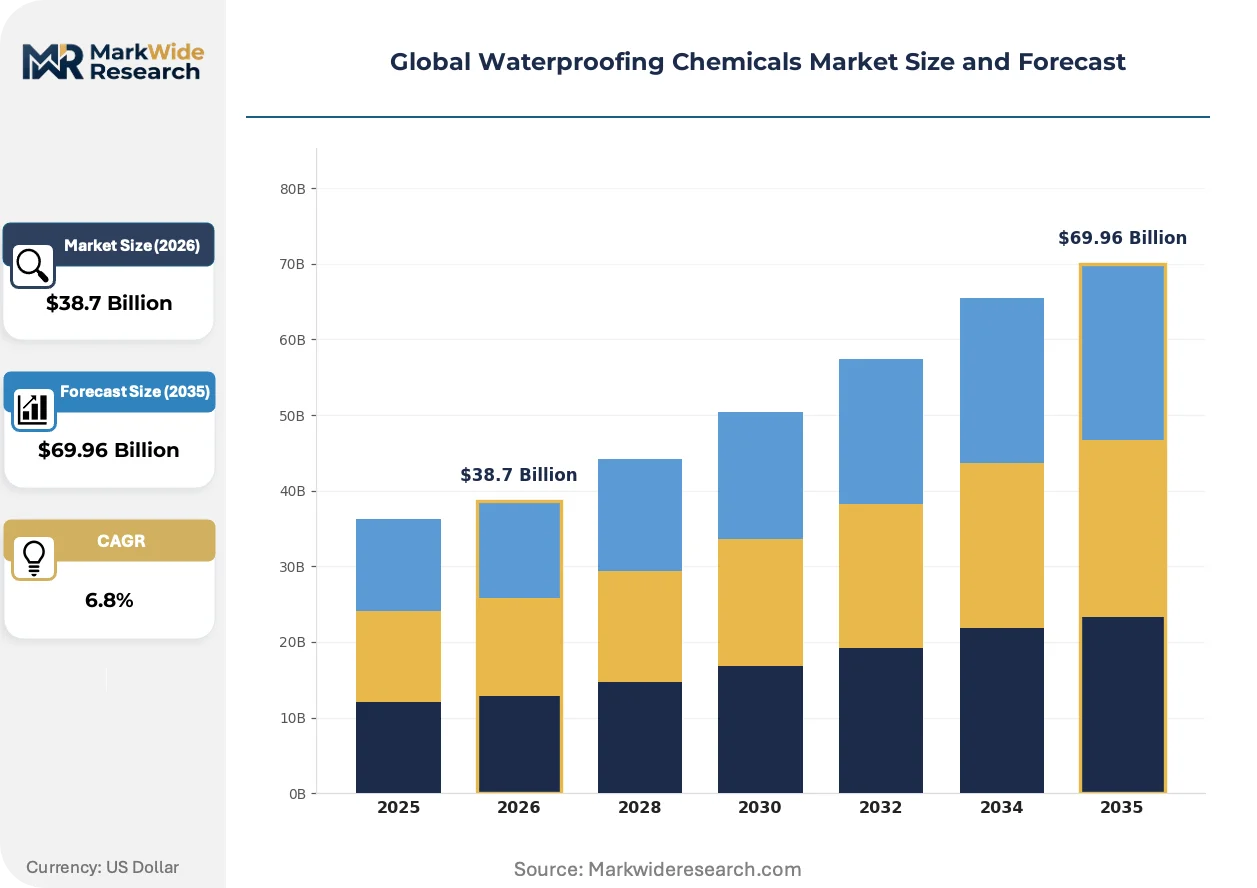
Market Dynamics
The imperative for enhanced structural longevity and sustainable construction practices is the central force shaping the waterproofing chemicals market. This is driven by regulatory pressures for environmentally sound materials, such as the EU Green Deal, and massive infrastructure development in Asia.
Growth Catalysts
- Infrastructure Investment:Demand from large-scale civil engineering projects, including tunnels, bridges, and sub-structural foundations in China and India, provides a consistent volume driver for high-performance waterproofing systems.
- Renovation and Repair:The aging building stock in North America and Europe necessitates extensive refurbishment, creating demand for liquid-applied coatings that can be easily applied over existing, complex substrates.
- Stringent Building Codes:Evolving building codes and standards focused on energy efficiency and resilience against extreme weather are mandating more robust and durable waterproofing solutions for roofing and building envelopes.
Market Restraints
- Raw Material Price Volatility:The market's heavy reliance on petrochemical derivatives like bitumen and various polymers links production costs directly to volatile crude oil and natural gas prices, impacting margin stability.
- Substitution from Admixtures:The use of crystalline waterproofing admixtures mixed directly into concrete during batching presents a substitution threat, potentially eliminating the need for topical membranes in some new construction.
- Application Skill Gap:The effective application of advanced systems like polyurethane or polyurea liquid coatings requires specialized training and equipment, and a shortage of skilled labor can hinder adoption rates.
Strategic Opportunities
- Bio-Based Formulations:Development of waterproofing chemicals derived from renewable resources like plant oils offers a path to meet green building standards and appeal to specifiers seeking sustainable materials.
- Cool Roof Coatings:Formulating highly reflective, light-colored liquid membranes provides an opportunity to address urban heat island regulations and energy efficiency mandates for commercial buildings.
- Below-Grade Structure Protection:Expanding product lines for specialized applications in deep foundations, basements, and tunnels in dense urban environments represents a significant growth area.
Industry Challenges
- Global Standards Harmonization:A lack of uniform international standards for testing long-term durability and performance makes it difficult for specifiers to compare products across different regions and manufacturers effectively.
- Complex Regulatory Navigation:Suppliers must manage a difficult matrix of chemical regulations, including REACH in Europe and VOC content limits set by the EPA in the United States, which increases compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waterproofing Chemicals Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bituminous Membranes, Liquid Applied Coatings, Cementitious Coatings, Polyurethane, Acrylics, EPDM Application: Roofing, Foundation Protection, Tunnels, Swimming Pools, Balconies, Underground Structures End User: Construction Companies, Contractors, Infrastructure Developers, Residential Building Owners, Commercial Developers, Institutional Facilities Deployment: New Construction, Renovation, Maintenance, Waterproofing Upgrades, Industrial Projects, Commercial Projects |
| Companies Covered | MAPEI S.p.A., Dow, Sika AG, Wacker Chemie AG, DuPont, BASF SE, Carlisle Companies Inc., Saint-Gobain, Pidilite Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waterproofing Chemicals Market Strategic Shifts & Innovations
Material science advancements are converging with a demand for simplified application and whole-system performance warranties. This is shifting the focus from individual product sales toward integrated solutions that guarantee long-term water tightness for specific structural components like roofs or foundations.
Polyurethane-bitumen hybrid systems combine the elasticity of polyurethanes with the cost-effectiveness and adhesive properties of bitumen. These formulations are gaining favor in commercial roofing and large-scale podium deck projects where a balance of performance and budget is essential. This technology is hybridizing the market by creating a performance tier that bridges the gap between traditional modified bitumen sheets and premium pure-polyurethane liquid membranes.
China's national GB standards for construction materials are becoming increasingly stringent, dictating higher performance benchmarks for tensile strength, elongation, and water impermeability. This regulatory tightening is forcing both domestic and international suppliers to reformulate products specifically for the Chinese market. It particularly affects bituminous membranes and cementitious waterproofing, pushing manufacturers to upgrade quality or risk losing market access.
A notable behavioral shift involves large asset owners and facility managers specifying waterproofing systems based on total cost of ownership rather than initial installation price. This disrupts the traditional low-bid model by prioritizing durability, maintenance cycles, and the availability of long-term warranties from the material supplier. This trend is most visible in the data center, hospital, and commercial real estate sectors in North America.
Global Waterproofing Chemicals Market Segmentation
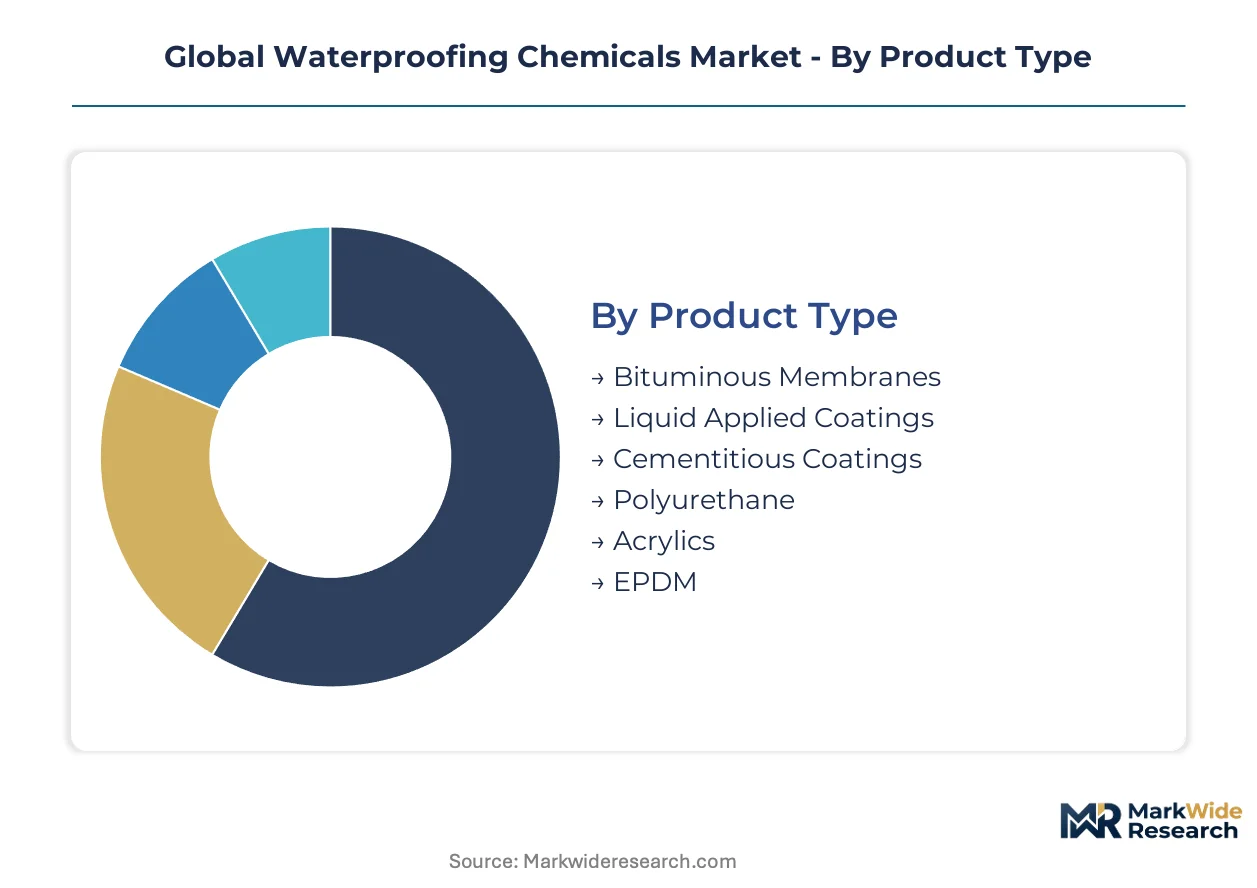
Understanding the segmentation of the global waterproofing chemicals market is crucial for discerning demand patterns and material preferences across diverse applications. This analysis highlights how product innovation, application specifics, and end-user requirements shape the competitive landscape and drive market evolution.
Product Type:
The product type segment spans mature, high-volume materials and rapidly evolving, specialized formulations.
- Bituminous Membranes:These materials, derived from petroleum, remain a foundational product type, extensively used for their cost-effectiveness and proven performance in large-scale roofing projects across Asia and Europe.
- Liquid Applied Coatings:Composed of polymers like polyurethane or acrylics, these coatings offer seamless application and flexibility, seeing rapid adoption for complex geometries in foundation protection and renovation projects in North America.
- Cementitious Coatings:These are mineral-based formulations, widely adopted for their breathability and ease of application in wet areas like bathrooms and basements, particularly in residential construction.
- Polyurethane:Known for its high elasticity and durability, polyurethane systems are specified for critical infrastructure such as bridges and tunnels where structural movement is anticipated.
- Acrylics:Acrylic-based waterproofing solutions provide excellent UV resistance and color stability, making them suitable for exposed applications like rooftops and facades in various climate zones.
- EPDM:Ethylene Propylene Diene Monomer (EPDM) is a synthetic rubber membrane valued for its long-term weather resistance and flexibility, commonly used in flat roofing systems in commercial buildings.
Bituminous Membranes handle the majority of throughput; Liquid Applied Coatings are the fastest mover on share.
Application:
Waterproofing chemicals are deployed across a diverse range of construction applications, each presenting distinct performance requirements.
- Roofing:This application demands materials with high UV resistance and durability to withstand weather cycles, consistently driving significant material demand across commercial and residential sectors.
- Foundation Protection:Protecting below-grade structures from water ingress is critical for structural integrity, with demand driven by large-scale civil engineering projects in China and India.
- Tunnels:Specialized systems are required for tunnels to manage hydrostatic pressure and provide long-term watertightness, often utilizing highly flexible and durable liquid-applied membranes.
- Swimming Pools:This application necessitates chemical-resistant and flexible waterproofing layers to prevent leaks and ensure longevity in both residential and public facilities.
- Balconies:Exposed to weather and foot traffic, balconies require durable and aesthetically pleasing waterproofing solutions that integrate well with architectural finishes.
- Underground Structures:This category encompasses basements, parking garages, and subway systems, requiring robust waterproofing to manage constant moisture exposure and structural movement.
Roofing applications consistently drive significant material demand; underground structures represent a high-growth segment for advanced systems.
End User:
End-user segmentation reveals distinct purchasing behaviors and project scales influencing material specification and volume.
- Construction Companies:These entities procure a broad spectrum of waterproofing chemicals for diverse project types, from residential builds to large commercial complexes, often influencing product selection based on project specifications.
- Contractors:Specialized waterproofing contractors focus on the application of specific systems, often influencing material choice through their expertise and relationships with material suppliers.
- Infrastructure Developers:These developers drive demand for high-performance, durable waterproofing systems for large-scale public works like bridges, dams, and transportation networks in countries like India.
- Residential Building Owners:This segment typically focuses on cost-effective and easy-to-apply solutions for home renovation and maintenance, often through retail channels or local contractors.
- Commercial Developers:Developers of office buildings, retail spaces, and hotels prioritize long-term durability and warranties, often specifying premium waterproofing systems to protect their assets.
- Institutional Facilities:Hospitals, schools, and government buildings require highly reliable and often environmentally compliant waterproofing solutions, driven by stringent building codes and longevity requirements.
Infrastructure Developers drive demand for specialized, high-performance systems, while Construction Companies influence broad product adoption.
Deployment:
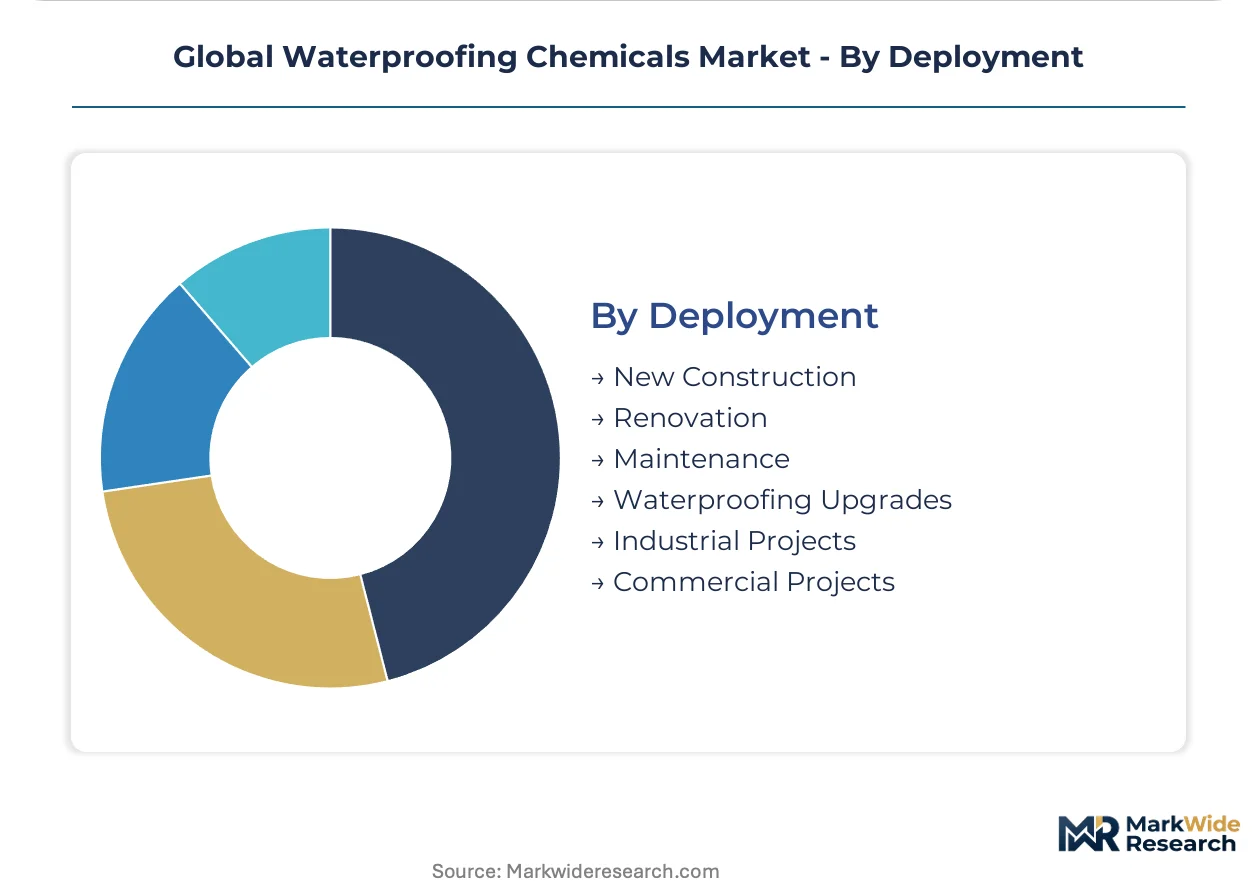
Deployment categorizes waterproofing chemical use based on project lifecycle stages, from initial build to long-term asset management.
- New Construction:This segment represents a consistent volume driver for foundational waterproofing, including membranes for roofs and foundations in expanding urban centers.
- Renovation:The refurbishment of aging building stock in North America and Europe creates substantial demand for flexible, liquid-applied coatings that can be applied over existing substrates.
- Maintenance:Routine upkeep and minor repairs of existing structures require accessible and quick-curing waterproofing solutions to address localized water ingress issues.
- Waterproofing Upgrades:This involves enhancing existing waterproofing systems to meet new performance standards or extend asset life, often driven by evolving building codes or climate resilience needs.
- Industrial Projects:Specialized waterproofing is essential for industrial facilities like chemical plants or power stations, requiring resistance to harsh environments and specific chemical exposures.
- Commercial Projects:This segment includes office buildings, retail centers, and hotels, where waterproofing solutions must balance performance, aesthetics, and long-term durability for high-value assets.
New Construction remains a foundational demand source; Renovation projects are expanding rapidly due to aging infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The development of extensive underground transportation networks and critical utility infrastructure globally underpins the diverse regional demand for waterproofing chemicals. These projects necessitate high-performance materials to ensure structural integrity and longevity. Regulatory frameworks and climate considerations further differentiate product adoption across continents.
China
Large-scale civil engineering projects, including extensive tunnel systems and sub-structural foundations, drive substantial demand in China. The national GB standards for construction materials are becoming more stringent, dictating higher performance benchmarks for waterproofing solutions. Manufacturers in the Yangtze River Delta region are actively reformulating products to meet these evolving quality requirements.
India
Infrastructure developers in India generate consistent demand for high-performance waterproofing systems in bridges and dams. Evolving national building codes increasingly mandate robust solutions to enhance structural resilience against monsoons. Major urban centers like Mumbai and Delhi are experiencing significant construction activity requiring advanced waterproofing applications.
United States
Extensive refurbishment of aging building stock and new commercial developments necessitate advanced waterproofing in the United States. EPA standards limit volatile organic compound (VOC) content in coatings, influencing product formulation and market access. Major commercial real estate hubs, including New York and Los Angeles, prioritize long-term durability and warranties for critical assets.
Germany
Sustainable construction practices and the imperative for structural longevity drive demand for specialized waterproofing in Germany. The EU Green Deal and REACH regulation influence product formulations towards environmentally friendly and durable solutions. Chemical manufacturers in Bavaria and North Rhine-Westphalia lead innovation in bio-based and low-VOC waterproofing systems.
Japan
Seismic resilience and ongoing urban redevelopment projects create specific waterproofing needs across Japan. JIS standards dictate stringent performance requirements for construction materials, including those designed for water impermeability. Major metropolitan areas like Tokyo and Osaka consistently deploy advanced liquid-applied coatings for high-rise building envelopes.
Global Waterproofing Chemicals Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing large multinational chemical conglomerates and specialized regional manufacturers. These players differentiate through broad chemical portfolios, specialized product lines, and integrated solution offerings, creating distinct strategic archetypes. Dominant competitive moves involve continuous portfolio diversification into sustainable formulations and strategic partnerships with construction firms. Capacity expansion in high-growth geographies also remains a key focus for many participants.
Diversified chemical giants, such as BASF SE, exemplify companies leveraging extensive R&D capabilities and a broad chemical portfolio across various construction applications. Sika AG, a Swiss AG, represents a leading specialized waterproofing solutions provider, known for its strong relationships with global construction firms and project specifiers. Meanwhile, MAPEI S.p.A., an Italian S.p.A., anchors the market for cementitious and specialized repair-focused product lines, maintaining a strong position in specific material segments. These entities collectively highlight the varied approaches to market penetration and product development within the waterproofing chemicals sector.
| Leading Market Players |
|---|
| MAPEI S.p.A. |
| Dow |
| Sika AG |
| Wacker Chemie AG |
| DuPont |
| BASF SE |
| Carlisle Companies Inc. |
| Saint-Gobain |
| Pidilite Industries Ltd. |
Cost & Logistics Intelligence
Bituminous membrane overcapacity in Asia, driven by high-volume production, influences supplier behavior by encouraging aggressive pricing strategies to maintain throughput. This utilization pressure directly impacts pricing posture across the broader waterproofing chemicals market.
Pricing Analysis
A tiered pricing structure across premium, standard, and economy levels characterizes the waterproofing chemicals market. Price differentiation stems from product performance, brand reputation, and the volume scale of large civil engineering projects. Pricing softness for commodity products reflects intense competition and raw material price volatility, particularly for petrochemical derivatives. Residential building owners exhibit the highest price sensitivity, while infrastructure developers prioritize long-term durability and system warranties.
Supply Chain Analysis
Raw material price volatility, particularly for petrochemical derivatives like bitumen and various polymers, represents a significant supply chain risk. Production of these inputs concentrates in major oil and gas-producing regions, influencing global supply. The distribution model primarily runs through large-scale building material suppliers, increasingly tilting towards specialized project channels managed by contractors. China and India anchor a significant portion of material consumption, creating regional supply dependencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The waterproofing chemicals market is experiencing a significant shift in buyer power, driven by large asset owners and facility managers prioritizing total cost of ownership over initial installation price. This behavioral change necessitates a re-evaluation of supplier strategies.
For Market Incumbents: Insulate core market share by investing in bio-based formulations to meet evolving sustainability mandates and regulatory pressures like the EU Green Deal. Deepen strategic partnerships with major global construction firms, offering integrated solutions and long-term warranties to counter substitution threats from admixtures. Expand R&D into advanced liquid-applied coatings, addressing the application skill gap through simplified systems and training programs. Capacity additions in high-growth regions like China and India further secure market position.
For New Entrants and Emerging Players: Build out specialized product lines targeting the rapidly expanding renovation and repair segment in North America and Europe, focusing on flexible liquid-applied coatings. Penetrate the below-grade structure protection market in urban environments by offering advanced, high-performance systems for basements and tunnels. Leverage a sustainability-focused go-to-market angle with bio-based formulations, appealing to green building standards and specifiers. Offer comprehensive application training to overcome the existing skill gap.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized waterproofing contractors offering long-term maintenance contracts and system warranties. The market's long-term viability hinges on the imperative for enhanced structural longevity and sustainable construction practices. Identify acquisition targets among manufacturers specializing in advanced liquid-applied coatings or bio-based formulations with strong R&D capabilities. The signal to watch is the continued tightening of national building codes and environmental regulations, driving demand for premium, compliant solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding production facilities in China and India addresses infrastructure demand. |
| Bio-Based Formulation R&D | Developing renewable material solutions meets green building standards. |
| Strategic Partnerships | Collaborating with global construction firms secures project specifications. |
| Product Diversification | Expanding liquid-applied coatings portfolio captures renovation market share. |
| Application Training Programs | Providing skilled labor training supports adoption of advanced systems. |
Research Approach
Operator-level perspectives from technical R&D directors, procurement leads at construction companies, specialized waterproofing contractors, and infrastructure developers anchored the qualitative base. This primary intelligence was validated against extensive secondary research, including regulatory filings from EPA and REACH, construction industry reports, and material science journals. A rigorous bottom-up and top-down triangulation process ensured data consistency and market sizing accuracy.
Scenario-bracketing across various macroeconomic assumptions informed the quantitative forecast framework over the projection horizon. The analysis modeled segmentation dimensions including product type, application, end user, deployment stage, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth patterns and projected demand drivers. Key forecast inputs included global infrastructure investment levels and evolving building code stringency.
Stress conditions across raw material price volatility and geopolitical instability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory stability and construction activity, acknowledging potential revisions from rapid technological substitution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Natural Fatty Alcohols Market
Chemicals
Diphenylamine (DPA) Market
Chemicals
Linear Mercaptans Market
Chemicals
Ferric Phosphate Market
Chemicals
Ferric Oxide Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Allyl Alcohol Market
Chemicals
Hydroxyzine Imine Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Solder Flux Market
Chemicals
Amine Oxide Market
Chemicals
Naturally Derived Fatty Alcohol Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
South America Construction Chemicals Market
Chemicals
Electronic Grade Hydrofluoric Acid Market