
 Diphenylamine (DPA) Market | 2026-2036
Diphenylamine (DPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Diphenylamine (DPA) Market Outlook
Market Dynamics
The capability gap between integrated aniline producers and merchant DPA specialists is reorganizing competitive tiers in the antioxidant supply chain. BASF SE leverages backward integration into nitrobenzene and aniline feedstocks to sustain margin resilience against volatile raw material costs. Eastman Chemical Company anchors its position through rubber additive formulation expertise and long-term offtake agreements with tire manufacturers. LANXESS AG competes by specializing in high-purity grades that meet pharmaceutical and agrochemical specifications, extending its reach beyond commodity rubber antioxidants.
Product Landscape
Diphenylamine is a secondary aromatic amine with the chemical formula (C6H5)2NH, produced primarily through the acid-catalyzed condensation of aniline, and functions industrially as a versatile antioxidant and stabilizer across rubber, lubricants, and propellant applications. Industrial Grade DPA dominates volume consumption as tire manufacturers specify this category for rubber processing antioxidants, while Pharmaceutical Grade commands premium positioning due to stringent impurity controls demanded by drug intermediate applications. The Agricultural Grade segment is gaining traction as DPA derivatives see expanded deployment in crop protection formulations, though Coatings applications remain comparatively mature with slower formulation change cycles.
Regulatory Environment
REACH regulations in Europe impose strict limits on secondary amine content and nitrosamine formation potential, compelling reformulation investments across the value chain. The EPA governs DPA handling and discharge thresholds in the United States, while China's MEE enforces emission controls on aniline-based chemical manufacturing clusters. Stakeholders must monitor evolving purity standards and substitution risks from phenolic antioxidant alternatives as regulatory scrutiny on amine-based stabilizers intensifies.
Market Dynamics
REACH restrictions on naphthylamine contaminants are forcing European supply chains to absorb costly purification investments while Chinese tire manufacturers accelerate DPA offtake to serve domestic production expansion.
Growth Catalysts
- REACH purity mandates:European ECHA enforcement tightens impurity specifications for rubber antioxidants, compelling reformulation upgrades across tire supply chains.
- Tire manufacturing expansion:Chinese domestic tire production consumes substantial antioxidant volumes as domestic vehicle sales sustain rubber chemical demand.
- Aniline feedstock availability:Integrated nitrobenzene-aniline production clusters in Asia-Pacific secure captive DPA precursor supply for regional antioxidant manufacturers.
Market Restraints
- Aniline price volatility:Benzene feedstock fluctuations transmit directly to DPA production economics, compressing merchant producer margins during crude oil instability.
- Phenolic antioxidant substitution:Non-amine stabilizers displace DPA in select lubricant applications where nitrosamine formation concerns drive specification changes.
- Specialized purification capex:Pharmaceutical-grade DPA requires multi-stage crystallization and solvent recovery systems that constrain capacity expansion for smaller producers.
Strategic Opportunities
- Agrochemical derivative expansion:DPA intermediates for fungicide and herbicide synthesis offer premium pricing outside commodity rubber antioxidant markets.
- India manufacturing localization:Domestic tire production growth under PLI scheme incentives creates import substitution potential for regional DPA supply.
- Propellant stabilizer qualification:Defense and aerospace specification approvals for high-purity grades open insulated demand channels with long contract durations.
Industry Challenges
- Specialized chemical engineering talent:Aromatic amine process safety and nitration expertise scarcity constrains operational expansion for new market entrants.
- Cross-regulatory compliance synchronization:Simultaneous EPA discharge thresholds, REACH substance registration, and MEE emission controls fragment quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diphenylamine (DPA) Market |
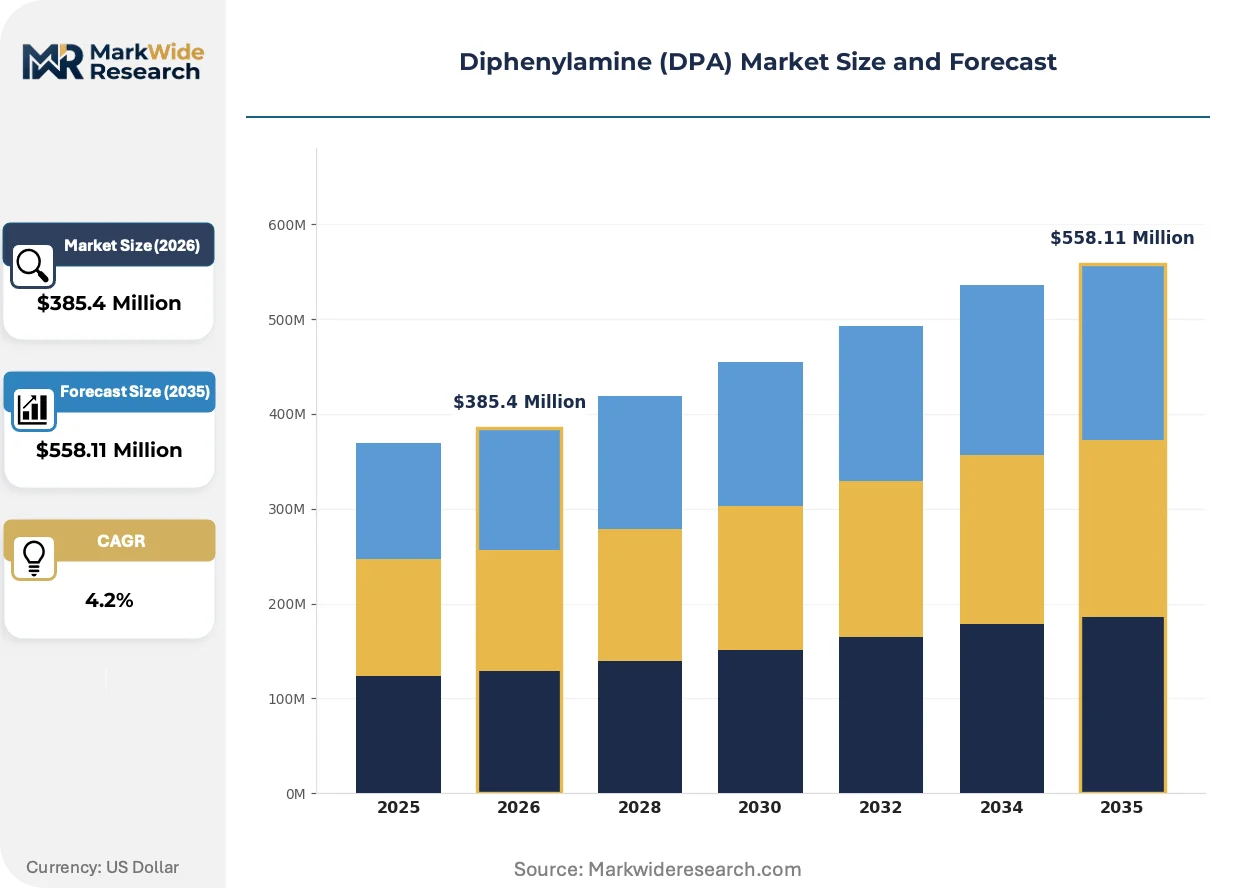
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Agricultural Grade Application: Rubber Processing, Agriculture, Coatings, Pharmaceuticals End User: Manufacturers, Distributors, Retailers, Consumers Distribution Channel: Online, Direct Sales, Wholesale, Retail |
| Companies Covered | Huntsman International LLC, Merck KGaA, BASF SE, Duslo a.s., SONGWON Industrial Co., Ltd., LANXESS AG, Arkema, Seiko Chemical Co., Ltd., Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diphenylamine (DPA) Market Strategic Shifts
Continuous processing technology and advanced purification systems are compressing production economics while regulatory chemistry demands reshape specification hierarchies across end-use verticals.
Membrane filtration systems for aniline recovery and DPA purification are miniaturizing plant footprints while maintaining pharmaceutical-grade output specifications. Specialty chemical producers in Germany and Switzerland adopt these compact units to retrofit existing facilities without greenfield expansion. The technology is miniaturizing capital barriers for high-purity grade entry, enabling mid-scale producers to contest LANXESS and BASF positions in pharmaceutical and agrochemical segments.
ECHA REACH Annex XVII restrictions on secondary amine content in consumer goods are compelling rubber formulators to document nitrosamine formation potential across tire and industrial rubber applications. The regulation forces antioxidant blend redesigns and supplier qualification audits throughout European automotive supply chains. Tire manufacturers specify certified low-nitrosamine DPA grades, creating specification divergence between European and other regional markets.
Long-term offtake contracting is displacing spot market purchasing among tier-one tire manufacturers seeking supply security amid aniline feedstock volatility. Bridgestone, Michelin, and Goodyear procurement teams negotiate multi-year antioxidant supply agreements with fixed-volume escalators. This concentration is most visible in China and Southeast Asia where new tire plant construction outpaces regional DPA capacity additions.
Diphenylamine (DPA) Market Segmentation
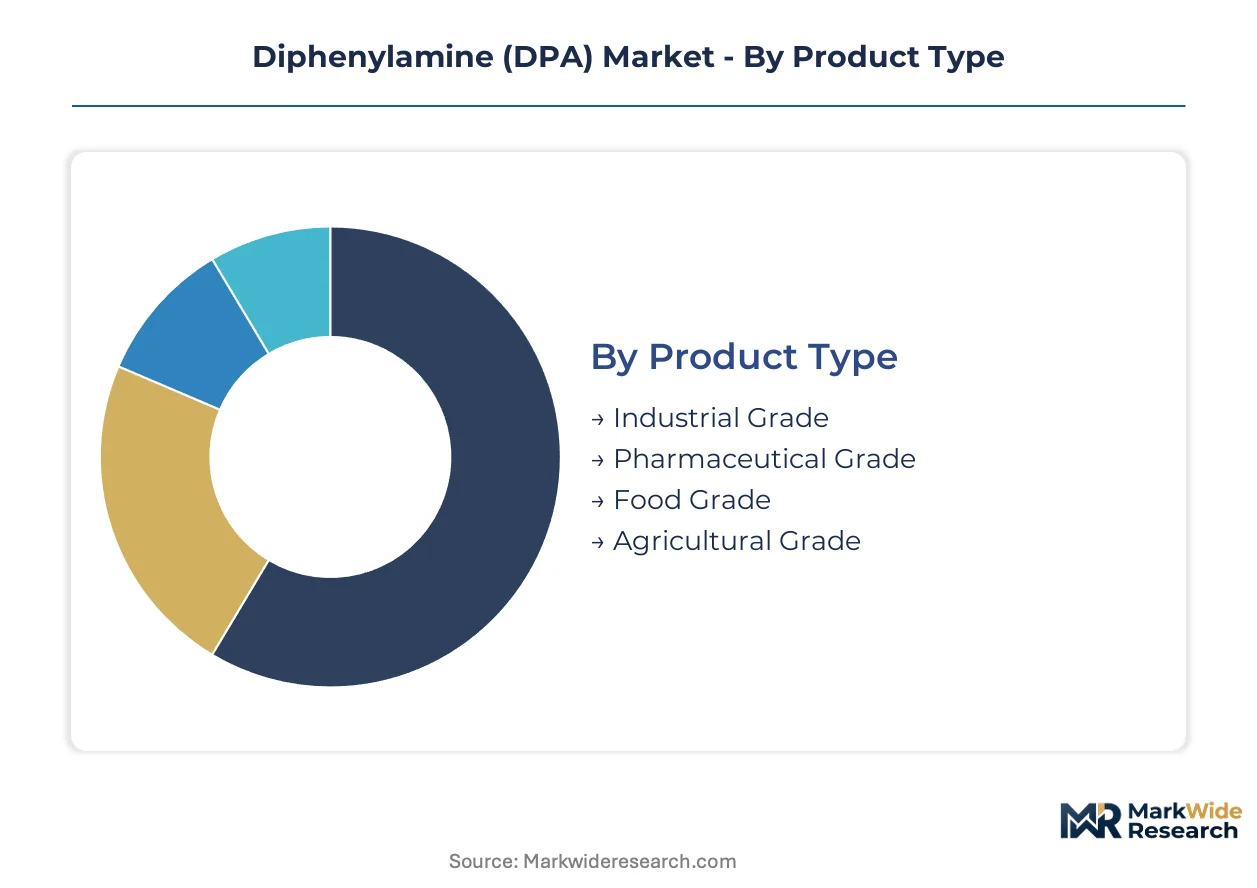
DPA grade specifications diverge sharply across end-use verticals, with rubber antioxidants commanding volume and pharmaceutical intermediates extracting premium margins. Segmentation discipline separates commodity producers from specialty chemical specialists competing on purity certification rather than scale economics.
Product Type:
Margin pools concentrate in certified high-purity grades where regulatory compliance creates pricing power, while industrial volumes sustain plant utilization.
- Industrial Grade:Standard aromatic amine purity levels serve tire manufacturing and general rubber compounding. Chinese domestic tire producers absorb the majority of global industrial grade offtake as domestic vehicle production sustains antioxidant demand. Industrial Grade holds the largest share; momentum sits with Agricultural Grade.
- Pharmaceutical Grade:Multi-stage crystallization achieves impurity profiles below 50ppm for drug intermediate applications. REACH naphthylamine limits and FDA intermediate specifications compel dedicated purification investments that smaller producers cannot replicate.
- Food Grade:Stringent migration limits and FSSAI packaging approvals constrain viable supply to a handful of certified producers with dedicated equipment trains.
- Agricultural Grade:Expanding fungicide and herbicide intermediate demand from Bayer Crop Science and Syngenta formulation networks drives specification evolution toward higher active content.
Industrial Grade anchors volume economics; Pharmaceutical Grade commands the steepest expansion trajectory in margin terms.
Application:
Application segmentation tracks divergent specification regimes—automotive rubber demands bulk antioxidants while crop protection requires precise derivative chemistry.
- Rubber Processing:Antioxidant stabilization of natural and synthetic rubber compounds consumes the majority of DPA derivatives. Bridgestone, Michelin, and Goodyear procurement teams negotiate multi-year offtake agreements with volume escalators tied to tire plant utilization.
- Agriculture:DPA-derived intermediates for fungicide synthesis command premium pricing outside commodity rubber markets. BASF and Syngenta formulation pipelines in Germany and Switzerland specify high-purity agricultural grades with documented impurity profiles.
- Coatings:Mature stabilizer applications in industrial coatings face slower formulation change cycles and gradual phenolic antioxidant displacement.
- Pharmaceuticals:Drug intermediate applications impose the most stringent analytical certification requirements, with batch-specific COA documentation mandatory for CDMO qualification.
Rubber Processing dominates volume consumption; Agriculture is climbing fastest on derivative chemistry expansion.
End User:
End user structure reflects supply chain position—direct manufacturer relationships lock in volume, while distributor channels serve fragmented demand.
- Manufacturers:Tire producers and agrochemical formulators purchase directly through qualified supplier programs with audit requirements. Long-term contracting is displacing spot purchasing among tier-one manufacturers seeking supply security amid aniline feedstock volatility.
- Distributors:Regional chemical distributors aggregate demand from mid-scale rubber compounders and specialty formulators lacking direct supplier relationships.
- Retailers:Limited relevance for DPA given industrial chemical classification and handling restrictions.
- Consumers:No direct consumer exposure; product classification prohibits retail availability.
Manufacturers concentrate procurement volume; distributor channels are gaining share fastest among emerging market compounders.
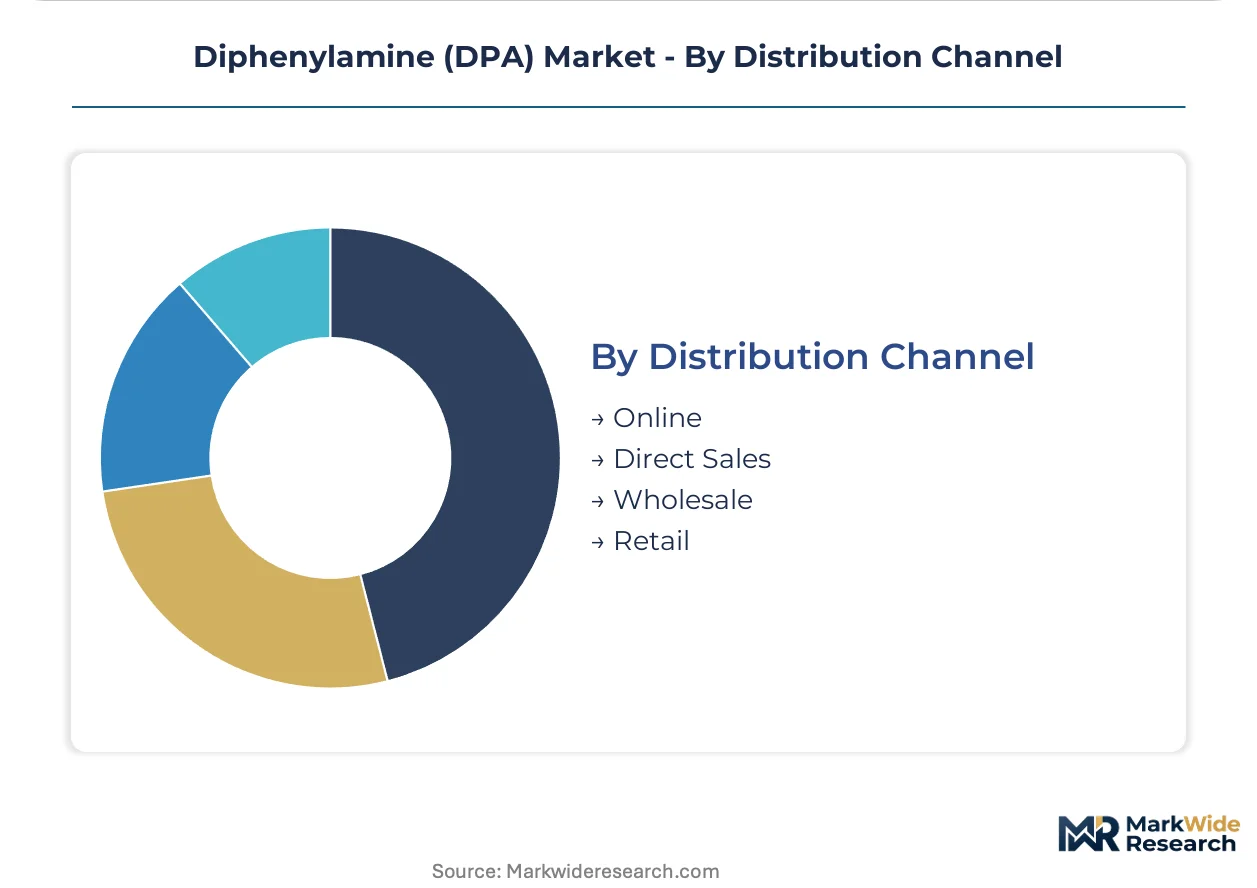
Distribution Channel:
Channel economics favor direct relationships for volume accounts, with digital platforms penetrating spot chemical purchasing.
- Direct Sales:Technical service integration and formulation support accompany volume contracts to major tire and agrochemical producers. Eastman Chemical and LANXESS field technical teams co-develop antioxidant blends with customer R&D departments.
- Online:Digital platforms from Chemours and specialty chemical marketplaces facilitate spot purchasing for mid-scale compounders. E-procurement penetration remains limited by hazardous material shipping regulations and sample qualification requirements.
- Wholesale:Regional chemical wholesalers maintain inventory positions for rubber processors with unpredictable demand patterns.
- Retail:Channel inapplicable for industrial chemical distribution.
Direct Sales commands the largest share; Online is expanding most quickly among mid-tier purchasers seeking price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German pharmaceutical-grade supply chains while Chinese industrial-grade volumes absorb margin compression from aniline feedstock volatility. This asymmetry reflects divergent regulatory burdens and end-use specifications across major production clusters.
China
Domestic tire manufacturers consume substantial antioxidant volumes as vehicle production sustains rubber chemical demand. MEE emission controls on aniline-based manufacturing clusters in Jiangsu and Shandong provinces compel purification upgrades. The Yangtze River Delta hosts integrated nitrobenzene-aniline production facilities supplying captive DPA precursor to regional antioxidant producers.
Germany
REACH Annex XVII restrictions on secondary amine content force rubber formulators to document nitrosamine formation potential across tire applications. ECHA enforcement tightens impurity specifications, compelling reformulation investments. The Rhine-Ruhr industrial corridor maintains specialty chemical production of high-purity grades for pharmaceutical and agrochemical specifications.
United States
EPA discharge thresholds govern DPA handling at Gulf Coast chemical manufacturing complexes serving lubricant and rubber processing markets. OSHA process safety management requirements constrain operational expansion for aromatic amine producers. The Texas-Louisiana petrochemical corridor anchors merchant DPA supply for North American tire compounders.
India
Domestic tire production growth under PLI scheme incentives creates import substitution potential for regional DPA supply. BIS quality standards for rubber processing chemicals tighten specification compliance for local formulators. Gujarat and Maharashtra industrial zones concentrate emerging antioxidant blending capacity serving automotive OEM supply chains.
Japan
METI industrial chemical regulations enforce rigorous purity documentation for DPA derivatives entering pharmaceutical intermediate applications. JIS standards for rubber antioxidants specify performance benchmarks that exclude lower-grade imports. The Osaka-Kobe chemical cluster maintains precision manufacturing of high-specification grades for agrochemical and electronic material applications.
Diphenylamine (DPA) Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the DPA supply chain. The market structures around three tiers: integrated petrochemical majors with captive aniline supply, specialty chemical houses with purification expertise, and regional merchant producers dependent on spot feedstock purchasing. Strategic differentiation follows two dominant competitive moves—backward integration into nitrobenzene-aniline feedstocks to secure margin resilience, and long-term offtake contracting with tire manufacturers to lock in volume visibility.
Among European-based chemical conglomerates, BASF SE and LANXESS AG exemplify divergent strategic positions within the antioxidant value chain. Eastman Chemical Company anchors the North American competitive set through rubber additive formulation relationships. These three entities collectively represent the integrated major, high-purity specialist, and formulation-anchored archetypes that define competitive positioning in amine-based stabilizer markets.
| Leading Market Players |
|---|
| Huntsman International LLC |
| Merck KGaA |
| BASF SE |
| Duslo a.s. |
| SONGWON Industrial Co., Ltd. |
| LANXESS AG |
| Arkema |
| Seiko Chemical Co., Ltd. |
| Eastman Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracting between tire manufacturers and DPA suppliers locks in multi-year volume visibility while insulating buyers from benzene-aniline feedstock volatility. This contract-structure pattern concentrates pricing power among integrated producers in China and Germany who can guarantee specification compliance across REACH purity mandates.
Pricing Analysis
The customization-premium spread between certified low-nitrosamine grades and standard industrial DPA widens as ECHA enforcement tightens. Three-tier pricing structure across pharmaceutical, agricultural, and industrial grades reflects purification intensity and certification documentation. Cost compression in industrial grades intensifies because Chinese domestic tire producers leverage scale procurement, while pharmaceutical-grade buyers show minimal price sensitivity due to regulatory qualification barriers.
Supply Chain Analysis
Inventory buffers at German and Swiss specialty chemical facilities extend lead times for pharmaceutical-grade orders while Chinese industrial-grade supply maintains just-in-time responsiveness. Production gravity centers on China, Germany, and the United States, with the Yangtze River Delta and Rhine-Ruhr corridor anchoring regional supply. The DPA supply chain draws from aniline, nitrobenzene, and hydrogen feedstocks, exposing margins to crude oil derivative volatility. Single-source vulnerability concentrates in high-purity crystallization capacity. Distribution runs through qualified supplier programs with technical service integration for tire manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DPA demand sits in early-cycle expansion as agrochemical derivative applications penetrate fungicide and herbicide formulation pipelines faster than prior adoption waves.
For Market Incumbents: Secure backward integration into nitrobenzene-aniline feedstocks to defend margin resilience against benzene price volatility. Lock in multi-year offtake agreements with Bridgestone, Michelin, and Goodyear procurement teams before new tire plant capacity absorbs regional supply. Invest in membrane filtration retrofit capacity to contest LANXESS positions in pharmaceutical-grade segments. For New Entrants and Emerging Players: REACH certification fast-track through ECHA pre-registration offers the most penetrable entry path for mid-scale producers targeting European rubber formulators. White-space concentrates in Indian domestic tire production under PLI scheme incentives and propellant stabilizer qualification for defense contractors. Lead with technical service co-development to differentiate against commodity merchant suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward high-purity specialists with documented impurity profiles below 50ppm and established CDMO qualification relationships. The 5-10 year viability window favors assets with pharmaceutical and agrochemical grade certification over commodity industrial-grade exposure. Watch for ECHA Annex XVII expansion into additional secondary amine restrictions as the inflection signal for accelerated substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Feedstocks | BASF and LANXESS leverage captive nitrobenzene supply to compress production economics. |
| Membrane Filtration Retrofit Deployment | German and Swiss producers miniaturize capital barriers for pharmaceutical-grade entry. |
| Long-term Supply Agreement with Tire OEMs | Bridgestone and Michelin procurement teams negotiate fixed-volume escalators for supply security. |
| REACH Certification Fast-track Investment | Mid-scale producers contest LANXESS positions through ECHA pre-registration pathways. |
| Agrochemical Derivative Capacity Expansion | BASF and Syngenta formulation pipelines drive specification evolution toward higher active content. |
Study Parameters
Operator-level perspectives from plant managers at integrated aniline facilities, procurement leads at tire manufacturers, technical R&D directors at agrochemical formulators, and distribution channel partners anchored the qualitative base. These primary interviews combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from chemical conglomerates, and MEE emission disclosure records. Bottom-up capacity modeling and top-down demand triangulation validated volume estimates across grade tiers and end-use verticals.
Sensitivity analysis tested forecast robustness against benzene price volatility scenarios and REACH regulatory expansion pathways across the projection horizon. Segmentation dimensions modeled include grade tier (industrial, pharmaceutical, agricultural), end-use industry (rubber processing, agrochemicals, pharmaceuticals), and regional production hub (China, Germany, United States, India). CAGRs derived from historical elasticity analysis and forward-looking capacity-expansion schedules, with specific inputs from tire plant utilization rates and agrochemical formulation pipeline disclosures.
Decision-makers should treat outputs as directional under sustained tire manufacturing expansion and stable aniline feedstock availability assumptions; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Laboratory Chemicals Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
India Methanol Market
Chemicals
Piroctone Olamine Market
Chemicals
Isopropanolamine Market
Chemicals
Coagulant Market
Chemicals
Hydrogen Fluoride Pyridine Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Japan Methanol Market
Chemicals
Maleic Acid Market
Chemicals
Global Syringaldehyde Market
Chemicals
Glyoxylic Acid Market
Chemicals
Global Cysteine Market
Chemicals
Cetyl Stearyl Alcohol Market
Chemicals
Chlorosilane Market
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market