
 Ferric Phosphate Market | 2026-2036
Ferric Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Ferric Phosphate Market Analysis
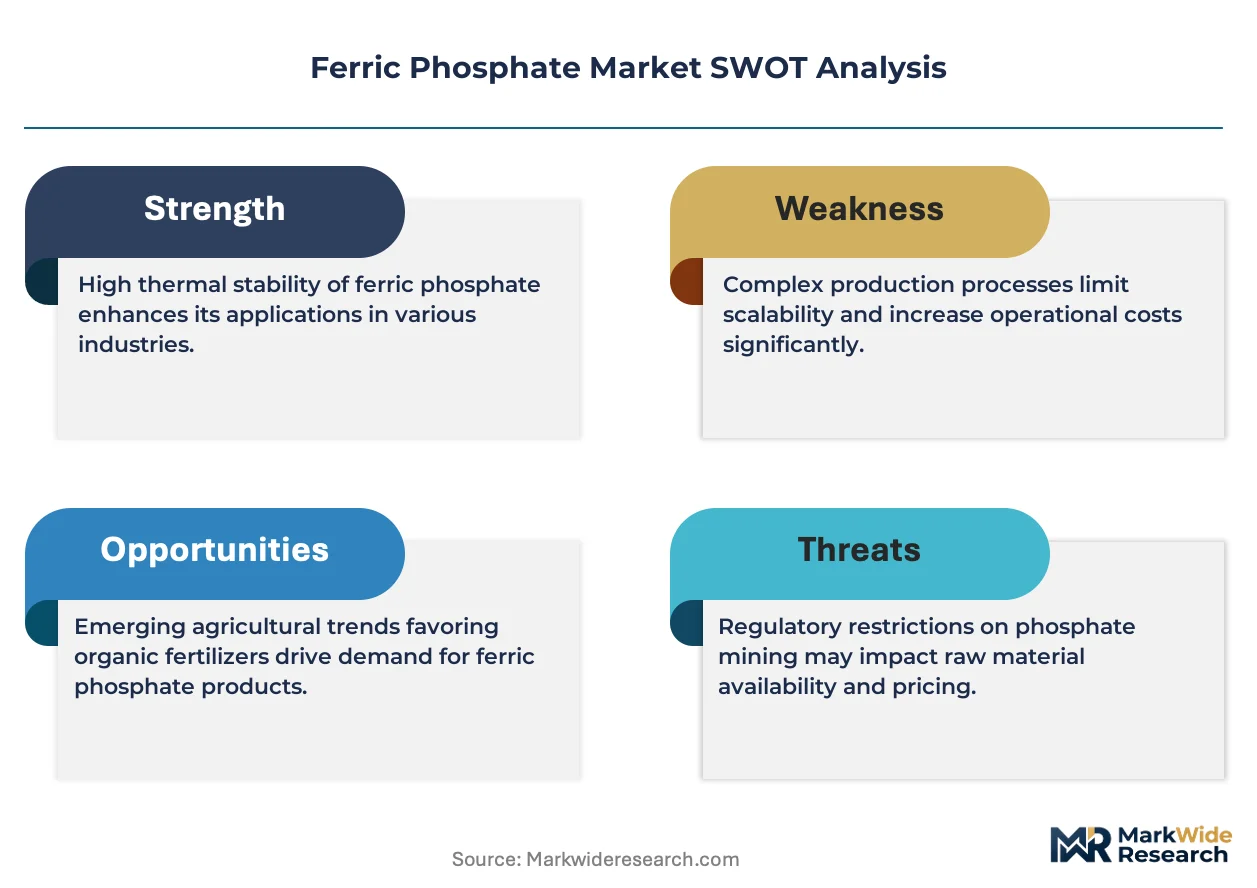
Pharmaceutical-grade purity thresholds are bifurcating the competitive landscape. Merck leverages its European GMP-certified production network to command premium positioning in drug-grade supply. Jost Chemical Co. anchors North American demand through FDA-registered manufacturing and dedicated pharmaceutical channels. American Elements competes on custom synthesis capabilities, serving research institutions and specialty battery developers with non-standard particle specifications.
Ferric phosphate is an iron(III) orthophosphate salt with the formula FePO₄, typically synthesized through controlled precipitation from ferric chloride and sodium phosphate solutions, yielding crystalline or amorphous forms with defined particle size distributions between 1-50 microns. The compound serves as a cathode precursor in lithium iron phosphate batteries, a nutritional fortificant in food supplements, and an active pharmaceutical ingredient in iron-deficiency therapies. Technical grade material dominates volume flows, supplying fertilizer and industrial applications where purity tolerances remain less stringent than pharmaceutical or battery-grade standards. Reagent grade output represents the fastest-expanding tier, driven by R&D intensity in next-generation cathode formulations and precision nutrition research. Pharmaceutical grade commands the deepest margin pools, constrained by validation costs and regulatory filing requirements that limit qualified supplier counts.
EPA guidelines on heavy-metal limits in agricultural runoff shape fertilizer-grade product specifications, while FDA current Good Manufacturing Practice rules govern pharmaceutical and food-supplement applications. China's NMPA and SAMR enforce dual-use chemical registration for battery-grade precursors, creating compliance layers that favor vertically integrated producers. REACH registration requirements in Europe constrain import flexibility for non-EU manufacturers. Stakeholders must monitor evolving cathode chemistry roadmaps, as silicon-iron phosphate blends and manganese doping protocols could redirect specification demand faster than capacity cycles adjust.
Market Dynamics
Battery-grade purity specifications are compressing technical-grade margins while concentrating qualified supplier pools around cathode precursor capabilities. China's dual carbon goals and SAMR feedstock standards are accelerating this bifurcation.
Growth Catalysts
- LFP Cathode Demand:Lithium iron phosphate battery manufacturers are absorbing high-purity ferric phosphate precursors at volumes that reshape supplier qualification priorities.
- EU Green Deal:REACH registration requirements for battery materials are creating preferential access for pre-certified European producers in cross-border trade.
- Iron Deficiency Therapeutics:Pharmaceutical formulators are expanding oral iron supplement portfolios, driving GMP-grade procurement from FDA-registered channels.
Market Restraints
- Phosphoric Acid Volatility:Wet-process phosphoric acid feedstock costs fluctuate with sulfur and energy input prices, squeezing precipitation-route margins.
- Jiangsu Supply Concentration:Cathode-grade output clusters in a single Chinese province expose buyers to localized environmental enforcement disruptions.
- Sodium-Ion Substitution:Prussian white cathode chemistries for grid storage applications are diverting some iron-based precursor demand.
Strategic Opportunities
- India PLI Scheme:Cell manufacturing incentives under the country's production-linked initiative are creating localized precursor demand outside established supply chains.
- Silicon-Iron Phosphate Blends:Next-generation cathode formulations incorporating silicon nanocomposites require custom particle specifications from synthesis specialists.
- Direct-to-Brewery Distribution:Food-grade ferric phosphate for nutritional fortification is bypassing traditional chemical distributors through vertical supply agreements with beverage manufacturers.
Industry Challenges
- Battery Qualification Timelines:OEM cathode validation cycles extend 18-24 months, locking working capital in pre-commercial inventory.
- Cross-Grade Contamination Control:Multi-product plants serving technical, reagent, and pharmaceutical tiers face batch segregation complexity under FDA current Good Manufacturing Practice rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferric Phosphate Market |
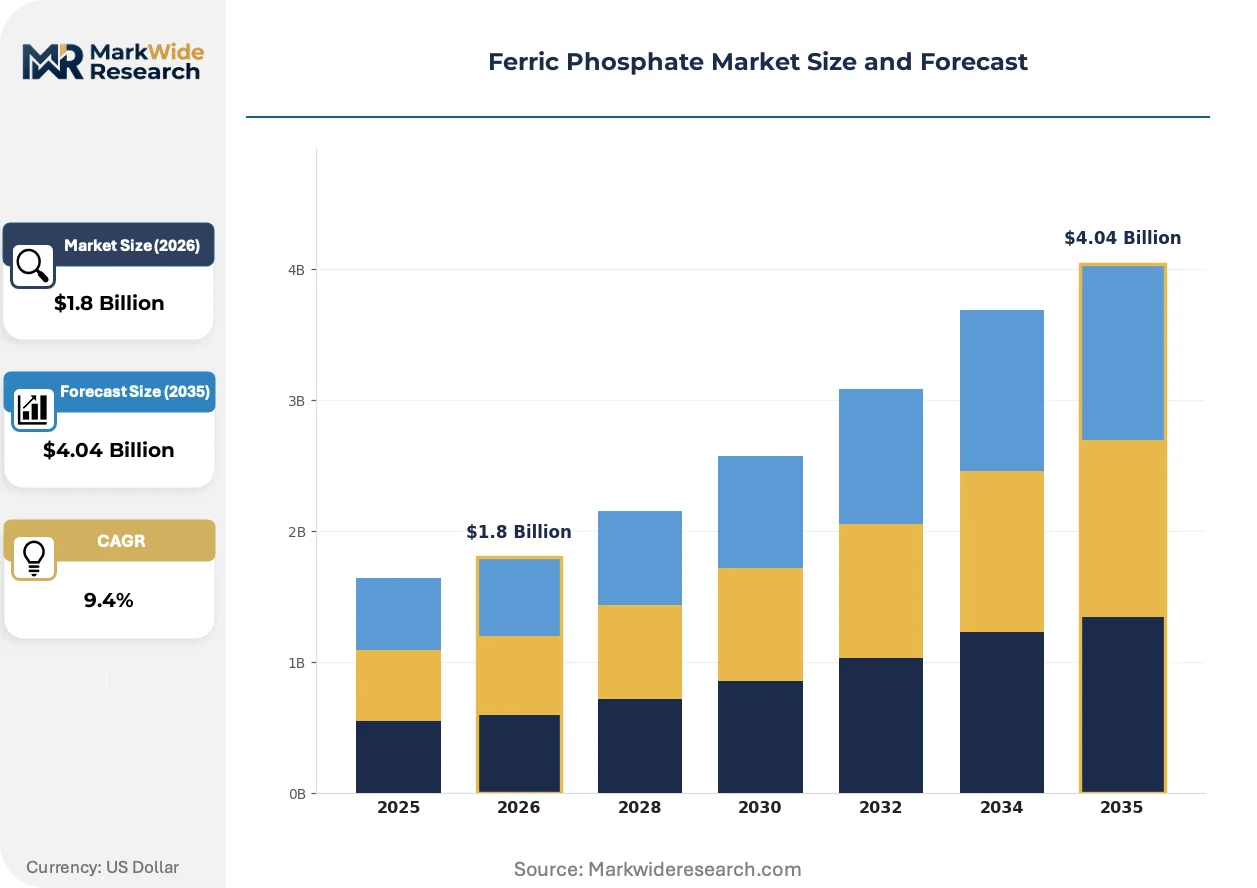
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Grade, Technical Grade, Pharmaceutical Grade, Industrial Grade Application: Food Supplement, Fertilizer, Pharmaceutical, Animal Feed End User: Pharmaceutical Companies, Agriculture Sector, Food Industry, Nutraceutical Firms Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | American Elements, Jost Chemical Co., Merck, Crest Industrial Chemicals, Charkit Chemical Corporation, Aarvee Chemicals, Alfa Aesar, Imperial Chem Incorporation, Hefei Asialon Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferric Phosphate Market Emerging Trajectories
Continuous precipitation reactor designs and real-time particle monitoring are compressing batch-to-batch variation. These advances are reshaping how producers defend specification premiums.
Sol-gel synthesis routes for sub-micron ferric phosphate are miniaturizing particle size distributions for high-rate cathode applications. Korean and Chinese cell manufacturers are qualifying these materials for premium electric vehicle platforms. The technology is miniaturizing the performance gap between LFP and nickel-rich chemistries in cold-start conditions.
China's NMPA and SAMR dual-use chemical registration framework is tightening documentation requirements for battery-grade exports. European importers now face additional substance identity verification steps. Cell producers are responding by qualifying secondary suppliers with pre-registered REACH dossiers.
Long-term offtake contracting is displacing spot market procurement for cathode-grade material. Tier-one battery manufacturers are locking multi-year supply agreements directly with precipitation specialists. This pattern is most visible in Jiangsu province, where integrated material parks enable pipeline delivery without intermediate packaging.
Ferric Phosphate Market Segmentation
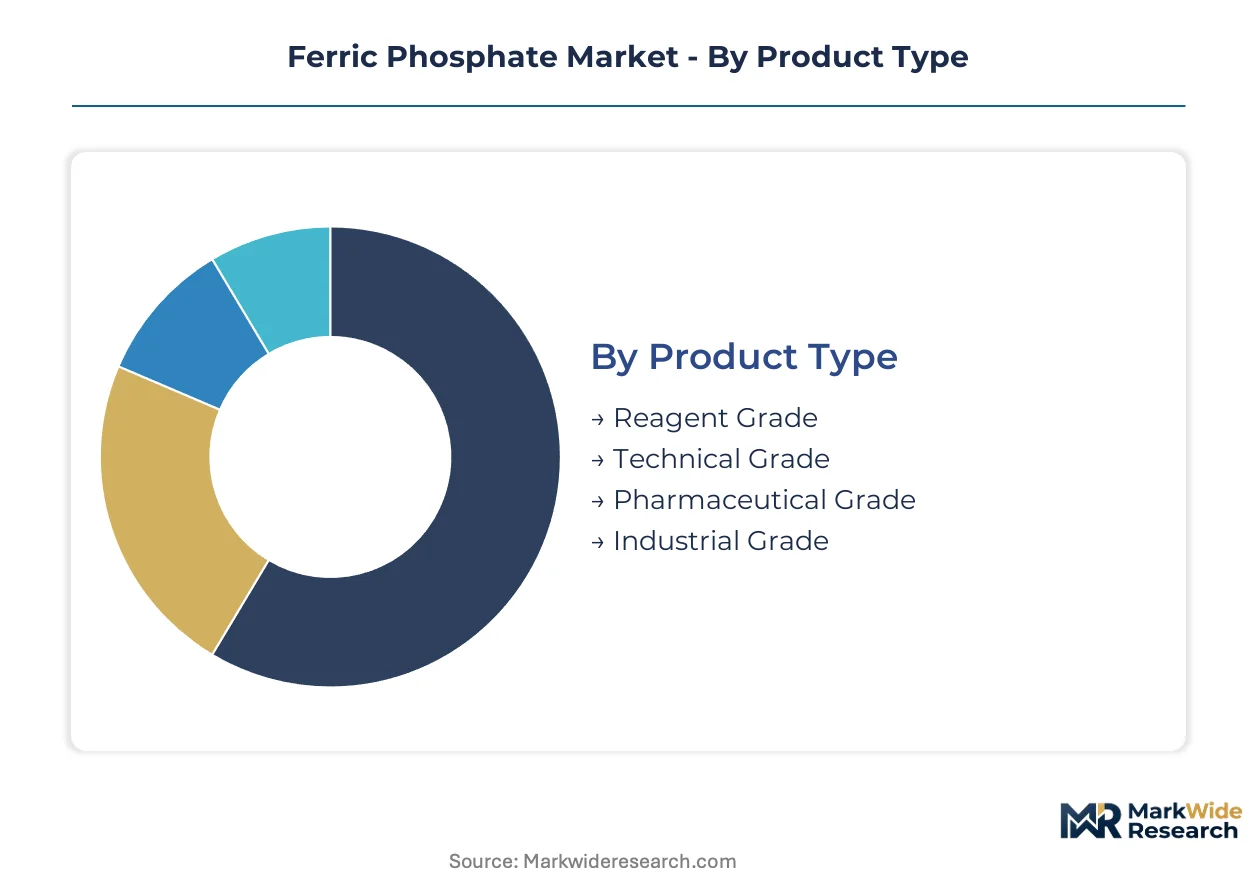
Ferric phosphate markets fragment across purity tiers that carry distinct regulatory burdens and margin structures. Each segment category reflects divergent qualification timelines, end-use specifications, and procurement patterns that reshape supplier economics.
Product Type:
FDA, EPA, and REACH frameworks enforce tiered purity mandates that separate qualified suppliers from commodity producers. Grade-specific registrations determine market access and pricing power.
- Reagent Grade:Sub-micron particle specifications synthesized through sol-gel routes for next-generation cathode R&D. Korean and Chinese cell manufacturers are qualifying these materials for premium electric vehicle platforms requiring high-rate performance.
- Technical Grade:Wet-process precipitation output serving fertilizer and industrial applications where heavy-metal tolerances align with EPA agricultural runoff guidelines. Volume concentrates in commodity chemical channels with compressed margins.
- Pharmaceutical Grade:GMP-certified production for iron-deficiency therapeutics governed by FDA current Good Manufacturing Practice rules and EMA quality directives. Validation costs limit qualified supplier pools.
- Industrial Grade:Standard purity precipitates for non-critical applications. Procurement flows through distributors serving regional manufacturing clusters without batch-specific documentation.
Established volume favors Technical Grade; emerging adoption favors Reagent Grade.
Application:
End-use specifications diverge sharply across nutritional, therapeutic, and agricultural pathways. Each application carries distinct contaminant thresholds and documentation requirements.
- Food Supplement:Nutritional fortification for beverages and dietary products regulated by FDA food additive rules and FSSAI standards in India. Direct-to-brewery distribution agreements are bypassing traditional chemical distributors.
- Fertilizer:Iron micronutrient delivery for soil amendment governed by EPA heavy-metal limits in agricultural runoff. Technical-grade material dominates this volume tier with price-sensitive procurement.
- Pharmaceutical:Oral iron therapies for deficiency anemia requiring GMP validation and FDA-registered manufacturing channels. Formulators are expanding supplement portfolios.
- Animal Feed:Livestock nutritional fortification with intermediate purity requirements. Feed additive regulations vary across USDA, EU feed hygiene standards, and national veterinary authorities.
Volume leadership sits with Fertilizer; steepest expansion trajectory belongs to Pharmaceutical applications.
End User:
Customer procurement sophistication ranges from validated pharmaceutical channels to spot-market agricultural buying. Qualification depth determines supplier stickiness and contract structure.
- Pharmaceutical Companies:GMP-grade procurement through FDA-registered manufacturers with 18-24 month validation cycles. Long-term offtake agreements are displacing spot purchasing.
- Agriculture Sector:Seasonal volume buying for fertilizer blending with sulfur and energy price sensitivity. Technical-grade suppliers compete on delivered cost to regional distribution hubs.
- Food Industry:Nutritional fortification for packaged goods and beverages. Direct supply agreements with manufacturers are compressing distributor margins.
- Nutraceutical Firms:Dietary supplement formulators requiring intermediate documentation between food and pharmaceutical standards. Procurement flexibility favors multi-grade suppliers.
Contract security favors Pharmaceutical Companies; price volatility exposure concentrates in Agriculture Sector.
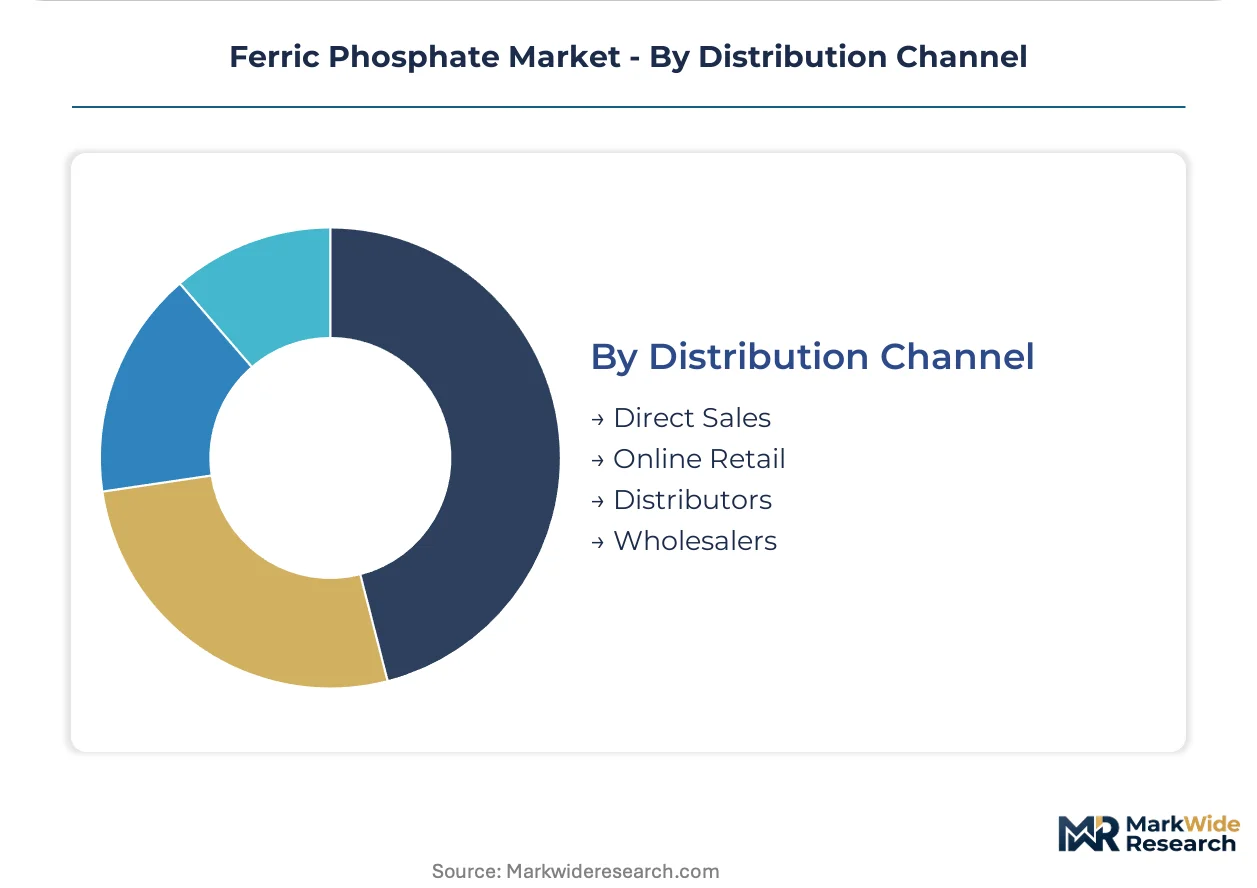
Distribution Channel:
Channel selection reflects customer scale, documentation requirements, and geographic concentration. Direct relationships are gaining share in high-specification tiers.
- Direct Sales:Long-term supply agreements between precipitation specialists and tier-one battery manufacturers. Pipeline delivery from Jiangsu material parks eliminates intermediate packaging.
- Online Retail:Small-volume procurement for research institutions and specialty formulators. Custom synthesis capabilities from American Elements and similar suppliers serve this channel.
- Distributors:Regional chemical distributors serving technical-grade fertilizer and industrial buyers. Margin compression from direct sales is forcing portfolio diversification.
- Wholesalers:Bulk commodity flows for agricultural and feed applications with minimal documentation. Price competition is intense and loyalty is low.
Relationship depth favors Direct Sales; transactional volume concentrates in Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China hosts the dominant share of cathode-grade precipitation capacity, with Jiangsu province material parks supplying tier-one battery manufacturers through pipeline delivery systems. European and North American markets remain import-dependent for high-purity grades, though domestic qualification programs are expanding.
China
Jiangsu province clusters serve domestic EV supply chains with integrated material parks enabling direct pipeline delivery to cathode manufacturers. SAMR dual-use chemical registration and NMPA export documentation requirements tighten feedstock purity thresholds for battery-grade precursors. Hefei Asialon Chemical and precipitation specialists in the Yangtze River Delta region are scaling continuous reactor designs to compress batch-to-batch variation.
United States
Pharmaceutical-grade demand anchors North American procurement through FDA-registered manufacturing channels with 18-24 month validation cycles. EPA guidelines on heavy-metal limits in agricultural runoff shape fertilizer-grade specifications for technical material. Jost Chemical Co. anchors domestic GMP-grade supply from Missouri-based production facilities serving iron-deficiency therapeutic formulators.
Germany
REACH registration requirements for battery materials create preferential market access for pre-certified European producers in cross-border trade. EMA quality directives govern pharmaceutical-grade imports with validation costs that limit qualified supplier pools. Merck leverages its GMP-certified European production network to command premium positioning in drug-grade supply across the continent.
India
Cell manufacturing incentives under the PLI scheme are creating localized precursor demand outside established Chinese supply chains. FSSAI standards regulate nutritional fortification applications for food supplements and beverage fortification. Aarvee Chemicals and regional distributors in Maharashtra and Gujarat are positioning to serve emerging cathode material requirements from domestic battery assembly operations.
South Korea
MFDS pharmaceutical regulations and METI-aligned industrial standards govern multi-grade import requirements for battery and therapeutic applications. Korean cell manufacturers are qualifying sub-micron sol-gel synthesis materials for premium electric vehicle platforms requiring high-rate cold-start performance. Domestic cathode producers in the Seoul Capital Area are locking multi-year offtake agreements directly with precipitation specialists to secure specification-grade supply.
Ferric Phosphate Market Vendor Landscape
Concentration sits with precipitation specialists and GMP-certified pharmaceutical manufacturers who control qualification-intensive tiers. Technical-grade supply remains fragmented across regional chemical distributors serving fertilizer and industrial applications. Three archetypes dominate: integrated cathode precursor specialists, FDA-registered pharmaceutical manufacturers, and custom synthesis providers serving R&D channels. Capacity expansion and long-term offtake contracting represent the dominant competitive moves as tier-one battery manufacturers seek supply security.
Within the GMP-certified tier, Merck and Jost Chemical Co. exemplify the regulatory-barrier strategy, occupying positions that validation costs protect from commodity competition. American Elements anchors the custom synthesis archetype, serving research institutions and specialty battery developers with non-standard particle specifications. Among technical-grade suppliers, Crest Industrial Chemicals and Charkit Chemical Corporation sit within regional distribution networks where price competition intensifies and loyalty remains low.
| Leading Market Players |
|---|
| American Elements |
| Jost Chemical Co. |
| Merck |
| Crest Industrial Chemicals |
| Charkit Chemical Corporation |
| Aarvee Chemicals |
| Alfa Aesar |
| Imperial Chem Incorporation |
| Hefei Asialon Chemical |
| Others |
Supply Flow & Price Mechanics
Continuous precipitation reactor scale economies in Jiangsu province compress unit costs while simultaneously elevating price floors for qualified battery-grade output. China's SAMR dual-use chemical registration and NMPA export documentation requirements create compliance barriers that protect margin pools for certified producers serving cathode manufacturers through pipeline delivery systems.
Pricing Analysis
FDA current Good Manufacturing Practice rules dictate the pricing tier structure across pharmaceutical, battery-grade, and technical material segments. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified therapeutics from cathode precursors and fertilizer-grade commodity flows. Cost compression in technical-grade channels is intensifying because wet-process phosphoric acid feedstock volatility squeezes precipitation-route margins. Agriculture sector buyers exhibit highest price sensitivity through seasonal spot purchasing, while pharmaceutical companies absorb premiums through locked multi-year offtake agreements.
Supply Chain Analysis
Strategic stockpiling dominates cathode-grade procurement as tier-one battery manufacturers lock 18-24 month qualification cycles, while fertilizer buyers prefer just-in-time seasonal restocking. Supply concentrates in China, South Korea, and Germany for high-purity precipitation capacity. Raw material dependencies rest on wet-process phosphoric acid, sulfur inputs, and sodium phosphate solutions. Single-source vulnerability in Jiangsu province exposes buyers to localized environmental enforcement disruptions. Distribution runs through direct pipeline delivery from integrated material parks to cathode manufacturers, bypassing traditional chemical distributors for qualified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lithium iron phosphate cathode chemistry disruption is accelerating supplier qualification timelines and concentrating procurement around precipitation specialists with continuous reactor capabilities. China's dual carbon goals and SAMR feedstock standards are tightening purity thresholds faster than commodity producers can adapt.
For Market Incumbents: Shield GMP-certified positioning through FDA-registered manufacturing network expansion and backward integration into wet-process phosphoric acid supply. Sodium-ion substitution via Prussian white cathode chemistries threatens iron-based precursor demand in grid storage applications. Capacity addition in India under PLI scheme incentives captures emerging localized demand outside Chinese supply chains.
For New Entrants and Emerging Players: Anchor in reagent-grade sol-gel synthesis for sub-micron particle specifications serving Korean and Chinese cell manufacturers qualifying high-rate cathode materials. India's PLI scheme creates the most penetrable geography for precursor supply localization. Direct-to-brewery distribution agreements for food-grade nutritional fortification bypass entrenched chemical distributor channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precipitation specialists with locked multi-year offtake agreements to tier-one battery manufacturers. Long-term viability across the next decade hinges on qualification depth and regulatory certification moats. Acquisition target archetype: continuous reactor operators with pre-registered REACH dossiers and existing cathode manufacturer relationships. Watch for silicon-iron phosphate blend qualification announcements as inflection indicator for next-generation cathode chemistry demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks 18-24 month qualification cycles with tier-one battery manufacturers in Jiangsu material parks. |
| Backward Integration | Captures wet-process phosphoric acid supply to defend margins against sulfur and energy price volatility. |
| Capacity Expansion | Scales continuous precipitation reactor output to serve India's PLI scheme localized precursor demand. |
| Green Manufacturing Transition | Aligns with China's dual carbon goals and SAMR feedstock purity tightening for battery-grade exports. |
| Joint Venture | Combines GMP-certified pharmaceutical expertise with cathode precursor precipitation capabilities. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cathode material procurement leads, precipitation plant managers, pharmaceutical formulators, and regulatory affairs specialists at FDA-registered manufacturers. Secondary validation drew from NMPA registration databases, SAMR export documentation filings, REACH dossier repositories, and customs trade flow records. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level outputs.
Across the projection horizon, the analytical framework modeled ferric phosphate markets by purity grade tier, end-use application, and regional production hub clustering. CAGRs were derived from installed capacity expansion trajectories, qualification timeline compression, and cathode chemistry adoption curves. Forecast inputs incorporated SAMR dual-use chemical registration enforcement intensity and PLI scheme incentive disbursement patterns.
Decision-makers should treat outputs as directional under sustained LFP cathode chemistry dominance and stable phosphoric acid feedstock availability; material deviation would warrant model refresh. Revision becomes warranted when sodium-ion substitution rates or silicon-iron phosphate blend qualification timelines cross commercialization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Pentanedione Market
Chemicals
Glyoxylic Acid Market
Chemicals
Asia-Pacific Gamma Butyrolactone Market
Chemicals
Cumene Market
Chemicals
United States Construction Chemicals Market
Chemicals
Spirodiclofen Market
Chemicals
Ethanolamine Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Ferric Chloride Market
Chemicals
South America Construction Chemicals Market
Chemicals
1, 4 Butanediol Market
Chemicals
White Phosphorus Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Resorcinol Market