
 Gas Barrier Membranes Market | 2026-2036
Gas Barrier Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Barrier Membranes Market Analysis
Polyvinylidene chloride is shifting toward ethylene vinyl alcohol and polyamide alternatives as processors respond to sustainability mandates and halogen-reduction targets. UBE Corporation leverages its polyimide expertise to anchor supply relationships in semiconductor and hydrogen infrastructure applications. Evonik Industries AG sustains R&D intensity in high-performance polymer formulations, while Air Liquide competes through integrated gas-and-membrane system offerings that bundle barrier technology with industrial gas supply contracts.
Gas barrier membranes are multi-layer polymer films engineered to restrict oxygen, moisture, carbon dioxide, and volatile organic compound transmission, typically achieving permeation rates below 1 cc/m²/day for oxygen at standard temperature and pressure; they serve to extend shelf life, protect sensitive electronics, and maintain fuel cell efficiency across industrial and consumer applications. Ethylene vinyl alcohol dominates food preservation applications due to its exceptional oxygen barrier performance, though coextrusion technology commands margin pools through complex multi-layer architectures that combine dissimilar polymers without adhesives. Coating processes are gaining traction in medical packaging as manufacturers seek thinner, more flexible sterile barriers that reduce material intensity while maintaining ISO 11607 compliance.
The EPA regulates volatile organic compound emissions from coating and lamination processes under NESHAP standards, while FDA enforces 21 CFR 177 compliance for food-contact barrier layers; California's SB 54 extended producer responsibility framework is reshaping recyclable packaging design requirements. REACH restrictions on per- and polyfluoroalkyl substances in Europe are accelerating fluoropolymer substitution timelines. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification thresholds as regulatory divergence between jurisdictions complicates product platform strategies.
Market Dynamics
Fluorine-free formulation mandates under Europe's F-Gas Regulation are compressing incumbent polymer platforms while pulling capital toward ethylene vinyl alcohol and polyamide alternatives. REACH compliance timelines are forcing multi-year substitution programs across packaging and construction supply chains.
Growth Catalysts
- Automotive fuel cell procurement:Germany's national hydrogen infrastructure program is generating dedicated membrane demand for fuel cell stack sealing and hydrogen storage containment systems.
- REACH substance restrictions:Per- and polyfluoroalkyl substance phase-outs are accelerating fluoropolymer substitution timelines across European packaging converters.
- Coextrusion technology maturation:Advanced multi-layer architectures without adhesive layers are capturing margin pools in medical packaging and high-barrier food applications.
Market Restraints
- Ethylene vinyl alcohol feedstock volatility:Ethylene and vinyl acetate monomer price swings compress converter margins and destabilize long-term supply agreements.
- Fluoropolymer supply concentration:Limited qualified producers of perfluorinated barrier resins create single-source vulnerability for semiconductor and aerospace specifications.
- Multi-layer recyclability barrier:Bonded polymer layers complicate mechanical recycling streams under California's SB 54 extended producer responsibility framework.
Strategic Opportunities
- India pharmaceutical packaging expansion:CDSCO serialization mandates and cold-chain infrastructure buildout are creating demand for moisture-oxygen dual barriers in injectable drug delivery.
- ISO 11607 compliance specialization:Sterile barrier system certification for medical device packaging commands premium positioning in European and North American hospital supply chains.
- Building-integrated photovoltaic sealing:Encapsulant barrier films for solar module edge seals represent an emerging specification channel with uncontracted volume.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with coextrusion die design expertise command compensation premiums that inflate R&D fixed costs.
- Cleanroom certification timelines:FDA 21 CFR 177 food-contact and medical device barrier qualifications require 18-24 month validation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Barrier Membranes Market |
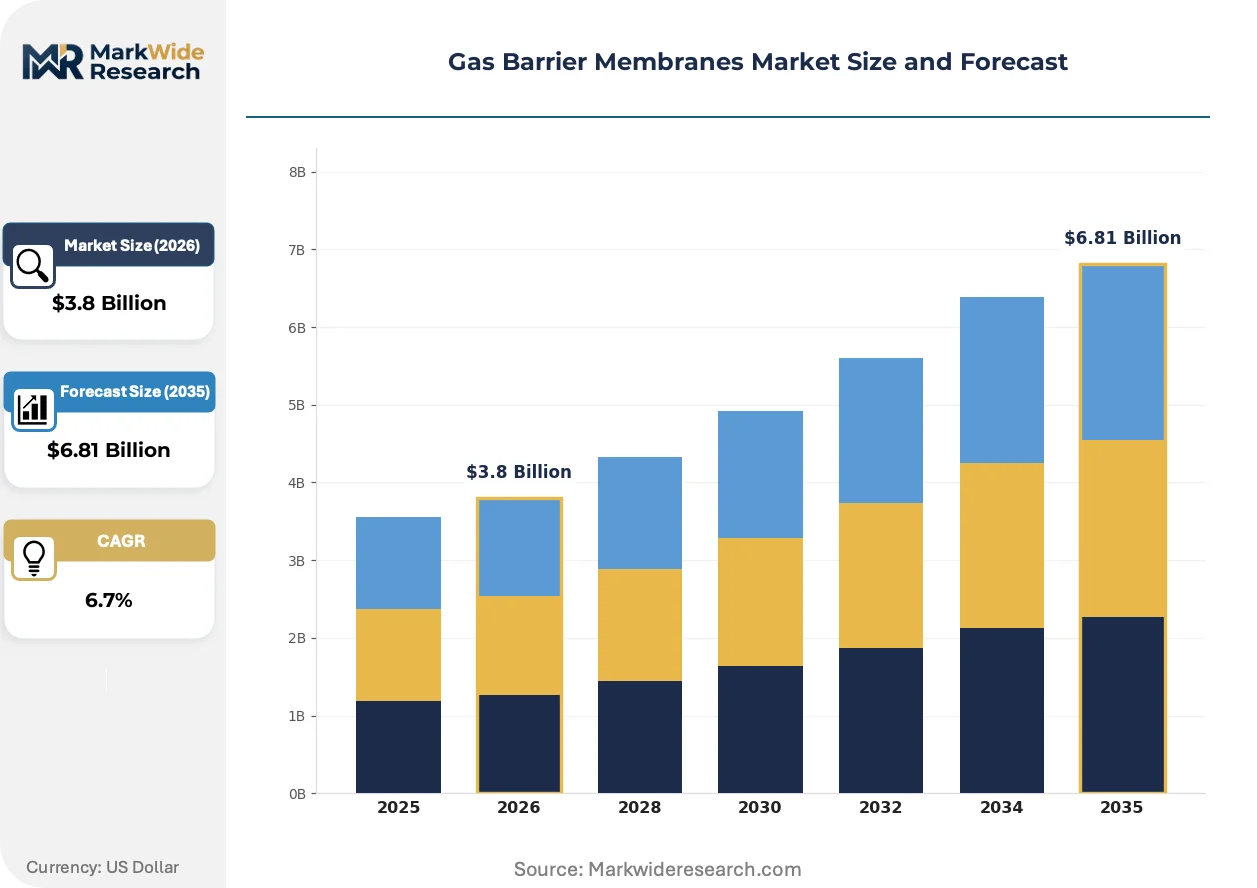
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyvinylidene Chloride, Ethylene Vinyl Alcohol, Others End User: Construction, Packaging, Automotive, Electronics Technology: Coextrusion, Lamination, Coating, Extrusion Application: Food Preservation, Medical Packaging, Fuel Cell, Automotive Parts |
| Companies Covered | Air Products and Chemicals, Inc., Air Liquide, Honeywell UOP, Membrane Technology and Research, Inc., UBE Corporation, Evonik Industries AG, Linde plc, Parker Hannifin Corporation, FUJIFILM Manufacturing Europe B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Barrier Membranes Market Emerging Trajectories
Active materials and process innovation are converging to thin-film barrier architectures that reduce polymer intensity while preserving gas transmission performance. Sustainability certification and regulatory substance restrictions are becoming primary design constraints rather than secondary optimization targets.
Water-based coating systems for oxygen and moisture barriers are expanding into pharmaceutical blister packaging and flexible medical device pouches. European converters adopting these formulations ahead of REACH perfluorinated substance deadlines are securing preferred supplier status with healthcare OEMs. The technology is expanding into specifications previously reserved for solvent-based fluoropolymer coatings.
Europe's F-Gas Regulation phase-down schedule is compressing hydrofluorocarbon-based barrier film production. Manufacturers are reformulating toward hydrocarbon and silicon-based chemistries to maintain barrier performance without fluorinated content. Medical packaging and electronics protection segments are absorbing the steepest compliance costs during this transition.
Hospital procurement consortia are consolidating sterile barrier film specifications around dual-certified suppliers meeting both ISO 11607 and FDA 21 CFR 177 standards. Group purchasing organizations are displacing individual hospital contracting for high-volume barrier membrane categories. This concentration is most visible in German and French hospital supply chains where regional purchasing alliances have captured substantial contract volume.
Gas Barrier Membranes Market Segmentation
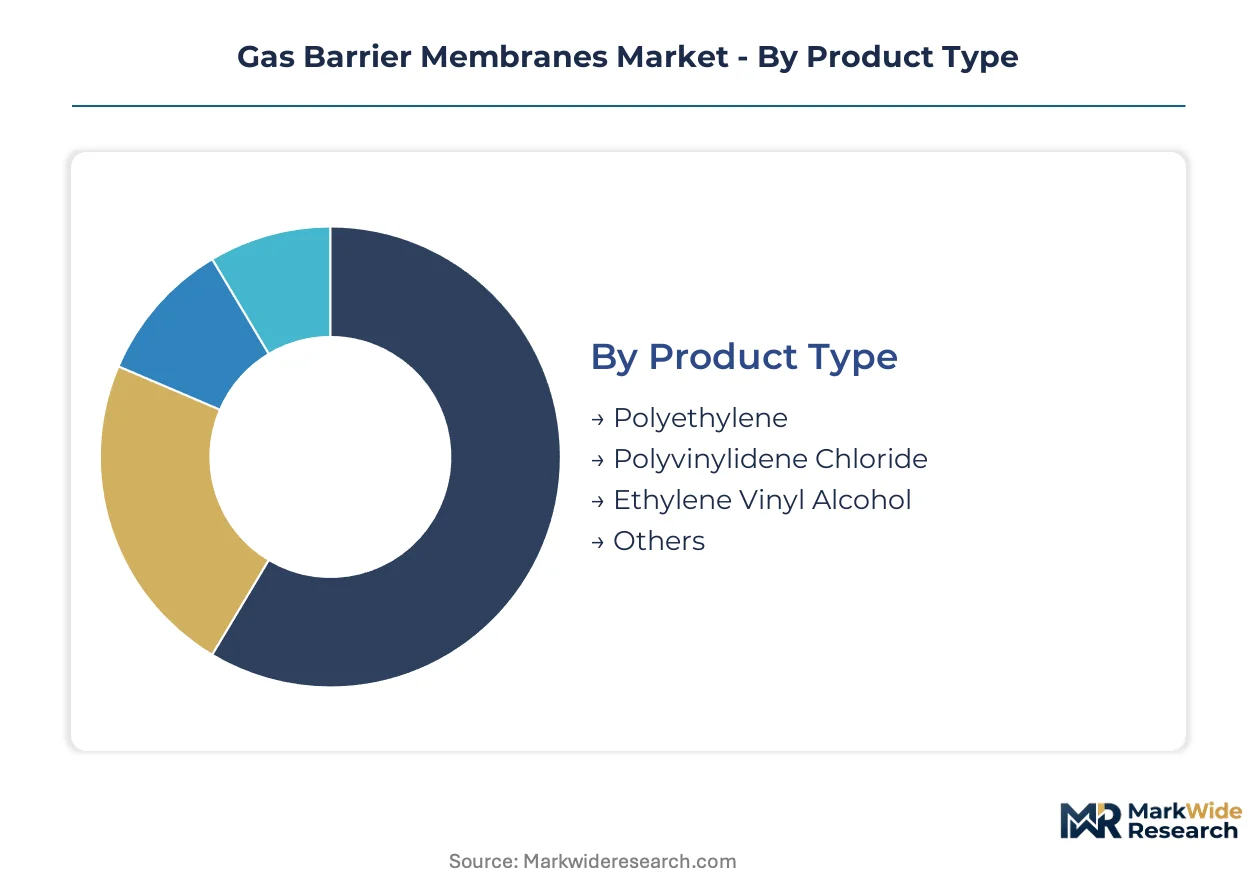
Gas barrier membrane procurement varies sharply by performance tier and regulatory exposure. Capital deployment and margin capture depend on matching polymer platforms to end-use certification requirements.
Product Type:
Ethylene vinyl alcohol and polyamide alternatives command the heaviest upfront investment in multi-layer coextrusion lines and cleanroom finishing capacity.
- Polyethylene:Baseline moisture barriers produced via blown film extrusion serve construction vapor retarders and commodity food pouches. German construction specifiers favor polyethylene-based solutions for below-slab radon protection in energy-efficient building codes.
- Polyvinylidene Chloride:Halogenated polymer with exceptional oxygen and aroma barrier performance historically dominated premium food wrap and pharmaceutical blister specifications. REACH substance restrictions and halogen-reduction mandates in European packaging are compressing conversion volumes toward fluorine-free alternatives.
- Ethylene Vinyl Alcohol:Semi-crystalline copolymer achieving oxygen transmission rates below 1 cc/m²/day through 20-micron films. Japan's METI fuel cell commercialization roadmap and Germany's hydrogen infrastructure program are concentrating demand for EVOH-based hydrogen containment layers in automotive stack sealing.
- Others:Polyimide, cyclic olefin copolymer, and silicon oxide-coated films address semiconductor wafer shipping trays and flexible electronics encapsulation where thermal stability exceeds standard polymer limits.
Most installed capacity flows through polyethylene commodity grades. Expansion is steepest in ethylene vinyl alcohol as fuel cell and pharmaceutical specifications multiply.
End User:
Customer concentration and contract duration separate stable revenue streams from project-based volatility across vertical applications.
- Construction:Below-grade radon and methane barriers, building envelope air sealing, and photovoltaic module edge encapsulation. California's SB 54 extended producer responsibility framework and German EnEV energy efficiency standards are reshaping recyclable membrane specifications in residential and commercial builds.
- Packaging:Multi-layer films for modified atmosphere meat cases, snack laminates, and pharmaceutical cold-chain pouches. Hospital procurement consortia in France and Germany are consolidating sterile barrier specifications around dual-certified suppliers meeting both ISO 11607 and FDA 21 CFR 177 standards.
- Automotive:Fuel cell stack gaskets, hydrogen tank liners, and battery pack thermal barriers. Germany's national hydrogen infrastructure program anchors specialized membrane demand for high-pressure storage containment.
- Electronics:Flexible circuit substrate protection, OLED encapsulation, and semiconductor wafer shipping media. Cleanroom certification timelines of 18-24 months for FDA 21 CFR 177 compliance create qualification barriers that favor incumbent suppliers with validated production lines.
Packaging absorbs the largest volume share. Automotive applications are climbing the fastest as fuel cell procurement scales.
Technology:
Process selection determines barrier performance ceiling, material efficiency, and recyclability compliance under emerging extended producer responsibility frameworks.
- Coextrusion:Simultaneous extrusion of dissimilar polymers through a single die produces adhesive-free multi-layer architectures. Medical packaging converters in Switzerland and Germany are capturing margin premiums through complex 5-7 layer structures combining EVOH cores with polyethylene skins.
- Lamination:Adhesive bonding of pre-formed films enables rapid product customization and short-run flexibility. Solvent-based lamination faces EPA NESHAP volatile organic compound emission constraints in US production facilities.
- Coating:Thin-film deposition of silicon oxide or aluminum oxide onto polymer substrates achieves barrier performance with 60-80% material reduction versus monolithic films. Water-based coating systems are expanding into pharmaceutical blister specifications ahead of REACH perfluorinated substance deadlines.
- Extrusion:Single-polymer blown or cast film production serves cost-sensitive construction and commodity packaging segments where moderate barrier performance satisfies specification.
Coextrusion dominates medical and high-barrier food applications. Coating technology is gaining share fastest in pharmaceutical and electronics segments seeking material intensity reduction.
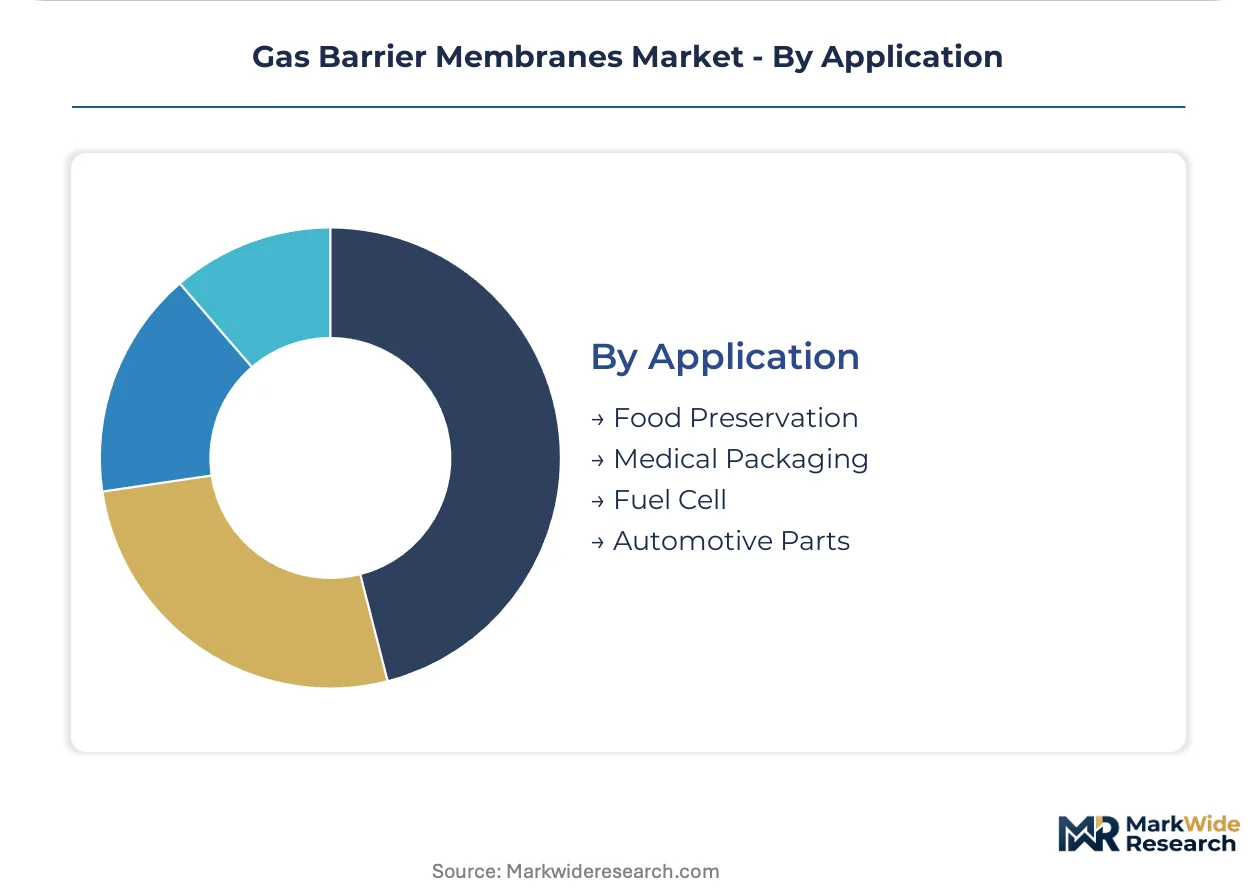
Application:
Certification burden and performance tolerance separate commodity procurement from premium specification channels.
- Food Preservation:Modified atmosphere packaging for fresh protein, snack laminates requiring aroma containment, and retort pouch structures for shelf-stable meals. European converters reformulating away from PVDC are securing preferred supplier status with retail private label programs.
- Medical Packaging:Sterile barrier systems for surgical instruments, implantable device pouches, and injectable drug containers. ISO 11607 compliance specialization commands 15-25% price premiums in North American and European hospital supply chains.
- Fuel Cell:Hydrogen permeation barriers for polymer electrolyte membrane stacks and high-pressure storage tank liners. Germany's KBA type-approval requirements and Japan's METI commercialization targets are concentrating procurement with qualified membrane suppliers.
- Automotive Parts:Battery pack thermal runaway barriers, interior air quality membranes, and fuel system vapor containment layers. OEM qualification cycles of 36-48 months lock in supplier relationships early in platform development.
Food preservation retains the broadest installed base. Fuel cell applications are expanding most quickly as hydrogen infrastructure deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hydrogen infrastructure cluster anchors specialized membrane demand for automotive fuel cell sealing and high-pressure storage containment systems.
Germany
Fuel cell stack procurement and pharmaceutical packaging clusters drive specialized EVOH membrane demand. The F-Gas Regulation and KBA type-approval requirements compress fluoropolymer adoption timelines. Stuttgart and Munich manufacturing corridors concentrate automotive barrier film qualification programs.
United States
Semiconductor wafer shipping and flexible electronics encapsulation sustain cleanroom-certified barrier production. EPA NESHAP standards constrain solvent-based coating capacity expansion. Arizona and Texas semiconductor fabrication hubs absorb premium polyimide membrane volumes.
Japan
METI fuel cell commercialization roadmaps and OLED display manufacturing sustain high-performance polymer demand. JIS standards govern medical packaging barrier specifications. Osaka-Kobe chemical industry corridors specialize in coextrusion technology for 5-7 layer architectures.
China
Building-integrated photovoltaic deployment and cold-chain pharmaceutical logistics expand moisture-oxygen dual barrier procurement. GB standards and dual carbon goals redirect capacity toward fluorine-free formulations. Yangtze River Delta packaging converters capture medical export certification volume.
Switzerland
Precision medical device packaging and pharmaceutical blister specifications command ISO 11607 compliance premiums. Swissmedic regulations enforce sterile barrier system validation timelines. Basel pharmaceutical manufacturing clusters source specialized coextruded films for injectable drug containers.
Gas Barrier Membranes Market Vendor Landscape
Global majors compete with regional champions across technology licensing and cleanroom certification dimensions. The vendor base separates into three tiers: integrated industrial gas suppliers bundling membrane systems, specialized polymer formulators with multi-layer coextrusion expertise, and regional packaging converters capturing compliance-driven substitution volume. Dominant competitive moves include strategic partnerships with fuel cell OEMs for 36-48 month qualification cycles and geographic expansion into Indian pharmaceutical packaging corridors.
Within the integrated gas-and-membrane tier, Air Liquide and Linde plc occupy positions that bundle barrier technology with industrial gas supply contracts. Among specialized polymer formulators, UBE Corporation anchors supply relationships in semiconductor and hydrogen infrastructure applications, while Evonik Industries AG exemplifies sustained R&D intensity in high-performance polymer formulations. These three entities represent distinct competitive archetypes: system integration, materials science specialization, and captive demand channels.
| Leading Market Players |
|---|
| Air Products and Chemicals, Inc. |
| Air Liquide |
| Honeywell UOP |
| Membrane Technology and Research, Inc. |
| UBE Corporation |
| Evonik Industries AG |
| Linde plc |
| Parker Hannifin Corporation |
| FUJIFILM Manufacturing Europe B.V. |
| Others |
Supply Flow & Price Mechanics
Ethylene and vinyl acetate monomer price swings cascade through EVOH converter margins, compressing mid-tier pricing power while premium medical and fuel cell specifications absorb volatility through long-term offtake contracts with German automotive OEMs and Swiss pharmaceutical clusters.
Pricing Analysis
Input-cost pass-through from ethylene and vinyl acetate monomer feeds into three-tier pricing structure across premium, standard, and economy levels. Premium tiers anchored in ISO 11607-certified medical packaging and KBA-qualified fuel cell membranes command 15-25% markups over commodity construction grades. Price differentiation hinges on certification grade and volume scale, with hospital procurement consortia extracting scale discounts while small-batch pharmaceutical converters pay customization premiums. Pricing pressure stems from REACH fluoropolymer substitution timelines forcing reformulation investments. Construction vapor retarder buyers exhibit highest price sensitivity; semiconductor and hydrogen infrastructure buyers show lowest.
Supply Chain Analysis
Reverse-logistics flows for multi-layer film scrap remain underdeveloped, complicating California SB 54 compliance and European extended producer responsibility frameworks. Supply concentrates in Germany, Japan, and China, with German corridors specializing in coextrusion equipment and cleanroom finishing. Raw material dependencies draw from ethylene feedstock networks, vinyl acetate monomer supply, and specialty polyimide resin channels. Single-source vulnerability pervades perfluorinated barrier resin qualification for semiconductor specifications. Distribution runs through regional packaging converter networks with direct OEM contracting for automotive and medical tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where Europe's F-Gas Regulation phase-down functions as a structural demand driver, forcing fluoropolymer substitution programs that reallocate margin pools toward EVOH and polyamide specialists.
For Market Incumbents: Lock in fuel cell OEM qualification cycles ahead of Germany's hydrogen infrastructure scale-up, securing 36-48 month platform lock-in before second-tier suppliers achieve KBA certification. Deepen backward integration into ethylene vinyl alcohol resin production to offset feedstock volatility exposure. Prioritize dual ISO 11607 and FDA 21 CFR 177 certification maintenance as hospital procurement consortia consolidate specifications. For New Entrants and Emerging Players: REACH per- and polyfluoroalkyl substance restrictions in Europe open a window for fluorine-free coating specialists to capture pharmaceutical blister packaging share from incumbent PVDC converters. Target India's CDSCO-mandated cold-chain expansion for moisture-oxygen dual barrier procurement. Pursue water-based coating technology licensing as the go-to-market angle, bypassing solvent-based capacity constraints under EPA NESHAP standards. For Investors and Strategic Acquirers: Consolidation pressure builds where cleanroom certification timelines of 18-24 months create qualification moats around validated production lines. Frame long-term viability around hydrogen infrastructure deployment trajectories and pharmaceutical serialization mandates. Target acquisition profiles emphasizing coextrusion die design expertise and existing ISO 11607 validation. Monitor Germany's KBA type-approval volume and India's CDSCO enforcement intensity as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin Production | Captive ethylene vinyl alcohol supply secures margin insulation against vinyl acetate monomer volatility. |
| Dual Certification Investment (ISO 11607 + FDA 21 CFR 177) | Hospital procurement consortia in Germany and France filter suppliers through combined validation requirements. |
| Fuel Cell OEM Partnership Program | KBA type-approval alignment with Germany's national hydrogen infrastructure program locks in multi-year membrane demand. |
| Water-Based Coating Capacity Expansion | REACH perfluorinated substance deadlines push pharmaceutical converters toward fluorine-free barrier alternatives. |
| Indian Pharmaceutical Packaging Corridor Entry | CDSCO serialization mandates and cold-chain buildout create uncontracted moisture-oxygen dual barrier volume. |
Methodological Framework
Coverage spans Germany, United States, Japan, China, and Switzerland, with primary inputs from each market cluster combining interviews with polymer formulation chemists, medical packaging procurement managers at hospital GPOs, fuel cell stack engineers, coextrusion equipment operators, and regulatory affairs specialists with secondary validation from ECHA REACH substance databases, EPA NESHAP compliance filings, KBA type-approval registries, and customs trade flow records. Bottom-up and top-down triangulation cross-validates regional production estimates against end-use demand aggregation.
Granularity-level framing models ethylene vinyl alcohol and polyamide product tiers, construction-packaging-automotive-electronics end-use splits, coextrusion-lamination-coating-extrusion technology pathways, and food preservation-medical packaging-fuel cell-automotive parts application segments across the analysis window. CAGRs derive from segment-level volume buildups tempered by regulatory substitution elasticity and feedstock price scenario weighting. Hydrogen infrastructure deployment schedules and pharmaceutical cold-chain investment cycles feed sector-specific demand curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under F-Gas Regulation acceleration or ethylene supply disruption scenarios. Forecasts reflect documented assumptions on substitution timelines and certification lag structures. Practitioners should monitor KBA type-approval volume thresholds, CDSCO enforcement intensity, and vinyl acetate monomer price band breaks for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Polysulfone Market
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Spiral Wound Membrane Market
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Membrane Separation Market