
 Hydrogenated Dimer Acid Market | 2026-2036
Hydrogenated Dimer Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogenated Dimer Acid Market Foresight
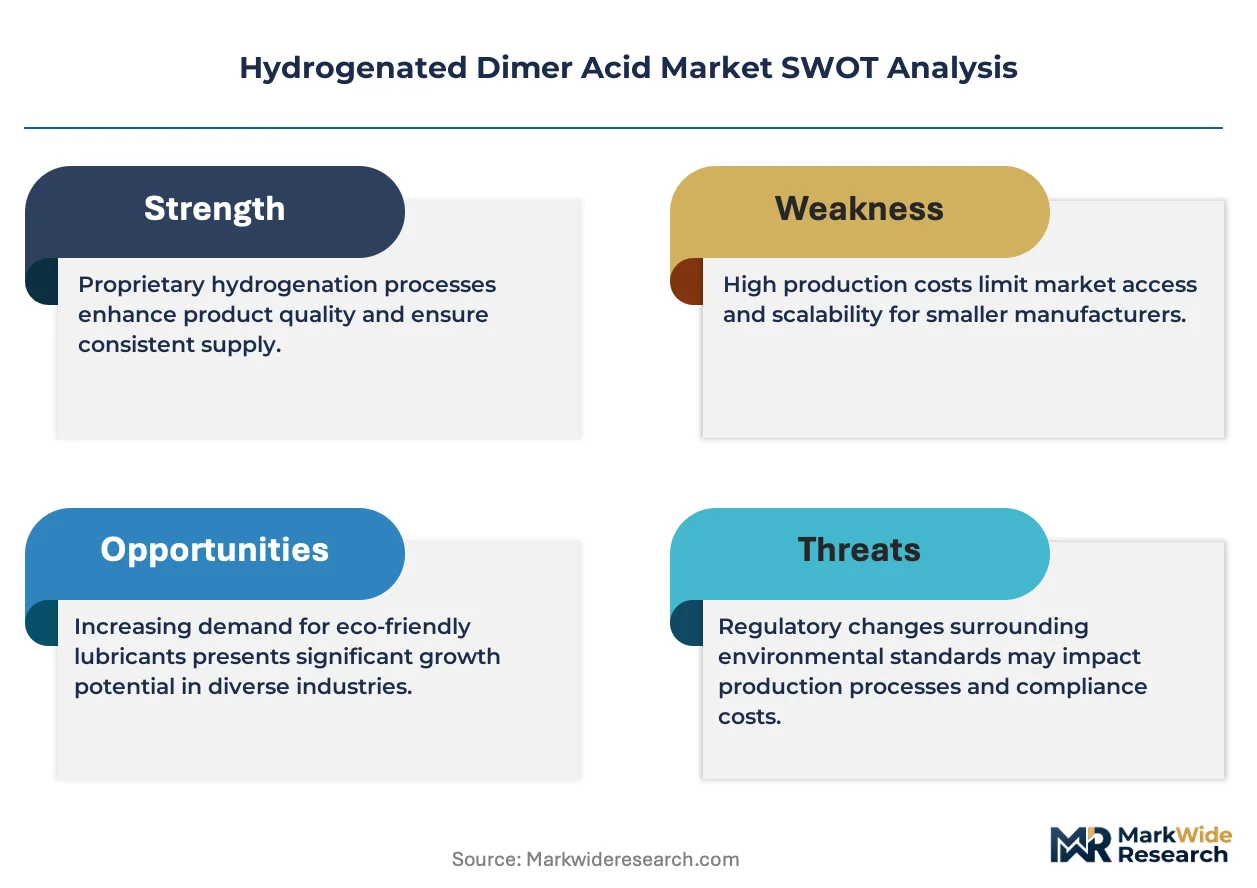
Modular formulation kits for polyamide hot-melt adhesives is recalibrating how buyers evaluate total cost of ownership across specification tiers. Emery Oleochemicals leverages integrated oleochemical refining from palm and soy feedstocks to secure upstream control over dimer acid precursors. Croda International Plc differentiates through bio-based certification programs that align with EU Green Deal procurement mandates. Kraton Corporation anchors its position via specialty polymer compounding expertise that bridges dimer acid intermediates to finished adhesive systems.
Hydrogenated dimer acid is a C36 dicarboxylic acid produced through catalytic hydrogenation of dimerized unsaturated fatty acids, yielding a saturated structure with melting points typically between 95°C and 105°C depending on hydrogenation depth and feedstock origin. The material serves primarily as a building block for polyamide resins, synthetic lubricants, and corrosion inhibitors where oxidative stability and hydrophobicity prove critical. Technical grade products occupy the dominant volume position due to broad compatibility with industrial polyamide formulations, while high purity grades command premium positioning in personal care and pharmaceutical applications where residual unsaturation must fall below stringent thresholds. Surfactant applications represent the fastest-expanding demand channel as formulators substitute petrochemical ethoxylates with bio-derived alternatives.
REACH registration requirements and ECHA substance evaluation protocols govern dimer acid import and formulation across European coatings and adhesive supply chains, elevating documentation burdens for non-EU producers. EPA TSCA Section 5 premanufacture notifications and FDA food contact substance determinations shape market access parameters for US-bound technical and pharmaceutical grades. Stakeholders must monitor evolving bio-based content verification standards and carbon border adjustment mechanisms that will restructure competitive cost positions between Southeast Asian palm-derived and North American soy-derived supply bases.
Market Dynamics
Feedstock provenance is splitting the competitive landscape between Southeast Asian palm-derived and North American soy-derived supply bases, with carbon accounting rules under the EU Green Deal forcing buyers to requalify suppliers against Scope 3 emission thresholds.
Growth Catalysts
- Polyamide resin demand in automotive underbody coatings:OEM specifications for corrosion resistance and oxidative stability are pulling hydrogenated dimer acid into high-performance coating formulations as a critical building block.
- REACH registration compliance:ECHA substance evaluation protocols are consolidating supplier bases by elevating documentation burdens for non-EU producers, advantaging registered incumbents with established dossiers.
- Bio-based surfactant substitution:Formulators are replacing petrochemical ethoxylates with hydrogenated dimer acid derivatives in personal care and industrial cleaning applications where hydrophobicity and mildness converge.
Market Restraints
- Crude tall oil and vegetable oil feedstock volatility:Price swings in palm and soy precursors transmit directly to dimer acid production economics, compressing margin predictability for non-integrated producers.
- Hydrogen supply concentration in China:Catalytic hydrogenation capacity clusters around domestic refining hubs, creating geographic dependency for hydrogenated grade output.
- Performance ceiling in high-temperature lubricants:Synthetic ester alternatives demonstrate superior thermal stability above 150°C, capping penetration in aerospace and heavy-duty engine oil segments.
Strategic Opportunities
- Pharmaceutical-grade certification expansion:Residual unsaturation thresholds below 0.5% open formulation access to excipient and active pharmaceutical ingredient applications governed by FDA food contact substance determinations.
- Modular hot-melt adhesive formulation kits:Pre-configured polyamide building blocks are compressing customer R&D cycles and embedding hydrogenated dimer acid as a specified intermediate in distributor-led technical service models.
- EU Carbon Border Adjustment Mechanism alignment:Early certification against evolving bio-based content verification standards positions suppliers for preferential procurement under tightening EU Green Deal mandates.
Industry Challenges
- Catalytic hydrogenation process engineering talent scarcity:Deep expertise in selective hydrogenation of C36 dimer structures without over-hydrogenation or isomerization defects resides with a narrow cohort of specialized oleochemical engineers.
- Multi-jurisdiction registration synchronization:Parallel EPA TSCA Section 5 premanufacture notifications, FDA food contact substance determinations, and REACH dossier maintenance create compliance timeline conflicts for product line expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogenated Dimer Acid Market |
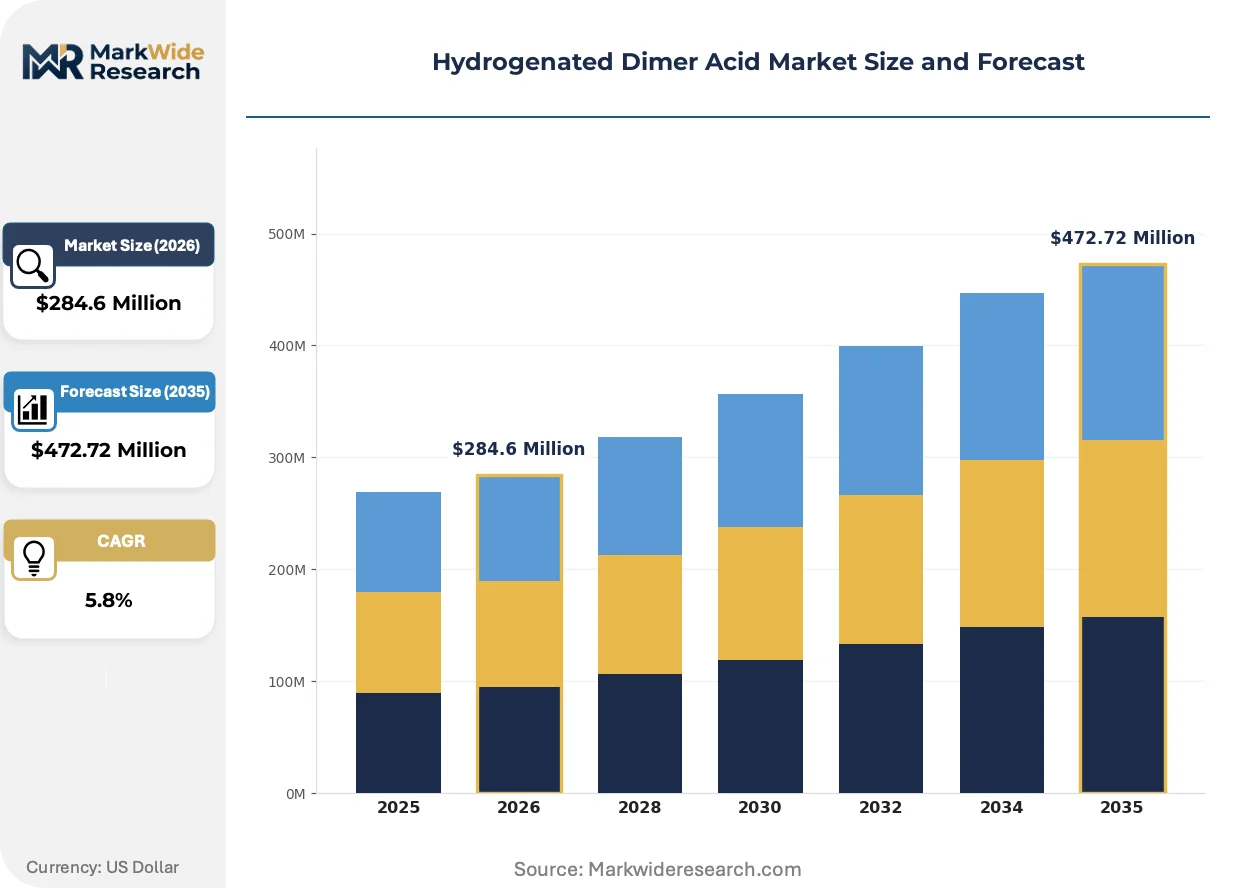
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $472.72 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Technical Grade, Pharmaceutical Grade, Industrial Grade Application: Surfactants, Adhesives, Coatings, Plastics End User: Chemical Manufacturing, Paints & Coatings, Personal Care, Food Industry Form: Liquid, Solid, Powder, Gel |
| Companies Covered | Emery Oleochemicals, Florachem Corporation, Croda International Plc, Kraton Corporation, Arkema S.A., Oleon NV, Harima Chemicals Group, Aturex Group, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogenated Dimer Acid Market Shifts & Advancements
Formulation science and regulatory compliance are converging to redefine value capture in hydrogenated dimer acid supply chains, with three distinct vectors reshaping competitive advantage.
Continuous flow hydrogenation reactor designs are electrifying process economics by enabling precise temperature and pressure control across catalytic beds. Polyamide resin producers in Germany and Japan are adopting these systems at pilot scale to reduce batch-to-batch variability in melting point specifications. The technology is electrifying capital efficiency by compressing reactor footprint and hydrogen consumption per ton of finished product.
EU Green Deal carbon accounting mandates are forcing feedstock provenance disclosure through the entire dimer acid value chain. ECHA is evaluating substance-specific carbon footprint methodologies that will differentiate palm-derived from soy-derived hydrogenated grades in procurement scoring. European coatings formulators are responding by dual-sourcing from certified sustainable supply bases to preempt border adjustment exposure.
Specification-driven procurement is fragmenting buyer-seller relationships as automotive Tier 1s demand lot-level certificates of analysis with full compositional mapping. Traditional commodity distributors are losing share to technical service providers who bundle formulation support with guaranteed property ranges. This pattern is most visible in China's Yangtze River Delta, where domestic polyamide capacity expansion has created a dense cluster of specification-intensive buyers.
Hydrogenated Dimer Acid Market Segmentation
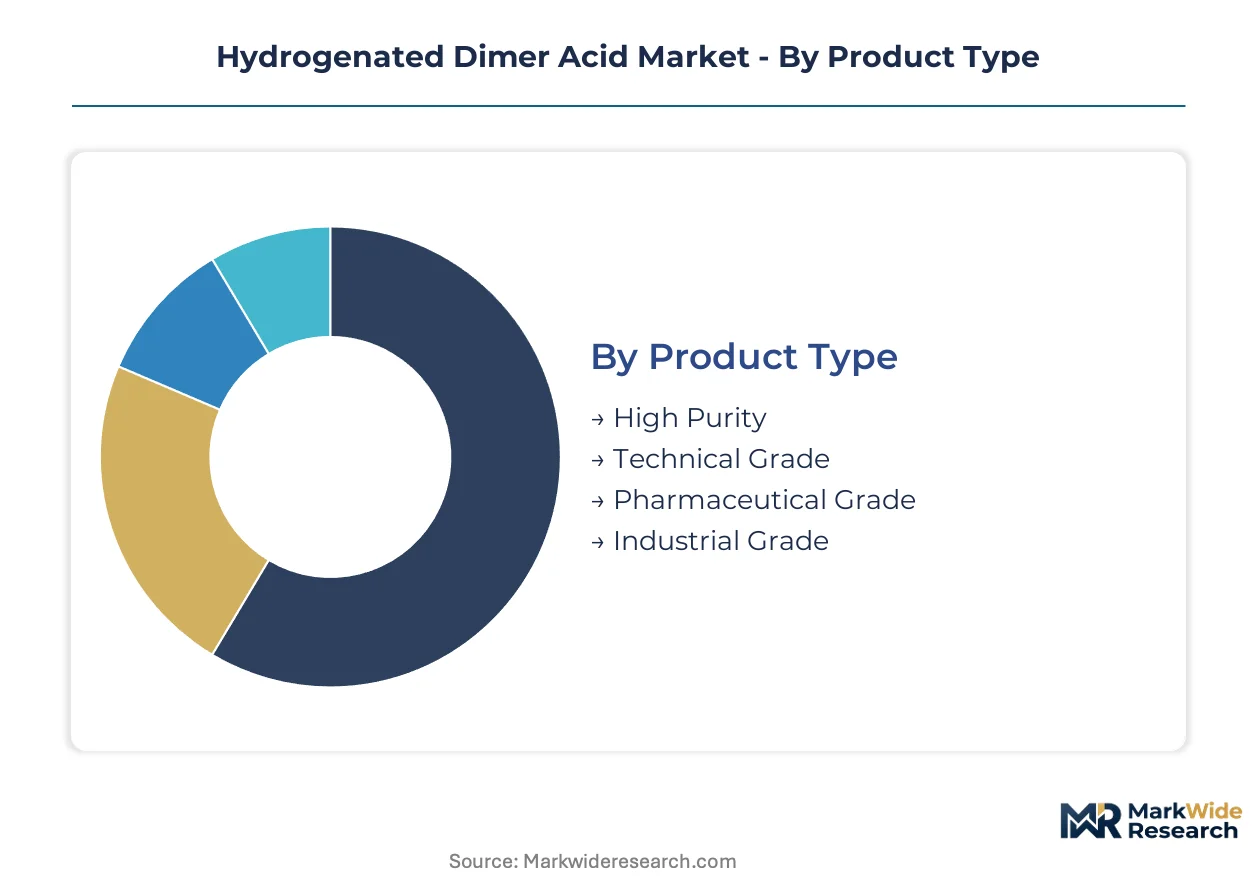
Specification tiers in hydrogenated dimer acid carry divergent regulatory burdens that reshape supplier economics. Certification requirements from FDA, ECHA, and national pharmaceutical regulators fragment the addressable market into distinct compliance-cost strata.
Product Type:
FDA food contact substance determinations and REACH registration protocols impose tiered documentation demands across purity grades, with pharmaceutical applications requiring the most intensive dossier maintenance.
- Technical Grade:Broad compatibility with industrial polyamide formulations defines this segment. Automotive underbody coating producers in Germany and Japan concentrate procurement here for corrosion-resistant formulations. REACH registration compliance elevates entry barriers for non-EU suppliers.
- High Purity:Residual unsaturation below 0.5% enables excipient and active pharmaceutical ingredient access. Personal care formulators in France and Switzerland drive specification intensity as they substitute petrochemical ethoxylates with bio-derived alternatives.
- Pharmaceutical Grade:Stringent FDA and EMA purity thresholds govern this segment.
- Industrial Grade:Standard hydrogenation depth serves cost-sensitive adhesive and coating applications.
Leading the category by volume: Technical Grade. Growing fastest: High Purity.
Application:
End-use performance requirements split the market between commodity-scale industrial buyers and specification-intensive formulators seeking oxidative stability and hydrophobicity.
- Surfactants:Bio-based substitution of petrochemical ethoxylates accelerates fastest in this channel. Industrial cleaning and personal care formulators in China's Yangtze River Delta cluster procurement around mildness and hydrophobicity convergence.
- Adhesives:Polyamide hot-melt systems dominate demand here. Modular formulation kits from German and Japanese resin producers compress customer R&D cycles and embed hydrogenated dimer acid as a specified intermediate.
- Coatings:Automotive OEM specifications for corrosion resistance pull material into high-performance underbody formulations.
- Plastics:Polyamide resin compounding serves specialty polymer applications.
Volume concentration: Adhesives. Steepest expansion trajectory: Surfactants.
End User:
Customer procurement sophistication ranges from distributor-led technical service models to direct mill-scale purchasing with lot-level certificate of analysis requirements.
- Chemical Manufacturing:Integrated oleochemical refiners and specialty polymer compounders anchor this segment. Emery Oleochemicals and Kraton Corporation leverage captive dimer acid supply and formulation expertise respectively to defend position.
- Personal Care:Bio-based certification alignment with EU Green Deal mandates drives supplier selection. Croda International Plc differentiates through verified sustainable supply chain documentation.
- Paints & Coatings:Automotive Tier 1 specification intensity fragments traditional distributor relationships.
- Food Industry:FDA food contact substance determinations govern market access parameters.
Dominant buyer type: Chemical Manufacturing. Procurement intensity rising fastest: Personal Care.
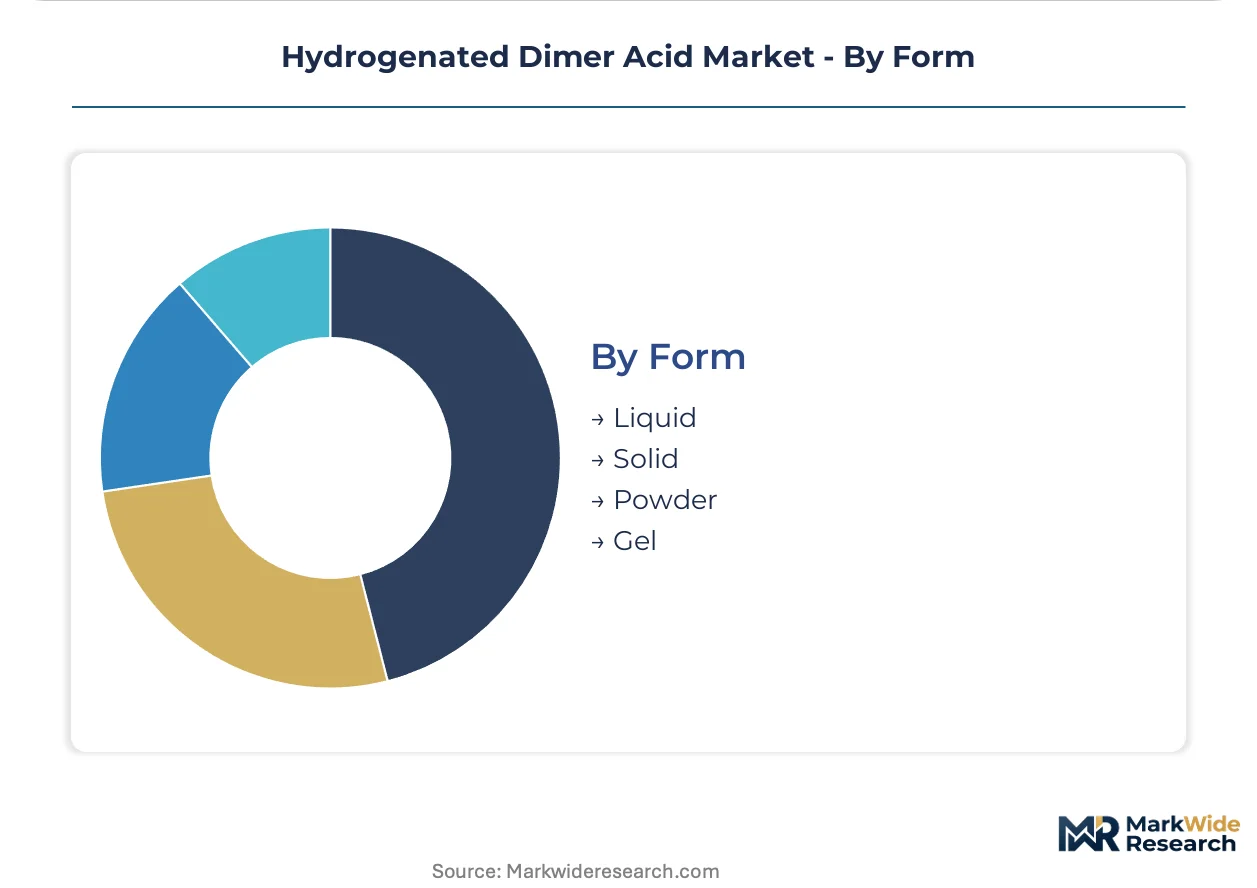
Form:
Physical state selection correlates with processing temperature requirements and downstream formulation equipment compatibility.
- Solid:Melting point specifications between 95°C and 105°C suit hot-melt adhesive compounding and polyamide resin synthesis. German and Japanese producers adopting continuous flow hydrogenation designs reduce batch-to-batch variability in this form.
- Liquid:Lower viscosity enables direct incorporation into surfactant and coating formulations without melting equipment.
- Powder:Surface area advantages serve specific dispersion requirements.
- Gel:Thixotropic properties address niche personal care and pharmaceutical applications.
Primary shipment form: Solid. Fastest adoption shift: Liquid for surfactant integration efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate hydrogenated dimer acid demand through polyamide capacity expansion and local refining investments. Germany's Ruhr industrial corridor anchors European technical-grade supply chains under REACH compliance mandates. The United States Gulf Coast petrochemical complex sustains soy-derived feedstock processing for North American adhesive markets.
China
Domestic polyamide resin producers in Jiangsu and Zhejiang provinces drive procurement volume through automotive underbody coating specifications. SAMR's evolving bio-based content verification standards tighten supplier qualification protocols. The Yangtze River Delta cluster concentrates specification-intensive buyers demanding lot-level certificates of analysis with full compositional mapping.
Germany
Automotive OEM corrosion resistance specifications pull technical-grade material into high-performance coating formulations across Bavaria and Baden-Württemberg. ECHA substance evaluation protocols under REACH elevate documentation burdens for non-EU producers. Continuous flow hydrogenation reactor designs at pilot scale in North Rhine-Westphalia reduce batch-to-batch variability in melting point specifications.
United States
Polyamide hot-melt adhesive compounders in Texas and Louisiana anchor demand for industrial-grade hydrogenated dimer acid. EPA TSCA Section 5 premanufacture notifications govern market access for technical and pharmaceutical grades. The Gulf Coast petrochemical corridor processes soy-derived feedstocks into dimer acid precursors with captive hydrogen supply integration.
Japan
Specialty polymer compounders in Kansai and Chubu regions specification-drive procurement for synthetic lubricant applications. METI's carbon accounting guidelines align with EU Green Deal procurement mandates for bio-based certification. Nagoya's automotive Tier 1 cluster fragments traditional distributor relationships through direct mill-scale purchasing with technical service bundling.
France
Personal care formulators in Île-de-France substitute petrochemical ethoxylates with high-purity hydrogenated dimer acid derivatives. ANSM pharmaceutical-grade certification requirements open excipient applications governed by EMA purity thresholds. The Paris-Saclay biocluster concentrates bio-based surfactant R&D driving mildness and hydrophobicity convergence.
Hydrogenated Dimer Acid Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across specification tiers. The vendor base stratifies between integrated oleochemical refiners controlling upstream feedstock supply and downstream formulation specialists bridging intermediates to finished systems. Three archetypes dominate: backward-integrated palm and soy processors, specialty polymer compounders with captive resin expertise, and technical service providers bundling formulation support with guaranteed property ranges. Competitive moves concentrate on strategic partnerships for carbon certification alignment and capacity expansion in hydrogenation reactor infrastructure.
Among integrated oleochemical refiners, Emery Oleochemicals and Oleon NV exemplify upstream control over dimer acid precursors through captive vegetable oil processing. Croda International Plc occupies a position within the certification-focused tier, aligning supplier selection with EU Green Deal bio-based mandates. Kraton Corporation anchors the specialty polymer compounding segment, bridging dimer acid intermediates to finished adhesive systems through formulation expertise.
| Leading Market Players |
|---|
| Emery Oleochemicals |
| Florachem Corporation |
| Croda International Plc |
| Kraton Corporation |
| Arkema S.A. |
| Oleon NV |
| Harima Chemicals Group |
| Aturex Group |
| BASF SE |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap oleochemical refiners in Malaysia and Indonesia anchor feedstock supply, translating plantation proximity into pricing discipline that resists spot-market volatility from palm and soy oil futures.
Pricing Analysis
Margin tightening in technical-grade material reflects hydrogen supply cost escalation at Chinese refining hubs. Contract-based long-term offtake dominates procurement for automotive coating producers seeking batch-to-batch consistency. Price differentiation separates pharmaceutical-grade certification holders from industrial-grade commodity suppliers. Chemical manufacturers demonstrate lowest price sensitivity due to captive formulation value capture, while distributor-led buyers face highest cost-down pressure from specification-intensive automotive Tier 1s.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale polyamide resin demand from Germany's automotive coating producers, while technical service providers bundle formulation support for mid-tier adhesive compounders. Supply concentrates in China, Malaysia, and Indonesia for hydrogenation capacity and palm-derived feedstock respectively. Catalytic hydrogenation depends on specialized reactor engineering talent concentrated in German and Japanese pilot facilities. Single-source vulnerability emerges from hydrogen supply clustering around Chinese domestic refining hubs. Distribution runs through certified sustainable supply bases to preempt EU Carbon Border Adjustment Mechanism exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive vegetable oil processing and downstream polyamide formulation expertise defines the vertical-integration race, with feedstock provenance certification emerging as the decisive ownership lever.
For Market Incumbents: Anticipate specification-driven procurement fragmentation by embedding lot-level compositional mapping into technical service bundles. Secure REACH dossier maintenance advantages against emerging entrants lacking ECHA substance evaluation experience. Prioritize continuous flow hydrogenation reactor investments to compress batch-to-batch variability for German and Japanese automotive coating producers. For New Entrants and Emerging Players: EU Green Deal bio-based certification mandates in Europe open a window for palm-derived supply bases with verified sustainable chain-of-custody documentation. Target personal care surfactant substitution in France's Paris-Saclay biocluster where petrochemical ethoxylate displacement accelerates fastest. Lead with carbon accounting transparency to differentiate against incumbent soy-derived supply bases facing Scope 3 emission threshold pressure. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty polymer compounders with captive resin expertise in China's Yangtze River Delta where domestic polyamide capacity expansion concentrates demand. Long-term viability hinges on hydrogenation reactor infrastructure ownership rather than tolling arrangements. Monitor SAMR bio-based content verification standard evolution as inflection indicator for supplier qualification protocol tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Processing | Captive palm and soy supply secures margin control against vegetable oil futures volatility. |
| Continuous Flow Hydrogenation Capacity Expansion | German and Japanese pilot-scale adoption reduces melting point variability for automotive coatings. |
| EU Green Deal Certification Alignment | Early carbon accounting verification positions suppliers for preferential procurement under tightening mandates. |
| Modular Hot-Melt Adhesive Formulation Kits | Pre-configured polyamide building blocks compress customer R&D cycles and embed specification lock-in. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA purity thresholds open excipient applications with residual unsaturation below 0.5%. |
Research Methodology
Document review covered customs trade data, ECHA registration dossiers, and SEC filings from integrated oleochemical refiners, complemented by interviews with polyamide resin plant managers, automotive Tier 1 procurement leads, and personal care formulation directors. Bottom-up volume estimates triangulated against top-down industry association data from ACC and Cefic.
Historical capacity utilization patterns cross-referenced with panel input from hydrogenation reactor engineering specialists shaped the analytical framework across the projection horizon. Segmentation modeling incorporated grade tier, end-use industry, and regional production hub dimensions. CAGRs derived from elasticity-adjusted demand curves for surfactant substitution and automotive coating specification intensity.
Caveats apply where feedstock price volatility, hydrogen supply concentration in China, or REACH dossier maintenance timeline disruptions could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Sulfur Chemicals Market
Chemicals
Dicaprylyl Carbonate Market
Chemicals
Thiourea Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
Ferric Chloride Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
Africa Sodium Cyanide Market
Chemicals
Malonic Acid Market
Chemicals
Global N-Butanol Market
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market
Chemicals
Asia-Pacific Non-Phthalate Plasticizers Market
Chemicals
Triethylaluminum Market
Chemicals
Asia Pacific Waterproofing Chemicals Market
Chemicals
India Anhydrous Hydrogen Fluoride Market
Chemicals
Diethyl Sulfate Market
Chemicals
Global Phosphorus Trichloride Market