
 Solder Flux Market | 2026-2036
Solder Flux Market Size, Share, and Industry Trends Forecast 2026-2036
Solder Flux Market Intelligence
Automotive electronics manufacturing is repositioning solder flux procurement toward no-clean and low-residue formulations that withstand higher thermal profiles during reflow. Henkel AG & Co. KGaA leverages its adhesives heritage to anchor automotive module assembly lines with specialized flux chemistry. Indium Corporation differentiates through indium-bearing flux systems for high-reliability applications. Senju Metal Industry Co., Ltd. dominates Asian supply chains with integrated solder paste and flux portfolios.
Solder flux comprises chemical agents—typically rosin, resin, or synthetic activator bases dissolved in solvents—that reduce metal oxide surfaces during soldering to enable wetting and joint formation; activator content, halide classification, and solids percentage determine performance across temperature ranges and residue requirements. No-clean formulations lead volume consumption in consumer electronics assembly where post-process cleaning adds cost, while water-soluble variants retain strong positions in military hardware and aerospace systems demanding ionic cleanliness verification. Paste form factors capture the largest share of electronics OEM demand due to compatibility with stencil printing and surface-mount technology lines.
REACH in Europe and RoHS directives constrain halogenated activator use, pushing reformulation toward organic acid and low-activator synthetic bases. The EPA and OSHA in the United States enforce workplace exposure limits on volatile organic compounds in liquid flux handling, shaping regional product availability and packaging formats. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's chemical footprint requirements, as these frameworks will determine which flux chemistries retain market access and which face phase-out timelines.
Market Dynamics
The solder flux market pivots on the collision between automotive electrification's thermal demands and tightening chemical restrictions across major manufacturing jurisdictions. No-clean flux formulations now face pressure to perform at higher reflow temperatures while maintaining compliance with evolving activator limits.
Growth Catalysts
- Automotive Module Assembly:Electric vehicle power electronics and advanced driver-assistance systems require flux systems that withstand extended thermal profiles above 260°C during lead-free reflow processes.
- REACH Reformulation Deadlines:ECHA's tightening restrictions on halogenated activators are forcing manufacturers toward organic acid and synthetic base alternatives that retain wetting performance.
- PCB Cluster Concentration:China's Guangdong and Jiangsu provinces host dense surface-mount technology lines that consume paste and liquid flux at scale unmatched elsewhere.
Market Restraints
- Rosin Supply Volatility:Gum rosin feedstock prices fluctuate with pine harvest cycles in Brazil and Indonesia, compressing margin stability for natural-resin formulations.
- Activator Chemistry Lock-in:Military and aerospace contractors face decade-long qualification timelines that freeze flux specifications regardless of newer compliant alternatives.
- Solvent Handling Costs:EPA workplace exposure limits on volatile organic compounds in liquid flux applications add ventilation and monitoring overhead that water-based systems avoid.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and PCB assembly are attracting contract manufacturers that require localized flux supply chains.
- Low-Temperature Alloys:Bismuth-tin and indium-bearing solder systems need specialized flux activators that activate below 180°C for temperature-sensitive substrates.
- EU Green Deal Alignment:Chemical footprint disclosure requirements favor flux suppliers with verified lifecycle data and bio-based solvent alternatives.
Industry Challenges
- Formulation Chemistry Expertise:The cross-disciplinary knowledge bridging organic chemistry, metallurgy, and surface science remains scarce as veteran formulators retire from the industry.
- Dual-Use Certification Overhead:Suppliers serving both commercial and defense segments must maintain parallel quality systems under AS9100 and IPC standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solder Flux Market |
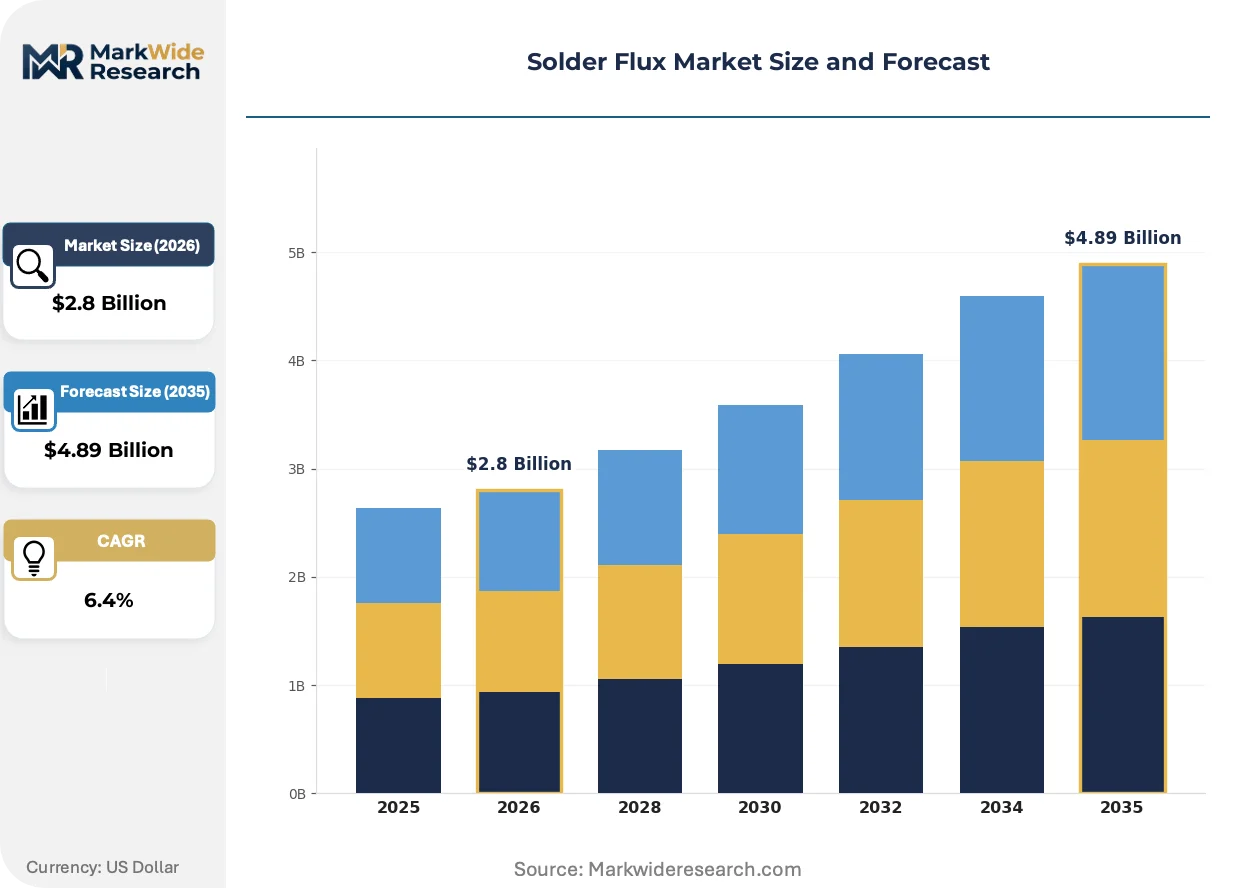
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: No-Clean, Rosin-Based, Water-Soluble, Organic, Inorganic, Activated Form: Liquid, Paste, Gel, Solid, Powder, Sheet Application: Consumer Electronics, Telecommunications Equipment, Aerospace Systems, Industrial Controls, Military Hardware, Household Appliances End User: OEMs, Contract Manufacturers, Repair Service Providers, Research Laboratories |
| Companies Covered | Henkel AG & Co. KGaA, Alpha Assembly Solutions, Indium Corporation, Shenmao Technology Inc., Senju Metal Industry Co., Ltd., Heraeus Holding GmbH, Kester, Tamura Corporation, AIM Solder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solder Flux Market Strategic Shifts & Innovations
Flux technology is bifurcating between ultra-low residue no-clean systems for high-volume consumer assembly and specialized high-activity formulations for demanding automotive and aerospace joints. This divergence is reshaping R&D allocation and manufacturing footprints across the supply base.
Synthetic resin flux chemistry is electrifying joint formation reliability under nitrogen reflow atmospheres. Automotive tier-one module suppliers are adopting these systems at accelerating rates for battery management and inverter assemblies. The technology is compressing defect rates on oxidized pad surfaces that traditional rosin formulations struggle to wet.
REACH Annex XVII restrictions on persistent organic pollutants are forcing activator redesign across European electronics manufacturing. The regulation's industrial consequence is a wholesale shift from halide-bearing to carboxylic acid activator bases. Water-soluble flux categories retain strong positions in medical device and military hardware where ionic cleanliness verification remains mandatory.
Consolidated procurement through electronic manufacturing service providers is displacing direct OEM-supplier relationships in volume electronics. Tier-one assemblers like Foxconn and Jabil now specify flux chemistry at contract level, compressing supplier counts. This concentration is most visible in China's Pearl River Delta, where three contract manufacturers account for dominant paste flux consumption.
Solder Flux Market Segmentation
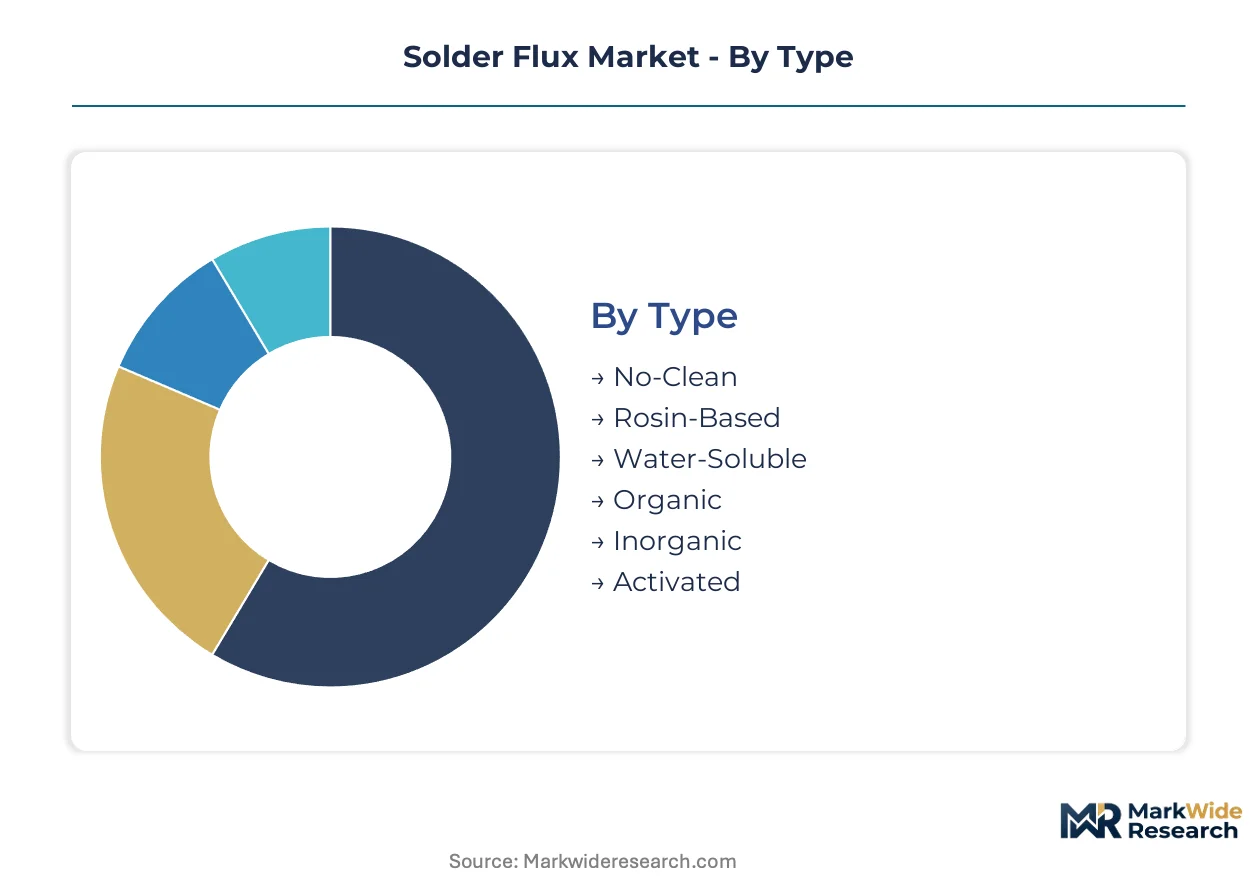
Solder flux segmentation tracks the divergence between high-volume consumer assembly and mission-critical industrial applications. Formulation chemistry, physical state, and end-use certification requirements create distinct procurement ecosystems with incompatible specification standards.
Type:
Buyers differentiate primarily by post-soldering cleaning economics and residue reliability requirements.
- No-Clean:Low-solids synthetic formulations leave benign residues that eliminate aqueous or solvent cleaning stages. Consumer electronics OEMs in China's Pearl River Delta specify these for smartphone and tablet surface-mount lines where throughput velocity dominates cost structures.
- Rosin-Based:Natural gum rosin dissolved in isopropanol or proprietary carriers provides reliable wetting across oxidized copper surfaces. Brazil and Indonesia pine harvest volatility compresses margin stability for suppliers dependent on natural feedstock.
- Water-Soluble:Organic acid activators in glycol or water vehicles enable complete ionic residue removal through deionized water rinses. Military hardware contractors mandate these for avionics where ionic contamination risks field failures.
- Organic:Synthetic resin bases with tailored activator packages bridge performance between rosin traditions and no-clean convenience. Automotive module assemblers adopt these for inverter and battery management systems requiring thermal profile flexibility.
- Inorganic:Halide-heavy mineral acid activators deliver aggressive oxide reduction for heavily tarnished substrates. Repair service providers retain limited demand for legacy equipment refurbishment where cosmetic residue concerns are secondary.
- Activated:Elevated activator concentration variants target difficult-to-solder surfaces including nickel-palladium-gold finishes. Niche demand concentrates in aerospace connector manufacturing with exotic metallization schemes.
No-Clean formulations lead volumes today; Organic types are gaining share fastest in automotive electrification applications.
Form:
Physical state selection hinges on application method capital investment and line speed requirements.
- Liquid:Low-viscosity solutions dispensed via spray, foam, or brush methods dominate through-hole and hand-soldering operations. EPA workplace exposure limits on volatile organic compounds add ventilation overhead that water-based alternatives avoid.
- Paste:Thixotropic suspensions of flux vehicle with solder powder enable stencil printing at surface-mount technology line speeds. Guangdong and Jiangsu province PCB clusters consume paste flux at scale unmatched elsewhere.
- Gel:High-viscosity formulations maintain position on vertical surfaces during preheating. Repair technicians favor these for BGA rework stations requiring precise, non-drip application.
- Solid:Bar or stick forms for dip soldering and wave fluxing of through-hole assemblies. Industrial control panel manufacturers retain limited demand for legacy equipment production.
- Powder:Dry particulate for specialized preform manufacturing and laser soldering applications. Research laboratories exploring additive electronics manufacturing represent emerging demand pockets.
- Sheet:Pre-cut film formats for uniform flux deposition on large-area substrates. Photovoltaic module interconnect applications drive thin-film solar panel assembly demand.
Paste formulations dominate electronics OEM procurement today; Gel forms are expanding most quickly in repair and rework segments.
Application:
End-use thermal profiles and reliability standards dictate activator chemistry selection.
- Consumer Electronics:Smartphone, laptop, and wearable assembly lines prioritize no-clean formulations that eliminate post-reflow cleaning capital. Foxconn and Pegatron procurement specifications set chemistry standards across their supplier bases.
- Telecommunications Equipment:Base station and router manufacturing demands flux systems surviving extended thermal cycling. 5G infrastructure deployment is accelerating paste consumption for high-density interconnect boards.
- Aerospace Systems:AS9100-qualified formulations with full ionic cleanliness verification documentation. REACH Annex XVII halogen restrictions are forcing activator redesign across European aerospace manufacturing.
- Industrial Controls:Programmable logic controller and motor drive assembly tolerates moderate residue levels. German and Japanese automation equipment OEMs specify rosin-based formulations for through-hole legacy compatibility.
- Military Hardware:MIL-STD-202G qualification requirements freeze specifications regardless of newer compliant alternatives. Decade-long approval timelines lock contractors into established supply relationships.
- Household Appliances:White goods control board assembly represents price-sensitive volume demand. Chinese domestic appliance manufacturers drive paste flux consumption through consolidated procurement.
Consumer Electronics captures the largest application volumes; Aerospace Systems are climbing the fastest as satellite and drone production scales.
End User:
Procurement authority concentration determines supplier relationship structures.
- OEMs:Original equipment manufacturers with captive assembly operations specify flux chemistry directly. Apple and Samsung qualification programs require extensive reliability testing before supplier approval.
- Contract Manufacturers:Electronic manufacturing service providers consolidate procurement across multiple OEM programs. Jabil, Flex, and Sanmina now dictate flux specifications at contract level, compressing supplier counts.
- Repair Service Providers:Fragmented aftermarket demand for gel and liquid formats serving board-level rework. Independent technicians prioritize shelf stability and packaging convenience over bulk pricing.
- Research Laboratories:Experimental soldering and materials science exploration requiring custom formulation sampling. University and corporate R&D facilities drive small-batch specialty chemistry development.
Contract Manufacturers lead procurement volumes today; OEMs are regaining direct supplier engagement for strategic automotive programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns in solder flux track diverging regulatory enforcement intensity across manufacturing jurisdictions. Assembly lines relocate toward jurisdictions offering lower compliance costs for volatile organic compound handling and activator chemistry restrictions.
China
Guangdong and Jiangsu provinces host dense surface-mount technology clusters consuming paste and liquid flux at unmatched scale. MIIT's dual carbon goals are tightening solvent emission standards for electronics manufacturers. Shenzhen and Suzhou PCB corridors drive volume procurement through consolidated contract manufacturer specifications.
Germany
Automotive module assembly for electric vehicle power electronics demands no-clean formulations surviving thermal profiles above 260°C. ECHA's REACH Annex XVII restrictions on halogenated activators force reformulation toward carboxylic acid bases. Bavaria's automotive tier-one supplier concentration anchors specialized flux chemistry development.
United States
Military hardware contractors maintain decade-long qualification timelines freezing flux specifications regardless of newer compliant alternatives. EPA workplace exposure limits on volatile organic compounds add ventilation overhead to liquid flux handling. Texas and Arizona electronics manufacturing corridors see expanding contract manufacturer footprints.
Japan
High-reliability applications in telecommunications infrastructure and automotive electronics drive demand for indium-bearing flux systems. METI's chemical management frameworks align with REACH-equivalent substance restrictions. Chubu region automotive electronics suppliers specify synthetic resin formulations for inverter and battery management assemblies.
India
PLI scheme incentives for semiconductor and PCB assembly are attracting contract manufacturers requiring localized flux supply chains. BIS standards for electronics manufacturing chemicals are converging with RoHS-aligned substance restrictions. Karnataka and Tamil Nadu electronics manufacturing zones represent emerging demand concentration.
Solder Flux Market Key Industry Players
Portfolio diversification dominates the current landscape as suppliers bifurcate between ultra-low residue no-clean systems and specialized high-activity formulations. The vendor base separates into three tiers: multinational chemical conglomerates with adhesives heritage, specialized solder material houses with integrated paste and flux portfolios, and regional Asian suppliers serving contract manufacturer procurement. Strategic archetypes include automotive-focused formulation specialists, military-qualified heritage suppliers, and scale-driven paste manufacturers. M&A activity and geographic expansion represent the dominant competitive vectors as suppliers establish localized blending capacity near PCB clusters.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA exemplifies the adhesives-heritage archetype anchoring automotive module assembly relationships. Indium Corporation occupies a position representing specialized high-reliability material houses with indium-bearing system expertise. Senju Metal Industry Co., Ltd. sits within the integrated solder paste and flux portfolio tier dominating Asian supply chain procurement specifications.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Alpha Assembly Solutions |
| Indium Corporation |
| Shenmao Technology Inc. |
| Senju Metal Industry Co., Ltd. |
| Heraeus Holding GmbH |
| Kester |
| Tamura Corporation |
| AIM Solder |
| Others |
Cost & Logistics Intelligence
Lead-free reflow adoption above 260°C is compressing formulation economics while concentrating procurement power among automotive tier-one module suppliers. This thermal transition simultaneously elevates activator chemistry costs and rewards suppliers with captive resin synthesis capabilities.
Pricing Analysis
Distributor margins on liquid flux formats absorb EPA ventilation compliance overhead before reaching contract manufacturers. Three-tier pricing structure across aerospace-qualified, automotive-specified, and consumer-grade formulations reflects AS9100 certification investment and ionic cleanliness verification documentation. Cost compression in natural rosin formulations stems from Brazilian and Indonesian pine harvest volatility. Consumer electronics OEMs exhibit highest price sensitivity, while military contractors accept premiums for decade-long qualified supply security.
Supply Chain Analysis
Chemical engineering talent scarcity in Guangdong and Jiangsu provinces constrains localized blending capacity expansion despite PCB cluster demand concentration. Feedstock supply draws from Brazilian gum rosin harvests, Indonesian pine resin operations, and German synthetic resin production. Single-source vulnerability concentrates in halide-free activator precursors subject to REACH Annex XVII phase-out timelines. Distribution runs through electronic manufacturing service providers consolidating specifications across Foxconn, Jabil, and Flex procurement portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solder flux procurement is shifting toward premium no-clean formulations as automotive electrification mandates thermal profile survivability above legacy consumer-grade specifications.
For Market Incumbents: Acquire specialized activator chemistry IP to defend against organic acid reformulation mandates under ECHA REACH deadlines. Backward integration into gum rosin processing mitigates Brazilian harvest volatility squeezing natural-resin margin stability. Certification investment in AS9100 and MIL-STD-202G documentation preserves military-aerospace supply relationships against decade-long qualification lock-in. For New Entrants and Emerging Players: Direct-to-contract-manufacturer digital platforms bypass entrenched distributor relationships in India's PLI-subsidized electronics manufacturing zones. White-space concentration exists in low-temperature bismuth-tin flux activators for temperature-sensitive medical device substrates. Technical service bundling with stencil printing optimization differentiates against established paste suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional Asian blending operations lacking automotive module supplier qualifications. Five-to-ten year viability hinges on EU Green Deal chemical footprint disclosure readiness and bio-based solvent substitution pipelines. Monitor ECHA Annex XVII halogen restriction expansion timelines as inflection signals for activator chemistry obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive gum rosin processing insulates margin stability from Brazilian harvest volatility. |
| Automotive Module Supplier Qualification | Thermal profile certification above 260°C unlocks electric vehicle power electronics procurement. |
| Bio-Based Solvent Substitution | EU Green Deal chemical footprint alignment preserves market access against disclosure mandates. |
| Low-Temperature Activator Development | Bismuth-tin compatibility addresses medical device and flexible substrate assembly demand. |
| India PLI Zone Manufacturing Footprint | Karnataka and Tamil Nadu blending capacity captures contract manufacturer localization requirements. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining procurement director discussions at Foxconn and Jabil with flux formulation chemist consultations at Henkel and Indium Corporation. Secondary validation drew from ECHA REACH restriction proposals, EPA workplace exposure limit filings, MIIT dual carbon policy documents, and SEC 10-K chemical segment disclosures. Bottom-up paste volume estimates from Guangdong and Jiangsu PCB clusters triangulated against top-down automotive electronics content-per-vehicle models.
Segment-weighting applied formulation type, physical form factor, and end-use certification tier as primary dimensions across the projection horizon. CAGRs derived from automotive electrification thermal profile adoption curves, REACH reformulation deadline impacts on activator chemistry transitions, and India PLI scheme contract manufacturer capacity buildouts. Modeling incorporated rosin feedstock price elasticity, nitrogen reflow atmosphere penetration rates, and military qualification timeline inertia.
REACH Annex XVII expansion scope, Brazilian pine harvest disruption frequency, and automotive OEM direct procurement reversal are the dominant revision risks to forecast assumptions. Practitioners should monitor ECHA restriction proposal comment periods, Indonesian forestry export policy shifts, and tier-one module supplier vertical integration announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Methylene Chloride Market
Chemicals
Global Bleaching Agents Market
Chemicals
Bakers Ammonia Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Japan Methanol Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Aerosol Insecticides Market
Chemicals
Hydrophobing Agents Market
Chemicals
Elemental Fluorine Market
Chemicals
Precious Metal Plating Chemicals Market
Chemicals
Morpholine Market
Chemicals
Deicing Fluid Market
Chemicals
Trimethylamine Market
Chemicals
Methylamines Market
Chemicals
Middle East and Africa Construction Chemicals Market