
 Italy Laboratory Chemicals Market | 2026-2036
Italy Laboratory Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Laboratory Chemicals Market Foresight
Italy is rewriting supply dynamics for laboratory chemicals across Southern Europe. Merck KGaA leverages its German manufacturing base to anchor reagent distribution throughout the peninsula. Thermo Fisher Scientific Inc. competes through specialized media formulations serving biotechnology customers in the Po Valley. DASIT Group SPA dominates domestic instrumentation channels and extends its reach into adjacent consumables.
Italy laboratory chemicals encompass reagents, solvents, standards, and buffers formulated to precise purity grades such as ACS, analytical, or pharmacopeial specifications for analytical and research procedures. These substances enable qualitative detection, quantitative measurement, and sample preparation across industrial and academic settings. Reagents command the largest revenue pool due to recurring consumption in clinical diagnostics and quality control workflows. Solvent demand is accelerating fastest among biotechnology applications as protein crystallization and chromatography protocols expand. Academic institutions represent a mature end-user segment with stable but price-sensitive procurement patterns.
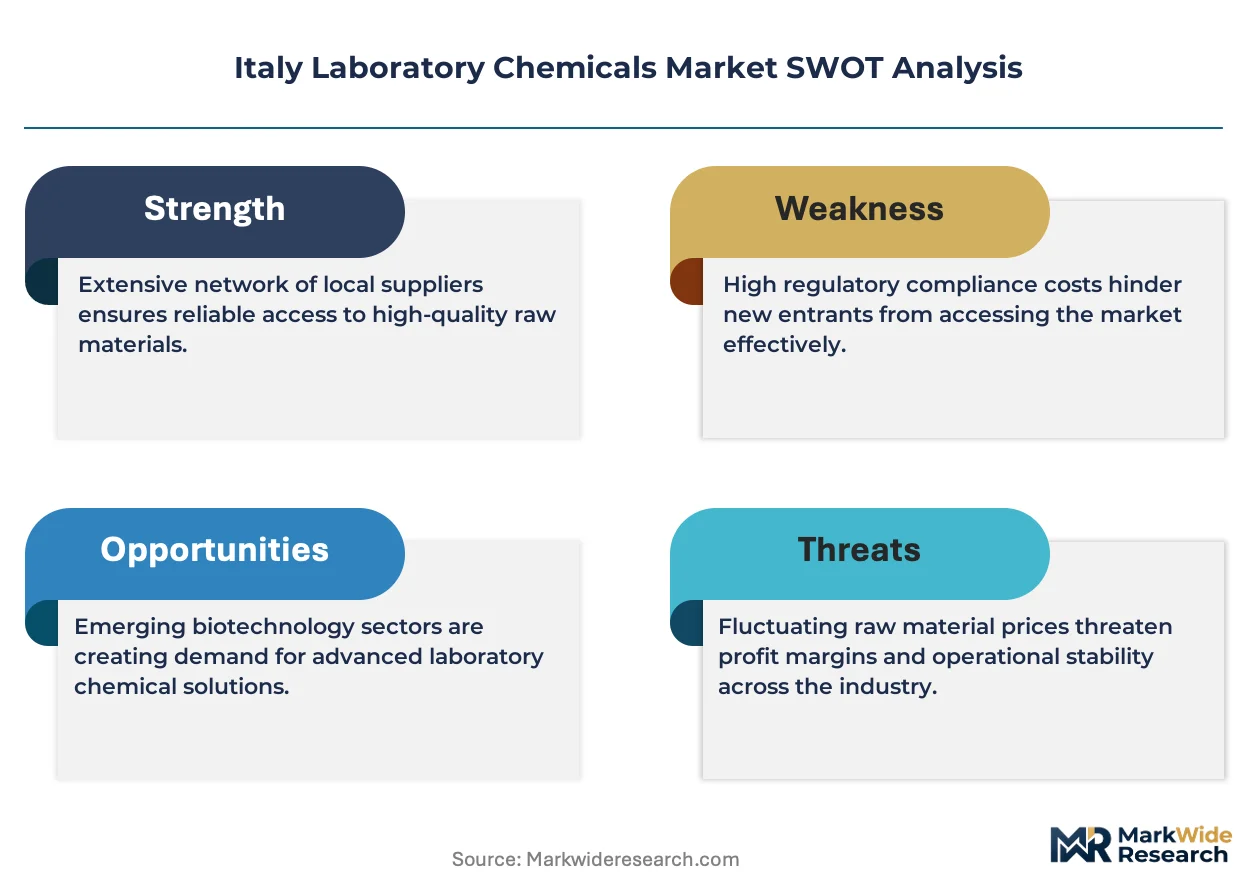
REACH registration requirements and the EU Green Deal framework constrain solvent formulations and mandate hazard communication standards across the Italian supply chain. BIS compliance for imported analytical standards adds a secondary layer of product verification for distributors serving quality control laboratories. Stakeholders must monitor how ECHA substance evaluation timelines and Italy's national chemical agency enforcement priorities reshape import sourcing strategies for critical reagent categories.
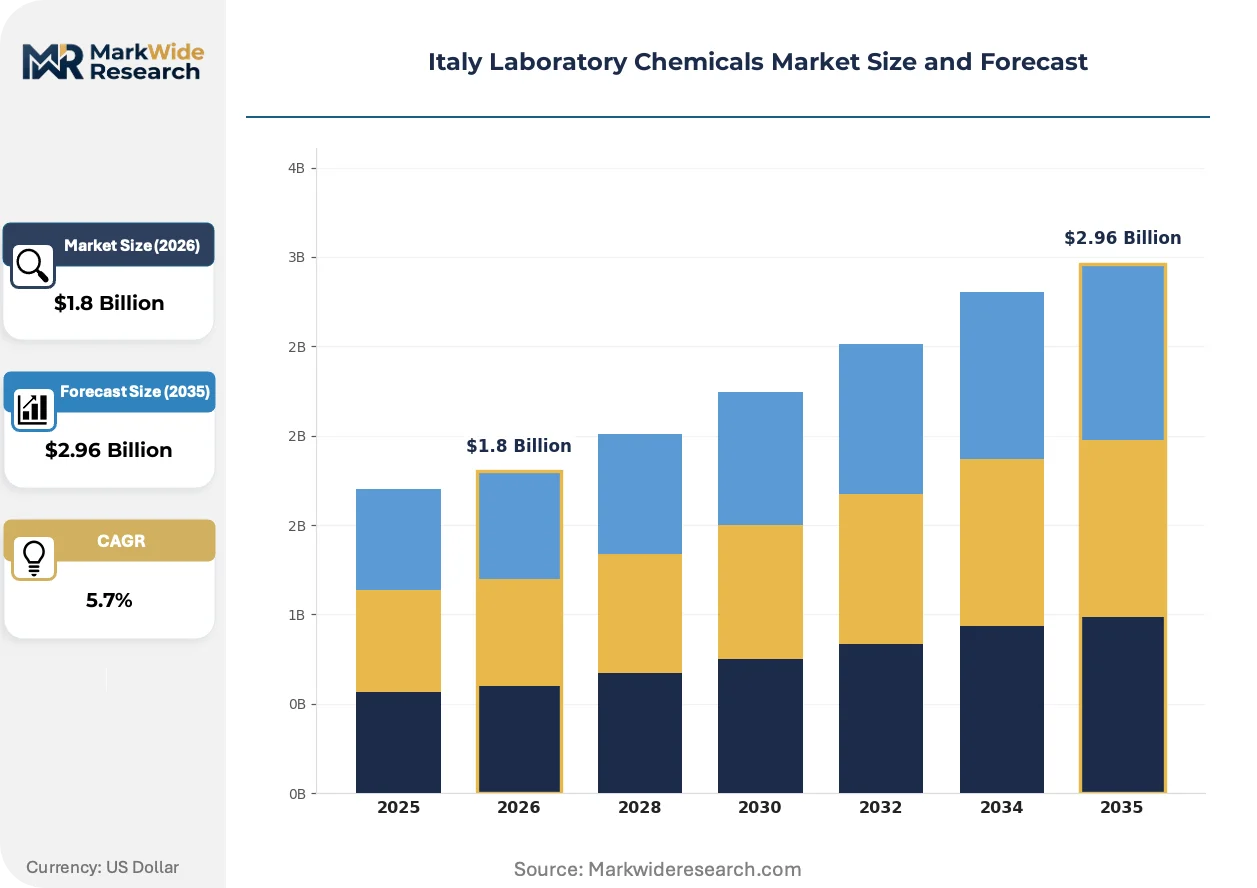
Market Dynamics
REACH substance evaluation timelines and Italy's national chemical agency enforcement priorities are compressing import lead times for critical reagent categories while pharmaceutical manufacturers in Lombardy accelerate analytical testing capacity.
Growth Catalysts
- EU Green Deal solvent mandates:Tightening purity specifications for imported solvents are forcing domestic distributors to upgrade purification infrastructure, creating captive demand for premium-grade formulations.
- Biotechnology protein crystallization protocols:Chromatography solvent consumption is accelerating fastest among Milan-Turin corridor biotech clusters as structural biology research expands.
- Lombardy life sciences corridor concentration:Pharmaceutical quality control laboratories in Milan's industrial belt generate recurring reagent demand through high-throughput analytical workflows.
Market Restraints
- German manufacturing dependency:Peninsula-wide distribution relies heavily on cross-Alpine supply chains from Bavarian chemical hubs, exposing buyers to freight cost volatility and border clearance friction.
- ACS-grade solvent cost structure:Energy-intensive fractional distillation required for analytical purity grades amplifies input cost sensitivity to natural gas pricing.
- BIS verification layering:Secondary product verification requirements for imported analytical standards add compliance overhead and extend procurement cycles for quality control laboratories.
Strategic Opportunities
- Po Valley biotechnology expansion:Specialized cell culture media formulations for mammalian expression systems remain underpenetrated outside Milan's core cluster.
- ECHA substance evaluation tailwinds:Accelerated SVHC identification creates first-mover advantage for domestic distributors pre-registering alternative reagent formulations.
- Direct-to-laboratory digital channels:E-procurement platforms serving Turin and Bologna academic institutions bypass traditional distribution markups.
Industry Challenges
- Analytical chemist talent scarcity:Northern Italy's quality control laboratories face recruitment gaps for ICP-MS and HPLC method development specialists.
- ISO 17025 certification timelines:Reference material producers encounter extended audit backlogs from Italian accreditation bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Laboratory Chemicals Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Solvents, Standards, Buffers Application: Biotechnology, Pharmaceuticals, Environmental Testing, Food & Beverage End User: Research Labs, Academic Institutions, Quality Control, Clinical Diagnostics Packaging Type: Bottles, Drums, Vials, Packs |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific Inc., GE Healthcare, DASIT Group SPA, ITW Reagents Division, Avantor Inc., BD, BIOMÉRIEUX, BiosYnth s.r.l., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Laboratory Chemicals Market Shifts & Advancements
Digital inventory management and green chemistry formulation standards are restructuring how Italian laboratories source and consume analytical reagents across the peninsula.
Pre-mixed buffer tablets and lyophilized reagent formats are collapsing traditional liquid reagent supply chains. Pharmaceutical quality control departments in Milan are adopting these formats fastest, eliminating cold-chain logistics and reducing storage footprint. The shift is collapsing distributor margin structures built on volume solvent sales.
REACH authorization requirements for SVHC-listed solvents are tightening substitution timelines across Italian industrial laboratories. The regulation forces reformulation of histology and extraction protocols previously dependent on legacy chlorinated solvents. Academic institutions in Bologna and Padua are responding by consolidating purchasing through pre-qualified green chemistry catalogs.
Consolidated e-procurement platforms serving the Turin-Polytechnic research corridor are unbundling after-sales technical support from reagent pricing. Small and mid-sized analytical laboratories now source consumables through digital marketplaces while purchasing application expertise separately. This bifurcation is most visible among food safety testing laboratories in Emilia-Romagna seeking transparent unit economics.
Italy Laboratory Chemicals Market Segmentation
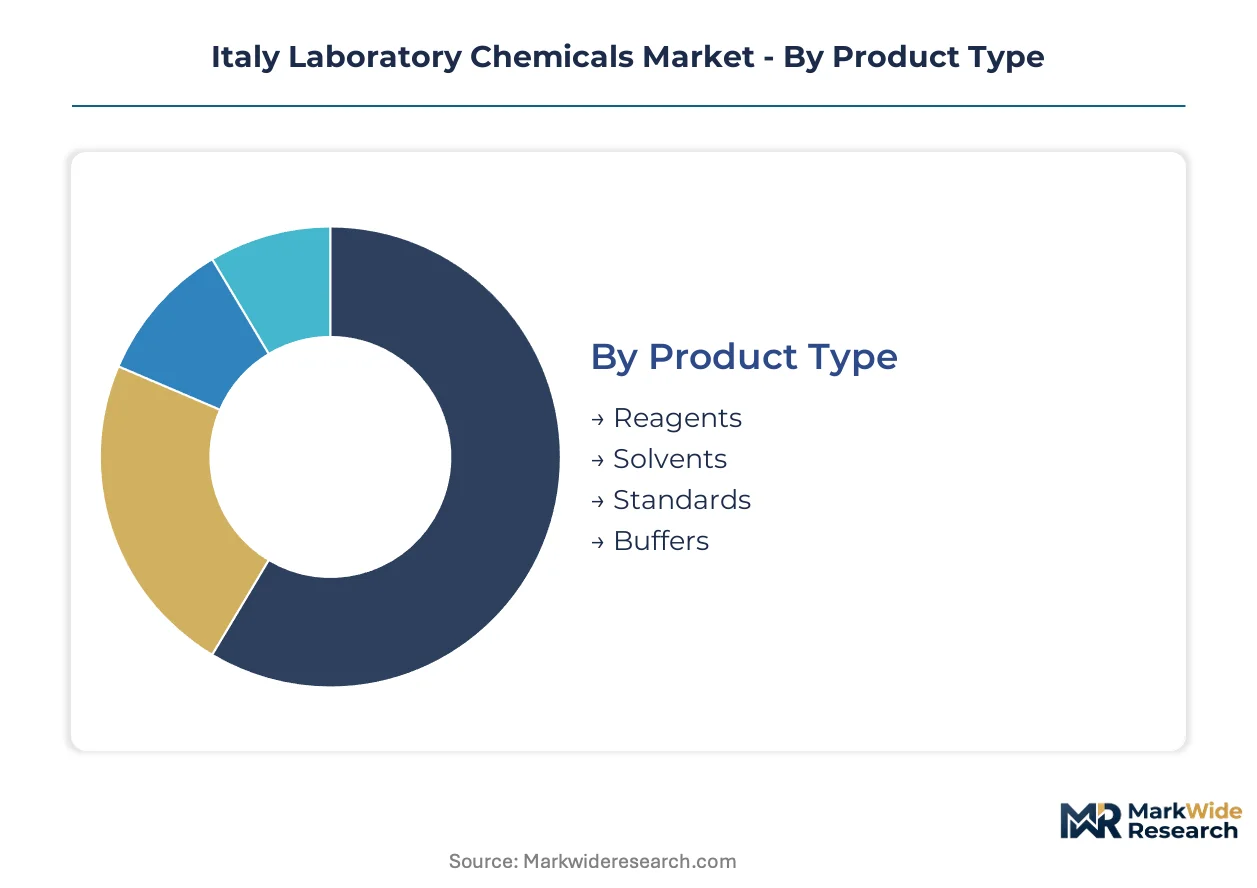
Segmentation in Italy's laboratory chemicals market reveals how procurement patterns diverge across purity grades, application protocols, and packaging formats. Understanding these fault lines enables suppliers to align inventory positioning with the distinct technical and logistical requirements of Milan's pharmaceutical belt versus Bologna's academic clusters.
Product Type:
After-sales technical support intensity varies sharply across product categories, with reagents requiring method development consultation while solvents demand primarily logistics coordination.
- Reagents:Compounds formulated for qualitative detection and quantitative measurement in analytical workflows. Demand concentrates in Lombardy's quality control laboratories where pharmaceutical manufacturers run high-throughput HPLC and ICP-MS protocols; recurring consumption patterns dominate procurement calendars.
- Solvents:ACS-grade and chromatography-purity liquids for sample preparation and mobile phase applications. Biotechnology clusters in the Milan-Turin corridor are expanding protein crystallization operations, driving fastest volume expansion among all product categories.
- Standards:Certified reference materials for instrument calibration and method validation. BIS verification requirements add compliance overhead for distributors serving quality control laboratories.
- Buffers:pH-stabilized aqueous solutions for biological sample handling. Pre-mixed tablet formats are displacing traditional liquid formulations in academic institutions seeking reduced cold-chain dependency.
Reagents hold the largest share; momentum sits with solvents.
Application:
Cost tier differentiation separates premium-grade formulations for regulated pharmaceutical environments from economy-grade alternatives serving routine environmental monitoring.
- Biotechnology:Cell culture media, protein purification reagents, and chromatography solvents for mammalian expression systems. Specialized formulations for structural biology research are expanding fastest in Turin's biotech corridor.
- Pharmaceuticals:Pharmacopeial-grade reagents and solvents for active pharmaceutical ingredient testing. Milan's industrial belt generates concentrated demand through mandatory release testing protocols.
- Environmental Testing:Analytical standards and extraction solvents for water and soil contamination analysis. REACH compliance timelines are tightening substitution requirements for legacy chlorinated solvents.
- Food & Beverage:Pesticide residue standards and mycotoxin detection reagents. Emilia-Romagna testing laboratories are consolidating procurement through pre-qualified green chemistry catalogs.
Pharmaceuticals commands the dominant revenue position; biotechnology is climbing the fastest.
End User:
Customer type determines volume scale and price sensitivity, with quality control operations purchasing at tenfold the scale of individual academic laboratories.
- Research Labs:Discovery-oriented facilities requiring specialized reagents for novel method development. Padua's life sciences institutes are adopting lyophilized formats to reduce storage footprint.
- Academic Institutions:University laboratories with stable but price-sensitive procurement patterns. Bologna and Turin Polytechnic corridors are migrating procurement to digital marketplaces that unbundle technical support from product pricing.
- Quality Control:Industrial laboratories performing batch release testing and regulatory compliance verification. Lombardy pharmaceutical manufacturers are scaling analytical testing capacity fastest.
- Clinical Diagnostics:Hospital and commercial laboratories running high-frequency diagnostic assays. Recurring reagent consumption supports long-term supply agreements with distributors.
Quality Control holds the largest share; momentum sits with Clinical Diagnostics.
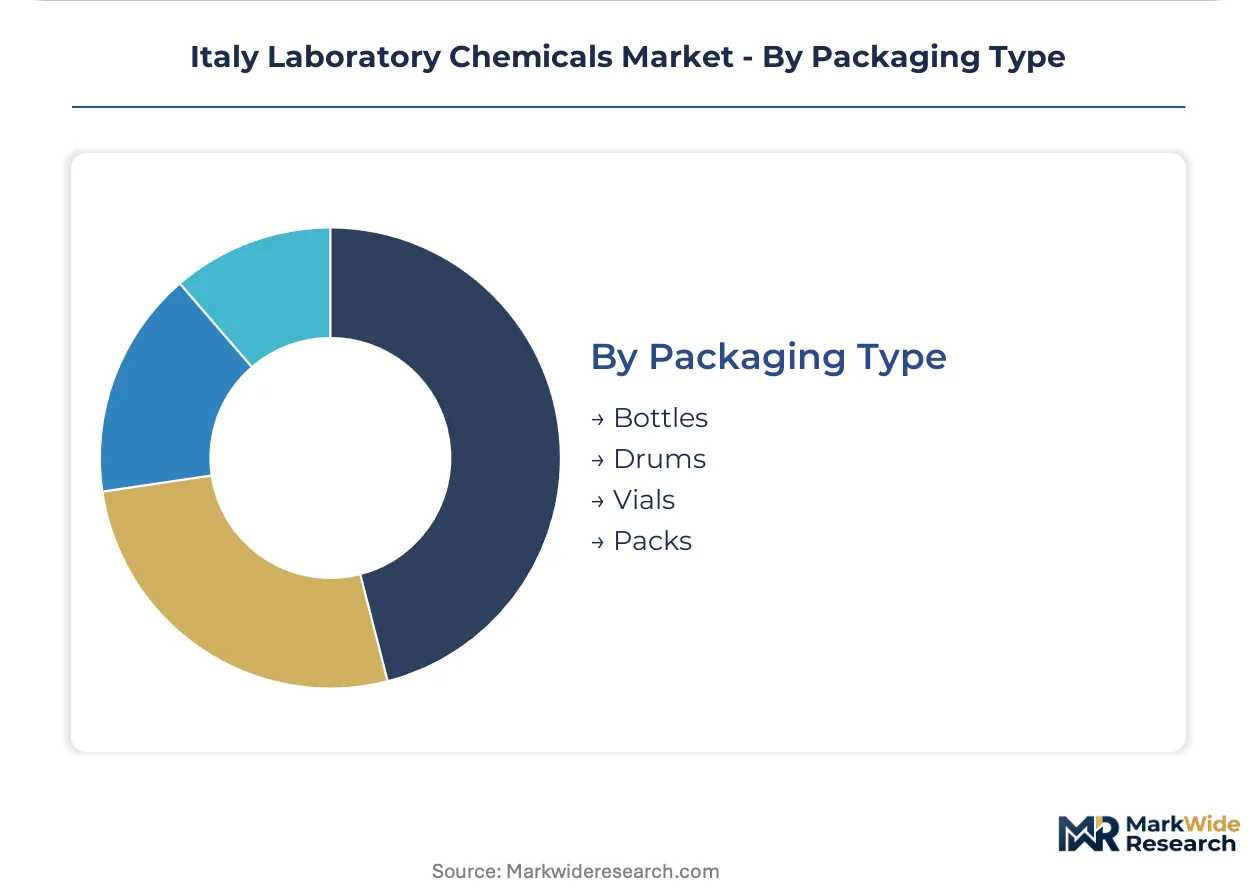
Packaging Type:
Supply concentration in bottling infrastructure near Milan determines lead time advantages for liquid formats versus solid alternatives.
- Bottles:Standard amber and clear glass containers for routine reagent and solvent distribution. Milan-area distributors maintain regional bottling capacity for fastest turnaround on high-rotation SKUs.
- Drums:Bulk liquid containment for industrial-scale solvent consumption. Energy-intensive fractional distillation for ACS grades amplifies cost sensitivity to natural gas pricing.
- Vials:Small-volume sealed containers for reference standards and precious reagents. Pre-certified vial formats reduce contamination risk in pharmaceutical quality control workflows.
- Packs:Pre-configured assortments and tablet-based formats for simplified inventory management. Pharmaceutical quality control departments in Milan are adopting these formats fastest.
Bottles hold the largest share; packs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-Alpine supply chains from Bavarian chemical hubs dominate Italian laboratory chemical distribution, with Lombardy-based distributors maintaining regional bottling capacity for fastest turnaround on high-rotation SKUs.
Lombardy
Milan's pharmaceutical belt generates concentrated demand for pharmacopeial-grade reagents through mandatory batch release testing protocols. REACH substance evaluation timelines compress import lead times for critical reagent categories. Quality control laboratories in the city's industrial corridor are scaling analytical testing capacity fastest among Italian sub-regions.
Piedmont
Turin's biotechnology corridor drives accelerating chromatography solvent consumption for protein crystallization and structural biology research. EU Green Deal solvent mandates force reformulation of legacy extraction protocols. Specialized cell culture media formulations for mammalian expression systems remain underpenetrated outside the core Milan-Turin cluster.
Emilia-Romagna
Food safety testing laboratories in this region consolidate procurement through pre-qualified green chemistry catalogs responding to REACH authorization requirements. BIS verification requirements add compliance overhead for imported analytical standards. Bologna's academic institutions are migrating procurement to digital marketplaces that unbundle technical support from reagent pricing.
Veneto
Padua's life sciences institutes adopt lyophilized reagent formats to reduce storage footprint and eliminate cold-chain logistics. ECHA substance evaluation tailwinds create first-mover advantage for distributors pre-registering alternative formulations. Academic research facilities here represent mature end-user segments with stable but price-sensitive procurement patterns.
Lazio
Rome's clinical diagnostic laboratories support long-term supply agreements with distributors through recurring reagent consumption in high-frequency diagnostic assays. Italy's national chemical agency enforcement priorities reshape import sourcing strategies for reference material producers. ISO 17025 certification timelines encounter extended audit backlogs from Italian accreditation bodies serving this central region.
Italy Laboratory Chemicals Market Competitive Landscape
German chemical conglomerates and diversified life sciences platforms split the market between cross-border supply dominance and specialized application expertise. The vendor base organizes around three strategic archetypes: integrated chemical manufacturers leveraging continental manufacturing scale, precision instrumentation specialists extending into adjacent consumables, and regional distributors upgrading purification infrastructure to meet tightening purity specifications. Consolidation pressure manifests through capacity expansion in Lombardy bottling facilities and strategic partnerships linking Bavarian production hubs with Po Valley biotechnology clusters.
Within the integrated manufacturer tier, Merck KGaA anchors reagent distribution throughout the peninsula from its German manufacturing base, while Thermo Fisher Scientific Inc. occupies a position exemplifying specialized media formulation expertise for biotechnology customers. DASIT Group SPA represents the domestic instrumentation channel archetype, extending reach from core equipment into adjacent consumables serving quality control workflows across northern Italy.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| GE Healthcare |
| DASIT Group SPA |
| ITW Reagents Division |
| Avantor Inc. |
| BD |
| BIOMÉRIEUX |
| BiosYnth s.r.l. |
| Others |
Supply & Pricing Matrix
Cross-Alpine freight corridors from Bavarian chemical hubs transmit cost volatility directly into Lombardy distributor margins while compressing price differentiation between ACS-grade and analytical-grade formulations. REACH compliance overhead and natural gas-linked distillation costs amplify tier separation across premium pharmacopeial grades versus economy environmental testing alternatives.
Pricing Analysis
REACH authorization requirements dictate the pricing tier structure across Italian laboratory chemicals, separating pharmacopeial-certified formulations for Milan pharmaceutical quality control from economy-grade alternatives serving routine environmental monitoring. Three-tier pricing stratifies across premium ACS/ISO 17025-certified reference materials, standard analytical grades for industrial QC, and economy solvents for academic bulk purchasing. Cost compression in premium grades is intensifying because energy-intensive fractional distillation amplifies input sensitivity to natural gas pricing. Academic institutions in Bologna and Padua exhibit highest price sensitivity through consolidated digital marketplace procurement, while Lombardy pharmaceutical manufacturers show lowest sensitivity due to regulatory-mandated certification requirements.
Supply Chain Analysis
Merck KGaA's German manufacturing base and Thermo Fisher's specialized media facilities anchor continental supply concentration for Italian peninsula distribution. Raw material dependencies rest on Bavarian petrochemical feedstocks for solvent precursors, Swiss fine chemical intermediates for reagent synthesis, and domestic Lombardy bottling infrastructure for final packaging. Single-source vulnerability concentrates in cross-Alpine logistics corridors exposed to Brenner Pass freight bottlenecks and German border clearance friction. Distribution runs through Milan-area distributors maintaining regional bottling capacity for fastest turnaround on high-rotation SKUs, with secondary channels serving Turin and Bologna through consolidated e-procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's laboratory chemicals market is recovering from cyclical compression in academic procurement budgets, with biopharmaceutical analytical testing expansion now driving reagent demand above prior-cycle peaks.
For Market Incumbents: Entrench position through backward integration into Lombardy-based purification infrastructure that captures premium-grade solvent margins currently flowing to German manufacturers. Add ISO 17025 certification capacity to reduce audit backlog exposure while locking in long-term supply agreements with Milan pharmaceutical quality control laboratories facing recruitment gaps for ICP-MS specialists. For New Entrants and Emerging Players: Specialized cell culture media formulations for mammalian expression systems in the Po Valley biotechnology corridor represent the most penetrable entry point outside Merck-Thermo Fisher dominance. Pre-mixed lyophilized reagent formats for Turin-Polytechnic research clusters offer a direct-to-laboratory digital channel bypassing traditional distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences conglomerates seeking to divest non-core reagent portfolios amid portfolio rationalization pressures. Five-to-ten year viability hinges on REACH pre-registration asset values for SVHC alternative formulations. Monitor ECHA substance evaluation acceleration timelines as the critical inflection signal for domestic distributor valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Purification Infrastructure | Captures premium solvent margins currently flowing to German chemical hubs across Brenner Pass corridors. |
| ISO 17025 Certification Capacity Expansion | Reduces audit backlog exposure from Italian accreditation bodies serving Lombardy reference material producers. |
| Pre-mixed Lyophilized Format Development | Eliminates cold-chain logistics for Padua life sciences institutes adopting reduced storage footprint protocols. |
| Direct-to-Laboratory Digital Channel Launch | Bypasses traditional distributor markups for Bologna academic institutions unbundling technical support from pricing. |
| SVHC Alternative Formulation Pre-registration | Creates first-mover advantage under ECHA substance evaluation timelines accelerating substitution mandates. |
Research Methodology
A spread of perspectives from pharmaceutical quality control managers, academic procurement officers, distributor technical sales leads, and REACH compliance consultants converged on the working assumptions underlying demand segmentation. Primary fieldwork combined structured interviews with laboratory directors at Milan-Turin corridor biotech clusters and procurement leads at Emilia-Romagna food safety testing facilities. Secondary validation drew from ECHA substance evaluation databases, Italian customs import records for analytical-grade solvents, SEC filings of listed life sciences suppliers, and Cefic sector reports on European chemical distribution. Bottom-up volume builds across product grades and end-user segments were triangulated against top-down market sizing from trade flow analysis.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions spanning purity grade tier, application protocol intensity, packaging format preference, and regional production hub proximity. CAGRs were derived from regression analysis against pharmaceutical R&D expenditure trends and biotechnology facility expansion announcements. Industry-specific forecast inputs included REACH authorization timeline acceleration scenarios and natural gas price sensitivity coefficients for fractional distillation cost structures.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial production indices and German chemical sector capacity utilization would shift the trajectory of import dependency assumptions. Forecasts reflect documented assumptions about ECHA enforcement priorities and Italian national chemical agency audit resource allocation. Quarterly review of SVHC candidate list updates and Lombardy pharmaceutical capital expenditure announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Boron Trifluoride Market
Chemicals
Thiourea Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Canada Methanol Market
Chemicals
Aluminium Chloride Market
Chemicals
Cumene Hydroperoxide Market
Chemicals
Peroxyacetic Acid Market
Chemicals
5 Dinitroaniline Market
Chemicals
Allyl Chloride Market
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Malonic Acid Market
Chemicals
Zinc Chemicals Market
Chemicals
Hydroxyzine Imine Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Detergent Alcohols Market
Chemicals
Cupric Chloride Market