
 Electronic Grade Hydrofluoric Acid Market | 2026-2036
Electronic Grade Hydrofluoric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Grade Hydrofluoric Acid Market Analysis
EU F-Gas Regulation is realigning the cost-of-entry calculus for fluorochemical producers serving European semiconductor fabs. Honeywell International Inc. leverages its integrated fluorine supply chain to sustain cost advantages across multiple purity grades. Stella Chemifa Corporation anchors its position through specialized ultrapure production lines serving Japanese and Taiwanese chipmakers. Solvay competes via controlled distribution networks that extend its reach into emerging European fabrication projects.
Electronic grade hydrofluoric acid denotes hydrofluoric acid refined to parts-per-billion impurity levels, typically achieving metal ion concentrations below one part per trillion for semiconductor applications through multi-stage distillation and sub-boiling purification processes. It serves primarily as an etchant and cleaning agent in silicon wafer processing, where trace contaminants cause catastrophic device failure. Semiconductor Grade commands the dominant value share as foundries at three-nanometer nodes impose ever-tighter specification windows. Electronics Manufacturing absorbs the largest application volume, though Chemical Synthesis registers the fastest expansion as pharmaceutical fluorination demand intersects with electronic-grade supply chains. Direct Sales channels dominate procurement for large semiconductor companies, while Distributors occupy the mid-tier laboratory and research laboratory segments where order fragmentation prevails.
EPA oversight in the United States and ECHA enforcement under REACH in Europe impose divergent but equally stringent reporting requirements on hydrofluoric acid handlers, while China's MEE implements GB standards that restrict emissions from fluorochemical plants serving domestic electronics firms. These regulatory frameworks shape demand by mandating purity documentation, forcing capital upgrades at older production facilities, and restricting market access for uncertified suppliers. Stakeholders must monitor evolving fluorine gas restrictions and fab localization policies to anticipate where qualification requirements will tighten next.
Market Dynamics
Advanced node semiconductor manufacturing at three-nanometer geometries is compressing impurity tolerance thresholds from parts-per-billion to parts-per-trillion specifications, forcing acid suppliers to rebuild purification infrastructure around sub-boiling distillation and ion-exchange polishing systems.
Growth Catalysts
- REACH RoHS alignment:ECHA enforcement tightens metal ion thresholds for European fabs, accelerating qualification of ultrapure suppliers who pre-certify against evolving impurity schedules.
- Gyeonggi cluster expansion:Samsung and SK Hynix captive chemical investments in South Korea's semiconductor corridor pull volume through dedicated high-purity production lines.
- Fluorination chemistry convergence:Pharmaceutical active ingredient manufacturing borrows electronic-grade supply chains for GMP-compliant fluorination, opening secondary demand channels.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar mining concentrates in Mexico and China, exposing processors to export quota volatility and input cost spikes.
- EU F-Gas Regulation friction:Phase-down schedules for hydrofluorocarbons intersect with HF acid production, complicating byproduct management and emissions compliance for European plants.
- Caustic soda substitution pressure:Alkaline etching chemistries advance in MEMS and power semiconductor segments where metal contamination tolerance remains higher.
Strategic Opportunities
- Indian fab localization:PLI scheme subsidies for semiconductor manufacturing in Gujarat and Karnataka create qualification windows for acid suppliers ahead of domestic volume ramp.
- Pharmaceutical fluorination premium:Contract manufacturers serving FDA-regulated drug sponsors seek electronic-grade certificates of analysis to satisfy GMP documentation requirements.
- Direct channel expansion:Large foundries bypass distributor markups through long-term offtake agreements with dedicated tanker logistics and on-site storage systems.
Industry Challenges
- Sub-boiling distillation expertise scarcity:Operations engineers capable of maintaining parts-per-trillion consistency across multi-stage purification trains command premium compensation and limited geographic mobility.
- Qualification timeline compression:Fab customers demand six-month certification cycles for new purity grades against eighteen-month historical baselines, stretching analytical validation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Grade Hydrofluoric Acid Market |
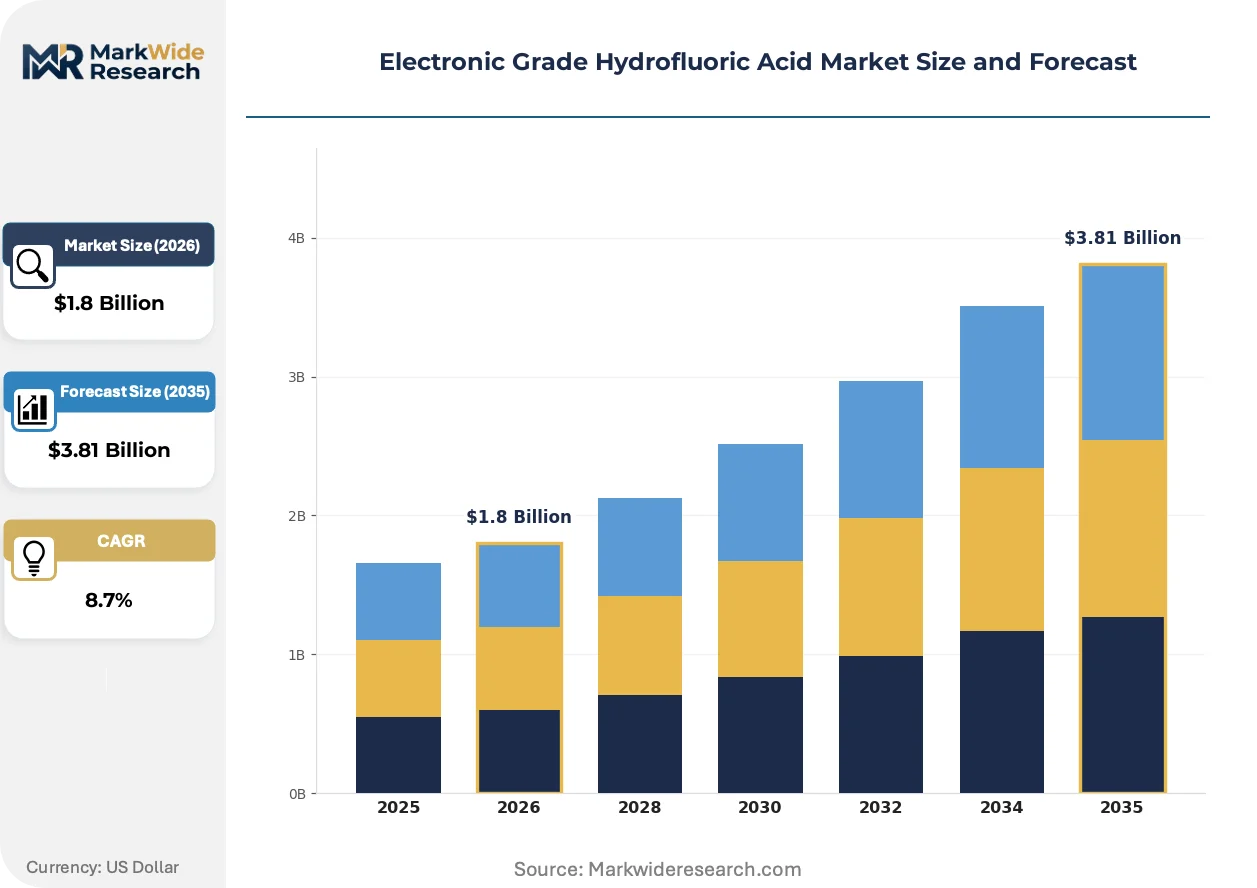
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semiconductor Grade, Laboratory Grade, Industrial Grade, High Purity Grade Application: Electronics Manufacturing, Metal Etching, Glass Etching, Chemical Synthesis End User: Semiconductor Companies, Research Laboratories, Chemical Manufacturers, Electronics Firms Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Stores |
| Companies Covered | Honeywell International Inc., Stella Chemifa Corporation, Solvay, Morita Chemical Industries Co. Ltd., Suzhou Crystal Clear Chemical Co. Ltd., Do-Fluoride Chemicals Co. Ltd., LANXESS, Formosa Daikin Advanced Chemicals Co. Ltd., Zhejiang Juhua Hanzheng New Materials Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Grade Hydrofluoric Acid Market Emerging Trajectories
Point-of-use purification systems are collapsing the traditional separation between bulk chemical distribution and wafer-process quality assurance, redrawing where value capture occurs in the supply chain.
Membrane-based final polishing is overtaking traditional packed-bed ion exchange for sub-parts-per-trillion metal removal in advanced node applications. TSMC and Intel fabs in Arizona and Ireland deploy these systems at the tool connection point. The technology is compressing acceptable transport distances between acid producer and fab gate, favoring regional purification hubs over centralized mega-plants.
China's MEE implements GB 31574-2015 emission standards that cap fluoride discharge from fluorochemical plants serving domestic electronics firms. Local producers in Jiangsu and Zhejiang provinces retrofit wet scrubber and calcium fluoride recovery systems. Semiconductor-grade output from these facilities faces elevated scrutiny from international chipmakers qualifying second-source suppliers.
Consolidated chemical management contracts now bundle acid supply with waste fluoride recovery and regeneration services. Large foundries in South Korea and Taiwan favor single-vendor arrangements covering delivery, monitoring, and spent acid reclamation. This model concentrates procurement decision authority with sustainability and EHS directors rather than traditional bulk chemical buyers.
Electronic Grade Hydrofluoric Acid Market Segmentation
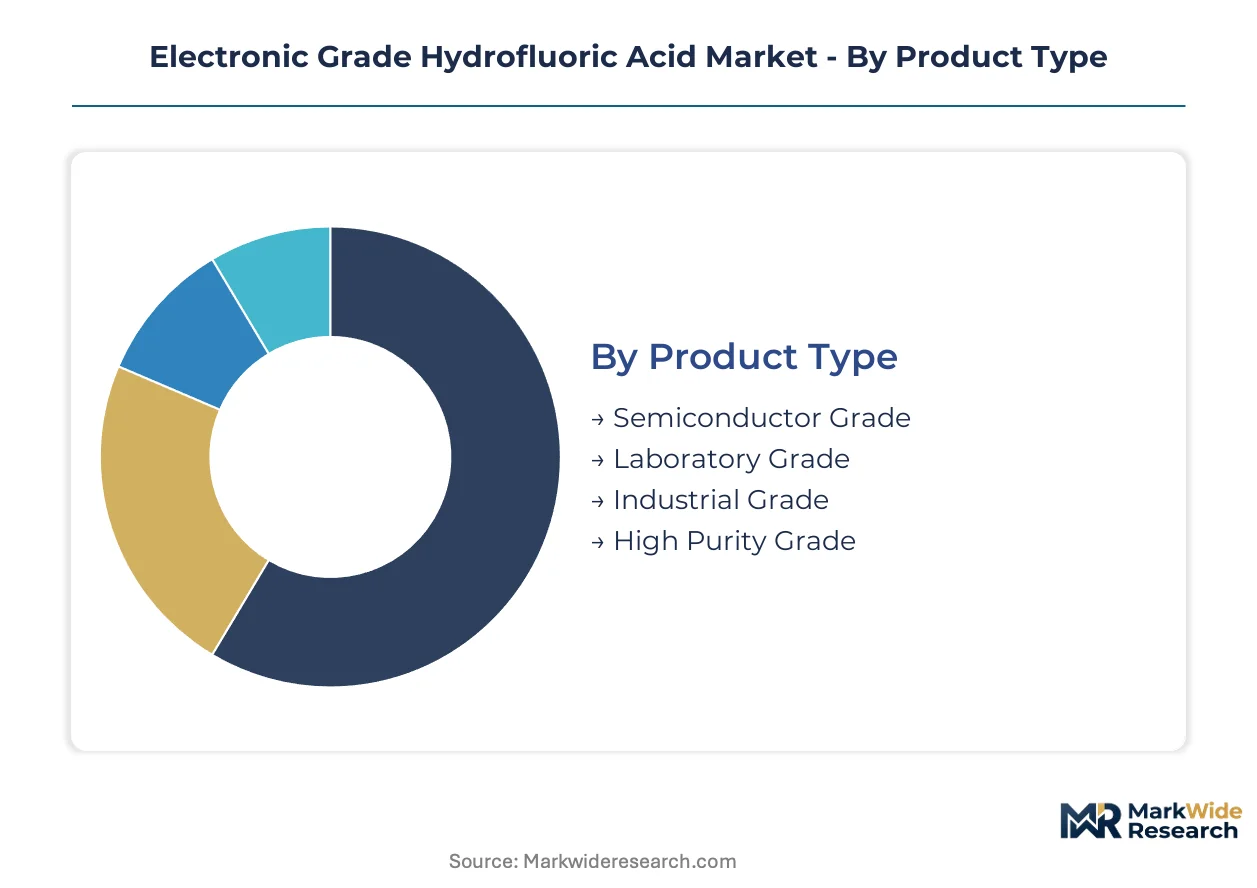
Segmentation in electronic grade hydrofluoric acid reveals how capital intensity and qualification barriers concentrate value capture. Purity thresholds, application criticality, and channel economics create distinct competitive arenas with divergent margin profiles.
Product Type:
Capital intensity escalates exponentially with purity grade as multi-stage sub-boiling distillation and ion-exchange infrastructure demands scale with specification stringency.
- Semiconductor Grade:Achieves metal ion concentrations below one part per trillion through dedicated purification trains. Samsung and SK Hynix fabs in South Korea's Gyeonggi corridor consume the dominant volume as three-nanometer node production compresses tolerance windows.
- High Purity Grade:Sits one tier below semiconductor grade with parts-per-billion impurity ceilings. Pharmaceutical fluorination applications in FDA-regulated contract manufacturing borrow this tier for GMP-compliant active ingredient synthesis.
- Laboratory Grade:Serves analytical chemistry and research protocols with documented trace metal certificates.
- Industrial Grade:Supplies glass etching and metal pickling where contamination tolerance permits higher throughput economics.
Most installed capacity flows through Semiconductor Grade. Expansion is steepest in High Purity Grade.
Application:
Application segmentation tracks how process criticality determines supplier qualification depth and contract duration.
- Electronics Manufacturing:Dominates volume as silicon wafer cleaning and etching at TSMC and Intel fabs demands continuous ultrapure supply. Point-of-use purification systems at Arizona and Ireland facilities compress acceptable transport distances, favoring regional hub configurations.
- Chemical Synthesis:Expanding most quickly as pharmaceutical fluorination converges with electronic-grade supply chains. Contract manufacturers seek certificates of analysis satisfying FDA documentation requirements.
- Metal Etching:Serves MEMS and power semiconductor segments where alkaline alternatives compete on cost.
- Glass Etching:Supplies architectural and automotive glass processing with lower purity tolerance.
Electronics Manufacturing commands the dominant share. Chemical Synthesis gains share fastest.
End User:
End user segmentation reflects procurement authority concentration and technical specification ownership.
- Semiconductor Companies:Large foundries in South Korea and Taiwan negotiate consolidated chemical management contracts bundling supply with waste fluoride recovery. Sustainability and EHS directors now control procurement authority previously held by bulk chemical buyers.
- Research Laboratories:Fragmented order patterns favor distributor channels with flexible packaging and documentation services.
- Chemical Manufacturers:Source electronic-grade material for downstream fluorochemical production.
- Electronics Firms:PCB and display manufacturers operate at lower purity tiers than wafer fabs.
Semiconductor Companies direct the largest volume flows. Research Laboratories exhibit the most dispersed procurement patterns.
Distribution Channel:
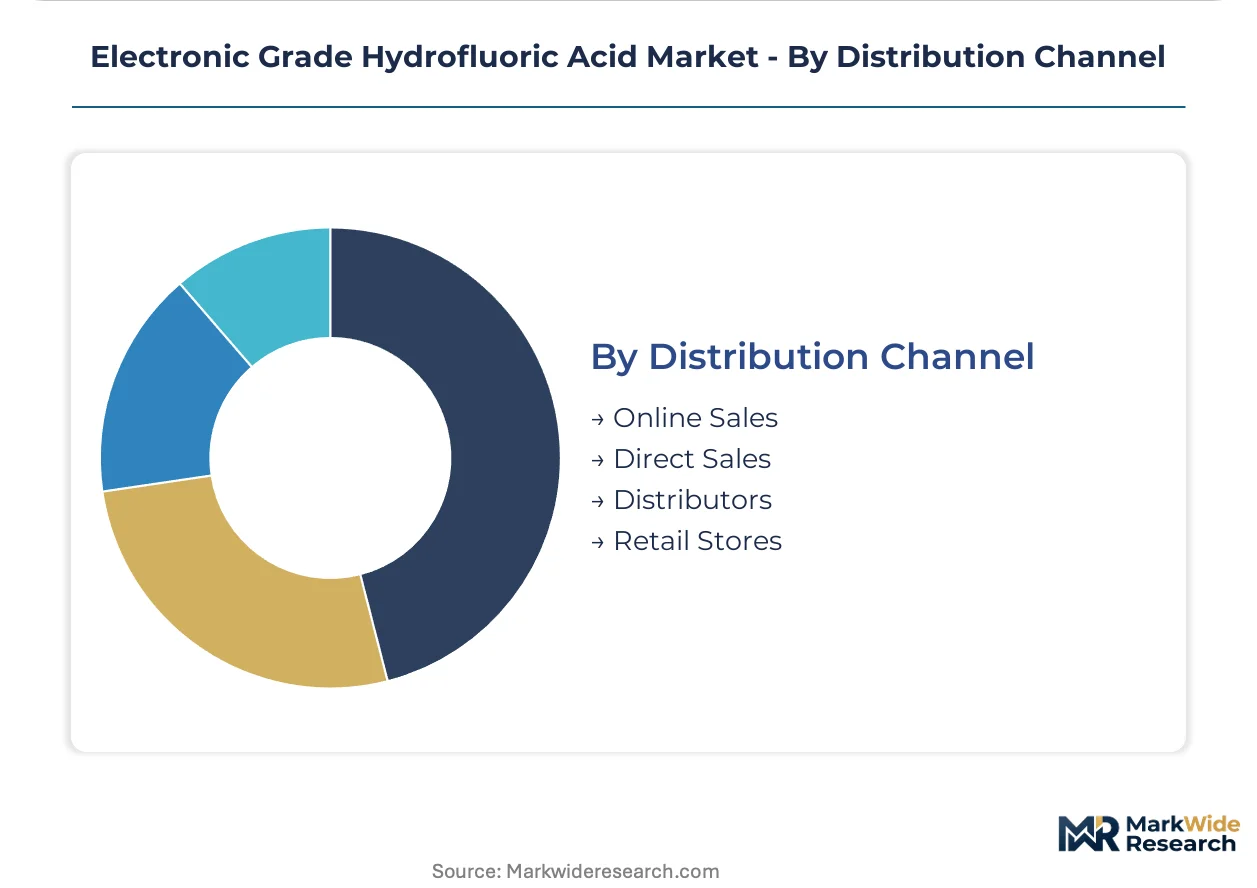
Channel segmentation mirrors customer scale and specification complexity, with direct relationships dominating where tanker logistics and on-site storage integrate into fab operations.
- Direct Sales:Large semiconductor companies bypass distributor markups through long-term offtake agreements with dedicated logistics and storage infrastructure. Honeywell and Stella Chemifa anchor positions through captive supply arrangements.
- Distributors:Occupy mid-tier laboratory and research segments where order fragmentation and documentation customization prevail. Solvay extends reach into emerging European fabrication projects through controlled distribution networks.
- Online Sales:Serves small-volume research and replacement orders with standardized packaging.
- Retail Stores:Minimal presence given hazardous material handling requirements and regulatory documentation needs.
Direct Sales channels handle the majority of tonnage. Distributors maintain the broadest customer count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineers capable of maintaining parts-per-trillion consistency across multi-stage purification trains concentrate in East Asian semiconductor corridors and select European chemical clusters.
United States
TSMC and Intel fabs in Arizona deploy point-of-use membrane polishing systems that compress acceptable transport distances from acid producer to fab gate. EPA oversight imposes stringent reporting requirements on hydrofluoric acid handlers, mandating purity documentation and emissions tracking. Regional purification hubs in the Southwest now compete with centralized mega-plants for advanced node supply contracts.
South Korea
Samsung and SK Hynix captive chemical investments in the Gyeonggi corridor pull dominant volume through dedicated high-purity production lines. The country's national environmental regulator enforces discharge standards that force capital upgrades at older fluorochemical facilities. Seoul Capital Area fabs negotiate consolidated chemical management contracts bundling acid supply with waste fluoride recovery services.
China
Domestic electronics manufacturers drive uptake as Jiangsu and Zhejiang province producers retrofit wet scrubber and calcium fluoride recovery systems under MEE emission standards. GB 31574-2015 caps fluoride discharge from fluorochemical plants serving the semiconductor sector. Yangtze River Delta facilities face elevated scrutiny from international chipmakers qualifying second-source suppliers.
Japan
Stella Chemifa Corporation anchors supply to Japanese and Taiwanese chipmakers through specialized ultrapure production lines. METI industrial policy shapes qualification protocols for materials serving domestic advanced node fabrication. Kyushu-based chemical clusters serve legacy semiconductor and emerging power device segments with differentiated purity tiers.
Germany
Solvay extends reach into emerging European fabrication projects through controlled distribution networks that navigate REACH and RoHS compliance requirements. ECHA enforcement tightens metal ion thresholds for fabs operating under EU F-Gas Regulation phase-down schedules. Bavaria and Saxony chemical corridors concentrate technical expertise in sub-boiling distillation process engineering.
Electronic Grade Hydrofluoric Acid Market Vendor Landscape
The competitive structure tilts toward integrated fluorochemical conglomerates with captive supply chain control. Three to five vertically positioned players dominate semiconductor-grade volume, while mid-tier specialists occupy pharmaceutical fluorination and laboratory segments. Two strategic archetypes prevail: diversified chemical majors leveraging integrated fluorine supply chains, and purity-focused specialists serving captive fab arrangements. Capacity expansion and qualification timeline compression represent the dominant competitive moves, as customers demand six-month certification cycles against eighteen-month historical baselines.
Among integrated conglomerates, Honeywell International Inc. and LANXESS exemplify archetypes built around upstream fluorine control and multi-grade production flexibility. Stella Chemifa Corporation occupies a position within the purity-specialist tier, representing suppliers whose qualification depth with East Asian foundries creates defensive positioning. Solvay sits within the European distribution-anchored archetype, extending geographic reach through controlled network arrangements rather than captive production scale. These three patterns illustrate how competitive positioning fragments across supply chain integration strategies, regional qualification depth, and channel architecture choices.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Stella Chemifa Corporation |
| Solvay |
| Morita Chemical Industries Co. Ltd. |
| Suzhou Crystal Clear Chemical Co. Ltd. |
| Do-Fluoride Chemicals Co. Ltd. |
| LANXESS |
| Formosa Daikin Advanced Chemicals Co. Ltd. |
| Zhejiang Juhua Hanzheng New Materials Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in South Korea and China anchor supply discipline through captive chemical investments that tighten pricing power at the semiconductor-grade tier. Their state-linked financing structures compress working capital cycles for high-purity acid production while forcing private competitors to absorb margin pressure from fluorspar cost volatility.
Pricing Analysis
Consolidated chemical management contracts bundle acid supply with waste fluoride recovery services, separating premium-priced integrated arrangements from unbundled spot transactions. Three-tier pricing structure across semiconductor-grade, high-purity-grade, and laboratory-grade levels tracks certification depth and volume commitment scale. Cost compression in the laboratory tier intensifies because distributor fragmentation erodes bargaining leverage. Research laboratories exhibit the highest price sensitivity as order fragmentation prevents scale discounts, while Samsung and SK Hynix fabs accept premium positioning for captive supply security.
Supply Chain Analysis
Spent acid regeneration flows reverse from foundry gates back to producer facilities, closing material loops that reduce virgin fluorspar dependence and reshape logistics economics. Primary production concentrates in China, South Korea, and Japan, with Jiangsu and Zhejiang provinces hosting retrofitting capacity under MEE emission standards. Acid-grade fluorspar mining draws from Mexican and Chinese deposits, exposing processors to export quota volatility. Single-source vulnerability concentrates in fluorspar supply, where geographic concentration amplifies disruption risk. Distribution runs through direct tanker logistics for large semiconductor companies and controlled distributor networks for mid-tier laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation phase-down schedules and REACH impurity threshold tightening accelerate demand for pre-certified ultrapure suppliers. ECHA enforcement milestones reshape supplier qualification protocols faster than capacity expansion timelines.
For Market Incumbents: Extend captive supply arrangements with foundry customers through dedicated on-site storage infrastructure that locks out second-source qualification. Deepen backward integration into acid-grade fluorspar sourcing to buffer Mexican and Chinese export quota volatility. Sub-boiling distillation expertise scarcity represents the critical defensive moat against emerging purification technology entrants. For New Entrants and Emerging Players: Begin with pharmaceutical fluorination applications in FDA-regulated contract manufacturing, where electronic-grade certificate requirements create qualification windows without semiconductor-grade capital intensity. Gujarat and Karnataka fab localization under India's PLI scheme offers the most penetrable geography ahead of domestic volume ramp. Lead with GMP-compliant documentation services as the go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional purification hub operators in the US Southwest and Ireland, where point-of-use membrane polishing compresses acceptable transport distances and favors asset-light hub configurations over centralized mega-plants. Target acquisition archetype: mid-cap specialists with existing sub-boiling distillation infrastructure and active foundry qualification pipelines. Monitor ECHA impurity schedule revisions as the inflection signal for accelerated qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar | Secures input supply against Mexican and Chinese export quota volatility for acid producers. |
| Point-of-Use Purification Deployment | TSMC and Intel fabs in Arizona deploy membrane polishing at tool connection points. |
| Consolidated Chemical Management Contracts | South Korean foundries bundle acid supply with waste fluoride recovery under single-vendor arrangements. |
| Pharmaceutical Fluorination Qualification | FDA-regulated contract manufacturers seek electronic-grade certificates for GMP documentation compliance. |
| Regional Purification Hub Expansion | Southwest US and Ireland hubs compete with centralized mega-plants for advanced node supply. |
Methodological Framework
Coverage spans East Asia, North America, and Europe, with primary inputs from each region's semiconductor manufacturing corridors and fluorochemical production clusters. The research combines structured interviews with plant managers at acid purification facilities, procurement leads at Samsung and SK Hynix, distribution channel partners serving laboratory segments, and technical R&D directors overseeing sub-boiling distillation process engineering. Secondary validation draws from SEC 10-K filings of integrated fluorochemical conglomerates, customs and trade data tracking acid-grade fluorspar flows, and ECHA REACH registration dossiers. Bottom-up capacity modeling and top-down demand triangulation from foundry capex disclosures ensure cross-verified outputs.
Granularity-level framing applies separate modeling tracks for semiconductor-grade, high-purity-grade, and laboratory-grade tiers, with additional disaggregation by direct sales versus distributor channel economics. The analytical framework projects volume and value outputs across the analysis window by linking foundry node transition timelines to impurity specification compression curves. CAGRs derive from segment-level growth rate blending weighted by purity-grade value capture. Forecast inputs include TSMC and Intel fab ramp schedules in Arizona and Ireland, plus MEE emission standard retrofitting timelines for Chinese producers.
Several conditions sit outside the modeled scope, including abrupt fluorspar export embargoes, breakthrough alkaline etching technology displacement, and unscheduled EU F-Gas Regulation acceleration. Forecasts reflect assumptions about six-month qualification cycle compression sustaining and pharmaceutical fluorination demand convergence continuing. Practitioners should monitor ECHA impurity schedule amendments, China MEE enforcement intensity, and captive chemical investment announcements from Samsung and SK Hynix for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Copper Oxychloride Market
Chemicals
5 Dinitroaniline Market
Chemicals
Phosphotungstic Acid Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Inorganic Chemicals Market
Chemicals
Global Acetic Anhydride Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Hexamine Market
Chemicals
Global Bleaching Agents Market
Chemicals
Hydroxyzine Imine Market
Chemicals
Trichlorosilane Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Tromethamine Market
Chemicals
Hydroxyethyl Methyl Cellulose Market