
 Asia Pacific Waterproofing Chemicals Market | 2026-2036
Asia Pacific Waterproofing Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Waterproofing Chemicals Market Analysis
Aftermarket membrane refurbishment revenue is reconfiguring margin distribution across the waterproofing chemicals value chain in Asia Pacific. Sika AG leverages its polyurethane technology leadership to capture specification-driven projects across Southeast Asian infrastructure corridors. Pidilite Industries anchors its position through backward integration into polymer emulsions, controlling raw material quality for cementitious systems. Oriental Yuhong dominates China's high-speed rail and metro tunnel segments through manufacturing scale that few regional competitors can match.
Waterproofing chemicals encompass bituminous coatings, polyurethane membranes, cementitious crystalline additives, and epoxy sealants formulated to prevent moisture ingress in concrete, masonry, and metal substrates. These materials achieve hydrostatic resistance ratings from 50 to over 150 meters water head while maintaining elastomeric recovery above 30% for structural movement accommodation. Membranes command the largest value pool due to their specified use in critical infrastructure, while polyurethane technology captures premium pricing in subterranean applications where chemical resistance and flexibility converge. Cementitious systems compete aggressively on installed cost in India's mass residential construction, though epoxy sealants remain confined to industrial containment and marine environments where solvent resistance proves essential.
China's GB standards for underground engineering waterproofing, administered by SAMR, mandate minimum service life requirements that elevate product performance thresholds. India's BIS certification for construction chemicals, coupled with state-level building codes in Maharashtra and Karnataka, creates compliance-driven procurement filters that favor tested formulations. The EU Green Deal's REACH-aligned substance restrictions are beginning to influence formulation strategies among exporters serving Southeast Asian projects with European contractor involvement. Stakeholders must monitor how China's dual carbon goals reshape bitumen-derived product economics and whether India's PLI scheme for construction materials accelerates domestic specialty chemical capacity.
Market Dynamics
China's dual carbon goals are compressing bitumen-derived product economics while elevating polymer-modified alternatives across infrastructure procurement. The tension between performance mandates and cost pressures is restructuring supplier relationships throughout the value chain.
Growth Catalysts
- GB Standards for Underground Engineering:China's SAMR-administered durability mandates extend minimum service life requirements, forcing specification upgrades in metro tunnel and high-speed rail segments.
- Urban Infrastructure Concentration:India's Mumbai-Delhi-Bangalore corridor generates concentrated demand for cementitious crystalline systems in mass residential foundations and commercial podium structures.
- Polyurethane Technology Maturation:Two-component elastomeric formulations achieve hydrostatic resistance above 150 meters water head while maintaining 30% elastomeric recovery, penetrating subterranean applications previously reserved for bituminous membranes.
Market Restraints
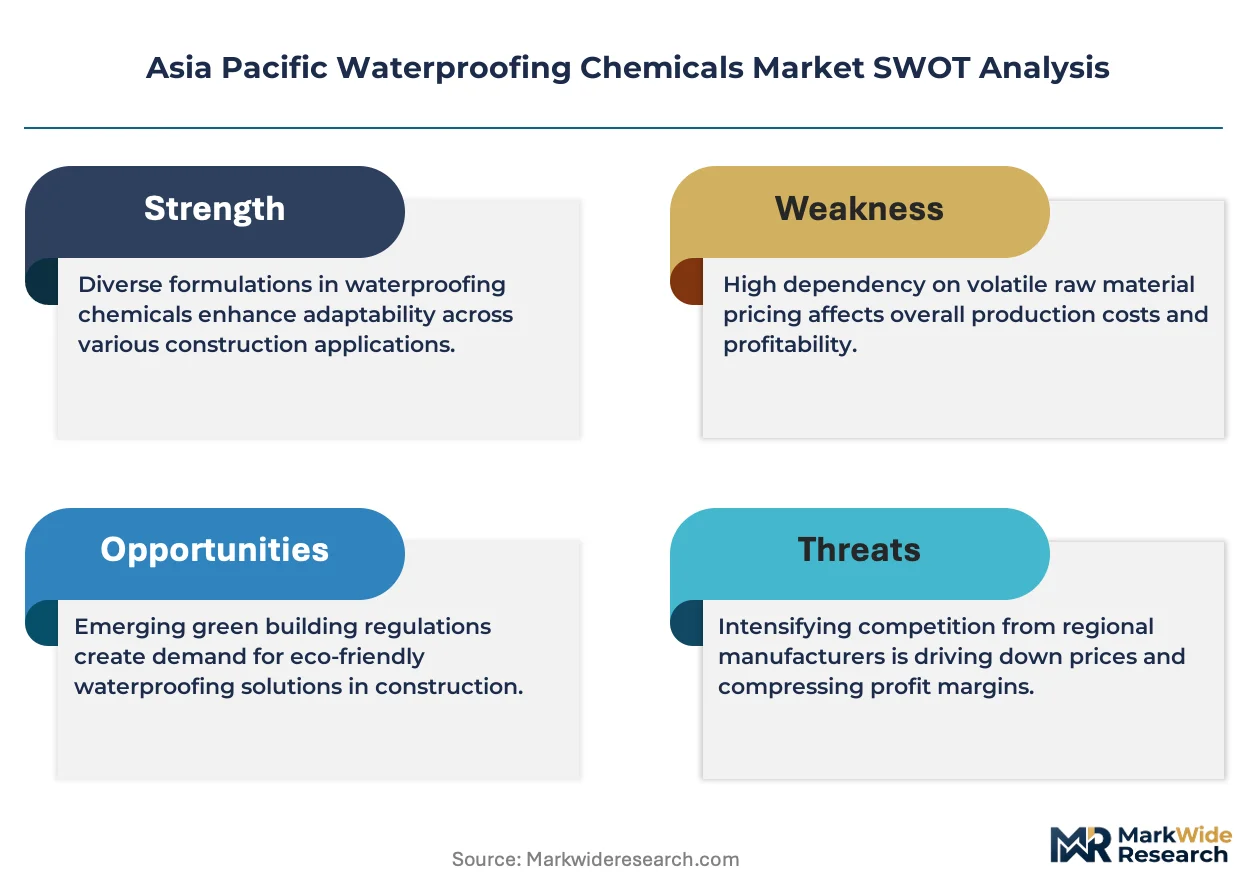
- Crude-Derived Input Volatility:Bitumen and polyurethane precursor costs fluctuate with naphtha and propylene chain pricing, compressing margin stability for coating manufacturers.
- Specialty Polymer Import Dependence:Southeast Asian formulators rely on Korean and Japanese suppliers for MDI and polyether polyols, exposing procurement to shipping corridor disruptions.
- Cementitious Performance Ceiling:Crystalline additives face inherent limitations in dynamic crack-bridging applications where structural movement exceeds 2% strain, restricting penetration in seismic zones.
Strategic Opportunities
- Vietnam Infrastructure Buildout:The country's northern manufacturing corridor and southern logistics hubs generate untapped specification demand for membrane systems in industrial warehousing.
- India PLI Scheme for Construction Materials:Domestic specialty chemical capacity expansion incentives enable import substitution for polymer emulsions currently sourced from European suppliers.
- Green Building Certification Convergence:LEED and GRIHA alignment creates procurement preference for low-VOC polyurethane formulations in premium commercial developments.
Industry Challenges
- Application Technician Certification Gaps:Two-component polyurethane and epoxy systems require trained applicators for proper mixing ratios and cure management, constraining deployment velocity in remote project sites.
- BIS Compliance Timeline Compression:India's certification body mandates extended testing protocols for construction chemicals, delaying product launches by 8-14 months versus unregulated alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Waterproofing Chemicals Market |
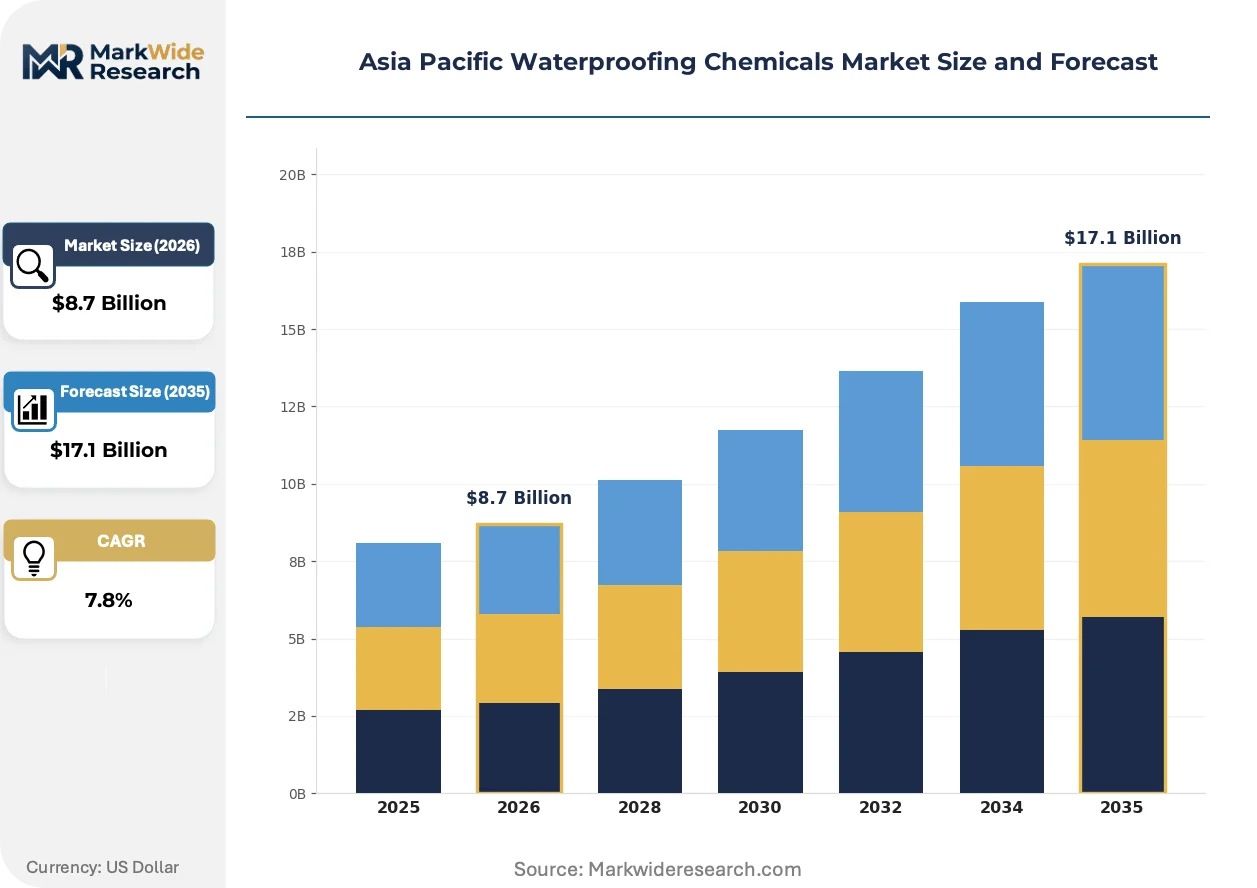
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membranes, Coatings, Sealants, Additives Application: Buildings, Infrastructure, Water & Waste Management, Industrial Technology: Polyurethane, Bituminous, Cementitious, Epoxy End User: Construction, Automotive, Marine, Commercial |
| Companies Covered | Pidilite Industries, Saint-Gobain Weber, Sika AG, Keshun Waterproof Technology Co., Ltd., Oriental Yuhong, BASF SE, Fosroc, Wacker Chemie AG, Mapei S.p.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Waterproofing Chemicals Market Emerging Trajectories
Formulation chemistry and procurement protocols are converging to reshape competitive positioning across the Asia Pacific waterproofing chemicals landscape. Three distinct vectors are compressing legacy business models while opening specification-driven revenue pools.
Single-component moisture-cure polyurethane technology is rendering obsolete two-part epoxy systems in industrial containment applications. Japanese automotive manufacturing facilities and Korean battery gigafactories specify these materials for chemical-resistant flooring where installation speed outweighs absolute solvent resistance. The shift compresses contractor labor costs by 40% while reducing cure-time risk in humidity-variable environments.
REACH-aligned substance restrictions from the EU Green Deal are propagating through Southeast Asian projects with European contractor involvement. ECHA candidate list substances including certain phthalate plasticizers and isocyanate monomers face substitution pressure, forcing reformulation investments among exporters. Chinese manufacturers serving Singapore and Thailand infrastructure are accelerating bio-based polyol development to maintain specification eligibility.
Specification-driven procurement is consolidating buyer power among engineering-procurement-construction firms with in-house testing laboratories. Tier-1 contractors in Australia's mining infrastructure and Indonesia's port developments now require batch-specific performance verification, displacing commodity distributors. This compression is most visible in Australia's Pilbara region and Indonesia's Batam industrial zone where project scale justifies captive quality assurance investment.
Asia Pacific Waterproofing Chemicals Market Segmentation
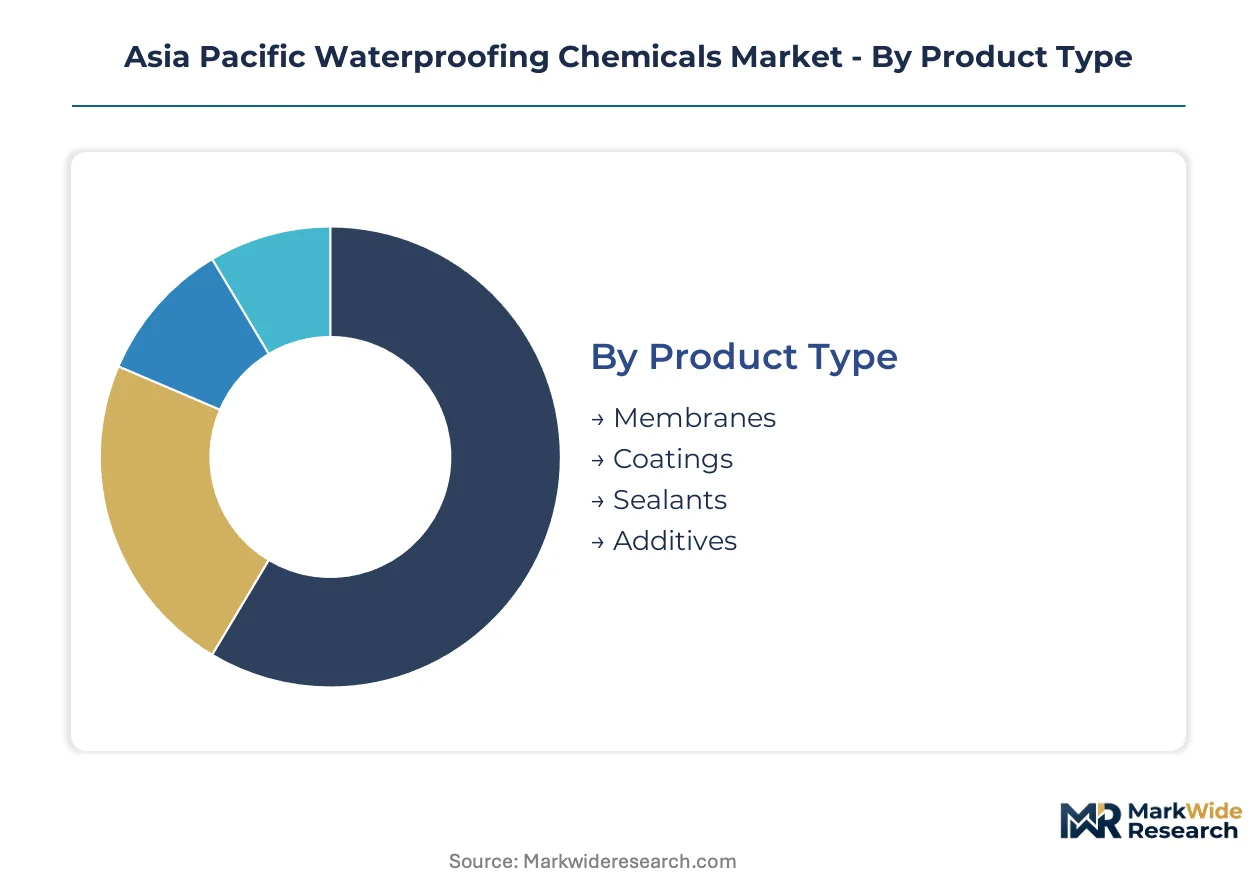
Waterproofing chemicals fragment across four distinct classification axes that govern procurement economics and specification requirements. Product type determines raw material intensity and margin structure. Application context dictates performance thresholds from residential basements to high-speed rail tunnels. Technology choice reflects the trade-off between installed cost and service life. End-user concentration shapes channel strategy from bulk distributor relationships to specification-driven project sales.
Product Type:
Membrane systems span sprayed liquid-applied sheets through preformed rolls, each tier serving distinct project scales and access constraints.
- Membranes:Preformed bituminous rolls and liquid-applied polyurethane sheets achieve hydrostatic resistance above 150 meters water head. China's metro tunnel specifications under GB standards mandate these systems for underground segments in Beijing and Shenzhen, where service life requirements exceed 50 years.
- Coatings:Brush or spray-applied bituminous and acrylic formulations deliver 50-100 meter water head resistance at lower installed cost. India's mass residential construction in the Mumbai-Delhi-Bangalore corridor consumes cementitious coatings for podium waterproofing where budget constraints dominate specification.
- Sealants:Elastomeric joint fillers accommodate structural movement in expansion joints and penetrations. These materials serve bridge deck applications across Vietnam's northern manufacturing corridor where thermal cycling demands 30% elastomeric recovery.
- Additives:Crystalline hydrophilic compounds integrate into concrete mix designs for integral waterproofing. BIS certification requirements in Maharashtra and Karnataka favor tested additive formulations for commercial foundation slabs.
The dominant share belongs to Membranes, while Coatings is closing the gap fastest.
Application:
Construction activity intensity varies sharply across end-use contexts, with infrastructure commanding premium specifications and buildings driving volume.
- Buildings:Residential, commercial, and institutional structures require below-grade and roof waterproofing. India's urban infrastructure belt generates concentrated demand for cementitious systems in high-rise foundations where construction pace favors rapid-cure materials.
- Infrastructure:Tunnels, bridges, and transportation corridors demand membrane systems with documented service life. China's high-speed rail network specifications under SAMR-administered GB standards elevate polyurethane technology penetration in subterranean segments.
- Water & Waste Management:Treatment plants and containment structures require chemical-resistant epoxy and polyurethane formulations. Australia's mining infrastructure in the Pilbara region specifies these materials for process water containment where solvent resistance proves essential.
- Industrial:Manufacturing floors and chemical processing facilities specify fast-cure polyurethane for installation speed. Korean battery gigafactories and Japanese automotive plants favor single-component moisture-cure systems to compress contractor labor schedules.
Infrastructure commands specification premiums, though Buildings generates the largest absolute volume.
Technology:
Chemistry selection reflects the intersection of performance mandate, substrate condition, and installed cost tolerance.
- Polyurethane:Two-component elastomeric and single-component moisture-cure formulations deliver hydrostatic resistance above 150 meters with 30% elastomeric recovery. These systems penetrate China's metro tunnel segments where GB standards mandate flexible crack-bridging capacity.
- Bituminous:SBS-modified and APP-modified asphalt membranes serve cost-sensitive applications with moderate movement accommodation. China's dual carbon goals are compressing economics for these crude-derived products while polymer-modified alternatives gain specification share.
- Cementitious:Crystalline additives and flexible polymer-modified coatings compete aggressively on installed cost. India's BIS certification creates compliance-driven procurement filters favoring tested cementitious formulations for mass residential foundations.
- Epoxy:Solvent-resistant rigid systems confine usage to industrial containment and marine environments. These materials serve Australia's mining infrastructure and Indonesia's port developments where chemical resistance outweighs flexibility requirements.
Polyurethane holds technology leadership in premium applications, while Cementitious systems expand most quickly in cost-driven segments.
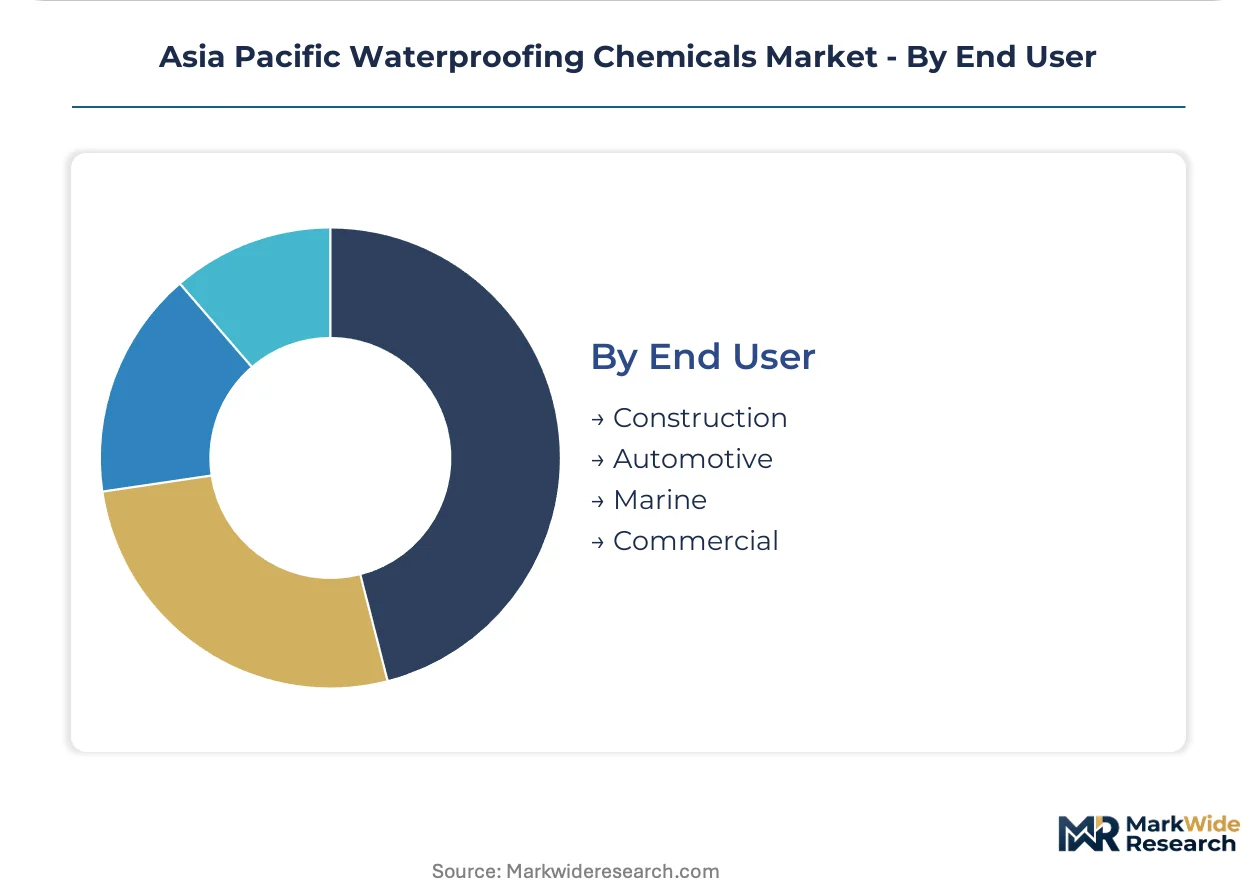
End User:
Buyer sophistication and procurement authority concentrate differently across end-user categories, shaping channel strategy and specification influence.
- Construction:General contractors and specialty waterproofing subcontractors drive procurement for buildings and infrastructure. Engineering-procurement-construction firms with captive testing laboratories now require batch-specific performance verification in Indonesia's Batam industrial zone and Australia's Pilbara region.
- Automotive:Manufacturing facility construction specifies fast-cure polyurethane flooring systems. Japanese automotive plants favor single-component moisture-cure technology to reduce cure-time risk in humidity-variable environments.
- Marine:Port infrastructure and shipbuilding require epoxy and polyurethane systems with saltwater resistance. These applications concentrate in Southeast Asian logistics hubs where European contractor involvement propagates REACH-aligned substance restrictions.
- Commercial:Premium developments pursue LEED and GRIHA alignment for low-VOC polyurethane formulations. Singapore and Bangkok commercial towers specify these materials for green building certification compliance.
Construction dominates procurement volume, though Automotive specifications are gaining technology influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Asia Pacific waterproofing chemicals landscape. India's mass residential construction tolerates cementitious systems at the lowest cost per square meter, while Australia's mining infrastructure and China's high-speed rail specifications absorb premium polyurethane membranes without elasticity.
China
Metro tunnel construction in Beijing and Shenzhen drives specification-grade membrane demand. SAMR-administered GB standards mandate 50-year service life minimums for underground engineering, elevating performance thresholds beyond regional competitors. The Yangtze River Delta manufacturing corridor supplies polymer-modified bitumen alternatives as dual carbon goals compress crude-derived product economics.
India
The Mumbai-Delhi-Bangalore urban infrastructure belt concentrates cementitious crystalline consumption for high-rise foundations. BIS certification requirements and Maharashtra state building codes create compliance filters favoring tested formulations. Karnataka's commercial podium construction generates parallel demand for rapid-cure polymer emulsions in tight construction schedules.
Australia
Mining infrastructure in the Pilbara region specifies epoxy and polyurethane systems for process water containment. Engineering-procurement-construction firms with captive testing laboratories now require batch-specific performance verification. Queensland's port developments absorb saltwater-resistant formulations where European contractor involvement propagates REACH-aligned substance restrictions.
Vietnam
Northern manufacturing corridors and southern logistics hubs generate membrane demand for industrial warehousing. Japanese and Korean foreign direct investment projects import specification standards from their home markets. Ho Chi Minh City's commercial tower construction increasingly references LEED alignment for low-VOC polyurethane procurement.
Indonesia
Batam industrial zone projects justify captive quality assurance investment among tier-1 contractors. Port infrastructure development across the archipelago requires chemical-resistant epoxy systems for marine exposure. State-owned infrastructure procurement is tightening material traceability requirements following high-profile construction failures.
Asia Pacific Waterproofing Chemicals Market Vendor Landscape
Capability concentration sits with specialized membrane formulators; scale advantage sits with diversified construction chemical conglomerates. The Asia Pacific waterproofing chemicals market structures around three tiers: global specialists with specification influence, regional integrators controlling polymer supply chains, and commodity distributors serving cost-driven residential segments. Competitive moves concentrate on backward integration into polymer emulsions and manufacturing scale expansion for metro tunnel specifications.
Among Indian specialists, Pidilite Industries anchors the backward-integrated tier through captive polymer emulsion production. Swiss conglomerate Sika AG exemplifies the specification-driven archetype with polyurethane technology leadership across Southeast Asian infrastructure corridors. Chinese scale players include Oriental Yuhong, which occupies a position in high-speed rail and metro tunnel segments through manufacturing footprint that regional competitors struggle to match.
| Leading Market Players |
|---|
| Pidilite Industries |
| Saint-Gobain Weber |
| Sika AG |
| Keshun Waterproof Technology Co., Ltd. |
| Oriental Yuhong |
| BASF SE |
| Fosroc |
| Wacker Chemie AG |
| Mapei S.p.A. |
| Others |
Supply Flow & Price Mechanics
The Malacca Strait shipping corridor's freight volatility feeds directly into procurement economics for Southeast Asian formulators, compressing margins on MDI and polyether polyol imports while enabling Chinese membrane manufacturers to capture price premiums through domestic polymer supply security. This logistics-cost asymmetry stratifies the market into specification-driven project tiers where certification-backed suppliers command 30-40% markups over commodity distributors serving India's mass residential segment.
Pricing Analysis
Long-term offtake contracts dominate procurement for China's metro tunnel and high-speed rail specifications under SAMR-administered GB standards, locking in volume commitments that insulate polyurethane membrane producers from naphtha chain volatility. Price differentiation rests on BIS certification tier and installed performance warranty length. Cost compression in cementitious coatings is intensifying because India's PLI scheme accelerates domestic polymer emulsion capacity, eroding European import premiums. Mass residential contractors in Mumbai exhibit highest price sensitivity, while Australian mining EPC firms absorb premium epoxy formulations without elasticity.
Supply Chain Analysis
Export-control regimes on advanced polymer catalysts from Japanese and Korean suppliers constrain technology transfer to Southeast Asian formulators, fragmenting regional production capabilities. Supply concentrates in China's Yangtze River Delta for bitumen modification, South Korea for MDI precursors, and India for cementitious additive compounding. Raw material dependencies span naphtha-derived bitumen, propylene oxide for polyols, and specialty amine curatives. Single-source vulnerability runs through Korean-Japanese MDI supply corridors. Distribution runs through project-direct sales for infrastructure specifications and bulk chemical distributors for residential construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: BIS certification timelines and GB standard compliance create 8-14 month product launch barriers that entrench tested incumbents against unverified alternatives.
For Market Incumbents: Pre-empt margin erosion in cementitious coatings by accelerating backward integration into polymer emulsions before India's PLI scheme matures domestic competitor supply. Capture specification-driven project pipelines across Vietnam's northern manufacturing corridor through captive applicator training programs that address technician certification gaps constraining two-component polyurethane deployment velocity. For New Entrants and Emerging Players: Build out white-space positions in Indonesia's Batam industrial zone where tier-1 contractors' captive testing laboratories have displaced commodity distributors, creating procurement access for batch-verified specialty formulators. Target Australia's Pilbara mining infrastructure for epoxy containment systems where European contractor involvement propagates REACH-aligned substance restrictions that favor reformulation-capable entrants over legacy bitumen suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified construction chemical conglomerates seeking to monetize non-core waterproofing divisions as specialty chemical valuations decouple from commodity construction exposure. Prioritize assets with demonstrated GB standard or BIS certification traction that can compound through India's urban infrastructure belt expansion. Watch for inflection when China's dual carbon goals trigger accelerated bitumen substitution mandates in provincial procurement guidelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Emulsions | Captive supply secures margin control against India's PLI-driven import substitution. |
| GB Standard Certification Investment | SAMR compliance unlocks 50-year service life specifications in Beijing-Shenzhen metro tunnels. |
| Applicator Training Network Expansion | Certified technician pools accelerate two-component polyurethane deployment in remote project sites. |
| REACH-Aligned Reformulation Program | Bio-based polyol development maintains specification eligibility for European-contractor projects in Thailand. |
| Long-Term Supply Agreement with EPC Firms | Batch-specific performance verification contracts consolidate buyer power in Indonesia's Batam zone. |
Methodological Framework
Desk research of customs trade databases, BIS certification registries, and SAMR GB standard documentation preceded structured interviews with plant managers at polymer emulsion facilities, procurement leads at Indian EPC firms, technical R&D directors at membrane formulators, and distribution channel partners across Southeast Asia. Primary fieldwork captured specification requirements, certification timelines, and raw material sourcing patterns. Secondary validation drew from SEC filings of listed construction chemical conglomerates, ACC industry reports, and import-export data for MDI and polyether polyol flows. Bottom-up project pipeline analysis triangulated against top-down market size estimates from construction activity indices.
Assumptions held fixed across the modeling period include China's dual carbon policy trajectory, India's PLI scheme continuation for construction materials, and REACH-aligned substance restriction propagation through European-contractor projects. Variables tested across sensitivity bands encompass naphtha-propylene chain pricing, BIS certification timeline compression, and Vietnamese infrastructure buildout acceleration. Segmentation dimensions modeled span product type, application context, technology chemistry, and end-user procurement sophistication. CAGRs derived from regression against construction spending forecasts and specification-grade penetration curves. Industry-specific inputs incorporated GB standard revision cycles and state-level building code adoptions in Maharashtra and Karnataka.
Stress conditions across crude derivative volatility, shipping corridor disruptions, and regulatory timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on policy continuity and technology substitution rates. Specific risks that could revise projections include accelerated bitumen substitution mandates in China, BIS testing protocol expansions, and Korean-Japanese export control tightening on polymer catalysts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Decabromodiphenyl Ether Market
Chemicals
Potassium Iodide Market
Chemicals
Europe Methanol Market
Chemicals
Global Bleaching Agents Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Sodium Azide Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Southeast Asia Construction Chemicals Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Potassium Zirconium Fluoride Market
Chemicals
United Kingdom Methanol Market
Chemicals
Fluorene Market
Chemicals
US Methanol Market
Chemicals
Diphenyl Sulfone Market
Chemicals
De-Icing Agents Market