
 Gold Plating Chemicals Market | 2026-2036
Gold Plating Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Gold Plating Chemicals Market Outlook
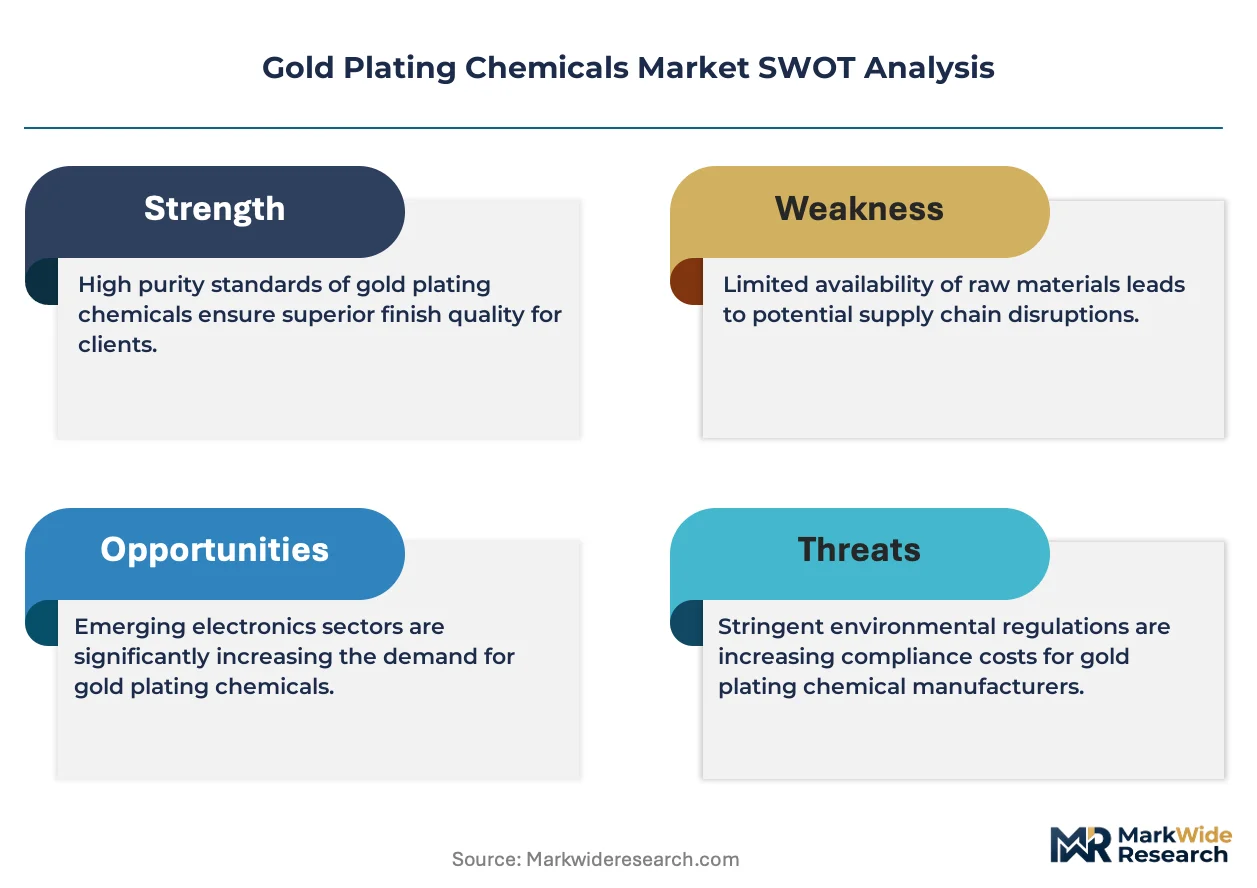
Palladium-nickel underplates is expanding as a cost buffer against volatile gold prices in connector applications. Heimerle + Meule leverages its precious metals refining heritage to dominate European jewelry plating supply. Umicore sustains leadership through captive refining and closed-loop chemical recovery systems. Heraeus anchors high-reliability electronics demand with specialized gold sulfite formulations for semiconductor packaging.
Gold plating chemicals comprise electrolytic and electroless formulations containing gold salts dissolved in aqueous media, typically operating at pH ranges from 4.0 to 10.0 and deposition rates between 0.1 and 5.0 microns per hour depending on bath chemistry. These formulations deposit corrosion-resistant, conductive surface layers onto substrates for electrical contact reliability, decorative finish durability, and biocompatibility in implanted devices. Electroless gold commands premium positioning due to its uniform coverage on complex geometries without external power, while gold cyanide retains volume leadership despite regulatory pressure because of its deposition efficiency and bath stability. Electronics applications generate the dominant revenue pool, though medical devices represent the fastest-expanding segment as miniaturized implantable devices require hypoallergenic noble metal surfaces.
EPA oversight of cyanide discharge limits shapes North American formulation choices, while REACH restrictions on hexavalent chromium and cadmium co-deposits redirect European buyers toward sulfite-based alternatives. China's MEE enforces wastewater discharge standards that elevate operating costs for electroplating facilities in Guangdong and Jiangsu provinces. Stakeholders must monitor substitution economics between cyanide and sulfite chemistries as metal price volatility intersects with tightening effluent regulations across major manufacturing jurisdictions.
Market Dynamics
The Gold Plating Chemicals Market faces intensifying pressure from regulatory phase-outs of cyanide-based formulations, forcing suppliers to re-engineer bath chemistries while maintaining deposition efficiency for semiconductor and medical device manufacturers.
Growth Catalysts
- REACH compliance deadlines:European electronics manufacturers are accelerating sulfite-based chemistry adoption ahead of cyanide restrictions, creating replacement demand for compliant formulations.
- Medical device miniaturization:Implantable neuromodulation and cardiovascular devices require biocompatible noble metal coatings, expanding electroless gold consumption.
- China's semiconductor buildout:Domestic fabrication capacity expansion in Jiangsu and Guangdong provinces drives chemical procurement for advanced packaging interconnects.
Market Restraints
- Precious metal price volatility:Gold price swings compress plating service margins and deter long-term chemical supply contracts.
- Refining capacity concentration:Captive precious metals recovery systems cluster among three European suppliers, limiting independent chemical producers' feedstock security.
- Deposition rate trade-offs:Non-cyanide sulfite chemistries achieve slower plating speeds, constraining high-volume connector throughput.
Strategic Opportunities
- Closed-loop recovery systems:Captive refining and spent bath metal reclamation create margin expansion for integrated chemical suppliers.
- Palladium-nickel underplate substitution:Electronics connector manufacturers are layering lower-cost barrier metals to reduce gold thickness requirements.
- India's electronics manufacturing incentives:PLI scheme subsidies for semiconductor and component production build local plating chemical demand.
Industry Challenges
- Formulation chemist scarcity:Expertise in cyanide-to-sulfite bath conversion resides with a shrinking pool of senior electroplating engineers.
- MEE wastewater compliance:China's discharge standards for heavy metals and cyanide complexes require costly effluent treatment infrastructure upgrades.
- Process validation timelines:Medical device OEMs demand 18-24 month qualification cycles for new plating chemistries, delaying supplier switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gold Plating Chemicals Market |
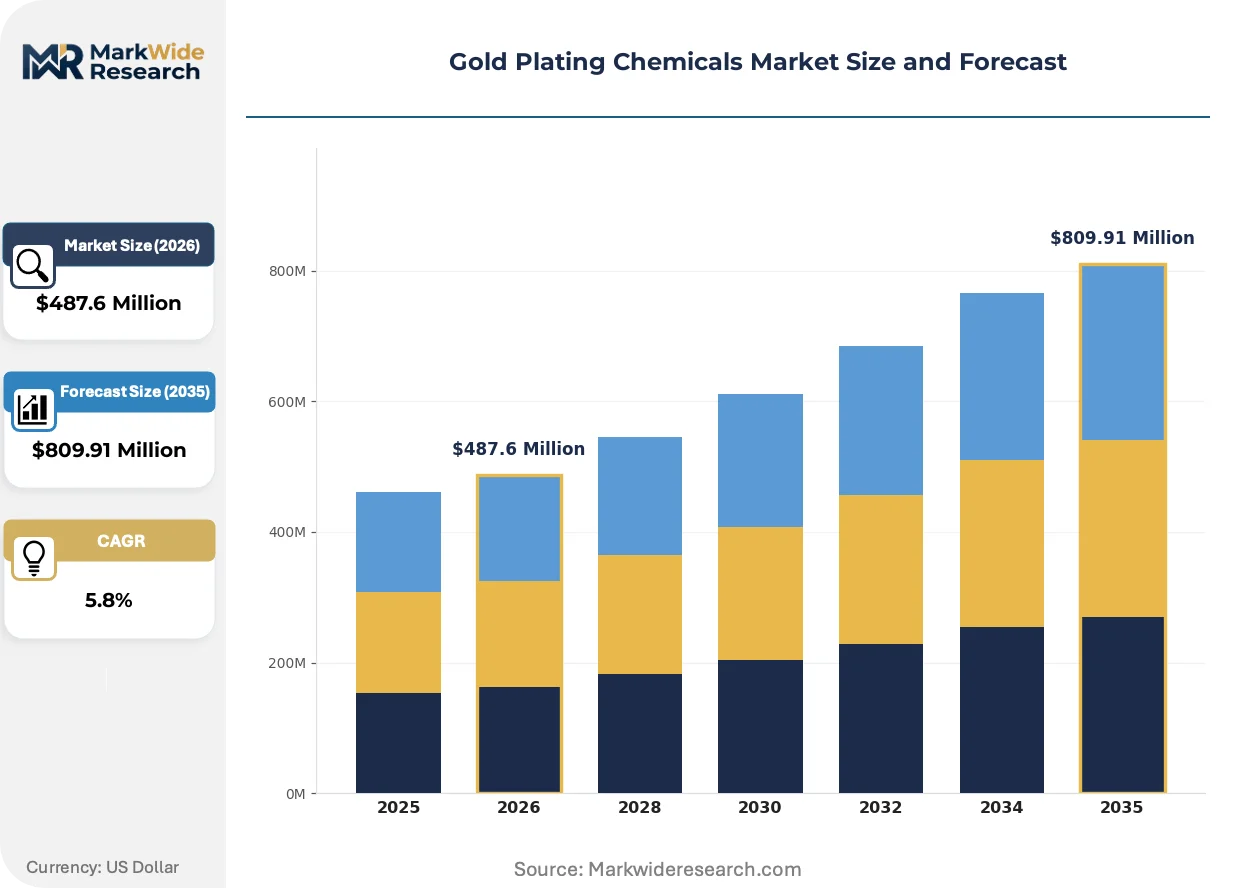
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroless Gold, Gold Cyanide, Gold Sulfite, Gold Chloride Application: Electronics, Jewelry, Aerospace, Medical Devices End User: Manufacturers, Retailers, OEMs, Craftspersons Form: Liquid, Powder, Paste, Solution |
| Companies Covered | Technic Inc., Heimerle + Meule, Umicore, Heraeus, Uyemura International Corporation, Atotech, Johnson Matthey, JCU, MacDermid Enthone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gold Plating Chemicals Market Strategic Shifts
Formulation chemistry is pivoting toward cyanide-free alternatives as deposition efficiency converges with environmental compliance requirements. Process automation and real-time bath monitoring are compressing variability in high-reliability applications.
Gold sulfite electrolytes are integrating into semiconductor packaging lines as deposition uniformity improves to match cyanide bath performance. Advanced substrate manufacturers in South Korea and Taiwan are adopting these formulations for flip-chip and wafer-level packaging. The technology is integrating with existing production equipment without requiring complete line replacement, lowering switching costs.
EPA cyanide discharge limits under the Clean Water Act are tightening effluent standards for electroplating facilities in Ohio and California. North American job shops face capital expenditure requirements for treatment systems or chemistry substitution. Connector manufacturers serving aerospace and defense are most affected, with some qualifying sulfite alternatives ahead of compliance deadlines.
Medical device OEMs are consolidating plating chemical suppliers to reduce qualification burden and secure supply continuity. Large contract manufacturers are specifying approved chemical lists, displacing fragmented regional plating shops. This concentration is most visible in Minnesota and Massachusetts clusters, where pacemaker and implantable device producers dominate procurement volumes.
Gold Plating Chemicals Market Segmentation
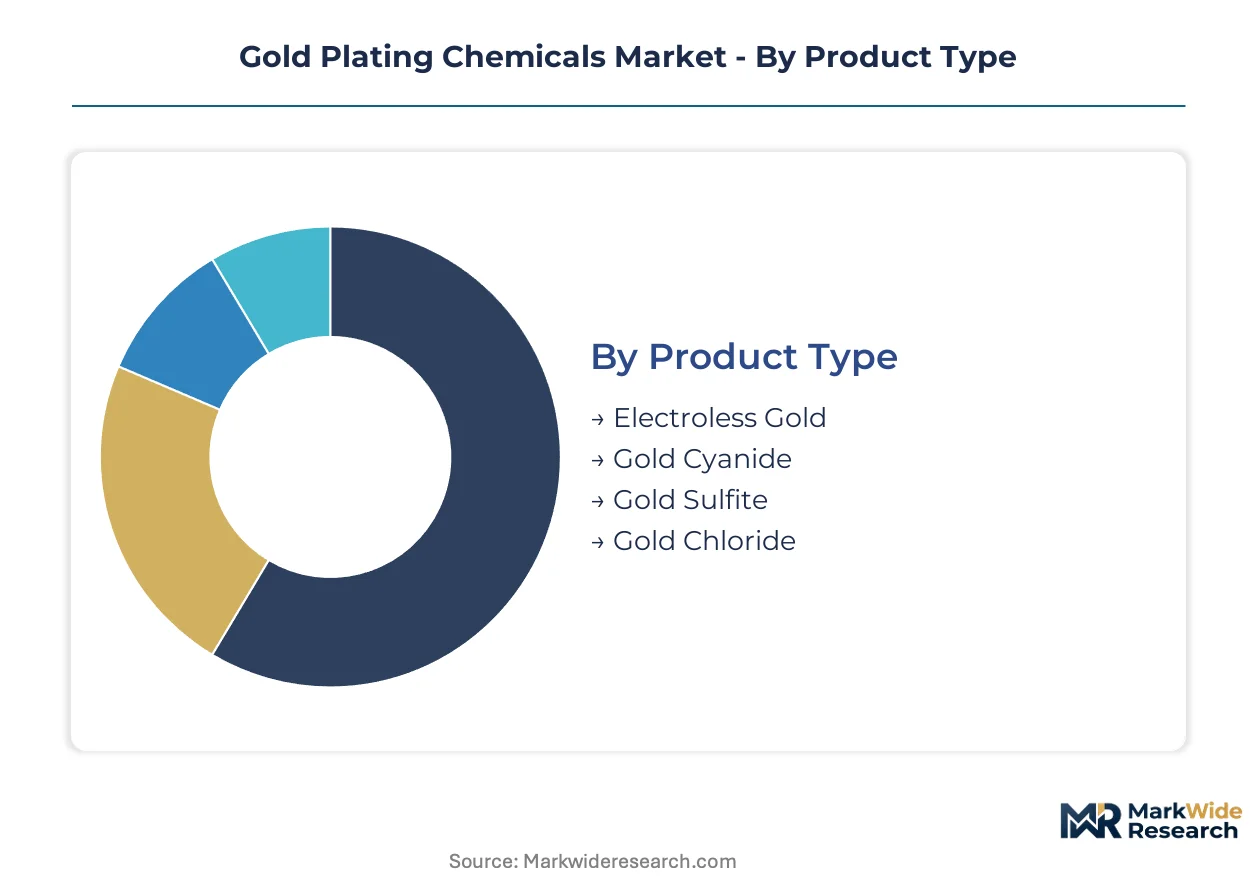
Segmentation in gold plating chemicals reveals how formulation chemistry, application requirements, and delivery form intersect with regulatory pressure and end-use economics. Distinct performance specifications across electronics miniaturization, medical biocompatibility, and decorative durability create divergent procurement patterns among buyers.
Product Type:
Formulation chemistry dictates deposition mechanism, bath stability, and regulatory compliance burden across end-use specifications.
- Electroless Gold:Autocatalytic reduction deposits uniform gold layers without external current, enabling complete coverage of complex geometries in semiconductor packaging. Demand concentrates in South Korean and Taiwanese flip-chip manufacturers as wafer-level packaging density requirements intensify.
- Gold Cyanide:Potassium gold cyanide baths deliver the highest deposition efficiency and operational stability, maintaining volume leadership despite REACH phase-out timelines. European jewelry manufacturers in Pforzheim and Vicenza continue procurement while qualifying sulfite alternatives ahead of compliance deadlines.
- Gold Sulfite:Cyanide-free electrolytes achieve comparable deposition uniformity for high-reliability electronics, with sodium gold sulfite formulations gaining traction in German automotive connector supply chains.
- Gold Chloride:Acidic chloride-based systems serve niche decorative and laboratory applications where deposition thickness requirements remain minimal.
Gold cyanide leads on scale; electroless gold leads on momentum.
Application:
End-use performance specifications range from electrical conductivity and corrosion resistance to biocompatibility and aesthetic durability.
- Electronics:Printed circuit board edge connectors, semiconductor packaging interconnects, and high-frequency RF components require low-contact resistance and fretting corrosion immunity. Jiangsu and Guangdong fabrication hubs in China drive procurement volume for advanced packaging chemistries.
- Medical Devices:Implantable pacemakers, neuromodulation systems, and surgical instruments demand hypoallergenic surfaces meeting ISO 10993 biocompatibility standards. Minnesota and Massachusetts device clusters specify approved chemical lists, consolidating supplier relationships.
- Jewelry:Decorative finishes prioritize color consistency and wear resistance over electrical properties, with Italian and Indian manufacturing centers sustaining distinct formulation preferences.
- Aerospace:Satellite and avionics connectors require extended thermal cycling performance, with sulfite formulations qualifying for defense contractor specifications under EPA discharge constraints.
Electronics dominates procurement volume; medical devices shows the steepest expansion trajectory.
End User:
Procurement scale and technical sophistication vary sharply across integrated manufacturers versus fragmented service providers.
- Manufacturers:Integrated electronics and medical device producers operate captive plating lines with direct chemical procurement, qualifying formulations through 18-24 month validation cycles.
- OEMs:Original equipment manufacturers specify plating requirements for outsourced component production, consolidating approved supplier lists to reduce qualification burden.
- Retailers:Jewelry and decorative goods distributors source finished plated products rather than raw chemicals, with limited direct market participation.
- Craftspersons:Artisanal jewelers and small repair shops consume pre-mixed solutions through distributor channels, representing minimal individual volume.
Manufacturers command procurement scale; OEMs concentrate specification authority.
Form:
Physical delivery state determines handling protocols, shelf stability, and integration with automated dosing systems.
- Liquid:Ready-to-use electrolytes dominate high-volume manufacturing with integrated bath monitoring and automated replenishment systems.
- Powder:Concentrated salts reduce shipping costs and extend storage stability, requiring on-site dissolution for jewelry and job shop applications.
- Solution:Pre-diluted formulations serve small-batch users and quality-sensitive medical device prototyping with minimal preparation variability.
- Paste:Thick-film compositions enable selective brush plating and touch-up repair in aerospace maintenance and jewelry restoration.
Liquid formulations lead on scale; powder concentrates gain share in cost-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Guangdong provinces anchor procurement volume for gold plating chemicals, with semiconductor fabrication hubs driving formulation demand across multiple jurisdictions amid tightening environmental compliance.
China
Domestic packaging capacity expansion in Suzhou and Shenzhen sustains chemical consumption for flip-chip interconnects. MEE wastewater discharge standards enforce costly effluent treatment upgrades across electroplating facilities. Guangdong's Pearl River Delta cluster concentrates advanced substrate manufacturing with captive plating lines qualifying sulfite alternatives.
Germany
Automotive connector manufacturers in Baden-Württemberg specify sodium gold sulfite formulations for high-reliability supply chains. REACH phase-out timelines for cyanide-based chemistries accelerate bath conversion programs. Pforzheim's jewelry manufacturing district maintains dual sourcing strategies while qualifying compliant alternatives.
United States
Minnesota and Massachusetts medical device clusters consolidate approved chemical lists for implantable pacemaker production. EPA cyanide discharge limits under the Clean Water Act tighten effluent standards for Ohio and California plating facilities. Aerospace connector manufacturers in Southern California qualify sulfite formulations ahead of compliance deadlines.
Japan
High-frequency RF component producers in Tokyo and Osaka prefectures demand low-contact resistance coatings for 5G infrastructure. METI industrial standards guide electroplating facility environmental management practices. Kyushu's semiconductor materials corridor integrates gold sulfite electrolytes into wafer-level packaging lines.
South Korea
Memory and logic chip packaging operations in Gyeonggi Province drive electroless gold consumption for uniform bump coverage. Korean Industrial Standards specify plating thickness tolerances for semiconductor interconnects. Suwon and Pyeongtaek fabrication complexes adopt real-time bath monitoring systems to compress process variability.
Gold Plating Chemicals Market Competitive Environment
Global majors compete with regional champions across precious metals refining heritage and captive recovery capabilities. The vendor base stratifies between integrated refiners with closed-loop systems and independent formulation specialists serving fragmented job shop segments. Three archetypes dominate: European precious metals houses with backward integration into refining, Asian chemical specialists with process equipment bundling, and diversified materials conglomerates with broad surface technology portfolios. Competitive moves center on sulfite chemistry R&D partnerships and captive metal reclamation capacity expansion.
Within the integrated refiner archetype, Umicore and Heraeus occupy positions defined by precious metals recovery infrastructure and high-reliability electronics specialization. Heimerle + Meule exemplifies the European jewelry-focused tier, leveraging regional heritage in decorative plating supply. Among Asia-Pacific formulation specialists, Uyemura International Corporation represents the equipment-integrated service model prevalent in semiconductor packaging corridors.
| Leading Market Players |
|---|
| Technic Inc. |
| Heimerle + Meule |
| Umicore |
| Heraeus |
| Uyemura International Corporation |
| Atotech |
| Johnson Matthey |
| JCU |
| MacDermid Enthone |
| Others |
Value Chain & Pricing Dynamics
Medical device OEM consolidation toward approved chemical lists is compressing supplier margins and forcing formulation specialists to absorb qualification costs or cede volume to integrated refiners with captive recovery systems.
Pricing Analysis
Input-cost pass-through from precious metal volatility dominates pricing dynamics, with gold price swings transmitted directly to bath chemistry contracts through quarterly adjustment clauses. Three-tier pricing structure across premium sulfite formulations, standard cyanide alternatives, and economy-grade chloride systems differentiates buyers by certification tier and volume commitment. Cost compression in standard-tier electronics plating is intensifying because REACH compliance deadlines accelerate chemistry conversion programs. Job shops in fragmented regional markets exhibit highest price sensitivity, while captive plating lines at semiconductor fabricators prioritize deposition uniformity over unit cost.
Supply Chain Analysis
ISO 10993 biocompatibility certification and 18-24 month OEM qualification cycles gate supply relationships, concentrating procurement authority among integrated refiners with established medical device approvals. Precious metals refining capacity clusters in Germany, Belgium, and Japan, with feedstock security resting on captive recovery systems rather than spot market sourcing. Sodium gold sulfite, potassium gold cyanide, and palladium-nickel barrier metals constitute critical input dependencies. Single-source vulnerability pervades high-reliability electronics segments where Heraeus and Umicore dominate qualified supplier lists. Distribution runs through direct technical sales for large manufacturers and regional distributors for jewelry job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gold plating chemicals constitute a late-cycle quality market where specification tightening toward REACH-compliant sulfite formulations rewards suppliers with proven deposition efficiency and established OEM validation records.
For Market Incumbents: Deploy captive refining capacity expansion to secure feedstock independence against precious metal price volatility. Deepen backward integration into spent bath metal reclamation to capture margin from circular chemistry economics. Consolidate formulation chemist expertise through targeted acquisition of regional specialists facing REACH compliance cost burdens. For New Entrants and Emerging Players: Digital direct-to-manufacturer technical service platforms offer route to bypass entrenched distributor relationships in India's PLI-subsidized electronics manufacturing corridors. Target sulfite chemistry supply gaps in South Korean flip-chip packaging expansion as the most penetrable white-space. Pursue equipment-bundled service models to lower customer switching costs against established Asian chemical specialists. For Investors and Strategic Acquirers: Asymmetric upside sits with European mid-cap formulation houses possessing REACH-compliant sulfite portfolios and pending medical device OEM qualifications. Five-to-ten year viability hinges on substitution economics between cyanide and sulfite chemistries converging with regulatory enforcement timelines. Watch for MEE wastewater discharge standard tightening in Jiangsu and Guangdong as inflection signal for sulfite adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metals Recovery | Umicore's closed-loop systems demonstrate margin expansion potential through captive metal reclamation. |
| Sulfite Chemistry R&D Partnership | Collaborations between German automotive connector manufacturers and formulation houses accelerate REACH compliance timelines. |
| Long-term Supply Agreement | Minnesota medical device clusters consolidate procurement through approved chemical lists reducing qualification burden. |
| Joint Venture in India | PLI scheme subsidies for semiconductor fabrication create localized chemical production economics. |
| Green Manufacturing Transition | Guangdong electroplating facilities invest in effluent treatment infrastructure under MEE discharge standards. |
Study Parameters
Bottom-up electronics and medical device demand modeling reconciled against top-down precious metals refining capacity tracking forms the analytical core of this study. Primary interviews with electroplating plant managers, procurement leads at semiconductor packaging houses, biomedical engineers at implantable device manufacturers, and technical R&D directors at formulation specialists were cross-validated against secondary sources including ECHA REACH registration databases, SEC filings from integrated refiners, customs trade data for gold salt imports, and MEE wastewater discharge compliance records.
Input-output matrices mapping formulation chemistry consumption to end-use fabrication capacity across product type, application, and regional production hub dimensions structured the projection framework. CAGRs were derived from segment-level demand elasticity analysis against semiconductor packaging buildout timelines and medical device miniaturization trajectories. Gold price volatility assumptions and regulatory phase-out schedules for cyanide-based chemistries informed scenario-weighted outputs across the analysis window.
The model assumes a particular technology adoption path favoring sulfite electrolyte convergence with cyanide bath performance; alternative pathways for electroless gold deposition efficiency breakthroughs would alter the outlook. Forecasts reflect documented assumptions regarding REACH enforcement timing and MEE standard implementation. A model refresh is warranted upon material change in precious metals price volatility regimes or regulatory acceleration of cyanide discharge limits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Construction Chemicals Market
Chemicals
Peroxyacetic Acid Market
Chemicals
Aluminum Chemicals Market
Chemicals
Aerosol Insecticides Market
Chemicals
Industrial Odor Management Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
South America Construction Chemicals Market
Chemicals
Flatting Agents Market
Chemicals
Tanning Agents Market
Chemicals
Chromium Trioxide Market
Chemicals
Acetophenone Market
Chemicals
Glycerol Carbonate Market
Chemicals
Barbituric Acid Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Calcium Hydroxide Market