
 Hydroxyzine Imine Market | 2026-2036
Hydroxyzine Imine Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxyzine Imine Market Analysis
Market Context with Strategic Players
Pharmaceutical-grade hydroxyzine imine specification is collapsing toward USP-grade standards as generic manufacturers compete on API purity. Pfizer Inc. leverages its vertical integration across active pharmaceutical ingredient synthesis to sustain cost advantages in hydroxyzine derivative production. Teva Pharmaceutical Industries anchors its position through specialized generic formulation capabilities, while Novartis International AG differentiates via advanced process chemistry for imine intermediates.
Technical Definition and Structural Segments
Hydroxyzine imine denotes the imine-functionalized intermediate in hydroxyzine synthesis, a piperazine-class compound manufactured through condensation reactions requiring controlled pH and temperature parameters to achieve specified purity thresholds above 99.5 percent. The substance serves primarily as a precursor in antihistamine and anxiolytic drug production for pharmaceutical applications. Tablet formulation dominates volume consumption across hospital and clinic channels, while injection delivery commands premium positioning in acute sedation settings where rapid onset determines therapeutic utility. Anxiety relief applications attract the fastest-growing demand as outpatient psychiatric prescribing expands, whereas allergy treatment segments remain mature with stable replacement demand.
Regulatory Framework and Outlook
FDA Current Good Manufacturing Practice standards govern hydroxyzine imine production for US-bound APIs, while EMA guidelines and ICH Q7 specifications shape quality benchmarks for European market access. India's CDSCO mandates import testing protocols that delay shipment clearance for non-registered foreign manufacturers, redirecting procurement toward domestic BIS-certified suppliers. Stakeholders must monitor evolving pharmacopeial monograph revisions and track DEA scheduling deliberations for hydroxyzine derivatives that could reshape formulation strategies.
Market Dynamics
FDA purity standard tightening is compressing supplier margins while concentrating procurement toward CDMOs with validated continuous-flow synthesis capabilities. This regulatory pressure is accelerating consolidation among intermediate manufacturers unable to fund compliance infrastructure upgrades.
Growth Catalysts
- USP-grade specification convergence:Generic API manufacturers are upgrading imine intermediate specifications to match innovator-grade thresholds, expanding addressable demand from formulation houses serving Western markets.
- Outpatient psychiatric prescribing expansion:Anxiety relief applications are pulling volume through hospital and clinic channels as behavioral health integration accelerates in primary care settings.
- Contract manufacturing cluster development:CDMO concentration in India and China is creating captive supply ecosystems that reduce Western sponsor qualification timelines.
Market Restraints
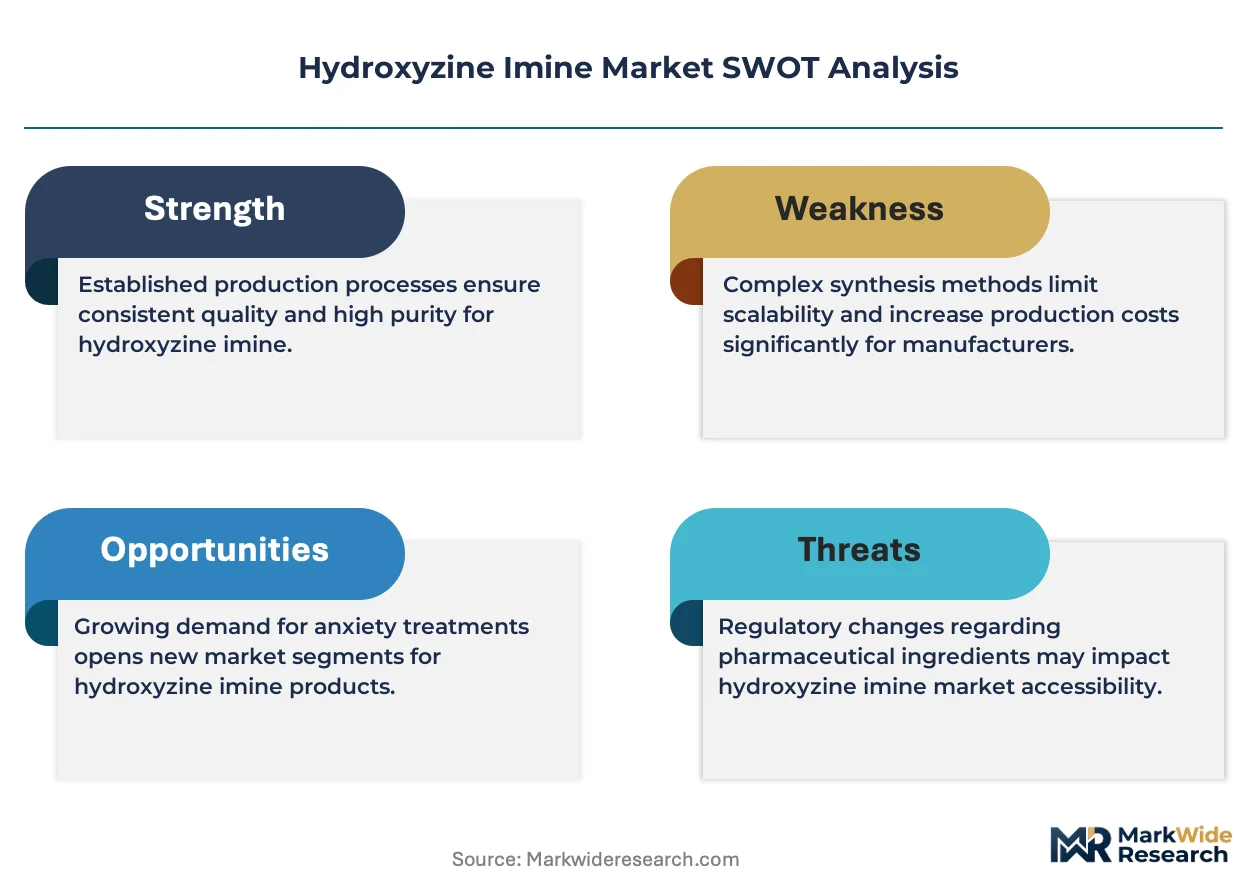
- Input cost volatility in piperazine feedstocks:Petrochemical-derived starting materials expose manufacturers to crude-linked pricing swings that compress batch economics.
- Supply concentration in dual-source geographies:Overreliance on Indian and Chinese CDMOs creates geopolitical exposure and contingency planning costs for Western drug sponsors.
- Technical limitation in impurity profiling:Genotoxic impurity detection at sub-ppm thresholds requires capital-intensive analytical infrastructure that excludes smaller synthesis houses.
Strategic Opportunities
- Brazilian regulatory pathway acceleration:ANVISA's streamlined API import registration is opening procurement channels for intermediate suppliers with established DMF filings.
- Pediatric formulation expansion:Liquid and orally disintegrating tablet formats for hydroxyzine derivatives are creating specialized imine purity requirements that command formulation premiums.
- Green chemistry incentive alignment:EPA sustainable manufacturing grants and EU Green Deal funding are subsidizing solvent reduction investments in imine condensation processes.
Industry Challenges
- Analytical chemist talent scarcity:Qualified personnel for ICH Q3D elemental impurity and nitrosamine risk assessment are concentrated at top-tier CDMOs, inflating compensation costs.
- Legacy equipment retrofitting capex:Continuous-flow reactor adoption requires complete batch infrastructure replacement, straining mid-tier manufacturers with depreciated asset bases.
- DMF amendment cycle delays:FDA responses to post-approval manufacturing change notifications are extending supplier qualification timelines and freezing process improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxyzine Imine Market |
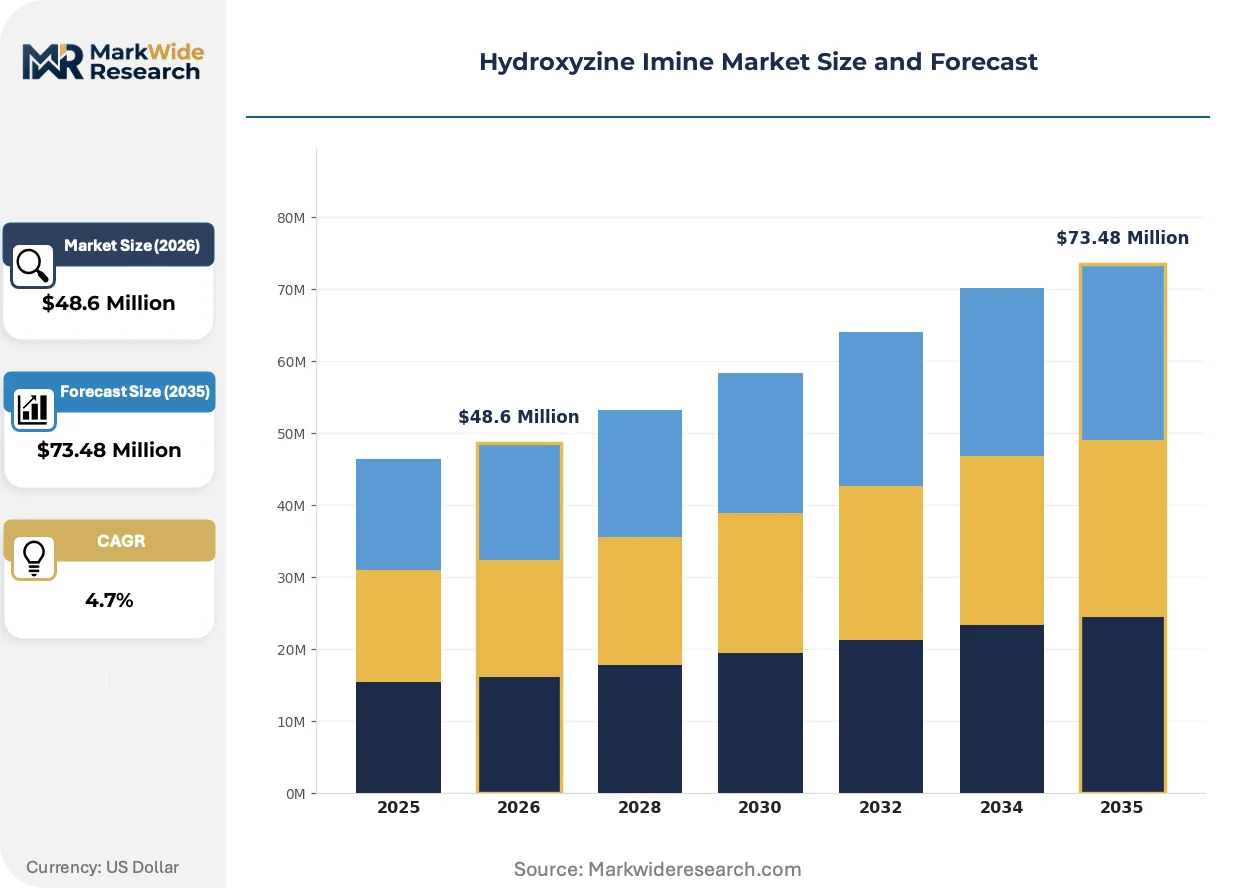
| Market Size in 2026 | $48.6 Million |
| Market Size in 2035 | $73.48 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Tablet, Syrup, Injection, Oral Solution End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Application: Anxiety Relief, Allergy Treatment, Sedation, Antiemetic Delivery Mode: Intravenous, Oral, Intramuscular, Subcutaneous |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries, GlaxoSmithKline plc, Novartis International AG, Piramal Healthcare UK Limited, Lupin Pharmaceuticals, Inc., Alliance Pharma PLC, Shanghai Ruizheng Chemical Technology Co., Ltd, Impax Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxyzine Imine Market Emerging Trajectories
Continuous-flow reactor technology is supplanting batch synthesis across intermediate manufacturing, while regulatory pharmacopeial harmonization and buyer procurement centralization are restructuring competitive access. These forces are compressing the viable supplier base toward integrated technical specialists.
Continuous-flow condensation systems are supplanting traditional batch vessels in hydroxyzine imine production, enabling real-time pH and temperature control that reduces impurity formation. Mid-scale CDMOs in India are adopting this technology to meet USP-grade specifications without capital-intensive cleanroom expansion. The shift is supplanting smaller batch operators unable to fund reactor retrofitting, concentrating supply among technology-advantaged manufacturers.
EMA's revised nitrosamine risk assessment guidelines are mandating comprehensive amine impurity screening across all piperazine-class intermediates. European formulation sponsors are now requiring CDMOs to submit enhanced nitrosamine control strategies prior to API sourcing agreements. This regulatory tightening is most acute for injection-grade hydroxyzine derivatives, where impurity thresholds are tightest and analytical burden highest.
Western drug sponsors are consolidating intermediate procurement through preferred CDMO partnerships with locked volume commitments and multi-year pricing. This behavioral shift is displacing spot-market purchasing and fragmenting access for non-prequalified suppliers. The pattern is most visible in North American psychiatric formulation supply chains, where sponsor quality audit costs favor incumbent relationship deepening over supplier diversification.
Hydroxyzine Imine Market Segmentation
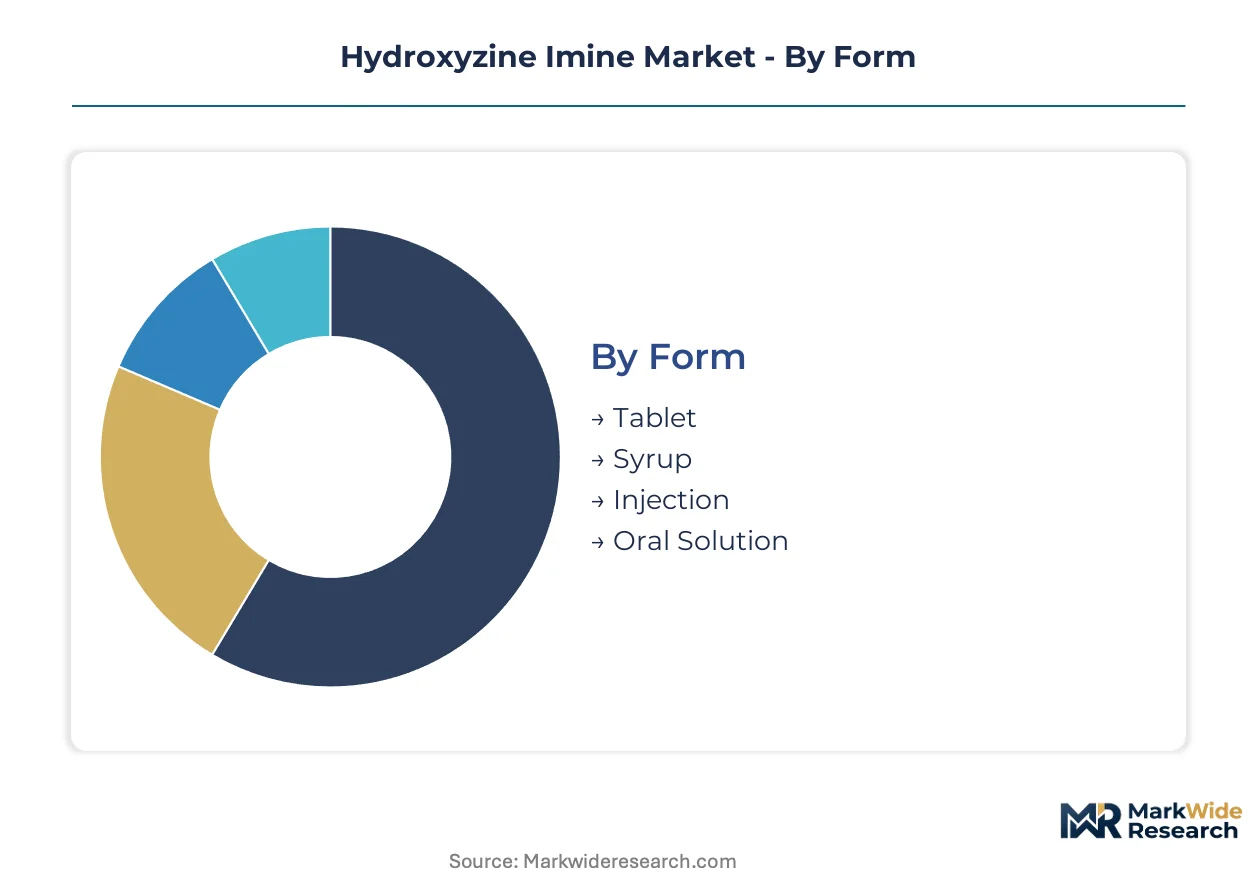
Hydroxyzine imine demand fragments across formulation formats, care settings, therapeutic targets, and administration routes. Each dimension carries distinct purity specifications and regulatory burdens that reshape supplier economics.
Form:
Tablet formulations face intensifying substitution pressure from orally disintegrating formats and liquid alternatives in pediatric and geriatric populations.
- Tablet:Compressed dosage forms dominate psychiatric outpatient prescribing for anxiety indications. Solid-state stability requirements favor crystalline imine intermediates with defined polymorph control. Hospital and clinic channels in the United States absorb the largest volume under FDA stability-testing protocols.
- Injection:Parenteral-grade hydroxyzine imine demands the highest purity thresholds for acute sedation in emergency departments. Aseptic processing requirements and endotoxin limits concentrate procurement among EMA-validated European CDMOs serving Western European hospital networks.
- Syrup:Liquid oral formulations serve pediatric allergy treatment with flavor-masked delivery systems. Palatability requirements impose additional excipient compatibility testing on imine intermediate specifications.
- Oral Solution:Unit-dose sachets and reconstitutable powders expand home care access. Convenience-driven packaging formats are gaining traction in Japanese and South Korean retail pharmacy channels.
Tablet anchors the volume base while Injection gains share at the steepest rate.
End User:
Cost tier stratification separates institutional buyers with locked procurement contracts from dispersed retail channels with spot-market pricing.
- Hospitals:Integrated health systems leverage formulary control to standardize on preferred hydroxyzine derivative suppliers. Bulk purchasing agreements with Indian CDMOs reduce per-unit API costs for high-throughput emergency departments.
- Clinics:Outpatient psychiatric practices drive anxiety-relief volume through electronic prescribing networks. Reimbursement coding alignment with behavioral health integration mandates shapes product selection.
- Home Care:Post-acute and long-term care settings favor simplified dosing regimens. Oral solution and syrup formats predominate for patient self-administration outside supervised environments.
- Rehabilitation Centers:Substance-use and dual-diagnosis facilities utilize hydroxyzine for alcohol withdrawal symptom management. Controlled-substance adjacent prescribing requires enhanced documentation and DEA-compliant supply chain tracking in the United States.
Hospitals anchor the volume base while Home Care climbs the fastest as aging-in-place policies expand reimbursement for outpatient psychiatric medication management.
Application:
Maturity gradients separate established allergy indications from expanding psychiatric uses with evolving clinical guidelines.
- Anxiety Relief:First-line anxiolytic prescribing in primary care settings is pulling imine intermediate demand toward higher-purity specifications. FDA guidance on non-benzodiazepine alternatives is reshaping formulary placement in United States health systems.
- Allergy Treatment:Antihistamine applications face generic commoditization with stable replacement demand. Seasonal prescribing patterns in European markets create predictable but low-margin volume cycles.
- Sedation:Pre-operative and procedural sedation requirements in hospital settings demand rapid-onset pharmacokinetics. Injection-grade imine intermediates command premium positioning for operating room and endoscopy suite applications.
- Antiemetic:Chemotherapy-induced nausea prophylaxis utilizes hydroxyzine as an adjunct therapy. Oncology clinic networks in Germany and France are expanding procurement for supportive care protocols.
Allergy Treatment anchors the volume base while Anxiety Relief expands most quickly through behavioral health integration in primary care.
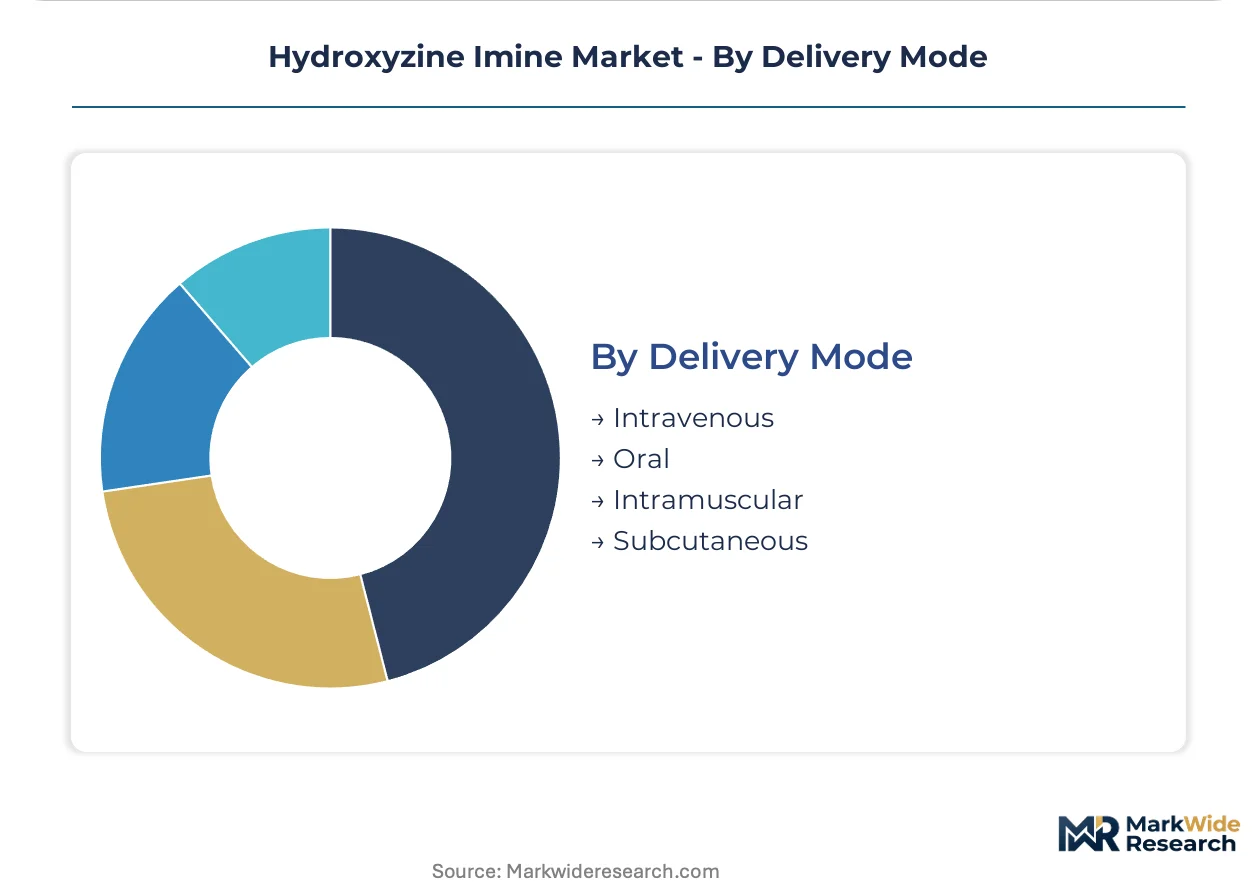
Delivery Mode:
Supply concentration in validated aseptic manufacturing creates margin tiering between oral and parenteral routes.
- Oral:Swallowed tablet and liquid formats dominate total consumption with the lowest barrier to intermediate qualification. CDMOs in Ahmedabad and Hyderabad, India, specialize in high-volume oral-grade imine production for Western generic sponsors.
- Intravenous:Direct vascular administration requires sterile imine derivatives with particulate matter controls. EMA GMP Annex 1 compliance costs restrict viable suppliers to tier-one manufacturers with isolator technology.
- Intramuscular:Depot injection formats extend duration of action for acute agitation management. Psychiatric emergency services in the United Kingdom favor this route for rapid tranquilization protocols.
- Subcutaneous:Minimally invasive delivery is emerging for home-based sedation applications. Device-compatible formulation development is driving specialized imine purity requirements in Swiss and German innovation clusters.
Oral anchors the volume base while Intravenous commands the steepest premium expansion through hospital consolidation of parenteral manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intermediate manufacturing clusters in India and China supply the bulk of pharmaceutical-grade hydroxyzine imine, while formulation demand concentrates in North American and European psychiatric care networks. Regulatory divergence across FDA, EMA, and national pharmacopeial standards fragments qualification pathways.
United States
Hospital systems and outpatient psychiatric clinics drive hydroxyzine derivative consumption through integrated formulary management. FDA Current Good Manufacturing Practice standards enforce USP-grade purity thresholds above 99.5 percent for API-bound intermediates. New Jersey and Massachusetts host contract research organizations that qualify Indian CDMOs for sponsor relationships.
Germany
EMA-validated manufacturers serve Western European hospital networks with parenteral-grade imine specifications for emergency sedation protocols. EMA revised nitrosamine risk assessment guidelines mandate comprehensive amine impurity screening across piperazine-class intermediates. The Rhine-Ruhr industrial corridor concentrates sterile API finishing capabilities for injection-grade derivatives.
India
CDMO clusters in Ahmedabad and Hyderabad produce oral-grade hydroxyzine imine for Western generic sponsors under locked volume commitments. CDSCO import testing protocols redirect procurement toward domestic BIS-certified suppliers with validated continuous-flow synthesis. Gujarat's pharmaceutical manufacturing belt anchors capacity expansion for USP-grade intermediate exports.
China
Petrochemical feedstock access supports piperazine derivative production at scale, though NMPA export certification requirements complicate Western market access. NMPA Good Manufacturing Practice inspections align with ICH Q7 specifications for international API supply. Shanghai and Zhejiang province house intermediate specialists upgrading batch infrastructure to continuous-flow reactor systems.
Brazil
Psychiatric medication demand expands through unified health system procurement and private insurance formulary inclusion. ANVISA streamlined API import registration opens procurement channels for intermediate suppliers with established DMF filings. São Paulo state concentrates formulation manufacturing for Latin American distribution.
Hydroxyzine Imine Market Vendor Landscape
Concentration sits with vertically integrated pharmaceutical conglomerates and specialized contract manufacturers serving Western drug sponsors. The supplier base compresses toward CDMOs with validated continuous-flow capabilities and EMA/FDA dual-site inspections. Three archetypes dominate: innovator-origin API producers with captive intermediate supply, Indian-Chinese CDMOs with cost-optimized batch infrastructure, and European specialists in parenteral-grade purification. Competitive moves center on backward integration into piperazine feedstock sourcing and multi-year preferred supplier agreements with locked pricing.
Among innovator-origin producers, Pfizer Inc. and Novartis International AG occupy positions reflecting vertical control over synthesis pathways. Teva Pharmaceutical Industries exemplifies the generic-specialist archetype with formulation-driven intermediate demand. Piramal Healthcare UK Limited and Lupin Pharmaceuticals, Inc. represent the India-UK CDMO nexus serving Western sponsor qualification programs.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries |
| GlaxoSmithKline plc |
| Novartis International AG |
| Piramal Healthcare UK Limited |
| Lupin Pharmaceuticals, Inc. |
| Alliance Pharma PLC |
| Shanghai Ruizheng Chemical Technology Co., Ltd |
| Impax Laboratories, Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day CDMO qualification timelines compress procurement windows and amplify pricing power for pre-validated Indian and Chinese suppliers serving Western drug sponsors. This lead-time band concentrates buyer dependence on incumbent contract manufacturers while squeezing spot-market alternatives.
Pricing Analysis
FDA Current Good Manufacturing Practice standards dictate the pricing tier structure across hydroxyzine imine supply, separating USP-grade certified batches from lower-specification alternatives. Pricing stratifies across injection-grade premium tiers, oral-grade standard tiers, and non-pharmaceutical economy tiers based on purity thresholds and endotoxin documentation. Cost compression in oral-grade segments is intensifying because generic API manufacturers consolidate volume through locked multi-year contracts. Hospital procurement committees exhibit the highest price sensitivity due to formulary budget constraints, while specialty CDMOs serving parenteral applications face the least pressure.
Supply Chain Analysis
Piperazine feedstock availability through Shanghai and Zhejiang province petrochemical corridors underwrites intermediate production scale for hydroxyzine imine synthesis. Manufacturing concentrates in India, China, and Germany, with Ahmedabad and Hyderabad clusters feeding oral-grade demand and Rhine-Ruhr facilities serving parenteral-grade requirements. Raw material dependencies rest on petrochemical-derived piperazine, acetic anhydride catalysts, and crystallization solvents. Single-source vulnerability in dual-source geographies creates contingency planning costs for Western sponsors. Distribution runs through preferred CDMO partnerships with direct API sponsor relationships rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-flow reactor adoption represents a technological inflection that will disrupt batch-dominant supply structures and reshape competitive viability across the forecast window.
For Market Incumbents: Shield market position by accelerating backward integration into piperazine feedstock sourcing and securing EMA/FDA dual-site inspection status before regulatory tightening excludes mid-tier competitors. Continuous-flow technology displacement threatens batch-dependent manufacturers with stranded asset risk. Locked volume commitments with Western sponsors provide the strongest defensive lever against spot-market erosion. For New Entrants and Emerging Players: Pediatric formulation capability gaps expose white-space opportunity in liquid and orally disintegrating tablet formats where specialized imine purity requirements command formulation premiums. Brazil's ANVISA streamlined registration pathway offers the most penetrable geography for intermediate suppliers with established DMF filings. Green chemistry positioning unlocks EPA and EU Green Deal subsidy access as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates spinning non-core intermediate manufacturing units amid portfolio rationalization pressures. Long-term viability favors CDMOs with validated continuous-flow infrastructure and cross-regulatory inspection history. Nitrosamine control strategy submission rates signal regulatory readiness differentiation worth monitoring as an inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Reactor Adoption | Real-time process control enables USP-grade purity without capital-intensive cleanroom expansion. |
| Backward Integration into Piperazine Feedstocks | Captive supply of petrochemical-derived starting materials insulates batch economics from crude-linked volatility. |
| EMA/FDA Dual-Site Inspection Qualification | Cross-regulatory validation opens procurement channels for parenteral-grade hospital network supply. |
| Pediatric Formulation Development | Liquid and ODT formats create specialized imine purity requirements with premium positioning potential. |
| Green Chemistry Process Certification | EPA sustainable manufacturing grants subsidize solvent reduction investments in condensation chemistry. |
Methodological Framework
Desk research of FDA drug master file databases, EMA regulatory submission records, and Indian CDSCO import registration logs preceded structured interviews with API procurement directors, CDMO operations heads, regulatory affairs specialists, and hospital formulary managers. Primary fieldwork combined telephone and video interviews with secondary validation against customs trade data, pharmaceutical manufacturing capacity disclosures, and pharmacopeial monograph revision notices. Bottom-up volume estimates from intermediate production capacities triangulated against top-down API demand projections from psychiatric prescribing databases.
Variance decomposition across formulation format, therapeutic application, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation modeling incorporated purity grade tier, end-use care setting, administration route, and CDMO certification status as core dimensions. CAGRs derived from volume-weighted average growth rates across segment-specific demand trajectories, with continuous-flow technology penetration curves and regulatory compliance cost inflation as key forecast inputs.
Underlying assumptions cover sustained FDA purity standard enforcement, stable petrochemical feedstock availability, and intact India-China export certification pathways, with deviation risk concentrated in DEA scheduling deliberations for hydroxyzine derivatives and geopolitical disruption to dual-source geographies. Practitioners should keep alternative scenarios live as nitrosamine guideline revisions and continuous-flow technology diffusion curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Benzalkonium Bromide Market
Chemicals
India Ethoxylates Market
Chemicals
SLS and LABSA Market
Chemicals
Spirodiclofen Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Global Glycine Market
Chemicals
Methanol to Gasoline Market
Chemicals
Egypt Acidulants Market
Chemicals
3,5-Dinitroaniline Market
Chemicals
Methidathion (CAS 950-37-8) Market
Chemicals
India Anhydrous Hydrogen Fluoride Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
North America Ethylene Dichloride (EDC) Market
Chemicals
3-Iodoaniline Market
Chemicals
Global N-Butanol Market
Chemicals
Global Cysteine Market