
 Natural Fatty Alcohols Market | 2026-2036
Natural Fatty Alcohols Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Fatty Alcohols Market Analysis
Personal care is restructuring demand patterns for natural fatty alcohols as clean-label formulations displace petrochemical alternatives in premium skincare and haircare lines. KLK OLEO leverages its integrated Malaysian palm kernel oil supply chain to secure feedstock cost advantages. BASF competes through biotechnology investments that expand microbial fermentation routes beyond traditional triglyceride hydrolysis. Ecogreen Oleochemicals anchors its position with dedicated lauryl and myristyl alcohol capacity serving Asian detergent manufacturers.
Natural fatty alcohols are saturated or unsaturated long-chain alcohols typically derived from coconut oil, palm kernel oil, or tallow through high-pressure hydrogenation of methyl esters or fatty acids, yielding carbon chain lengths from C8 to C22 with melting points ranging from 15°C to 72°C depending on chain length and saturation. These compounds function primarily as non-ionic surfactant precursors, emulsion stabilizers, and viscosity modifiers across consumer and industrial formulations. Lauryl alcohol dominates volume flows through its role as the principal feedstock for sodium lauryl sulfate and related detergent intermediates. Cetyl and stearyl alcohols command margin premiums in cosmetics and pharmaceutical ointments where emollient performance and label claims drive purchasing decisions.
REACH registration requirements in Europe mandate comprehensive toxicological dossiers for fatty alcohol substances imported above one tonne annually, while the EU Green Deal pushes downstream formulators toward certified sustainable palm and mass-balance chain-of-custody documentation. EPA Safer Choice labeling in the United States creates parallel demand pull for biobased surfactant building blocks with verified lifecycle profiles. India's BIS standards for detergent-grade fatty alcohols impose quality specifications that shape import sourcing patterns for domestic formulators. Stakeholders must monitor evolving biofuel policy intersections in Southeast Asia that could divert palm kernel oil volumes away from oleochemical channels.
Market Dynamics
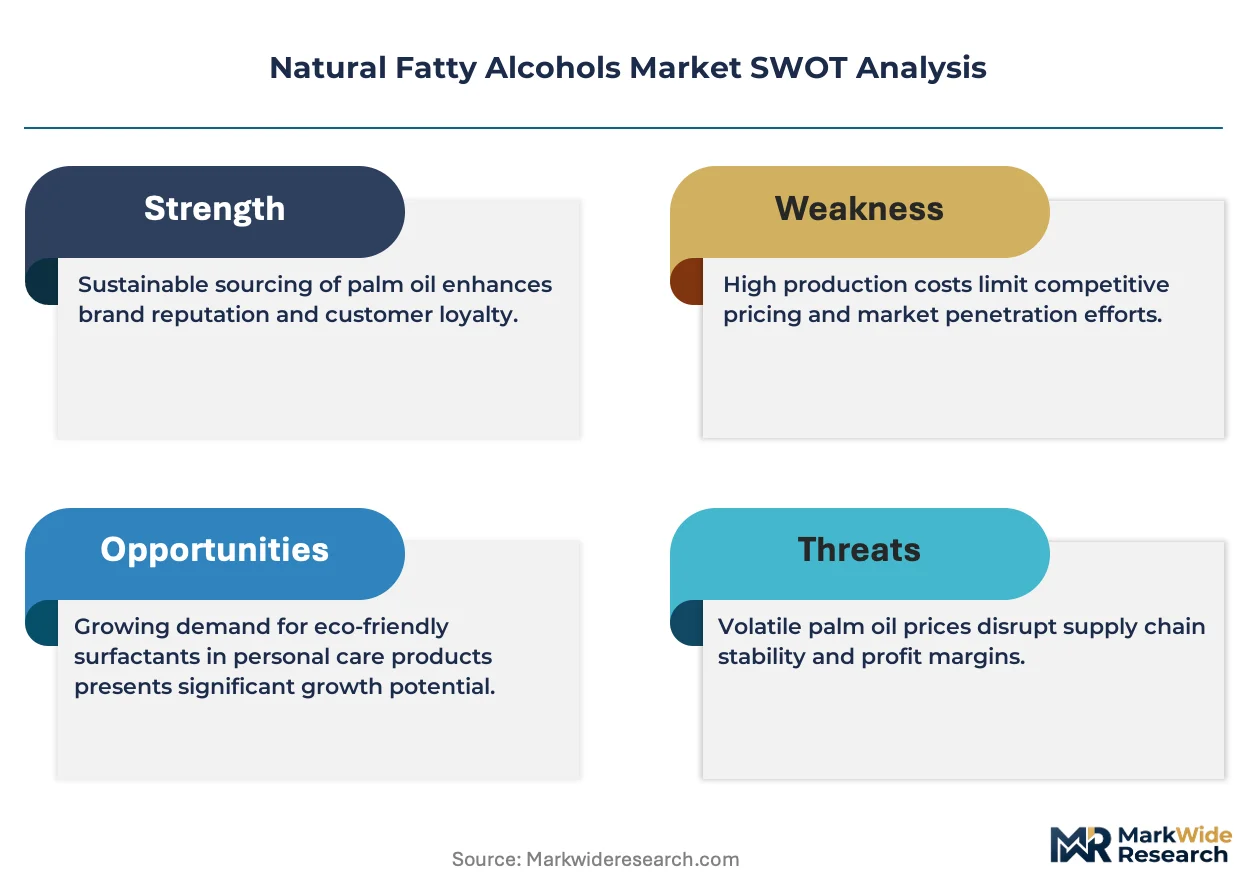
Clean-label mandates from personal care formulators are restructuring feedstock procurement toward certified sustainable palm and coconut derivatives, compressing margins for producers lacking mass-balance chain-of-custody documentation.
Growth Catalysts
- EU Green Deal traceability requirements:Downstream brands now require certified sustainable palm documentation, pulling volume toward audited oleochemical suppliers with integrated plantation-to-alcohol capabilities.
- Surfactant demand in Southeast Asian personal care:Indonesian and Malaysian formulators are expanding plant-derived surfactant procurement for domestic and export skincare lines.
- Biotechnology fermentation routes:Microbial production of fatty alcohols from sugar feedstocks is diversifying supply beyond traditional triglyceride hydrolysis, reducing dependency on tropical oil price cycles.
Market Restraints
- Feedstock concentration in Indonesia and Malaysia:Over 70 percent of global coconut and palm kernel oil processing sits within these two markets, creating geographic supply risk from weather, policy, or logistics disruption.
- REACH registration cost burden:European toxicological dossier requirements for substances above one tonne annually impose fixed compliance costs that disadvantage smaller importers.
- Petrochemical surfactant price competition:Synthetic fatty alcohols derived from ethylene oligomerization continue to undercut natural variants in mass-market detergent applications where label claims carry less weight.
Strategic Opportunities
- Indian domestic formulator expansion:BIS quality specifications for detergent-grade fatty alcohols are shaping import sourcing patterns, creating openings for suppliers with certified production and local technical service.
- Pharmaceutical ointment emollients:Cetyl and stearyl alcohols command margin premiums in topical drug delivery systems where excipient purity and documentation standards exceed cosmetic requirements.
- EPA Safer Choice biobased certification:Verified lifecycle profiles for surfactant building blocks are unlocking preferred supplier status with US institutional cleaning and household product manufacturers.
Industry Challenges
- High-pressure hydrogenation capex requirements:Continuous catalytic hydrogenation of methyl esters demands specialized reactor vessels and hydrogen supply infrastructure that strain balance sheets at sub-scale capacities.
- RSPO and ISCC certification timelines:Multi-year audit and documentation processes delay market access for new entrants seeking premium positioning against established certified producers.
- Process chemistry talent scarcity:Specialized expertise in selective hydrogenation catalyst management and fractionation distillation is concentrating at integrated Malaysian and Indonesian producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Fatty Alcohols Market |
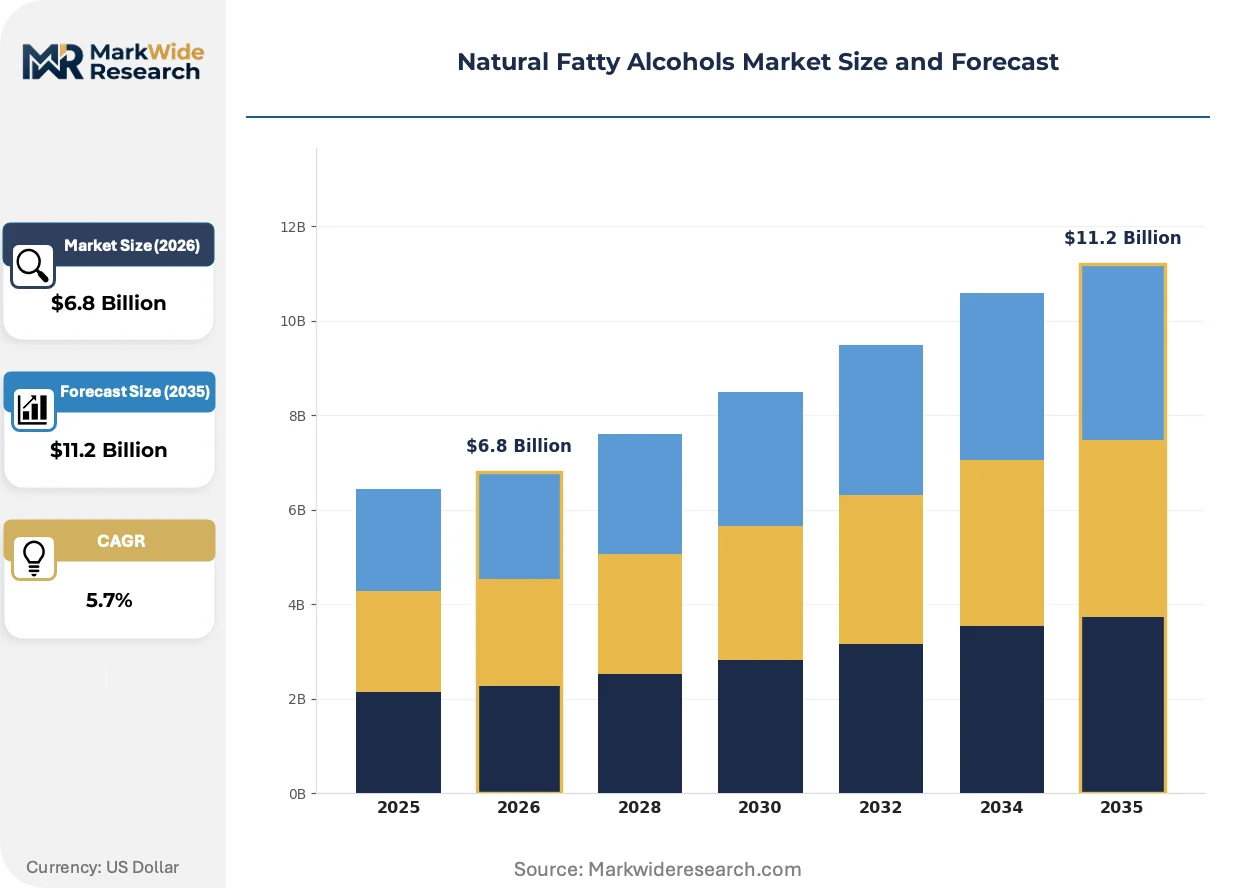
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stearyl Alcohol, Lauryl Alcohol, Myristyl Alcohol, Cetyl Alcohol Application: Cosmetics, Detergents, Personal Care, Industrial Form: Solid, Liquid, Gel, Emulsion End User: Household, Pharmaceuticals, Manufacturing, Food |
| Companies Covered | Wilmar International, KLK OLEO, Ecogreen Oleochemicals, BASF, Sasol, Musim Mas, Emery Oleochemicals, Kao Corporation, Godrej Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Fatty Alcohols Market Emerging Trajectories
Biotechnology, regulatory traceability mandates, and procurement model evolution are converging to reshape competitive positioning across the natural fatty alcohols value chain.
Microbial fermentation of fatty alcohols from lignocellulosic sugars is absorbing research investment from diversified chemical producers seeking feedstock flexibility beyond palm and coconut oils. Specialty surfactant houses in Western Europe are piloting fermentation-derived lauryl alcohol for premium personal care lines where carbon source transparency commands price premiums. This technology is absorbing capital that might otherwise expand traditional hydrogenation capacity, compressing the addressable market for new triglyceride-based projects.
REACH registration requirements now mandate comprehensive toxicological dossiers for every fatty alcohol substance imported above one tonne annually into the European Union. The industrial consequence is a consolidation of import registrations among integrated producers with dedicated regulatory affairs functions. Small and mid-scale traders are exiting the European market, redirecting volume toward less regulated Asian destinations where documentation requirements remain lighter.
Personal care brands are consolidating supplier relationships around integrated producers with captive plantation assets and certified sustainability credentials. Long-term offtake agreements with fixed volume commitments are displacing spot market purchases for premium detergent and cosmetic applications. This pattern is most visible in Southeast Asia, where Indonesian and Malaysian formulators are locking in multi-year contracts with KLK OLEO and Ecogreen Oleochemicals to secure feedstock traceability for export-bound finished goods.
Natural Fatty Alcohols Market Segmentation
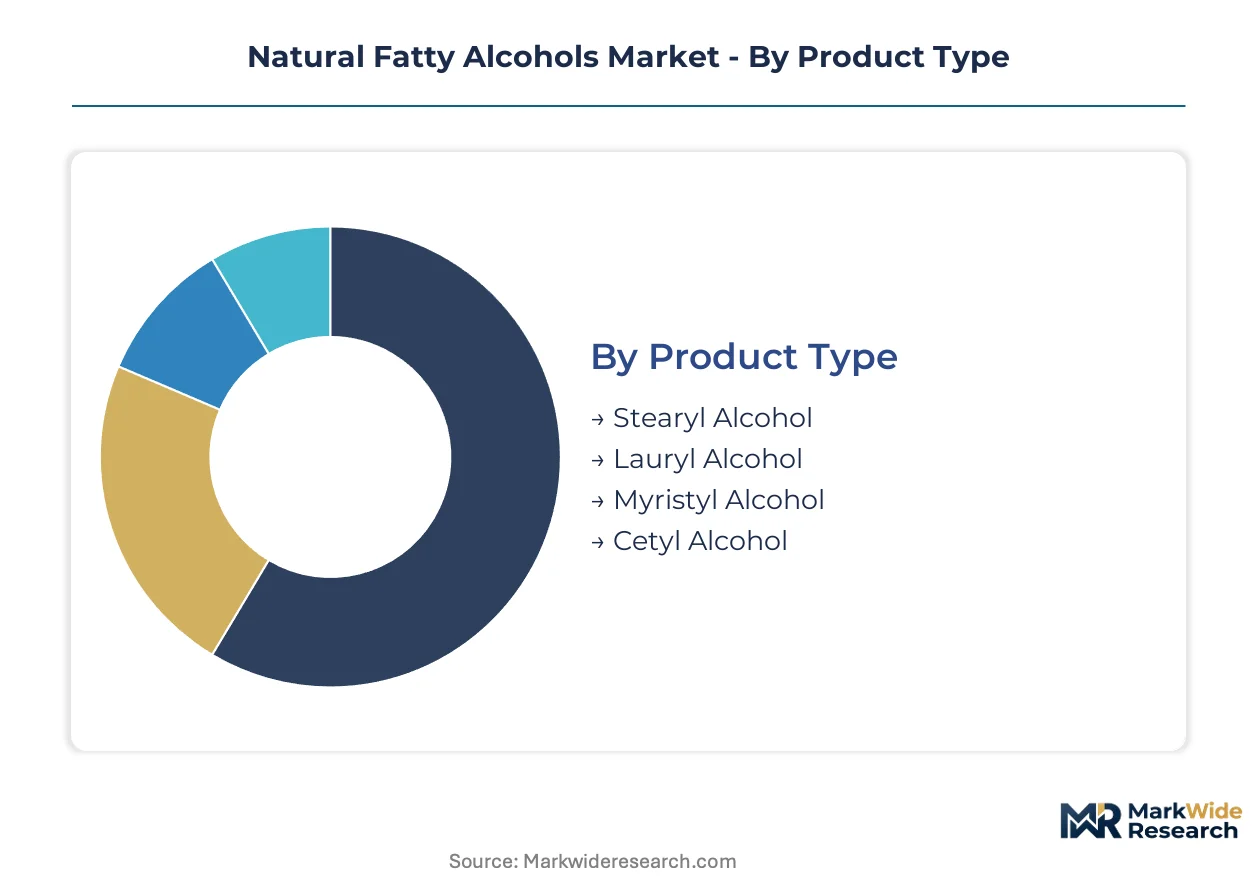
Natural fatty alcohols exhibit divergent demand patterns across product chemistry, formulation requirements, and end-use specifications. Procurement decisions hinge on chain-length purity, certification status, and functional performance in target applications.
Product Type:
Upgrade cycles in surfactant chemistry are pushing formulators toward higher-purity fractions with tighter carbon-chain distribution controls.
- Stearyl Alcohol:An eighteen-carbon saturated alcohol functioning as a primary emollient and viscosity builder in topical formulations. Pharmaceutical ointment manufacturers in Germany specify stearyl alcohol for excipient-grade applications where USP monograph compliance is mandatory.
- Lauryl Alcohol:A twelve-carbon alcohol dominating detergent intermediate production through its conversion to sodium lauryl sulfate and ether sulfates. Indonesian and Malaysian personal care formulators are expanding procurement of lauryl-derived surfactants for domestic skincare lines.
- Myristyl Alcohol:A fourteen-carbon fraction serving niche cosmetic emollient applications with lighter skin-feel characteristics.
- Cetyl Alcohol:A sixteen-carbon alcohol prized for emulsion stabilization in hair conditioning and moisturizing creams.
Volume placements concentrate in lauryl alcohol; the faster expansion belongs to stearyl alcohol.
Application:
Cost-tier stratification separates premium cosmetic grades from commodity detergent specifications.
- Cosmetics:High-purity cetyl and stearyl alcohols command certification premiums for RSPO mass-balance documentation. French and German formulators are locking in long-term supply agreements with audited Malaysian producers to secure traceability for export-bound premium skincare.
- Detergents:Lauryl alcohol serves as the dominant feedstock for anionic surfactant production in household and industrial cleaning. Indian domestic manufacturers are expanding capacity under BIS quality specifications that shape import sourcing patterns.
- Personal Care:Hair conditioning and body wash formulations drive demand for blended cetyl-stearyl alcohols with defined melting point ranges.
- Industrial:Metalworking fluids and textile processing applications consume lower-purity fractions where color and odor specifications are relaxed.
Cosmetics commands the steepest margin premiums; detergent applications absorb the largest absolute volumes.
Form:
Processing economics favor solid flaked products for long-haul shipping, while liquid and gel formats serve just-in-time formulation needs.
- Solid:Flaked or pastilled fatty alcohols dominate bulk shipments to detergent manufacturers and compounders. Solid form minimizes oxidation degradation during tropical storage and enables mechanical handling without heated tank infrastructure.
- Liquid:Molten or solvent-dissolved alcohols serve cosmetic formulators requiring rapid incorporation into emulsion systems. Liquid delivery eliminates melting energy costs for high-throughput personal care plants.
- Gel:Pre-thickened alcohol preparations target small-batch cosmetic producers lacking dedicated heating and mixing equipment.
- Emulsion:Pre-dispersed cetyl or stearyl alcohols in water-based systems accelerate processing for skincare manufacturers with limited emulsification expertise.
Solid shipments handle the greatest tonnage; emulsion formats are climbing fastest among specialty cosmetic houses.
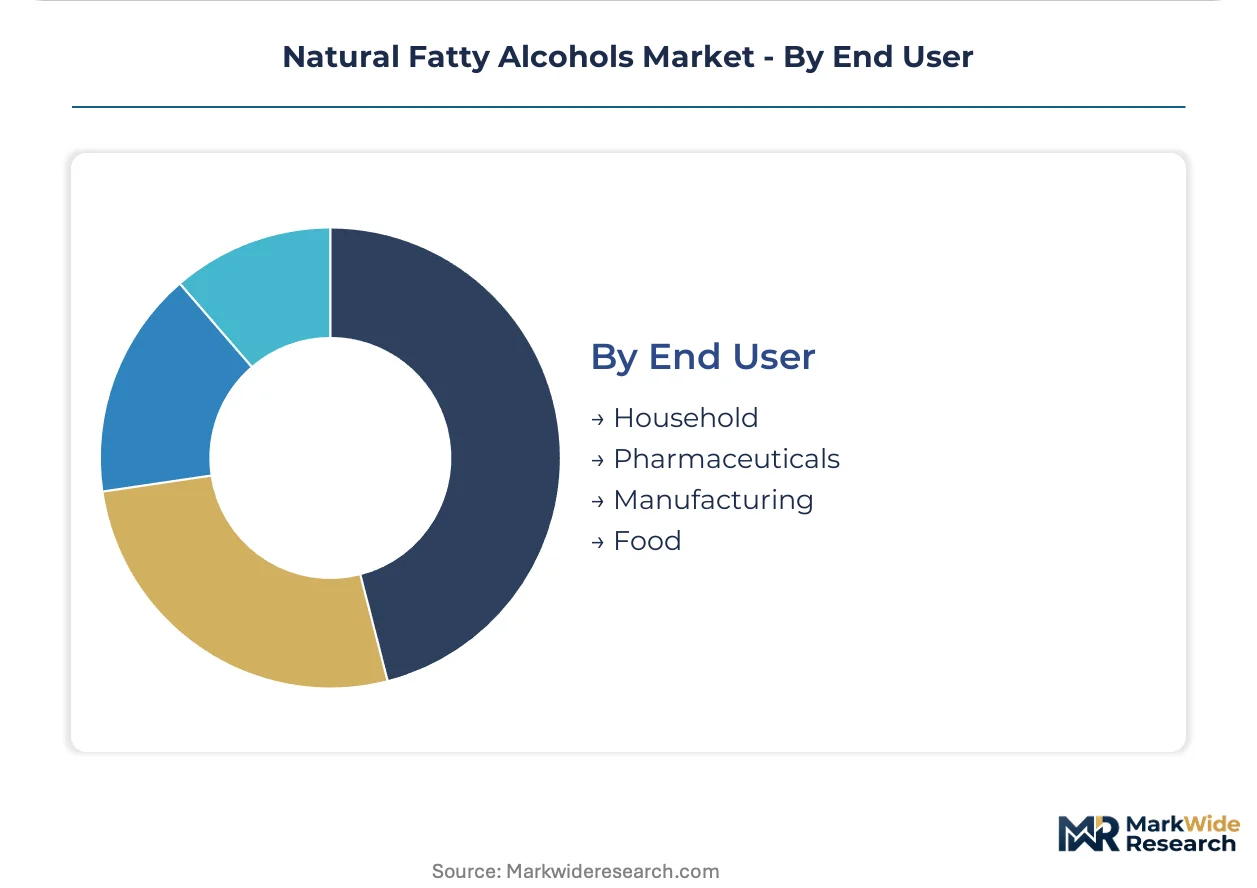
End User:
Customer-type differentiation separates specification-intensive pharmaceutical buyers from price-sensitive household product manufacturers.
- Household:Laundry and dishwashing detergent producers purchase lauryl alcohol in bulk for surfactant intermediate production. Indian and Indonesian formulators are expanding plant-derived surfactant procurement for domestic and export markets.
- Pharmaceuticals:Topical drug delivery systems demand cetyl and stearyl alcohols with comprehensive CofA documentation and excipient-grade purity. German pharmaceutical manufacturers specify DMF-supported suppliers for EU regulatory submissions.
- Manufacturing:Industrial lubricant and plasticizer producers consume broader-cut fatty alcohol fractions with relaxed cosmetic-grade specifications.
- Food:Defoaming and coating applications in food processing require food-grade certifications and kosher-halal compliance for global supply chains.
Household applications anchor volume demand; pharmaceuticals generate the highest per-kilogram value realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iskandar Malaysia and Pasir Gudang anchor Southeast Asian oleochemical processing through tax incentives for integrated plantation-to-derivatives operations. These zones concentrate hydrogenation capacity and methyl ester production facilities serving export markets.
Indonesia
Domestic personal care brands in Jakarta and Surabaya are expanding lauryl alcohol procurement for sulfate-based surfactants in shampoo and body wash formulations. The Ministry of Industry's downstream palm oil incentive program supports oleochemical cluster development in North Sumatra. Medan and Belawan host integrated fatty alcohol production serving ASEAN detergent manufacturers.
Malaysia
Klang Valley and Pasir Gudang processors command captive palm kernel oil supply chains that lower feedstock costs for C12-C14 alcohol fractions. The Malaysian Investment Development Authority grants pioneer status tax holidays for hydrogenation capacity expansions. Johor Bahru concentrates the region's largest lauryl and myristyl alcohol output for Asian surfactant houses.
Germany
Pharmaceutical excipient manufacturers in Frankfurt and Ludwigshafen specify stearyl alcohol with USP monograph compliance for topical drug delivery systems. ECHA's REACH enforcement mandates comprehensive toxicological dossiers for all fatty alcohol imports above one tonne annually. The Rhineland chemical corridor hosts formulation R&D centers that drive high-purity cetyl alcohol demand.
United States
EPA Safer Choice labeling pulls institutional cleaning product formulators toward biobased surfactant building blocks with verified lifecycle profiles. Midwest detergent manufacturers in Ohio and Illinois are locking in long-term offtake agreements for mass-balance certified alcohols. Chicago and Cincinnati serve as distribution hubs for flaked fatty alcohol shipments to domestic compounders.
India
BIS quality specifications for detergent-grade fatty alcohols are reshaping import sourcing patterns among Mumbai and Ahmedabad formulators. The Production Linked Incentive scheme for specialty chemicals supports domestic hydrogenation capacity buildouts. Gujarat's Dahej and Hazira industrial zones concentrate emerging fatty alcohol production serving South Asian surfactant markets.
Natural Fatty Alcohols Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated plantation operators commanding premium-tier positioning through mass-balance certification while toll processors serve price-sensitive detergent applications. The vendor base concentrates among Malaysian and Indonesian oleochemical houses with captive feedstock access, alongside diversified chemical multinationals with biotechnology capabilities. Three archetypes dominate: integrated plantation-to-alcohol operators, fermentation-technology developers, and regional toll hydrogenation specialists. Competitive dynamics center on backward integration into palm kernel crushing and multi-year offtake contracting with personal care brands.
Within the integrated operator tier, KLK OLEO and Ecogreen Oleochemicals exemplify producers with captive Malaysian supply chains. BASF occupies a position representing biotechnology diversification beyond traditional triglyceride routes. Wilmar International anchors the plantation-integrated archetype with Indonesian and Malaysian asset footprints. These three patterns illustrate how feedstock security, certification credentials, and technology portfolios define competitive positioning across premium and commodity alcohol segments.
| Leading Market Players |
|---|
| Wilmar International |
| KLK OLEO |
| Ecogreen Oleochemicals |
| BASF |
| Sasol |
| Musim Mas |
| Emery Oleochemicals |
| Kao Corporation |
| Godrej Industries |
| Others |
Supply Flow & Price Mechanics
Personal care formulators in Southeast Asia anchor demand concentration for natural fatty alcohols, locking in contract-based long-term offtake agreements that compress spot market liquidity and elevate premiums for uncommitted volume. This buyer archetype consolidation rewards integrated producers with captive plantation assets while squeezing toll processors dependent on volatile feedstock procurement.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations, with cosmetic houses in France and Germany paying marked-up rates for certified sustainable palm derivatives against standard delivery windows. Three-tier pricing structure across premium, standard, and economy levels separates RSPO mass-balance certified grades from conventional mass-market detergent specifications and industrial fractions with relaxed purity standards. Cost compression in commodity lauryl alcohol is intensifying because Indonesian and Malaysian producers are expanding hydrogenation capacity ahead of demand absorption. Household detergent manufacturers exhibit the highest price sensitivity, while pharmaceutical excipient buyers prioritize documentation and purity over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's Production Linked Incentive scheme for specialty chemicals are reshaping sourcing patterns, redirecting investment toward Gujarat's Dahej and Hazira industrial zones. Feedstock supply concentrates in Indonesia and Malaysia, with over seventy percent of global coconut and palm kernel oil processing anchored in these markets. Hydrogenation catalysts, methyl ester intermediates, and specialized reactor vessels constitute critical input dependencies. Single-source vulnerability from tropical weather disruption and policy shifts in Southeast Asian biofuel regulation presents structural supply risk. Distribution runs through integrated plantation-to-derivatives operators with captive logistics networks serving Asian surfactant houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural fatty alcohols sector is accelerating into a vertical-integration race, with backward control over palm kernel crushing emerging as the decisive margin lever separating premium-tier positioning from commodity toll processing.
For Market Incumbents: To counter biotechnology fermentation routes that threaten to bypass traditional triglyceride hydrolysis, KLK OLEO and Ecogreen Oleochemicals should deepen captive plantation assets through long-term land lease consolidation in Malaysian palm kernel supply zones. Certification investment in ISCC and RSPO mass-balance chain-of-custody documentation defends premium positioning against emerging fermentation-derived alternatives targeting personal care transparency claims.
For New Entrants and Emerging Players: Pharmaceutical excipient manufacturers in Germany present an underserved buyer archetype demanding USP monograph compliance and DMF-supported documentation that incumbent oleochemical houses address inconsistently. Specialty cetyl and stearyl alcohol fractions for topical drug delivery systems offer the most penetrable segment, with technical service partnerships replacing transactional supply relationships as the essential go-to-market mechanism.
For Investors and Strategic Acquirers: The window for entry favors fermentation-technology developers with demonstrated microbial production pathways from lignocellulosic sugars, positioning ahead of feedstock diversification imperatives. Acquisition targets should display proprietary strain development capabilities and pilot-scale production validation. The inflection signal to monitor is regulatory momentum behind EU Green Deal traceability requirements that could accelerate displacement of uncertified palm-derived supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Kernel Crushing | Captive feedstock supply secures cost advantages against volatile tropical oil price cycles. |
| RSPO Mass-Balance Certification Investment | Audit documentation unlocks premium pricing from EU personal care brands facing Green Deal compliance. |
| Microbial Fermentation Scale-Up | Sugar-derived lauryl alcohol diversifies supply beyond Indonesian and Malaysian concentration risk. |
| Long-Term Supply Agreement with Formulators | Fixed volume commitments reduce spot market exposure and stabilize hydrogenation capacity utilization. |
| Pharmaceutical Excipient Grade Capacity | USP monograph compliance opens margin-rich topical drug delivery applications in German manufacturing. |
Methodological Framework
Trade databases, oleochemical industry association reports, and customs shipment records formed the secondary backbone for this analysis, cross-referenced with primary interviews involving hydrogenation plant managers, procurement leads at Southeast Asian personal care formulators, distribution channel partners in Indian surfactant markets, and technical R&D directors at fermentation technology developers. Bottom-up capacity modeling and top-down demand validation triangulated volume estimates across product chemistry and application segments.
Historical trendline analysis of fatty alcohol production capacity and surfactant intermediate demand established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including carbon chain length purity, certification grade tier, end-use industry application, and regional production hub concentration. CAGRs were derived from regression analysis of feedstock cost trajectories and downstream formulation growth patterns, incorporating hydrogenation capacity expansion schedules and biotechnology pilot project timelines as industry-specific forecast inputs.
Revisions become necessary when biofuel policy intersections in Indonesia and Malaysia divert palm kernel oil volumes away from oleochemical channels, or when REACH enforcement intensification accelerates import registration consolidation beyond current trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Methidathion (CAS 950-37-8) Market
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
SLS and LABSA Market
Chemicals
Trichlorosilane Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
China Inorganic Iodide Market
Chemicals
Fluorene Market
Chemicals
Acetophenone Market
Chemicals
Cold Phosphating Chemicals Market
Chemicals
Guaiazulene Market
Chemicals
Solder Flux Market
Chemicals
Benzhydrol Market