
 Amine Oxide Market | 2026-2036
Amine Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Amine Oxide Market Intelligence
The shift toward bio-based and sulfate-free surfactant systems is fragmenting traditional supply chains for home and personal care formulations. Stepan Company specializes in surfactant chemistry for specific industrial and institutional cleaning applications. BASF SE leverages its integrated Verbund production sites and global distribution network to supply large-volume contracts. Clariant, in contrast, differentiates through its focus on specialty amine oxides for high-performance cosmetic and hair care products.
Amine oxides are non-ionic surfactants produced through the controlled oxidation of tertiary amines and hydrogen peroxide. Their unique amphiphilic molecular structure provides excellent foam boosting, viscosity building, and emulsifying properties in aqueous solutions. Laurylamine oxide and cocamidopropylamine oxide represent the largest product type segments, serving as core ingredients in personal care. While the household cleaners application remains the dominant volume driver, the agriculture chemicals segment offers higher growth potential as a wetting agent and adjuvant in pesticide formulations.
The regulatory environment is defined by frameworks like the US Environmental Protection Agency's Safer Choice program, which promotes ingredients with better environmental and human health profiles. In Europe, compliance with REACH and ECHA substance registration is mandatory for market access, influencing ingredient selection. Successfully navigating divergent regional standards for biodegradability and aquatic toxicity is becoming a central challenge for chemical producers seeking global market penetration.
Market Dynamics
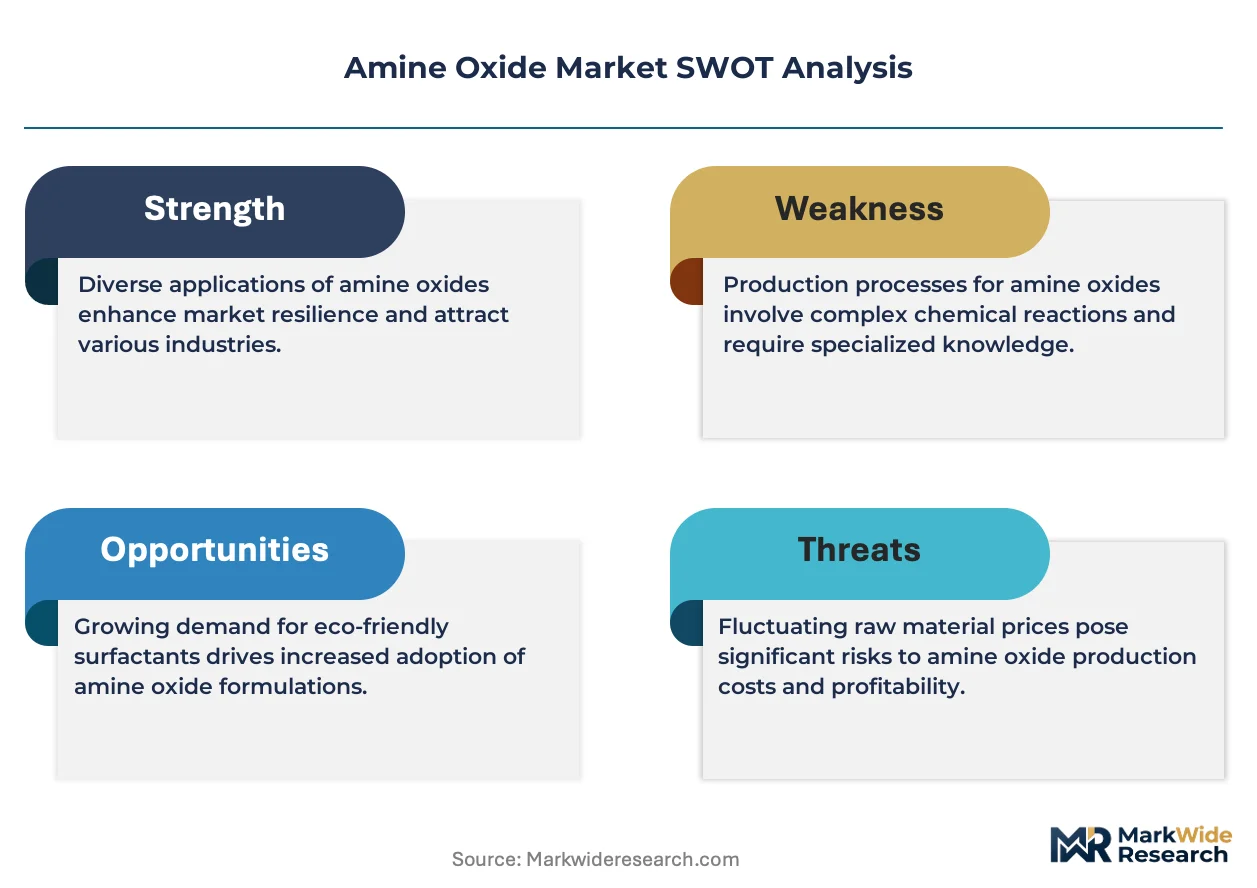
The amine oxide market is shaped by a fundamental tension between the performance demands of the home and personal care industries and the intensifying regulatory pressure for safer, more sustainable chemical ingredients. This dynamic forces producers to innovate on both formulation efficacy and environmental profile simultaneously.
Growth Catalysts
- Sulfate-Free Formulations:The consumer-driven shift toward milder, sulfate-free shampoos, body washes, and facial cleansers creates direct demand for amine oxides as primary or secondary surfactants to build viscosity and stabilize foam.
- EU REACH Regulation:The European Union's REACH framework mandates comprehensive safety and environmental data for all chemical substances, favoring well-characterized and registered ingredients like specific amine oxides over less-documented alternatives.
- Chinese Manufacturing Expansion:China's expanding domestic production of household cleaners and personal care products, coupled with rising consumer hygiene standards, concentrates a significant volume of demand for surfactant raw materials.
Market Restraints
- Feedstock Price Volatility:The market is exposed to price fluctuations in key raw materials, including tertiary amines derived from fatty acids and hydrogen peroxide, which can compress manufacturer margins.
- Performance in Bio-Based Systems:While demand for green formulations is high, achieving desired levels of foam stability, viscosity, and cleaning performance with bio-derived amine oxides can present technical challenges compared to conventional versions.
- Threat of Substitution:Amine oxides compete with other amphoteric and non-ionic surfactants, such as betaines and alkyl polyglucosides (APGs), which can offer similar functionalities in certain formulations, creating substitution risk.
Strategic Opportunities
- Agricultural Adjuvant Penetration:The agriculture chemicals segment offers a significant growth vector for amine oxides as wetting agents and adjuvants that improve the efficacy and leaf-surface adhesion of pesticide and herbicide formulations.
- Bio-Based Feedstock Development:Investing in R&D to produce amine oxides from renewable, plant-based feedstocks presents an opportunity to capture demand from brands committed to ESG goals and a circular economy.
- Water-Scarce Formulations:Developing concentrated or solid-format products, such as shampoo bars or laundry pods, that utilize the viscosity-building properties of amine oxides opens new product categories driven by sustainability.
Industry Challenges
- Navigating Divergent Regulations:Producers face significant complexity and cost in aligning product portfolios with varying regional standards for biodegradability and aquatic toxicity, such as the EPA's Safer Choice program and ECHA's substance evaluations.
- Capital-Intensive Production:The controlled oxidation process required to produce high-purity amine oxides necessitates significant capital investment in specialized reactors and safety systems to manage the reaction involving hydrogen peroxide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amine Oxide Market |
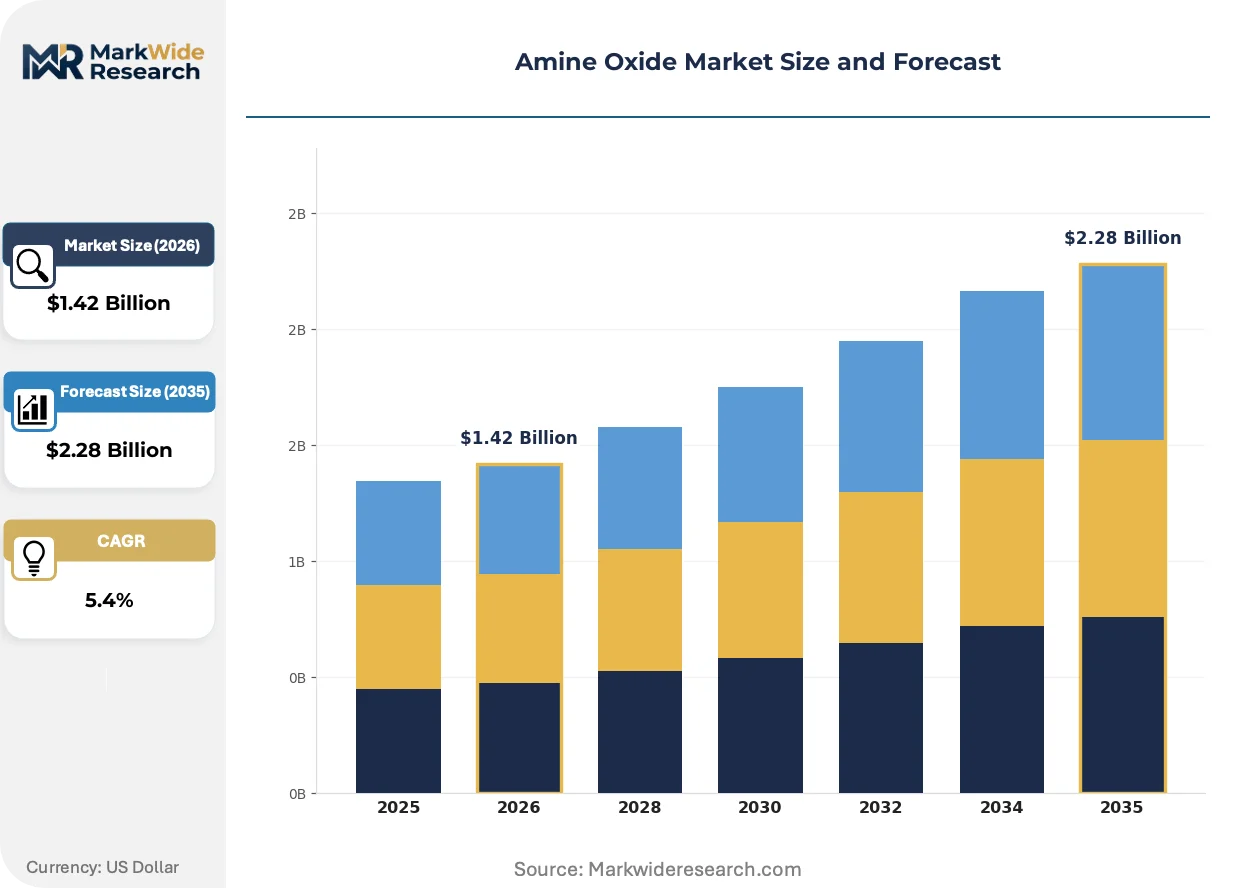
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laurylamine Oxide, Cocamidopropylamine Oxide, Decylamine Oxide, Myristamine Oxide, Others Form: Liquid, Powder, Granular, Paste Application: Personal Care, Household Cleaners, Agriculture Chemicals, Oilfield Chemicals, Leather Processing End Use Industry: Cosmetics Manufacturers, Homecare Product Makers, Agrochemical Firms, E&P Companies, Tanneries |
| Companies Covered | AkzoNobel, Lubrizol, Stepan, Pilot Chemical, Oxiteno, Clariant, Kao Chemicals, BASF SE, Evonik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amine Oxide Market Strategic Shifts & Innovations
Formulation science is advancing to reconcile the demand for high-performance surfactants with the non-negotiable requirements for sustainability and regulatory compliance. This evolution prioritizes ingredients that deliver functional benefits without compromising environmental or human safety profiles.
High-purity, low-color amine oxides represent a key product evolution. These specialized grades are being adopted by formulators in the premium cosmetics and hair care sectors to create crystal-clear gels and stable emulsions. This innovation is collapsing the perceived performance gap between synthetic and naturally-derived ingredients, enabling brands to meet consumer demand for "clean beauty" without sacrificing product aesthetics or stability.
The US Environmental Protection Agency’s Safer Choice program is a significant regulatory driver. This voluntary labeling initiative provides a clear market incentive for developing ingredients that meet stringent criteria for human health and environmental safety. The household and institutional cleaning segments are most affected, with formulators actively reformulating products to include Safer Choice-approved surfactants like laurylamine oxide to gain a competitive advantage on retail shelves.
A notable behavioral shift is the demand for radical transparency in ingredient sourcing. Brand owners in the personal care space are moving beyond basic compliance, requiring suppliers to provide comprehensive data on feedstock origin, processing methods, and carbon footprint. This disrupts traditional procurement models based on cost and specification, creating an advantage for chemical producers who can offer fully traceable, documented supply chains, a trend most visible in Europe.
Amine Oxide Market Segmentation
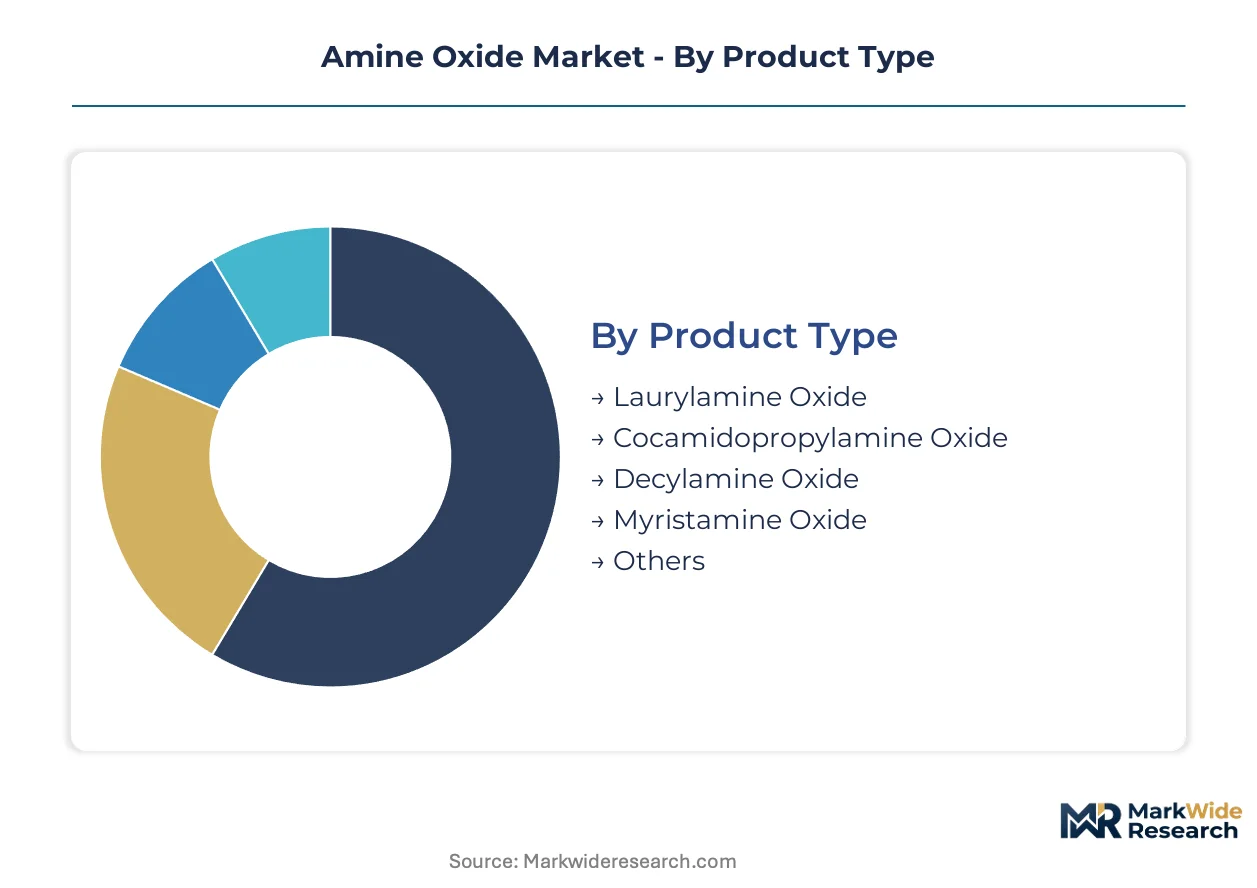
The amine oxide market's segmentation provides a granular view of product types, physical forms, key applications, and end-use industries. Understanding these distinct segments is crucial for chemical producers to align product portfolios with specific market demands. This detailed breakdown highlights areas of concentrated consumption and emerging growth opportunities.
Product Type:
The product type segment for amine oxides spans both mature and emerging chemical compositions, reflecting diverse functional requirements across consumer and industrial applications.
- Laurylamine Oxide:This long-chain alkylamine oxide functions as an excellent foam booster and viscosity builder, frequently used in personal care formulations. Demand concentrates in the household cleaners sector, driven by its mildness and effective cleaning properties in various products.
- Cocamidopropylamine Oxide:Derived from coconut oil, this amphoteric surfactant enhances foam stability and provides conditioning benefits in shampoos and body washes. Its demand is increasing in European personal care products, influenced by consumer preferences for natural-derived ingredients and mild formulations.
- Decylamine Oxide:This shorter-chain amine oxide provides effective wetting and emulsification, often used in hard surface cleaners.
- Myristamine Oxide:A medium-chain amine oxide, it contributes to foam enhancement and viscosity control in various detergent systems.
- Others:This category includes various specialty amine oxides tailored for niche industrial applications and specific performance attributes.
Laurylamine Oxide handles the majority of throughput; Cocamidopropylamine Oxide is the fastest mover on share.
Form:
The form in which amine oxides are supplied directly influences their handling, storage, and integration into diverse manufacturing processes.
- Liquid:This common form offers ease of handling and blending for large-scale industrial applications, ensuring consistent product integration. Liquid amine oxides are widely consumed by homecare product makers in China due to their formulation flexibility and cost-effectiveness.
- Powder:Powdered amine oxides facilitate concentrated formulations and reduce shipping costs, appealing to manufacturers of solid-format personal care products. Demand for powder forms is rising in Europe, driven by sustainability initiatives promoting waterless and compact products.
- Granular:Granular forms provide good flowability and reduced dusting, suitable for specific dry-mix applications.
- Paste:Paste forms offer a higher concentration than liquids, often used in specialized industrial cleaning compounds.
Liquid formulations dominate consumer product integration, while solid forms are gaining share for concentrated offerings.
Application:
Amine oxides find diverse utility across a spectrum of industrial applications, leveraging their surfactant properties in various end products.
- Personal Care:Amine oxides serve as foam boosters, viscosity modifiers, and mild cleansing agents in shampoos, body washes, and facial cleansers. The personal care sector in the US drives demand for milder, sulfate-free formulations incorporating these surfactants.
- Household Cleaners:This segment represents the largest volume consumption, utilizing amine oxides for their cleaning, foaming, and emulsifying capabilities in detergents and dishwashing liquids. Chinese manufacturers heavily integrate amine oxides into their expanding range of domestic cleaning products.
- Agriculture Chemicals:Amine oxides function as wetting agents and adjuvants, improving the spread and efficacy of pesticide and herbicide formulations on plant surfaces.
- Oilfield Chemicals:They are used in drilling fluids and enhanced oil recovery processes for their emulsifying and anti-corrosion properties.
- Leather Processing:Amine oxides act as degreasing agents and auxiliaries in the tanning process, ensuring consistent leather quality.
Household cleaners represent the largest consumption volume; agriculture chemicals are expanding most quickly.
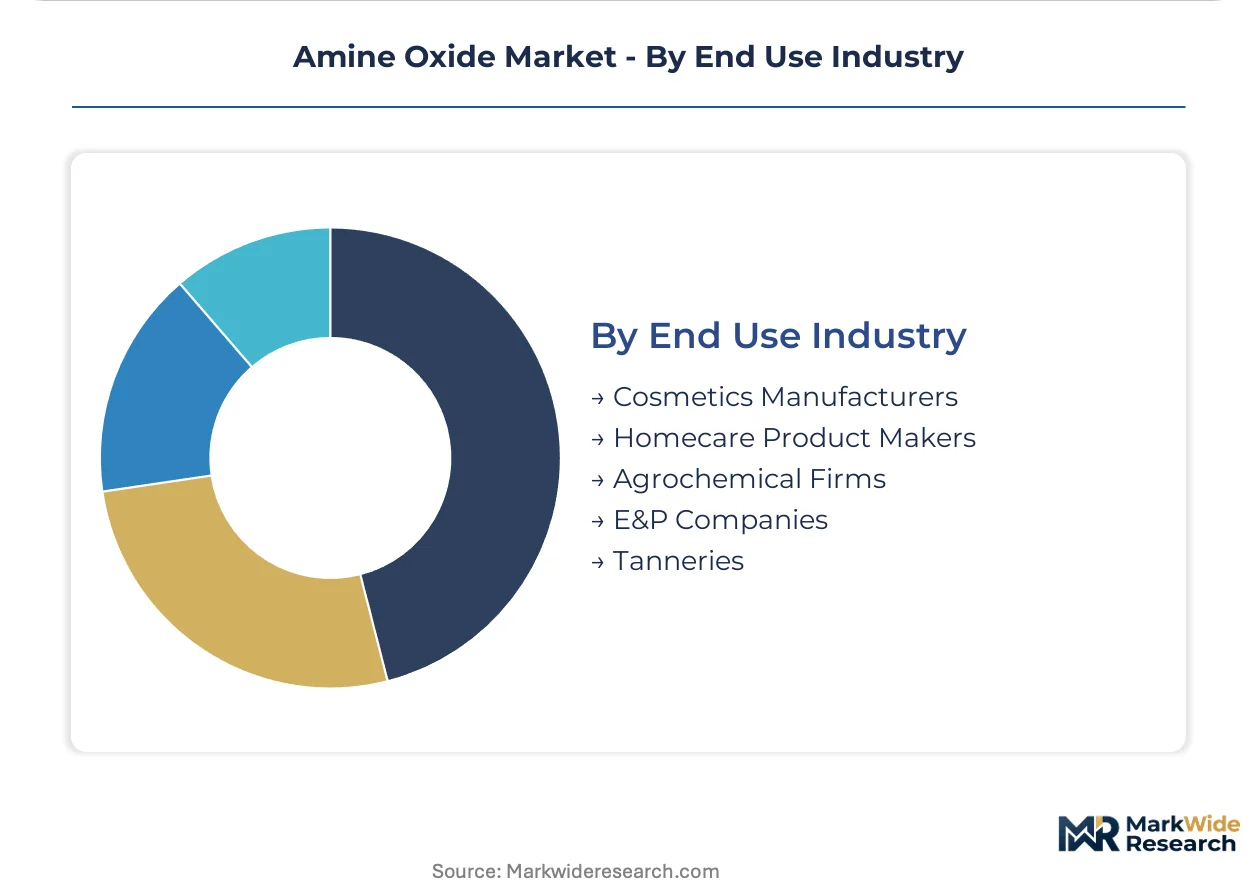
End Use Industry:
Different end-use industries procure amine oxides based on their specific manufacturing and formulation requirements, driving distinct demand patterns.
- Cosmetics Manufacturers:These firms incorporate amine oxides into premium hair care and skin care products for their foam-stabilizing and conditioning properties. European cosmetics manufacturers seek high-purity amine oxides to meet stringent clean beauty standards and consumer preferences.
- Homecare Product Makers:This segment includes producers of laundry detergents, dishwashing liquids, and surface cleaners, relying on amine oxides for cleaning performance and foam generation. North American homecare brands prioritize Safer Choice-approved amine oxides for environmental and health profiles.
- Agrochemical Firms:These companies utilize amine oxides as co-formulants to improve the dispersion and adhesion of crop protection products.
- E&P Companies:Exploration and Production companies use amine oxides in their specialized chemical blends for oil and gas extraction.
- Tanneries:Leather tanneries employ amine oxides as processing aids for degreasing and cleaning animal hides.
Homecare product makers consume the largest volumes, with agrochemical firms showing significant expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expanding manufacturing base for home and personal care products drives significant demand for amine oxides, influencing trade flows globally. This domestic production surge positions China as a major consumer and exporter of finished goods, impacting raw material procurement patterns across other key regions. The market's geographical distribution reflects consumer preferences, regulatory frameworks, and industrial development levels in various countries.
China
Domestic consumer goods manufacturing and rising hygiene standards drive demand for amine oxides in China. The Ministry of Ecology and Environment (MEE) regulations increasingly influence chemical ingredient selection, pushing for safer alternatives. Manufacturing hubs in the Yangtze River Delta region intensely consume liquid amine oxides for household cleaner formulations.
United States
The US personal care sector drives demand for milder, sulfate-free formulations incorporating amine oxides. The Environmental Protection Agency's (EPA) Safer Choice program provides market incentives for environmentally sound ingredients. Homecare product makers in the Gulf Coast chemical corridor prioritize Safer Choice-approved amine oxides for retail shelf advantage.
Germany
German cosmetics manufacturers seek high-purity amine oxides to meet stringent clean beauty standards and consumer preferences. Compliance with the European Union's REACH regulation is mandatory, influencing ingredient selection for market access. Chemical industry clusters around Ludwigshafen focus on specialized amine oxide grades for high-performance applications.
Japan
Japan's demand for amine oxides stems from its advanced personal care market, favoring mild and effective formulations. The Ministry of Economy, Trade and Industry (METI) oversees chemical substance management, impacting product development. Chemical producers in the Kansai region concentrate on developing specialty amine oxides for premium cosmetic products.
India
India's expanding domestic Fast-Moving Consumer Goods (FMCG) sector and agricultural chemicals segment contribute to amine oxide consumption. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for chemical ingredients. Industrial growth in states like Gujarat and Maharashtra fuels demand for surfactants in both household and agrochemical applications.
Amine Oxide Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure for amine oxides. Large, integrated chemical companies leverage extensive supply chains and production scale to serve diverse industries. Specialty chemical providers focus on niche applications with high-performance formulations and technical support. Dominant competitive moves include strategic partnerships to access new markets and portfolio diversification to meet evolving sustainability demands.
Specialists in high-performance surfactant chemistry include Stepan, which focuses on industrial and institutional cleaning applications. BASF SE, an integrated chemical producer, exemplifies a global distribution network for large-volume contracts across various end-use industries. Clariant differentiates through its focus on specialty amine oxides for high-performance cosmetic and hair care products. These companies collectively shape the market's innovation trajectory and supply dynamics.
| Leading Market Players |
|---|
| AkzoNobel |
| Lubrizol |
| Stepan |
| Pilot Chemical |
| Oxiteno |
| Clariant |
| Kao Chemicals |
| BASF SE |
| Evonik |
| Others |
Cost & Logistics Intelligence
Commodity volatility in tertiary amines and hydrogen peroxide dictates pricing tier spreads and shapes the supply chain for amine oxide manufacturers. This exposure to raw material fluctuations influences production locations and contract structures across the market.
Pricing Analysis
The current-generation amine oxides command price premiums over conventional surfactants due to their milder profiles and performance benefits. Pricing stratifies across premium, standard, and economy tiers, driven by purity grade and certification levels like EPA Safer Choice approval. Pricing pressure stems from competition with alternative surfactants such as betaines, particularly in cost-sensitive household cleaner formulations. The household cleaners segment is most price-sensitive, while specialty cosmetics value performance over cost.
Supply Chain Analysis
Extended payment terms are common in the amine oxide supply chain, particularly for large volume contracts with homecare product makers. Supply concentrates in China, the US, and Germany, drawing from tertiary amines and hydrogen peroxide as key raw materials. A structural risk involves logistics chokepoints due to the specialized transport requirements for hydrogen peroxide. Distribution runs through a mix of direct sales to large manufacturers and regional chemical distributors for smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The amine oxide market is at a platform-economics inflection, driven by the clean beauty ecosystem demanding ingredient interoperability with bio-based formulations. This shift requires chemical producers to align product development with evolving consumer and regulatory expectations.
For Market Incumbents:Build a regulatory compliance moat by investing in comprehensive REACH and EPA Safer Choice certifications for all product lines. This defends against emerging entrant archetypes leveraging sustainability claims. Deepen vertical integration into specialized tertiary amine production to mitigate feedstock price volatility. Expand capacity in high-purity grades to meet the growing demand from premium cosmetics.
For New Entrants and Emerging Players:Build out bio-based amine oxide portfolios to target the underpenetrated green formulations segment. Focus on cocamidopropylamine oxide derivatives for mild personal care products in Europe. The most penetrable segment is specialty agricultural adjuvants, offering higher growth potential. A go-to-market angle involves partnering directly with brands committed to ESG goals, providing full traceability data.
For Investors and Strategic Acquirers:EU REACH compliance reshapes the acquisition landscape, favoring companies with well-documented, registered chemical substances. Long-term viability over a 5-10 year window hinges on portfolios aligned with safer chemistry principles. Acquisition targets are mid-cap specialists with proprietary bio-based synthesis capabilities or strong intellectual property in high-purity grades. The signal to watch is accelerating adoption of Safer Choice-approved ingredients by major North American homecare brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity Grades | Expands supply to meet rising demand from premium cosmetics manufacturers in Europe. |
| Bio-Based Feedstock R&D Investment | Addresses brand owner demand for renewable ingredients, aligning with circular economy objectives. |
| Comprehensive Regulatory Certification | Ensures market access in Europe and enhances competitive advantage under EPA Safer Choice programs. |
| Agricultural Adjuvant Portfolio Development | Penetrates a high-growth application segment by improving pesticide efficacy for agrochemical firms. |
| Supply Chain Traceability Platforms | Meets evolving procurement requirements from personal care brands for feedstock origin transparency. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association reports, and customs data. Primary research involved interviews with chemical plant managers, procurement leads at homecare product makers, R&D directors in cosmetics, and distribution channel partners. This approach ensures bottom-up volume sizing and top-down market validation.
Forecast inputs consider historical consumption trends, raw material availability, and regulatory shifts across the analysis window. The analytical framework models amine oxide demand by product type, physical form, application, and regional regulatory compliance. Compound annual growth rates were derived from projected end-use industry expansion and specific ingredient adoption rates. Key inputs include consumer hygiene spending and agricultural chemical formulation changes.
Stress conditions across feedstock price volatility and new regulatory mandates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions and industry-specific risk factors. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Benzhydrol Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Mercury (I) Sulphate Market
Chemicals
Pentanedione Market
Chemicals
Catechol Market
Chemicals
South America Surface Treatment Chemicals Market
Chemicals
Potassium Permanganate Market
Chemicals
China Inorganic Iodide Market
Chemicals
Cyclopentylamine Market
Chemicals
Iso Nonanol Market
Chemicals
Global Syringaldehyde Market
Chemicals
Azodicarbonamide (ADC) Market
Chemicals
RDX and HMX Market
Chemicals
Chemical Distribution Market
Chemicals
Global Aldehyde Market
Chemicals
Global Anhydrous Aluminum Chloride Market