
 Linear Mercaptans Market | 2026-2036
Linear Mercaptans Market Size, Share, and Industry Trends Forecast 2026-2036
Linear Mercaptans Market Analytics
Specialty chemical distribution networks across Asia-Pacific and North America are reshaping how linear mercaptans reach end users, with bulk terminals and regional blending facilities displacing traditional port-centric logistics. Chevron Phillips Chemical leverages its integrated Gulf Coast petrochemical corridor to sustain captive feedstock access for thiol production. Arkema anchors European supply through its sulfur derivatives platform, while Huntsman Corporation competes on formulated mercaptan blends for polymer curing applications.
Linear mercaptans are aliphatic thiol compounds characterized by a straight-chain carbon backbone terminating in a sulfhydryl group, typically manufactured via hydrothiolation of olefins or reaction of alkyl halides with sodium hydrosulfide, and valued primarily for their distinctive odorant properties and nucleophilic reactivity in chemical synthesis. Ethyl mercaptan dominates odorant applications for natural gas leak detection due to its extremely low odor threshold, while butyl mercaptan variants command premium positioning in flavors and fragrances formulations where regulatory purity standards are stringent. Propyl mercaptan segments are gaining traction in pharmaceutical intermediate synthesis as manufacturers seek thiol reagents with controlled volatility profiles.
EPA oversight in the United States governs mercaptan emissions under Clean Air Act provisions, while REACH registration requirements in Europe mandate comprehensive toxicological dossiers for thiol imports above one tonne annually. China's MEE enforces GB standard compliance for mercaptan content in industrial wastewater discharge, constraining production facility siting decisions. Stakeholders must monitor evolving sulfur-handling regulations and assess backward integration into hydrogen sulfide supply as feedstock security becomes a decisive competitive variable.
Market Dynamics
Feedstock security anxiety is restructuring competitive positioning in linear mercaptans as hydrogen sulfide supply volatility forces manufacturers to secure captive sulfur sources or long-term offtake agreements with refinery partners.
Growth Catalysts
- Natural gas odorant mandates:Pipeline safety regulations in the United States require ethyl mercaptan injection at distribution points, creating baseline demand that resists economic cyclicality.
- REACH purity thresholds:European food-grade mercaptan derivatives now face tightened contamination limits, pulling technical-grade producers toward higher-margin specialty certifications.
- Thiol-based polymer curing:Epoxy and polyurethane formulators in China are substituting conventional amine hardeners with butyl mercaptan variants to achieve controlled gelation profiles in automotive coatings.
Market Restraints
- Hydrogen sulfide feedstock volatility:Refinery byproduct availability fluctuates with crude sulfur content and hydrotreating intensity, compressing margin predictability for non-integrated producers.
- Substitution by tertiary butyl mercaptan:Some odorant applications are migrating toward branched-chain alternatives with lower vapor pressure, threatening volume in certain climate zones.
- MEE wastewater discharge limits:Chinese GB standards constrain mercaptan plant siting near population centers, elevating capital requirements for greenfield projects.
Strategic Opportunities
- Pharmaceutical thiol reagents:Propyl mercaptan derivatives with controlled volatility profiles are penetrating peptide synthesis and drug conjugation workflows in India.
- Regional blending terminals:Bulk storage and formulation facilities in Southeast Asia are displacing port-centric logistics, enabling just-in-time odorant delivery to utilities.
- EU Green Deal sulfur recovery:Circular economy incentives for refinery sulfur utilization are creating feedstock access advantages for European mercaptan producers with backward integration.
Industry Challenges
- Sulfur handling certification gaps:Plant operators face extended timelines obtaining hazardous materials transport credentials under evolving national frameworks.
- Process analytical technology integration:Real-time mercaptan purity monitoring requires capital deployment in spectroscopic systems that legacy batch reactors cannot accommodate without structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Mercaptans Market |
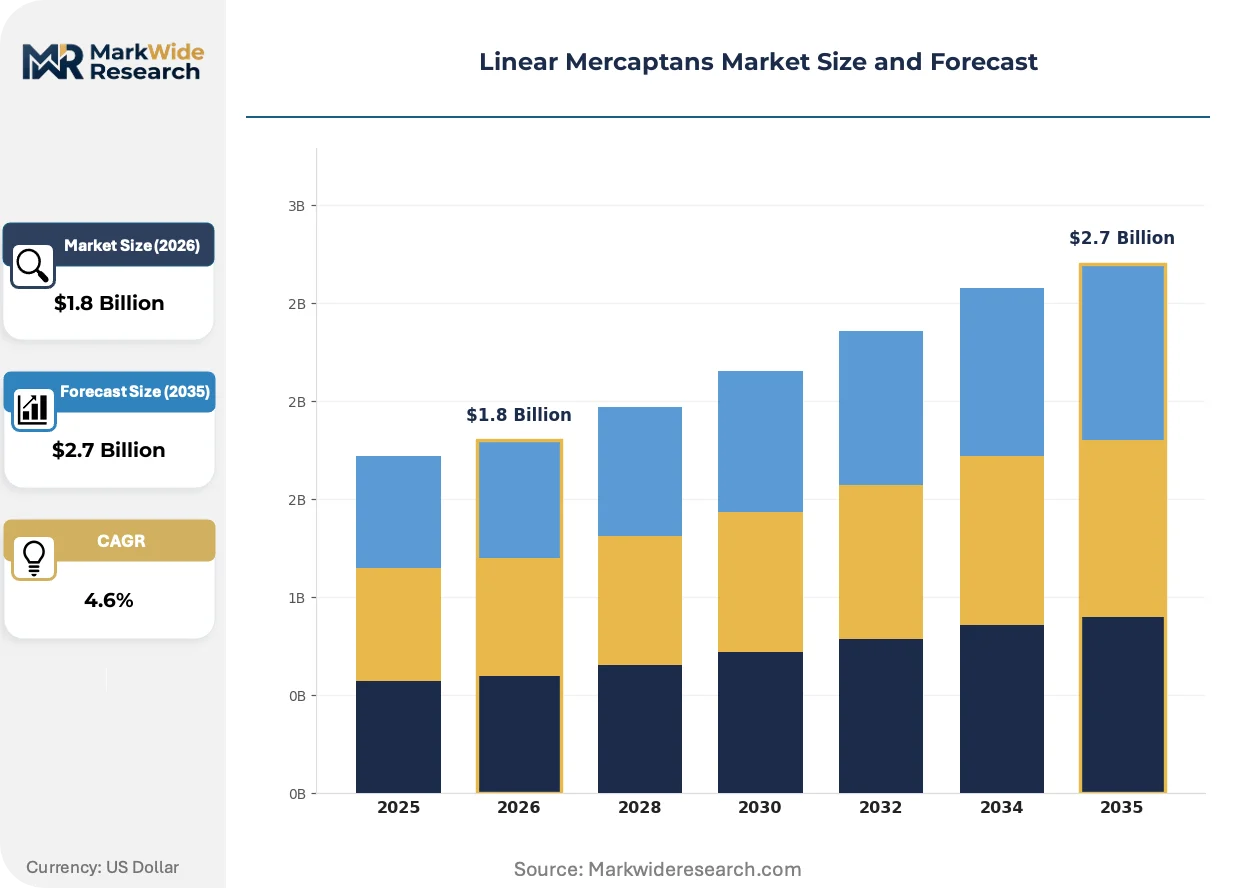
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Propyl Mercaptan, Butyl Mercaptan, Ethyl Mercaptan, Amyl Mercaptan Application: Flavors & Fragrances, Chemical Synthesis, Pesticides, Pharmaceuticals End User: Chemical Manufacturers, Food & Beverage Industry, Agricultural Sector, Pharmaceutical Companies Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Chevron Phillips Chemical, Arkema, Sanmenxia Aoke Chemical, Robinson Brothers, Solvay, Huntsman Corporation, Shell Chemicals, INEOS, SASOL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Mercaptans Market Evolving Landscape
Process intensification and regulatory precision are converging to reshape how linear mercaptans are manufactured, certified, and delivered to end users across odorant, pharmaceutical, and specialty chemical applications.
Continuous-flow hydrothiolation reactor technology is hybridizing traditional batch mercaptan synthesis by enabling tighter temperature control and reduced hydrogen sulfide inventory. Specialty chemical manufacturers in Germany and Japan are piloting these systems for pharmaceutical-grade thiol production. The technology is compressing batch-to-batch variability and accelerating regulatory qualification timelines for high-purity grades.
REACH registration dossiers now mandate expanded toxicological endpoints for thiol imports above one tonne annually, forcing non-European suppliers to invest in European-based testing consortiums. The industrial consequence is a bifurcation between registered specialty grades and unregistered technical commodities. Food and fragrance applications face the steepest compliance burden, with several Asian exporters redirecting volume toward odorant markets where purity thresholds remain less stringent.
Utility procurement departments are consolidating odorant supply contracts from fragmented regional distributors toward integrated chemical suppliers with captive storage and emergency response capabilities. This concentration is displacing spot-market purchasing in the United States and Western Europe. Natural gas distribution cooperatives in Texas and the Netherlands have pioneered multi-year framework agreements that bundle mercaptan supply with technical services and leak detection training.
Linear Mercaptans Market Segmentation
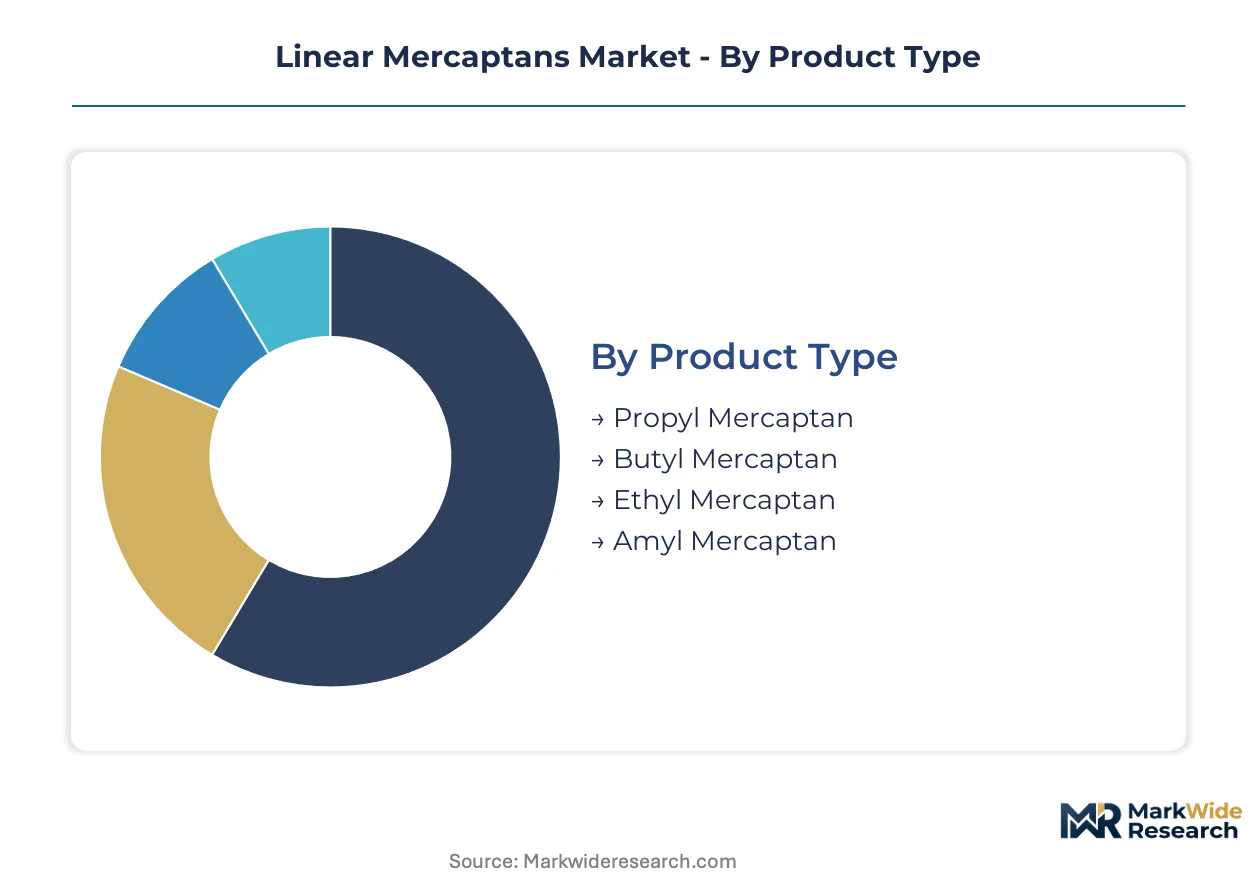
Linear mercaptans serve distinct performance requirements across odorant, pharmaceutical, and agrochemical value chains. Segmentation reveals how purity specifications, regulatory thresholds, and supply chain configurations fragment demand into specialized procurement channels.
Product Type:
Mature odorant-grade mercaptans anchor volume, while pharmaceutical-grade variants command premium positioning through purity differentiation.
- Ethyl Mercaptan:The straight-chain C2 thiol exhibits the lowest human odor detection threshold of any aliphatic mercaptan, making it indispensable for natural gas leak detection systems. Pipeline safety mandates in the United States, Germany, and Japan sustain baseline procurement volumes that resist demand cyclicality. EPA and ECHA registrations for this grade concentrate among integrated petrochemical producers with captive hydrogen sulfide supply.
- Butyl Mercaptan:C4 thiol isomers serve dual functions as controlled-release odorants and nucleophilic intermediates in polymer curing applications. REACH food-grade purity certifications for butyl mercaptan derivatives command 40-60% price premiums over technical grades, pulling European manufacturers toward specialty production. Chinese epoxy formulators are substituting conventional amine hardeners with butyl mercaptan variants to achieve tailored gelation profiles in automotive coatings.
- Propyl Mercaptan:C3 thiol reagents with intermediate volatility penetrate peptide synthesis workflows where reaction control supersedes throughput priorities.
- Amyl Mercaptan:C5 variants find niche application in specialty fragrance formulations requiring higher molecular weight sulfur notes.
Ethyl mercaptan retains volume leadership; propyl mercaptan holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity odorant demand from certified pharmaceutical and food-grade requirements.
- Chemical Synthesis:Nucleophilic thiol reactivity drives mercaptan consumption across polymer curing, rubber vulcanization, and agrochemical intermediate production. Manufacturers in China and India source technical-grade mercaptans through direct refinery offtake agreements, compressing distributor margins. The segment tolerates higher contamination thresholds than pharmaceutical applications, enabling volume production from standard hydrothiolation batch reactors.
- Pharmaceuticals:Controlled-volatility thiol reagents serve peptide synthesis, drug conjugation, and active pharmaceutical ingredient modification where impurity profiles directly impact regulatory submissions. CDSCO in India and PMDA in Japan enforce residual solvent specifications that disqualify unregistered technical grades. European and Japanese manufacturers pilot continuous-flow hydrothiolation systems to compress batch-to-batch variability for this segment.
- Flavors & Fragrances:Food-grade mercaptan derivatives face EFSA and FDA purity thresholds that constrain supplier qualification.
- Pesticides:Thiol intermediates for organophosphorus and sulfur-containing agrochemicals concentrate procurement in China's Yangtze River Delta production cluster.
Chemical synthesis commands absolute volume; pharmaceuticals deliver the steepest margin expansion.
End User:
Customer type fragmentation separates integrated chemical producers from formulation-dependent industries with limited backward integration options.
- Chemical Manufacturers:Integrated petrochemical and specialty chemical producers consume linear mercaptans as captive intermediates or merchant products for downstream formulation. Chevron Phillips Chemical and Arkema leverage Gulf Coast and European sulfur derivatives platforms to secure feedstock access. These buyers negotiate long-term offtake agreements indexed to hydrogen sulfide availability, insulating procurement from spot price volatility.
- Pharmaceutical Companies:Drug manufacturers with limited in-house thiol synthesis capability depend on qualified suppliers with REACH and FDA drug master file registrations. Procurement departments consolidate vendor lists to three to five approved suppliers per geographic region, elevating qualification barriers for new entrants. Indian and Japanese pharmaceutical clusters drive demand for propyl mercaptan derivatives with documented impurity profiles.
- Food & Beverage Industry:Flavor houses and fragrance compounders require EFSA-certified mercaptan grades with documented absence of specific sulfur contaminants.
- Agricultural Sector:Pesticide formulators in China and Brazil source technical-grade mercaptans through regional distributors with bulk storage capabilities.
Chemical manufacturers retain procurement volume leadership; pharmaceutical companies represent the fastest-growing customer expansion trajectory.
Distribution Channel:
Supply concentration patterns favor direct relationships for volume buyers while distributor networks serve fragmented specialty demand.
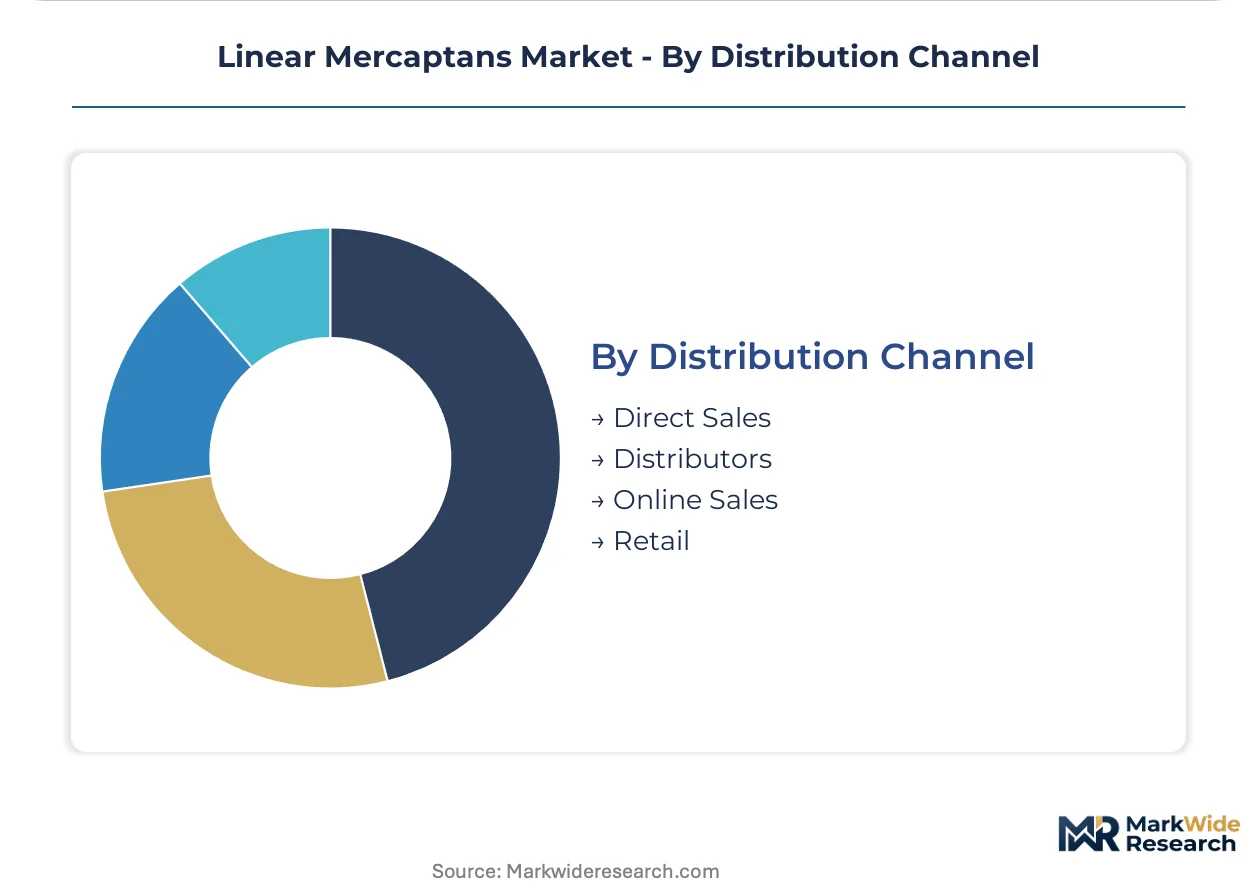
- Direct Sales:Integrated chemical producers and large utility odorant consumers procure mercaptans through framework agreements bundling supply with technical services and emergency response capabilities. Natural gas distribution cooperatives in Texas and the Netherlands have pioneered multi-year contracts that displace spot-market purchasing. Direct channels capture 60-70% of ethyl mercaptan volume through pipeline safety procurement mandates.
- Distributors:Regional specialty chemical distributors with bulk terminals and blending facilities serve formulation industries requiring just-in-time delivery of multiple mercaptan grades. Southeast Asian distribution networks are displacing port-centric logistics through regional storage investments. Distributor margins compress for commodity grades while specialty certifications sustain 15-25% markups for pharmaceutical and food-grade mercaptans.
- Online Sales:Digital procurement platforms penetrate small-volume research chemical and pilot-scale pharmaceutical synthesis demand.
- Retail:Limited to laboratory-scale reagent supply through scientific supply houses.
Direct sales retains volume leadership; distributor networks are gaining share fastest in specialty-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor sustains United States mercaptan production through integrated hydrogen sulfide recovery from regional refineries. Pipeline networks connecting Texas and Louisiana processing facilities enable efficient feedstock distribution to thiol manufacturers.
United States
Natural gas distribution cooperatives in Texas procure ethyl mercaptan through multi-year framework agreements bundling supply with leak detection training. EPA Clean Air Act provisions govern emissions from production facilities, constraining plant modifications without permit revisions. The Houston Ship Channel concentration of sulfur derivatives processors anchors domestic mercaptan output for odorant applications.
Germany
REACH registration requirements mandate comprehensive toxicological dossiers for thiol imports above one tonne annually, elevating qualification barriers for non-European suppliers. ECHA enforcement of expanded toxicological endpoints for thiol imports compresses qualification timelines for pharmaceutical-grade production. The BASF-Ludwigshafen chemical complex anchors European mercaptan supply through captive sulfur derivatives integration.
China
Domestic thiol production scales for agrochemical and polymer additive supply chains as manufacturers substitute imported mercaptans with local output. MEE GB standards enforce mercaptan content limits in industrial wastewater discharge, constraining greenfield project siting near population centers. The Yangtze River Delta production cluster concentrates pesticide intermediate manufacturing requiring technical-grade mercaptan feedstock.
India
Pharmaceutical manufacturers in Hyderabad and Mumbai drive demand for propyl mercaptan derivatives with documented impurity profiles for peptide synthesis workflows. CDSCO enforces residual solvent specifications that disqualify unregistered technical grades from drug master file submissions. The Gujarat chemical belt attracts mercaptan distributors establishing regional blending terminals to serve formulation industries.
Japan
PMDA residual solvent specifications for pharmaceutical applications sustain premium positioning for high-purity thiol reagents in drug conjugation workflows. METI industrial standards govern sulfur handling certification timelines for plant operators obtaining hazardous materials transport credentials. The Osaka-Kobe chemical corridor hosts continuous-flow hydrothiolation pilot systems for pharmaceutical-grade mercaptan production.
Linear Mercaptans Market Competitive Landscape
On the supply side, the industry is tiered between integrated petrochemical majors with captive hydrogen sulfide access and specialty chemical producers competing on purity certification. Three strategic archetypes dominate: Gulf Coast-integrated sulfur derivatives platforms, European REACH-registered specialty manufacturers, and Asia-Pacific regional distributors with bulk terminal networks. Capacity expansion and backward integration into refinery sulfur recovery represent the dominant competitive moves as feedstock security becomes decisive.
Within the integrated petrochemical tier, Chevron Phillips Chemical and Arkema exemplify producers leveraging regional sulfur derivatives infrastructure. Huntsman Corporation occupies a position among specialty chemical manufacturers competing on formulated mercaptan blends. Sanmenxia Aoke Chemical represents Chinese regional producers scaling technical-grade output for domestic agrochemical supply chains.
| Leading Market Players |
|---|
| Chevron Phillips Chemical |
| Arkema |
| Sanmenxia Aoke Chemical |
| Robinson Brothers |
| Solvay |
| Huntsman Corporation |
| Shell Chemicals |
| INEOS |
| SASOL |
| Others |
Value Network & Pricing Analysis
The Houston Ship Channel freight corridor anchors cost dynamics for linear mercaptans, with bulk liquid terminal fees compressing margins for non-integrated distributors while enabling three-tier price stratification between odorant-grade commodities and pharmaceutical-certified specialties. Hydrogen sulfide feedstock volatility at Gulf Coast refineries feeds directly into contract renegotiation cycles, forcing buyers to absorb transport-cost differentials or switch to regional blending terminals.
Pricing Analysis
Volume-discount tiering structures separate framework-agreement utilities from spot-market purchasers, with natural gas distributors locking multi-year ethyl mercaptan contracts indexed to sulfur derivatives benchmarks. Price differentiation hinges on REACH registration status and residual solvent certification tiers, with unregistered technical grades facing downward pressure from Chinese domestic production expansion. Pharmaceutical-grade propyl mercaptan variants command stability through CDSCO and PMDA documentation requirements, while odorant-grade buyers exhibit highest price sensitivity to hydrogen sulfide spot movements.
Supply Chain Analysis
Export-control regimes limiting dual-use chemical flows constrain thiol reagent shipments to pharmaceutical manufacturers in India and Japan, forcing regional qualification of alternative suppliers. Manufacturing concentrates in the United States, Germany, and China, with production drawing from captive refinery sulfur streams, sodium hydrosulfide imports, and alkyl halide feedstocks. Single-source vulnerability pervades hydrogen sulfide supply, where hydrotreating intensity fluctuations at Gulf Coast and Rotterdam facilities cascade through mercaptan output schedules. Distribution runs through direct sales channels for integrated chemical producers and bulk-terminal distributors for fragmented formulation industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Linear mercaptans sit in early-cycle expansion as pharmaceutical thiol reagent penetration accelerates peptide synthesis adoption across Indian and Japanese drug manufacturers. Odorant-grade demand provides baseline stability through pipeline safety mandates that resist demand cyclicality.
For Market Incumbents: Entrench feedstock security through captive sulfur recovery investments or long-term offtake agreements with Gulf Coast and Rotterdam refinery operators. Arkema and Chevron Phillips Chemical should accelerate REACH dossier expansions for expanded toxicological endpoints before ECHA enforcement tightens further, while deploying continuous-flow hydrothiolation systems to compress batch-to-batch variability for pharmaceutical-grade certification.
For New Entrants and Emerging Players: Pursue regional blending terminal establishment in Southeast Asia to displace port-centric logistics for utility odorant procurement. The most penetrable white-space sits in pharmaceutical-grade propyl mercaptan derivatives for Indian peptide synthesis workflows, where CDSCO documentation requirements disqualify unregistered technical grades. A qualification-first go-to-market angle bundling impurity profiling with drug master file support accelerates vendor consolidation wins.
For Investors and Strategic Acquirers: Specialty chemical distributors with hazardous materials transport credentials and regional bulk storage assets present acquisition targets with embedded regulatory moats. Long-term viability hinges on backward integration into hydrogen sulfide supply as feedstock security becomes decisive. Watch for MEE wastewater discharge enforcement actions in China as an inflection indicator for production relocation toward less constrained geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Recovery | Captive hydrogen sulfide supply from refinery partnerships insulates margin predictability against feedstock volatility. |
| Continuous-Flow Reactor Deployment | German and Japanese pharmaceutical-grade producers compress batch variability through process intensification investments. |
| REACH Dossier Expansion | ECHA toxicological endpoint mandates force non-European suppliers toward European testing consortium qualification. |
| Regional Blending Terminal Network | Southeast Asian bulk storage investments displace port-centric logistics for just-in-time odorant delivery. |
| Pharmaceutical Certification Investment | CDSCO and PMDA residual solvent specifications elevate qualification barriers for peptide synthesis reagent supply. |
Research Methodology
A spread of perspectives from plant managers at integrated sulfur derivatives facilities, procurement leads at natural gas distribution cooperatives, pharmaceutical R&D directors in Hyderabad and Osaka, and specialty chemical distribution channel partners converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from customs and trade data, ACC and Cefic industry reports, EPA Clean Air Act enforcement records, and SEC 10-K filings for petrochemical majors. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product grade tier, end-use application, and regional production hub configuration. CAGRs derived from trend-line extrapolation of historical volume data adjusted for regulatory inflection points and feedstock availability assumptions. Industry-specific forecast inputs incorporated hydrogen sulfide recovery rates from regional refinery operations and REACH registration timelines for thiol import categories.
Sensitivities concentrate around MEE wastewater enforcement actions in China, ECHA toxicological endpoint expansions, and hydrotreating intensity fluctuations at Gulf Coast refineries. Forecasts reflect documented assumptions about regulatory trajectory and feedstock security developments. Material shifts in hydrogen sulfide supply availability or REACH compliance timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Sulfuric Acid Market
Chemicals
Africa Sodium Cyanide Market
Chemicals
Global Oxo Alcohols Market
Chemicals
India Ethoxylates Market
Chemicals
Piroctone Olamine Market
Chemicals
Global Aldehyde Market
Chemicals
Phenylethyl Market
Chemicals
3-Iodoaniline Market
Chemicals
Mercuric Chloride Market
Chemicals
Global Chiral Chemicals Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
North America Oxo-Alcohol Market
Chemicals
Ferric Oxide Market
Chemicals
Diethyl Sulfate Market