
 Aloe Vera Derivatives Market | 2026-2036
Aloe Vera Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Aloe Vera Derivatives Market Analysis
Aftermarket formulation services is tilting margin pools away from raw commodity trading toward value-added blending and private-label contract manufacturing. Forever Living Products leverages its captive plantation network in Texas and the Dominican Republic to control gel supply from leaf to finished extract. Lily of the Desert anchors its position through certified organic processing and vertical integration into juice concentrate production. Terry Laboratories competes on pharmaceutical-grade aloe vera extract supply to topical drug developers seeking FDA-compliant raw material documentation.
Aloe vera derivatives comprise the processed outputs of Aloe barbadensis miller leaf tissue, including stabilized inner leaf gel containing acemannan polysaccharides at minimum concentrations, decolorized whole leaf extract, and spray-dried powder with defined mesh particle sizes for industrial formulation. These materials serve as functional actives, emollients, and stabilizing agents across personal care, oral care, beverage fortification, and over-the-counter topical therapeutic products. Aloe vera gel dominates volume throughput due to its direct incorporation into rinse-off and leave-on cosmetic bases, while aloe vera powder commands premium positioning in dry-format nutraceutical capsules and powdered drink mixes where water activity constraints limit liquid alternatives. Pharmaceutical-grade aloe vera extract carries the tightest specification thresholds and longest qualification cycles, creating a defensible margin tier for processors with drug master file experience.
The FDA Center for Food Safety and Applied Nutrition monitors aloe vera ingredient status in dietary supplements under New Dietary Ingredient notification requirements, while the EU Cosmetics Regulation mandates safety assessment dossiers for botanical extracts in leave-on products. India's Ministry of Ayush and the Food Safety and Standards Authority of India regulate aloe vera in traditional medicine and functional food categories, creating parallel compliance pathways for exporters. Stakeholders must monitor evolving limits on anthraquinone content and polysaccharide standardization methods as these parameters increasingly determine market access eligibility across destination countries.
Market Dynamics
Clean-label formulation mandates from personal care brands are compressing specification tolerances for aloe vera derivatives, forcing processors to invest in captive cultivation and certified organic supply chains to maintain procurement relationships with multinational cosmetics houses.
Growth Catalysts
- EU Cosmetics Regulation purity benchmarks:Tightening anthraquinone limits and polysaccharide standardization requirements are disqualifying commodity traders, creating volume concentration for qualified processors with drug master file documentation.
- K-beauty and Ayurvedic brand sourcing:South Korean and Indian personal care manufacturers are mandating certified organic aloe vera gel for serum and essence formulations, pulling supply toward vertically integrated plantation operators.
- Spray-drying technology advances:Improved low-temperature dehydration methods are preserving acemannan bioactivity in powder formats, opening formulation flexibility for dry nutraceutical capsules and functional beverage premixes.
Market Restraints
- Input cost volatility:Irrigation water scarcity in Texas and Dominican Republic plantation zones is squeezing leaf yield consistency, forcing processors to hedge through multi-year cultivation contracts.
- Supply concentration risk:Pharmaceutical-grade extract capacity clusters with processors holding FDA drug master files, creating qualification bottlenecks for topical drug developers seeking compliant raw material documentation.
- Substitution threat:Centella asiatica and snail mucin extracts are displacing aloe vera in certain K-beauty formulations where brands prioritize novel active positioning over established botanical credentials.
Strategic Opportunities
- Underpenetrated oral care applications:Toothpaste and mouthwash manufacturers in Germany and France remain lightly served by aloe vera derivatives, presenting white space for decolorized whole leaf extract suppliers with taste-masking capabilities.
- Regulatory tailwind from India's PLI scheme:Production-linked incentives for herbal extract processing are attracting investment into Madhya Pradesh and Rajasthan cultivation clusters, lowering cost structures for export-oriented processors.
- Technology convergence:Encapsulation technologies combining aloe vera polysaccharides with hyaluronic acid are enabling extended-release skincare formats that command premium positioning in professional salon channels.
Industry Challenges
- Analytical chemist scarcity:Qualified personnel for acemannan quantification and anthraquinone profiling are concentrated among legacy processors, slowing new entrant qualification timelines for pharmaceutical-grade supply.
- Certification timeline compression:USDA Organic and COSMOS certification cycles are extending due to auditor backlog, delaying contract manufacturing launches for brands with fixed product launch windows.
- Legacy ERP integration friction:Plantation management systems for leaf-to-lot traceability are proving incompatible with multinational cosmetics houses' supplier portals, requiring middleware investment for real-time inventory visibility.
Report Scope
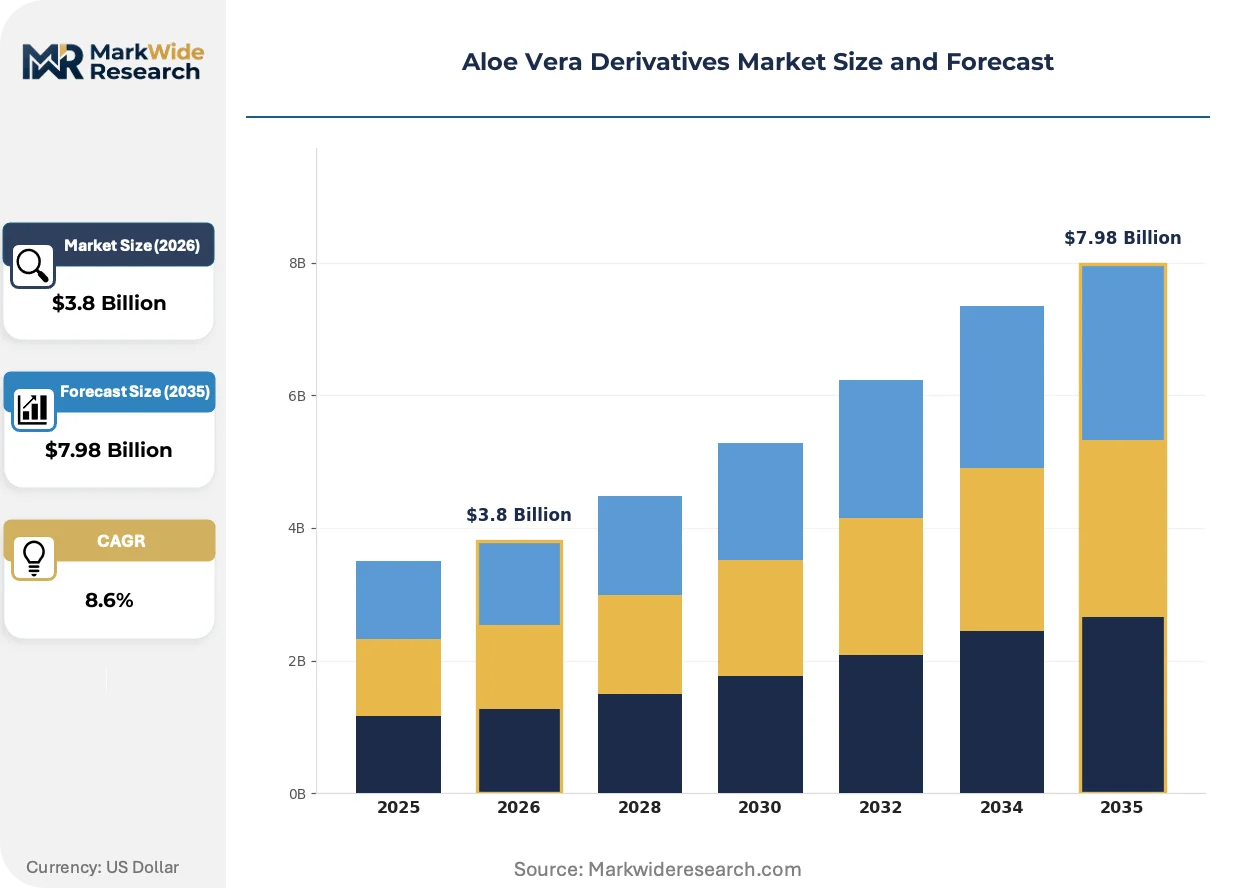
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aloe Vera Derivatives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aloe Vera Gel, Aloe Vera Powder, Aloe Vera Juice, Aloe Vera Extract Application: Cosmetics, Food & Beverages, Pharmaceuticals, Nutraceuticals End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Forever Living Products, Lily of the Desert, Aloe Laboratories, Stockton Aloe 1, Aloe Queen, Terry Laboratories, Herbalife, Omica Organics, Aloecorp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aloe Vera Derivatives Market Emerging Trajectories
Processing technology and regulatory documentation requirements are compressing the supplier base while opening margin tiers for processors with certified organic capacity and pharmaceutical-grade qualification experience.
Cold-pressed inner leaf gel extraction is collapsing the cost differential between commodity-grade and premium stabilized gel formats. Mid-tier cosmetics manufacturers in South Korea and France are adopting this technology to access acemannan-standardized inputs without paying legacy processor premiums. The technology is collapsing traditional three-tier supply structures into a bifurcated market of certified-organic qualified suppliers and undifferentiated commodity traders.
REACH registration requirements for botanical extracts in leave-on products are tightening substance identity documentation obligations for EU market access. Processors must now submit full safety assessment dossiers including polysaccharide molecular weight distribution data. German and French cosmetics houses are responding by consolidating supplier panels to processors with existing REACH compliance infrastructure, accelerating volume concentration among established players.
Direct-to-brand contract manufacturing is displacing traditional ingredient distributor intermediation in the personal care channel. K-beauty incubators and Ayurvedic-inspired direct-to-consumer brands are negotiating formulation services directly with plantation-integrated processors. This pattern is most visible in California and Seoul, where clean-label skincare startups prioritize supply chain transparency narratives over distributor-managed inventory programs.
Aloe Vera Derivatives Market Segmentation
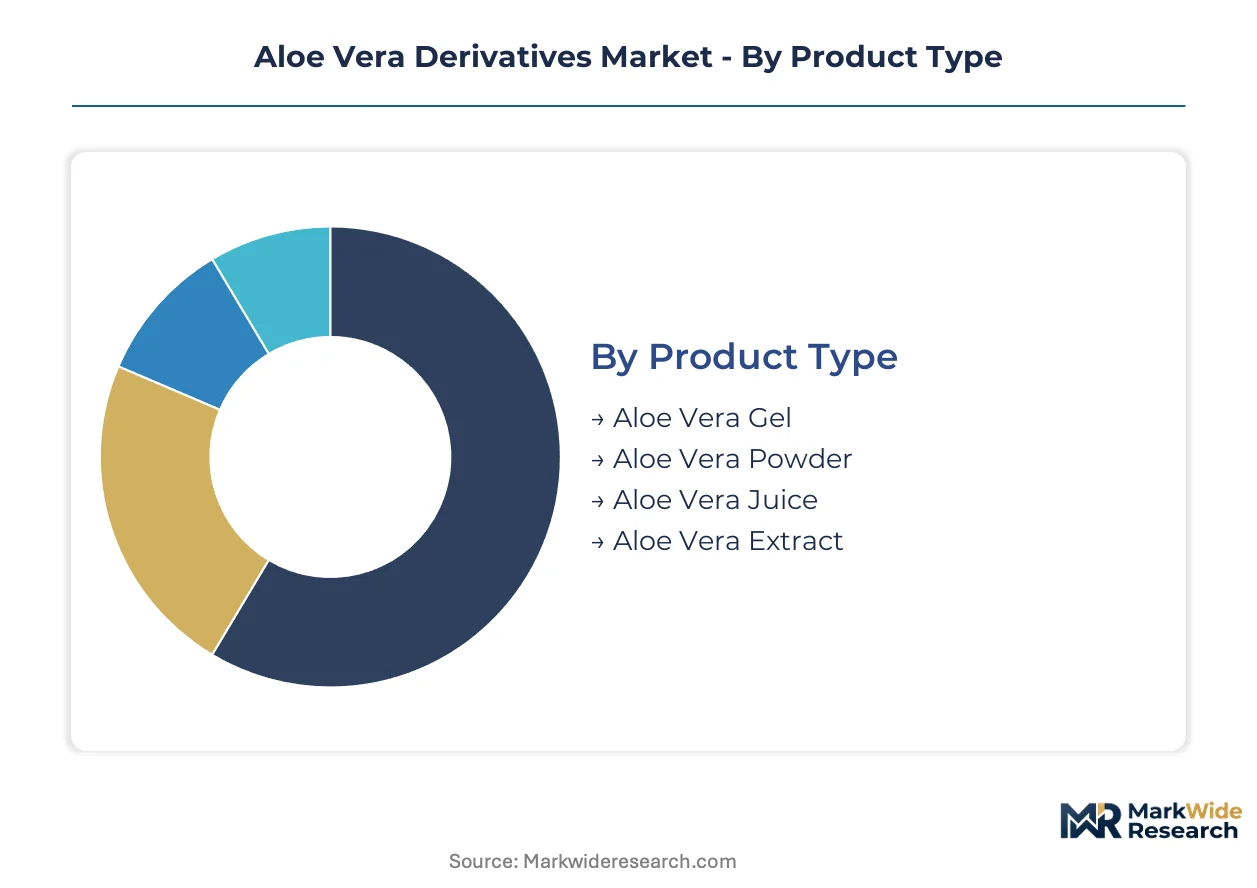
Aloe vera derivatives fragment across four distinct category axes, each governed by divergent margin structures and qualification barriers. Product type and application segmentation reveal the deepest strategic fault lines, as pharmaceutical-grade extract and cosmetics-grade gel operate under incompatible regulatory and pricing regimes.
Product Type:
Mature formats dominate volume throughput while emerging dehydration technologies reshape powder economics.
- Aloe Vera Gel:Stabilized inner leaf gel containing acemannan polysaccharides serves as the foundational input for rinse-off and leave-on cosmetic bases. Demand concentrates in Germany, South Korea, and India where K-beauty and Ayurvedic brands mandate certified organic sourcing for serum formulations; cold-pressed extraction technology is collapsing traditional premium-commodity price differentials.
- Aloe Vera Powder:Spray-dried particulate formats with defined mesh sizes enable dry nutraceutical capsules and functional beverage premixes where water activity constraints exclude liquid alternatives. South Korean and French manufacturers are adopting low-temperature dehydration to preserve bioactivity; this segment gains share fastest in powdered drink mix applications.
- Aloe Vera Juice:Decolorized whole leaf or inner fillet beverages for direct consumption and beverage fortification. Lily of the Desert anchors supply through certified organic processing and in-house juice concentrate production.
- Aloe Vera Extract:Pharmaceutical-grade material with tight specification thresholds for topical drug development. Terry Laboratories competes on FDA-compliant raw material documentation; qualification bottlenecks concentrate supply with processors holding drug master files.
Aloe Vera Gel retains volume leadership; Aloe Vera Powder holds the steepest expansion curve.
Application:
End-use segmentation tracks divergent regulatory exposure and margin capture across personal care, therapeutic, and ingestible categories.
- Cosmetics:Serum, essence, and moisturizer formulations absorb the majority of gel and extract throughput. Clean-label mandates from multinational cosmetics houses in France and Germany are compressing specification tolerances and disqualifying commodity traders.
- Pharmaceuticals:Over-the-counter topical therapeutic products require drug master file documentation and acemannan standardization. FDA guidance on botanical drug development tightens purity benchmarks; analytical chemist scarcity slows new entrant qualification timelines.
- Food & Beverages:Beverage fortification and functional food applications operate under FSSAI regulation in India and FDA Center for Food Safety and Applied Nutrition oversight in the United States.
- Nutraceuticals:Dry-format capsules and tablets leverage powder formats; New Dietary Ingredient notification requirements govern United States market entry.
Cosmetics commands absolute volume; Pharmaceuticals delivers the highest margin per kilogram.
End User:
Customer type determines procurement modality and supply chain transparency requirements.
- Manufacturers:Personal care, pharmaceutical, and food processors sourcing bulk derivatives for formulation. Direct-to-brand contract manufacturing displaces traditional distributor intermediation in California and Seoul.
- Distributors:Ingredient traders and specialty chemical distributors serving mid-tier formulators without plantation-direct relationships.
- Retailers:Private-label skincare and supplement brands negotiating formulation services directly with plantation-integrated processors.
- Consumers:Direct purchases of finished aloe vera products; minimal raw derivative exposure.
Manufacturers retain procurement volume leadership; Retailers are climbing the fastest as direct-to-consumer brands consolidate supplier relationships.
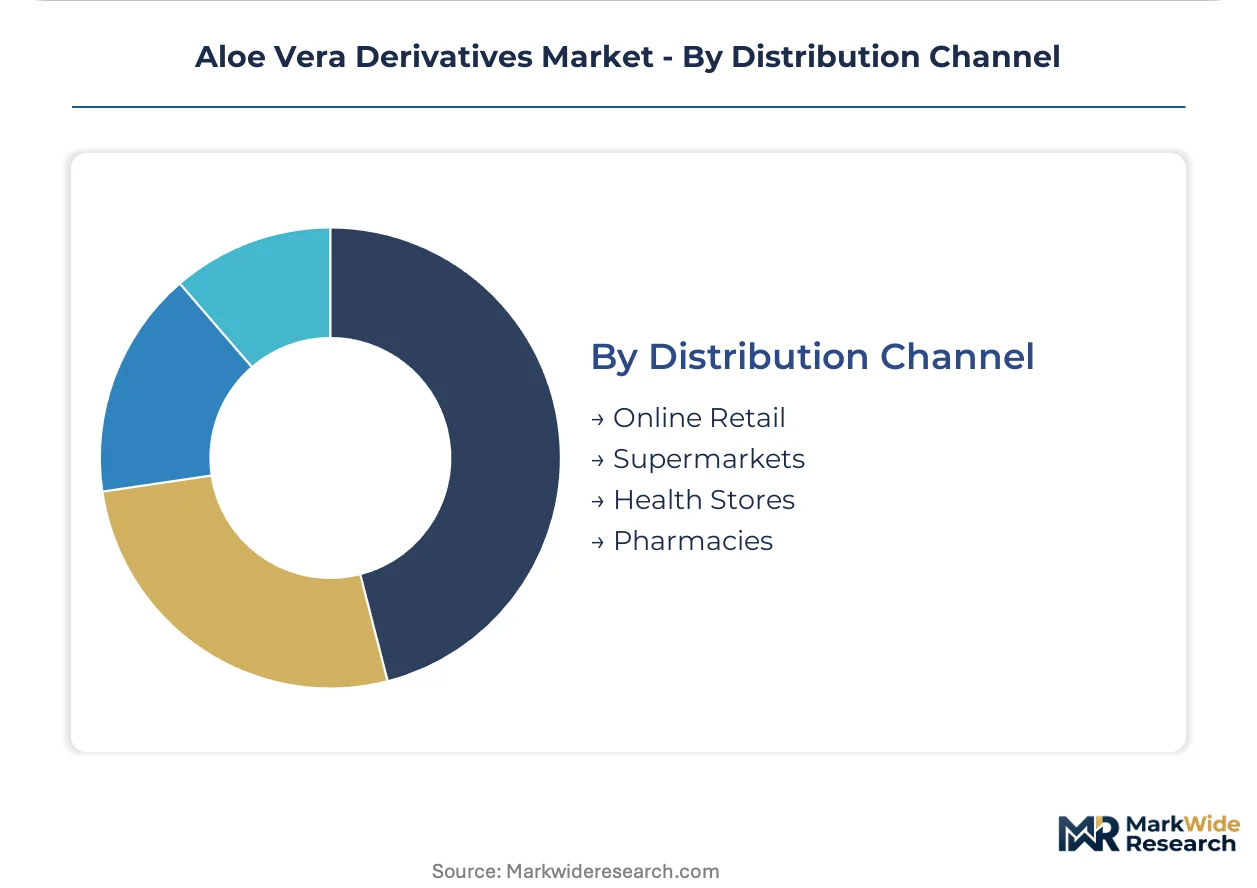
Distribution Channel:
Channel segmentation reflects inventory velocity and certification documentation requirements.
- Online Retail:E-commerce platforms serving direct-to-consumer brands and small-batch formulators; real-time inventory visibility demands strain legacy ERP integration.
- Supermarkets:Mass-market finished goods distribution with limited raw derivative penetration.
- Health Stores:Specialty retailers for organic and Ayurvedic-positioned products; COSMOS certification documentation required for shelf placement in Germany and France.
- Pharmacies:Pharmaceutical-grade extract distribution for topical drug developers; FDA-compliant raw material documentation mandatory.
Online Retail captures volume leadership; Health Stores gain share fastest on clean-label positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Germany demonstrate low price elasticity for certified organic aloe vera gel, while commodity traders in India face intense margin compression from tightening purity benchmarks. Demand concentrates where clean-label mandates intersect with established cosmetics manufacturing infrastructure.
United States
Personal care manufacturers in California and Texas are expanding procurement for clean-label skincare formulations. The FDA Center for Food Safety and Applied Nutrition monitors aloe vera ingredient status under New Dietary Ingredient notification requirements. Forever Living Products operates captive plantations across Texas and the Dominican Republic to secure leaf-to-extract supply control.
Germany
Cosmetics houses in Hamburg and Düsseldorf are consolidating supplier panels to processors with REACH compliance infrastructure. The EU Cosmetics Regulation mandates safety assessment dossiers including polysaccharide molecular weight distribution data. German formulators are disqualifying commodity traders as anthraquinone limits tighten.
India
Ayurvedic-inspired brands in Maharashtra and Gujarat are sourcing certified organic derivatives for traditional medicine applications. The Ministry of Ayush and FSSAI regulate parallel compliance pathways for exporters. Production-linked incentives for herbal extract processing are attracting investment into Madhya Pradesh and Rajasthan cultivation clusters.
South Korea
K-beauty manufacturers in Seoul and Gyeonggi-do are mandating certified organic aloe vera gel for serum and essence formulations. The MFDS oversees cosmetic safety assessments while brands prioritize supply chain transparency narratives. Direct-to-brand contract manufacturing is displacing traditional distributor intermediation among clean-label skincare startups.
France
Oral care and cosmetics formulators in Paris and Lyon remain lightly served by aloe vera derivatives for toothpaste and mouthwash applications. ANSM enforces COSMOS certification documentation for organic-positioned products. French manufacturers are compressing specification tolerances and forcing processors to invest in certified organic supply chains.
Aloe Vera Derivatives Market Vendor Landscape
Plantation-integrated processors and pharmaceutical-grade specialists split the market into divergent margin tiers. The supplier base compresses as clean-label mandates and regulatory documentation requirements disqualify undifferentiated commodity traders. Three archetypes dominate: captive cultivation operators with leaf-to-finished-extract control, certified organic processors with juice concentrate integration, and drug master file holders serving topical drug developers. Competitive moves center on backward integration into cultivation assets and qualification infrastructure for FDA-compliant raw material documentation.
Within the plantation-integrated tier, Forever Living Products and Lily of the Desert exemplify archetypes built on supply chain control and certified organic positioning respectively. Terry Laboratories occupies a position representing pharmaceutical-grade extract supply where drug master file experience creates qualification bottlenecks. These three anchors illustrate how regulatory documentation requirements and cultivation asset ownership separate premium-tier processors from commodity traders facing disqualification.
| Leading Market Players |
|---|
| Forever Living Products |
| Lily of the Desert |
| Aloe Laboratories |
| Stockton Aloe 1 |
| Aloe Queen |
| Terry Laboratories |
| Herbalife |
| Omica Organics |
| Aloecorp |
| Others |
Supply Flow & Price Mechanics
Anthraquinone limit tightening under the EU Cosmetics Regulation determines both pricing tier spreads and supply chain shape, compressing margins for commodity traders while concentrating volume with processors holding drug master file documentation and certified organic capacity. Irrigation water scarcity in Texas and Dominican Republic plantation zones feeds back into multi-year cultivation contracting as processors hedge input cost volatility through captive leaf supply arrangements.
Pricing Analysis
Aftermarket formulation services and extended contract manufacturing agreements drive lifetime value capture across the supplier base. Three-tier pricing structure across pharmaceutical-grade extract, certified organic gel, and commodity-grade powder segments separates processors by qualification depth and documentation burden. Cost compression in commodity-grade powder runs through cold-pressed extraction technology adoption by mid-tier South Korean and French cosmetics manufacturers. Brand managers at K-beauty incubators and Ayurvedic direct-to-consumer startups demonstrate lowest price sensitivity, while mid-tier nutraceutical capsule manufacturers in India face acute margin pressure from FSSAI compliance costs.
Supply Chain Analysis
Tariff exposure between Dominican Republic processing facilities and EU destination markets dominates risk assessment for plantation-integrated operators serving German and French cosmetics houses. Supply draws from cultivation clusters in Texas, Dominican Republic, and Rajasthan, with Madhya Pradesh emerging under India's PLI scheme for herbal extract processing. Raw material sourcing rests on acemannan-standardized leaf tissue, decolorized whole leaf input, and spray-dried particulate intermediates. Single-source vulnerability concentrates with Terry Laboratories and legacy drug master file holders serving FDA-compliant topical drug developers. Distribution runs through direct-to-brand contract manufacturing channels displacing traditional ingredient distributor intermediation in California and Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to K-beauty and Ayurvedic brand sourcing waves, with clean-label formulation mandates from multinational cosmetics houses compressing specification tolerances and disqualifying undifferentiated commodity traders in successive qualification cycles.
For Market Incumbents: Insulate margin position through backward integration into Rajasthan and Madhya Pradesh cultivation assets under India's PLI scheme, while accelerating REACH compliance infrastructure investment to capture German and French cosmetics house supplier panel consolidation. Centella asiatica and snail mucin substitution threats in K-beauty formulations demand acemannan bioactivity preservation capabilities as a defensive moat. Certification investment in USDA Organic and COSMOS documentation creates stickiness with direct-to-brand contract manufacturing clients.
For New Entrants and Emerging Players: Pursue oral care white space in German and French toothpaste and mouthwash applications, where decolorized whole leaf extract supply remains lightly served and taste-masking capabilities command premium positioning. India's FSSAI-regulated functional food category offers the most penetrable regulatory pathway for export-oriented processors with Ministry of Ayush compliance experience. A go-to-market angle anchored to encapsulation technology partnerships with hyaluronic acid suppliers enables extended-release skincare format differentiation in professional salon channels.
For Investors and Strategic Acquirers: FDA botanical drug development guidance reshapes the acquisition landscape toward processors with drug master file experience and analytical chemist teams capable of acemannan quantification and anthraquinone profiling. Long-term viability over a multi-year horizon favors certified organic plantation-integrated operators with juice concentrate production capabilities and real-time ERP integration for multinational cosmetics house supplier portals. The signal to watch is COSMOS certification auditor backlog resolution, which will unlock contract manufacturing launch timing for brands with fixed product launch windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Assets | Captive leaf supply from Texas and Dominican Republic plantations secures acemannan-standardized input consistency against irrigation water scarcity. |
| Certified Organic Capacity Expansion | USDA Organic and COSMOS certification unlocks procurement relationships with K-beauty and Ayurvedic-inspired clean-label skincare brands. |
| Drug Master File Qualification Investment | FDA-compliant raw material documentation creates qualification bottlenecks defensible against commodity trader displacement. |
| Direct-to-Brand Contract Manufacturing | Formulation services displace distributor intermediation among California and Seoul clean-label skincare startups prioritizing supply chain transparency. |
| Encapsulation Technology Partnership | Hyaluronic acid convergence enables extended-release skincare formats commanding premium positioning in professional salon channels. |
Methodological Framework
A standing panel of plantation operations managers, cosmetics formulation chemists, regulatory affairs specialists at FDA and EMA, and procurement directors at German and French multinational cosmetics houses provided ongoing calibration across primary fieldwork and secondary validation. Secondary sources included EU Cosmetics Regulation safety assessment dossiers, FDA New Dietary Ingredient notification filings, FSSAI functional food compliance records, and REACH botanical extract registration documentation. Bottom-up volume modeling across gel, powder, juice, and extract formats triangulated against top-down value estimates from cosmetics, pharmaceutical, and nutraceutical application spend.
Scenario-bracketing around regulatory timeline compression and certification auditor backlog produced bounded projections across the analysis window. Segmentation dimensions spanned product type, application, end user archetype, and distribution channel, with additional modeling of acemannan concentration tier and anthraquinone compliance grade. CAGRs derived from fitted growth curves calibrated to clean-label mandate adoption rates and K-beauty sourcing pattern shifts. Industry-specific forecast inputs included cold-pressed extraction technology penetration and spray-drying bioactivity preservation coefficients.
Sensitivities concentrate around EU Cosmetics Regulation anthraquinone limit enforcement timing, FDA botanical drug development guidance finalization, and India PLI scheme disbursement velocity for Madhya Pradesh and Rajasthan cultivation clusters. Forecasts embed assumptions regarding certification cycle duration and analytical chemist labor market tightness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Citrus Powder Market
Extracts
Labdanum Market
Extracts
Pennyroyal Oil Market
Extracts
Tagetes Oil Market
Extracts
Polygonum Cuspidatum Extract Market
Extracts
Citronella Oil Market
Extracts
Cassia Seed Extract Market
Extracts
Lemon Balm Extract Market
Extracts
Chamomile Oil Market
Extracts
Cochineal Extract Market
Extracts
Myrrh Powder Market
Extracts
Nigella Sativa Extract Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Bee Venom Extract Market
Extracts
Irish Moss Extract Market
Extracts
Natural Rosemarine Extract Market