
 Naturally Derived Fatty Alcohol Market | 2026-2036
Naturally Derived Fatty Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Naturally Derived Fatty Alcohol Market Foresight
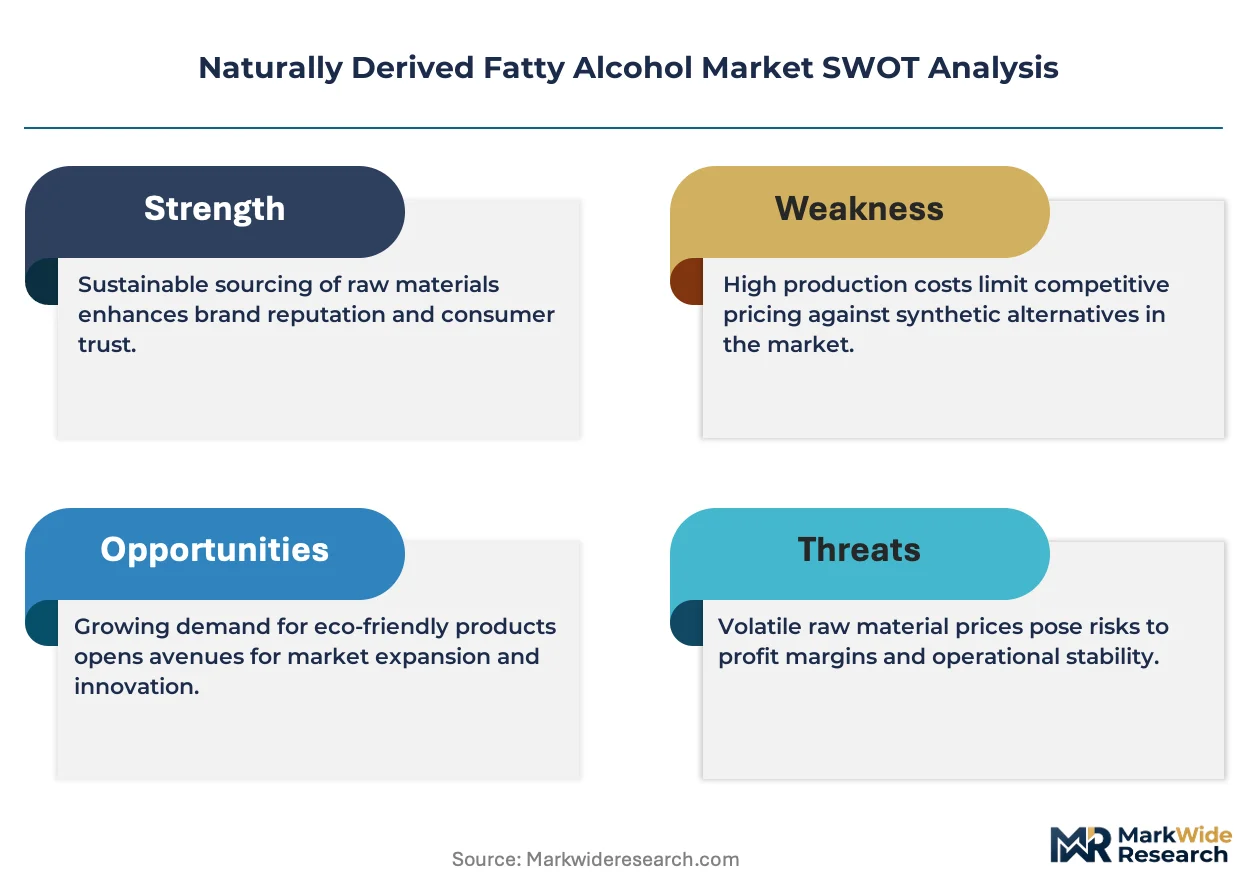
Capital-intensity divergence between integrated plantation operators and standalone alcohol refiners is unwinding traditional margin structures in the naturally derived fatty alcohol sector. BASF leverages backward integration into European rapeseed methyl ester streams to secure feedstock certainty. Wilmar International anchors its position through plantation-to-port control across Indonesian and Malaysian supply chains. Ecogreen Oleochemicals differentiates via dedicated oleochemical complexes in Southeast Asia with co-located fractionation and hydrogenation units.
Naturally derived fatty alcohols comprise saturated and unsaturated long-chain aliphatic alcohols obtained through catalytic hydrogenation of fatty acid methyl esters or triglycerides, typically ranging from C8 to C22 chain lengths with melting points between 48°C and 72°C for solid fractions; these molecules function primarily as non-ionic surfactant precursors, emulsion stabilizers, and viscosity modifiers across consumer and industrial formulations. Coconut-derived cuts lead volume globally due to favorable lauric-myristic C12-C14 profiles for foaming applications, while oleyl alcohol commands premium positioning in pharmaceutical and cosmetic emollients where unsaturation enhances spreadability. Stearyl fractions occupy mature, cost-competitive territory in household and industrial cleaner bases where hardness and opacity drive specification rather than sensory performance.
REACH registration requirements and the EU Green Deal carbon border adjustments shape import economics for Asian oleochemical exporters serving European cosmetic and cleaning product manufacturers. FDA oversight of food-contact substances and EPA Safer Choice labeling influence qualification thresholds for fatty alcohols entering US household and food additive channels. Stakeholders must monitor feedstock certification fragmentation—RSPO, ISCC, and national sustainability schemes—as procurement rules harden across downstream brand owner specifications.
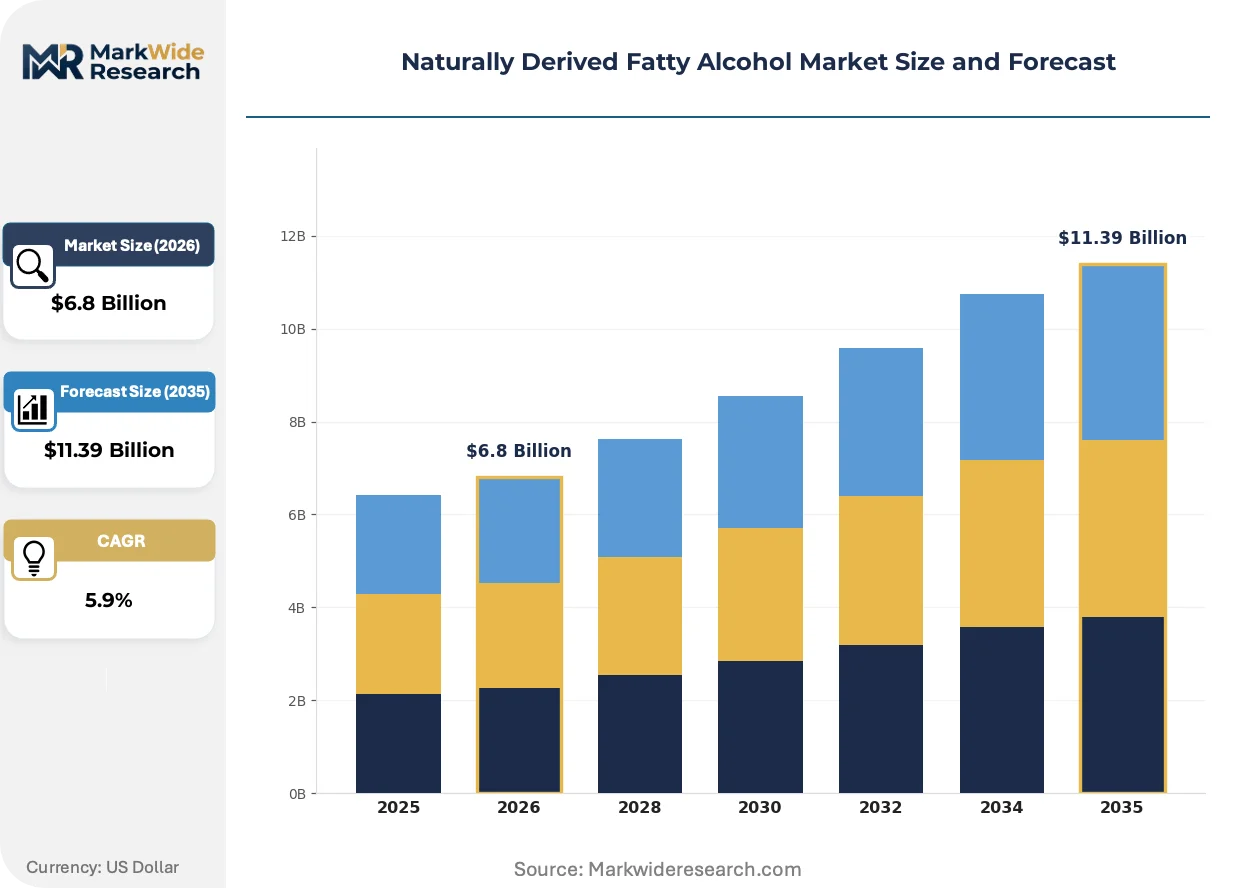
Market Dynamics
Integrated plantation-to-refinery control is compressing margin capture for standalone fatty alcohol processors while REACH carbon border adjustments force feedstock traceability investments across European supply chains.
Growth Catalysts
- Sulfate-free cosmetic formulations:Personal care manufacturers in Germany and France are substituting petrochemical surfactants with coconut-derived C12-C14 alcohols to meet clean-label specifications.
- EU Green Deal carbon accounting:Import declarations now require verified scope 3 emissions data, accelerating certified sustainable palm kernel oil procurement from Indonesian and Malaysian suppliers.
- Bio-based industrial cleaners:EPA Safer Choice qualification thresholds are pulling stearyl alcohol into food-contact surface applications across US institutional channels.
Market Restraints
- Feedstock price volatility:Crude palm oil futures on Bursa Malaysia Derivatives Exchange swing 15-25% seasonally, squeezing standalone hydrogenation unit margins.
- Supply concentration risk:Over 70% of global lauric oils originate from Indonesian and Malaysian estates exposed to El Niño drought cycles and export levy volatility.
- Petrochemical substitution:Shell higher olefins process-derived synthetic fatty alcohols undercut natural C16-C18 cuts in price-sensitive detergent applications.
Strategic Opportunities
- Indian personal care expansion:BIS certification alignment and FSSAI cosmetic ingredient approvals are opening formulation-grade oleyl alcohol demand in Mumbai and Bangalore manufacturing clusters.
- Pharmaceutical emollient qualification:USP-NF monograph compliance for oleyl alcohol is creating premium positioning in transdermal drug delivery systems.
- Biorefinery co-location:Integrated fatty acid methyl ester and hydrogenation complexes in Johor and Rotterdam are capturing scope 2 emissions reductions for EU Green Deal compliance.
Industry Challenges
- RSPO-ISCC certification fragmentation:Downstream brand owners impose non-aligned sustainability criteria, forcing dual-audit burden on Southeast Asian processors.
- Catalytic hydrogenation expertise scarcity:Nickel catalyst optimization and selective fatty acid methyl ester conversion require specialized chemical engineering talent concentrated in European and Japanese technical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naturally Derived Fatty Alcohol Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut, Palm, Oleyl, Stearyl Application: Personal Care, Household Products, Industrial Cleaners, Food Additives End User: Cosmetic Manufacturers, Food Industry, Cleaning Products Companies, Pharmaceutical Firms Distribution Channel: Online Retailers, Distributors, Supermarkets, Direct Sales |
| Companies Covered | BASF, Procter & Gamble, Sasol, Shell Chemicals, Ecogreen Oleochemicals, Kao Chemicals, Wilmar International, KLK Oleo, Musim Mas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naturally Derived Fatty Alcohol Market Shifts & Advancements
Membrane fractionation and enzymatic interesterification are displacing thermal distillation in lauric oil processing, while digital traceability platforms reshape procurement verification workflows across cosmetic and pharmaceutical supply chains.
Supercritical CO2 extraction technology is miniaturizing for mid-scale oleochemical processors, enabling on-site C8-C10 caprylic-capric fractionation without centralized refinery infrastructure. Specialty chemical distributors in the Netherlands and Singapore are piloting containerized units for just-in-time cosmetic ingredient supply. This distributed processing architecture is compressing working capital requirements for regional formulators while challenging economies of scale at legacy hydrogenation complexes.
REACH registration dossier updates under ECHA substance evaluation protocols now mandate extended aquatic toxicity data for C12-C18 alcohol ethoxylates. German and French cleaning product manufacturers are accelerating substitution toward C10-derived alternatives with favorable biodegradation profiles. The regulatory pressure is fragmenting surfactant precursor specifications across EU member state competent authorities.
Direct farm-to-refinery contracting is displacing spot market procurement for certified sustainable feedstocks. Major cosmetic brand owners in California and New York are executing multi-year offtake agreements with Indonesian plantation cooperatives, bypassing traditional oleochemical trading houses. This channel compression is most visible in lauric oil supply chains serving North American sulfate-free shampoo and body wash formulations.
Naturally Derived Fatty Alcohol Market Segmentation
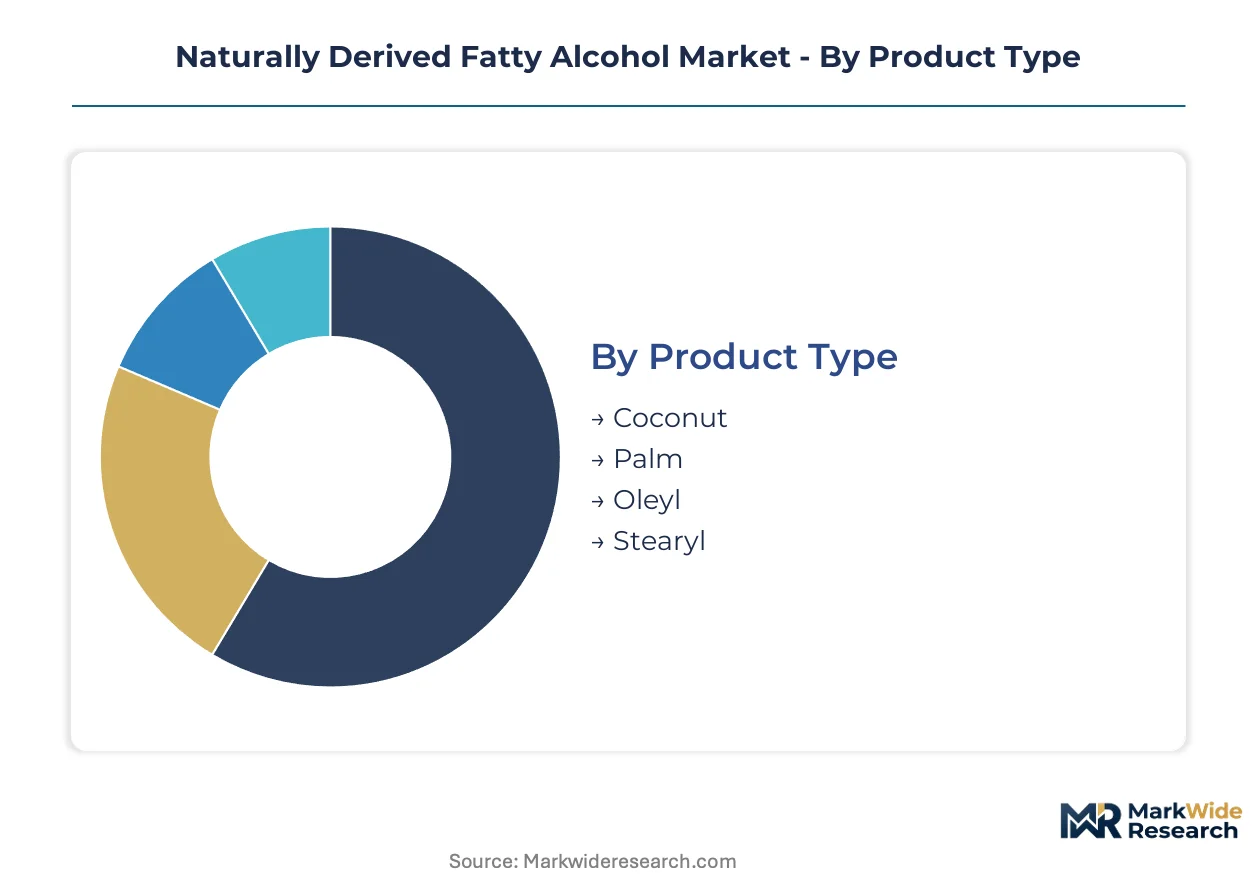
Segmentation in naturally derived fatty alcohols reveals how feedstock origin, application chemistry, and channel economics split margin capture across the value chain. Procurement patterns diverge sharply between plantation-integrated supply and spot-market sourcing, with certification requirements now filtering segment access in European and North American markets.
Product Type:
Domestic consumption dominates palm and stearyl fractions in Southeast Asian markets, while coconut and oleyl grades serve export-led demand in European cosmetic and pharmaceutical channels.
- Coconut:Lauric-myristic C12-C14 profiles deliver superior foaming performance in sulfate-free shampoo and body wash formulations. German and French cosmetic manufacturers source certified sustainable cuts through Rotterdam trading hubs to satisfy EU Green Deal carbon accounting requirements.
- Oleyl:Unsaturated C18:1 structure provides spreadability and skin penetration critical to pharmaceutical emollients and premium cosmetic serums. USP-NF monograph compliance positions this grade in transdermal drug delivery systems manufactured in New Jersey and California facilities.
- Palm:C16-C18 saturated fractions from Malaysian and Indonesian estates supply cost-competitive detergent alcohols for Asian household cleaner bases.
- Stearyl:C18 solid alcohol serves industrial cleaner opacity and hardness specifications across price-sensitive institutional channels in India and Brazil.
Coconut holds the largest share; momentum sits with oleyl as pharmaceutical qualification expands.
Application:
Cost tier stratification separates premium-positioned personal care grades from commodity industrial segments, with certification premiums widening the spread.
- Personal Care:Sulfate-free formulation mandates in California and New York cosmetic manufacturing pull RSPO-certified lauric alcohols through dedicated supply contracts. Clean-label positioning commands 15-40% procurement premiums over standard detergent grades.
- Household Products:Stearyl and palm-based C16-C18 cuts dominate laundry and dish formulations where opacity and cleaning efficiency outweigh sensory performance. Indian and Indonesian domestic markets absorb volume through local brand manufacturing clusters.
- Industrial Cleaners:EPA Safer Choice qualification thresholds in US institutional channels favor bio-based C12-C14 ethoxylates for food-contact surface applications.
- Food Additives:FDA food-contact substance notifications restrict fatty alcohol use to emulsifier and coating functions in confectionery and bakery segments.
Household products hold the largest share; personal care is climbing the fastest as clean-label specifications harden.
End User:
Customer type determines procurement sophistication, with pharmaceutical and cosmetic buyers demanding full feedstock traceability while industrial channels prioritize volume security.
- Cosmetic Manufacturers:L'Oréal and Unilever procurement teams execute multi-year offtake agreements with Indonesian plantation cooperatives, bypassing traditional oleochemical traders to secure RSPO-certified lauric supply chains.
- Pharmaceutical Firms:USP-NF monograph compliance and ICH Q3C residual solvent specifications drive oleyl alcohol qualification for transdermal patches and topical creams manufactured in Basel and Boston facilities.
- Food Industry:FDA food-contact notifications and FSSAI cosmetic ingredient approvals govern emulsifier applications in processed foods across US and Indian markets.
- Cleaning Products Companies:Institutional channel buyers in Germany and France source stearyl fractions through Rotterdam distributors for EU Ecolabel-compliant surface cleaners.
Cosmetic manufacturers hold the largest share; pharmaceutical firms show steepest expansion trajectory as emollient qualification deepens.
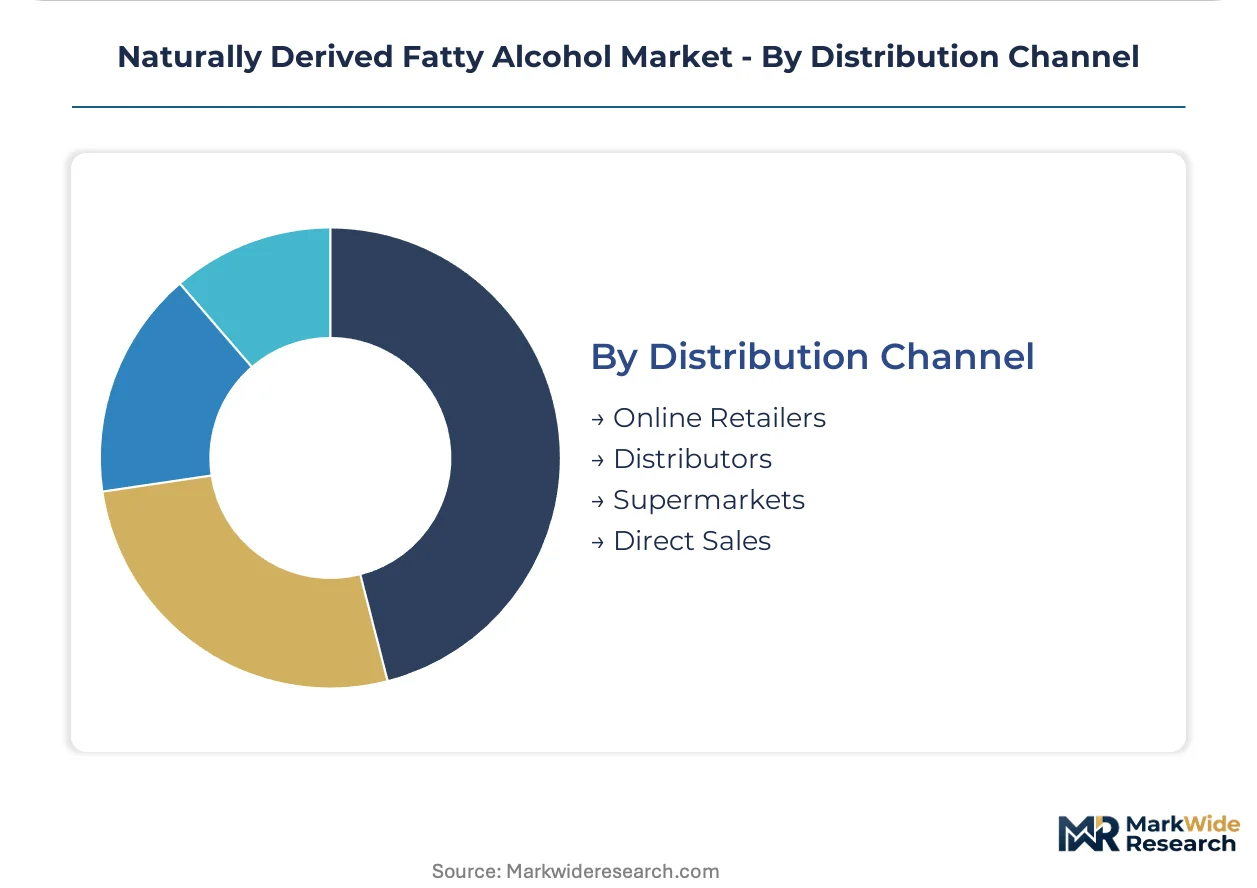
Distribution Channel:
Supply concentration in Southeast Asian production clusters shapes channel economics, with direct sales capturing plantation-integrated volumes and distributors serving fragmented regional formulators.
- Distributors:Dutch and Singapore specialty chemical distributors maintain Johor and Rotterdam warehouse positions for just-in-time delivery to mid-scale cosmetic formulators. Inventory pooling reduces working capital burdens for regional manufacturers lacking direct plantation contracts.
- Direct Sales:BASF and Wilmar International execute long-term supply agreements with major brand owners, embedding carbon accounting data and RSPO certification directly into procurement contracts.
- Online Retailers:Alibaba and specialty chemical platforms serve small-batch cosmetic ingredient purchases in Indian and Southeast Asian markets.
- Supermarkets:Limited to consumer-facing finished products rather than industrial fatty alcohol volumes.
Distributors hold the largest share; direct sales are gaining share fastest as channel compression accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Southeast Asian plantation belts while European refiners absorb carbon border compliance costs. Indonesian and Malaysian estates capture upstream margins through direct farm contracting. Rotterdam and Hamburg processors face compressed spreads as REACH documentation requirements harden.
Indonesia
Sumatran and Kalimantan plantation cooperatives supply over half of global lauric oil feedstock through direct offtake agreements with cosmetic brand owners. The national export levy structure on crude palm oil derivatives shapes regional pricing benchmarks. Surabaya oleochemical complexes are expanding hydrogenation capacity to capture downstream value from captive palm kernel supplies.
Germany
Rapeseed methyl ester streams from North Rhine-Westphalia biorefineries anchor European oleochemical self-sufficiency ambitions. ECHA substance evaluation protocols now mandate extended aquatic toxicity data for C12-C18 alcohol ethoxylates. BASF's Ludwigshafen complex leverages backward integration into regional oilseed crushing to secure feedstock certainty against import volatility.
United States
New Jersey and California pharmaceutical manufacturing clusters drive USP-NF monograph demand for oleyl alcohol in transdermal drug delivery systems. EPA Safer Choice qualification thresholds pull bio-based C12-C14 ethoxylates into institutional food-contact surface applications. Gulf Coast petrochemical corridors maintain synthetic fatty alcohol capacity that undercuts natural C16-C18 cuts in price-sensitive detergent channels.
India
Mumbai and Bangalore cosmetic manufacturing clusters are opening formulation-grade fatty alcohol demand as BIS certification alignment accelerates. FSSAI cosmetic ingredient approvals govern emulsifier applications in domestic personal care products. Gujarat-based refiners are expanding fractionation capacity to serve both export and rapidly growing domestic household cleaner markets.
Netherlands
Rotterdam trading hubs function as the primary European entry point for RSPO-certified lauric oils from Southeast Asian suppliers. EU Green Deal carbon border adjustments force verified scope 3 emissions documentation on all oleochemical imports. Dutch specialty chemical distributors maintain Johor and Rotterdam warehouse positions for just-in-time delivery to mid-scale cosmetic formulators across the Rhine-Ruhr industrial corridor.
Naturally Derived Fatty Alcohol Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with plantation-integrated operators commanding feedstock economics while specialized refiners dominate pharmaceutical-grade qualification. The vendor base splits between Southeast Asian estate-holders with captive supply chains and European chemical conglomerates with catalytic hydrogenation expertise. Two strategic archetypes define positioning: integrated plantation-to-refinery operators capturing upstream margins, and standalone processors relying on spot market sourcing and technical differentiation. Dominant competitive moves include direct farm contracting to bypass trading intermediaries and biorefinery co-location to capture scope 2 emissions reductions for EU compliance.
Among plantation-integrated operators, Wilmar International and KLK Oleo exemplify the archetype of upstream control through Indonesian and Malaysian estate networks. BASF represents the technology-anchored European model, leveraging rapeseed methyl ester streams and catalytic expertise to serve pharmaceutical and cosmetic qualification requirements. Ecogreen Oleochemicals occupies a position between these poles, with dedicated oleochemical complexes in Southeast Asia that co-locate fractionation and hydrogenation units to bridge feedstock access and technical processing capability.
| Leading Market Players |
|---|
| BASF |
| Procter & Gamble |
| Sasol |
| Shell Chemicals |
| Ecogreen Oleochemicals |
| Kao Chemicals |
| Wilmar International |
| KLK Oleo |
| Musim Mas |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon border adjustments gate both supply qualification and price differentiation simultaneously, forcing Rotterdam and Hamburg processors to absorb verified scope 3 documentation costs while plantation-integrated operators in Sumatra and Kalimantan capture upstream premiums through direct farm contracting.
Pricing Analysis
Certification-premium spreads separate RSPO-certified lauric cuts from standard detergent grades by 15-40% procurement premiums. Price differentiation hinges on sustainability certification tier and volume scale, with cosmetic manufacturers in Germany and France absorbing premium costs for clean-label positioning. Cost compression in stearyl and palm-based C16-C18 fractions is intensifying because Shell higher olefins process-derived synthetics undercut natural cuts in price-sensitive Indian and Brazilian institutional channels. Industrial cleaner buyers exhibit highest price sensitivity; pharmaceutical formulators in New Jersey and Basel show lowest.
Supply Chain Analysis
Port congestion on the Singapore-Rotterdam trade lane elevates inbound logistics costs for spot-market processors lacking plantation contracts. Supply concentrates in Indonesia, Malaysia, and the Philippines, with over 70% of global lauric oils originating from estates in Sumatra and Kalimantan. Feedstock dependencies rest on crude palm oil futures, palm kernel oil availability, and coconut oil harvest cycles. Single-source vulnerability from El Niño drought exposure in Indonesian and Malaysian supply chains threatens volume security. Distribution runs through Dutch and Singapore specialty chemical distributors maintaining Johor and Rotterdam warehouse positions for just-in-time cosmetic ingredient delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon accounting mandates constitute a technological-regulatory inflection, compressing margin structures for standalone hydrogenation units while rewarding plantation-integrated operators with captive feedstock traceability systems.
For Market Incumbents: Shield margin capture by deepening backward integration into Indonesian and Malaysian plantation cooperatives, bypassing volatile spot markets for lauric oil procurement. Invest in nickel catalyst optimization capabilities at European technical centers to defend against Japanese and German engineering expertise concentration. Prioritize RSPO-ISCC dual certification to preempt downstream brand owner fragmentation of sustainability criteria. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade oleyl alcohol qualification, where USP-NF monograph compliance creates defensible positioning in transdermal drug delivery systems. Target Mumbai and Bangalore cosmetic manufacturing clusters, where BIS certification alignment and FSSAI approvals are opening formulation-grade demand faster than supply response. Pursue biorefinery co-location in Johor or Rotterdam to capture scope 2 emissions reductions for EU compliance without legacy infrastructure burdens. For Investors and Strategic Acquirers: EU Green Deal implementation reshapes the acquisition landscape toward plantation-integrated operators with direct farm contracting capabilities and verified carbon accounting systems. Five-to-ten year viability favors upstream control over standalone processing assets exposed to feedstock volatility. Target acquisition archetype: Southeast Asian estate-holders with captive palm kernel supply chains and existing hydrogenation capacity. Monitor ECHA substance evaluation protocol expansion as inflection signal for C12-C18 alcohol ethoxylate substitution toward C10-derived alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captures upstream margins and secures feedstock certainty against Bursa Malaysia futures volatility. |
| Dual RSPO-ISCC Certification Investment | Preempts downstream brand owner fragmentation and qualifies supply for EU Green Deal carbon accounting. |
| Biorefinery Co-location in Rotterdam or Johor | Captures scope 2 emissions reductions for EU compliance while bridging fractionation and hydrogenation capabilities. |
| Pharmaceutical-Grade Oleyl Alcohol Qualification | Positions for USP-NF monograph compliance in transdermal drug delivery systems manufactured in New Jersey and Basel. |
| Direct Farm-to-Refinery Contracting | Bypasses traditional oleochemical trading houses and embeds carbon accounting data into long-term offtake agreements. |
Research Methodology
Initial hypotheses were tested against primary input from oleochemical plant managers, cosmetic procurement leads at downstream brand owners, specialty chemical distribution channel partners, and technical R&D directors in catalytic hydrogenation, then refined against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed operators, and Bursa Malaysia Derivatives Exchange crude palm oil futures records. Bottom-up volume modeling from individual production facilities was triangulated against top-down demand aggregation from personal care and pharmaceutical formulation channels.
Variance decomposition across feedstock price volatility, certification penetration rates, and regional regulatory implementation timelines shaped the analytical framework. Segmentation dimensions modeled include feedstock origin tier, application chemistry grade, end-use industry vertical, and regional production hub cluster. CAGRs were derived from fitted growth curves calibrated to historical volume trajectories and projected substitution elasticities between natural and synthetic fatty alcohols. Forecast inputs incorporated REACH registration dossier update schedules and EPA Safer Choice qualification threshold evolutions.
Forecasts assume regulatory continuity in EU Green Deal carbon border adjustments and ECHA substance evaluation protocols; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Hydrophobing Agents Market
Chemicals
Formalin Market
Chemicals
Europe Methanol Market
Chemicals
South America Isoamyl Acetate Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
Aircraft Cleaning Chemicals Market
Chemicals
Calcium Carbide Market
Chemicals
Peroxyacetic Acid Market
Chemicals
India Ethoxylates Market
Chemicals
Thiourea Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
Germany Methanol Market
Chemicals
Sodium Ethyl P-Hydroxybenzoate Market
Chemicals
Sodium Hydride Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
China Inorganic Iodide Market