
 Postoperative Pain Market | 2026-2036
Postoperative Pain Market Size, Share, and Industry Trends Forecast 2026-2036
Postoperative Pain Market Outlook
Ambulatory surgical centers are unwinding the historical dominance of inpatient pharmacy purchasing for postoperative analgesia. Pfizer Inc. leverages its manufacturing scale across injectable and oral formulations to serve this channel shift. Johnson & Johnson sustains competitive presence through specialized hospital contracts for its non-opioid portfolio. Pacira BioSciences Inc. differentiates via liposomal bupivacaine technology leadership in long-acting local anesthesia.
Postoperative pain encompasses acute nociceptive and inflammatory pain states arising from tissue trauma following surgical intervention, typically managed through pharmacological modulation of peripheral and central pain signaling pathways. The condition demands therapeutics with rapid onset, predictable duration, and minimized systemic adverse effects to enable early mobilization and reduced length of stay. Non-opioid analgesics now command the fastest expansion within product type segmentation as institutional formularies restrict opioid exposure. Intravenous delivery mode retains primacy in perioperative settings, though transdermal formats gain traction in home care transitions where patient self-administration becomes necessary. Hospitals remain the dominant end user channel, capturing the deepest margin pools through bundled payment structures that reward effective pain control and complication avoidance.
The FDA shapes product development through REMS mandates for opioid analgesics and accelerated pathways for novel non-opioid mechanisms, while the DEA imposes manufacturing quotas that constrain supply planning for scheduled substances. EMA's MDR requirements for combination drug-device products add compliance layers to regional market access for advanced delivery systems. Stakeholders must monitor evolving payer policy on multimodal protocols and prepare portfolio pivots as institutional procurement shifts toward outcome-guaranteed contracts.
Market Dynamics
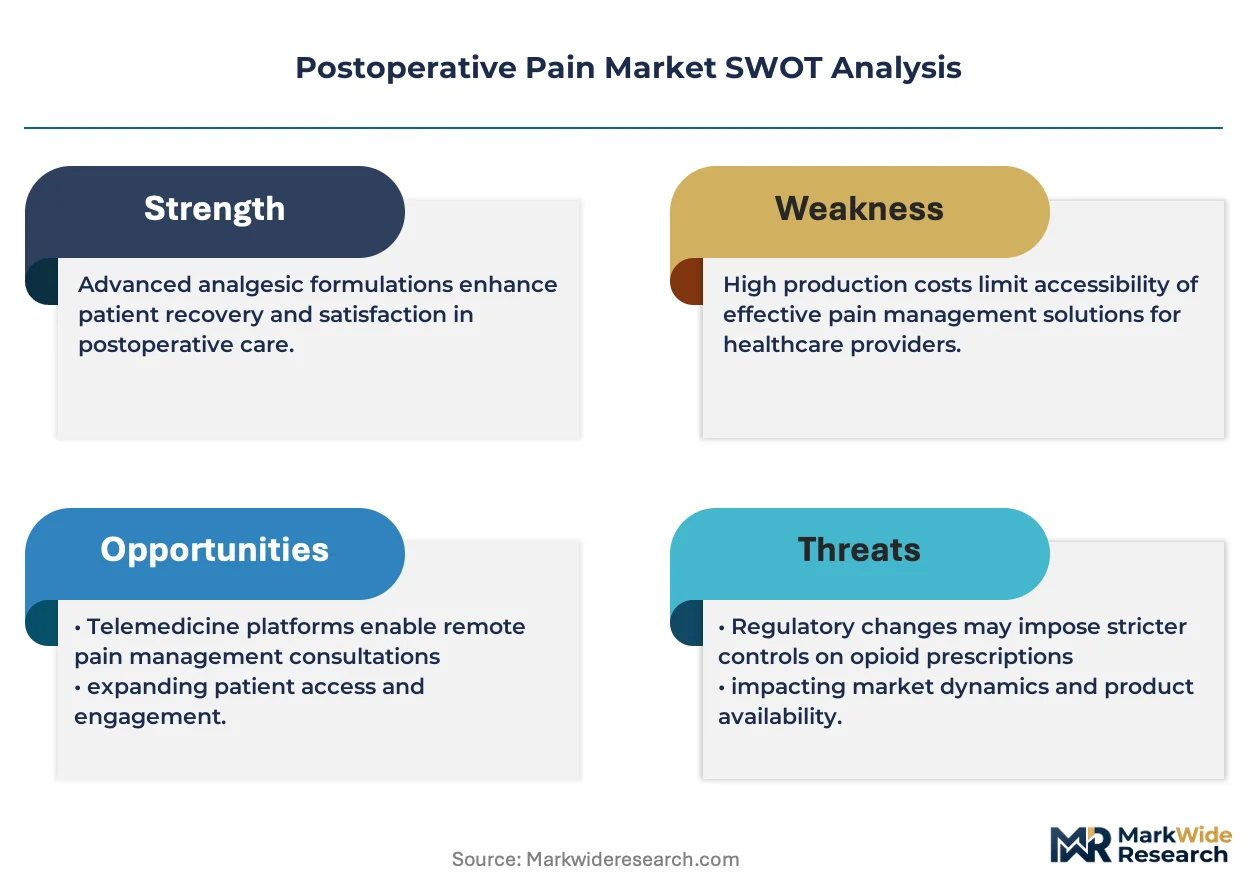
The FDA's Risk Evaluation and Mitigation Strategy mandates for extended-release opioids are structurally redirecting prescriber behavior toward non-opioid multimodal protocols, forcing pharmaceutical portfolios and hospital formularies to realign around analgesic efficacy without respiratory depression risk.
Growth Catalysts
- REMS Compliance Pressure:The FDA's enhanced opioid REMS requirements are accelerating institutional adoption of non-opioid alternatives in perioperative settings, creating procurement urgency for multimodal analgesia.
- Ambulatory Surgery Expansion:Same-day discharge mandates across United States hospital systems are amplifying demand for long-acting local anesthetics that enable outpatient mobilization without opioid rescue.
- Liposomal Formulation Advances:Sustained-release bupivacaine delivery technologies are extending single-injection analgesia duration from hours to days, displacing continuous catheter approaches in orthopedic and colorectal procedures.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Bupivacaine base supply chains concentrate among a limited cohort of Indian and Chinese manufacturers, exposing formulation sponsors to quota volatility and import inspection delays.
- Combination Product Complexity:The EMA's Medical Device Regulation imposes extended clinical evidence requirements on drug-device combinations, elongating European market access timelines for advanced delivery systems.
- Generic Infiltration:Plain bupivacaine and ropivacaine commoditization is compressing margin pools in short-acting local anesthesia, constraining R&D reinvestment capacity for novel formulations.
Strategic Opportunities
- Home Care Transition Protocols:Transdermal non-opioid delivery formats are penetrating post-discharge pain management, capturing value from surgical episode bundling that extends accountability beyond hospital walls.
- Enhanced Recovery After Surgery Alignment:ERAS protocol standardization across academic medical centers is creating formulary entry pathways for agents demonstrating opioid-sparing outcomes in prospective registry data.
- Japan's Aging Surgical Population:PMDA's accelerated review pathways for geriatric-appropriate analgesics are opening access for formulations with reduced cognitive side effect profiles in Asia-Pacific's fastest-aging surgical market.
Industry Challenges
- Biostatistical Talent Scarcity:Sponsors face recruitment constraints for statisticians experienced in analgesic trial design, particularly for patient-reported outcome validation and responder analyses required by FDA Division of Anesthesia.
- Legacy EHR Integration:Pain management decision support tools require costly interface development with entrenched hospital information systems, slowing algorithmic dosing protocol deployment.
- Reimbursement Evidence Generation:Payer contracts increasingly demand real-world opioid consumption data, forcing manufacturers to fund costly post-marketing studies without guaranteed coverage expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postoperative Pain Market |
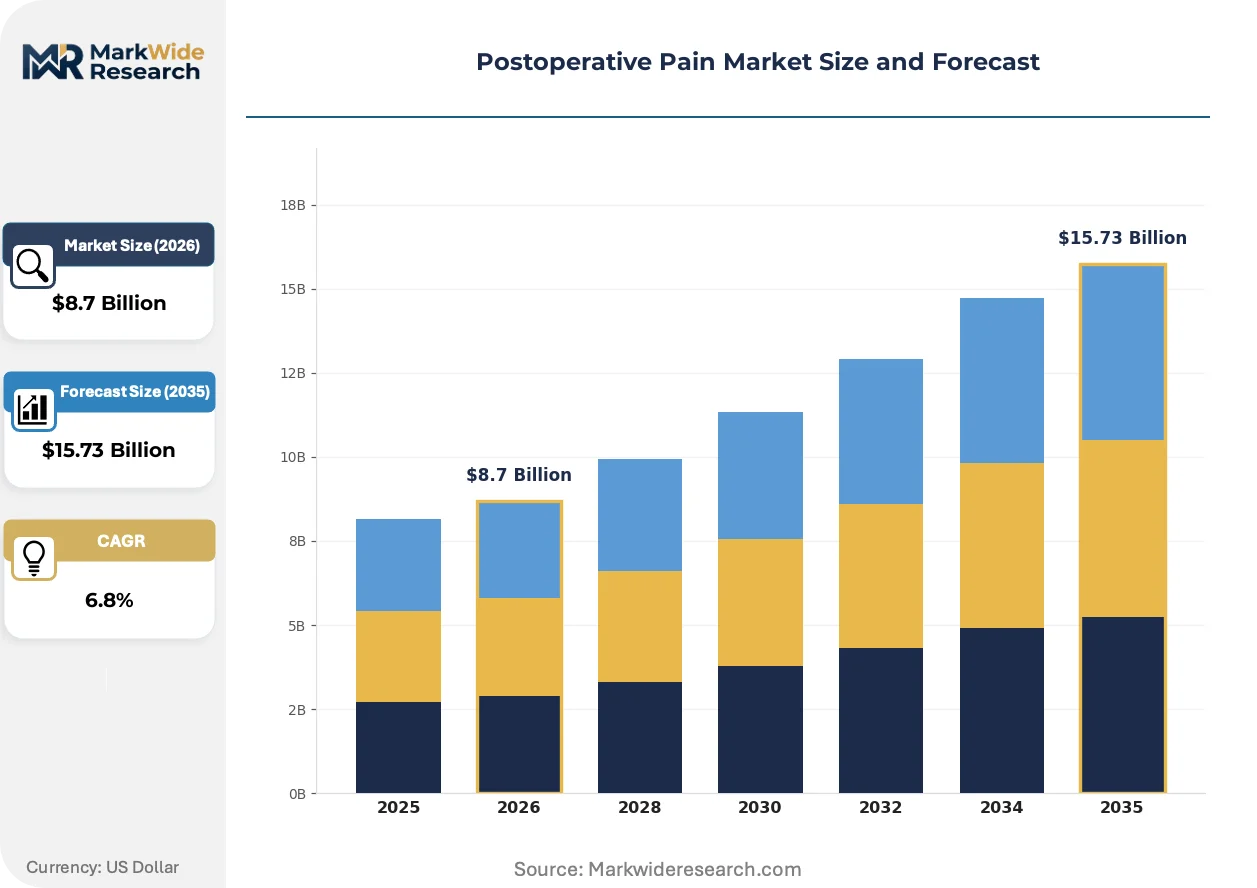
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Anesthetics, Opioids, Non-Opioids Delivery Mode: Oral, Intravenous, Transdermal, Subcutaneous End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Application: Post-Surgical, Trauma, Chronic Pain Management, Labor Pain |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Novartis AG, Merck & Co. Inc., AbbVie, Pacira BioSciences Inc., Heron Therapeutics Inc., Teva Pharmaceutical Industries Ltd., GSK plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postoperative Pain Market Strategic Shifts
Product development trajectories in postoperative analgesia center on duration extension and systemic exposure minimization, with formulation science and delivery mechanism innovation converging to enable opioid-sparing recovery pathways.
Extended-release local anesthetic depot technologies are displacing continuous peripheral nerve catheter systems in total joint replacement protocols. Orthopedic service lines at major United States academic centers have adopted single-injection liposomal bupivacaine as standard of care, eliminating pump management logistics and reducing catheter-related infection rates while maintaining comparable pain scores through 72 hours postoperatively.
REACH regulation amendments on microplastic-containing medicinal products are compelling European manufacturers to reformulate sustained-release matrices. The ECHA restriction proposal targets polymeric carrier systems common in long-acting injectables, forcing sponsors to validate biodegradable alternatives or face market withdrawal timelines, with Germany's hospital procurement consortia already signaling preference for compliant formulations in 2025 tenders.
Hospital pharmacy committees are consolidating analgesic purchasing through outcome-guaranteed contracts that tie payment to achieved pain control metrics. This behavioral shift concentrates volume with suppliers demonstrating measurable opioid reduction in their institutional data, disadvantaging generic plain local anesthetics without accompanying clinical services or protocol support, most visibly in California's integrated delivery network consolidations.
Postoperative Pain Market Segmentation
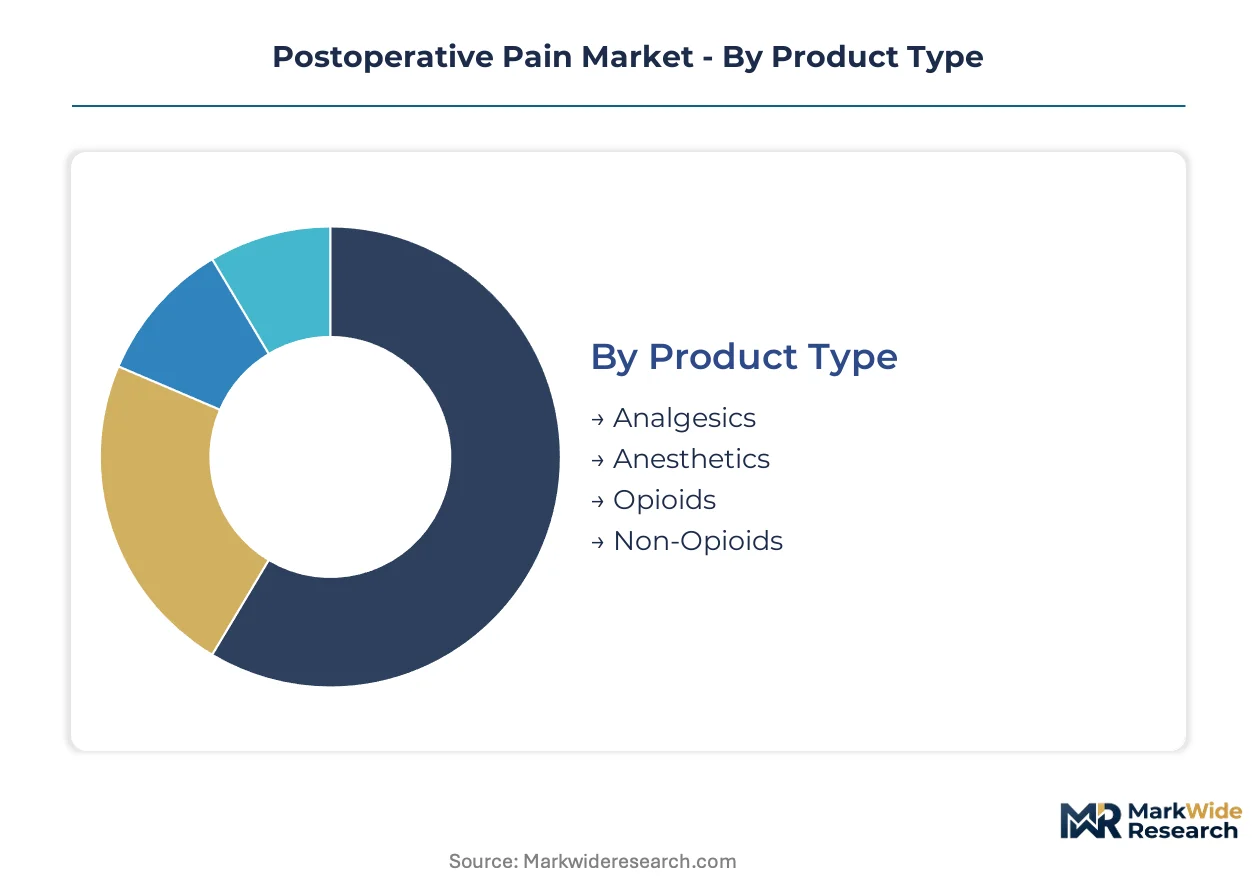
Postoperative pain therapeutics fragment across four distinct dimensions that determine reimbursement pathways, procurement contracts, and clinical adoption velocity. Each segmentation axis reveals divergent margin structures and competitive intensity that shape portfolio prioritization for formulation sponsors.
Product Type:
Margin pools concentrate in formulations that enable institutional compliance with opioid-reduction mandates while preserving surgical throughput.
- Non-Opioids:Multimodal analgesia protocols favor NSAIDs, acetaminophen combinations, and novel peripherally acting agents that avoid respiratory depression risk. United States academic medical centers now require non-opioid first-line regimens in orthopedic and colorectal service lines, driving formulary placement premiums.
- Anesthetics:Long-acting local anesthetic formulations, particularly liposomal depot technologies, command price multiples over plain bupivacaine through extended duration claims. Ambulatory surgery centers in Texas and Florida have adopted single-injection protocols as standard of care, displacing continuous catheter systems.
- Analgesics:Systemic pain modulators including gabapentinoids and NMDA antagonists serve adjuvant roles in multimodal stacks, though generic penetration limits pricing power.
- Opioids:REMS-mandated extended-release formulations face contracting restrictions and prescriber education burdens that compress utilization in perioperative settings.
Non-Opioids holds installed capacity. Anesthetics is rotating up the share rankings.
Delivery Mode:
Application setting dictates route selection, with perioperative control favoring parenteral administration and discharge transitions enabling patient-directed formats.
- Intravenous:Perioperative analgesia relies on IV push and patient-controlled analgesia systems for rapid titration during emergence and immediate recovery. Hospital pharmacy committees in California and New York prioritize IV formulations with compatible stability profiles for Y-site administration.
- Transdermal:Patch-based delivery penetrates post-discharge pain management where oral compliance fails or gastrointestinal absorption is compromised. Home health agencies in Medicare Advantage networks specify transdermal options for total joint replacement episodes.
- Oral:Immediate-release tablets and solutions dominate step-down protocols, though payer step therapy requirements delay access without prior IV documentation.
- Subcutaneous:Depot injections and implantable reservoir systems serve niche populations requiring sustained plasma levels without vascular access.
Intravenous anchors hospital procurement. Transdermal is climbing the fastest as bundled payments extend accountability beyond facility walls.
End User:
Channel concentration reflects site-of-care migration and reimbursement model evolution across the surgical episode.
- Hospitals:Inpatient and outpatient surgical departments capture the deepest analgesic margins through bundled payment structures that reward effective pain control and complication avoidance. Integrated delivery networks in Illinois and Pennsylvania consolidate purchasing through outcome-guaranteed contracts.
- Home Care:Discharge pain management services expand as same-day surgery mandates lengthen the post-acute accountability window. Skilled nursing facilities in Arizona and Nevada now stock long-acting local anesthetic kits for wound infiltration protocols.
- Clinics:Ambulatory surgical centers unwind historical hospital pharmacy dominance with direct contracting for procedure-specific analgesia packs.
- Rehabilitation Centers:Post-acute facilities emphasize functional recovery metrics that favor non-sedating pain regimens enabling early mobilization.
Hospitals retain volume concentration. Home Care is gaining share fastest as surgical episode bundling matures.
Application:
Clinical indication determines efficacy thresholds, duration requirements, and competitive substitution patterns.
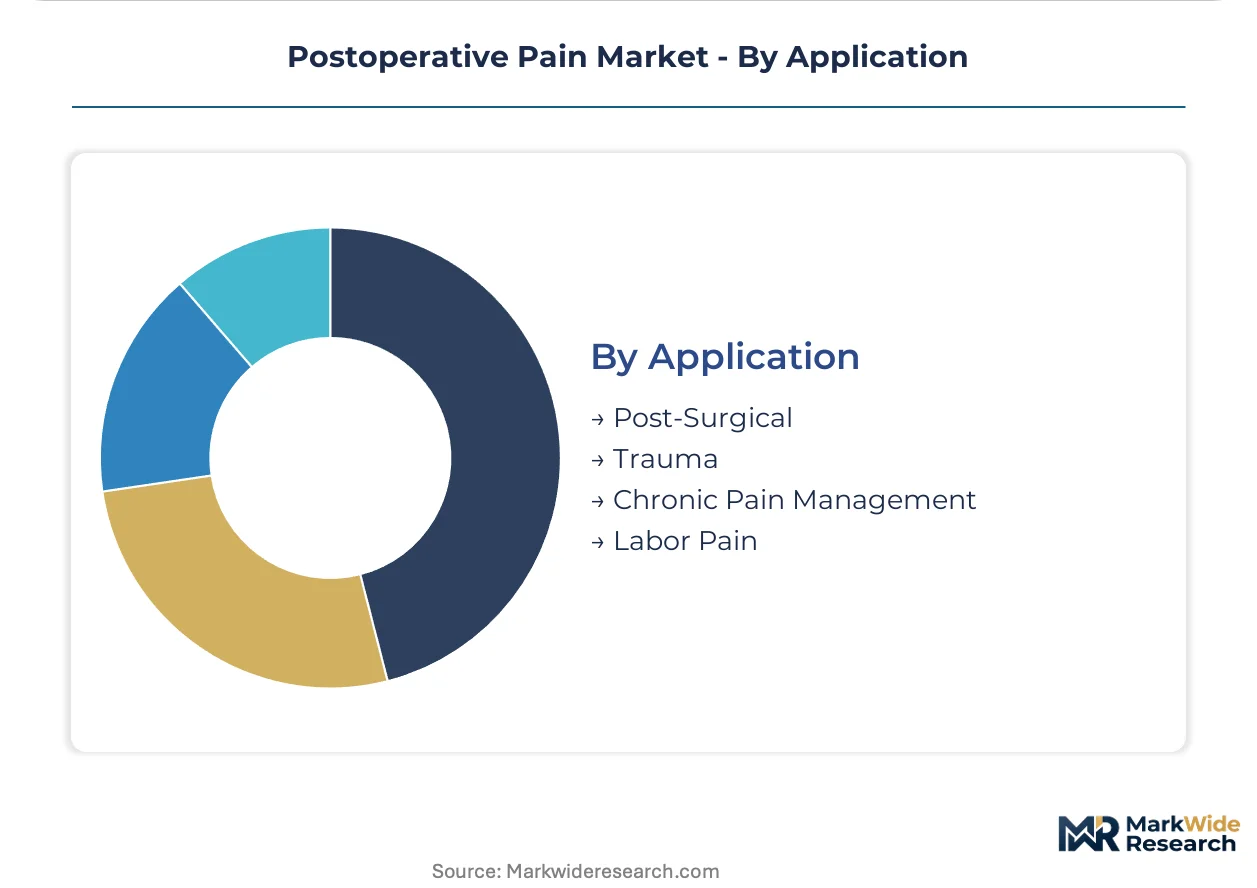
- Post-Surgical:Acute nociceptive and inflammatory pain states from tissue trauma demand rapid onset and predictable offset to enable early mobilization. Orthopedic and colorectal procedures in United States academic centers drive adoption of opioid-sparing multimodal protocols.
- Trauma:Emergency and urgent surgical interventions require flexible analgesic stacks accommodating unknown injury severity and polypharmacy risk.
- Chronic Pain Management:Postoperative pain that transitions to persistent states requires sustained-release formulations with abuse-deterrent properties.
- Labor Pain:Obstetric analgesia emphasizes fetal safety and maternal mobility, favoring neuraxial techniques over systemic administration.
Post-Surgical commands the largest addressable population. Chronic Pain Management represents the steepest expansion trajectory as recognition of surgical pain chronification improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pharmaceutical exports flow primarily to European Union member states and Japan, with liposomal bupivacaine formulations and multimodal analgesia protocols commanding premium positioning in these regulated markets.
United States
Same-day discharge mandates and bundled payment structures drive procurement of long-acting local anesthetics. FDA REMS requirements for extended-release opioids accelerate prescriber migration toward non-opioid alternatives. Texas and Florida ambulatory surgery centers have adopted single-injection protocols as standard of care.
Germany
Hospital procurement consortia signal preference for REACH-compliant formulations ahead of 2025 tender cycles. ECHA restrictions on microplastic-containing medicinal products force reformulation of sustained-release matrices. Bavarian medical centers lead adoption of ERAS-aligned analgesic protocols in orthopedic service lines.
Japan
PMDA accelerated review pathways target geriatric-appropriate analgesics for Asia-Pacific's fastest-aging surgical population. Cognitive side effect profiles determine formulary placement in metropolitan Tokyo and Osaka academic centers. Domestic manufacturers face import competition for novel delivery technologies.
India
Active pharmaceutical ingredient concentration in bupivacaine base supply chains exposes formulation sponsors to quota volatility. CDSCO manufacturing facility inspections create import delays for European and North American sponsors. Hyderabad and Ahmedabad clusters specialize in generic local anesthetic production.
United Kingdom
NHS England opioid reduction targets reshape perioperative prescribing patterns across integrated care systems. MHRA post-Brexit regulatory divergence creates parallel submission requirements for novel formulations. Greater London academic medical centers pilot outcome-guaranteed analgesic purchasing contracts.
Postoperative Pain Market Competitive Environment
Listed leaders compete with private specialists across formulation technology and channel access dimensions. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with manufacturing scale, mid-cap specialists in sustained-release delivery, and regional generic manufacturers competing on price. Archetypes include technology licensors, hospital contract aggregators, and API-forward integrators. Competitive moves concentrate on strategic partnerships for ERAS protocol alignment and capacity expansion for liposomal manufacturing.
Within the technology specialist tier, Pacira BioSciences Inc. and Heron Therapeutics Inc. exemplify sustained-release formulation leadership, while Pfizer Inc. anchors the scale-driven multinational segment with cross-channel manufacturing presence.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Novartis AG |
| Merck & Co. Inc. |
| AbbVie |
| Pacira BioSciences Inc. |
| Heron Therapeutics Inc. |
| Teva Pharmaceutical Industries Ltd. |
| GSK plc. |
| Others |
Value Chain & Pricing Dynamics
Outcome-guaranteed contracts between hospital systems and analgesic suppliers lock in multi-year supply access while anchoring price visibility to achieved opioid-reduction metrics, with California's integrated delivery networks and Texas ambulatory surgery centers already standardizing this procurement architecture.
Pricing Analysis
Prior-generation plain bupivacaine and ropivacaine formulations trade at commodity price points, while current-generation liposomal depot technologies command substantial premiums through duration-extension claims, and next-generation biodegradable matrices face pricing uncertainty pending ECHA compliance validation. Three-tier pricing structure across premium liposomal formulations, standard long-acting injectables, and economy plain local anesthetics reflects differentiation by clinical evidence depth and ERAS protocol alignment. Cost compression in the economy tier is intensifying because Indian and Chinese API manufacturers are expanding generic bupivacaine capacity. Ambulatory surgery centers exhibit the highest price sensitivity due to thin procedure margins, while academic medical centers prioritize clinical outcome guarantees over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate hospital pharmacy procurement for perioperative IV formulations, though strategic stockpiling of liposomal bupivacaine kits is emerging among high-volume orthopedic centers managing catheter-to-depot protocol transitions. Active pharmaceutical ingredient production concentrates in India, China, and the United States, with Hyderabad and Ahmedabad clusters supplying bupivacaine base to global formulation sponsors. Finished dosage manufacturing draws from polymeric carrier systems for sustained-release matrices, sterile injectable fill-finish capacity, and abuse-deterrent packaging components. Single-source vulnerability in liposomal manufacturing expertise constrains supply elasticity for advanced depot formulations. Distribution runs through hospital GPO contracts, specialty pharmaceutical wholesalers, and direct-to-ASC procedure pack assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Postoperative pain management is shifting toward platform-economics dynamics where ERAS protocol standardization creates interoperability requirements across analgesic agents, surgical workflows, and outcomes measurement systems.
For Market Incumbents: Consolidate formulary position through backward integration into liposomal manufacturing capacity and exclusive data-sharing partnerships with academic medical centers generating prospective opioid-sparing outcomes registries. Pfizer Inc. and Johnson & Johnson should deepen hospital contract aggregation to defend against mid-cap specialists capturing ambulatory surgery center volume through direct procedure-pack contracting.
For New Entrants and Emerging Players: Anchor in Japan's geriatric-appropriate analgesic segment where PMDA accelerated review pathways reward reduced cognitive side effect profiles, and penetrate Medicare Advantage home health networks with transdermal non-opioid formats for post-discharge pain episodes. Target skilled nursing facilities in Arizona and Nevada with wound infiltration protocol support services bundled with long-acting local anesthetic kits.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap formulation specialists possessing liposomal manufacturing expertise and ERAS-aligned clinical data assets, with viability extending through the next decade as bundled payment structures mature. The signal to watch is CMS reimbursement policy evolution for outpatient surgical episodes, which would accelerate or constrain transdermal and long-acting local anesthetic adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| ERAS Protocol Alignment | Hospital formulary placement now requires prospective registry data demonstrating opioid-sparing outcomes in orthopedic and colorectal service lines. |
| Liposomal Manufacturing Scale-Up | Capacity constraints in sterile depot formulation are limiting supply elasticity for single-injection protocols displacing continuous catheter systems. |
| REACH-Compliant Reformulation | ECHA restrictions on microplastic-containing medicinal products are forcing validation of biodegradable carrier alternatives for European market access. |
| Home Care Transition Partnerships | Medicare Advantage networks are specifying transdermal options for total joint replacement episodes extending accountability beyond facility walls. |
| Biostatistical Talent Acquisition | Sponsors face recruitment constraints for statisticians experienced in analgesic trial design and patient-reported outcome validation required by FDA. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA REMS documentation, EMA MDR submission databases, hospital procurement records, and clinical trial registries, with input from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation validate market size estimates across the analysis window.
Segmentation dimensions modeled include product type, delivery mode, end user channel, and application setting, with CAGRs derived from procedure volume projections, formulary adoption curves, and pricing trajectory assumptions. Forecast inputs incorporate ambulatory surgery expansion rates, REMS compliance timelines, and bundled payment penetration by integrated delivery network.
Material uncertainties — regulatory restriction amendments, API supply disruptions, and payer policy reversals — sit outside the modeled envelope. Revision becomes warranted when FDA opioid REMS requirements or CMS reimbursement thresholds cross thresholds altering prescriber behavior or procurement urgency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Opioid Withdrawal Management Market
Pain Management
Migraine Management Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Pain Patches Market
Pain Management
Ketorolac Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Heat Therapy Market
Pain Management
Painkillers Market
Pain Management
OTC Painkiller Market
Pain Management
Medical Morphine Market
Pain Management
Bone Pain Treatment Market
Pain Management
Muscle Tension Dysphonia Treatment Market