
 Barlow's Syndrome Market | 2026-2036
Barlow's Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Barlow's Syndrome Market Outlook
EU MDR is recalibrating the cost-of-entry calculus for transcatheter mitral valve repair systems in Europe. Edwards Lifesciences leverages its European notified-body relationships to sustain first-mover certification advantages. Medtronic anchors its competitive position through in-house manufacturing of delivery catheters. Abbott Laboratories differentiates via specialized imaging-integrated procedural platforms.
Barlow's Syndrome, or mitral valve prolapse with myxomatous degeneration, involves excessive leaflet tissue and chordal elongation that permits systolic billowing into the left atrium; transesophageal echocardiography with three-dimensional reconstruction remains the gold standard for pre-procedural annular sizing. Surgical Interventions capture the dominant margin pool due to high device-implant reimbursement and procedural complexity premiums. Monitoring Devices are gaining fastest traction as remote cardiac telemetry platforms expand into post-discharge surveillance protocols.
FDA pre-market approval pathways and EU MDR conformity assessment procedures shape product development timelines and clinical trial investment requirements for valve repair manufacturers. ISO 13485 quality management standards govern supplier qualification across the cardiovascular device supply chain. Health Technology Assessment bodies in France and Germany determine market access velocity for novel repair technologies. Stakeholders must weigh regulatory capital intensity against the contracting window for premium pricing in commoditizing catheter segments.
Market Dynamics
EU MDR conformity assessment timelines are compressing product development cycles for transcatheter mitral valve repair manufacturers, forcing earlier clinical evidence generation and stricter post-market surveillance commitments across European notified-body jurisdictions.
Growth Catalysts
- Hospital-based cardiac care units:Specialized valve centers in Germany coordinate referral networks across Bavaria and Baden-Württemberg, concentrating procedural expertise and device utilization.
- Remote cardiac telemetry expansion:Post-discharge surveillance protocols are extending monitoring device deployment into ambulatory settings, creating new revenue streams beyond acute intervention.
- Three-dimensional transesophageal echocardiography:Gold-standard annular sizing capabilities are improving patient selection accuracy and reducing procedural complications.
Market Restraints
- Pre-market clinical evidence requirements:EU MDR tightening demands extended follow-up data, elongating certification timelines and inflating development costs.
- Chordal tissue supply concentration:Biological scaffold sourcing depends on a limited network of accredited tissue banks, creating procurement vulnerability.
- Surgical intervention substitution:Conventional sternotomy approaches retain preference in complex multi-valve cases, limiting transcatheter penetration in high-acuity segments.
Strategic Opportunities
- Specialized imaging-integrated platforms:Real-time procedural guidance systems are opening differentiation pathways beyond standalone device competition.
- Health Technology Assessment alignment:Early engagement with French HAS and German IQWiG bodies accelerates novel repair technology reimbursement decisions.
- In-house delivery catheter manufacturing:Captive production of precision delivery systems insulates margin pressure from component supplier concentration.
Industry Challenges
- Interventional cardiologist training pipelines:Complex transcatheter mitral repair demands extended proctoring programs that outpace fellowship graduation rates.
- ISO 13485 supplier qualification:Quality management audits across cardiovascular device supply chains impose documentation burdens that delay component onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barlow's Syndrome Market |
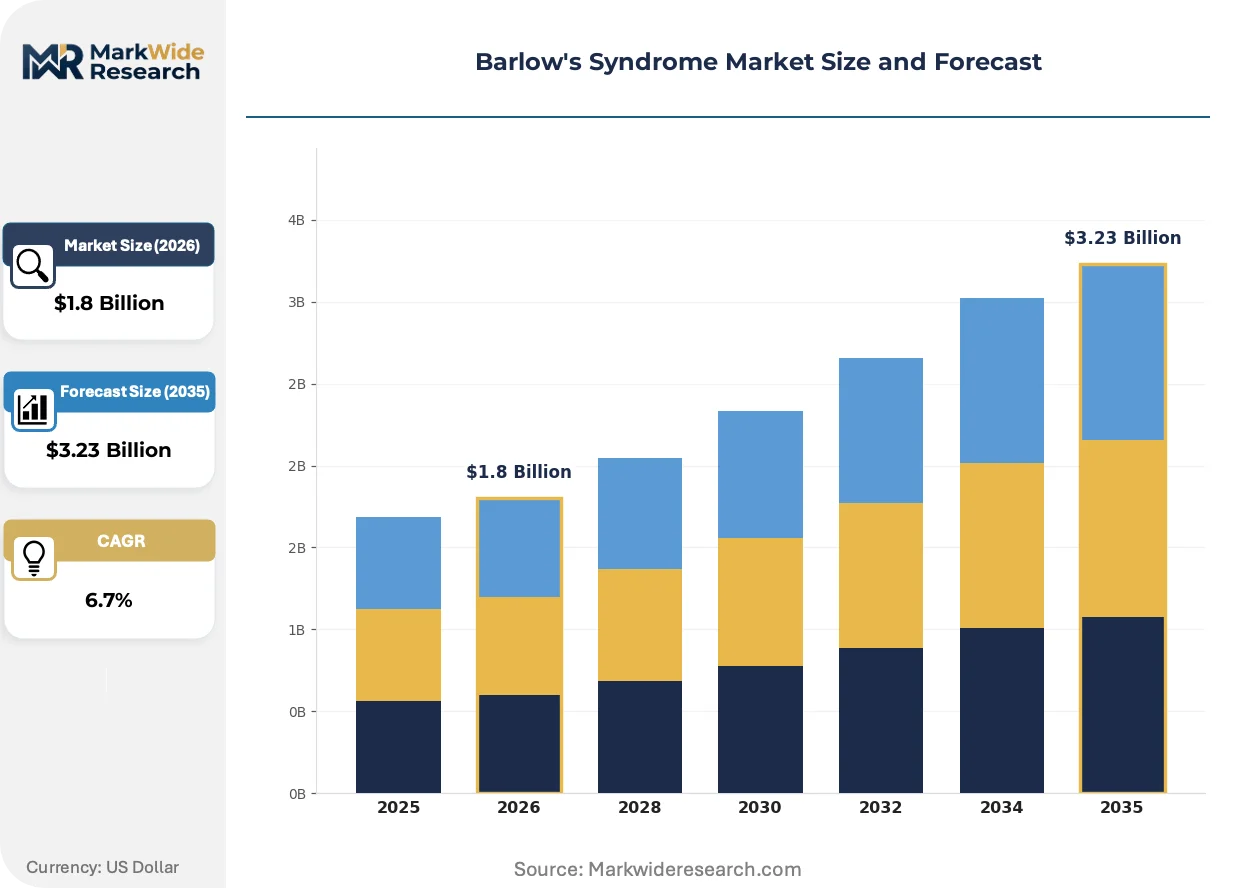
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Interventions, Diagnostic Tools, Monitoring Devices Treatment Approach: Conservative Management, Surgical Repair, Regular Monitoring, Symptomatic Treatment End User: Cardiologists, General Practitioners, Patients, Hospitals Technology: Non-Invasive Imaging, Telemedicine, Wearable Devices, Genetic Testing |
| Companies Covered | Medtronic, Edwards Lifesciences, Abbott Laboratories, Boston Scientific, LivaNova, Pfizer, Novartis, JenaValve Technology, Biotronik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barlow's Syndrome Market Strategic Shifts
Transcatheter repair platforms are fragmenting procedural control away from centralized surgical suites, redistributing competence requirements across hybrid catheterization laboratories and altering capital allocation patterns in cardiac service line planning.
Artificial chordae implantation systems are decentralizing mitral valve repair from open-heart surgical theaters into percutaneous settings. Interventional cardiologists at tertiary valve centers adopt these platforms faster than community hospitals, compressing the traditional cardiac surgery referral pathway and reallocating procedure economics toward catheter-based specialists.
EU MDR Article 117 implantable device requirements are mandating clinical investigation designs that parallel pharmaceutical trial rigor. Manufacturers face expanded notified-body scrutiny of biocompatibility data and post-market clinical follow-up protocols, disproportionately affecting small-cap entrants lacking established quality management infrastructure.
Referral pattern consolidation around specialized valve centers is reshaping procurement authority. Hospital cardiac service lines now centralize device selection decisions through valve heart team committees, displacing individual surgeon preference and concentrating purchasing leverage among high-volume German and French institutions.
Barlow's Syndrome Market Segmentation
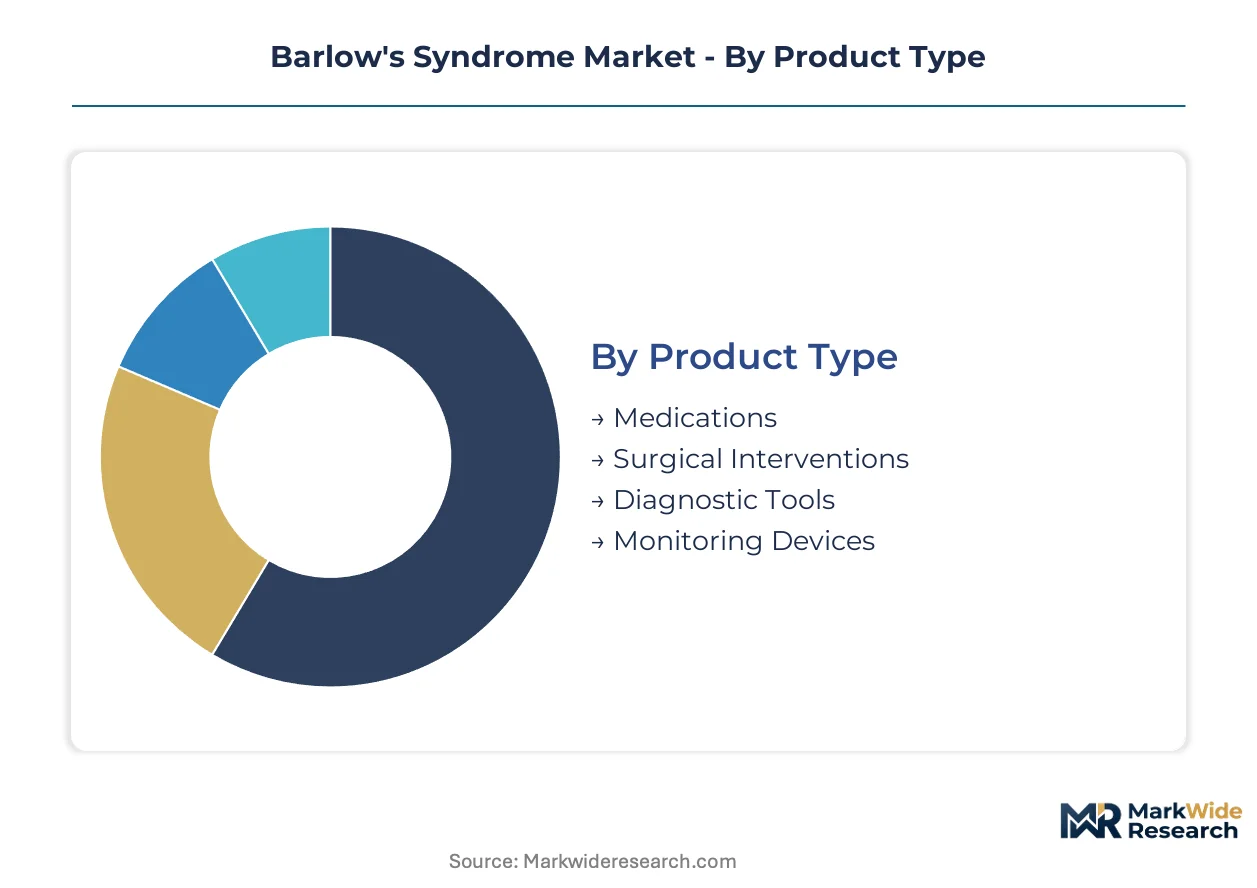
Barlow's Syndrome management spans acute intervention and chronic surveillance, with segmentation reflecting divergent margin profiles across invasive procedures and digital monitoring platforms. Product and technology categories reveal a market bifurcated between high-value surgical interventions and volume-driven diagnostic tools.
Product Type:
Surgical Interventions command premium reimbursement tiers while Monitoring Devices scale through ambulatory deployment economics.
- Surgical Interventions:Transcatheter mitral valve repair systems and artificial chordae implantation platforms address myxomatous degeneration through percutaneous leaflet stabilization. German valve centers in Bavaria and Baden-Württemberg concentrate procedural volume, driven by EU MDR certification timelines that favor established manufacturers with notified-body relationships.
- Monitoring Devices:Remote cardiac telemetry platforms extend post-discharge surveillance into ambulatory settings through wearable ECG patches and implantable loop recorders. Hospital-based cardiac care units in Germany deploy these systems fastest, propelled by referral network consolidation around specialized valve centers.
- Medications:Beta-blockers and anticoagulants manage arrhythmia and thromboembolic risk in asymptomatic patients.
- Diagnostic Tools:Three-dimensional transesophageal echocardiography systems enable pre-procedural annular sizing for repair candidacy assessment.
Today's leader: Surgical Interventions. Tomorrow's challenger: Monitoring Devices.
Treatment Approach:
Conservative protocols dominate patient volume while Surgical Repair captures intervention economics.
- Conservative Management:Asymptomatic patients with mild prolapse undergo periodic echocardiographic surveillance without immediate intervention. Cardiologists in German specialized valve centers coordinate these protocols through structured follow-up regimens.
- Surgical Repair:Leaflet resection, chordal replacement, and annuloplasty address severe regurgitation in symptomatic cases. EU MDR implantable device requirements mandate clinical investigation designs that parallel pharmaceutical trial rigor for repair technologies.
- Regular Monitoring:Structured surveillance tracks leaflet thickening and chordal elongation progression.
- Symptomatic Treatment:Diuretics and antiarrhythmics address palpitations and dyspnea pending definitive intervention.
Volume concentrates in Conservative Management. Value accumulates in Surgical Repair.
End User:
Hospital cardiac service lines centralize procurement authority while Cardiologists drive clinical decision-making.
- Hospitals:Specialized valve heart team committees consolidate device selection decisions, displacing individual surgeon preference. French and German high-volume institutions concentrate purchasing leverage through centralized procurement.
- Cardiologists:Interventional specialists at tertiary valve centers adopt transcatheter platforms faster than community practitioners, compressing traditional cardiac surgery referral pathways.
- General Practitioners:Primary care gatekeepers initiate referral pathways to specialized valve centers.
- Patients:Direct-to-consumer genetic testing and wearable monitoring create emerging self-directed management channels.
Purchasing power: Hospitals. Clinical influence: Cardiologists.
Technology:
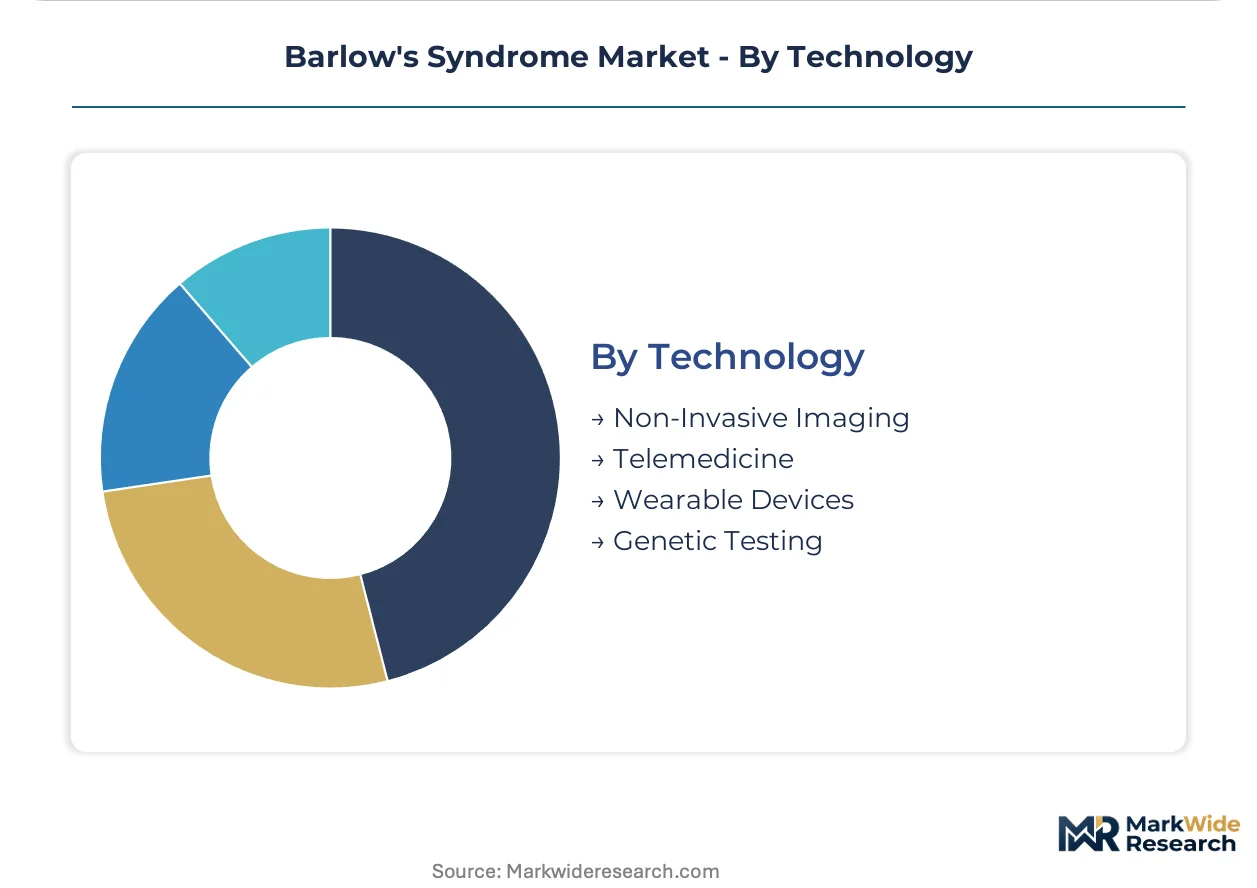
Non-Invasive Imaging anchors diagnostic workflows while Wearable Devices expand surveillance reach.
- Non-Invasive Imaging:Three-dimensional transesophageal echocardiography with reconstruction capabilities remains the gold standard for annular sizing and leaflet morphology assessment. German specialized valve centers deploy these systems for pre-procedural planning.
- Wearable Devices:ECG-enabled smartwatches and patch monitors detect arrhythmia and asymptomatic episodes in post-discharge protocols. Remote cardiac telemetry platforms are gaining traction fastest in ambulatory surveillance applications.
- Telemedicine:Virtual consultation platforms extend specialist access for rural and underserved populations.
- Genetic Testing:Fibrillin and TGF-beta pathway analysis identifies familial clustering and guides screening intensity.
Established standard: Non-Invasive Imaging. Steepest expansion trajectory: Wearable Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized interventional cardiologists cluster in German valve centers, concentrating procedural expertise and device procurement authority for Barlow's Syndrome management across European and North American markets.
Germany
Valve heart teams in Bavaria and Baden-Württemberg coordinate referral networks that concentrate transcatheter mitral repair volume. EU MDR notified-body relationships favor established manufacturers with Berlin and Munich-based certification infrastructure. IQWiG health technology assessments in Cologne determine reimbursement velocity for novel repair platforms.
United States
FDA pre-market approval pathways shape clinical trial investment requirements for artificial chordae implantation systems. Tertiary valve centers in Cleveland, New York, and Houston deploy three-dimensional transesophageal echocardiography for annular sizing. Remote cardiac telemetry platforms expand fastest through post-discharge surveillance protocols in Medicare Advantage networks.
France
HAS health technology assessment procedures govern market access for transcatheter repair devices in Paris and Lyon specialized centers. Myxomatous degeneration cases concentrate in Île-de-France academic hospitals with established mitral valve surgery programs. ANSM post-market surveillance requirements align with EU MDR clinical follow-up mandates for implantable devices.
Switzerland
Zurich and Geneva valve centers leverage Swissmedic expedited review pathways for breakthrough repair technologies. Precision manufacturing clusters in Basel supply catheter components to European device manufacturers. Bilingual regulatory documentation requirements streamline cross-border market access into neighboring EU jurisdictions.
United Kingdom
NICE technology appraisals determine NHS commissioning for transcatheter mitral valve repair in London and Manchester heart centers. Post-Brexit UKCA marking requirements create parallel conformity assessment obligations alongside retained EU MDR compliance. Regional cardiac networks in the Midlands consolidate procedural volume through hub-and-spoke referral models.
Barlow's Syndrome Market Competitive Environment
The competitive structure tilts toward diversified cardiovascular conglomerates with established notified-body relationships and captive catheter manufacturing infrastructure. Strategic archetypes separate into integrated device-delivery manufacturers, imaging-platform integrators, and biological-scaffold specialists. Dominant competitive moves center on EU MDR certification velocity and in-house production of precision delivery systems.
Among diversified cardiovascular device conglomerates, Medtronic, Edwards Lifesciences, and Abbott Laboratories exemplify the integrated-manufacturer archetype. Medtronic occupies a position anchored in catheter production infrastructure. Edwards Lifesciences sits within the tier leveraging European regulatory relationships. Abbott Laboratories represents the imaging-integrated platform specialist segment. These three entities collectively demonstrate how notified-body access and manufacturing control define competitive positioning under tightened EU MDR timelines.
| Leading Market Players |
|---|
| Medtronic |
| Edwards Lifesciences |
| Abbott Laboratories |
| Boston Scientific |
| LivaNova |
| Pfizer |
| Novartis |
| JenaValve Technology |
| Biotronik |
| Others |
Value Chain & Pricing Dynamics
Nitinol alloy spot pricing on the London Metal Exchange cascades through cardiovascular device supply chains, compressing margins on transcatheter delivery catheters while amplifying cost advantages for manufacturers with captive wire-drawing facilities in Germany and Switzerland.
Pricing Analysis
Bundled procedural packages dominate German valve center contracting, with device-plus-imaging-plus-discharge-monitoring combinations commanding premium reimbursement tiers against unbundled component procurement in smaller French and UK institutions. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-certified artificial chordae systems from transitional CE-marked inventory and emerging market surplus. Pricing pressure stems from IQWiG reference pricing benchmarks that cap device reimbursement in German ambulatory settings. Community hospitals exhibit acute price sensitivity, while Bavarian tertiary centers prioritize procedural outcome guarantees over unit cost.
Supply Chain Analysis
ISO 13485 supplier qualification gating concentrates biological scaffold sourcing on a limited network of accredited tissue banks in Germany, Switzerland, and the United States. Nitinol wire, biological patch materials, and precision catheter extrusions draw from specialized metallurgical processors in Basel, polymer specialists in Minnesota, and bovine pericardium processors in southern Germany. Single-source vulnerability pervades chordal tissue supply, where ANSM and Swissmedic accreditation timelines extend eighteen to thirty-six months. Distribution runs through hospital cardiac service line committees that centralize procurement authority away from individual surgeon preference.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German IQWiG reimbursement velocity runs three to six months faster than French HAS timelines, creating geographic-arbitrage opportunities for manufacturers prioritizing Berlin and Munich certification infrastructure over Paris market entry.
For Market Incumbents: Acquire in-house catheter extrusion capacity to insulate margin pressure from nitinol wire price volatility. Defensive consolidation around biological tissue bank accreditation accelerates as EU MDR post-market surveillance commitments elongate small-cap competitor development cycles. Prioritize Bavarian and Baden-Württemberg valve center exclusivity agreements before referral networks crystallize around established device platforms. For New Entrants and Emerging Players: Telemedicine-enabled remote cardiac telemetry platforms offer the most penetrable white-space entry point, bypassing capital-intensive catheter manufacturing barriers. Target post-discharge surveillance protocols in UK NHS regional cardiac networks where hub-and-spoke models concentrate monitoring device procurement authority. Deploy direct-to-clinician digital education campaigns that compress traditional distributor markup structures. For Investors and Strategic Acquirers: Asymmetric upside sits with imaging-integrated procedural platform specialists possessing FDA breakthrough device designation and EU MDR notified-body pre-submission feedback. Five-to-ten-year viability hinges on reimbursement pathway clarity across German, French, and US Medicare frameworks. Watch for IQWiG positive benefit assessment signals as inflection indicators for transcatheter mitral repair technology category expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified-Body Pre-Submission | Early engagement with Berlin and Munich certification infrastructure compresses approval timelines against competitors. |
| Hospital System Partnership | Exclusive supply agreements with Bavarian valve centers lock in procedural volume before referral networks mature. |
| Biological Tissue Bank Accreditation | Swissmedic and ANSM accreditation creates procurement moats that small-cap entrants cannot replicate. |
| Software Companion Development | Three-dimensional transesophageal echocardiography integration differentiates platforms beyond standalone device competition. |
| Reimbursement Strategy | IQWiG and HAS early alignment accelerates market access velocity for novel artificial chordae implantation systems. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with interventional cardiologists, hospital purchasing committee chairs, biomedical engineers at German valve centers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified-body public summaries, CMS Medicare reimbursement databases, and hospital procurement registry data. Bottom-up device shipment modeling and top-down cardiac service line expenditure analysis triangulated market sizing across surgical intervention and monitoring device segments.
Segment-weighting approaches distributed value projections across product type, treatment approach, end user, and technology dimensions, with surgical interventions and monitoring devices receiving differential growth assumptions. CAGRs derived from procedure volume elasticity to reimbursement rate changes, EU MDR certification timeline compression effects, and telemetry platform ambulatory deployment ramp rates. Nitinol commodity price trajectories and IQWiG assessment outcome probabilities fed scenario-weighted forecast distributions.
The model assumes a particular technology adoption path; alternative pathways for artificial chordae implantation versus conventional surgical repair would alter the outlook. Forecasts reflect assumptions about EU MDR implementation consistency, German valve center referral network stability, and remote cardiac telemetry reimbursement expansion. A model refresh is warranted upon material change in IQWiG benefit assessment methodology or FDA transcatheter mitral valve repair guidance revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Germ Cell Tumors Market
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Seasonal Allergy Market