
 Painkillers Market | 2026-2036
Painkillers Market Size, Share, and Industry Trends Forecast 2026-2036
Painkillers Market Analytics
Multi-source API procurement is repositioning how generic painkiller manufacturers secure active pharmaceutical ingredients. Pfizer Inc. leverages captive fermentation capacity for ibuprofen intermediates, while Teva Pharmaceuticals sustains cost leadership through diversified supplier networks across Eastern European chemical parks. Johnson & Johnson anchors premium positioning in acetaminophen combinations through controlled-release polymer technology.
Painkillers comprise pharmacologically active compounds that modulate nociceptive signaling through cyclooxygenase inhibition, opioid receptor agonism, or serotonin-norepinephrine reuptake blockade, formulated to achieve defined pharmacokinetic profiles including Cmax, Tmax, and half-life specifications for predictable analgesic effect. Their primary commercial purpose centers on interrupting pain transmission or perception across acute postsurgical, chronic musculoskeletal, and neuropathic indications. The NSAIDs segment dominates volume throughput in retail pharmacy channels due to over-the-counter accessibility and gastrointestinal risk profiles that drive proton-pump inhibitor co-prescription revenue pools. Opioids face structural contraction in chronic non-cancer pain as REMS compliance costs escalate, while transdermal patch formulations within the broader formulation taxonomy capture margin expansion through improved patient adherence and reduced breakthrough-dose requirements.
The FDA's REMS program for extended-release and long-acting opioids mandates prescriber certification and patient counseling protocols that constrain market access for new entrants. EMA's pharmacovigilance requirements under the EU Good Pharmacovigilance Practices framework impose post-authorization safety study obligations that shape European product portfolios. Stakeholders must monitor how the Drug Enforcement Administration's aggregate production quota adjustments for Schedule II substances redistribute manufacturing capacity between immediate-release and abuse-deterrent formulation investments.
Market Dynamics
The FDA's REMS program for extended-release opioids has triggered a wholesale restructuring of prescribing protocols, forcing manufacturers to redirect R&D investment toward abuse-deterrent formulations while hospital procurement shifts toward multimodal analgesia protocols.
Growth Catalysts
- Postoperative multimodal protocols:Surgical volume recovery across US hospital systems is expanding demand for non-opioid adjuvants including COX-2 inhibitors and gabapentinoids used in combination regimens.
- EMA pharmacovigilance frameworks:Mandatory post-authorization safety studies under EU Good Pharmacovigilance Practices are accelerating the withdrawal of legacy NSAIDs with unfavorable cardiovascular profiles, opening market space for newer entrants.
- Transdermal delivery advances:Polymer matrix technologies enabling sustained-release fentanyl and buprenorphine patches are capturing adherence advantages in chronic pain management through reduced breakthrough dosing requirements.
Market Restraints
- API supply concentration:Ibuprofen and naproxen intermediate production clusters in Indian and Chinese chemical parks expose generic manufacturers to input volatility from environmental compliance shutdowns.
- REMS compliance burden:The FDA's prescriber certification and patient counseling mandates for extended-release opioids impose fixed cost structures that disadvantage smaller entrants lacking dedicated regulatory affairs infrastructure.
- Opioid litigation overhang:State attorney general settlements and ongoing civil liability exposure are compressing risk-adjusted returns on Schedule II substance manufacturing capacity investments.
Strategic Opportunities
- Japan's aging demographic:METI-supported chronic pain management initiatives are expanding reimbursement for extended-release formulations in a market historically constrained by opioid stigma and conservative prescribing.
- Digital therapeutics convergence:Prescription digital therapeutics for pain management are creating combination product pathways that pair pharmacologic intervention with cognitive behavioral therapy protocols.
- Specialty pharmacy channels:Limited distribution networks for REMS-compliant products are enabling direct-to-patient adherence monitoring services that capture lifetime value from long-therapy chronic pain patients.
Industry Challenges
- Abuse-deterrent formulation expertise:Polymer chemistry and intravenous extraction resistance testing capabilities remain concentrated among a narrow set of contract development and manufacturing organizations, creating bottlenecks for pipeline progression.
- DEA quota allocation uncertainty:Annual aggregate production quota adjustments for oxycodone and hydrocodone immediate-release formulations force capacity planning against unpredictable federal scheduling decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Painkillers Market |
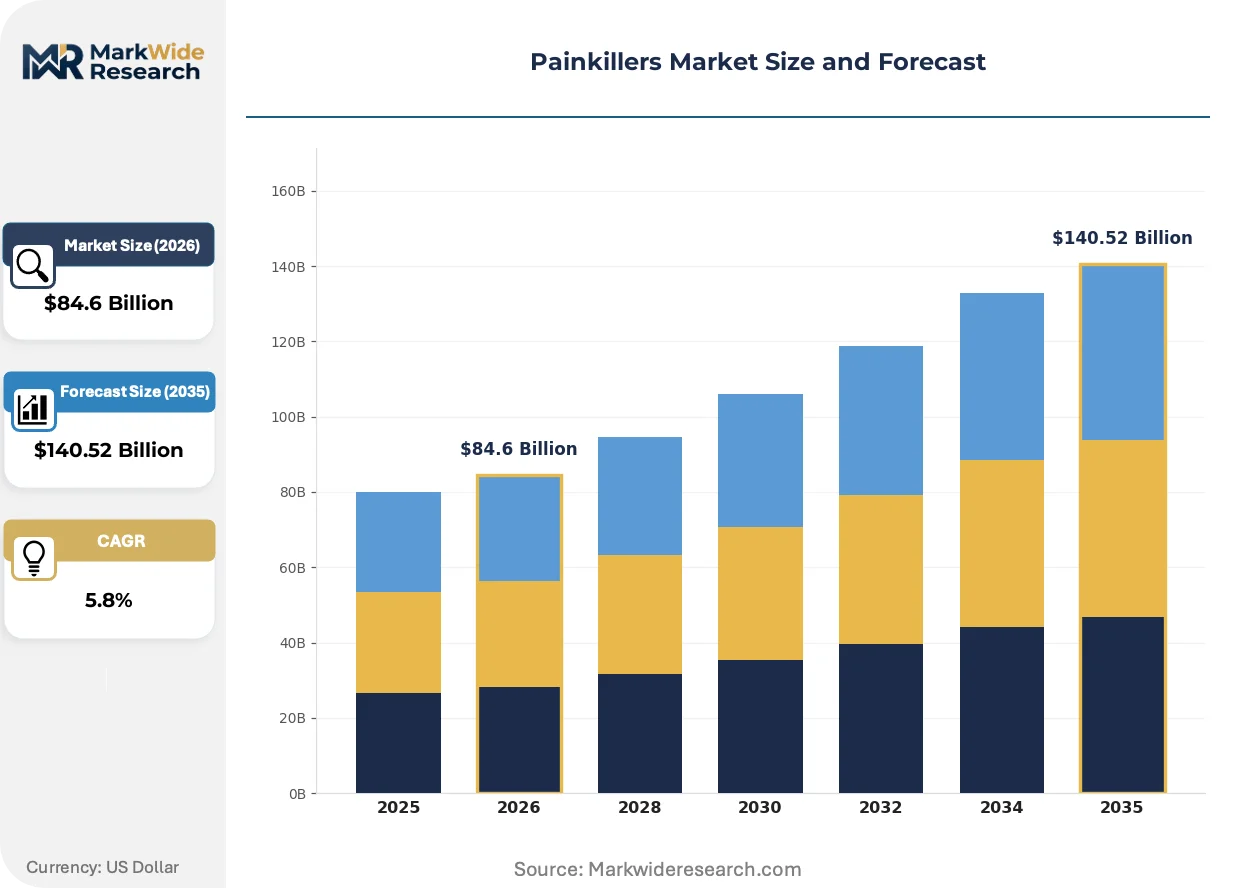
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $140.52 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, Acetaminophen, Opioids, Antidepressants Therapy Area: Chronic Pain, Acute Pain, Cancer Pain, Postoperative Pain End User: Hospitals, Clinics, Pharmacies, Homecare Formulation: Tablets, Liquids, Injections, Patches |
| Companies Covered | Pfizer Inc., Abbott Laboratories, Johnson & Johnson, Novartis AG, GSK plc, Teva Pharmaceuticals, Endo Pharmaceuticals Inc., Bausch Health Companies Inc., F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Painkillers Market Evolving Landscape
Formulation science and digital adherence tools are converging to redefine how analgesic efficacy is measured and reimbursed, shifting value capture from molecule exclusivity toward integrated therapy management platforms.
Abuse-deterrent polymer matrices incorporating physical barriers and aversive agents are rewriting competitive positioning in the opioid segment. Hospital formularies in the United States are adopting these formulations as standard of care for postoperative discharge prescribing. The technology is compressing market access for legacy immediate-release tablets lacking comparable extraction resistance profiles.
REACH authorization requirements for chemical substances are forcing European API manufacturers to requalify excipient suppliers and document full substance lifecycle environmental impact. The industrial consequence is accelerated consolidation of formulation partnerships around compliant chemical parks in Germany and the Netherlands. Extended-release patch manufacturers with established REACH dossiers are capturing preferential procurement status from risk-averse European hospital buying groups.
Hospital value-based purchasing programs are unbundling analgesic costs from procedural bundles and reimbursing separately for multimodal protocols demonstrating reduced opioid consumption. Surgical service lines are replacing traditional pharmacy-driven dispensing with anesthesia-led acute pain service models. This shift is most visible in US health systems participating in CMS bundled payment demonstrations for orthopedic and colorectal procedures.
Painkillers Market Segmentation
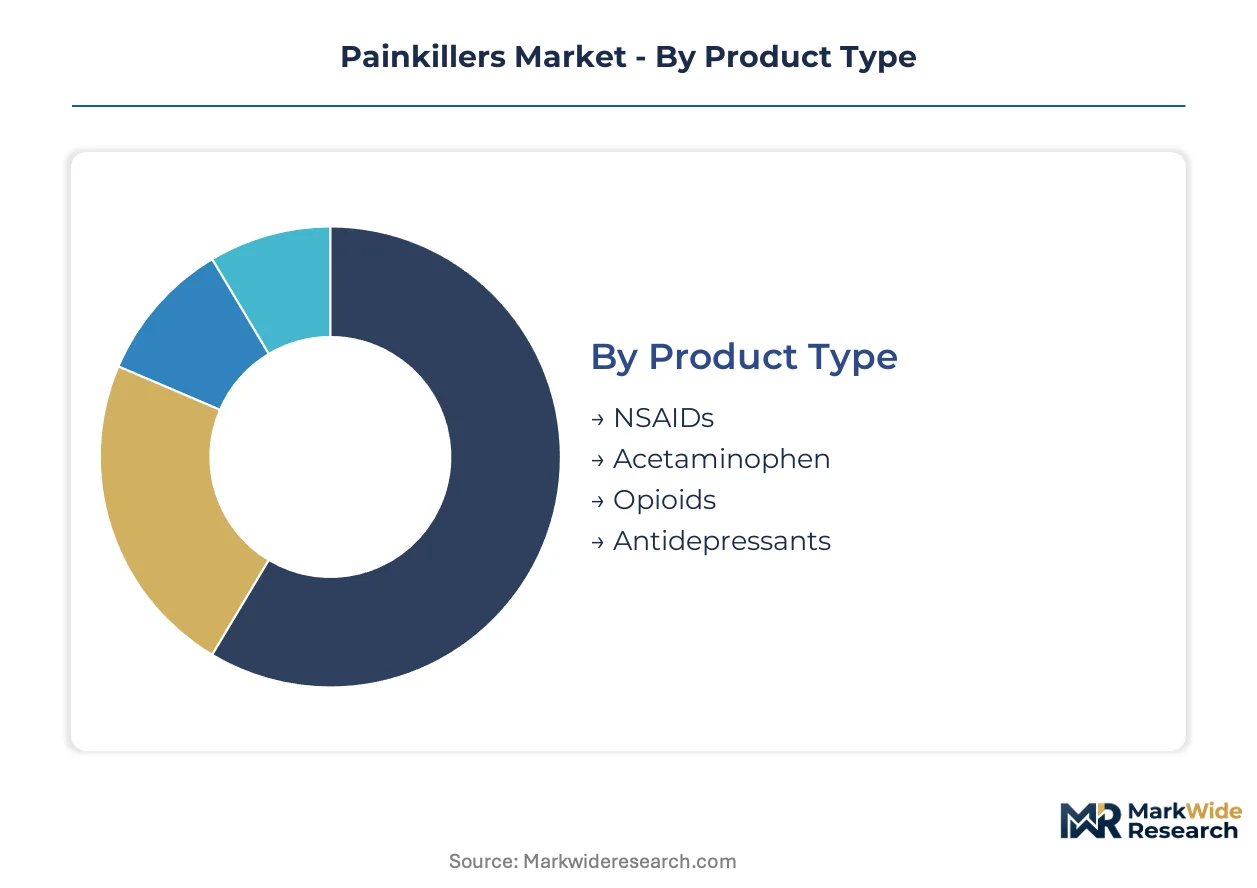
Painkiller segmentation reveals divergent margin profiles across therapeutic intensity and delivery sophistication. Product type and therapy area classifications determine reimbursement pathways, while formulation and end-user channels shape distribution economics and compliance burdens.
Product Type:
Standardization dominates the high-volume NSAID and acetaminophen segments, whereas opioid and antidepressant categories demand customized manufacturing protocols and REMS-aligned distribution infrastructure.
- NSAIDs:Cyclooxygenase-inhibiting compounds including ibuprofen, naproxen, and diclofenac formulated for oral, topical, and parenteral delivery. Demand concentrates in US retail pharmacy channels where over-the-counter accessibility drives volume throughput, though proton-pump inhibitor co-prescription requirements erode net margins for chronic users.
- Opioids:Mu-receptor agonists spanning immediate-release and extended-release morphine, oxycodone, and hydrocodone formulations with escalating abuse-deterrent polymer barriers. Hospital procurement in the United States is shifting toward multimodal protocols that displace pure opioid regimens, compressing addressable volume despite premium per-dose pricing.
- Acetaminophen:Centrally acting analgesic with ceiling-dose hepatotoxicity constraints driving combination formulations with codeine or tramadol. Fixed-dose combinations dominate prescription volume in European markets with restrictive opioid prescribing cultures.
- Antidepressants:Serotonin-norepinephrine reuptake inhibitors and tricyclic compounds repurposed for neuropathic pain indications. Duloxetine and amitriptyline capture off-label prescribing in US pain management clinics seeking non-scheduled alternatives.
Leading the category by volume: NSAIDs. Expanding most quickly: Antidepressants for neuropathic indications.
Therapy Area:
Application intensity varies from episodic acute intervention to decades-long chronic maintenance, with cancer pain occupying the highest reimbursement tier across all geographies.
- Chronic Pain:Persistent musculoskeletal, neuropathic, and inflammatory conditions requiring sustained pharmacologic management. US Medicare Part D formularies favor extended-release formulations with demonstrated adherence metrics, while European gatekeeping systems restrict long-term opioid exposure.
- Acute Pain:Trauma, fracture, and emergency department presentations demanding rapid-onset analgesia with short treatment duration. Immediate-release tablets and parenteral formulations capture this segment, with generic price compression most severe in hospital tender processes.
- Cancer Pain:Oncologic nociception spanning somatic, visceral, and neuropathic mechanisms with escalating WHO analgesic ladder protocols. Transdermal fentanyl and buprenorphine patches gain preference in US hospice and palliative care settings for predictable plasma concentration profiles.
- Postoperative Pain:Surgical site and procedure-specific analgesia protocols increasingly incorporating regional anesthesia and non-opioid adjuvants. US health systems participating in CMS bundled payment demonstrations are unbundling analgesic costs from procedural reimbursements.
Revenue concentrates in: Chronic Pain. Steepest expansion trajectory: Postoperative multimodal protocols.
End User:
Customer type determines regulatory exposure and service intensity, with hospitals requiring REMS compliance infrastructure that excludes smaller dispensers.
- Hospitals:Inpatient and surgical service lines with anesthesia-led acute pain services replacing traditional pharmacy dispensing. US systems are adopting abuse-deterrent formulations as discharge standard of care.
- Clinics:Outpatient pain management and orthopedic practices with direct prescriber-patient relationships subject to state-level opioid prescribing limits.
- Pharmacies:Retail and specialty channels with divergent margin structures between generic substitution pressures and limited-distribution REMS products.
- Homecare:Hospice, long-term care, and patient-directed administration with adherence monitoring through connected delivery devices.
Procurement volume leaders: Hospitals. Fastest channel growth: Homecare with remote monitoring integration.
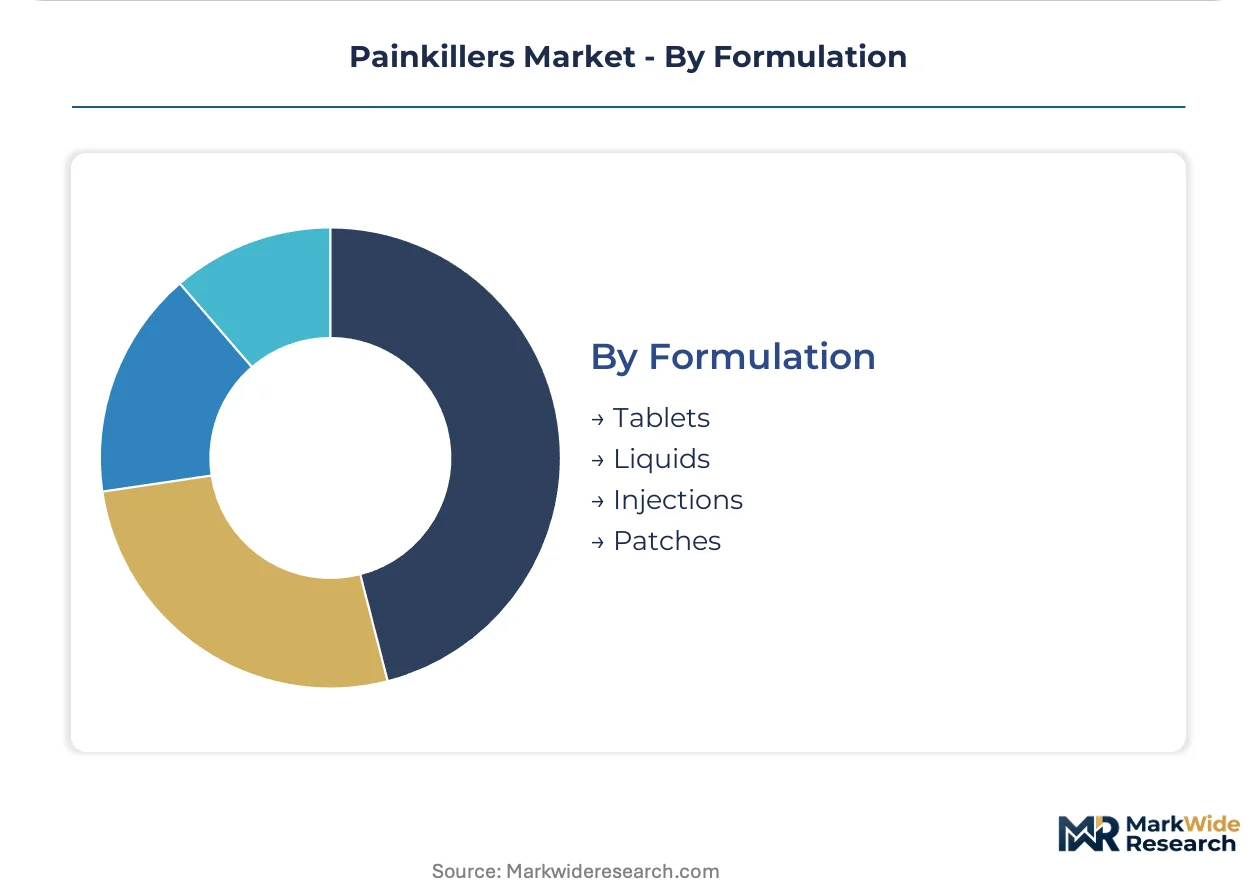
Formulation:
Delivery technology stratifies across cost efficiency, onset speed, and duration control, with polymer matrix advances reshaping competitive positioning in extended-release categories.
- Tablets:Immediate-release and controlled-release oral solid dosage forms with crushing-resistant polymer matrices for opioid categories. US hospital formularies are compressing market access for legacy formulations lacking extraction resistance.
- Injections:Parenteral NSAIDs, opioids, and local anesthetics for perioperative and emergency settings where oral bioavailability is compromised.
- Liquids:Pediatric, geriatric, and dysphagia-appropriate formulations with flavor masking and dose flexibility advantages.
- Patches:Transdermal polymer matrices enabling sustained-release fentanyl, buprenorphine, and lidocaine delivery with reduced breakthrough-dose requirements. REACH-authorized European manufacturers with established dossiers capture preferential procurement from risk-averse hospital buying groups.
Volume dominance: Tablets. Technology-led expansion: Patches with adherence advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand concentrates the highest volume of extended-release opioid consumption and multimodal postoperative protocols. Hospital procurement shifts and REMS compliance infrastructure reshape competitive access. Manufacturing clusters in New Jersey and North Carolina supply controlled-release formulations to domestic health systems.
United States
Chronic pain prevalence and Medicare Part D reimbursement for extended-release formulations drive prescription volume. FDA REMS mandates prescriber certification and patient counseling for long-acting opioids. New Jersey's pharmaceutical corridor hosts polymer matrix manufacturing for abuse-deterrent tablets.
Germany
REACH-authorized excipient suppliers and conservative opioid prescribing culture favor transdermal patch adoption. EMA pharmacovigilance requirements under EU Good Pharmacovigilance Practices accelerate legacy NSAID withdrawals. Chemical parks in Ludwigshafen and Leverkusen consolidate API sourcing for European hospital buying groups.
Japan
Aging demographics and METI-supported chronic pain initiatives expand reimbursement for extended-release formulations. PMDA oversight maintains stringent approval pathways for new molecular entities. Osaka-Kobe pharmaceutical clusters specialize in polymer matrix technologies for sustained-release delivery.
India
Generic API manufacturing for ibuprofen and naproxen intermediates supplies global volume requirements. CDSCO environmental compliance inspections trigger periodic production shutdowns in Gujarat and Telangana chemical parks. Hyderabad's fermentation capacity anchors cost leadership for fermentation-derived analgesic precursors.
China
Domestic consumption of NSAID raw materials and government hospital procurement reforms reshape distribution channels. NMPA serialization requirements track controlled substances through manufacturing to dispensing. Zhejiang and Jiangsu province chemical parks concentrate paracetamol intermediate production for export markets.
Painkillers Market Competitive Landscape
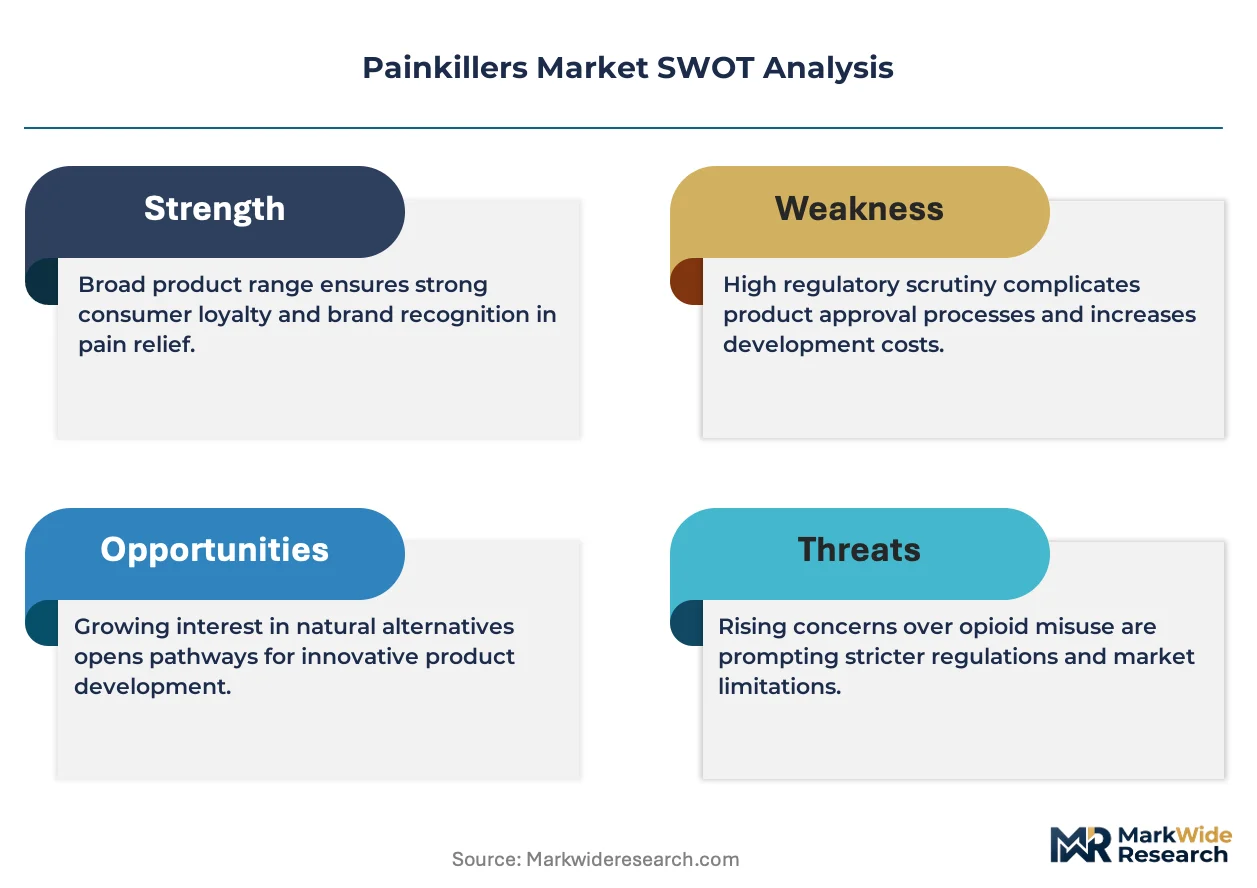
Abuse-deterrent formulation R&D dominates the current landscape as manufacturers redirect investment from legacy immediate-release tablets. The market structure tiers across diversified pharmaceutical conglomerates, generic volume specialists, and polymer technology licensors. Strategic archetypes include REMS-compliant infrastructure builders, API-backward-integrated cost leaders, and transdermal delivery technology specialists. M&A activity targets polymer chemistry capabilities, while capacity expansion concentrates in REACH-authorized European chemical parks.
Within the diversified pharmaceutical tier, Pfizer Inc. and Johnson & Johnson occupy positions defined by captive manufacturing infrastructure and controlled-release polymer expertise. Teva Pharmaceuticals exemplifies the generic volume archetype through diversified supplier networks. These three entities anchor distinct competitive vectors: proprietary formulation technology, multimodal protocol integration, and cost-optimized API sourcing.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Abbott Laboratories |
| Johnson & Johnson |
| Novartis AG |
| GSK plc |
| Teva Pharmaceuticals |
| Endo Pharmaceuticals Inc. |
| Bausch Health Companies Inc. |
| F. Hoffmann-La Roche Ltd. |
| Others |
Value Network & Pricing Analysis
REACH authorization requirements for chemical substances gate qualified supply access for European pharmaceutical manufacturers while simultaneously stratifying pricing tiers between compliant and non-compliant API sourcing. Premium-tier formulation partnerships cluster around Ludwigshafen and Leverkusen chemical parks where established dossiers command procurement preference from risk-averse hospital buying groups.
Pricing Analysis
Volume throughput concentrates in generic NSAID tablets where price compression runs through hospital tender processes, while margin capture shifts toward abuse-deterrent opioid formulations with polymer matrix barriers. Price differentiation hinges on FDA REMS certification tier and after-sales adherence monitoring bundling. Cost compression in immediate-release generics is intensifying because Indian and Chinese environmental compliance shutdowns disrupt API availability. Retail pharmacy channels exhibit highest price sensitivity; specialty pharmacy limited-distribution networks for REMS products demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with ibuprofen and naproxen intermediate production clustered in Gujarat and Telangana chemical parks, where CDSCO environmental inspections trigger unplanned capacity reductions. Raw material dependencies draw from paracetamol intermediates, fermentation-derived precursors, and controlled-release polymer excipients. Regulatory restriction risk emanates from DEA aggregate production quota adjustments for Schedule II substances redistributing manufacturing capacity unpredictably. Distribution runs through hospital formularies adopting anesthesia-led acute pain service models and specialty pharmacy channels with direct-to-patient monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The painkillers market functions as a vertical-integration race where captive fermentation capacity for API intermediates separates cost leaders from margin-compressed assemblers. Players are pursuing upstream control over polymer matrix technologies to capture premium positioning in abuse-deterrent formulations.
For Market Incumbents: Anchor REMS-compliant infrastructure as a defensive moat against regulatory escalation while consolidating formulation partnerships around REACH-authorized European chemical parks. Pfizer Inc.'s captive ibuprofen fermentation demonstrates how backward integration into API production insulates against Indian environmental shutdown volatility. Capacity expansion in polymer matrix manufacturing preserves hospital formulary access as extraction-resistant tablets displace legacy immediate-release volumes. For New Entrants and Emerging Players: The price-point gap between premium abuse-deterrent formulations and economy-tier immediate-release generics creates white-space opportunity for mid-tier players with differentiated delivery technologies. Japan's METI-supported chronic pain initiatives offer the most penetrable geography given historical opioid stigma and conservative prescribing norms. A go-to-market angle pairing transdermal patch formulations with remote adherence monitoring captures homecare channel growth. For Investors and Strategic Acquirers: DEA quota reallocation announcements are the leading indicator that manufacturing capacity is shifting toward abuse-deterrent investments and away from commoditized immediate-release exposure. Long-term viability over a multi-year horizon rests on polymer chemistry capabilities concentrated among narrow contract development and manufacturing organization sets. Acquisition targets should profile as transdermal delivery specialists with established PMDA or FDA submission pathways. The signal to monitor is EMA pharmacovigilance-driven legacy NSAID withdrawals accelerating market space opening.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation R&D | Polymer matrix barriers satisfy FDA REMS hospital formulary requirements while compressing legacy tablet access. |
| REACH-Authorized Supplier Consolidation | Chemical parks in Ludwigshafen and Leverkusen capture preferential procurement from European hospital buying groups. |
| Transdermal Patch Manufacturing Scale-Up | Sustained-release fentanyl and buprenorphine delivery reduces breakthrough-dose requirements in hospice settings. |
| Specialty Pharmacy Channel Integration | Limited-distribution networks enable direct-to-patient adherence monitoring capturing lifetime chronic pain value. |
| Captive Fermentation Capacity Expansion | In-house ibuprofen intermediate production insulates Pfizer Inc. from Indian environmental compliance shutdowns. |
Research Methodology
Document review covered FDA REMS program filings, EMA pharmacovigilance submissions, and DEA aggregate production quota records, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from ClinicalTrials.gov, CMS Medicare Part D formulary databases, and SEC 10-K pharmaceutical segment disclosures. Bottom-up volume modeling across dosage forms and administration routes triangulated against top-down therapeutic category expenditure estimates.
Cross-referencing historical FDA approval pathways with expert panel input on polymer matrix technology diffusion shaped the analytical framework across the analysis window. Segmentation dimensions modeled included product type, therapy area, formulation technology, and end-user channel. CAGRs were derived from surgical volume recovery trajectories, REMS compliance cost escalations, and transdermal delivery adoption curves. Forecast inputs incorporated DEA quota allocation patterns and METI chronic pain reimbursement policy shifts.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in real-time inventory positioning at Indian chemical parks introduce uncertainty bands around API supply disruption scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Cluster Headache Market
Pain Management
Chronic Lower Back Pain Treatment Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Bone Pain Treatment Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Neuropathic Pain Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Migraine Management Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Radiofrequency Ablation Devices for Pain Management Market
Pain Management
OTC Painkiller Market
Pain Management
Visceral Pain Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Postoperative Pain Market