
 Niemann-Pick Disease Type C Therapeutics Market | 2026-2036
Niemann-Pick Disease Type C Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Niemann-Pick Disease Type C Therapeutics Market Foresight
Multi-source clinical supply networks is expanding across the Niemann-Pick Type C development landscape as sponsors diversify manufacturing partnerships to mitigate rare-disease trial risk. Zevra Therapeutics anchors its program through specialized lipid metabolism expertise and dedicated rare disease infrastructure. Cyclo Therapeutics, Inc. leverages cyclodextrin chemistry leadership to differentiate its neurodegenerative approach. Johnson & Johnson Services, Inc. sustains broader neurology portfolio investments that compete for internal resource allocation against orphan indications.
Niemann-Pick Disease Type C therapeutics comprise pharmacological interventions targeting intracellular cholesterol trafficking defects caused by NPC1 or NPC2 gene mutations, with formulations requiring blood-brain barrier penetration for neurological efficacy. These treatments aim to modify disease progression in a fatal lysosomal storage disorder affecting approximately one in 100,000 live births. Small molecule drugs currently occupy the most mature development pathway with established regulatory precedents, while gene therapy represents the fastest-advancing segment despite manufacturing complexity and delivery challenges. Pediatric settings concentrate initial demand as early intervention determines neurological outcome, though adult treatment applications are widening with improved diagnostic biomarker availability.
FDA orphan drug incentives and EMA priority medicines designation shape competitive entry timelines and exclusivity value for developers in this space. The European Medicines Agency coordinates centralized pediatric investigation plans that dictate trial enrollment requirements across EU member states. Health Canada and the FDA maintain aligned chemistry, manufacturing, and controls standards that streamline cross-border supply logistics. Stakeholders must monitor regulatory divergence on gene therapy durability endpoints as these evidentiary standards will determine which platforms secure accelerated pathways versus full approval requirements.
Market Dynamics
Gene therapy manufacturing scale-up is compressing clinical development timelines while blood-brain barrier delivery platforms are fragmenting competitive positioning across the Niemann-Pick Type C pipeline. FDA accelerated approval pathways for rare neurodegenerative indications are reshaping how sponsors sequence registrational trials.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market exclusivity post-approval incentivizes rare disease development despite small addressable populations.
- Pediatric Early Intervention:Neonatal screening expansion in metabolic disorder clinics is compressing diagnostic delays and expanding treatable incident cases.
- Cyclodextrin Chemistry Maturation:Intrathecal delivery refinements are improving central nervous system drug exposure profiles.
Market Restraints
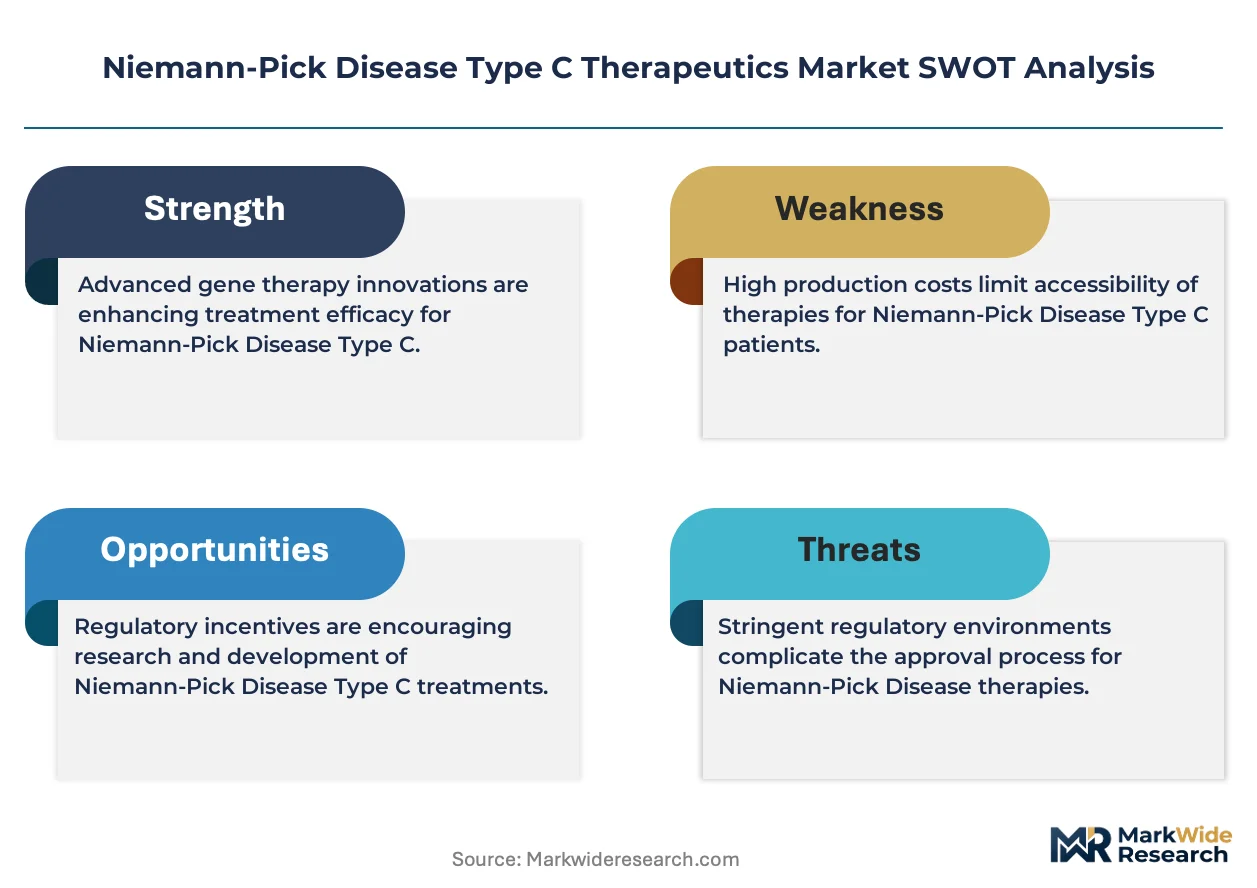
- Plasmid DNA Supply Concentration:Viral vector manufacturing depends on a limited network of GMP-certified facilities in the United States and Europe.
- Intrathecal Administration Infrastructure:Specialized neurosurgical access requirements restrict treatment to academic medical centers with pediatric neurosurgery capabilities.
- Natural History Study Gaps:Variable disease progression complicates endpoint selection for regulatory submissions.
Strategic Opportunities
- EMA Priority Medicines Pathway:Accelerated assessment timelines reduce development-to-approval intervals for qualifying therapies.
- Adult Diagnostic Biomarker Expansion:Plasma oxysterol testing availability is widening the treatable population beyond pediatric incident cases.
- Companion Diagnostic Integration:NPC1/NPC2 mutation profiling is converging with treatment selection protocols in specialized metabolic centers.
Industry Challenges
- Gene Therapy Durability Uncertainty:Long-term expression stability remains uncharacterized, complicating label claims and reimbursement negotiations.
- Neurodegenerative Endpoint Standardization:Composite clinical rating scales require harmonization across international investigator networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Niemann-Pick Disease Type C Therapeutics Market |
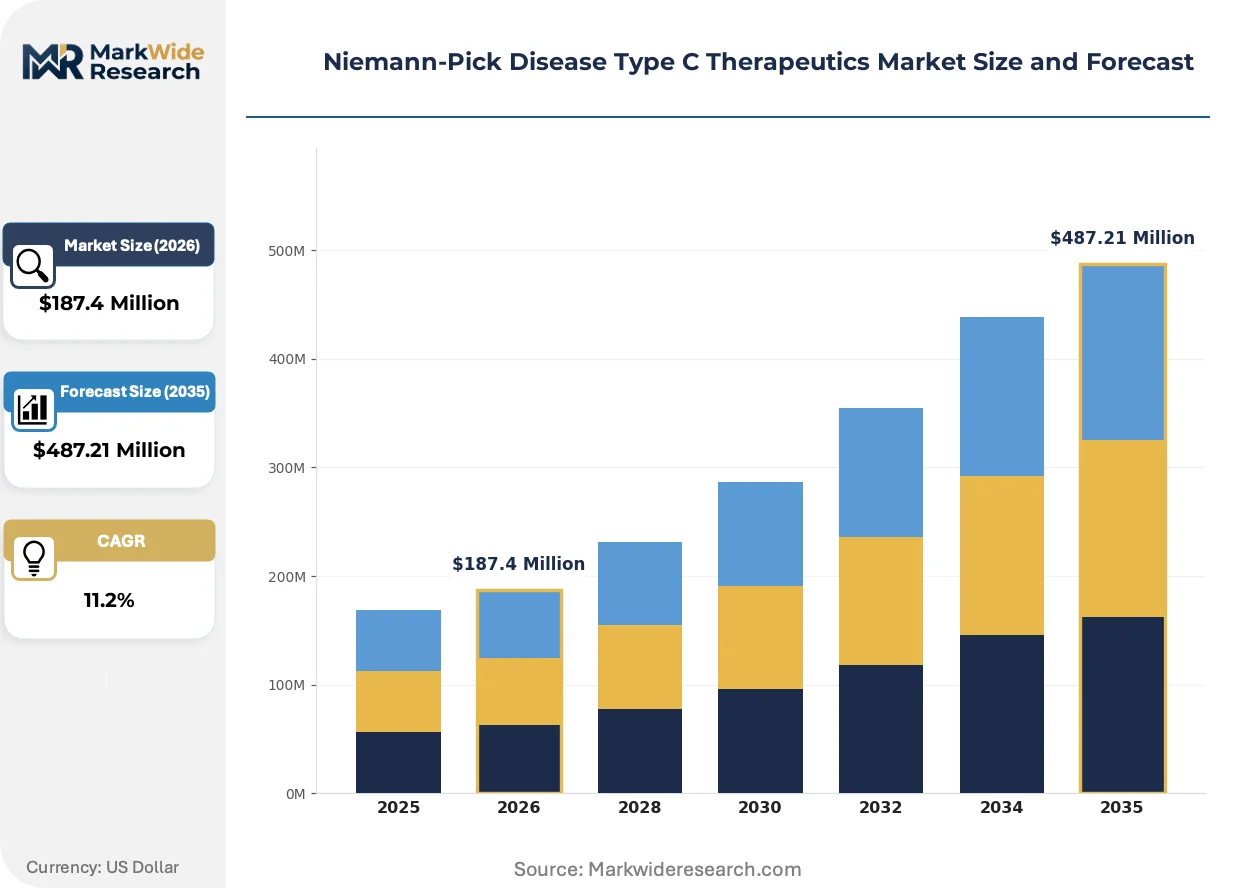
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cholesterol Transport Modulators, Gene Therapy, Enzyme Replacement Therapy, Small Molecule Drugs Application: Pediatric Settings, Adult Treatment, Neurological Disorders, Metabolic Disorders End User: Hospitals, Specialty Clinics, Research Institutions, Home Care Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation |
| Companies Covered | Azafaros A.G., Sarepta Therapeutics, Inc., Cyclo Therapeutics, Inc., Swedish Orphan Biovitrum AB, Orphazyme A/S, IntraBio, Inc., Johnson & Johnson Services, Inc., StrideBio, Zevra Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Niemann-Pick Disease Type C Therapeutics Market Shifts & Advancements
Biomarker-driven trial designs are compressing enrollment timelines while manufacturing platform standardization is reducing per-patient production costs. These shifts are enabling smaller sponsors to retain development control.
Adeno-associated viral vector engineering is converging with blood-brain barrier shuttle technologies to improve transduction efficiency in neuronal populations. Pediatric gene therapy centers in the United States and Germany are piloting these dual-platform approaches in first-in-human protocols. This convergence is compressing the efficacy gap between systemic and direct CNS delivery modalities.
EMA centralized pediatric investigation plans now mandate age-appropriate formulation development alongside adult trials. This regulatory architecture forces sponsors to allocate manufacturing capacity across multiple dosage strengths earlier in development. European metabolic disorder networks are responding by consolidating trial infrastructure across France, Germany, and the Netherlands.
Academic medical centers are unbundling clinical trial execution from longitudinal natural history data collection. Contract research organizations with rare disease neurology expertise are displacing traditional site management models in the United States. This restructuring concentrates patient access within established NPC referral networks at Boston Children's Hospital, the National Institutes of Health, and University Hospital Heidelberg.
Niemann-Pick Disease Type C Therapeutics Market Segmentation
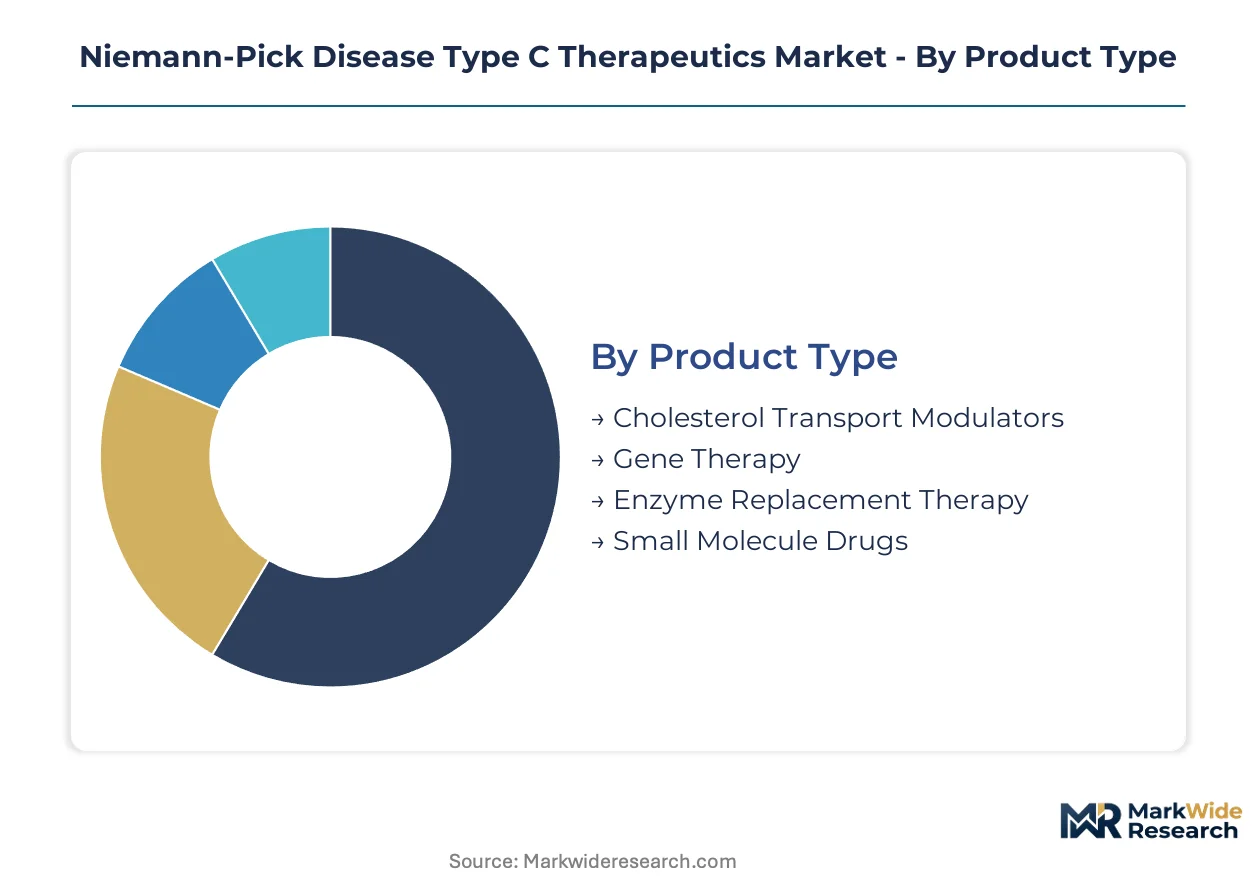
Segmentation in Niemann-Pick Type C therapeutics reveals how treatment complexity fragments across patient age, disease manifestation, and delivery infrastructure. Understanding these divisions exposes where development capital concentrates and where access bottlenecks persist.
Product Type:
Treatment selection hinges on disease stage and neurological involvement severity, with mechanism of action determining blood-brain barrier penetration and regulatory pathway.
- Small Molecule Drugs:Lipid-soluble compounds designed for oral bioavailability and intracellular cholesterol trafficking correction. Pediatric metabolic centers in the United States prioritize these agents for early intervention protocols due to established FDA regulatory precedents and manageable manufacturing scale.
- Gene Therapy:Adeno-associated viral vectors delivering functional NPC1 or NPC2 gene copies directly to the central nervous system. Academic medical centers in Germany and the United States are piloting these approaches for rapid neurological progression cases, though plasmid DNA supply constraints limit enrollment expansion.
- Cholesterol Transport Modulators:Cyclodextrin-based compounds administered intrathecally to mobilize accumulated lipids from neuronal lysosomes.
- Enzyme Replacement Therapy:Exogenous enzyme formulations targeting peripheral disease manifestations with limited CNS penetration.
Small Molecule Drugs lead on scale; Gene Therapy leads on momentum.
Application:
Disease presentation age dictates therapeutic urgency and endpoint selection, with neurological versus metabolic symptom dominance channeling patients into distinct care pathways.
- Pediatric Settings:Neonatal and early childhood cases requiring immediate intervention to preserve neurodevelopmental trajectory. Tertiary metabolic centers at Boston Children's Hospital and University Hospital Heidelberg concentrate incident case capture through expanded newborn screening programs.
- Neurological Disorders:Progressive cerebellar ataxia, dementia, and vertical gaze palsy manifestations demanding CNS-penetrant therapies. Specialized neurology units prioritize blood-brain barrier delivery platforms as disease advances to this stage.
- Adult Treatment:Late-onset diagnoses following years of unexplained psychiatric or movement disorder symptoms.
- Metabolic Disorders:Hepatosplenomegaly and visceral lipid accumulation without primary neurological involvement.
Pediatric Settings lead on scale; Adult Treatment gains share fastest.
End User:
Care setting determines treatment complexity tolerance, with infrastructure requirements for intrathecal administration restricting certain therapies to specialized facilities.
- Specialty Clinics:Dedicated lysosomal storage disorder centers managing longitudinal care and clinical trial enrollment. These sites in the United States, France, and the Netherlands coordinate natural history data collection alongside therapeutic administration.
- Hospitals:Academic medical centers with pediatric neurosurgery capabilities required for intrathecal drug delivery. Surgical access infrastructure concentrates at NIH Clinical Center and select German university hospitals.
- Research Institutions:Sites conducting first-in-human gene therapy protocols and biomarker validation studies.
- Home Care:Settings supporting oral small molecule maintenance therapy for stable patients.
Hospitals lead on scale; Specialty Clinics lead on momentum.
Delivery Mode:
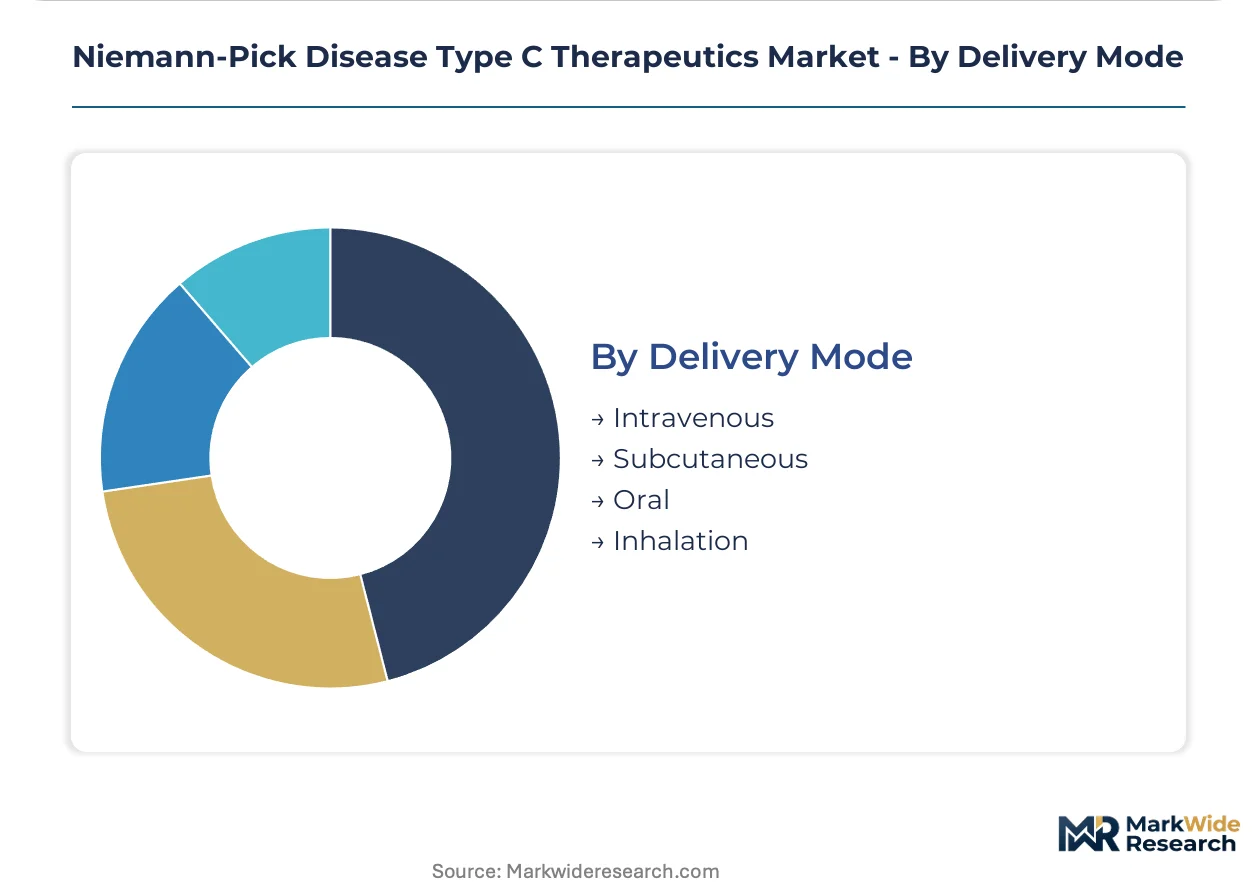
Route of administration directly constrains treatment location and patient compliance, with CNS penetration requirements driving the most complex delivery approaches.
- Intravenous:Systemic administration for peripheral disease modification and enzyme replacement approaches. This route enables broader site participation but achieves limited neuronal transduction for neurological manifestations.
- Oral:Small molecule formulations supporting outpatient maintenance and home-based care continuity. Patient adherence advantages expand addressable population beyond surgical center catchment areas.
- Subcutaneous:Intermediate complexity delivery for selected biologic formulations.
- Inhalation:Investigational pulmonary targeting for specific respiratory manifestations.
Intravenous leads on scale; Oral climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston Children's Hospital anchors specialized metabolic disorder infrastructure, concentrating pediatric clinical trial enrollment and natural history data collection for Niemann-Pick Type C development programs.
United States
The National Institutes of Health Clinical Center and Boston Children's Hospital drive incident case capture through expanded newborn screening. FDA orphan drug exclusivity provisions accelerate sponsor timelines for rare neurodegenerative indications. Maryland and Massachusetts academic medical centers coordinate gene therapy first-in-human protocols with specialized pediatric neurosurgery units.
Germany
University Hospital Heidelberg and Hamburg-Eppendorf University Medical Center concentrate European gene therapy pilot programs. EMA centralized pediatric investigation plans mandate age-appropriate formulation development alongside adult trials. Bavarian and Baden-Württemberg metabolic networks consolidate trial infrastructure across Frankfurt, Munich, and Stuttgart referral corridors.
France
Parisian lysosomal storage disorder centers at Necker-Enfants Malades Hospital capture late-onset adult diagnoses through plasma oxysterol testing expansion. ANSM coordinates early access programs for investigational neurodegenerative therapies. Île-de-France and Auvergne-Rhône-Alpes regions host specialized neurology units managing vertical gaze palsy progression cases.
Netherlands
Erasmus MC Sophia Children's Hospital and Amsterdam UMC anchor Benelux metabolic disorder referral networks. Dutch healthcare insurance mandates for rare disease treatments reduce reimbursement negotiation friction for approved therapies. Randstad medical centers coordinate natural history data collection alongside therapeutic administration for multinational sponsor programs.
Switzerland
Swissmedic's alignment with EMA accelerated assessment pathways reduces development-to-approval intervals for qualifying therapies. University Hospital Zurich and Geneva University Hospitals concentrate adult diagnostic biomarker research. Basel and Zurich pharmaceutical clusters host contract manufacturing organizations supplying cyclodextrin-based formulations to global trials.
Niemann-Pick Disease Type C Therapeutics Market Competitive Landscape
Global majors compete with regional champions across regulatory strategy and patient access infrastructure, producing a tiered structure where large pharmaceutical conglomerates share terrain with dedicated rare disease specialists. The vendor base clusters around three strategic archetypes: cyclodextrin chemistry specialists, gene therapy platform developers, and diversified neurology portfolio holders. Capacity expansion into plasmid DNA manufacturing and strategic partnerships with academic medical centers constitute the dominant competitive moves reshaping participant positioning.
Within the rare disease specialist tier, Zevra Therapeutics and Cyclo Therapeutics, Inc. exemplify focused development models targeting lipid metabolism expertise and cyclodextrin chemistry leadership respectively. Johnson & Johnson Services, Inc. occupies a position representing diversified pharmaceutical conglomerates competing for internal resource allocation against orphan indications. These three entities collectively illustrate how competitive positioning fragments between dedicated single-asset developers and broader portfolio holders.
| Leading Market Players |
|---|
| Azafaros A.G. |
| Sarepta Therapeutics, Inc. |
| Cyclo Therapeutics, Inc. |
| Swedish Orphan Biovitrum AB |
| Orphazyme A/S |
| IntraBio, Inc. |
| Johnson & Johnson Services, Inc. |
| StrideBio |
| Zevra Therapeutics |
| Others |
Supply & Pricing Matrix
Plasmid DNA manufacturing costs cascade through gene therapy pricing tiers, with GMP-certified facility scarcity in the United States and Europe compressing margins for sponsors while concentrating pricing power among contract manufacturers serving academic medical centers.
Pricing Analysis
Input-cost pass-through from viral vector production dominates pricing structures, with cyclodextrin raw material grades and AAV plasmid purity tiers separating premium intrathecal formulations from standard-of-care options. FDA orphan drug exclusivity supports value-based pricing for first-to-market small molecules, though gene therapy developers face downward pressure from durability uncertainty in reimbursement negotiations. Pediatric metabolic centers exhibit lowest price sensitivity due to limited therapeutic alternatives, while adult diagnostic expansion segments demand cost transparency.
Supply Chain Analysis
Direct-to-specialty-clinic channels handle investigational therapy distribution, with cold-chain logistics tethered to academic medical centers in Maryland, Massachusetts, and Baden-Württemberg. Plasmid DNA supply rests on GMP facilities in the United States, Germany, and Switzerland, while cyclodextrin active pharmaceutical ingredients feed from Basel and Zurich manufacturing clusters. Single-source viral vector vulnerability creates tariff-exposure risk for sponsors dependent on cross-border European production. Distribution runs through dedicated rare disease pharmacy networks coordinating with NIH Clinical Center and Boston Children's Hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications in neurological endpoints are hardening as FDA and EMA convergence on composite clinical rating scales elevates evidentiary thresholds for premium positioning.
For Market Incumbents: Extend manufacturing capacity into captive plasmid DNA production to secure vector supply against emerging platform competitors. Lock in long-term contracts with University Hospital Heidelberg and NIH Clinical Center site networks before gene therapy trial infrastructure saturates. Cyclodextrin chemistry leaders should deepen backward integration into pharmaceutical-grade raw material sourcing. For New Entrants and Emerging Players: Blood-brain barrier shuttle technologies offer entry pathways where established AAV platforms face transduction efficiency constraints. Adult diagnostic biomarker expansion represents the most penetrable segment, with plasma oxysterol testing availability widening addressable populations beyond pediatric incident capture. Partner with Dutch and Swiss reimbursement specialists to navigate early access program structures. For Investors and Strategic Acquirers: Consolidation pressure builds where gene therapy durability data gaps create valuation uncertainty for single-asset developers. Five-to-ten year viability hinges on manufacturing platform standardization rather than clinical-stage asset accumulation. Target acquisition archetypes include cyclodextrin formulation specialists with intrathecal delivery expertise. Watch for EMA centralized pediatric investigation plan compliance as inflection signal for European market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Biomarker-driven designs at NIH and Heidelberg compress enrollment timelines for neurological endpoints. |
| Regulatory Approval Pathway | FDA orphan drug exclusivity and EMA PRIME designation accelerate development-to-approval intervals. |
| Manufacturing Scale-Up | Plasmid DNA capacity expansion in Maryland and Bavaria reduces per-patient production costs. |
| Pipeline Diversification | Gene therapy platforms combined with cyclodextrin chemistry hedge against single-mechanism durability risk. |
| Strategic Partnership | Academic medical center alliances at Boston Children's and Erasmus MC secure patient access infrastructure. |
Research Methodology
Coverage spans the United States, Germany, France, Netherlands, and Switzerland, with primary inputs from each market cluster combined with secondary validation. Drug development executives, regulatory affairs leads at FDA and EMA, hospital procurement managers at academic medical centers, and payer access specialists provided qualitative inputs. Secondary sources include FDA orphan drug filings, EMA PRIME designation records, ClinicalTrials.gov protocol databases, and hospital formulary documentation. Bottom-up patient incidence modeling and top-down therapeutic category sizing were triangulated against manufacturer capacity disclosures.
Rate-of-change decomposition across the analysis window separates volume drivers from price mix effects. Segmentation dimensions include product type, application by disease presentation age, end-user care setting, and delivery mode complexity. CAGRs were derived from patient population projections, treatment penetration assumptions, and pricing evolution by mechanism of action. Forecast inputs incorporate newborn screening expansion trajectories, plasma oxysterol test availability curves, and intrathecal administration infrastructure buildout.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene therapy durability data, regulatory divergence on CNS delivery endpoints, and plasmid DNA manufacturing capacity expansion timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Europe Down Syndrome Market