
 Medicated Pain Relieving Plasters Market | 2026-2036
Medicated Pain Relieving Plasters Market Size, Share, and Industry Trends Forecast 2026-2036
Medicated Pain Relieving Plasters Market Outlook
Aftermarket service revenue from patient adherence programs and pharmacy counseling is tilting toward patch manufacturers with direct-to-clinic distribution networks. Hisamitsu Pharmaceutical sustains dominance in Japan through captive manufacturing of adhesive substrates and proprietary cooling technologies. GSK leverages its OTC pharmacy relationships across Europe to secure shelf placement for lidocaine patches. Johnson & Johnson anchors North American retail presence through chain drugstore partnerships and private-label contract manufacturing.
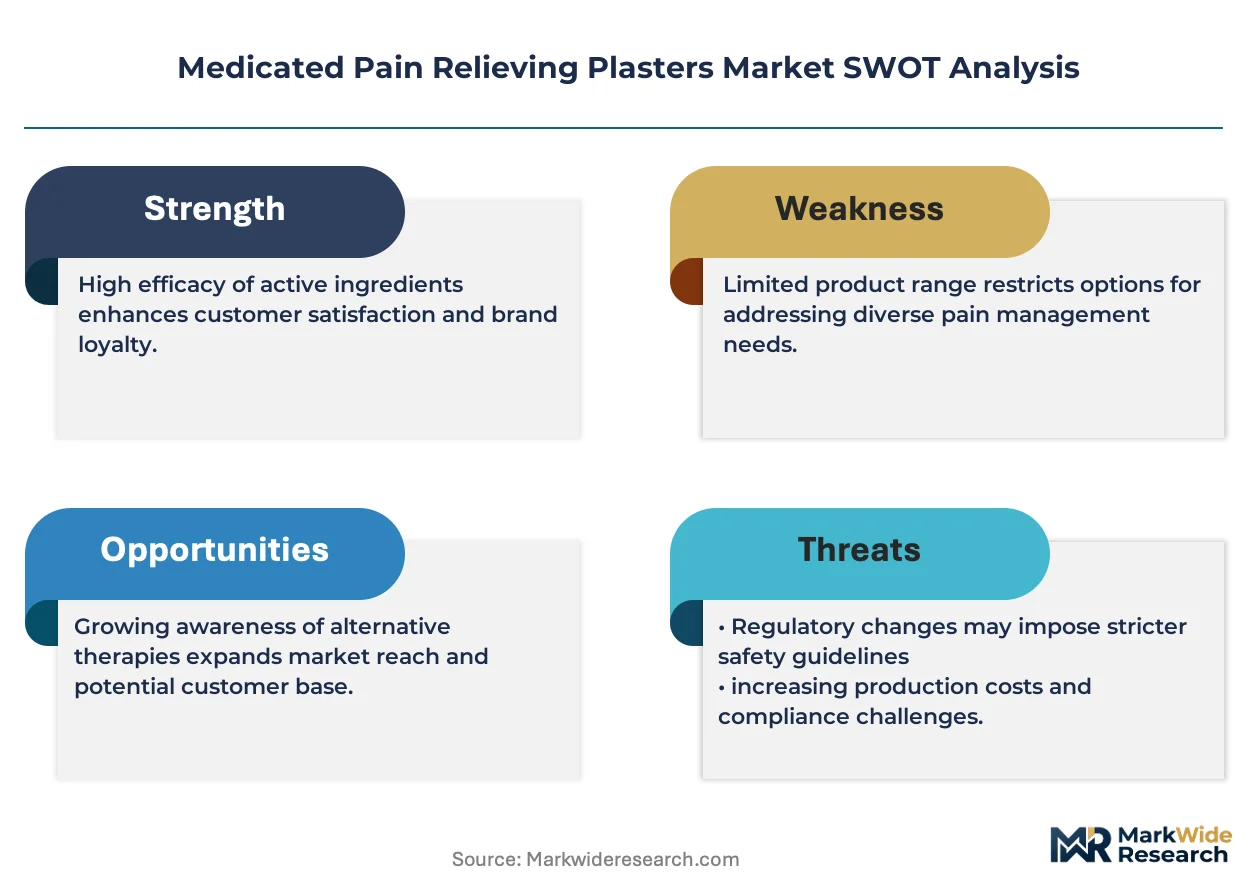
Medicated pain relieving plasters are transdermal or topical adhesive systems containing active pharmaceutical ingredients—typically NSAIDs, local anesthetics, or counterirritants—delivered through a polymer matrix at controlled release rates to achieve localized analgesia without systemic peak concentrations. These products serve commercial and clinical purposes by offering non-invasive pain management for musculoskeletal conditions, postoperative recovery, and sports injuries where oral administration poses gastrointestinal or dependency risks. Gel patches command premium positioning in Asia-Pacific markets due to superior skin tolerability and moisture retention properties, while adhesive patches retain volume leadership in European pharmacy channels where reimbursement frameworks favor established formats. Transdermal patches incorporating ibuprofen or capsaicin represent the fastest-growing active ingredient segment as clinicians seek alternatives to opioid prescriptions for chronic lower back and osteoarthritis pain.
The FDA's Quality by Design requirements for transdermal dosage forms and the EMA's MDR compliance deadlines for adhesive medical devices are elevating manufacturing standards and excluding smaller contract producers from regulated markets. Japan's PMDA maintains distinct pharmacovigilance reporting for topical analgesics that shapes formulation decisions by Nichiban and Teikoku Seiyaku. Stakeholders must monitor evolving bioequivalence protocols for generic patch approvals and calibrate R&D budgets against tightening extractables and leachables testing mandates.
Market Dynamics
FDA Quality by Design mandates for transdermal dosage forms are compressing supplier margins while forcing adhesive matrix reformulations that favor manufacturers with captive polymer synthesis capabilities.
Growth Catalysts
- Japan's aging demographics:The country's 65-plus population sustains category-leading consumption of topical analgesics where oral NSAIDs pose gastrointestinal risks.
- EMA MDR compliance deadlines:Elevated manufacturing standards for adhesive medical devices are accelerating consolidation toward producers with in-house extractables testing laboratories.
- Lidocaine patch adoption in sports medicine:Professional athletic organizations are expanding acute injury management protocols with local anesthetic patches to reduce opioid exposure.
Market Restraints
- Petrochemical feedstock volatility:Acrylic adhesive precursors and silicone release liners face input cost swings that compress gross margins for polymer-dependent patch producers.
- Single-source API concentration:Synthetic capsaicin manufacturing clusters in China create supply vulnerability for Western formulators lacking backward integration into active ingredient production.
- Skin irritation liability thresholds:PMDA pharmacovigilance reporting requirements for topical analgesics limit formulation flexibility and extend development timelines for new entrants.
Strategic Opportunities
- Rural pharmacy networks in India:Underpenetrated distribution infrastructure for medicated plasters creates first-mover advantage for OTC brands establishing direct-to-clinic logistics.
- Wearable sensor convergence:Integration of temperature-monitoring electronics with analgesic patches enables real-time adherence tracking for postoperative pain protocols.
- US IRA drug pricing provisions:Medicare negotiation pressure on oral analgesics creates relative cost advantage for non-reimbursed topical alternatives in chronic pain management.
Industry Challenges
- Bioequivalence protocol complexity:Generic patch approvals require expensive clinical endpoint studies that strain R&D budgets for mid-scale manufacturers.
- Adhesion engineering talent scarcity:Formulation chemists with transdermal polymer matrix expertise command premium compensation that concentrates capability at incumbent firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicated Pain Relieving Plasters Market |
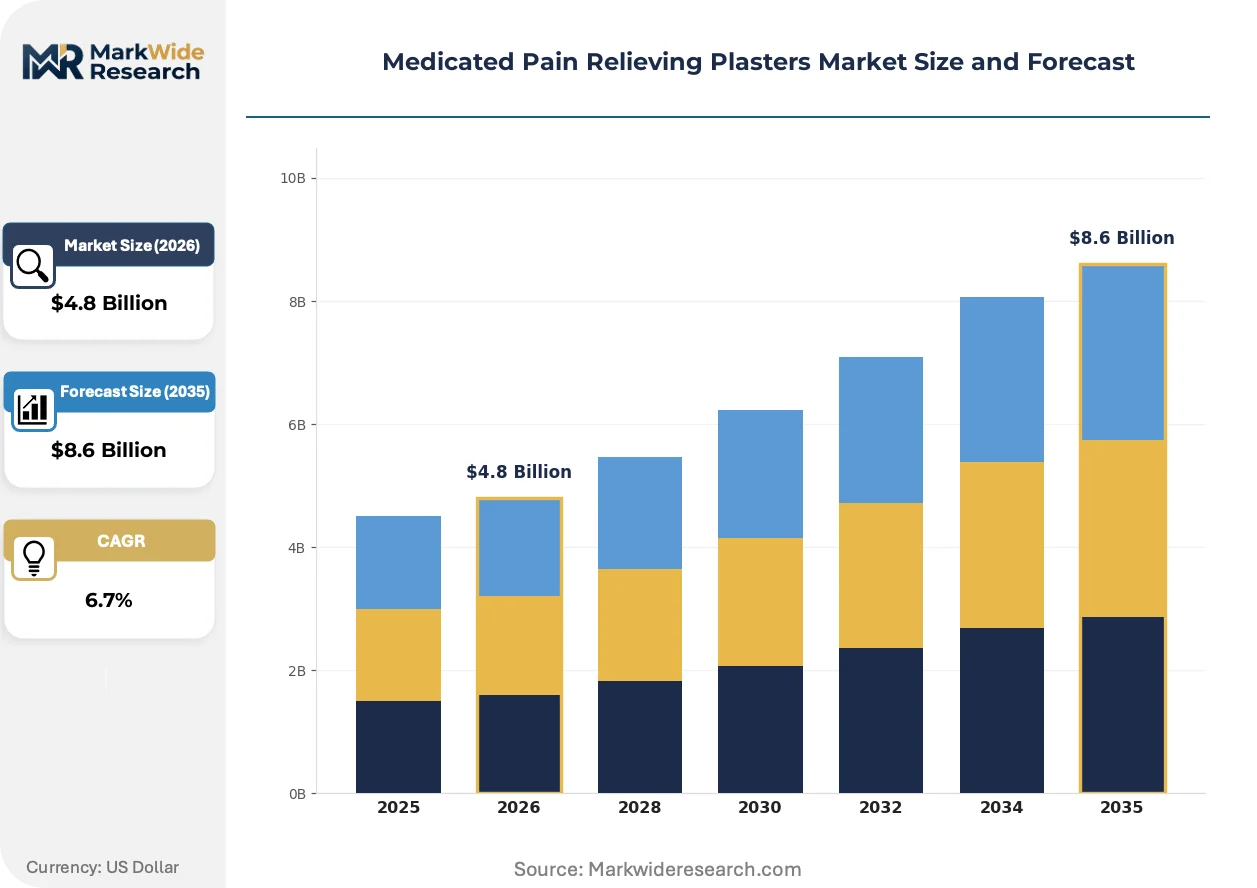
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transdermal Patches, Adhesive Patches, Gel Patches, Herbal Patches Active Ingredient: Ibuprofen, Lidocaine, Capsaicin, Methyl Salicylate End User: Retail Customers, Healthcare Providers, Sports Teams, Home Care Distribution Channel: Pharmacies, Online Stores, Supermarkets, Hospitals |
| Companies Covered | Nichiban Co., Ltd., Teva Pharmaceutical Industries Ltd., Hisamitsu Pharmaceutical Co., Inc., Sanofi, Grünenthal GmbH, Teikoku Seiyaku Co., Ltd., Beiersdorf AG, GSK, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicated Pain Relieving Plasters Market Strategic Shifts
Digital manufacturing and closed-loop quality systems are compressing batch-to-batch variability while enabling mass customization of patch geometries for anatomically specific applications.
Micro-needle array technology is virtualizing the conventional reservoir-and-membrane patch architecture by creating direct dermal channels for lidocaine and diclofenac delivery. Pain management clinics in Germany and Switzerland are piloting these systems for neuropathic conditions where stratum corneum penetration limits conventional formulations. The technology is virtualizing competitive positioning by collapsing the efficacy gap between topical and injectable local anesthetics.
REACH restrictions on persistent organic pollutants are forcing European manufacturers to replace halogenated solvents in adhesive coating processes with aqueous or supercritical carbon dioxide alternatives. The industrial consequence is capital-intensive production line retrofits that favor producers with multi-site manufacturing networks. Gel patch categories face the steepest compliance costs due to their reliance on solvent-based polymer cross-linking chemistries.
Hospital procurement consortia are consolidating purchasing authority for postoperative analgesia supplies, displacing fragmented pharmacy-level ordering with centralized tenders that prioritize total cost-of-therapy metrics. This concentration is most visible in France and the Netherlands where regional health authorities bundle patch procurement with infusion pump contracts. The shift compresses margin for manufacturers lacking dedicated institutional sales infrastructure.
Medicated Pain Relieving Plasters Market Segmentation
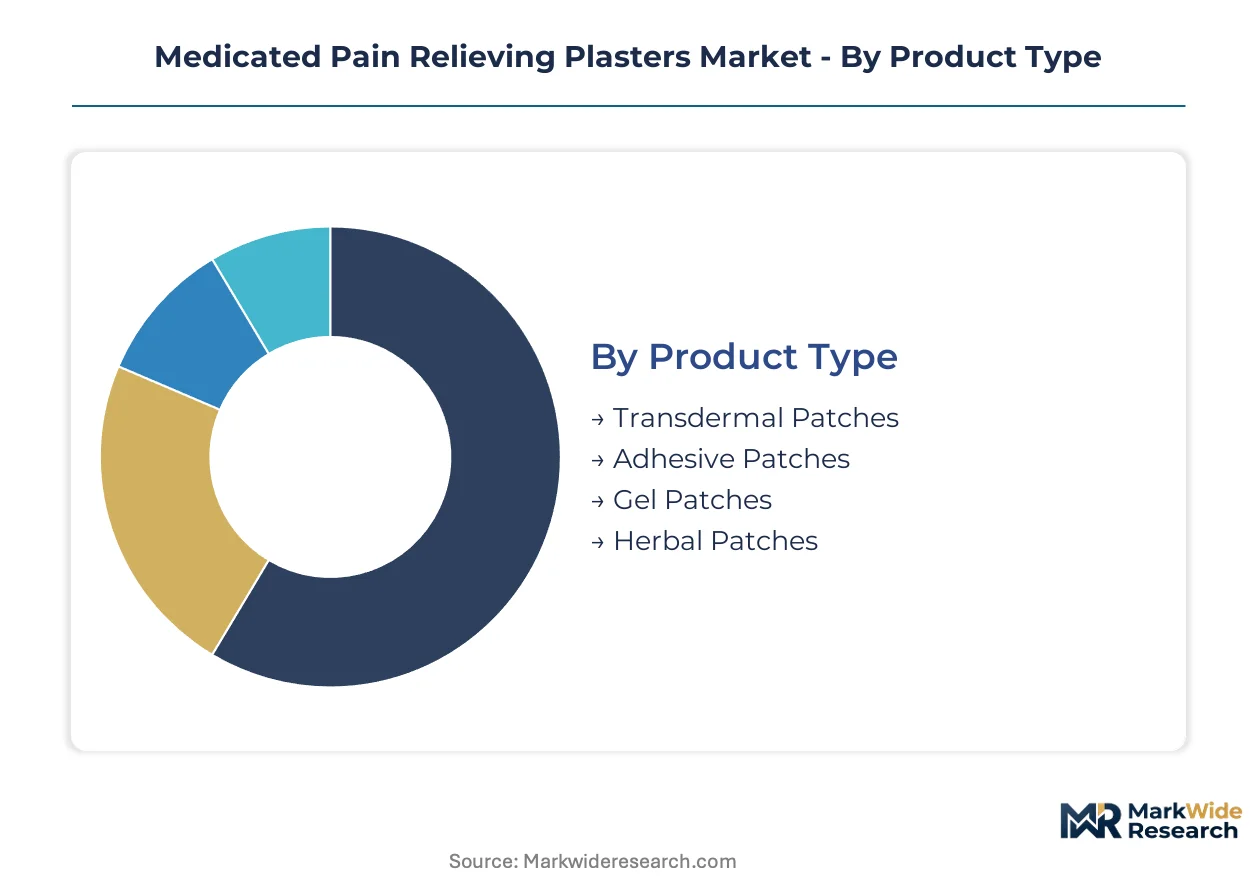
Segmentation in medicated pain relieving plasters reveals divergent margin profiles and regulatory pathways. Product format determines manufacturing capital intensity while active ingredient selection shapes reimbursement eligibility and clinical adoption velocity.
Product Type:
Adhesive patches turn inventory fastest through pharmacy channels, while gel patches require longer production cycles due to moisture-retention formulation steps.
- Transdermal Patches:Reservoir-matrix systems with rate-controlling membranes deliver sustained API release over 12-24 hours. Demand concentrates in German pain management clinics where opioid-sparing protocols prioritize controlled-release local anesthetics for chronic neuropathic conditions.
- Adhesive Patches:Acrylic or silicone-based matrices with immediate-release profiles dominate European pharmacy reimbursement frameworks. Volume leadership in France and Netherlands reflects institutional procurement bundling with postoperative care supplies.
- Gel Patches:Hydrogel substrates with superior skin tolerability command premium positioning in Japan's aging demographic segments where moisture retention reduces irritation incidence.
- Herbal Patches:Traditional formulations incorporating menthol or camphor derivatives sustain niche demand in South Korean and Taiwanese retail channels where cultural preference for botanical analgesics persists.
Adhesive patches dominate installed base. Gel patches are where expansion concentrates.
Active Ingredient:
Cost tier stratification separates premium-priced local anesthetics from commoditized counterirritants, with synthesis complexity determining margin capture.
- Lidocaine:Amide-type local anesthetic formulated in 4% or 5% concentrations for peripheral neuropathy and postherpetic neuralgia. Procurement by professional sports medicine departments in the United States accelerates as athletic organizations implement opioid-reduction protocols for acute injury management.
- Capsaicin:Synthetic or naturally derived vanilloid compound depleting substance P from sensory neurons. Supply vulnerability from Chinese API manufacturing clusters constrains Western formulators lacking backward integration into active ingredient production.
- Ibuprofen:NSAID delivered through topical gel or adhesive matrix for osteoarthritis and soft tissue inflammation. EMA MDR compliance costs for adhesive medical devices elevate manufacturing standards for European producers.
- Methyl Salicylate:Counterirritant producing superficial warming sensation through vasodilation. Standard-grade positioning in North American mass retail channels where price competition with private-label alternatives compresses brand premiums.
Lidocaine captures premium pricing tiers. Capsaicin is climbing the fastest as clinicians seek opioid alternatives.
End User:
Customer type determines purchasing authority concentration, with institutional buyers consolidating tender power while retail remains fragmented.
- Healthcare Providers:Hospital procurement consortia and pain management clinics with centralized purchasing authority for postoperative analgesia supplies. Regional health authorities in France bundle patch procurement with infusion pump contracts.
- Sports Teams:Professional athletic organizations expanding acute injury management protocols with local anesthetic patches to reduce opioid exposure. Direct-to-clinic distribution networks capture aftermarket service revenue from adherence programs.
- Retail Customers:Self-medicating consumers purchasing OTC products through pharmacy and supermarket channels. Japan's aging demographics sustain category-leading consumption where oral NSAIDs pose gastrointestinal risks.
- Home Care:Post-discharge patients requiring extended pain management outside institutional settings. Pharmacy counseling services tilt toward manufacturers with patient adherence program infrastructure.
Healthcare providers dominate installed base. Sports teams are where expansion concentrates.
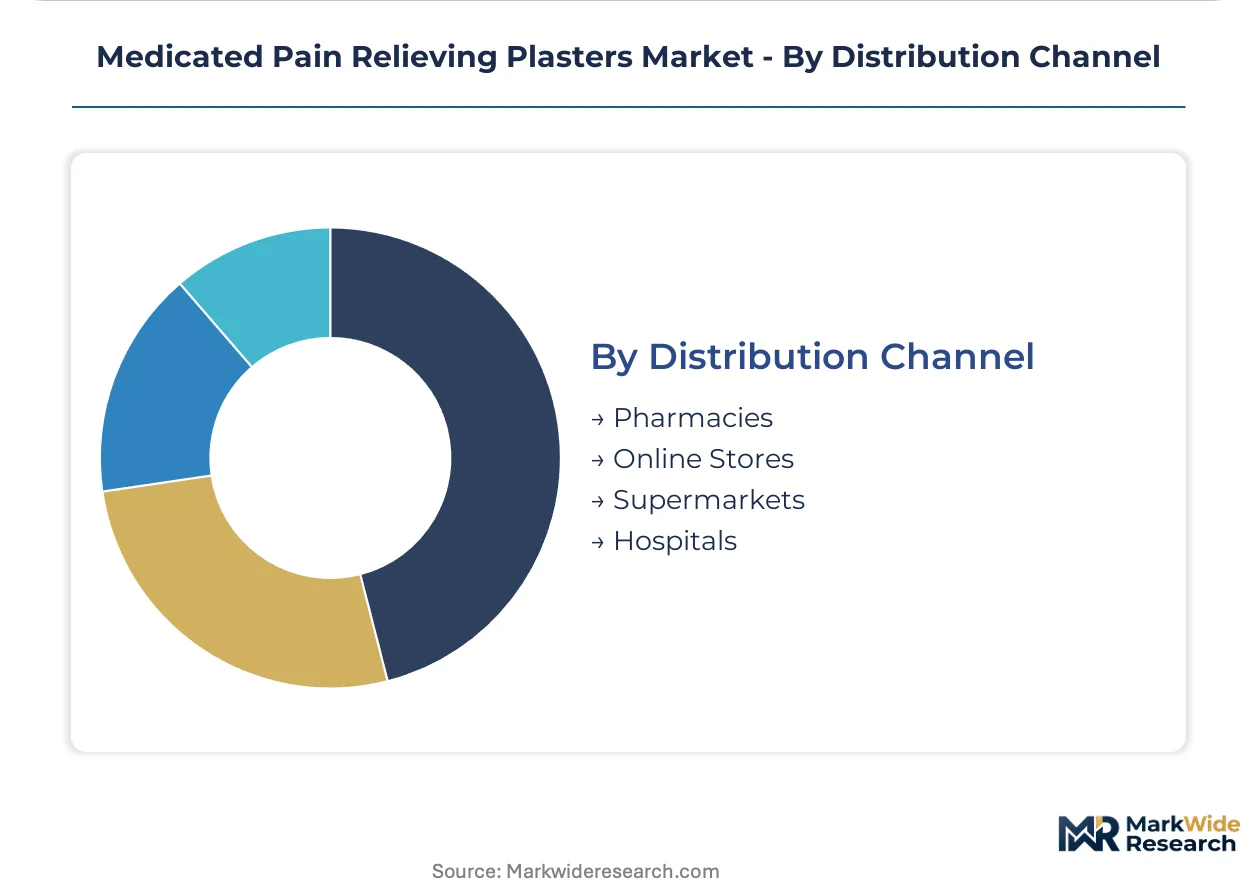
Distribution Channel:
Channel mix reflects geographic reimbursement heterogeneity, with pharmacy-dependent markets contrasting direct-hospital supply models.
- Pharmacies:Primary channel for reimbursed topical analgesics in European markets where pharmacist counseling influences brand selection. GSK leverages OTC relationships across Germany and the United Kingdom to secure shelf placement.
- Hospitals:Centralized tender procurement for postoperative and inpatient analgesia. Consolidated purchasing authority in Dutch regional health authorities prioritizes total cost-of-therapy metrics over unit pricing.
- Online Stores:Direct-to-consumer platforms capturing subscription-based chronic pain management demand. Regulatory fragmentation across national e-pharmacy frameworks creates compliance complexity for cross-border fulfillment.
- Supermarkets:Mass retail placement for standard-grade counterirritant patches. Private-label contract manufacturing by Johnson & Johnson anchors North American chain drugstore and grocery partnerships.
Pharmacies dominate installed base. Hospitals are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between aging societies that favor gel-based tolerability and athletic economies prioritizing rapid-onset local anesthetics for injury protocols. Japan's geriatric preference for moisture-retaining formats contrasts with US sports medicine procurement concentrated on lidocaine patches. European pharmacy reimbursement frameworks sustain adhesive patch volumes despite manufacturing compliance cost pressures.
Japan
Hisamitsu Pharmaceutical and Nichiban anchor domestic production through captive adhesive substrate manufacturing in Saga and Tokyo prefectures. PMDA pharmacovigilance reporting requirements for topical analgesics shape formulation decisions and extend development timelines. Kansai region manufacturing clusters specialize in proprietary cooling technologies for gel patch categories targeting consumers over 65.
United States
Professional athletic organizations in Texas and California expand procurement of lidocaine patches for acute injury management to reduce opioid exposure. FDA Quality by Design mandates for transdermal dosage forms compress supplier margins while favoring manufacturers with captive polymer synthesis. New Jersey-based contract manufacturers serve chain drugstore private-label programs.
Germany
Pain management clinics in Bavaria and North Rhine-Westphalia pilot micro-needle array systems for neuropathic conditions where stratum corneum penetration limits conventional formulations. EMA MDR compliance deadlines for adhesive medical devices elevate manufacturing standards and accelerate consolidation. REACH restrictions on halogenated solvents force aqueous coating process retrofits.
China
Synthetic capsaicin API manufacturing clusters in Jiangsu and Zhejiang provinces create supply vulnerability for Western formulators lacking backward integration. NMPA transdermal drug delivery guidelines prompt reformulation of adhesive matrices for enhanced bioavailability. Yangtze River Delta production facilities face dual carbon goals pressure on petrochemical feedstock consumption.
India
Rural pharmacy networks in Maharashtra and Gujarat remain underpenetrated for medicated plasters, creating first-mover advantage for OTC brands establishing direct-to-clinic logistics. CDSCO bioequivalence protocols for generic patch approvals require expensive clinical endpoint studies. Tamil Nadu manufacturing hubs concentrate solvent-based polymer cross-linking capacity for export markets.
Medicated Pain Relieving Plasters Market Competitive Environment
Capability concentration sits with adhesive substrate specialists possessing captive polymer synthesis; scale advantage sits with diversified pharmaceutical conglomerates leveraging existing pharmacy distribution infrastructure. The market structures around three tiers: Japanese specialists with proprietary cooling technologies, European pain management focused entities, and diversified consumer health conglomerates with OTC channel dominance. Consolidation accelerates through M&A targeting extractables testing laboratories and strategic partnerships for micro-needle array licensing.
Within the Japanese specialist tier, Hisamitsu Pharmaceutical Co., Inc. and Nichiban Co., Ltd. exemplify capability concentration through captive manufacturing of adhesive substrates. Teva Pharmaceutical Industries Ltd. represents the diversified pharmaceutical archetype with institutional channel reach. Grünenthal GmbH anchors European pain management positioning through German manufacturing heritage. These three entities collectively illustrate the competitive tension between proprietary technology control and scaled distribution leverage.
| Leading Market Players |
|---|
| Nichiban Co., Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Hisamitsu Pharmaceutical Co., Inc. |
| Sanofi |
| Grünenthal GmbH |
| Teikoku Seiyaku Co., Ltd. |
| Beiersdorf AG |
| GSK |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Chinese synthetic capsaicin manufacturing clusters compresses margin flexibility for Western formulators while simultaneously dictating procurement contract structures and inventory holding patterns across the value chain.
Pricing Analysis
Long-term offtake agreements anchor procurement relationships between Japanese adhesive substrate specialists and European pharmaceutical distributors, insulating premium gel patch tiers from acrylic adhesive feedstock volatility. Pricing stratifies across premium, standard, and economy tiers based on cooling technology differentiation and PMDA pharmacovigilance certification status. Cost compression in standard-grade counterirritant patches intensifies as private-label contract manufacturers consolidate North American retail placement. Sports medicine procurement departments exhibit lowest price sensitivity due to opioid-reduction protocol mandates, while mass retail channels in India demonstrate highest elasticity.
Supply Chain Analysis
Extended payment terms from European hospital procurement consortia strain working capital for mid-scale adhesive patch producers lacking supply-chain finance facilities. Manufacturing gravity centers on Japan for proprietary cooling technologies, China for synthetic capsaicin API synthesis, and Germany for micro-needle array pilot production. Acrylic adhesive precursors, silicone release liners, and hydrogel polymer substrates constitute critical input dependencies. Single-source vulnerability in Jiangsu and Zhejiang capsaicin clusters creates supply disruption exposure for Western formulators. Distribution runs through pharmacy reimbursement networks in Europe, direct-to-clinic logistics in North American sports medicine, and underpenetrated rural channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oral NSAID manufacturers and opioid analgesic producers represent converging substitute threats that topical patch incumbents must neutralize through efficacy differentiation and regulatory positioning.
For Market Incumbents: Harden supply chain resilience through backward integration into adhesive substrate manufacturing or captive API synthesis partnerships in alternate geographies. Consolidate extractables testing laboratory capabilities ahead of EMA MDR compliance deadlines to exclude smaller contract producers from tender eligibility. Defensive patent positioning around micro-needle array licensing frameworks will constrain entrant access to neuropathic pain protocols.
For New Entrants and Emerging Players: Rural pharmacy networks in Maharashtra and Gujarat represent the most penetrable entry point for OTC brands establishing direct-to-clinic logistics infrastructure. Wearable sensor convergence for postoperative adherence tracking offers white-space positioning against incumbent adhesive patch commoditization. Licensing micro-needle array technology from German pain management clinics provides differentiated clinical channel access.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors adhesive substrate specialists with captive polymer synthesis capabilities over diversified pharmaceutical conglomerates. Acquisition targets should prioritize firms possessing in-house extractables testing laboratories and PMDA-compliant cooling technology IP. Inflection indicators include FDA bioequivalence protocol revisions for generic patch approvals and REACH solvent restriction enforcement trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Substrate Manufacturing | Captive polymer synthesis insulates margin from petrochemical feedstock volatility and FDA Quality by Design compliance costs. |
| Micro-Needle Array Licensing Agreement | German and Swiss pain clinic partnerships collapse efficacy gaps between topical and injectable local anesthetics. |
| Direct-to-Clinic Distribution Expansion | Patient adherence program infrastructure captures aftermarket service revenue from sports medicine procurement departments. |
| Extractables Testing Laboratory Acquisition | In-house capability satisfies EMA MDR compliance deadlines and excludes smaller contract producers from regulated tenders. |
| Rural Pharmacy Network Partnership | First-mover logistics positioning in Maharashtra and Gujarat unlocks underpenetrated OTC demand. |
Study Parameters
Cross-validation between formulary director interviews and FDA transdermal drug delivery guideline documents anchors the qualitative findings on bioequivalence protocol evolution. Primary fieldwork encompassed regulatory affairs leads at Japanese pharmaceutical manufacturers, hospital procurement managers at French regional health authorities, and pain management clinicians at German neuropathic treatment centers. Secondary validation drew from FDA 510(k) filings, EMA MDR compliance guidance, PMDA pharmacovigilance reporting databases, and clinical endpoint studies for generic patch approvals. Bottom-up demand modeling from pharmacy channel audits and top-down supply analysis from adhesive substrate production capacity triangulated volume estimates.
Calibration against historical pricing trajectories for lidocaine patches and capsaicin API spot markets refined elasticity assumptions across the projection horizon. Segmentation dimensions encompassed product format, active ingredient mechanism, end-user purchasing authority concentration, and regional reimbursement framework heterogeneity. CAGRs were derived from patient population demographics, sports medicine protocol adoption curves, and regulatory approval velocity for novel transdermal delivery systems. Industry-specific inputs included PMDA cooling technology patent expirations and IRA drug pricing provision impacts on oral analgesic substitution patterns.
Stress conditions across petrochemical feedstock volatility bands, Chinese API supply disruption scenarios, and EMA MDR compliance timeline slippage were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement trajectories and clinical adoption velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Tattoo Numbing Cream Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Visceral Pain Market
Pain Management
Migraine Management Market
Pain Management
Medical Morphine Market
Pain Management
Chronic Pain Market
Pain Management
Cancer Pain Market
Pain Management
Global Pain Management Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Cluster Headache Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Palliative Care Market
Pain Management
Radiofrequency Ablation Devices for Pain Management Market